
 Asia Pacific Gas Insulated Switchgear Market | 2026-2036
Asia Pacific Gas Insulated Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Gas Insulated Switchgear Market Outlook
Modular GIS configurations is decoupling procurement from traditional turnkey contracts across Asia Pacific utilities. Mitsubishi Electric Corporation leverages its manufacturing scale to anchor supply contracts for high-voltage installations in Japan and export markets. Siemens Energy AG competes through technology leadership in digital switchgear with integrated remote monitoring capabilities. CHINT Group Co., Ltd. sustains cost advantages across medium-voltage segments through in-house production of core insulating components.
Gas insulated switchgear encloses electrical conductors and circuit breakers within sulfur hexafluoride or alternative gas-filled metal compartments, achieving dielectric strength at significantly reduced physical footprint compared to air-insulated alternatives. High voltage switchgear dominates capital deployment as ultra-high-voltage transmission corridors expand across China and India. Digital technology within the technology segment records the fastest adoption trajectory as grid operators prioritize predictive maintenance and real-time fault detection. Compact installation configurations command premium positioning in urban substations where land scarcity forces vertical or underground buildouts.
China's GB standards and SAMR certification requirements shape product entry protocols for foreign manufacturers, while India's CEA technical standards and BIS marking govern domestic procurement eligibility. The EU F-Gas Regulation's extraterritorial influence pressures regional OEMs to accelerate SF6 alternative development ahead of anticipated Asia Pacific regulatory convergence. Stakeholders must monitor which national regulators adopt phased fluorinated gas restrictions first, as this will determine manufacturing relocation patterns and technology partnership priorities across the region.
Market Dynamics
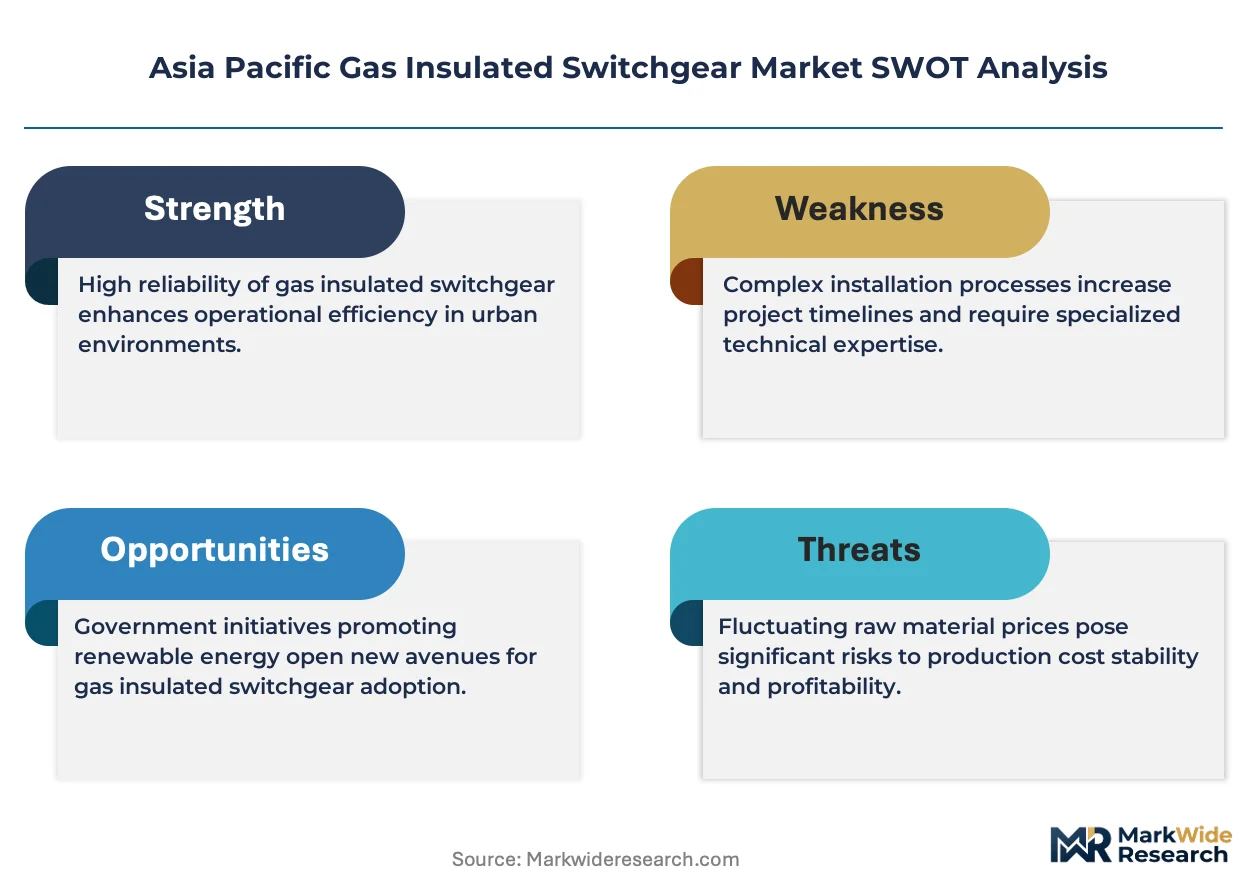
Urban densification across Southeast Asian megacities is forcing utilities toward compact substation architectures that minimize land acquisition costs and accelerate permitting timelines. This spatial constraint is restructuring procurement specifications toward modular, vertically integrated GIS configurations that reduce civil works requirements.
Growth Catalysts
- China's dual carbon goals:National emissions targets mandate grid efficiency improvements that favor SF6-alternative GIS technologies in new transmission corridors.
- State transmission utilities in India:Modernization programs prioritize footprint reduction and disaster resilience in coastal and seismic zones.
- Modular GIS configurations:Standardized plug-and-play designs compress installation schedules and reduce dependency on specialized commissioning crews.
Market Restraints
- SF6 gas price volatility:Sulfur hexafluoride supply concentrates among Chinese chemical producers, exposing OEMs to input cost spikes and export restriction risks.
- Technical limitation in alternative gases:Current fluoronitrile and fluoroketone blends operate at higher pressures, requiring thicker vessel walls that offset compactness advantages.
- Regulatory friction from EU F-Gas Regulation:Extraterritorial disclosure requirements complicate export documentation for Asia Pacific manufacturers serving European project developers.
Strategic Opportunities
- Vietnam and Philippines transmission buildout:Grid expansion programs in these markets lack established supplier relationships, creating first-mover positioning for qualified entrants.
- Digital switchgear convergence:Integration of dissolved gas analysis sensors with edge computing platforms enables predictive maintenance contracts.
- India's PLI scheme for power infrastructure:Production-linked incentives reward domestic manufacturing investment with procurement preference in state tenders.
Industry Challenges
- Specialized gas handling certification:Technician licensing for SF6 recovery and alternative gas filling remains inconsistent across national borders, complicating service deployment.
- Legacy air-insulated substation integration:Hybrid retrofits require custom interface engineering that extends project timelines and strains engineering capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Gas Insulated Switchgear Market |
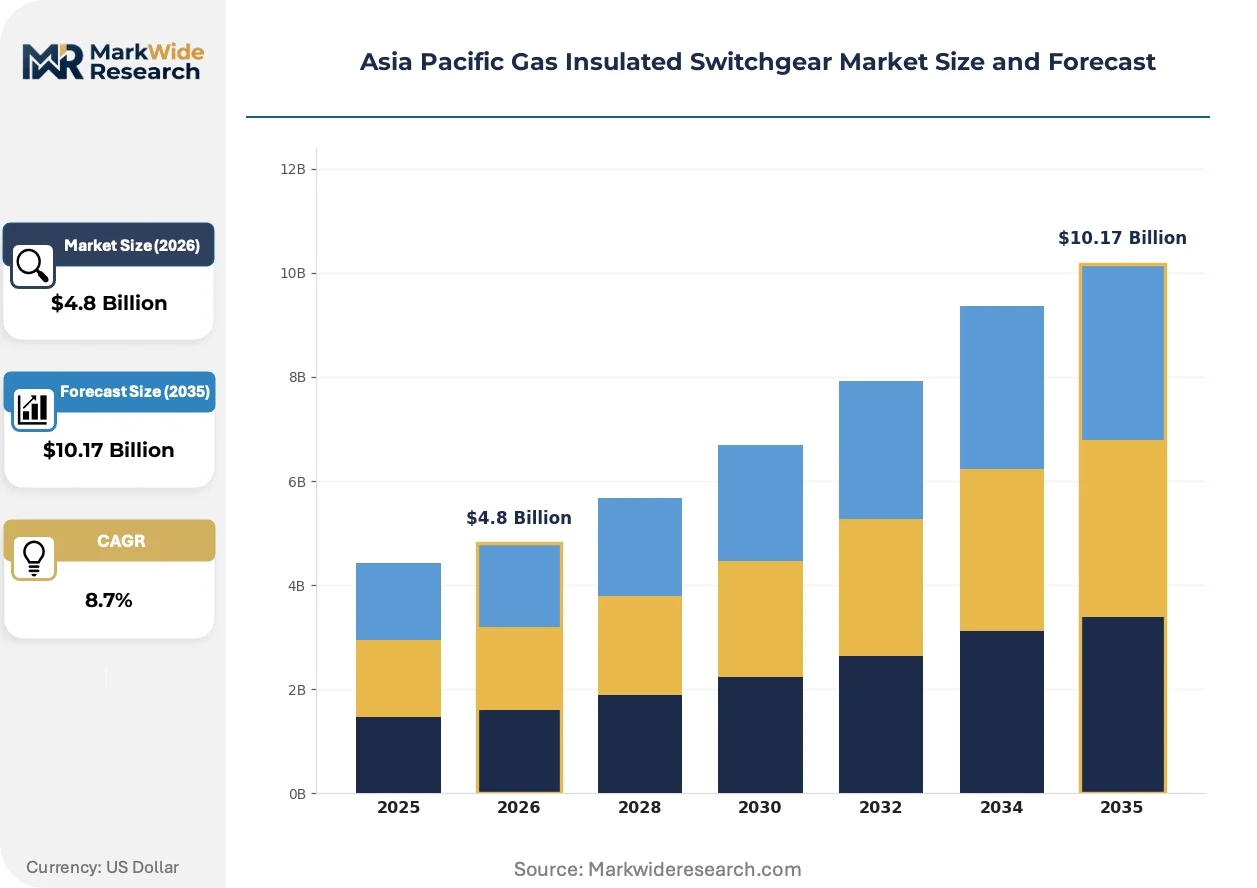
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Voltage, Medium Voltage, Low Voltage, Specialty Switchgear End User: Utilities, Industrial, Commercial, Renewable Energy Installation: Indoor, Outdoor, Hybrid, Compact Technology: Conventional, Digital, Remote Monitoring, Smart Grid |
| Companies Covered | ABB Ltd., Siemens Energy AG, Schneider Electric SE, Mitsubishi Electric Corporation, Eaton Corporation PLC, Hitachi Energy Ltd., Toshiba Corporation, Bharat Heavy Electricals Limited, CHINT Group Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Gas Insulated Switchgear Market Strategic Shifts
Digitalization is compressing the traditional boundary between primary switchgear hardware and grid management software across Asia Pacific utility procurement. Three interconnected developments are restructuring competitive positioning and technology investment priorities.
Digital twin platforms for GIS assets are unifying design validation, commissioning documentation, and operational monitoring into continuous data streams. Japanese and South Korean utilities lead adoption, requiring vendors to deliver native API connectivity rather than retrofit adapters. This unification is compressing supplier margins on standalone hardware while expanding recurring revenue pools for integrated service contracts.
China's GB standards and SAMR certification protocols are tightening electromagnetic compatibility and seismic withstand requirements for imported equipment. Foreign manufacturers must establish domestic testing partnerships or absorb extended approval timelines. High-voltage installations above 245kV face the most stringent documentation burdens, redirecting some project flows toward certified local producers.
State procurement authorities in India and Thailand are unbundling engineering-procurement-construction contracts into separate equipment supply and installation service awards. This fragmentation enables specialist civil contractors to bid substation construction while GIS vendors focus on factory acceptance testing and warranty terms. The shift is most visible in urban underground substation projects where tunneling expertise sits outside traditional electrical OEM capabilities.
Asia Pacific Gas Insulated Switchgear Market Segmentation
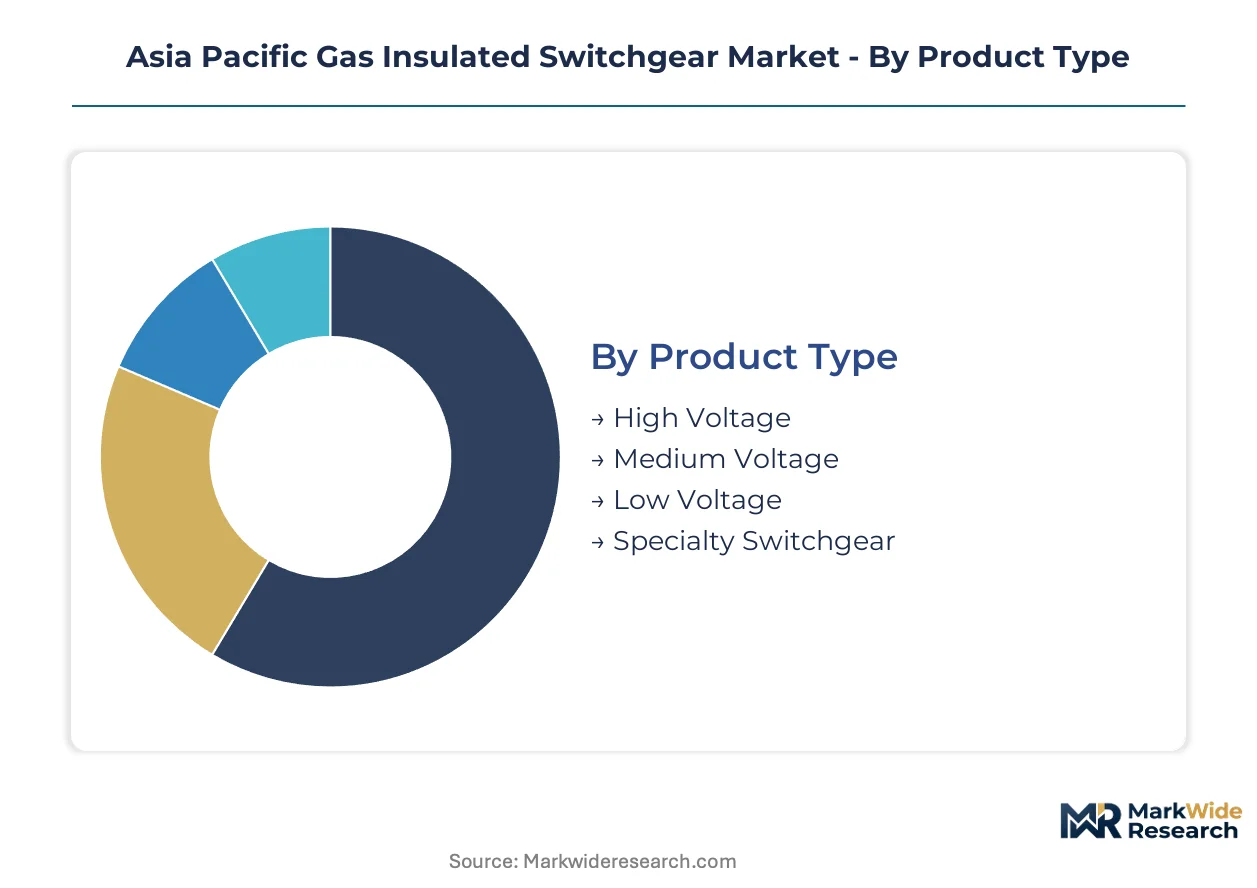
Segmentation in Asia Pacific gas insulated switchgear procurement reveals how voltage requirements, deployment constraints, and grid modernization priorities fragment demand across distinct technical specifications. Procurement officers balance footprint limitations against reliability mandates when specifying equipment categories.
Product Type:
High voltage equipment commands premium positioning due to material intensity and certification complexity, while medium voltage segments drive procurement volume across distribution utilities.
- High Voltage:Encompasses switchgear rated above 52kV with sulfur hexafluoride or fluoronitrile insulation for ultra-high-voltage transmission corridors. State Grid Corporation of China and Power Grid Corporation of India concentrate procurement here as they expand 800kV and 765kV backbone networks across western provinces and central corridors.
- Medium Voltage:Covers 1kV to 52kV ratings dominating urban distribution substations where space constraints force compact designs. Metro rail authorities in Delhi, Bangkok, and Singapore specify these configurations for underground power distribution infrastructure.
- Low Voltage:Serves industrial facility protection with standardized 415V to 1kV ratings.
- Specialty Switchgear:Addresses seismic-resistant and coastal corrosion specifications for Japan's Nankai Trough preparedness and Philippines typhoon zones.
Today's leader: High Voltage. Tomorrow's challenger: Specialty Switchgear.
End User:
Customer archetypes diverge sharply between regulated utilities with standardized tender protocols and industrial buyers prioritizing operational continuity over capital cost.
- Utilities:Comprises state transmission companies and distribution licensees operating under CEA technical standards in India and GB standards in China. These buyers specify full lifecycle cost models and mandate 25-year asset warranties for substation modernization programs.
- Industrial:Encompasses steel, cement, and petrochemical facilities requiring arc-resistant enclosures for personnel protection. POSCO's Korean steel complexes and Reliance Industries' Jamnagar refinery anchor demand for customized gas handling protocols.
- Commercial:Covers data centers and hospital complexes in Singapore and Hong Kong where uninterrupted power supplies justify premium compact installations.
- Renewable Energy:Connects solar parks and offshore wind substations requiring salt-mist resistant specifications along Vietnam's central coast and Tamil Nadu's Coromandel shoreline.
Procurement gravity centers on Utilities. Margin expansion concentrates in Commercial.
Installation:
Physical deployment configuration determines civil engineering requirements and permitting timelines across dense urban versus remote rural contexts.
- Indoor:Deploys within purpose-built switchgear halls with controlled atmospheric conditions. Tokyo Electric Power Company specifies these for coastal substations vulnerable to salt spray corrosion and typhoon debris impact.
- Outdoor:Utilizes weatherproof enclosures for transmission switching stations where land availability permits conventional layouts. China's State Grid deploys these across Xinjiang and Inner Mongolia renewable collection points.
- Hybrid:Combines indoor breaker compartments with outdoor bus configurations for retrofit projects.
- Compact:Integrates all functions within single-enclosure designs for underground Tokyo substations and Seoul metro interconnections.
Urban densification is forcing Compact adoption fastest. Hybrid configurations bridge legacy infrastructure gaps.
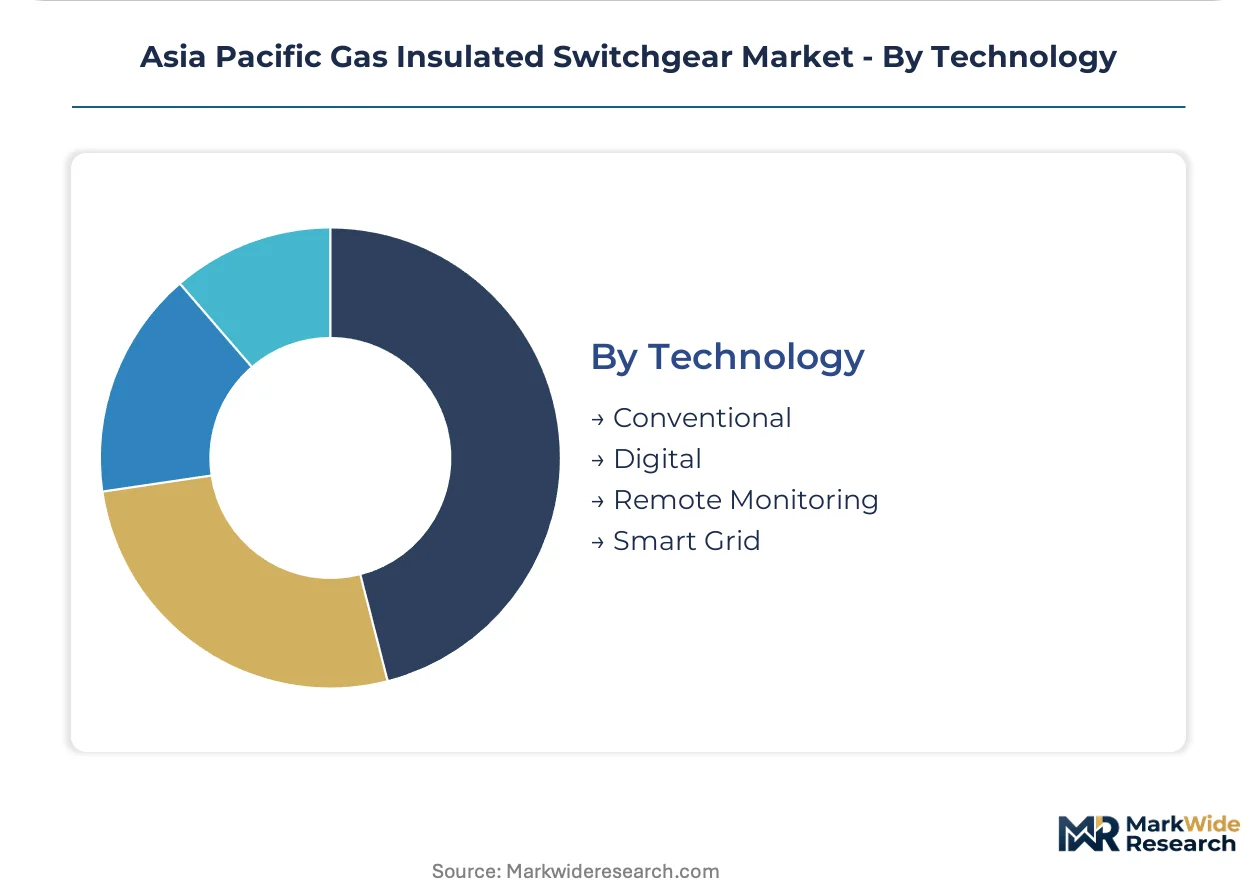
Technology:
Intelligence integration separates commodity hardware from service-enabled platforms as grid operators prioritize predictive capabilities over passive protection.
- Conventional:Relies on electromechanical protection relays and manual gas monitoring without data connectivity. These systems dominate legacy asset replacement cycles in Indonesia's Perusahaan Listrik Negara distribution network where digital infrastructure remains underdeveloped.
- Digital:Embeds microprocessor-based protection and local HMI interfaces for automated fault sectionalization. Korea Electric Power Corporation mandates these for new 154kV urban substations in Seoul metropolitan expansion zones.
- Remote Monitoring:Transmits dissolved gas analysis and thermal imaging data to centralized control centers.
- Smart Grid:Integrates with distribution management systems for automated reconfiguration and demand response coordination.
Digital platforms anchor current procurement specifications. Smart Grid integration represents the steepest expansion trajectory as AMI rollout accelerates across the region.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GIS technology first achieved commercial scale in Japan during the 1960s as Tokyo Electric Power Company deployed compact substations to serve dense metropolitan load centers. This Japanese foundation established the engineering templates that later diffused across Asia Pacific utility procurement standards.
China
State Grid Corporation of China and China Southern Power Grid anchor regional demand through ultra-high-voltage corridor buildouts spanning western renewable bases to eastern load centers. SAMR certification protocols and GB standards tighten electromagnetic compatibility requirements for imported equipment above 245kV. The Yangtze River Delta cluster around Shanghai concentrates manufacturing investment as domestic OEMs scale SF6-alternative production lines.
India
Power Grid Corporation of India and state transmission utilities modernize substations to reduce footprint in seismic and coastal zones. CEA technical standards and BIS marking govern procurement eligibility, while the PLI scheme for power infrastructure redirects tenders toward domestic manufacturing. Gujarat and Maharashtra host the most active urban underground substation deployments for metro rail and commercial district electrification.
Japan
Tokyo Electric Power Company and Chubu Electric Power specify seismic-resistant GIS for Nankai Trough preparedness and typhoon-prone coastal installations. METI efficiency mandates and JIS standards shape product specifications, with particular emphasis on disaster resilience. The Kanto region around Tokyo maintains the highest concentration of compact underground substations serving metropolitan load density.
South Korea
Korea Electric Power Corporation mandates digital switchgear for new 154kV urban substations in Seoul metropolitan expansion zones. MFDS electrical safety frameworks and national smart grid roadmaps accelerate remote monitoring adoption. The Seoul Capital Area drives procurement volume as vertical land use forces substation construction below grade.
Vietnam
National Power Transmission Corporation and provincial electricity authorities expand 500kV backbone networks to connect northern hydropower to southern industrial zones. The country's national power regulator has yet to establish comprehensive GIS-specific standards, creating first-mover positioning for qualified foreign entrants. Central coast provinces from Da Nang to Quang Ngai concentrate renewable integration projects requiring salt-mist resistant specifications.
Asia Pacific Gas Insulated Switchgear Market Competitive Environment
Premium-margin players sit above commodity-margin players across voltage tier and certification complexity. The market structures into three concentration bands: multinational electrical OEMs with integrated energy portfolios, regional specialists with deep domestic regulatory relationships, and emerging domestic champions capturing state-backed procurement preferences. Strategic differentiation concentrates on digital service integration, alternative gas technology licensing, and backward integration into core insulating component production.
Within the multinational OEM tier, ABB Ltd., Siemens Energy AG, and Mitsubishi Electric Corporation exemplify divergent geographic anchoring strategies. ABB's European incorporation and Swiss operational heritage position it within premium-tier specification markets. Siemens Energy AG represents German-engineered technology leadership in digital switchgear platforms. Mitsubishi Electric Corporation anchors Japanese manufacturing scale for high-voltage installations across domestic and export markets. These three entities collectively illustrate how heritage geography shapes competitive positioning without predetermining market share outcomes.
| Leading Market Players |
|---|
| ABB Ltd. |
| Siemens Energy AG |
| Schneider Electric SE |
| Mitsubishi Electric Corporation |
| Eaton Corporation PLC |
| Hitachi Energy Ltd. |
| Toshiba Corporation |
| Bharat Heavy Electricals Limited |
| CHINT Group Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Sulfur hexafluoride feedstock costs cascade through three distinct pricing tiers as Chinese chemical producers concentrate global supply and Indian PLI incentives redirect procurement toward domestic manufacturing premiums.
Pricing Analysis
Project-based equipment supply contracts dominate high-voltage procurement, separating factory acceptance testing from civil installation awards. Price differentiation hinges on SAMR certification grade for imports above 245kV and BIS marking compliance for Indian state tenders. Cost compression in medium-voltage segments is intensifying because CHINT and Bharat Heavy Electricals scale in-house insulating component production. State transmission utilities exhibit lowest price sensitivity given 25-year lifecycle cost mandates, while commercial data center buyers negotiate aggressively on compact underground configurations.
Supply Chain Analysis
Freight costs for specialized gas handling equipment escalate sharply on routes serving Vietnam and Philippines transmission buildouts where domestic manufacturing remains underdeveloped. Component production concentrates in China, Japan, and South Korea, with SF6 gas supply anchored in Chinese chemical complexes and alternative fluoronitrile blends sourced from Japanese specialty chemical producers. Single-source vulnerability in SF6 supply exposes OEMs to export restriction risks from MEE environmental enforcement. Distribution runs through State Grid Corporation of China and Power Grid Corporation of India procurement hubs for high-voltage installations, with specialist electrical distributors serving industrial retrofit segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU F-Gas Regulation extraterritorial disclosure requirements accelerate SF6-alternative R&D investment ahead of anticipated Asia Pacific convergence.
For Market Incumbents: Lock in digital service revenue streams by embedding dissolved gas analysis sensors with native API connectivity for Tokyo Electric Power Company and Korea Electric Power Corporation specifications. Backward integration into fluoronitrile gas production hedges against Chinese SF6 supply volatility. Defend certification moats through domestic testing partnerships in Shanghai and Delhi that compress SAMR and BIS approval timelines below competitor benchmarks.
For New Entrants and Emerging Players: India's PLI scheme for power infrastructure opens a window for domestic manufacturing investment that secures procurement preference in Gujarat and Maharashtra state tenders. Vietnam's national power regulator has yet to establish comprehensive GIS-specific standards, creating first-mover positioning for qualified foreign entrants in 500kV backbone expansions. Target salt-mist resistant specialty switchgear for central coast renewable integration projects as the most penetrable technical niche.
For Investors and Strategic Acquirers: Consolidation pressure builds where digital twin platform capabilities separate integrated service providers from commodity hardware vendors. Long-term viability favors targets with captive alternative gas technology licensing and established CEA technical standards compliance for Indian transmission utility procurement. Watch for India's phased fluorinated gas restriction announcements as the inflection signal determining manufacturing relocation patterns.
| Strategic Initiative | Industry Significance |
|---|---|
| SF6-Alternative Technology Licensing | Positions vendors ahead of EU F-Gas Regulation convergence across Asia Pacific national frameworks. |
| Domestic Manufacturing Footprint Expansion | Captures India's PLI scheme procurement preferences in Gujarat and Maharashtra state tenders. |
| Digital Twin Platform Integration | Meets Tokyo Electric Power Company and Korea Electric Power Corporation native API connectivity mandates. |
| Specialty Switchgear Certification Investment | Unlocks seismic-resistant and salt-mist resistant segments for Japan's Nankai Trough preparedness. |
| Long-Term Service Contract Structuring | Converts hardware margins into recurring revenue through predictive maintenance enabled by edge computing platforms. |
Study Parameters
Coverage spans China, India, Japan, South Korea, and Southeast Asia, with primary inputs from each market combining interviews with utility planning officers, OEM procurement teams, EPC contractors, and grid operators with secondary validation from State Grid Corporation of China procurement disclosures, CEA technical standards documentation, METI efficiency mandate filings, and customs trade data on SF6 gas imports. Bottom-up equipment shipment tracking triangulates against top-down transmission infrastructure investment forecasts.
Rate-of-change decomposition separates volume growth from price trajectory across voltage tier, installation configuration, and technology intelligence level throughout the forecast period. Segmentation modeling incorporates product type, end user archetype, deployment configuration, and digital capability integration. CAGRs derive from utility capital expenditure pipeline analysis and renewable integration project tracking, with particular weighting on metro rail electrification programs and ultra-high-voltage corridor buildouts.
Revisions become necessary when national regulators accelerate fluorinated gas phase-out timelines or when Chinese SF6 export restrictions materialize beyond current environmental enforcement patterns. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Global Duct Heaters Market
Electrical Power Equipment
Alternate Current (AC) Drives Market
Electrical Power Equipment
Gas Water Heater Market
Electrical Power Equipment
Latin America Hazardous Location Motor Starters Market
Electrical Power Equipment
Power Strip Market
Electrical Power Equipment
Frameless Brushless DC Motors Market
Electrical Power Equipment
Unitary Heaters Market
Electrical Power Equipment
Alternators Market
Electrical Power Equipment
Middle East and Africa Hazardous Location Motor Starters Market
Electrical Power Equipment
Industrial Power Supply Market
Electrical Power Equipment
AC Drives Market
Electrical Power Equipment
Low Voltage Protection Control Market
Electrical Power Equipment
Global Low Voltage Electric Drives Market
Electrical Power Equipment
Substation Testing Equipment Market
Electrical Power Equipment
Global Explosion-Proof Electric Motors and Actuators Market
Electrical Power Equipment
Electric Substation Market