
 Taiwan Electric Power Equipment Market | 2026-2036
Taiwan Electric Power Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Taiwan Electric Power Equipment Market Intelligence
Taiwan's net-zero 2050 commitment is pivoting procurement criteria across the electric power equipment sector. Mean Well leverages its specialization in high-efficiency power supplies to capture demand from data center operators under stricter carbon accounting rules. FSP Technology anchors its position through vertical integration from component sourcing to finished transformer assemblies. AcBel Polytech competes aggressively in industrial-grade switchgear, where reliability specifications now incorporate lifecycle emissions metrics.
Taiwan electric power equipment encompasses transformers, circuit breakers, switchgear, and generators engineered for voltage transformation, fault interruption, and power conditioning across 50-60 Hz grid frequencies. These systems employ silicon steel cores, SF6 or vacuum interrupters, and microprocessor-based protection relays to ensure grid stability in high-density industrial zones. The product type dimension shows switchgear commanding attention due to offshore wind interconnection requirements, while the technology dimension reveals smart grid deployments outpacing conventional transmission investments as Taipower modernizes substation automation. The end user dimension reflects utilities dominating capital expenditure, though industrial buyers in semiconductor and petrochemical clusters are accelerating direct procurement of on-site generation and energy storage systems.
The Bureau of Energy under Taiwan's Ministry of Economic Affairs enforces grid connection standards for renewable energy assets, while the Industrial Development Bureau administers energy efficiency labeling that shapes product certification requirements. CNS national standards and IEC-aligned testing protocols govern transformer losses and circuit breaker interrupting ratings, creating compliance barriers for non-certified suppliers. Stakeholders must monitor how Taipower's phased smart meter rollout and distributed energy resource interconnection rules reshape procurement specifications for voltage regulation and load management equipment.
Market Dynamics
Taipower's phased smart meter rollout and offshore wind interconnection mandates are compressing procurement cycles for voltage regulation equipment, forcing suppliers to reconfigure delivery timelines around grid modernization deadlines.
Growth Catalysts
- Net-Zero 2050 Policy:Taiwan's carbon neutrality commitment redirects utility capex toward transformer efficiency upgrades and SF6-free switchgear replacements.
- Semiconductor Cluster Expansion:Hsinchu Science Park fabs are procuring uninterruptible power supply systems with sub-cycle voltage regulation for advanced process nodes.
- Offshore Wind Buildout:Taipower's interconnection standards for 5.7 GW of planned offshore capacity are driving procurement of high-voltage switchgear and dynamic compensation equipment.
Market Restraints
- Silicon Steel Supply Concentration:Core transformer material sourcing concentrates among Japanese and South Korean mills, exposing Taiwanese OEMs to alloy price volatility and extended lead times.
- CNS Certification Friction:Bureau of Energy testing protocols for grid-connected equipment create 6-12 month approval windows that delay product launches.
- SF6 Phase-Down Technical Constraints:Vacuum interrupter alternatives face dielectric limitations above 145 kV, constraining high-voltage switchgear substitution timelines.
Strategic Opportunities
- Energy Storage Integration:Taipower's distributed energy resource interconnection rules create white space for power conditioning systems that manage bidirectional flow from battery assets.
- Taichung Precision Machinery Corridor:Industrial automation clusters in central Taiwan are accelerating direct procurement of on-site generation equipment with embedded voltage regulation.
- Digital Twin Convergence:Integration of IEC 61850 substation automation with predictive maintenance analytics enables service revenue models for switchgear lifecycle management.
Industry Challenges
- Protection Relay Engineering Talent:Microprocessor-based relay programming and cybersecurity hardening require skill sets scarce in Taiwan's electrical engineering labor pool.
- Legacy Substation Retrofit Complexity:Taipower's existing air-insulated switchgear installations demand custom engineering for smart grid sensor integration without service interruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taiwan Electric Power Equipment Market |
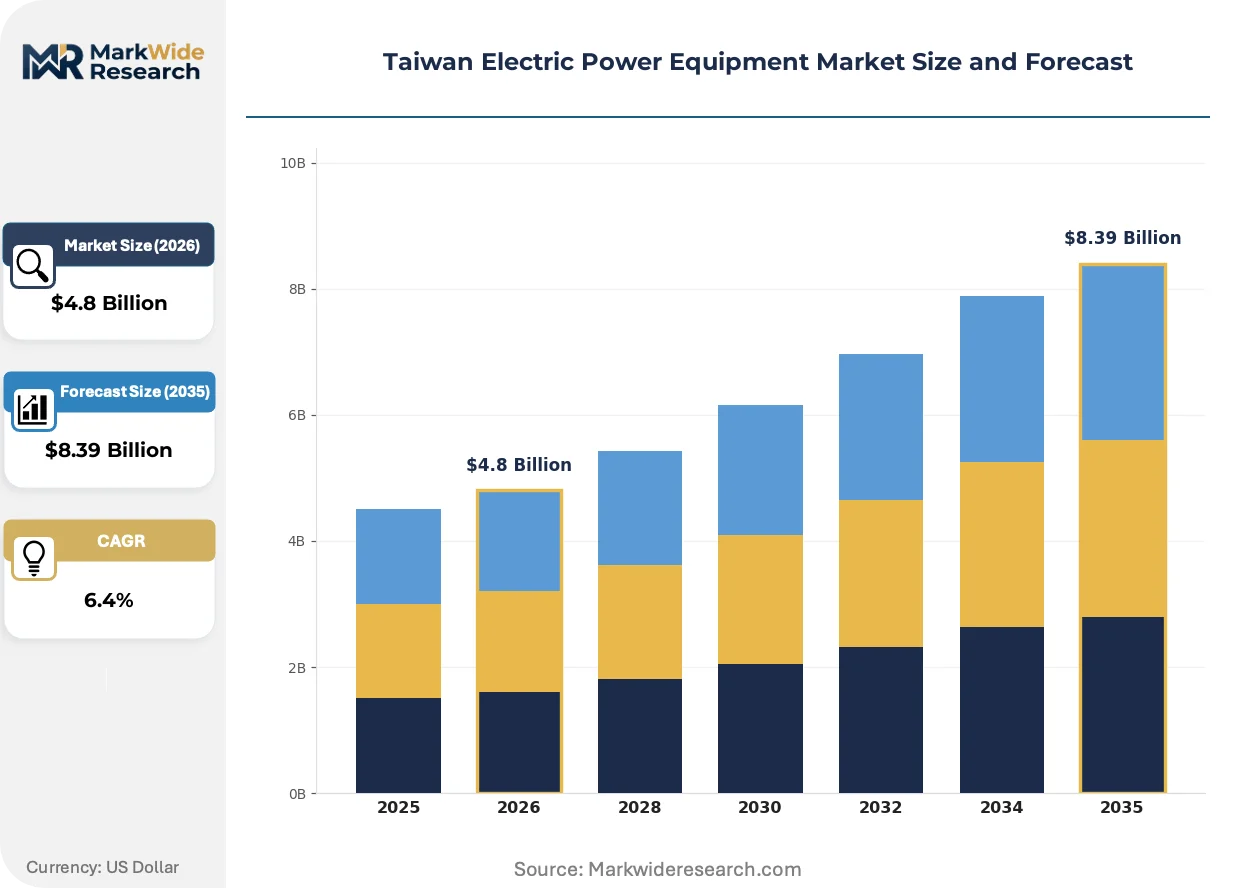
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transformers, Circuit Breakers, Switchgear, Generators End User: Utilities, Industrial, Commercial, Residential Technology: Smart Grid, Renewable Energy, Transmission, Distribution Application: Power Generation, Energy Storage, Load Management, Voltage Regulation |
| Companies Covered | AcBel Polytech, FSP Technology, Mean Well, Sea Sonic, Asian Power Devices, PHIHONG, Sunpower Technology, TECO Electric and Machinery, P-Duke, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taiwan Electric Power Equipment Market Strategic Shifts & Innovations
Digital substation architectures and condition-based monitoring systems are displacing scheduled maintenance regimes across Taiwan's transmission network. Equipment suppliers are embedding intelligence at the edge to capture recurring revenue from grid operators.
Digital twin platforms for transformer asset management are automating thermal modeling and dissolved gas analysis interpretation. Taipower and industrial buyers in the petrochemical corridor are deploying these systems to compress fault detection intervals from weeks to hours. The technology is automating procurement criteria toward predictive performance guarantees rather than capital cost minimization.
Taiwan's Bureau of Energy has aligned CNS standards with IEC 61850-9-2 for process bus communication in new substation builds. This regulatory convergence mandates fiber-optic instrument transformer interfaces and eliminates copper wiring for protection circuits. High-voltage switchgear manufacturers serving the offshore wind interconnection segment are reengineering product platforms to meet these protocol requirements.
Direct procurement by semiconductor fabs and petrochemical operators is displacing traditional utility-mediated equipment sourcing. Industrial buyers in Hsinchu and Mailiao are establishing technical specifications for on-site generation and energy storage systems that exceed Taipower's grid code minima. This pattern concentrates in facilities where power quality interruptions carry million-dollar-per-hour cleanroom or continuous-process exposure.
Taiwan Electric Power Equipment Market Segmentation
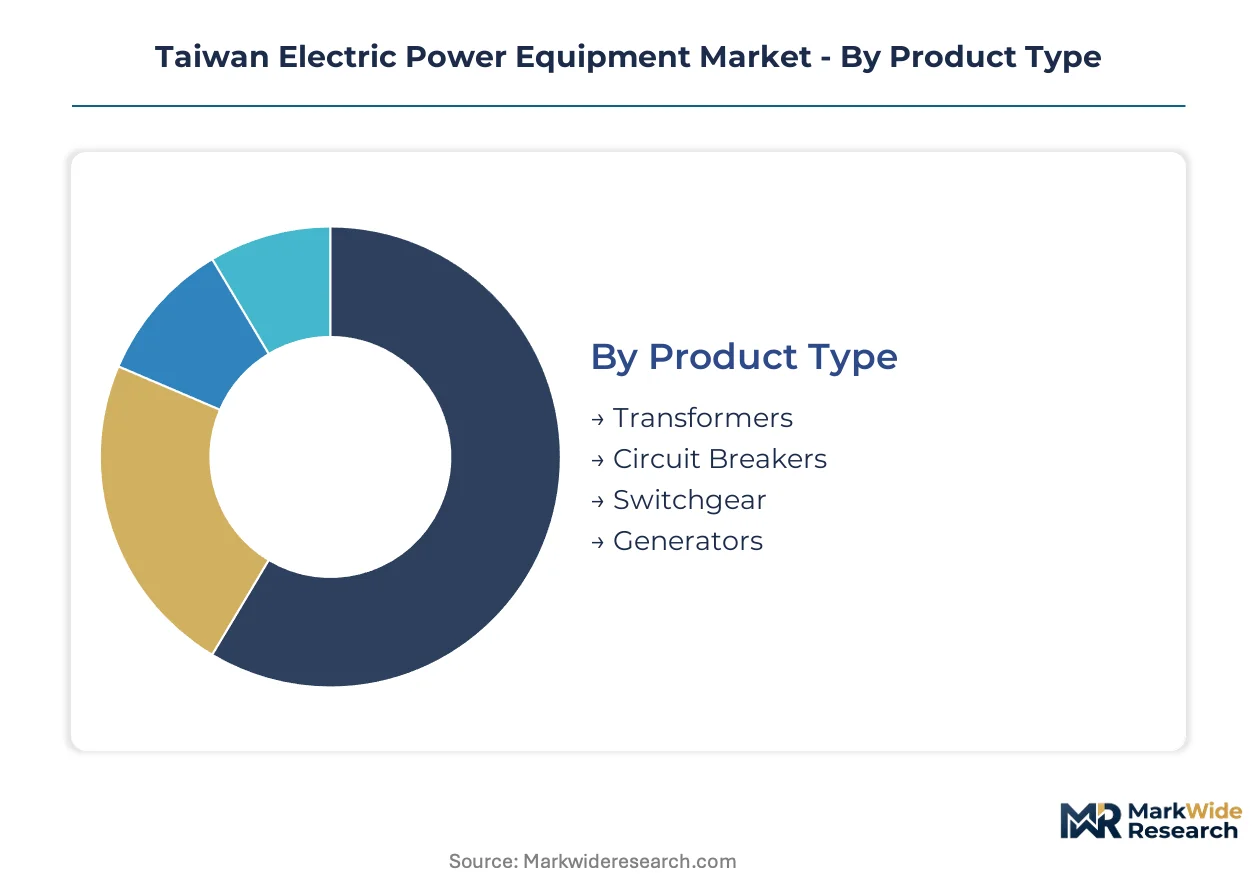
Segmentation reveals how Taiwan's grid modernization and industrial electrification create divergent procurement specifications across voltage classes and automation levels. Equipment suppliers must align product architectures with distinct lifecycle and reliability requirements.
Product Type:
Upgrade cycles vary sharply by product category, with some assets requiring 30-year replacement horizons while others face accelerated obsolescence from environmental regulations.
- Transformers:Silicon steel-cored voltage conversion systems rated from distribution-level 11 kV to transmission-class 345 kV. Taipower's efficiency mandates are forcing premature retirement of pre-2010 units with core losses exceeding modern CNS standards. Procurement concentrates in Taichung's precision machinery corridor where voltage stability requirements exceed utility-grade specifications.
- Switchgear:Metal-enclosed assemblies integrating SF6 or vacuum interrupters with microprocessor-based protection. Offshore wind interconnection standards are compressing procurement cycles for 145 kV+ units as Taipower phases in dynamic compensation requirements. Hsinchu Science Park fabs specify seismic-rated switchgear with sub-cycle fault clearing.
- Circuit Breakers:High-speed fault interruption devices employing SF6, vacuum, or air-blast technologies. Bureau of Energy testing protocols for grid-connected assets create extended approval windows for new breaker platforms.
- Generators:Synchronous and induction machines for on-site power generation in industrial and backup applications. Direct procurement by semiconductor and petrochemical operators is displacing traditional utility-mediated sourcing for premium reliability tiers.
Transformers sit at the top of the volume ranking, with switchgear climbing the fastest due to offshore wind interconnection mandates.
End User:
Customer type determines pricing tolerance and specification stringency, with industrial buyers commanding premium tiers through direct technical intervention.
- Utilities:Taipower and regional distribution operators procuring standardized transmission and distribution assets. Capex prioritization follows net-zero 2050 policy targets with accelerated transformer efficiency upgrades and SF6-free switchgear replacements.
- Industrial:Semiconductor fabrication, petrochemical processing, and precision manufacturing facilities specifying custom voltage regulation and uninterruptible power systems. Mailiao and Hsinchu clusters establish technical specifications exceeding Taipower grid code minima where power quality interruptions carry million-dollar-per-hour exposure.
- Commercial:Data centers, hospitals, and large retail complexes requiring backup generation and power conditioning. Mean Well and FSP Technology compete for high-efficiency power supply contracts under stricter carbon accounting rules.
- Residential:Single-family and multi-unit buildings served through standard distribution infrastructure with limited direct equipment procurement beyond distributed solar inverters.
Utilities dominate absolute procurement value, with industrial buyers expanding fastest through direct sourcing of on-site generation and energy storage systems.
Technology:
Technology tiering reflects capital intensity and interoperability requirements, with smart grid deployments commanding integration premiums over conventional hardware.
- Smart Grid:IEC 61850-compliant substation automation, digital twins, and condition-based monitoring systems. Taipower's phased smart meter rollout and fiber-optic process bus mandates are reengineering procurement specifications toward predictive performance guarantees.
- Renewable Energy:Grid-forming inverters, dynamic compensation equipment, and battery energy storage power conditioning systems. Taipower's distributed energy resource interconnection rules create specification white space for bidirectional flow management.
- Transmission:High-voltage switchgear, shunt reactors, and series compensation for 345 kV backbone infrastructure. Legacy air-insulated substations demand custom engineering for sensor integration without service interruption.
- Distribution:Medium-voltage switchgear, voltage regulators, and capacitor banks for 11-69 kV networks. Rural feeder automation lags urban deployment due to return-on-investment constraints.
Smart grid technology holds the steepest expansion trajectory as Taipower modernizes substation automation, while renewable energy integration requirements are gaining share fastest among new-build specifications.
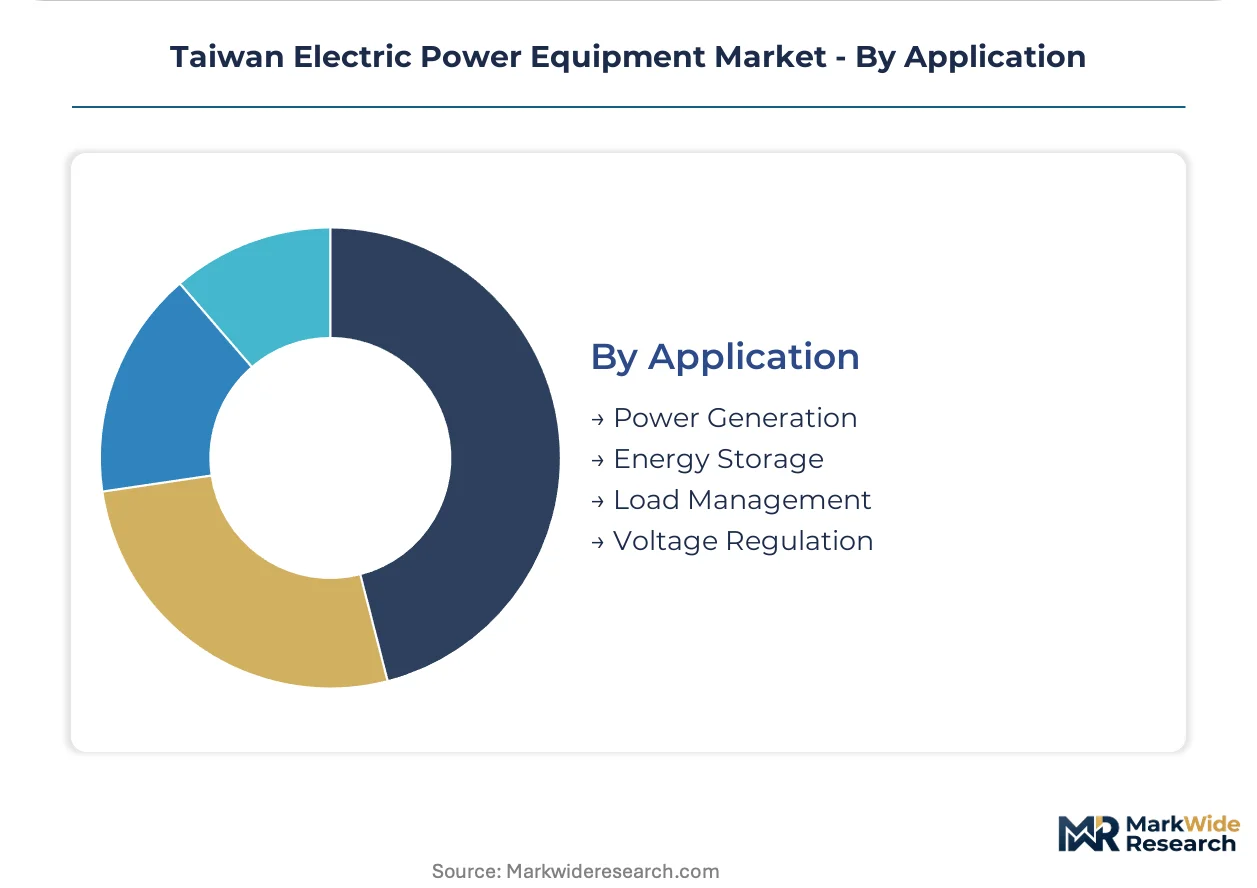
Application:
Application focus determines equipment duty cycles and environmental operating envelopes, with energy storage imposing bidirectional stress profiles absent in conventional generation.
- Power Generation:Prime movers, excitation systems, and grid synchronization equipment for thermal, renewable, and emergency generation. Offshore wind buildout is redirecting capital toward marine-environment-rated switchgear and dynamic compensation.
- Energy Storage:Battery management systems, power conversion systems, and grid-forming inverters for utility-scale and industrial assets. Taipower's interconnection standards for 5.7 GW of planned offshore capacity are driving procurement of high-reliability conditioning equipment.
- Load Management:Demand response controllers, smart meters, and automated feeder switches. Phased smart meter rollout is compressing procurement cycles for voltage regulation equipment.
- Voltage Regulation:Tap-changing transformers, static VAR compensators, and synchronous condensers maintaining grid stability. Semiconductor fabs in Hsinchu Science Park procure sub-cycle regulation systems for advanced process nodes.
Voltage regulation commands the highest unit value, with energy storage applications expanding most quickly through utility and industrial battery deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's electric power equipment industry traces its scale to the 1970s-1980s electronics manufacturing boom, when precision machinery and semiconductor fabrication created sustained demand for voltage-stable infrastructure.
Northern Taiwan
Taipei and New Taipei anchor administrative procurement through Taipower headquarters operations. The Bureau of Energy enforces CNS transformer efficiency standards that accelerate retirement of pre-2010 distribution assets. Hsinchu Science Park fabs specify sub-cycle voltage regulation systems where power quality interruptions carry million-dollar-per-hour cleanroom exposure.
Central Taiwan
Taichung Precision Machinery corridor drives industrial-grade switchgear procurement for automation-intensive manufacturing clusters. The Industrial Development Bureau administers energy efficiency labeling that shapes product certification requirements for voltage regulation equipment. Changhua and Nantou counties host expanding solar PV installations requiring grid-forming inverter and dynamic compensation deployment.
Southern Taiwan
Kaohsiung petrochemical complexes and Mailiao refinery operations establish technical specifications exceeding Taipower grid code minima for continuous-process reliability. Taipower's offshore wind interconnection standards for 5.7 GW of planned capacity redirect capital toward marine-environment-rated high-voltage switchgear. Tainan Science Park semiconductor expansion compresses procurement cycles for uninterruptible power supply systems.
Eastern Taiwan
Hualien and Taitung rural feeder networks lag urban automation deployment due to return-on-investment constraints on smart meter rollout. The Bureau of Energy's phased smart meter mandates prioritize western grid density before eastern extension. Limited industrial load concentration restricts direct procurement of on-site generation equipment relative to western corridors.
Taiwan Electric Power Equipment Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification tier and vertical integration depth, with CNS-certified suppliers commanding pricing premiums over non-certified competitors. The vendor base organizes into three strategic archetypes: integrated power supply specialists, component-to-system vertical fabricators, and industrial-grade switchgear focused operators. Capacity expansion and backward integration into core material sourcing represent the dominant competitive moves as silicon steel supply concentration exposes margins to alloy price volatility.
Among Taiwan-based fabricators, Mean Well, FSP Technology, and AcBel Polytech exemplify distinct positioning within the premium tier. Mean Well occupies a position anchored in high-efficiency power supply specialization for data center and industrial automation applications. FSP Technology represents the integrated archetype through captive control over component sourcing and finished transformer assembly operations. AcBel Polytech sits within the industrial switchgear segment where reliability specifications now incorporate lifecycle emissions metrics under net-zero procurement criteria.
| Leading Market Players |
|---|
| AcBel Polytech |
| FSP Technology |
| Mean Well |
| Sea Sonic |
| Asian Power Devices |
| PHIHONG |
| Sunpower Technology |
| TECO Electric and Machinery |
| P-Duke |
| Others |
Cost & Logistics Intelligence
Microprocessor-based relay programming talent concentration in northern Taiwan widens labor-cost spreads between premium-certified and economy-tier switchgear suppliers. Taipower procurement officers and industrial buyers in Hsinchu absorb these differentials through performance-guarantee contracts that bundle lifecycle service.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement, with CNS certification grade and seismic rating specifications driving spreads. Price differentiation intensifies as semiconductor fabs demand sub-cycle voltage regulation while commercial buyers prioritize carbon-accounting compliance. Cost compression in standard-tier transformers runs through silicon steel alloy volatility. Industrial buyers in Mailiao and Hsinchu exhibit lowest price sensitivity; residential distributed solar inverter purchasers remain most elastic.
Supply Chain Analysis
Dual-sourcing mandates from Taipower and major industrial buyers force Taiwanese OEMs to qualify Japanese and South Korean silicon steel mills alongside domestic processors. Core transformer production draws from grain-oriented electrical steel, SF6 gas or vacuum interrupter assemblies, and microprocessor-based protection relays. Single-source vulnerability concentrates in high-grade silicon steel alloying. Distribution runs through direct utility procurement channels and industrial EPC contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Taiwan's electric power equipment sector functions as a stable compounder, with net-zero 2050 policy mandates ensuring sustained replacement demand across transmission and distribution infrastructure.
For Market Incumbents: Hedge silicon steel exposure through long-term offtake agreements with Japanese and South Korean mills. Deepen captive control over component sourcing to defend margins against alloy price spikes. Accelerate IEC 61850 certification investments before Bureau of Energy mandates harden compliance windows. For New Entrants and Emerging Players: Taipower's distributed energy resource interconnection rules in Taiwan open a window for power conditioning system specialists. Target energy storage integration white space where bidirectional flow management specifications remain unsettled. Pursue joint development agreements with offshore wind EPC contractors seeking local switchgear qualification. For Investors and Strategic Acquirers: Industrial automation conglomerates are the most active acquirer in this space, seeking captive voltage regulation capabilities. Five-to-ten year viability rests on smart grid software integration depth. Monitor Taipower smart meter deployment cadence as inflection signal for voltage regulation equipment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Steel Sourcing | Captive alloy supply insulates margins from Japanese and South Korean mill price volatility. |
| IEC 61850 Certification Investment | Fiber-optic process bus compliance unlocks Taipower substation automation procurement. |
| Energy Storage Power Conditioning Development | Bidirectional flow management addresses Taipower's 5.7 GW offshore wind interconnection standards. |
| Digital Twin Platform Deployment | Predictive maintenance analytics enable recurring service revenue from transformer lifecycle contracts. |
| SF6-Free Switchgear Engineering | Vacuum interrupter platforms capture net-zero 2050-driven replacement cycles above 145 kV. |
Research Approach
Coverage spans northern, central, southern, and eastern Taiwan, with primary inputs from each region. Utility planning officers at Taipower, IPP project developers for offshore wind capacity, EPC contractors, and grid operators provided forward procurement visibility. Secondary validation drew from Bureau of Energy regulatory filings, CNS standard documentation, Industrial Development Bureau efficiency labeling records, and customs trade data for transformer and switchgear imports. Bottom-up equipment unit economics and top-down utility capex aggregation were triangulated.
Rate-of-change decomposition anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type, end user archetype, technology tier, and application duty cycle. CAGRs were derived from utility capital expenditure trajectories, industrial direct procurement patterns, and renewable energy interconnection mandates. Semiconductor fab expansion timelines and offshore wind construction schedules served as industry-specific volume drivers.
Revisions become necessary when Bureau of Energy testing protocol timelines compress, silicon steel supply disruptions materialize, or SF6 phase-down technical constraints ease unexpectedly. Deviation in Taipower smart meter rollout cadence would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Alternate Current (AC) Drives Market
Electrical Power Equipment
North America Power Inverter Market
Electrical Power Equipment
Europe Electric Space Heaters Market
Electrical Power Equipment
Composite Line Post Insulators Market
Electrical Power Equipment
North America Air-Insulated Switchgear Market
Electrical Power Equipment
Magnetic Optical Current Transformer Market
Electrical Power Equipment
Alternating Current (AC) Electric Drives Market
Electrical Power Equipment
Substation Market
Electrical Power Equipment
Global Switchgear Monitoring Market
Electrical Power Equipment
Battery Charger Market
Electrical Power Equipment
AC Drives Market
Electrical Power Equipment
Fuse Link Market
Electrical Power Equipment
Electric Substation Market
Electrical Power Equipment
Alternator Regulator Market
Electrical Power Equipment
Composite Insulators Market
Electrical Power Equipment
Immersion Heater Market