
 Saudi Arabia Power EPC Market | 2026-2036
Saudi Arabia Power EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Power EPC Market Analytics
Ultra-supercritical steam parameters and 60% combined cycle efficiency benchmarks is bifurcating contractor capabilities in the Saudi Arabia Power EPC Market. Doosan Enerbility leverages its boiler and turbine manufacturing depth to anchor thermal project execution. ACWA Power sustains its developer-contractor hybrid model across utility-scale renewable and desalination-linked power schemes. Hyundai E&C competes on Korean-financed infrastructure packages tied to Saudi industrial zone expansions.
Power Engineering, Procurement, and Construction (EPC) denotes a turnkey delivery framework where a single contractor assumes design accountability, equipment sourcing, civil installation, and commissioning for generation assets, typically governed by ISO 9001 quality management and IEC 60045 turbine performance standards. The primary purpose is to transfer completion risk from asset owners to contractors while achieving guaranteed output, heat rate, and schedule metrics. Mega Projects within the Project Size dimension command disproportionate margin pools due to long-dated contracts and limited qualified bidder pools, while Renewable Energy within the Technology dimension attracts developer capital seeking power purchase agreement-backed yields. Commissioning services represent a structurally undersupplied segment where specialized firms extract premium pricing for grid code compliance and reliability testing.
The Saudi Electricity Company (SEC) grid codes, SFDA industrial safety mandates, and GOSI contractor qualification requirements collectively shape equipment specifications, labor composition, and market access thresholds for foreign EPC firms bidding on public projects. The National Renewable Energy Program's local content requirements are forcing technology suppliers to establish domestic manufacturing or forfeit eligibility for government-anchored tenders. Stakeholders must monitor the pace of SEC unbundling and private sector participation rules, as these will determine whether integrated developer-EPC consortia or pure engineering contractors capture the next wave of gigawatt-scale awards.
Market Dynamics
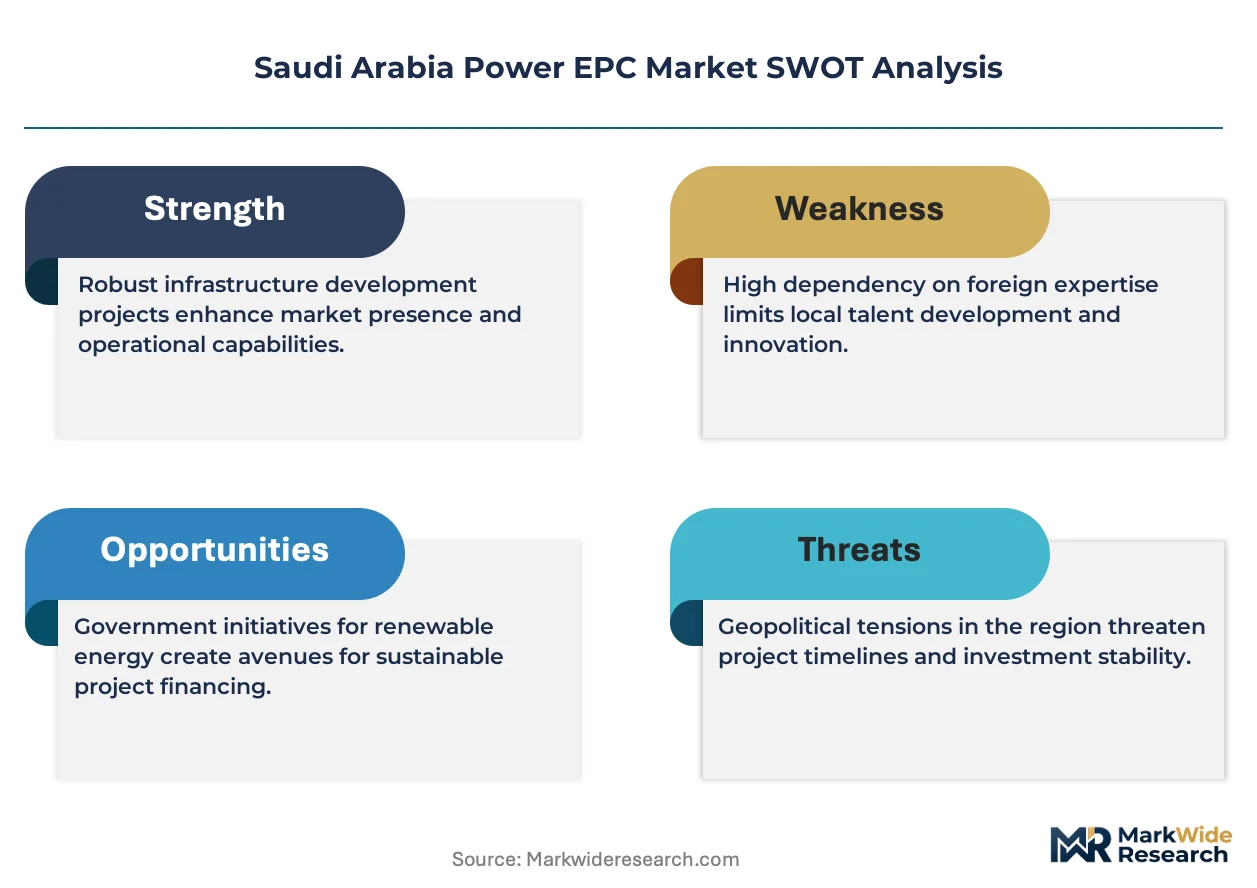
The Saudi Electricity Company's unbundling timeline and the Saudi Green Initiative's renewable capacity mandates are forcing contractors to restructure execution models around solar-wind hybrid plants and ultra-supercritical thermal retrofits.
Growth Catalysts
- SFDA industrial safety mandates:Stringent contractor qualification requirements under Saudi Arabia's industrial safety framework are filtering out undercapitalized bidders and concentrating awards among firms with proven safety records.
- Solar PV manufacturing localization:The National Renewable Energy Program's domestic content rules are pulling module assembly and inverter production into the Kingdom, creating captive supply chains for EPC bundling.
- Eastern Province industrial load centers:Petrochemical and smelting expansions near Jubail and Ras Al-Khair are anchoring gigawatt-scale combined cycle demand with 25-year offtake visibility.
Market Restraints
- Specialized turbine supply concentration:Heavy gas turbine manufacturing concentrates among a handful of European and East Asian OEMs, exposing Saudi projects to 18-24 month delivery queues and currency fluctuation pass-through.
- Steel and copper input volatility:Transmission tower and cable costs swing with London Metal Exchange pricing, compressing fixed-price EPC margins on long-dated contracts.
- GOSI contractor qualification thresholds:Foreign engineering firms face escalating Saudi workforce ratio requirements and joint venture mandates that extend pre-qualification timelines by 6-12 months.
Strategic Opportunities
- NEOM gigaproject zone:The linear city's 100% renewable mandate and green hydrogen export ambitions are creating first-mover slots for integrated power-water-hydrogen EPC consortia.
- Grid-scale battery integration:Lithium-ion and emerging sodium-ion storage systems are converging with solar PV to enable firm renewable dispatch, opening new commissioning and control system specialties.
- Red Sea coastal wind corridor:Underdeveloped sites between Yanbu and Duba offer 7+ meter-per-second wind resources with minimal transmission congestion, attracting early-stage developer-EPC partnerships.
Industry Challenges
- Grid code compliance engineering:SEC's evolving frequency response and voltage ride-through standards require specialized power system studies that outpace local university pipeline output.
- Multi-technology integration complexity:Hybrid plants combining combined cycle, solar PV, and battery storage demand cross-functional commissioning teams with scarce IEC 60045 and IEEE 1547 dual certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Power EPC Market |
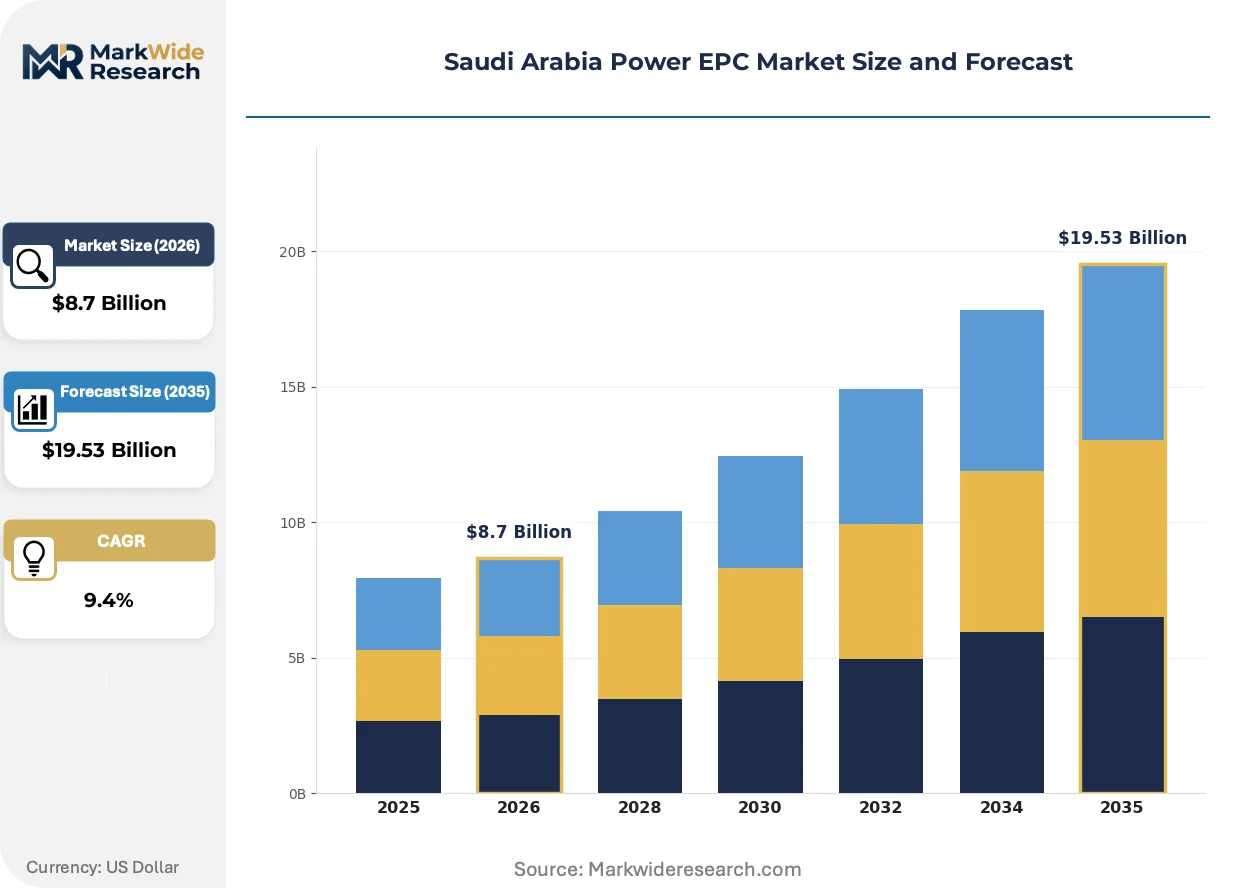
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Engineering, Procurement, Construction, Commissioning Project Size: Small Scale, Medium Scale, Large Scale, Mega Projects End User: Government, Private Sector, Industrial, Utilities Technology: Renewable Energy, Thermal Power, Gas Turbine, Hydro Power |
| Companies Covered | Doosan Enerbility, Saudi Electricity Co. – NCC, ACWA Power, GE Vernova, Hyundai E&C, PowerChina, Siemens Energy, Alfanar, Larsen & Toubro, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Power EPC Market Evolving Landscape
Digital twin deployment and modular construction methods are compressing project schedules while Saudi regulatory pressure on carbon intensity is accelerating technology substitution in thermal plant design.
Modular solar PV racking and skid-mounted substation assemblies are decomposing traditional stick-built construction sequences. EPC contractors are adopting these prefabricated systems for 500MW-plus solar parks in Riyadh Province, collapsing civil works duration by 30-40% and shifting labor composition toward module installation specialists rather than field welders and concrete crews.
The National Renewable Energy Program's local content enforcement is tightening equipment sourcing rules. Manufacturers without Saudi-based module assembly or inverter production facilities are losing eligibility for government-anchored tenders, pushing Korean and Chinese suppliers toward joint ventures with Saudi industrial partners in Rabigh and Jeddah Economic City.
Asset owners are unbundling long-term service agreements from initial EPC awards. Saudi Electricity Company and ACWA Power are separating 15-25 year O&M contracts from construction bids, allowing specialized operators to compete on availability guarantees and forcing pure engineering contractors to defend margin position through construction excellence rather than captive aftermarket revenue.
Saudi Arabia Power EPC Market Segmentation
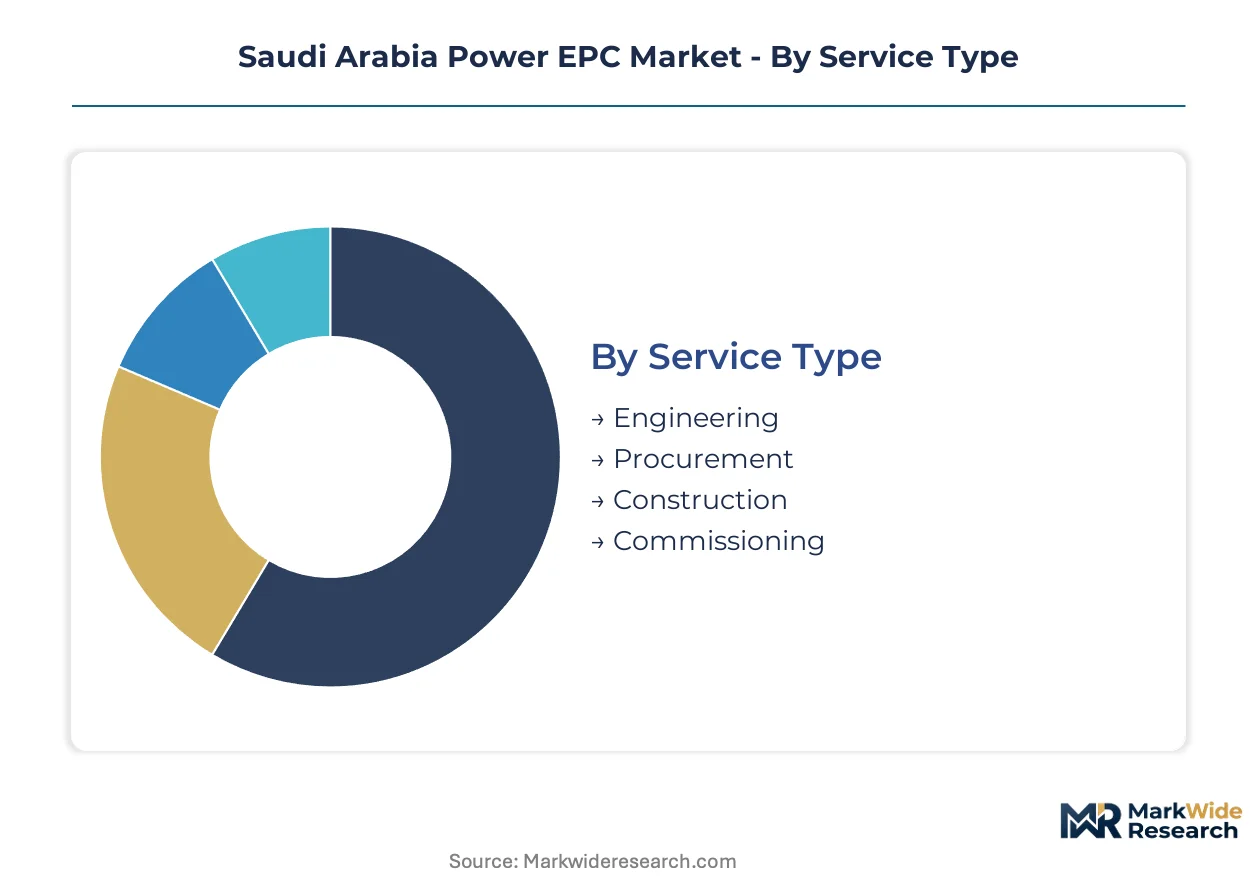
Segmentation in the Saudi Arabia Power EPC Market reveals how contractor capabilities, regulatory thresholds, and technology choices intersect. SFDA safety mandates and GOSI qualification rules create divergent entry barriers across service types and project scales.
Service Type:
SFDA industrial safety mandates impose tiered contractor qualification requirements that filter eligibility across engineering, procurement, construction, and commissioning disciplines.
- Engineering:Front-end design and detailed engineering services require IEC 60045 turbine performance certification and power system modeling expertise. Riyadh-based engineering hubs concentrate talent for grid code compliance studies that SEC mandates for all new interconnections.
- Procurement:Equipment sourcing and vendor management functions carry currency exposure and long-lead scheduling risk. Eastern Province industrial load centers drive procurement bundling for combined cycle plants with 25-year offtake visibility.
- Construction:Civil works, mechanical erection, and electrical installation form the labor-intensive execution phase. Modular construction methods are compressing schedules for 500MW-plus solar parks in Riyadh Province.
- Commissioning:Grid code compliance testing and reliability verification represent a structurally undersupplied segment. Specialized firms extract premium pricing for frequency response and voltage ride-through certification.
Construction handles the majority of throughput; Commissioning is the fastest mover on share.
Project Size:
Cost tier differentiation separates bidder pools and margin structures across project scales.
- Mega Projects:Gigawatt-scale developments command disproportionate margin pools due to limited qualified bidder pools and long-dated contract structures. NEOM's 100% renewable mandate and green hydrogen export ambitions anchor this tier.
- Large Scale:Utility-scale combined cycle and solar PV developments cluster near industrial load centers in Jubail and Ras Al-Khair. Petrochemical expansions provide offtake visibility that attracts Korean-financed infrastructure packages.
- Medium Scale:Distributed generation and grid substation projects suit regional contractors with GOSI qualification. Red Sea coastal wind corridor developments between Yanbu and Duba fall into this tier.
- Small Scale:Commercial and industrial rooftop solar installations face compressed margins but faster cycle times. Local content requirements under the National Renewable Energy Program shape equipment sourcing.
Mega Projects capture the dominant share of contract value; Medium Scale is expanding most quickly as distributed renewable mandates proliferate.
End User:
Customer type determines risk allocation, financing structure, and local content enforcement intensity.
- Utilities:Saudi Electricity Company unbundling is restructuring procurement around integrated EPC services for generation and grid infrastructure. SEC grid codes and reliability standards govern equipment specifications.
- Industrial:Petrochemical and smelting operators in the Eastern Province anchor demand with captive power requirements and desalination-linked power schemes.
- Government:National Renewable Energy Program tenders enforce domestic content rules that pull module assembly into the Kingdom. Public project bidding requires GOSI contractor qualification and Saudi workforce ratio compliance.
- Private Sector:Independent power producers and commercial offtakers seek power purchase agreement-backed yields. Developer-EPC hybrid models dominate this customer type.
Utilities anchor the largest project pipeline; Industrial is climbing the fastest on the back of Eastern Province zone expansions.
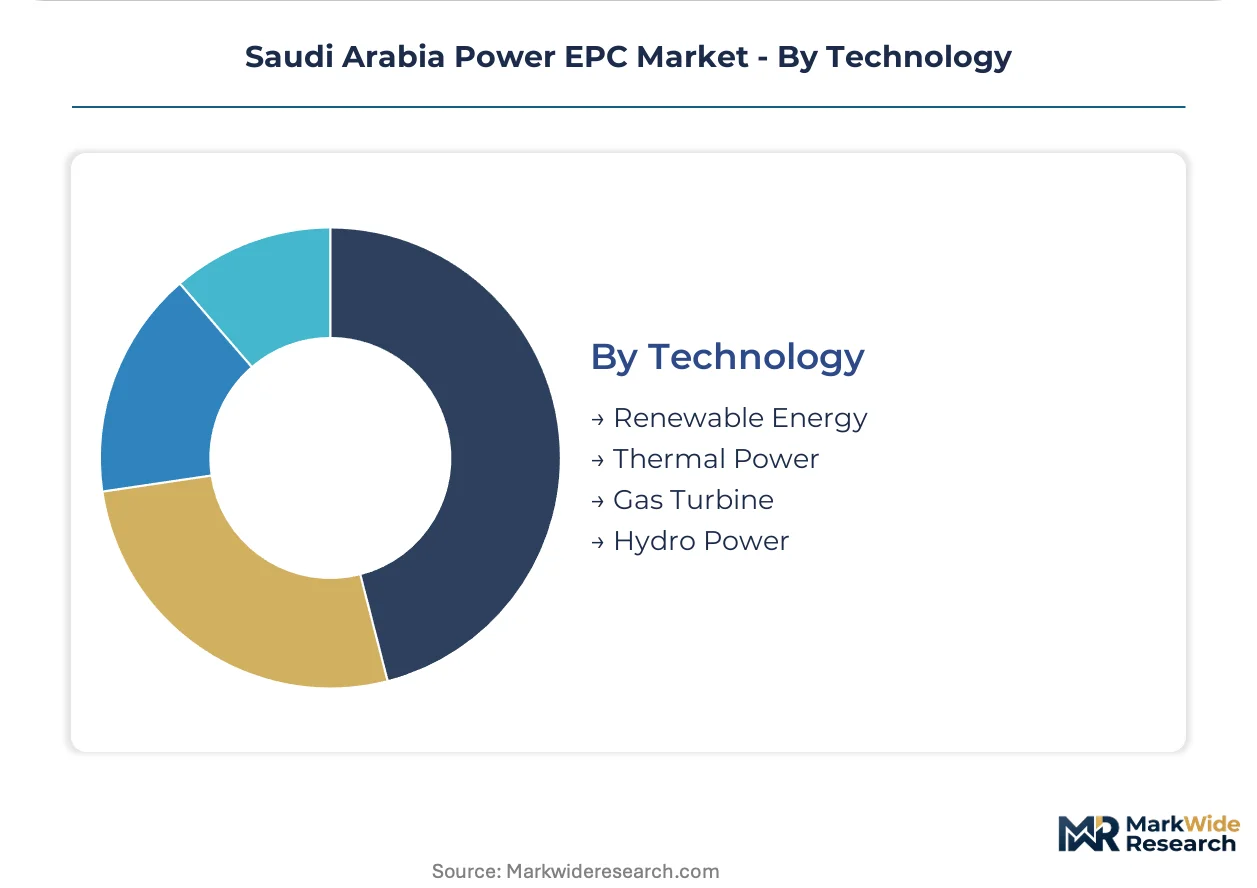
Technology:
Maturity curves and supply concentration differentiate execution risk across generation technologies.
- Renewable Energy:Solar PV and wind-integrated projects are accelerating under Saudi Green Initiative mandates. Grid-scale battery integration is converging with solar to enable firm renewable dispatch.
- Thermal Power:Ultra-supercritical steam parameters and efficiency retrofits dominate the existing fleet upgrade cycle. Doosan Enerbility leverages boiler and turbine manufacturing depth for execution.
- Gas Turbine:Heavy gas turbine supply concentrates among European and East Asian OEMs, exposing projects to 18-24 month delivery queues. Combined cycle efficiency benchmarks bifurcate contractor capabilities.
- Hydro Power:Limited resource availability constrains deployment to small-scale run-of-river developments in southwestern highlands. This technology holds minimal share in the Saudi market.
Renewable Energy commands the steepest expansion trajectory; Thermal Power retains the largest installed base requiring retrofit services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heavy gas turbine fabrication and ultra-supercritical boiler manufacturing concentrate among East Asian and European industrial conglomerates, creating 18-24 month delivery queues for Saudi projects. Korean-financed infrastructure packages and Chinese state-backed development finance are reshaping contractor selection in the Kingdom's eastern industrial zones.
Riyadh
Gigawatt-scale solar PV parks and combined cycle developments cluster around the capital's transmission backbone. SEC grid codes and GOSI contractor qualification requirements govern equipment specifications for new interconnections. The Riyadh Province hosts 500MW-plus modular solar installations where prefabricated racking systems compress civil works schedules.
Eastern Province
Petrochemical expansions near Jubail and Ras Al-Khir anchor captive power demand with 25-year offtake visibility. SFDA industrial safety mandates filter bidder pools for desalination-linked power schemes. Korean-financed infrastructure packages from Hyundai E&C concentrate execution capacity in this industrial corridor.
Western Region
Red Sea coastal wind sites between Yanbu and Duba offer 7+ meter-per-second wind resources with minimal transmission congestion. The National Renewable Energy Program's local content rules pull module assembly into Jeddah Economic City. Early-stage developer-EPC partnerships are securing land access ahead of competitive tender rounds.
NEOM Northwest
The linear city's 100% renewable mandate and green hydrogen export ambitions are creating first-mover slots for integrated power-water-hydrogen EPC consortia. Grid-scale battery integration with solar PV enables firm renewable dispatch for industrial offtake. Specialized commissioning firms extract premium pricing for grid code compliance in this greenfield zone.
Saudi Arabia Power EPC Market Competitive Landscape
Concentration sits with integrated developer-contractor hybrids and heavy industrial conglomerates possessing in-house turbine manufacturing depth. The market structure bifurcates between firms with captive equipment supply and those competing on construction excellence alone. Two strategic archetypes dominate: Korean-financed infrastructure packagers leveraging state-backed development finance, and Saudi-Gulf joint ventures meeting GOSI local content thresholds. Competitive moves center on backward integration into module assembly and strategic partnerships for electrolyzer bundling.
Among East Asian industrial conglomerates, Doosan Enerbility and Hyundai E&C occupy positions anchored by domestic manufacturing ecosystems. Doosan exemplifies the equipment-integrated archetype through its boiler and turbine production depth. Hyundai E&C represents the Korean-financed infrastructure packaging model tied to Saudi industrial zone expansions. Within the Saudi-Gulf hybrid tier, ACWA Power sits as a developer-contractor model spanning utility-scale renewable and desalination-linked schemes.
| Leading Market Players |
|---|
| Doosan Enerbility |
| Saudi Electricity Co. – NCC |
| ACWA Power |
| GE Vernova |
| Hyundai E&C |
| PowerChina |
| Siemens Energy |
| Alfanar |
| Larsen & Toubro |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts with 25-year visibility anchor Saudi power project economics, locking in equipment procurement schedules and insulating EPC margins from spot commodity swings while binding contractors to fixed-price execution risk.
Pricing Analysis
SFDA industrial safety mandates dictate the pricing tier structure across contractor qualification levels. Three-tier pricing separates IEC 60045-certified premium execution from standard GOSI-qualified bids and economy-tier regional packages. Cost compression in solar EPC is intensifying because module assembly localization forces technology suppliers into joint venture equity stakes. Government tenders show least price sensitivity due to local content enforcement, while private IPPs negotiate aggressively on construction risk allocation.
Supply Chain Analysis
Port congestion at Jeddah Islamic Port and container availability on Asia-Middle East trade lanes govern inbound logistics costs for heavy gas turbine components. Manufacturing gravity centers on South Korea, Japan, and Germany for ultra-supercritical boilers and heavy gas turbines. Raw material dependencies span high-grade steel, copper conductors, and polysilicon feedstock. Single-source vulnerability concentrates in European OEM turbine supply. Distribution runs through SEC-specified logistics corridors to Riyadh and Eastern Province load centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Saudi power EPC market is entering a cyclical recovery phase as gigawatt-scale renewable tenders accelerate under Saudi Green Initiative capacity mandates and SEC unbundling restructures procurement flows.
For Market Incumbents: Consolidate execution capabilities around modular solar construction and grid-scale battery integration to defend margin position against Korean-financed infrastructure packagers. Deepen backward integration into Saudi-based module assembly to satisfy National Renewable Energy Program domestic content thresholds. Lock in long-term service agreement separations that pure EPC contractors cannot match. For New Entrants and Emerging Players: IEC 60045 turbine performance certification fast-track offers the most penetrable entry vector for specialized commissioning firms seeking premium pricing in grid code compliance. Target the Red Sea coastal wind corridor between Yanbu and Duba where land access precedes competitive tender rounds. Lead with power system modeling expertise for SEC frequency response studies that outpace local university pipeline output. For Investors and Strategic Acquirers: Capital is best deployed toward developer-EPC hybrid archetypes with captive equipment supply and Saudi-Gulf joint venture structures meeting GOSI workforce ratio requirements. Long-term viability over a multi-year horizon rests on electrolyzer bundling capabilities for NEOM green hydrogen export schemes. Watch SEC unbundling pace as the inflection signal determining whether integrated consortia or pure engineering contractors capture next-wave awards.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Module Assembly | Joint ventures in Rabigh and Jeddah Economic City satisfy National Renewable Energy Program local content enforcement. |
| Grid-Scale Battery Integration | Lithium-ion and sodium-ion storage convergence with solar PV opens new commissioning specialties for firm renewable dispatch. |
| Power Purchase Agreement Structuring | 25-year offtake visibility from Eastern Province petrochemical expansions anchors Korean-financed infrastructure package economics. |
| Electrolyzer Bundling Capability | NEOM's 100% renewable mandate and green hydrogen export ambitions create first-mover slots for integrated power-water-hydrogen consortia. |
| SFDA Safety Certification Investment | Tiered contractor qualification requirements filter undercapitalized bidders and concentrate awards among proven safety record holders. |
Research Methodology
A standing panel of utility planning officers, IPP project developers, EPC contractors, and grid operators provided ongoing calibration throughout the research cycle. Primary interviews with SEC interconnection specialists and ACWA Power development executives combined with secondary validation from EIA data, IEA reports, FERC filings, and project development databases. Bottom-up project pipeline aggregation and top-down macroeconomic triangulation anchored market sizing across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type. CAGRs were derived from installed capacity buildout trajectories and capital intensity assumptions. Forecast inputs incorporated SEC unbundling timelines and Saudi Green Initiative renewable capacity mandates without year-specific anchoring.
Underlying assumptions cover equipment delivery schedules, local content enforcement intensity, and contractor qualification pipeline throughput, with deviation risk concentrated in heavy gas turbine OEM delivery queues and London Metal Exchange steel and copper volatility. Recalibration cycles align with material shifts in SEC procurement restructuring and National Renewable Energy Program tender pacing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Uzbekistan Power EPC Market
Power Equipment
Natural Gas Turbine Market
Power Equipment
Automatic Power Factor Controller Market
Power Equipment
Power Plant Lightning Protection Services Market
Power Equipment
Power Grid Primary and Secondary Fusion Equipment Market
Power Equipment
Nigeria Power EPC Market
Power Equipment
Global Power Rental Systems Market
Power Equipment
Middle East Power Filter Market
Power Equipment
United Kingdom Power EPC Market
Power Equipment
Europe SCR Power Controller Market
Power Equipment
South America Nuclear Power Plant Equipment Market
Power Equipment
Asia-Pacific Gas Turbine Service Market
Power Equipment
Turbomachinery Control Systems, Retrofitting, and Ancillary Services Market
Power Equipment
France Power EPC Market
Power Equipment
Power Conditioning Services Market
Power Equipment
Power Engineering, Procurement, and Construction (EPC) Market