
 Enclosed Flares Market | 2026-2036
Enclosed Flares Market Size, Share, and Industry Trends Forecast 2026-2036
Enclosed Flares Market Insights
Buyer concentration across North American refineries is rebalancing as integrated oil majors consolidate maintenance vendor lists while independent petrochemical operators fragment procurement across regional specialists. Zeeco sustains technology leadership through proprietary burner designs for high-H2S gas streams. John Zink Hamworthy Combustion anchors its position via extensive field service networks across Permian Basin processing facilities. MRW Technologies specializes in modular enclosed flare packages for midstream compression stations.
Enclosed flares are combustion devices that destroy volatile organic compounds and hazardous air pollutants within a refractory-lined chamber, typically achieving destruction efficiencies above 98% through controlled air-fuel mixing and residence times exceeding 0.5 seconds. Their primary purpose is to enable continuous or emergency vent gas combustion while concealing flames, reducing noise, and minimizing radiant heat exposure in populated or congested industrial areas. Low-emission flares and ground flares capture expanding share as fence-line community pressure intensifies and real estate encroaches on legacy plant boundaries. Thermal oxidizers command premium pricing due to complex refractory requirements and integrated heat recovery systems. Oil and gas applications dominate current installations, though chemical processing represents the fastest-growing demand pool as specialty chemical producers face heightened benzene and butadiene emission scrutiny.
The EPA enforces New Source Performance Standards under the Clean Air Act that mandate minimum flare combustion efficiency and visible emission limits, directly shaping equipment specification and retrofit timelines. OSHA process safety management requirements and state-level air quality implementation plans layered by Texas Commission on Environmental Quality and California Air Resources Board add compliance complexity that favors engineered solutions over commodity burners. Stakeholders must monitor evolving methane fee structures and state-level carbon intensity scoring that could revalue gas recovery against combustion-based destruction.
Market Dynamics
Refinery operators face mounting pressure to replace open-flare infrastructure as fence-line communities expand and EPA methane rules tighten. Equipment procurement cycles are compressing from five-year replacement windows to accelerated retrofit timelines driven by consent decree enforcement.
Growth Catalysts
- EPA New Source Performance Standards:Updated combustion efficiency mandates force immediate equipment upgrades across petrochemical corridors. Refiners must achieve 98% destruction efficiency or face operational penalties.
- Midstream compression station buildout:Permian Basin gas gathering infrastructure requires enclosed flares at every custody transfer point. Pipeline operators specify modular packages for rapid deployment.
- Hydrogen blending in fuel gas streams:High-H2S burner technologies enable safe combustion of increasingly variable refinery off-gas compositions. This process flexibility extends equipment lifecycles.
Market Restraints
- Refractory material cost volatility:High-alumina ceramic prices fluctuate with bauxite supply disruptions from Guinea and Australia. This input compression squeezes fabricator margins.
- Fabrication capacity concentration:Heavy-wall pressure vessel manufacturing clusters along the US Gulf Coast. Hurricane exposure creates single-point supply risk.
- Gas recovery economics:Vapor recovery units compete for capital allocation against enclosed flares. When natural gas prices drop below threshold levels, combustion-based destruction loses financial justification.
Strategic Opportunities
- California carbon intensity scoring:The state's LCFS program rewards methane destruction with tradable credits. This incentive structure revalues enclosed flare installations at California refineries.
- Biogas upgrading facilities:Landfill gas and anaerobic digestion plants require enclosed combustion for odor control. This application segment remains underpenetrated by incumbent flare vendors.
- Digital twin integration:Combining CFD modeling with IoT sensor feeds enables predictive refractory maintenance. This convergence reduces unplanned downtime.
Industry Challenges
- Combustion engineer scarcity:Specialized expertise in high-H2S burner design concentrates among retiring practitioners. Knowledge transfer gaps threaten project execution timelines.
- Texas Commission on Environmental Quality permitting:Air permit amendments for flare modifications require 18-24 month review cycles. These delays stall equipment commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enclosed Flares Market |
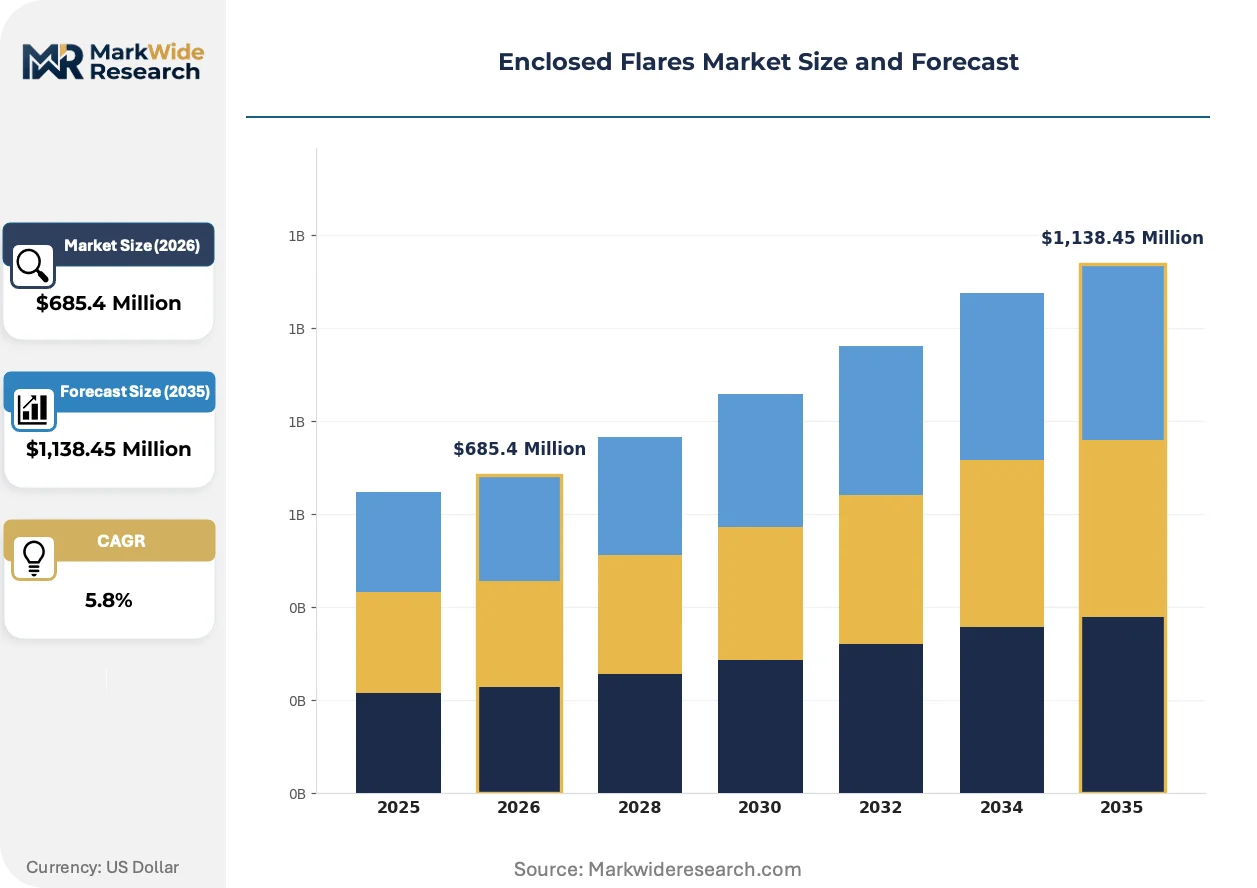
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Emission Flares, Thermal Oxidizers, Elevated Flares, Ground Flares Application: Oil & Gas, Chemical Processing, Waste Management, Industrial Heating Technology: Flame Arrestors, Gas Recovery, Control Systems, Monitoring Solutions End User: Refineries, Petrochemical Plants, Power Plants, Manufacturing Facilities |
| Companies Covered | Cimarron Energy, Fives ITAS, MRW Technologies, Zeeco, John Zink Hamworthy Combustion, Honeywell UOP, Encore Combustion, NAO, AEREON, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enclosed Flares Market Trends and Innovations
Equipment specification is pivoting toward integrated emission monitoring and automated combustion control. Vendors now compete on data transparency rather than hardware durability alone.
Plasma-assisted ignition technology is electrifying startup reliability in high-wind conditions. Offshore platform operators in the Gulf of Mexico deploy these systems to eliminate pilot flame extinction. This electrification is compressing maintenance intervals and reducing personnel exposure to hazardous ignition attempts.
EPA's updated flare monitoring requirements under 40 CFR Part 60 Subpart Ja mandate continuous parameter monitoring systems. Refiners must install redundant thermocouples and flow meters with real-time data logging. US Gulf Coast facilities are responding by bundling instrumentation upgrades with full flare replacement projects.
Service contracting is fragmenting as integrated oil majors unbundle engineering procurement from long-term maintenance. Independent refiners in the Midwest now source spare burner tips through direct OEM channels rather than bundled service agreements. This disintermediation is most visible among Ohio River Valley petrochemical processors seeking cost transparency.
Enclosed Flares Market Segmentation
Equipment specification in the enclosed flares market diverges sharply between premium engineered systems and commoditized combustion hardware. Understanding these segment boundaries clarifies where margin concentrates versus where procurement consolidates on price.
Product Type:
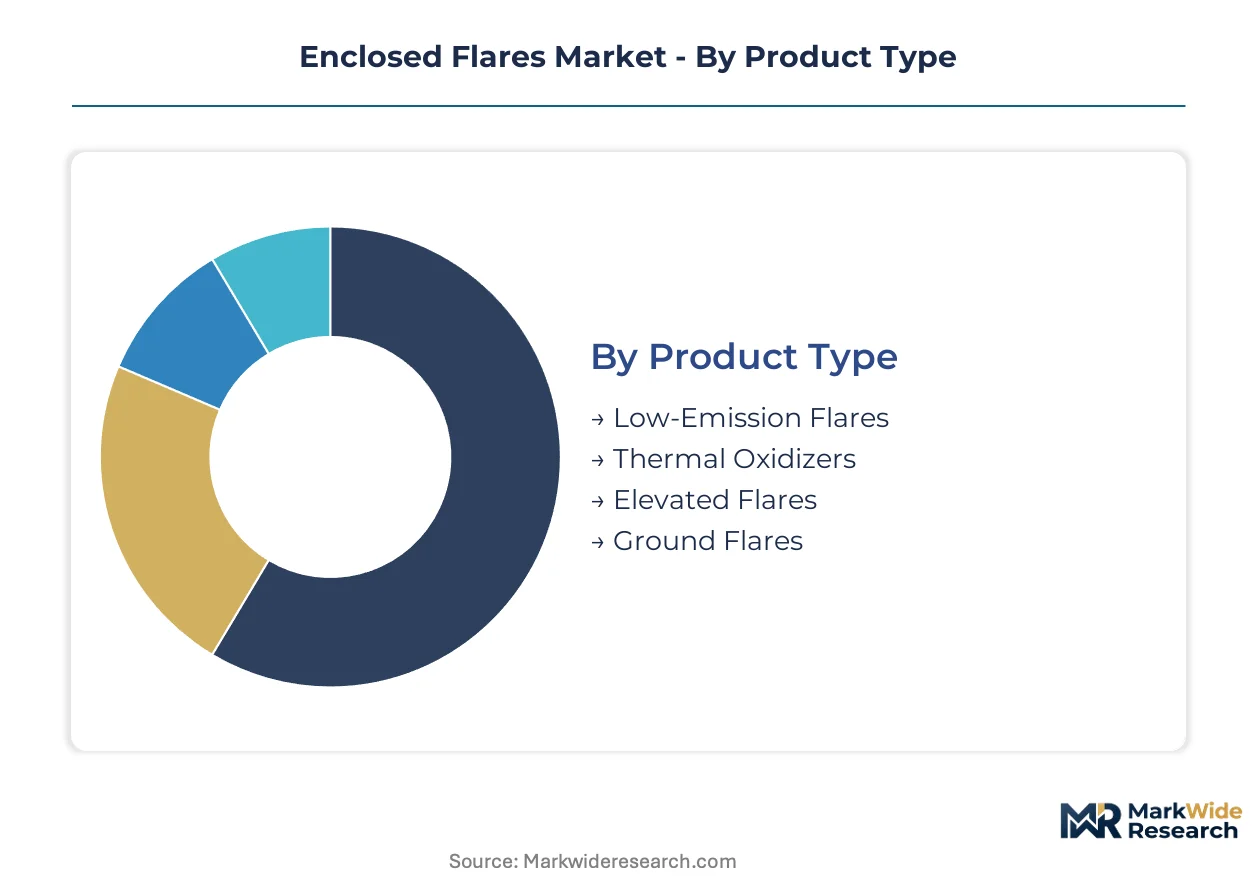
Volume concentrates in standardized ground flare packages, while premium pricing attaches to thermal oxidizers with integrated heat recovery.
- Low-Emission Flares:These systems achieve sub-98% destruction efficiency through staged combustion and induced draft control. Fence-line community pressure in Texas Gulf Coast counties accelerates refinery procurement of concealed-flame designs that eliminate visible plumes and radiant heat exposure.
- Thermal Oxidizers:Complex refractory-lined chambers with residence times exceeding 0.75 seconds command premium positioning. California refineries under CARB jurisdiction specify these for benzene and butadiene destruction mandates where minimum 99% efficiency is non-negotiable.
- Elevated Flares:Traditional open-flare replacements with structural steel stacks dominate legacy retrofit budgets.
- Ground Flares:Modular packages with refractory enclosures suit midstream compression stations requiring rapid deployment.
Today's leader: Thermal Oxidizers. Tomorrow's challenger: Low-Emission Flares.
Application:
Application demand tracks regulatory enforcement intensity more than underlying industrial activity.
- Oil & Gas:Upstream gathering systems and downstream refining constitute the installed base majority. EPA New Source Performance Standards enforcement across Permian Basin processing facilities sustains replacement cycles for open-flare infrastructure.
- Chemical Processing:Specialty chemical producers face heightened scrutiny on benzene, butadiene, and HAP emissions. This segment climbs fastest as OSHA process safety management audits intensify and consent decree timelines compress.
- Waste Management:Landfill gas and biogas upgrading facilities require enclosed combustion for odor control compliance.
- Industrial Heating:Cement and steel auxiliary fuel gas disposal represents a price-sensitive procurement pool.
Where enforcement tightens fastest, Chemical Processing gains share.
Technology:
Technology segmentation separates hardware-only sales from integrated system architectures that bundle monitoring and control.
- Flame Arrestors:Passive safety devices prevent flashback propagation into vent headers. Offshore platform specifications in the Gulf of Mexico mandate redundant arrestor configurations where wind-driven flame instability risks personnel exposure.
- Gas Recovery:Vapor recovery units compete directly with enclosed flares for capital allocation. When Henry Hub pricing sustains above threshold levels, recovery economics displace combustion-based destruction at Permian Basin compressor stations.
- Control Systems:Automated air-fuel ratio modulation and pilot ignition sequencing.
- Monitoring Solutions:Continuous parameter monitoring systems with real-time data logging for EPA Subpart Ja compliance.
Hardware margins stagnate in Flame Arrestors. Integrated Monitoring Solutions capture expanding attach rates.
End User:
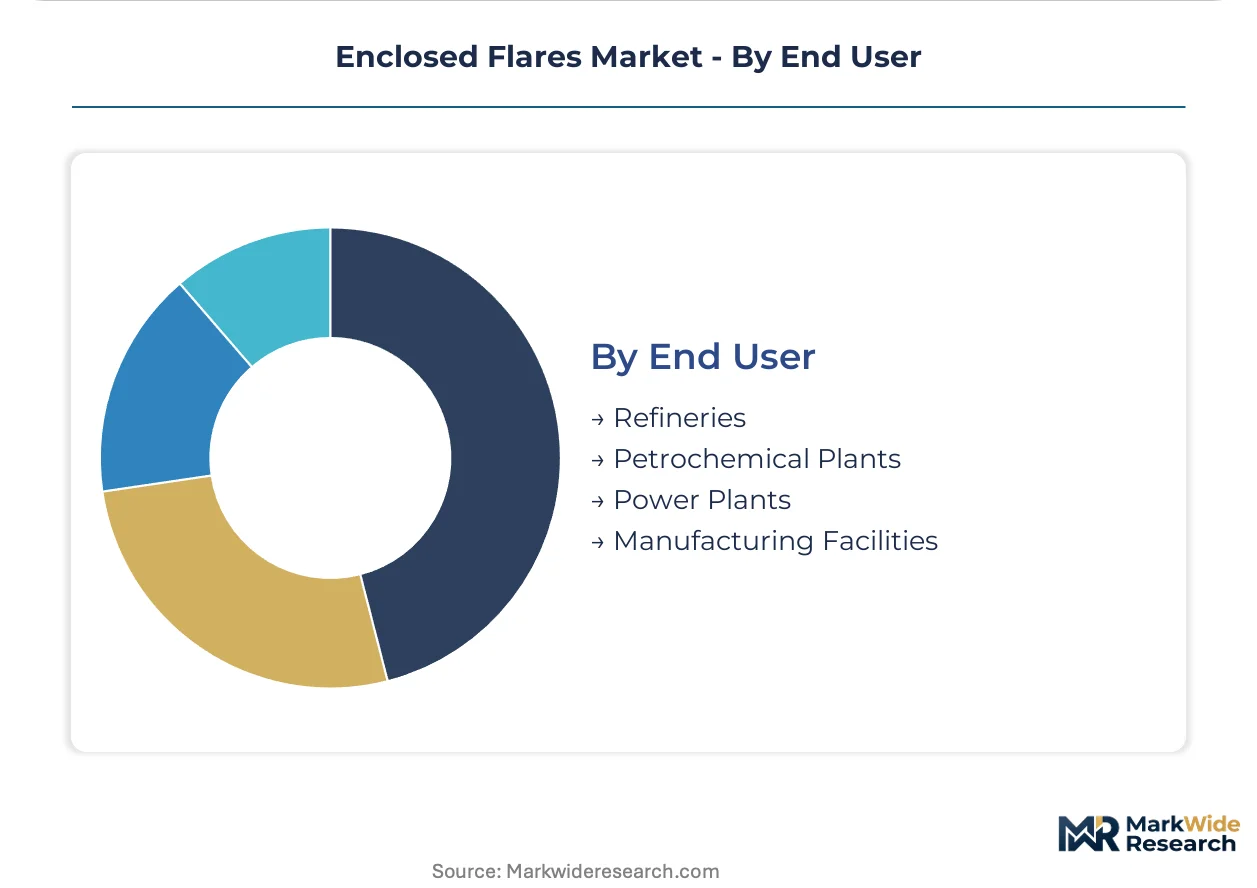
End user concentration reflects the geographic clustering of emission-intensive processing capacity.
- Refineries:Integrated oil majors consolidate vendor lists while accelerating consent decree-driven retrofits. US Gulf Coast refining corridors from Corpus Christi to Lake Charles concentrate procurement volume for high-H2S burner specifications.
- Petrochemical Plants:Ethylene crackers and aromatics complexes generate variable off-gas streams requiring flexible combustion systems. Ohio River Valley processors source spare burner tips through direct OEM channels, disintermediating bundled service agreements.
- Power Plants:Auxiliary fuel gas handling and startup venting applications.
- Manufacturing Facilities:Dispersed industrial boilers and coating operations with smaller unit scale.
Refineries anchor current procurement. Petrochemical Plants drive specification evolution for variable gas composition handling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Combustion engineering talent concentrates along the US Gulf Coast, with specialized expertise in high-H2S burner design clustering around Houston and Lake Charles. This workforce concentration shapes procurement patterns and vendor relationships across the enclosed flares value chain.
United States
EPA New Source Performance Standards enforcement accelerates refinery retrofit timelines across Texas and Louisiana processing corridors. The Texas Commission on Environmental Quality imposes 18-24 month air permit review cycles that stall equipment commissioning. Corpus Christi to Lake Charles refining clusters drive procurement volume for modular ground flare packages.
Canada
Alberta oil sands operators face provincial methane reduction mandates that expand enclosed flare deployment at upgrading facilities. Environment and Climate Change Canada regulations align with federal methane pricing mechanisms. Calgary-based engineering procurement concentrates on cold-climate combustion systems for northern extraction sites.
Germany
Chemical processing demand climbs as specialty producers face heightened benzene emission scrutiny under EU Industrial Emissions Directive. The Federal Immission Control Act mandates minimum destruction efficiency thresholds for hazardous air pollutants. BASF-Ludwigshafen and Bayer-Leverkusen chemical corridors specify thermal oxidizer systems with integrated heat recovery.
Saudi Arabia
Saudi Aramco's gas processing expansion creates demand for enclosed combustion at master gas system facilities. The Saudi Standards, Metrology and Quality Organization implements emission control regulations aligned with Vision 2030 environmental targets. Jubail Industrial City petrochemical complexes specify high-capacity ground flare systems for ethylene cracker off-gas handling.
China
Refinery capacity additions in Shandong and Guangdong provinces drive procurement of low-emission flare technologies. The Ministry of Ecology and Environment enforces volatile organic compound control standards under the Air Pollution Prevention and Control Law. Yangtze River Delta petrochemical processors upgrade open-flare infrastructure ahead of 2025 emission compliance deadlines.
Enclosed Flares Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct technology tiers. The vendor base organizes around three strategic archetypes: integrated combustion technology platforms with field service networks, modular package fabricators serving midstream infrastructure, and regional specialists anchored to specific industrial clusters. Competitive dynamics center on technology licensing partnerships and geographic expansion through local fabrication alliances.
Among US-based combustion technology providers, Zeeco and John Zink Hamworthy Combustion exemplify the integrated platform archetype with extensive Gulf Coast service infrastructure. MRW Technologies occupies a specialist position serving midstream compression station applications with rapid-deployment modular systems. These three companies represent distinct competitive vectors—technology leadership, service network density, and application-specific agility—rather than direct substitution relationships.
| Leading Market Players |
|---|
| Cimarron Energy |
| Fives ITAS |
| MRW Technologies |
| Zeeco |
| John Zink Hamworthy Combustion |
| Honeywell UOP |
| Encore Combustion |
| NAO |
| AEREON |
| Others |
Pricing and Supply Chain Analysis
Performance-grade bifurcation between thermal oxidizers with integrated heat recovery and standardized ground flare packages manifests in divergent margin structures and procurement channel configurations across the US Gulf Coast. EPA New Source Performance Standards enforcement compresses pricing power at the commodity tier while California carbon intensity scoring sustains premium positioning for high-efficiency systems.
Pricing Analysis
Capacity additions in modular ground flare fabrication along the Texas-Louisiana corridor are reshaping price floors for midstream compression station packages. Project-based pricing dominates engineered thermal oxidizers, while standardized ground flares trade on per-unit transactional terms. Price differentiation rests on EPA Subpart Ja compliance certification and after-sales field service bundling. Cost compression in refractory-lined chambers is intensifying because bauxite supply disruptions from Guinea squeeze input costs. Independent petrochemical operators in the Ohio River Valley exhibit highest price sensitivity, whereas integrated oil majors prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Freight costs for heavy-wall pressure vessels from US Gulf Coast fabrication clusters to Permian Basin installation sites amplify landed cost differentials against regional competitors. Manufacturing concentrates in the United States, China, and Germany. Supply chains draw from high-alumina ceramic refractories, specialty alloy steels, and precision burner components. Single-source vulnerability concentrates in hurricane-exposed Gulf Coast fabrication yards. Distribution runs through EPC contractors and direct OEM channels to refinery maintenance departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA methane fee structures and state-level carbon intensity scoring compound regulatory demand for enclosed flare retrofits, with consent decree enforcement compressing procurement timelines from five-year cycles to accelerated replacement windows.
For Market Incumbents: Deepen vertical integration into refractory material supply to defend margins against bauxite price volatility. Anchor field service network density across Permian Basin processing facilities to lock out modular specialists. Invest in high-H2S burner R&D as hydrogen blending in refinery fuel gas streams extends equipment lifecycle requirements.
For New Entrants and Emerging Players: Digital-channel routes through direct OEM spare parts platforms enable bypass of bundled service agreements that dominate Midwest independent refinery procurement. Target biogas upgrading facilities and landfill gas operations as underpenetrated segments where incumbent flare vendors lack application-specific expertise. Pursue rapid-deployment modular positioning for midstream compression station buildout.
For Investors and Strategic Acquirers: Consolidation pressure builds where combustion engineer scarcity concentrates specialized expertise among retiring practitioners. Five-to-ten-year viability favors vendors with integrated monitoring solutions attach rates rather than hardware-only sales. Watch California LCFS credit pricing as the inflection signal for thermal oxidizer demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Refractory Supply Integration | Captive sourcing from Guinea and Australian bauxite corridors insulates margin compression from ceramic input volatility. |
| Digital Twin Platform Development | CFD modeling combined with IoT sensor feeds enables predictive maintenance contracts at US Gulf Coast refineries. |
| California Market Expansion | LCFS credit monetization revalues thermal oxidizer installations at CARB-jurisdictioned facilities. |
| Midstream Modular Packaging | Standardized ground flare configurations suit Permian Basin custody transfer point deployment timelines. |
| Biogas Application Engineering | Landfill gas and anaerobic digestion odor control specifications open segments beyond oil and gas incumbency. |
Research Methodology
Bottom-up refinery and petrochemical plant modeling reconciled against top-down combustion equipment shipment tracking forms the analytical core of this study. Primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads combine with secondary validation from EPA enforcement databases, TCEQ air permit filings, SEC 10-K equipment supplier disclosures, and ACC industry reports. Triangulation across these sources ensures demand-side and supply-side estimates converge.
Historical trendline analysis of replacement cycle compression and regulatory enforcement intensity informs projection frameworks across the analysis window. Segmentation dimensions modeled include product type tier, application industry, technology integration level, and end-user concentration pattern. CAGRs derive from equipment procurement elasticity to methane fee structures and consent decree timelines. Forecast inputs incorporate refractory material cost trajectories and hydrogen blending adoption curves in refinery fuel gas systems.
Regulatory enforcement delays, bauxite supply disruption severity, and gas recovery economics displacement are the dominant revision risks to modeled outcomes. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Middle-East and Africa Liner Hanger System Market
Oil & Gas
Indonesia Oil and Gas Midstream Market
Oil & Gas
Middle-East Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Large Scale LNG Terminal Market
Oil & Gas
Gulf of Mexico Oil and Gas Upstream Market
Oil & Gas
Leak Detection for Oil & Gas Market
Oil & Gas
Crude Oil Desalter Market
Oil & Gas
North America Hydraulic Fracturing Fluids Market
Oil & Gas
Oman Directional Drilling Market
Oil & Gas
Oil and Gas Field Services Market
Oil & Gas
Europe Seismic Survey Market
Oil & Gas
Small Scale LNG Terminal Market
Oil & Gas
Asia Pacific Oil Storage Tank Service Market
Oil & Gas
United States Liner Hanger System Market
Oil & Gas
Flexible Pipes for Oil and Gas Market
Oil & Gas
Distributed Fiber Optic Sensor in Oil & Gas Market