
 Full Truck Load (FTL) Market | 2026-2036
Full Truck Load (FTL) Market Size, Share, and Industry Trends Forecast 2026-2036
Full Truck Load (FTL) Market Insights
FMCSA Compliance, Safety, Accountability scoring is unwinding competitive access for smaller carriers unable to invest in safety technology upgrades. J.B. Hunt Transport leverages its intermodal container fleet to anchor cross-border volume through Mexico manufacturing corridors. Knight-Swift Transportation Holdings sustains one of the largest refrigerated trailer pools in North America, dominating temperature-controlled FTL lanes. Schneider National specializes in dedicated contract carriage for automotive and consumer packaged goods shippers, occupying a defensible position in just-in-time supply chains.
Full truck load denotes motor carrier service where a single shipper contracts the entire capacity of a tractor-trailer unit, typically moving shipments exceeding ten thousand pounds or occupying more than half a trailer's cubic volume, with transit obligations governed by federally mandated hours-of-service limits and electronic logging device verification. The transportation mode dimension shows road freight commanding the value pool while intermodal rail-truck combinations capture the fastest expansion as fuel cost volatility pushes shippers toward multimodal optimization. Within load type, dry freight retains mature volume dominance but refrigerated segments concentrate margin premiums due to equipment scarcity and specialized driver certification requirements.
The US FMCSA enforces hours-of-service rules and electronic logging device mandates that directly constrain available driver capacity, while the EPA Phase 3 greenhouse gas standards force fleet operators toward aerodynamic retrofits or zero-emission powertrain investments. The Department of Transportation's infrastructure grant programs further shape lane economics by prioritizing corridor improvements along designated freight networks. Stakeholders must weigh capital allocation between compliance-driven equipment refresh cycles and digital freight matching platforms that promise asset utilization gains without expanding physical fleet footprints.
Market Dynamics
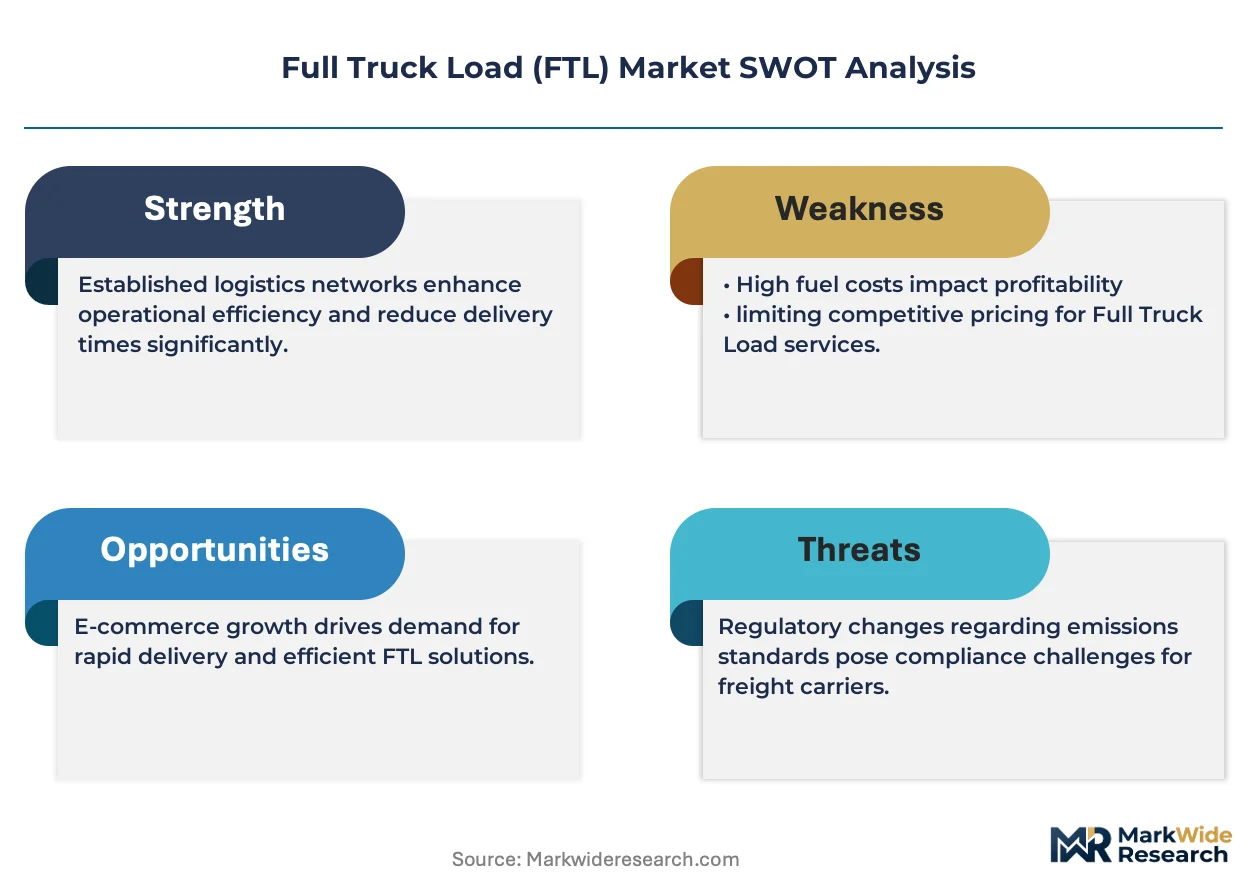
US EPA Phase 3 greenhouse gas standards are compressing fleet replacement cycles and forcing capital toward zero-emission powertrains, while FMCSA electronic logging device mandates constrain driver-hour availability and reshape lane economics.
Growth Catalysts
- E-commerce dedicated fleet contracts:Retailers are locking tractor-trailer capacity through multi-year agreements to secure coverage during peak fulfillment windows.
- Intermodal rail-truck optimization:Fuel cost volatility pushes shippers toward multimodal combinations that reduce highway mileage on long-haul corridors.
- Sun Belt manufacturing concentration:Industrial facility expansion across Texas through Georgia generates sustained outbound freight density.
Market Restraints
- Diesel price volatility:Fuel represents 25-30% of operating costs for asset-based carriers, compressing margins during price spikes.
- Driver supply concentration:Demographic constraints and CDL certification bottlenecks limit available operator hours.
- Zero-emission powertrain capital intensity:Battery-electric and hydrogen fuel cell tractors require 2-3x upfront investment versus diesel equivalents.
Strategic Opportunities
- Cross-border Mexico manufacturing corridors:Nearshoring trends generate northbound volume from Monterrey and Guadalajara industrial zones.
- Refrigerated equipment scarcity premiums:Specialized temperature-controlled trailers command rate multiples due to driver certification requirements and limited pool depth.
- Digital freight matching platforms:Algorithmic load-truck pairing promises asset utilization gains without physical fleet expansion.
Industry Challenges
- Hours-of-service compliance complexity:FMCSA regulations require real-time electronic logging with limited flexibility for unforeseen delays.
- Legacy dispatch system integration:Older transportation management software lacks API connectivity to modern visibility platforms.
- Aerodynamic retrofit certification timelines:EPA compliance modifications require extended shop time and engineering validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Full Truck Load (FTL) Market |
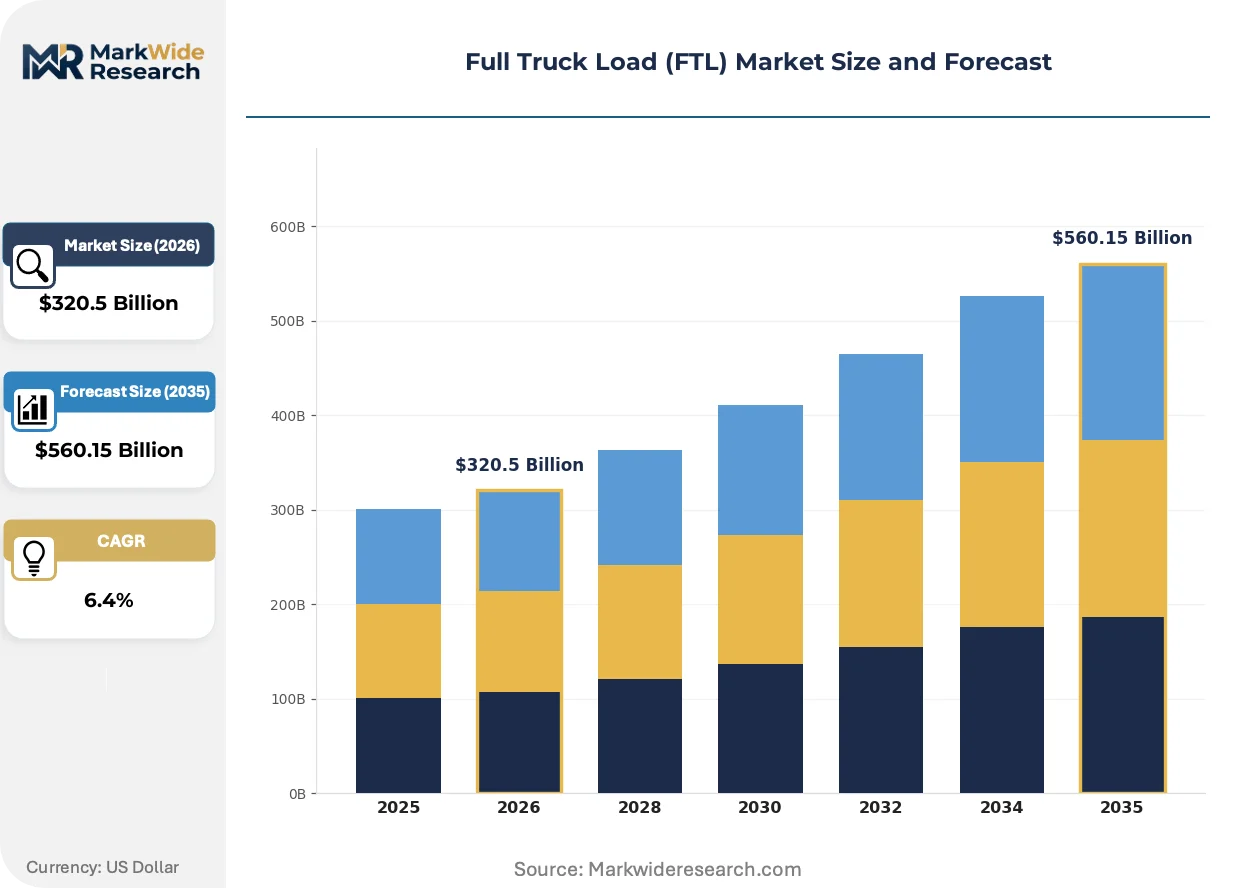
| Market Size in 2026 | $320.5 Billion |
| Market Size in 2035 | $560.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transportation Mode: Road, Rail, Intermodal, Water Contract Type: Dedicated, Spot, Bid, Time-Based Load Type: Dry Freight, Refrigerated, Liquid, Hazardous Materials Customer Type: Retailers, Manufacturers, Distributors, E-commerce |
| Companies Covered | C.H. Robinson, J.B. Hunt Transport, Knight-Swift Transportation Holdings, Landstar System, Ryder System, Schneider National, Werner Enterprises, ArcBest, TFI International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Full Truck Load (FTL) Market Trends and Innovations
Telematics and predictive analytics are rewriting how carriers price capacity and manage asset deployment, compressing the information advantage once held by large integrated networks.
Autonomous trucking technology is supplanting human-operated long-haul on designated freight corridors. Major retailers and consumer packaged goods shippers are piloting driverless lane segments between Dallas and Houston. This shift is compressing the wage cost structure that historically anchored carrier operating models.
EPA Phase 3 greenhouse gas standards mandate fleet-wide emissions reductions through model year 2032. The regulation forces operators toward aerodynamic tractor designs or zero-emission alternatives. Refrigerated and dedicated contract carriage segments face the steepest compliance costs due to equipment specialization.
Shipper procurement patterns are consolidating volume with fewer core carriers and demanding guaranteed capacity commitments. Large retailers now require dedicated fleet allocation during promotional windows. This concentration is most visible in automotive and consumer packaged goods verticals serving the US Southeast manufacturing belt.
Full Truck Load (FTL) Market Segmentation
FTL segmentation reveals how carrier asset allocation and shipper procurement strategies diverge across operational dimensions. Understanding these splits exposes where margin concentrates and which infrastructure investments yield utilization gains.
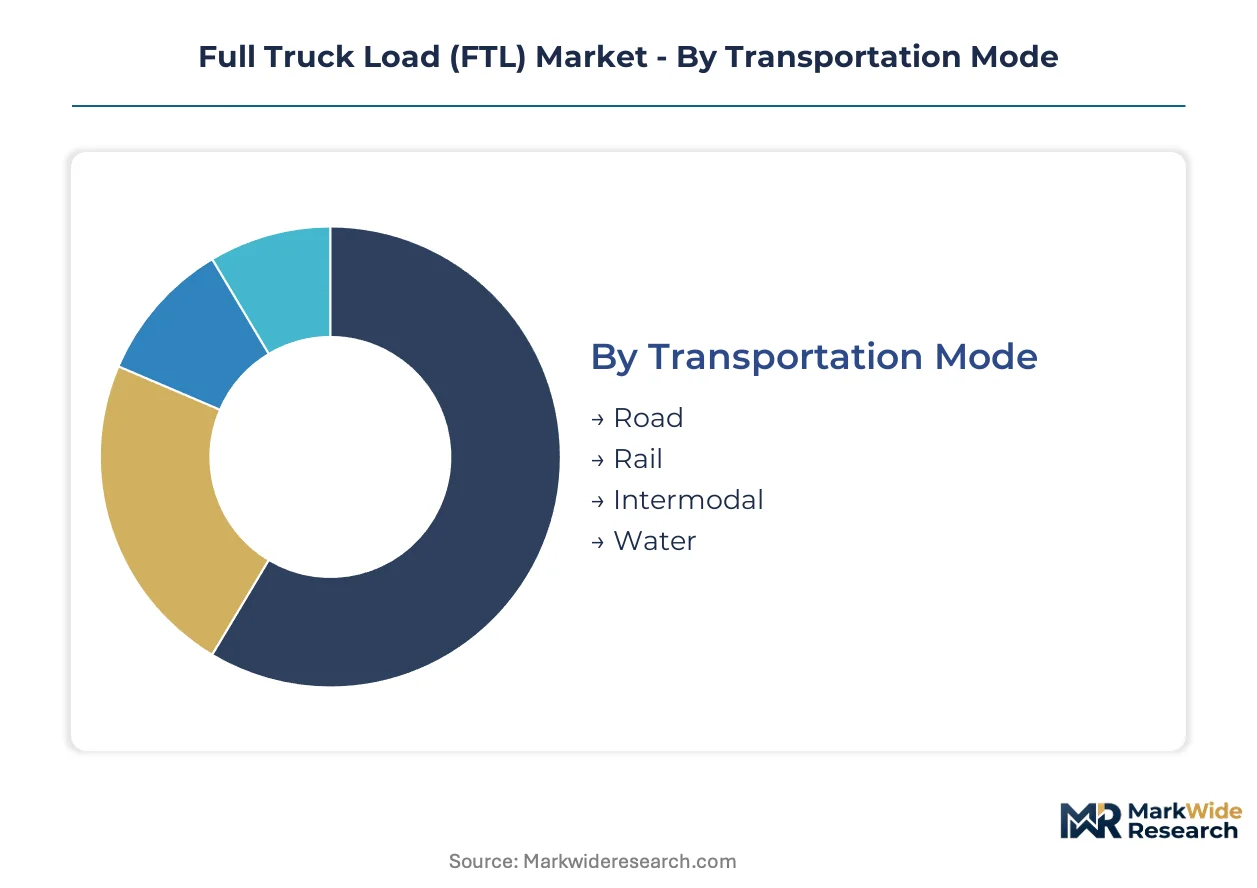
Transportation Mode:
Road freight dominates domestic lane economics while intermodal combinations capture cross-border and long-haul density.
- Road:Tractor-trailer units handle point-to-point delivery with maximum scheduling flexibility. US Sun Belt manufacturing corridors from Texas through Georgia generate sustained outbound road freight density as industrial facility expansion accelerates.
- Intermodal:Rail-truck combinations reduce highway mileage on corridors exceeding 500 miles. Fuel cost volatility pushes shippers toward multimodal optimization, particularly on lanes connecting Mexico manufacturing zones to US distribution centers.
- Rail:Bulk commodities and containerized freight move on dedicated track infrastructure. The mode captures economies of scale on fixed corridors with limited origin-destination flexibility.
- Water:Coastal and inland barge movements handle heavy project cargo and liquid bulk. Port congestion and modal handoff complexity limit FTL integration outside specialized chemical and agricultural supply chains.
Road holds the largest share; momentum sits with intermodal as fuel hedging becomes a procurement priority.
Contract Type:
Procurement structure determines revenue predictability and capital deployment horizons for asset-based carriers.
- Dedicated:Multi-year fleet allocation agreements guarantee capacity for single-shipper volume. Large retailers now require dedicated tractor-trailer allocation during promotional windows, compressing spot market participation.
- Spot:Transactional pricing responds to immediate capacity imbalances. Digital freight matching platforms algorithmically pair spot loads with available trucks, compressing broker margins.
- Bid:Annual or quarterly procurement events aggregate lane volume for competitive tender. Automotive and consumer packaged goods shippers concentrate bid volume with fewer core carriers.
- Time-Based:Hourly or daily rate structures align carrier compensation with actual asset utilization. The model gains traction in project logistics and seasonal peak coverage.
Dedicated contracts command the value pool; spot market digitization is climbing the fastest.
Load Type:
Equipment specialization creates tiered margin structures based on driver certification requirements and asset scarcity.
- Dry Freight:Standard van trailers handle non-temperature-sensitive general cargo. The segment retains mature volume dominance but faces rate compression from oversupply in core lanes.
- Refrigerated:Temperature-controlled units maintain cold chain integrity for food and pharmaceutical shipments. Specialized driver certification requirements and limited trailer pool depth command rate multiples.
- Liquid:Tank trailers transport chemicals, fuels, and food-grade products. EPA Phase 3 greenhouse gas standards force fleet operators toward aerodynamic retrofits or zero-emission powertrain investments.
- Hazardous Materials:Placarded equipment and certified operators handle regulated substances. FMCSA Compliance, Safety, Accountability scoring unwinds competitive access for smaller carriers unable to invest in safety technology upgrades.
Dry freight maintains volume leadership; refrigerated segments gain share fastest on e-commerce grocery expansion.
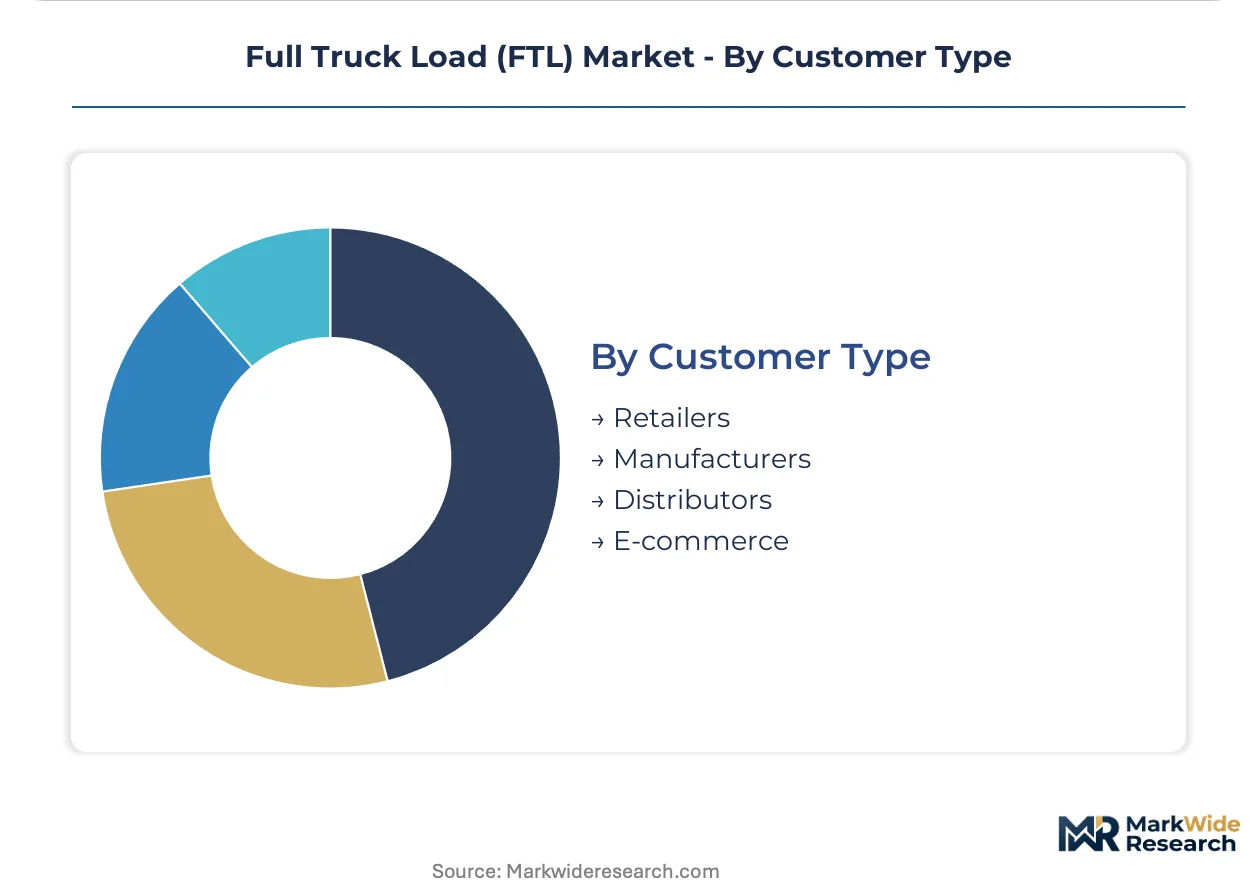
Customer Type:
End-user industry concentration shapes lane density patterns and seasonality exposure for carrier networks.
- Retailers:Big-box and grocery chains require synchronized inbound replenishment. E-commerce retailers are expanding dedicated fleet contracts to secure capacity during peak fulfillment windows.
- Manufacturers:Industrial shippers demand just-in-time delivery cadence tied to production schedules. Nearshoring trends generate northbound volume from Monterrey and Guadalajara industrial zones.
- Distributors:Wholesale intermediaries aggregate fragmented shipper demand into consolidated movements. Their procurement consolidates volume with fewer core carriers.
- E-commerce:Pure-play fulfillment networks prioritize speed over cost on final-mile injection. The segment drives intermodal rail-truck optimization as fuel cost volatility pushes shippers toward multimodal combinations.
Manufacturers anchor the largest contract value; e-commerce is expanding most quickly on fulfillment network buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Major retailers and automotive manufacturers concentrate procurement power across distinct freight corridors, shaping regional lane economics through dedicated fleet commitments and cross-border manufacturing integration.
United States
The US Sun Belt corridor from Texas through Georgia generates sustained outbound freight density as industrial facility expansion accelerates. EPA Phase 3 greenhouse gas standards compress fleet replacement cycles and force capital toward zero-emission powertrains. Dallas-Fort Worth anchors autonomous trucking pilots between Texas manufacturing zones.
Mexico
Nearshoring trends generate northbound volume from Monterrey and Guadalajara industrial zones serving US distribution centers. Cross-border manufacturing corridors benefit from intermodal rail-truck optimization reducing highway mileage. Nuevo León's automotive cluster drives dedicated contract carriage demand.
Canada
TFI International leverages domestic network density to capture cross-border volume into US Midwest distribution hubs. Transport Canada harmonizes electronic logging device mandates with US FMCSA standards. Ontario's manufacturing belt sustains just-in-time supply chain requirements.
Germany
EU Green Deal regulations accelerate fleet electrification timelines for international haulage operators serving Central European manufacturing. KBA enforces strict emissions certification for commercial vehicles. Bavaria's automotive supplier network demands synchronized inbound replenishment cadences.
China
Dual carbon goals under MEE oversight force logistics operators toward new energy commercial vehicle adoption. Yangtze River Delta manufacturing clusters generate high-volume FTL demand between Shanghai and inland production bases. MIIT standards reshape heavy-duty truck fleet composition.
Full Truck Load (FTL) Market Competitive Landscape
Player mix skews toward integrated asset-based carriers with intermodal capabilities and dedicated contract carriage specialization. Tiered concentration separates national networks with cross-border infrastructure from regional operators dependent on spot market participation. Strategic archetypes include intermodal-anchored integrators, temperature-controlled specialists, and digital freight platforms. Dominant competitive moves encompass dedicated fleet contract expansion and autonomous trucking corridor development.
Within the integrated carrier tier, J.B. Hunt Transport and Knight-Swift Transportation Holdings exemplify asset-heavy network operators with intermodal container fleet advantages. Schneider National occupies a position in dedicated contract carriage for automotive and consumer packaged goods verticals. These three represent the consolidation trajectory as shipper procurement concentrates volume with fewer core carriers.
| Leading Market Players |
|---|
| C.H. Robinson |
| J.B. Hunt Transport |
| Knight-Swift Transportation Holdings |
| Landstar System |
| Ryder System |
| Schneider National |
| Werner Enterprises |
| ArcBest |
| TFI International |
| Others |
Pricing and Supply Chain Analysis
Fleet scale economies concentrated among asset-heavy operators compress rate floors while amplifying pricing power on dedicated contract lanes. The US Sun Belt corridor from Texas through Georgia concentrates capacity deployment, shaping regional rate differentials as shippers compete for guaranteed tractor-trailer allocation during peak windows.
Pricing Analysis
Cost-plus contracts indexed to diesel fuel benchmarks dominate long-term dedicated agreements, insulating carriers from the 25-30% operating cost exposure that volatile petroleum prices impose. Price differentiation separates refrigerated temperature-controlled services from standard dry van capacity, with specialized driver certification requirements and limited trailer pools commanding rate multiples. Pricing pressure stems from spot market digitization as algorithmic freight matching platforms compress broker margins and accelerate rate discovery. E-commerce retailers demonstrate the lowest price sensitivity, prioritizing guaranteed capacity commitments over transactional savings during promotional fulfillment surges.
Supply Chain Analysis
US-Mexico border crossings at Laredo and Otay Mesa underwrite northbound manufacturing volume flows as nearshoring accelerates. Tractor manufacturing concentrates in Mexico, Tennessee, and Michigan, while trailer production clusters in Indiana, Ohio, and Texas. Raw material dependencies span steel coil from domestic mills, aluminum extrusions from Canadian smelters, and semiconductor components for telematics and electronic logging devices. Supply chain risk centers on single-source vulnerability for battery-electric powertrain components as EPA Phase 3 standards force fleet electrification timelines. Distribution runs through dedicated contract carriage networks, intermodal rail-truck terminals, and digital freight matching platforms algorithmically pairing spot loads with available assets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Full Truck Load market sits in early-cycle expansion as autonomous trucking pilots on designated freight corridors compress operating cost structures and reshape competitive economics. E-commerce fulfillment network buildouts and nearshoring-driven cross-border volume growth provide sustained adoption tailwinds for dedicated contract carriage and temperature-controlled specialization.
For Market Incumbents: Consolidate market position through dedicated fleet contract expansion with large retailers requiring guaranteed capacity during promotional windows, while accelerating zero-emission powertrain pilot programs to preempt EPA Phase 3 compliance cost shocks. Vertical integration into intermodal container ownership anchors cross-border lane economics against spot market volatility. For New Entrants and Emerging Players: Lead with digital freight matching platforms targeting the fragmented spot market where algorithmic load-truck pairing promises asset utilization gains without physical fleet investment. The most penetrable white space sits in refrigerated segment rate arbitrage, where specialized driver certification bottlenecks create persistent capacity scarcity and margin premiums. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors asset-heavy carriers with intermodal infrastructure and dedicated contract carriage specialization over pure-play digital brokers lacking physical network control. Long-term viability hinges on cross-border Mexico corridor access and autonomous trucking pilot participation. The signal to watch is FMCSA regulatory clarity on driverless operation permits, which would accelerate capital reallocation toward technology-enabled carriers.| Strategic Initiative | Industry Significance |
|---|---|
| Dedicated Fleet Contract Expansion | Multi-year capacity commitments with large retailers secure revenue predictability against spot market volatility. |
| Zero-Emission Powertrain Investment | Battery-electric and hydrogen fuel cell tractors preempt EPA Phase 3 compliance cost escalation. |
| Cross-Border Infrastructure Development | Intermodal terminals and customs-bonded facilities capture nearshoring volume from Monterrey manufacturing zones. |
| Autonomous Trucking Corridor Pilot | Driverless lane segments between Dallas and Houston compress wage cost structures in long-haul operations. |
| Refrigerated Capacity Specialization | Temperature-controlled trailer pools command rate multiples on e-commerce grocery expansion lanes. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with fleet operations directors, shipper procurement managers, intermodal terminal operators, and FMCSA compliance officers; and secondary validation through DOT freight statistics, EPA regulatory filings, carrier SEC 10-K disclosures, and customs trade data on US-Mexico cross-border movements. Bottom-up triangulation across carrier fleet counts and top-down reconciliation with national freight tonnage estimates anchored volume and value sizing.
Across the projection horizon, the analytical framework modeled segmentation dimensions including transportation mode, contract type, load type, and customer vertical, with CAGRs derived from regression analysis against industrial production indices and e-commerce fulfillment growth curves. Forecast inputs incorporated EPA Phase 3 compliance cost trajectories, autonomous trucking technology adoption curves, and Sun Belt manufacturing facility expansion pipelines.
The analysis sits within stated boundaries; outcomes outside sustained nearshoring momentum, stable diesel price regimes, or permissive autonomous vehicle regulatory frameworks would require recalibration. Forecasts reflect documented assumptions around driver supply demographics and equipment replacement cycles. Practitioners should keep alternative scenarios live as FMCSA hours-of-service enforcement intensity and zero-emission powertrain Total Cost of Ownership parity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Global Oversized Cargo Transportation Market
Heavy-Duty Trucks
Vacuum Truck Market
Heavy-Duty Trucks
Egypt Trucks Market
Heavy-Duty Trucks
Truck Tank Market
Heavy-Duty Trucks
Heavy-Truck Composite Component Market
Heavy-Duty Trucks
China Full-Truck-Load (FTL) Market
Heavy-Duty Trucks
Global Snow Sweeper Truck Market
Heavy-Duty Trucks
Platooning Trucks Market
Heavy-Duty Trucks
Garbage Collection Trucks Market
Heavy-Duty Trucks
Dump Trucks Market
Heavy-Duty Trucks
North America Vacuum Truck Market
Heavy-Duty Trucks
US Tanker Truck Market
Heavy-Duty Trucks
Airport Catering Truck Market
Heavy-Duty Trucks
Dump Truck & Body Market
Heavy-Duty Trucks
Articulated Hauler Market
Heavy-Duty Trucks
India Vacuum Truck Market