
 Medium and Heavy Duty Commercial Vehicles (MHCV) Market | 2026-2036
Medium and Heavy Duty Commercial Vehicles (MHCV) Market Size, Share, and Industry Trends Forecast 2026-2036
Medium and Heavy Duty Commercial Vehicles (MHCV) Market Insights
Certified diesel-engine technicians is bifurcating the competitive landscape between legacy manufacturers and electrification entrants. Daimler Truck AG leverages its captive vocational training network to sustain production velocity across European plants. Tata Motors Limited anchors its South Asian position through in-house engine casting and axle manufacturing. PACCAR Inc competes in North American sleeper-cab segments with modular platform architectures that reduce assembly complexity.
Medium and heavy duty commercial vehicles span gross vehicle weight ratings above 3.5 tonnes, incorporating ladder-frame chassis, multi-leaf or air suspension systems, and powertrains delivering 150–600 hp for sustained loaded operation across interstate corridors and jobsites. Trucks dominate unit economics in freight corridors, while electric powertrains represent the fastest-growing engine category as battery energy density improves and charging infrastructure densifies along logistics corridors. Construction and logistics applications concentrate the largest revenue pools, with tippers commanding premium pricing in mining-heavy geographies.
The EPA and NHTSA coordinate greenhouse-gas and fuel-economy standards that dictate engine calibration and aerodynamic package requirements for US-registered vehicles, while the EU's CO2 emission performance standards for heavy-duty vehicles mandate fleet-average reductions that accelerate powertrain diversification. India's BIS certification and axle-load norms reshape domestic product specifications and import eligibility. Stakeholders must calibrate capital allocation between ICE refinement and battery-electric platform development as regulatory compliance timelines compress and total-cost-of-ownership equations shift.
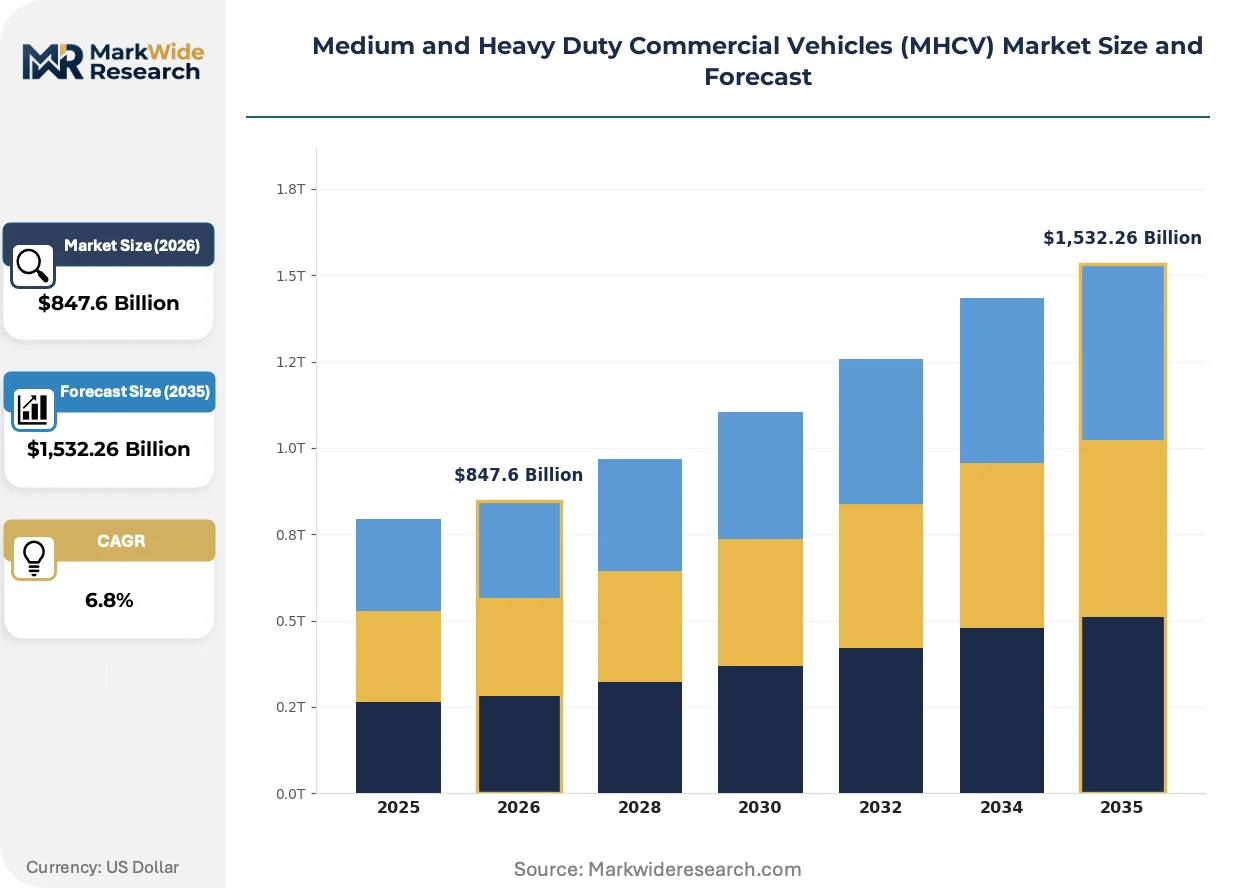
Market Dynamics
Connected truck architectures and battery-electric powertrains are bifurcating capital allocation across legacy manufacturers and electrification entrants, compressing product development cycles while expanding compliance burdens from multi-jurisdictional emission regimes.
Growth Catalysts
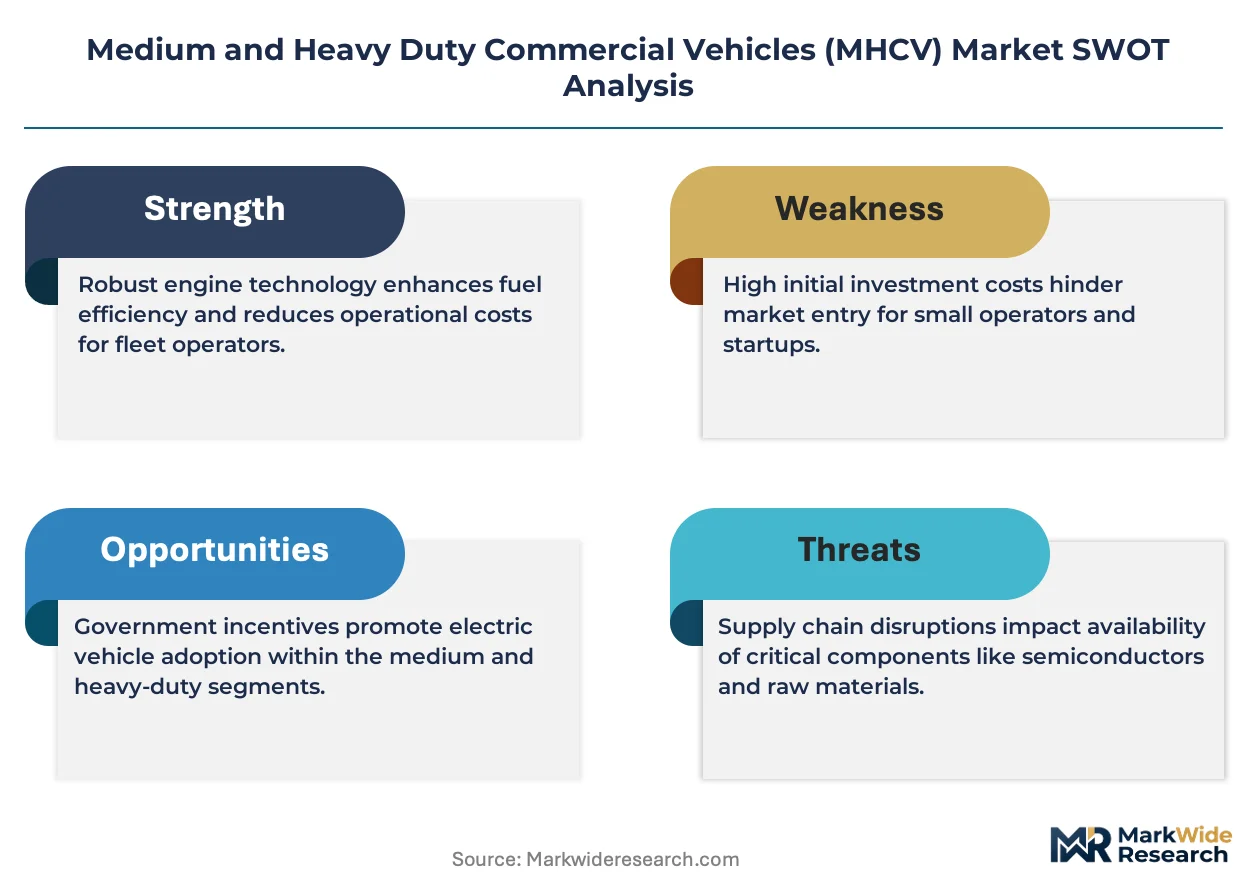
- EU CO2 Performance Standards:Fleet-average emission mandates for heavy-duty vehicles accelerate powertrain diversification and R&D spending across European manufacturing bases.
- China battery energy density improvements:Cell chemistry advances enable 500+ km range for electric tractors on long-haul corridors, unlocking fleet electrification at scale.
- Construction vertical demand:Mining and infrastructure tippers command premium pricing in resource-intensive geographies, sustaining high-margin order backlogs.
Market Restraints
- Lithium and cobalt price volatility:Raw material input swings compress battery pack margins and destabilize electric vehicle total-cost-of-ownership calculations.
- Certified diesel-technician scarcity:Vocational training pipeline gaps constrain service network expansion and warranty resolution velocity.
- Charging infrastructure deserts:Sparse high-power charging along interstate freight corridors limits electric truck deployment to return-to-base applications.
Strategic Opportunities
- India BIS compliance services:Emission certification and axle-load norm advisory creates recurring revenue streams for engineering consultancies.
- Battery leasing and energy-as-a-service:Asset-light ownership models reduce fleet operator capex barriers to electric adoption.
- Telematics and predictive maintenance convergence:Connected vehicle data monetization opens software revenue pools adjacent to hardware sales.
Industry Challenges
- High-voltage technician certification timelines:EV safety training programs lag production ramp schedules, throttling service capacity.
- Platform integration complexity:Modular architectures must reconcile legacy ICE supply chains with electric axle and battery pack sourcing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medium and Heavy Duty Commercial Vehicles (MHCV) Market |
| Market Size in 2026 | $847.6 Billion |
| Market Size in 2035 | $1,532.26 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Trucks, Buses, Trailers, Tippers Engine Type: Diesel, CNG, LNG, Electric Application: Construction, Logistics, Public Transport, Waste Management End User: Fleet Operators, Government Agencies, Private Enterprises, NGOs |
| Companies Covered | Tata Motors Limited, Isuzu Motors Limited, PACCAR Inc, Iveco S.p.A., Scania AB, Daimler Truck AG, Traton SE, Ashok Leyland Limited, Volvo Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medium and Heavy Duty Commercial Vehicles (MHCV) Market Trends and Innovations
Powertrain electrification, regulatory compliance automation, and fleet data monetization are compressing traditional vehicle lifecycle economics and reshaping stakeholder value capture mechanisms.
Modular battery pack architectures are decomposing proprietary powertrain integration. Logistics fleet operators in Germany and the Netherlands are specifying swappable cell configurations to match route profiles. This standardization pressure is fragmenting supplier hierarchies and eroding captive component margins.
EPA and NHTSA coordinated greenhouse-gas standards are recalibrating engine calibration investments. US-registered heavy-duty vehicles now require integrated aerodynamic packages and predictive cruise control. Sleeper-cab segments bear the steepest compliance cost increases, accelerating pre-buy cycles ahead of rule phase-ins.
Long-haul fleet operators are consolidating procurement around total-cost-of-ownership metrics rather than sticker price. Leasing subsidiaries and captive finance arms are displacing traditional bank lending in European markets. This shift concentrates buyer power among mega-fleets and compresses residual value risk onto manufacturers.
Medium and Heavy Duty Commercial Vehicles (MHCV) Market Segmentation
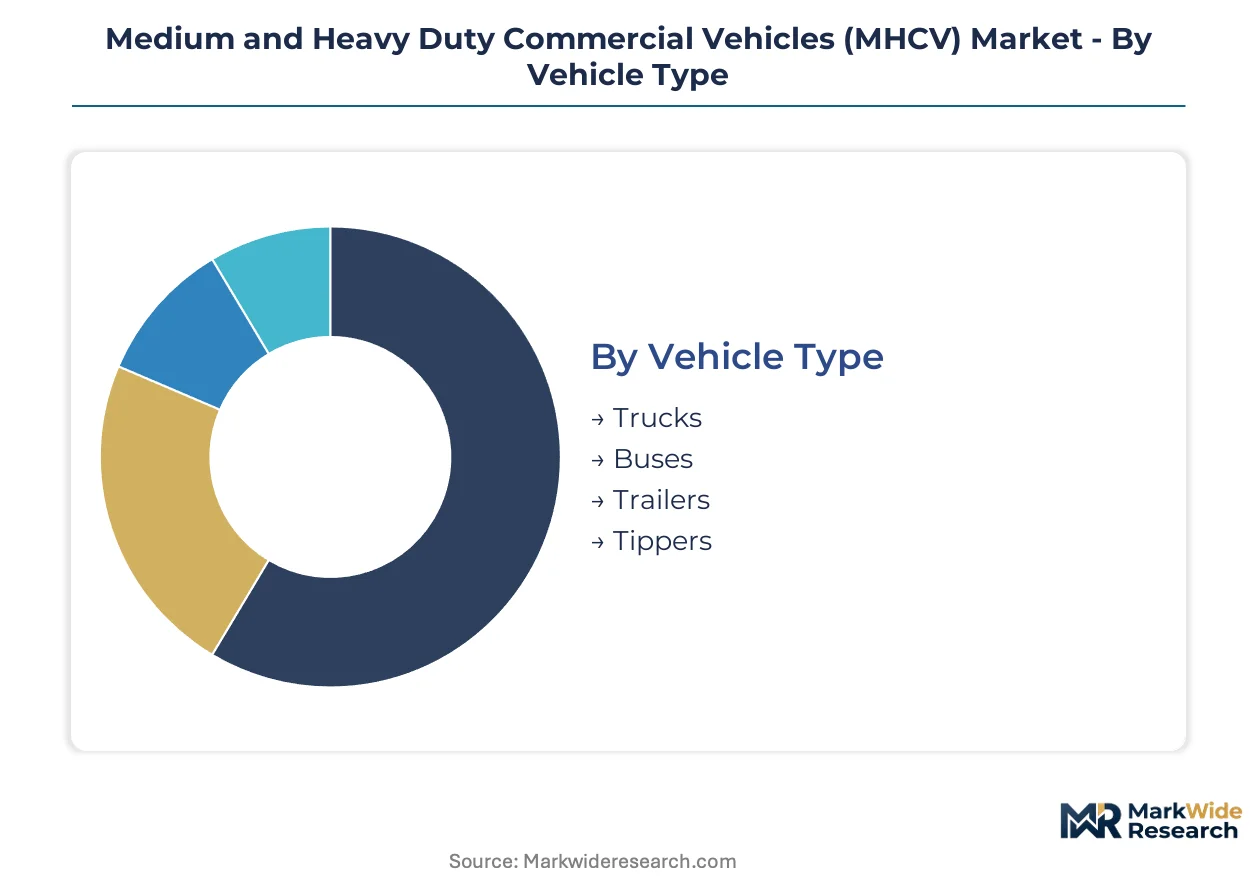
Segmentation in the MHCV market determines procurement patterns, regulatory compliance pathways, and service network design. Fleet operators calibrate specifications across vehicle weight, fuel type, and duty cycle to optimize total-cost-of-ownership equations.
Vehicle Type:
Trucks dominate domestic production volumes across India, Germany, and the United States. Buses and tippers concentrate export-led demand corridors into mining-intensive economies.
- Trucks:Tractor-trailers and rigid trucks incorporate ladder-frame chassis rated for 16–44 tonne gross vehicle weights. Demand concentrates in long-haul logistics corridors connecting the Port of Rotterdam to German industrial clusters, driven by EU CO2 fleet-average mandates accelerating aerodynamic package adoption.
- Buses:Intercity coaches and transit buses utilize low-floor architectures with compressed natural gas or battery-electric powertrains. Procurement localizes around municipal transport authorities in Paris, London, and São Paulo, constrained by charging infrastructure deployment timelines and depot retrofit costs.
- Trailers:Skeletal, flatbed, and refrigerated variants extend payload capacity without powertrain integration.
- Tippers:Mining and construction dump bodies command premium pricing in resource-extractive geographies.
Trucks command the established base. The steepest expansion runs through tippers in infrastructure-intensive developing markets.
Engine Type:
Cost tiers separate established diesel platforms from emerging electric architectures requiring capital-intensive battery pack integration.
- Diesel:Compression-ignition engines deliver 150–600 hp through common-rail fuel injection and selective catalytic reduction aftertreatment. Production volumes concentrate at Daimler Truck AG plants in Germany and Tata Motors facilities in India, constrained by certified technician scarcity and tightening EPA NHTSA emission calibrations.
- Electric:Battery-electric powertrains integrate permanent-magnet synchronous motors with 300–600 kWh pack configurations. Demand clusters in Shenzhen logistics hubs and Dutch distribution corridors, enabled by cell chemistry advances pushing range beyond 500 kilometers.
- CNG:Spark-ignited compressed natural gas engines serve urban freight with lower particulate emissions.
- LNG:Liquefied natural gas suits long-haul corridors with cryogenic tank storage extending range.
Diesel retains the volume base. Electric configurations are climbing the fastest as battery energy density improvements compress total-cost-of-ownership gaps.
Application:
Customer maturity varies sharply: construction and logistics operate on established replacement cycles, while waste management electrification remains nascent.
- Construction:Tippers and concrete mixers require reinforced suspensions and all-terrain axle configurations. Demand localizes around mining belts in Western Australia and infrastructure corridors in India's National Highway Development zones, driven by public capital expenditure commitments and mineral commodity pricing.
- Logistics:Tractor-trailers and box trucks prioritize aerodynamic efficiency and telematics integration. Fleet procurement concentrates among German supermarket chains and US e-commerce distributors, constrained by driver shortage pressures and sleeper-cab regulatory compliance costs.
- Public Transport:Transit buses and coaches serve municipal route networks with accessibility mandates.
- Waste Management:Refuse collection vehicles utilize low-entry cabs and automated lifting mechanisms.
Logistics commands the established base. Construction applications are gaining share fastest in resource-intensive geographies.
End User:
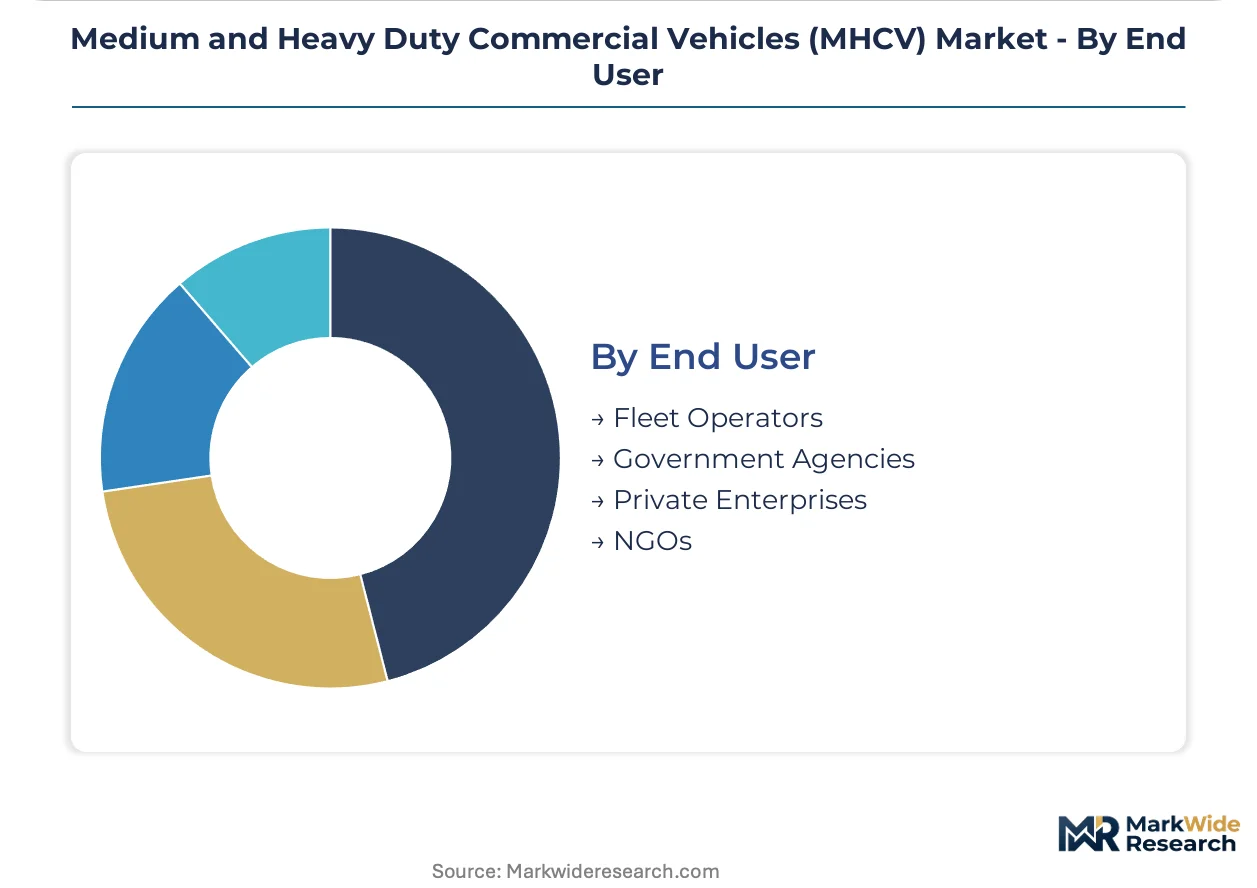
Procurement scale separates mega-fleet operators with captive financing from fragmented private enterprise purchasing.
- Fleet Operators:Logistics companies and leasing subsidiaries consolidate procurement around total-cost-of-ownership metrics. Contract concentration occurs at German supermarket chains and US parcel carriers, driven by EU CO2 fleet mandates and predictive maintenance data monetization opportunities.
- Government Agencies:Municipal transport authorities and defense procurement offices specify domestic content requirements. Orders localize around state-owned operators in Delhi and São Paulo, constrained by fiscal capacity and BIS certification timelines.
- Private Enterprises:Construction contractors and manufacturers operate smaller fleet sizes with decentralized purchasing.
- NGOs:Humanitarian and development organizations deploy specialized vehicle configurations for remote access.
Fleet operators command the established base. Government agencies are expanding most quickly as electrification mandates deepen public procurement commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. European fleet operators prioritize aerodynamic compliance packages for long-haul corridors. Indian buyers emphasize axle-load durability for rough infrastructure. Chinese logistics firms demand extended-range electric configurations for urban distribution networks.
United States
Long-haul freight corridors dominate procurement, with sleeper-cab tractors absorbing compliance investments for EPA and NHTSA coordinated greenhouse-gas standards. The Port of Los Angeles-to-Chicago rail-truck intermodal corridor concentrates electrification pilots. Detroit-based manufacturing clusters refine engine calibration for 2027 emission phase-ins.
Germany
EU CO2 fleet-average mandates accelerate powertrain diversification across the Rhine-Ruhr industrial belt. Daimler Truck AG anchors production velocity through captive vocational training networks. Stuttgart engineering consultancies monetize compliance advisory for cross-border logistics operators.
China
Shenzhen logistics hubs drive battery-electric tractor demand as cell chemistry advances push range beyond 500 kilometers. MIIT emission standards and dual carbon goals compress diesel platform timelines. Yangtze River Delta manufacturing clusters integrate permanent-magnet synchronous motors at scale.
India
Infrastructure tippers command premium pricing across National Highway Development zones. BIS certification and axle-load norms reshape domestic specifications and import eligibility. Jamshedpur and Pune industrial corridors sustain in-house engine casting and axle manufacturing capabilities.
Brazil
Mining belts in Minas Gerais sustain high-margin tipper order backlogs for resource-extractive operations. ANVISA and environmental licensing constraints extend procurement cycles for foreign manufacturers. São Paulo logistics clusters consolidate fleet procurement around total-cost-of-ownership metrics.
Medium and Heavy Duty Commercial Vehicles (MHCV) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive component manufacturing and modular platform architectures separating scale players from regional assemblers. The upper tier commands sleeper-cab and long-haul segments through backward integration into powertrain casting and vocational training networks. Strategic archetypes include European engineering-led conglomerates, Asian cost-optimized volume producers, and North American modular-platform specialists. Competitive moves concentrate on M&A for electric axle and battery pack sourcing, plus geographic expansion through localized assembly joint ventures.
Among European-based manufacturers, Daimler Truck AG and Volvo Group occupy positions within the integrated engineering tier, anchoring compliance-heavy segments through captive supply chains. Tata Motors Limited represents the Asian volume-optimized archetype, with in-house component manufacturing sustaining cost discipline across price-sensitive developing markets. PACCAR Inc exemplifies the North American modular-platform approach, reducing assembly complexity through standardized architectures across sleeper-cab configurations.
| Leading Market Players |
|---|
| Tata Motors Limited |
| Isuzu Motors Limited |
| PACCAR Inc |
| Iveco S.p.A. |
| Scania AB |
| Daimler Truck AG |
| Traton SE |
| Ashok Leyland Limited |
| Volvo Group |
| Others |
Pricing and Supply Chain Analysis
Battery cell chemistry substitution for diesel engine blocks is redrawing procurement geography from Stuttgart and Jamshedpur toward Yangtze River Delta gigafactories, simultaneously compressing powertrain margins and inflating logistics costs for European and Indian assemblers.
Pricing Analysis
Long-term offtake contracts dominate fleet procurement in German supermarket chains and US parcel networks, while spot-market transactions persist for construction tippers in mining belts. Three-tier pricing structure across premium aerodynamic packages, standard sleeper cabs, and economy rigid trucks separates EU CO2-compliant configurations from BIS-certified Indian models. Price differentiation hinges on certification grade and volume scale, with mega-fleets extracting double-digit discounts unavailable to fragmented private enterprises. Cost compression in battery-electric segments is intensifying because lithium and cobalt price volatility destabilizes total-cost-of-ownership calculations. Government agencies exhibit lowest price sensitivity due to domestic content mandates, while private construction contractors face acute margin pressure.
Supply Chain Analysis
Strategic stockpiling of battery cells and permanent-magnet materials is displacing just-in-time engine component flows as Chinese, South Korean, and Japanese suppliers consolidate cathode and anode production. Raw material dependencies center on lithium carbonate from Chile and Australia, cobalt from the Democratic Republic of Congo, and rare-earth elements from Chinese processing facilities. Single-source vulnerability in high-voltage inverter semiconductors threatens European electric axle ramp schedules. Distribution runs through captive leasing subsidiaries in Germany, OEM-direct channels in India, and independent dealer networks across North American sleeper-cab markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of certified high-voltage technicians and vocational training capacity is constraining service network expansion, creating defensive moats for incumbents with captive apprenticeship pipelines while raising entry barriers for battery-electric specialists.
For Market Incumbents: Compound backward integration into battery pack assembly and electric axle manufacturing to secure supply continuity against Chinese cell chemistry dominance. Deepen captive vocational training networks in Germany and India to sustain warranty resolution velocity as high-voltage technician certification timelines lag production ramps. Prioritize modular platform architectures that reconcile legacy ICE supply chains with electric powertrain sourcing. For New Entrants and Emerging Players: Lead with battery leasing and energy-as-a-service models to reduce fleet operator capex barriers in return-to-base logistics applications. Target Indian BIS compliance advisory and emission certification services as recurring revenue white space. Penetrate through telematics convergence partnerships that monetize predictive maintenance data adjacent to hardware sales. For Investors and Strategic Acquirers: The market sits at a powertrain transition phase that favors engineering-led conglomerates with captive component manufacturing over pure-play assemblers. Long-term viability rests on platform integration capabilities spanning ICE refinement and battery-electric development. Monitor charging infrastructure deployment velocity along interstate freight corridors as the inflection signal for long-haul electrification scalability. Revision becomes warranted when high-power charging density crosses thresholds that unlock 500-kilometer electric tractor economics.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Cell chemistry partnerships with Yangtze River Delta suppliers secure cathode capacity for EU CO2 compliance. |
| Platform Standardization | Modular architectures reduce assembly complexity across Daimler Truck AG's European sleeper-cab configurations. |
| Software-Defined Vehicle Investment | Telematics integration enables predictive maintenance monetization for German supermarket fleet operators. |
| Geographic Manufacturing Footprint | Localized Jamshedpur and Pune production satisfies India's BIS axle-load norms and domestic content requirements. |
| Charging Infrastructure Partnership | High-power corridor deployment unlocks electric tractor range for Shenzhen logistics hub operations. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fleet procurement directors, OEM platform engineers, Tier 1 supplier account managers, and aftermarket service heads; and secondary validation through vehicle production databases, IHS Markit registration data, EPA and NHTSA emission filings, EU CO2 fleet monitoring reports, and MIIT standard disclosures. Bottom-up unit economics modeling triangulated against top-down macroeconomic projections.
Across the projection horizon, the analytical framework modeled volume and value trajectories by vehicle class, propulsion architecture, application vertical, and regional production cluster. CAGRs were derived from replacement cycle analysis, regulatory compliance timeline compression, and battery energy density improvement curves. Forecast inputs incorporated fleet operator total-cost-of-ownership sensitivity thresholds and charging infrastructure deployment schedules.
Forecasts assume regulatory continuity in EPA NHTSA coordinated standards, EU CO2 performance mandates, and India BIS certification regimes; material policy shifts would require re-modeling. Specific risks include lithium price volatility, high-voltage technician training pipeline gaps, and charging infrastructure desert persistence along long-haul corridors. Revision becomes warranted when battery pack cost curves cross total-cost-of-ownership parity thresholds against diesel platforms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
China Full-Truck-Load (FTL) Market
Heavy-Duty Trucks
Global Oversized Cargo Transportation Market
Heavy-Duty Trucks
Vacuum Truck Market
Heavy-Duty Trucks
Logging Trucks Market
Heavy-Duty Trucks
Global Boom Truck Market
Heavy-Duty Trucks
Europe Medium and Heavy-Duty Commercial Vehicles Market
Heavy-Duty Trucks
Dump Truck & Body Market
Heavy-Duty Trucks
Garbage Truck Bodies Market
Heavy-Duty Trucks
Automotive High Performance Trucks Market
Heavy-Duty Trucks
Flatbed Truck Market
Heavy-Duty Trucks
Truck Diagnostic Market
Heavy-Duty Trucks
Hydrogen Trucks Market
Heavy-Duty Trucks
Full Truck Load (FTL) Market
Heavy-Duty Trucks
Europe Medium & Heavy-Duty Truck Rental Market
Heavy-Duty Trucks
Dump Trucks Market
Heavy-Duty Trucks
Truck Headache Rack Market