
 Tipper Truck Market | 2026-2036
Tipper Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Tipper Truck Market Outlook
India is tilting toward expanded tipper production capacity as domestic infrastructure outlays strain existing fleet supply. Daimler Truck AG leverages its BharatBenz manufacturing footprint to anchor medium-duty tipper output for South Asian contractors. Tata Motors Ltd. dominates the sub-15-ton segment through deep distribution into tier-two and tier-three construction markets. AB Volvo competes on premium articulated tippers for mining operators demanding higher payload efficiency.
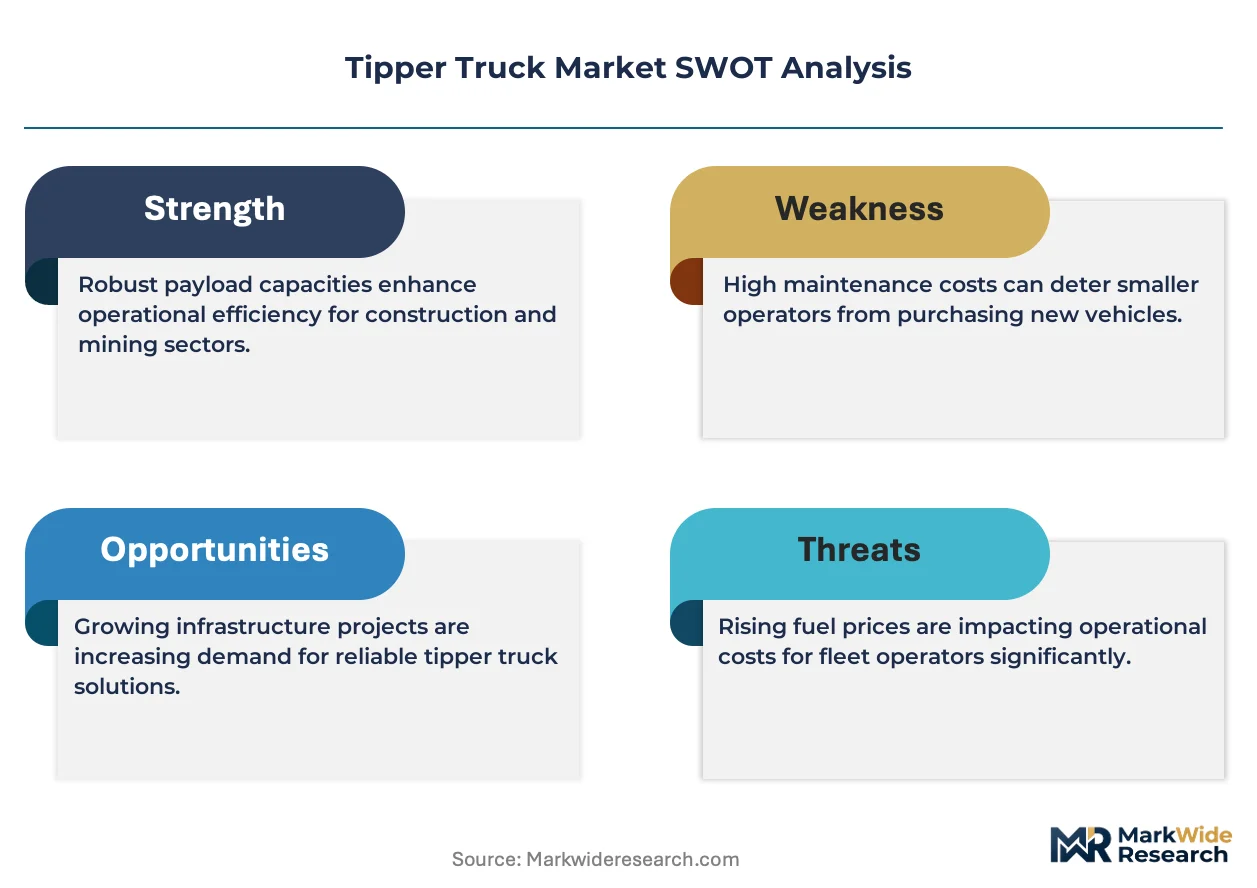
A tipper truck employs a hydraulically actuated cargo bed that elevates at the front to discharge loose materials such as sand, gravel, ore, or demolition waste through gravity flow; chassis designs integrate high-tensile steel frames with reinforced suspension systems rated for repeated shock loading in off-highway conditions. Standard tippers occupy the mature volume tier where margin compression from commodity chassis competition limits differentiation, while articulated tippers concentrate margin pools in mining applications where payload-to-weight ratios determine fleet economics. Electric engine variants within the 5-10 ton payload band represent the fastest-growing configuration as urban construction zones impose zero-emission access rules.
India's CEA enforces axle-load norms that reshape chassis engineering for domestic tipper manufacturers, while the EU's F-Gas Regulation and Euro VII proposals constrain diesel powertrain continuity across European export markets. China's MIIT administers dual carbon compliance timelines that accelerate NEV tipper certification requirements for domestic OEMs. Stakeholders must monitor how divergent emission enforcement timelines across India, Europe, and China fragment platform development budgets and supplier qualification pathways.
Market Dynamics
Powertrain electrification is fragmenting platform development budgets as OEMs engineer parallel diesel, hybrid, and battery-electric architectures to satisfy divergent emission enforcement timelines across India, Europe, and China.
Growth Catalysts
- India's state-level infrastructure corridors:Aggregate transport demand from highway and dam construction is accelerating fleet replacement cycles in Maharashtra, Karnataka, and Uttar Pradesh.
- Euro VII emission proposals:Anticipated NOx and particulate limits are forcing European mining operators to pre-order compliant tippers ahead of enforcement deadlines.
- High-tensile steel chassis engineering:Advanced metallurgy is extending service intervals for off-highway articulated units operating in Australian iron ore and South African platinum belts.
Market Restraints
- Lithium-ion cell supply concentration:Battery raw material processing dominance in China creates input cost volatility for electric tipper programs.
- Axle-load compliance engineering:India's CEA norms mandate structural reinforcement that adds tare weight and compresses payload capacity.
- Hydraulic system substitution:Electric actuation for dump mechanisms threatens incumbent hydraulic component suppliers.
Strategic Opportunities
- Urban zero-emission zones:London, Berlin, and Shenzhen congestion rules create demand for 5-10 ton electric tippers in metropolitan construction logistics.
- Remanufactured powertrain programs:Circular economy incentives under EU Green Deal funding enable lower-cost fleet modernization for mid-tier contractors.
- Telematics and payload optimization convergence:Real-time weight monitoring fused with route algorithms is opening subscription revenue streams for OEMs.
Industry Challenges
- High-voltage technician scarcity:Electric tipper maintenance requires certified specialists that mining and construction fleet operators struggle to recruit.
- Dual certification timelines:Parallel homologation for Euro VI, China's MIIT NEV standards, and India's AIS norms fragments engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tipper Truck Market |
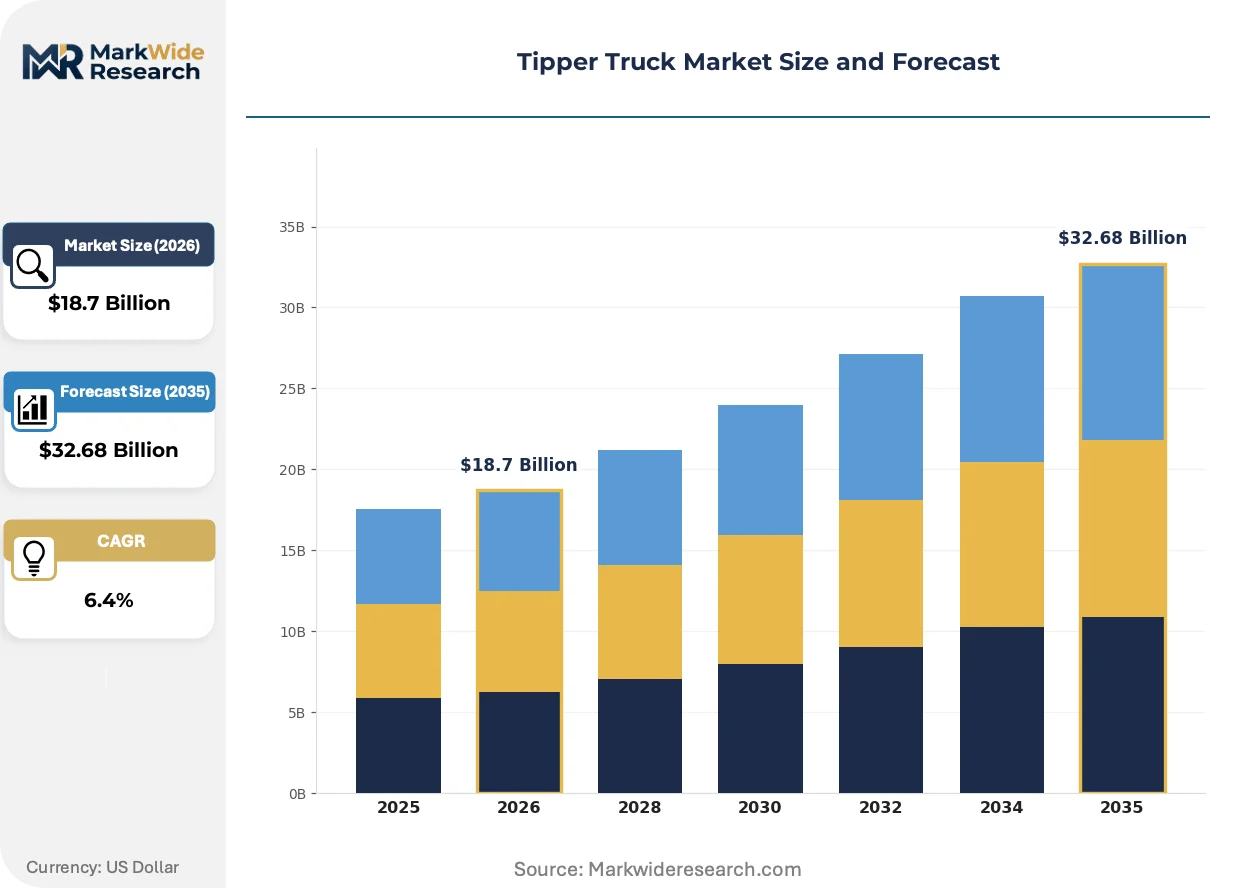
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Tipper, Semi-Tipper, Articulated Tipper, Mini Tipper End User: Construction, Mining, Agriculture, Waste Management Payload Capacity: Under 5 Tons, 5-10 Tons, 10-15 Tons, Above 15 Tons Engine Type: Diesel, Electric, Hybrid, Gasoline |
| Companies Covered | MAN Truck & Bus AG, Iveco Group N.V., Daimler Truck AG, Hino Motors, Ltd., Isuzu Motors Limited, AB Volvo, Scania AB, Tata Motors Ltd., PACCAR Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tipper Truck Market Strategic Shifts
Electrification, digital integration, and material science advances are compressing traditional product lifecycles and forcing OEMs to restructure R&D allocation across combustion and zero-emission platforms simultaneously.
Integrated battery-electric powertrains with modular pack architectures are rendering obsolete the conventional diesel-hydraulic tipper configuration for urban construction fleets. Municipal contractors in London and Shenzhen are specifying electric units for zero-emission zone compliance. The technology is rendering obsolete the established 7-10 year diesel platform refresh cycles as battery chemistries evolve faster than chassis designs.
China's MIIT dual carbon compliance timelines are accelerating NEV certification requirements for domestic tipper manufacturers. OEMs must submit battery-electric and fuel-cell variants for homologation ahead of diesel phase-out schedules. Mining operators in Inner Mongolia and Shanxi are pre-ordering hydrogen-fueled articulated units to secure allocation before subsidy windows narrow.
Contractors are consolidating fleet procurement through integrated equipment-leasing platforms that bundle tippers with telematics, maintenance, and operator training. Traditional dealer networks face disintermediation as mining houses and infrastructure developers negotiate direct OEM relationships. India's largest construction conglomerates are piloting this model in the Delhi-Mumbai Industrial Corridor, compressing supplier margins while locking in multi-year service commitments.
Tipper Truck Market Segmentation
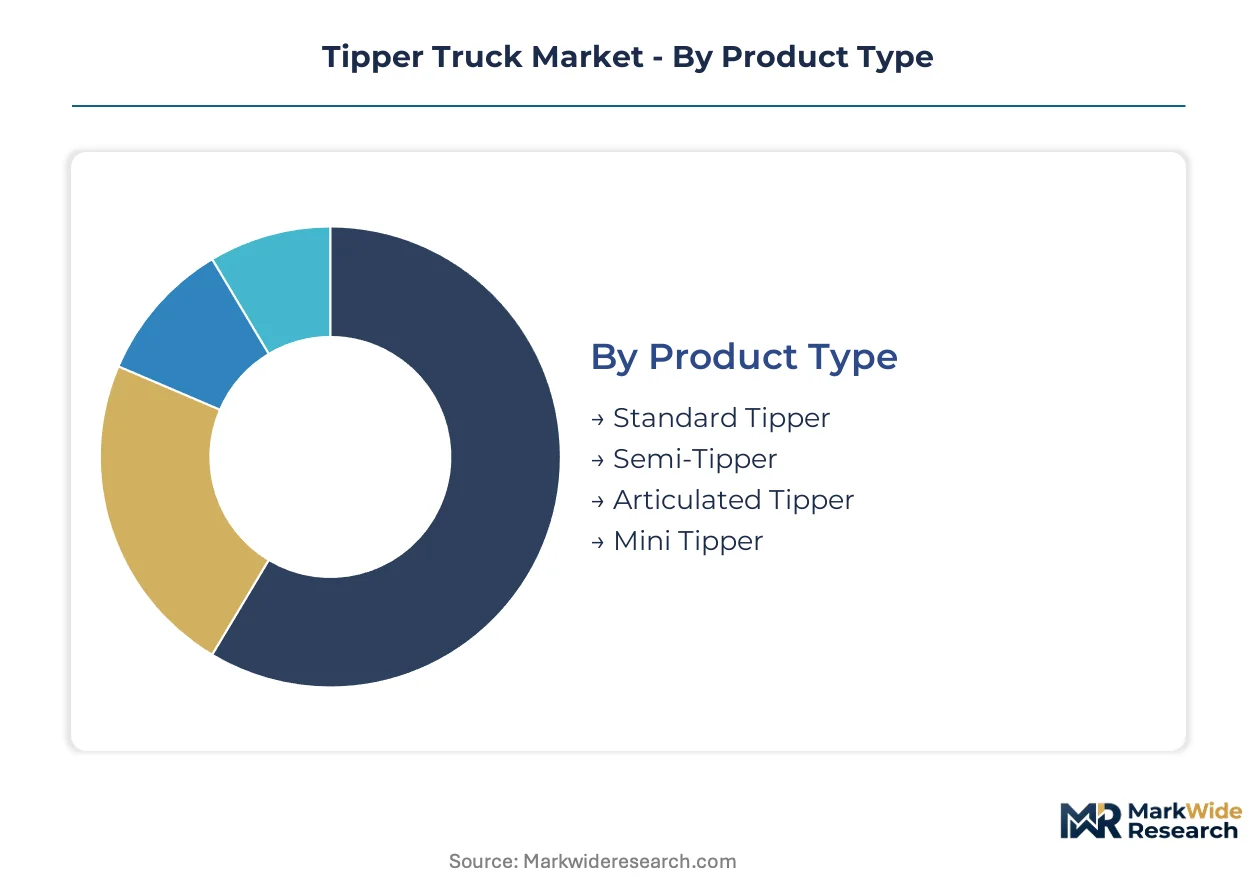
Tipper truck segmentation determines fleet procurement economics across radically different duty cycles. Construction contractors prioritize payload-to-tare ratios for urban aggregate transport, while mining operators demand chassis durability under shock-loading conditions that destroy standard configurations.
Product Type:
After-sales service intensity varies dramatically by tipper architecture, with articulated units requiring specialized field engineering that standard tippers rarely need.
- Standard Tipper:Fixed-chassis designs with rear-hinged beds dominate volume procurement for highway construction and municipal waste collection. India's state infrastructure corridors in Maharashtra and Karnataka are absorbing fleets for dam and highway aggregate transport, though margin compression from commodity chassis competition limits manufacturer differentiation.
- Articulated Tipper:Pivot-steering configurations with separate tractor and trailer units achieve payload-to-weight ratios above 1:1 in Australian iron ore and South African platinum belts. Mining operators demand these units for pit-to-crusher haulage where terrain instability would destabilize rigid chassis; high-tensile steel frame engineering extends service intervals beyond 15,000 operating hours.
- Semi-Tipper:Tractor-trailer combinations with detachable beds offer fleet flexibility for contractors serving multiple project types.
- Mini Tipper:Sub-3.5-ton gross vehicle weight configurations access urban congestion zones with restricted commercial vehicle permissions.
Standard Tipper holds the largest share; momentum sits with Articulated Tipper.
End User:
Application-specific duty cycles dictate chassis reinforcement specifications and hydraulic system sizing across customer categories.
- Construction:Aggregate transport from quarries to batching plants drives demand for 10-15 ton payload configurations with reinforced suspension systems. India's Delhi-Mumbai Industrial Corridor contractors are consolidating procurement through integrated leasing platforms that bundle telematics and maintenance.
- Mining:Off-highway operations in Inner Mongolia and Shanxi province demand articulated configurations with frames rated for repeated shock loading. Pre-orders for hydrogen-fueled units are accelerating ahead of China's MIIT subsidy window narrowing.
- Agriculture:Seasonal grain and fertilizer transport favors lighter chassis with corrosion-resistant bed coatings.
- Waste Management:Municipal collection routes in London and Shenzhen are specifying electric 5-10 ton units for zero-emission zone compliance.
Construction commands the greatest fleet volume; mining exhibits the steepest expansion trajectory.
Payload Capacity:
Axle-load regulations in India and gross vehicle weight rules in Europe fragment platform development across weight classes.
- 5-10 Tons:Urban construction logistics in European zero-emission zones favor this band for electric powertrain packaging. Battery-electric configurations with modular pack architectures are displacing diesel-hydraulic setups in London and Berlin metropolitan fleets.
- Above 15 Tons:Heavy mining haulage in Australian iron ore belts requires frames engineered for 50-ton payload cycles. High-tensile steel metallurgy and reinforced suspension bushings extend component life under sustained overload conditions.
- Under 5 Tons:Last-mile delivery and narrow-access construction sites favor compact dimensions.
- 10-15 Tons:Highway construction aggregate transport represents the mature volume tier.
Above 15 Tons dominates mining procurement; 5-10 Tons is gaining share fastest.
Engine Type:
Powertrain diversification is fragmenting OEM engineering resources across parallel certification pathways.
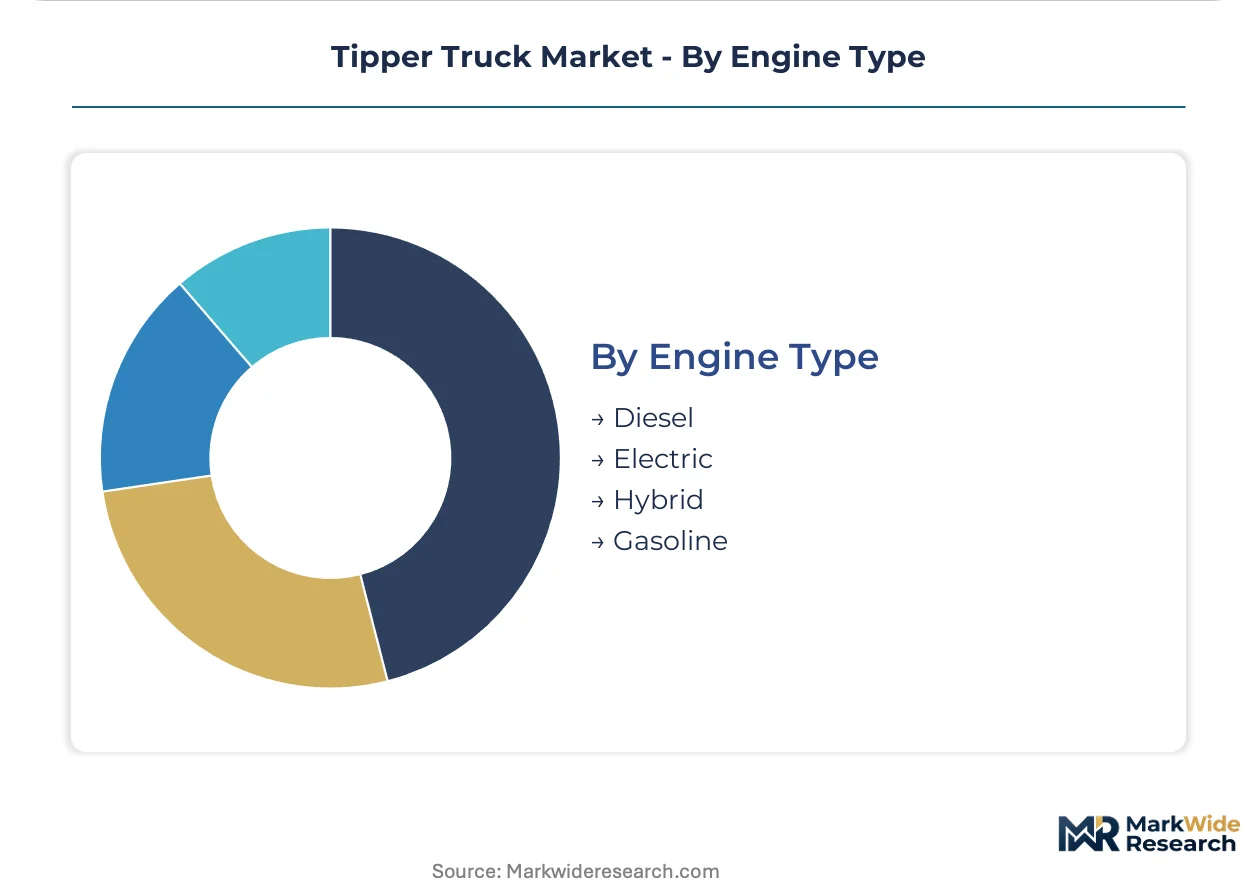
- Electric:Battery-electric powertrains with centralized motor drives and regenerative braking systems serve urban construction zones with access restrictions. Shenzhen and London municipal contractors are specifying these for congestion charge exemptions.
- Diesel:Compression-ignition engines with selective catalytic reduction remain essential for mining applications where charging infrastructure is absent. Euro VII NOx and particulate proposals are forcing European operators to pre-order compliant units ahead of enforcement deadlines.
- Hybrid:Parallel diesel-electric architectures offer fuel consumption reduction for variable-load construction duty cycles.
- Gasoline:Spark-ignition configurations occupy niche mini-tipper applications with low utilization rates.
Diesel retains the installed base; electric powertrains are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's CEA anchors the dominant geography through axle-load enforcement that reshapes chassis engineering for domestic tipper manufacturers. Fleet procurement concentrates in corridors where state infrastructure spending accelerates replacement cycles.
India
Maharashtra and Karnataka infrastructure corridors drive aggregate transport demand for dam and highway construction. CEA axle-load norms mandate structural reinforcement that adds tare weight and compresses payload capacity. The Delhi-Mumbai Industrial Corridor concentrates fleet deployment where construction conglomerates pilot integrated equipment-leasing platforms.
China
Mining operators in Inner Mongolia and Shanxi pre-order hydrogen-fueled articulated units ahead of MIIT subsidy window narrowing. Dual carbon compliance timelines accelerate NEV certification requirements for domestic OEMs. The Yangtze River Delta clusters battery-electric tipper production for municipal zero-emission zone deployment.
Germany
Euro VII NOx and particulate proposals force mining operators to pre-order compliant tippers ahead of enforcement deadlines. KBA homologation requirements fragment engineering resources across parallel certification pathways. The Ruhr industrial belt concentrates remanufactured powertrain programs under EU Green Deal funding.
Australia
Iron ore belts in Western Australia demand articulated configurations with frames rated for 50-ton payload cycles. High-tensile steel metallurgy extends service intervals beyond 15,000 operating hours. The Pilbara region concentrates premium articulated tipper procurement where payload-to-weight ratios determine fleet economics.
United Kingdom
London congestion rules create demand for 5-10 ton electric tippers in metropolitan construction logistics. F-Gas Regulation constrains diesel powertrain continuity across European export markets. The Greater Southeast cluster specifies battery-electric units for zero-emission zone compliance.
Tipper Truck Market Competitive Environment
Volume manufacturers and premium specialists split the market along payload-tier lines. The structure consolidates around OEMs with captive distribution networks and integrated service platforms. Three archetypes dominate: diversified automotive conglomerates with construction vehicle divisions, dedicated commercial vehicle manufacturers with mining-focused portfolios, and regional champions serving protected domestic markets. Competitive moves center on backward integration into powertrain production and geographic expansion through localized assembly partnerships.
Among diversified automotive conglomerates, Daimler Truck AG and Tata Motors Ltd. exemplify the scale-driven archetype with manufacturing footprints anchored in high-volume construction corridors. AB Volvo occupies a position within the premium-tier vector for articulated mining applications. These three represent distinct strategic postures: German-engineered platforms for regulated European markets, Indian cost-optimized chassis for emerging infrastructure corridors, and Swedish premium configurations for resource extraction operators demanding payload efficiency.
| Leading Market Players |
|---|
| MAN Truck & Bus AG |
| Iveco Group N.V. |
| Daimler Truck AG |
| Hino Motors, Ltd. |
| Isuzu Motors Limited |
| AB Volvo |
| Scania AB |
| Tata Motors Ltd. |
| PACCAR Inc. |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Rotterdam maritime corridor's freight cost volatility transmits directly into tipper chassis landed prices, compressing margins for European distributors while amplifying price spreads between Asian-manufactured standard units and premium articulated configurations sourced from specialized mining-equipment hubs.
Pricing Analysis
Geographic price spreads between Indian-manufactured standard tippers and European premium articulated units exceed factor ranges driven by axle-load certification tiers and high-tensile steel content. Three-tier pricing structure across premium, standard, and economy levels stratifies by payload capacity band and after-sales service bundling, with mining operators showing lowest price sensitivity due to fleet economics dominance. Cost compression in the sub-15-ton segment intensifies because commodity chassis competition from domestic Indian OEMs erodes brand premiums. Municipal contractors in zero-emission zones exhibit highest price sensitivity as electric powertrain premiums strain capital budgets.
Supply Chain Analysis
Tariff exposure between China and key battery material processing jurisdictions concentrates supply risk for electric tipper programs dependent on lithium-ion cell imports. Manufacturing gravity centers on China for battery-electric powertrain components, India for steel chassis fabrication, and Germany for hydraulic system engineering. Raw material dependencies span high-tensile steel from integrated Indian mills, rare-earth permanent magnets from Chinese processors, and synthetic hydraulic fluids from German chemical specialists. Distribution runs through OEM-captive dealer networks in construction corridors and direct procurement relationships for mining fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Powertrain electrification fragments the tipper market into parallel certification ecosystems, creating specialist niches for regional champions and technology-focused entrants alongside established volume manufacturers.
For Market Incumbents: Entrench position through backward integration into battery pack assembly and captive high-tensile steel supply from Indian mill partnerships. Hydrogen fuel-cell substitution in mining applications threatens diesel platform continuity; prioritize Euro VII pre-certification investments to lock in European mining fleet replacement cycles ahead of enforcement deadlines. For New Entrants and Emerging Players: Southeast Asian infrastructure corridors exhibit lowest incumbent penetration for electric tipper deployment. Target Indonesia's nickel-processing belt and Vietnam's coastal highway construction zones where state-level spending accelerates fleet procurement. Pursue integrated leasing platforms bundling telematics and maintenance to bypass established dealer networks. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified automotive conglomerates seeking to divest commercial vehicle divisions amid powertrain transition capital intensity. Five-to-ten-year viability hinges on platform standardization across electric and hydrogen architectures. Monitor MIIT subsidy window narrowing in China as inflection indicator for hydrogen tipper demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Powertrain Platform Standardization | Reduces engineering fragmentation across Euro VI, MIIT NEV, and India's AIS certification pathways. |
| Battery Supply Agreement | Secures lithium-ion cell allocation from Chinese processors amid raw material processing concentration. |
| Telematics Integration Investment | Enables subscription revenue streams through real-time payload optimization fused with route algorithms. |
| Geographic Manufacturing Footprint | Localizes assembly in Maharashtra and Karnataka corridors to serve India's state infrastructure spending. |
| Hydrogen Infrastructure Partnership | Pre-positions for Inner Mongolia and Shanxi mining operator pre-orders ahead of subsidy window narrowing. |
Study Parameters
Operator-level perspectives from fleet procurement managers, maintenance directors at mining houses, OEM platform engineers, and aftermarket service heads anchored the qualitative base. Primary interview findings triangulated against secondary sources including vehicle production databases, customs and trade flow records, SEC filings from listed commercial vehicle manufacturers, and regulatory submissions to India's CEA, China's MIIT, and Germany's KBA. Bottom-up unit economics modeling converged with top-down market sizing across segmentation dimensions.
Scenario-bracketing framed demand projections across the analysis window, with volume and value outputs reflecting triangulated approaches across product type, payload capacity tier, engine architecture, and end-use application. CAGRs derived from fitted growth curves applied to base-year estimates, incorporating powertrain transition timelines, infrastructure spending trajectories, and emission enforcement schedules as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese battery-electric specialists or accelerated Euro VII enforcement would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Dump Trucks Market
Heavy-Duty Trucks
Saudi Arabia Refrigerated Truck Market
Heavy-Duty Trucks
Utility Trucks Market
Heavy-Duty Trucks
Europe Medium & Heavy-Duty Truck Rental Market
Heavy-Duty Trucks
India Vacuum Truck Market
Heavy-Duty Trucks
North America Heavy Commercial Vehicle (HCV) TMPS Market
Heavy-Duty Trucks
Heavy-Duty Truck Dashboard Switch Panel Systems Market
Heavy-Duty Trucks
United States Refrigerated Trucking Market
Heavy-Duty Trucks
Truck Racks Market
Heavy-Duty Trucks
Truck Bedliner Market
Heavy-Duty Trucks
US Tanker Truck Market
Heavy-Duty Trucks
Garbage Collection Trucks Market
Heavy-Duty Trucks
Garbage Truck Bodies Market
Heavy-Duty Trucks
Airport Catering Truck Market
Heavy-Duty Trucks
Global Vocational Truck Market
Heavy-Duty Trucks
Automotive High Performance Trucks Market