
 Automotive Overhead Console Market | 2026-2036
Automotive Overhead Console Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Overhead Console Market Analysis
Subscription-based over-the-air feature activation for ambient lighting and climate interfaces is broadening what automakers monetize beyond hardware. Magna International leverages its vertical integration across plastic molding and electronics assembly to capture margin pools in premium console programs. Yanfeng Automotive Interiors anchors its position through manufacturing scale in Asia-Pacific assembly corridors. Hella GmbH & Co. KGaA differentiates via lighting technology leadership embedded directly into overhead module architectures.
An automotive overhead console is an interior roof-mounted module that integrates lighting, storage, electronic interfaces, and climate vents, typically manufactured through thermoplastic injection molding with Class A surface finishing for visible cabin aesthetics. Its primary purpose is to centralize driver and passenger convenience functions while reducing discrete component count across the headliner assembly. Consoles with sunroof integration command higher value per unit due to structural complexity and sealing requirements, whereas wireless charging feature sets represent the fastest-growing attachment rate as smartphone power standards proliferate. Plastic material formulations still dominate volume production, though composite substrates gain share where OEMs pursue mass reduction targets.
The EPA enforces volatile organic compound limits on interior cabin materials, compelling suppliers to reformulate adhesives and substrate coatings used in console assembly. NHTSA distraction guidelines shape how touchscreen and button interfaces get positioned within driver sightlines. OEMs and Tier-1 suppliers must monitor how software-defined cabin features alter warranty liability and aftermarket revenue splits without relying on hardware replacement cycles.
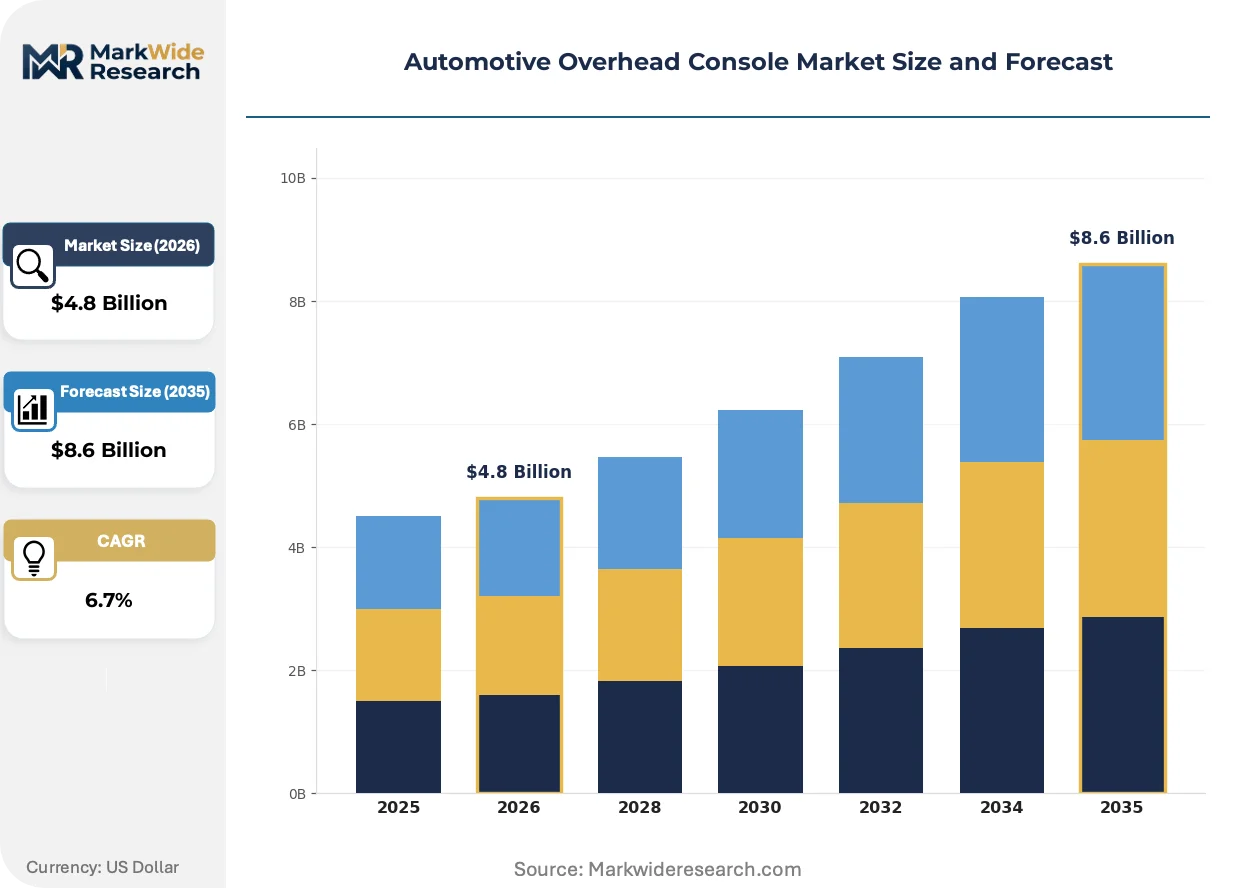
Market Dynamics
Software-defined cabin architectures are reconfiguring how overhead console functionality gets monetized, decoupling feature activation from physical hardware replacement cycles and forcing suppliers to develop recurring revenue models alongside traditional manufacturing contracts.
Growth Catalysts
- EU REACH Regulation:Material safety mandates are accelerating supplier migration toward compliant low-VOC substrates and adhesive formulations, creating upgrade cycles across installed European vehicle fleets.
- Wireless Charging Standardization:Qi and PMA protocol proliferation across smartphone ecosystems is embedding power transmission coils into overhead module designs as a default specification.
- German Premium Cluster:Stuttgart and Munich OEM engineering centers are specifying integrated overhead systems with sunroof structural interfaces, concentrating high-value program awards in southern Germany.
Market Restraints
- Petrochemical Input Volatility:ABS and polycarbonate resin prices fluctuate with crude oil benchmarks, compressing margin predictability for thermoplastic injection molders serving volume programs.
- Tooling Concentration Risk:Large-tonnage injection mold fabrication concentrates among a limited supplier base in China and Germany, creating single-source vulnerability for complex Class A surface tooling.
- Headliner Integration Complexity:Sealing and NVH requirements for sunroof-compatible consoles impose technical constraints that extend development timelines and validation costs.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for automotive component manufacturing are drawing console assembly capacity toward Chennai and Pune industrial corridors.
- Over-the-Air Monetization:Subscription activation for ambient lighting scenes and climate interface personalization creates recurring revenue streams detached from hardware refresh cycles.
- Composite Substrate Convergence:Natural fiber-reinforced thermoplastics meeting mass reduction targets are opening specification opportunities at European OEMs pursuing fleet CO2 compliance.
Industry Challenges
- Embedded Software Competency Gap:Traditional plastic molding suppliers lack firmware development capabilities required for touchscreen and gesture interface integration, forcing partnership or acquisition investments.
- Multi-Regulatory Certification Overlap:Simultaneous EPA VOC compliance, NHTSA distraction guideline adherence, and EU REACH material documentation creates fragmented validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Overhead Console Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Consoles with Sunroof, Consoles without Sunroof, Premium Consoles, Standard Consoles Material: Plastic, Metal, Composite, Fabric Feature: Wireless Charging, Built-in Lighting, Climate Control, Storage Compartments End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | Magna International, Hella GmbH & Co. KGaA, Grupo Antolin, Lear Corporation, Visteon Corporation, Gentex Corporation, Continental AG, Toyota Boshoku Corporation, Yanfeng Automotive Interiors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Overhead Console Market Emerging Trajectories
Electronics-physical integration is compressing the traditional boundary between lighting hardware and software control layers, enabling dynamic cabin experiences that reconfigure without component replacement.
Capacitive touch interfaces with haptic feedback are consolidating discrete mechanical switches into programmable surface panels. Luxury OEM specification teams in Germany and Japan are mandating these architectures for 2026 model year programs. This consolidation is eliminating separate button supply chains while concentrating electronics sourcing among semiconductor-integrated module suppliers.
EPA volatile organic compound limits on interior cabin materials are compelling adhesive and coating reformulations across North American supply chains. Tier-1 suppliers must revalidate bonding chemistries to maintain structural performance while meeting emission thresholds. Console programs targeting US fleet customers are experiencing 4-6 month certification timeline extensions as a result.
Fleet procurement departments are bundling overhead console specifications into total cabin interior awards rather than sourcing modules separately. Full-service interior integrators are displacing component specialists in contract negotiations at European and North American OEMs. This concentration is most visible in Germany, where Stuttgart-based engineering teams now specify console functionality through Yanfeng and Magna interior platform contracts rather than direct component sourcing.
Automotive Overhead Console Market Segmentation
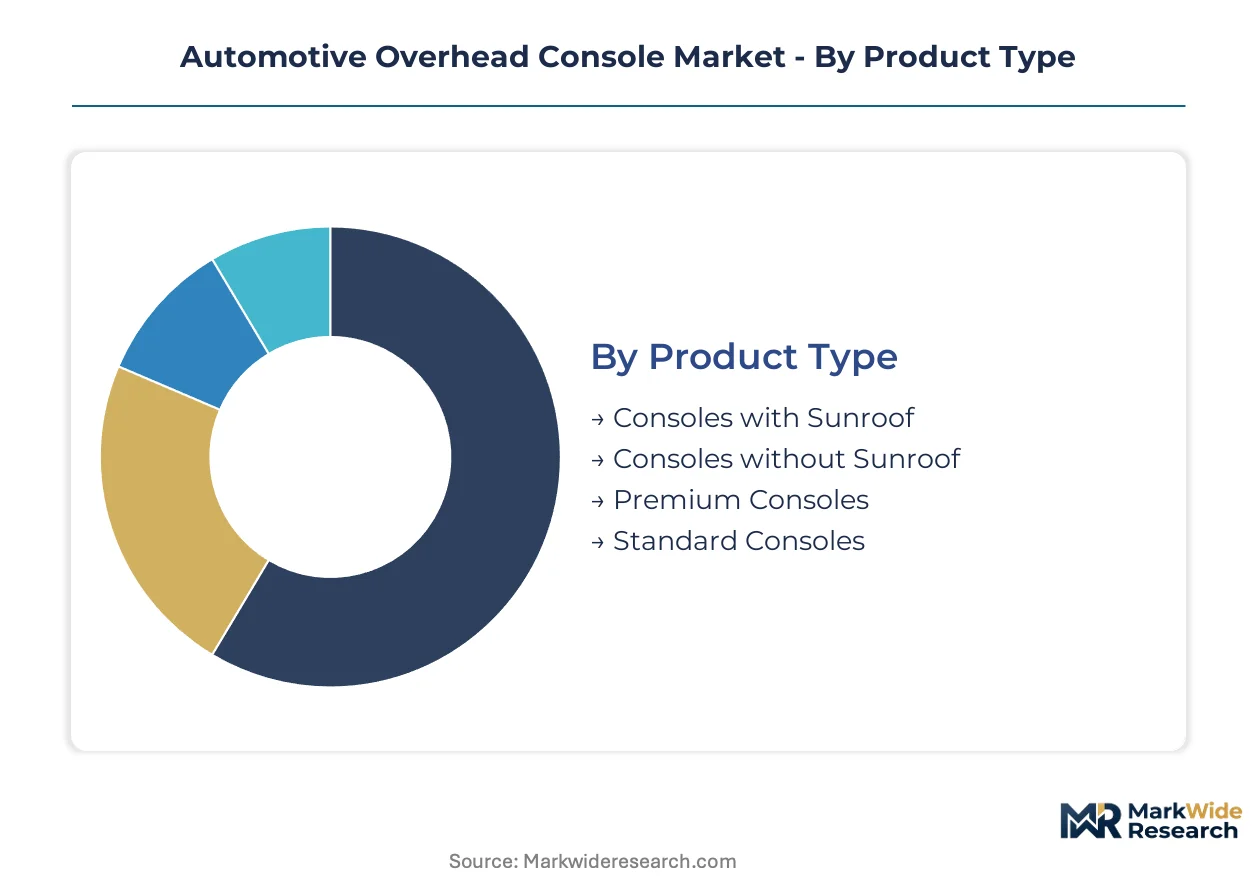
Automotive overhead console segmentation reveals how engineering specifications, material science, and feature integration create distinct value tiers. Suppliers must align production capabilities with the precise technical and commercial requirements of each category to capture program awards.
Product Type:
Customization intensity varies dramatically across this category, from standardized modules for mass-market platforms to highly engineered systems requiring sunroof structural integration.
- Consoles with Sunroof:These modules incorporate reinforced substrates and dual-seal architectures to maintain headliner NVH performance while accommodating glass panel mechanisms. German premium OEM engineering centers in Stuttgart and Munich specify these configurations for their flagship sedans and SUVs, where sunroof penetration exceeds 80 percent. The structural complexity commands higher program values and extends development timelines by 6-9 months.
- Premium Consoles:Specifications demand Class A surface finishing, capacitive touch interfaces, and integrated ambient lighting with software-defined scene control. Luxury vehicle programs in Japan and Germany are mandating these architectures for their 2026 model year launches, consolidating electronics sourcing among semiconductor-integrated module suppliers.
- Consoles without Sunroof:Standardized designs serve volume compact and mid-size vehicle platforms where cost discipline dominates sourcing decisions.
- Standard Consoles:Basic configurations with mechanical switches and conventional lighting satisfy fleet and economy vehicle procurement requirements.
Leading the category by volume: Consoles without Sunroof. Growing fastest: Consoles with Sunroof.
Material:
Cost tier positioning and regulatory compliance requirements determine substrate selection, with petrochemical volatility pressing molders toward alternative formulations.
- Plastic:ABS and polycarbonate resins still dominate volume production through thermoplastic injection molding, though crude oil price fluctuations compress margin predictability for suppliers serving high-volume programs. EPA volatile organic compound limits are compelling adhesive and coating reformulations across North American supply chains.
- Composite:Natural fiber-reinforced thermoplastics are gaining specification share at European OEMs pursuing fleet CO2 compliance through cabin mass reduction. The EU REACH regulation on material safety is accelerating migration toward these compliant low-VOC substrates.
- Metal:Aluminum and magnesium alloys serve structural reinforcement requirements in sunroof-integrated modules where torsional rigidity is critical.
- Fabric:Textile-wrapped substrates address premium aesthetic requirements in luxury vehicle headliner assemblies.
Volume concentration: Plastic. Expanding most quickly: Composite.
Feature:
Application-driven bundling patterns are reshaping how functionality gets specified, with smartphone ecosystem convergence dictating default inclusion of certain capabilities.
- Wireless Charging:Qi and PMA protocol proliferation across smartphone ecosystems is embedding power transmission coils into overhead module designs as a default specification. This capability is climbing the fastest as smartphone power standards achieve near-universal adoption across premium and mass-market vehicle segments.
- Built-in Lighting:LED architectures with software-controlled dimming and color temperature adjustment are consolidating discrete dome and map light assemblies into programmable systems.
- Climate Control:Overhead vent integration with independent temperature zones serves multi-row vehicle configurations in North American full-size SUV programs.
- Storage Compartments:Sunglass holders and overhead bins remain standard across all vehicle classes, though their design complexity varies by interior trim level.
Most widely specified: Built-in Lighting. Steepest expansion trajectory: Wireless Charging.
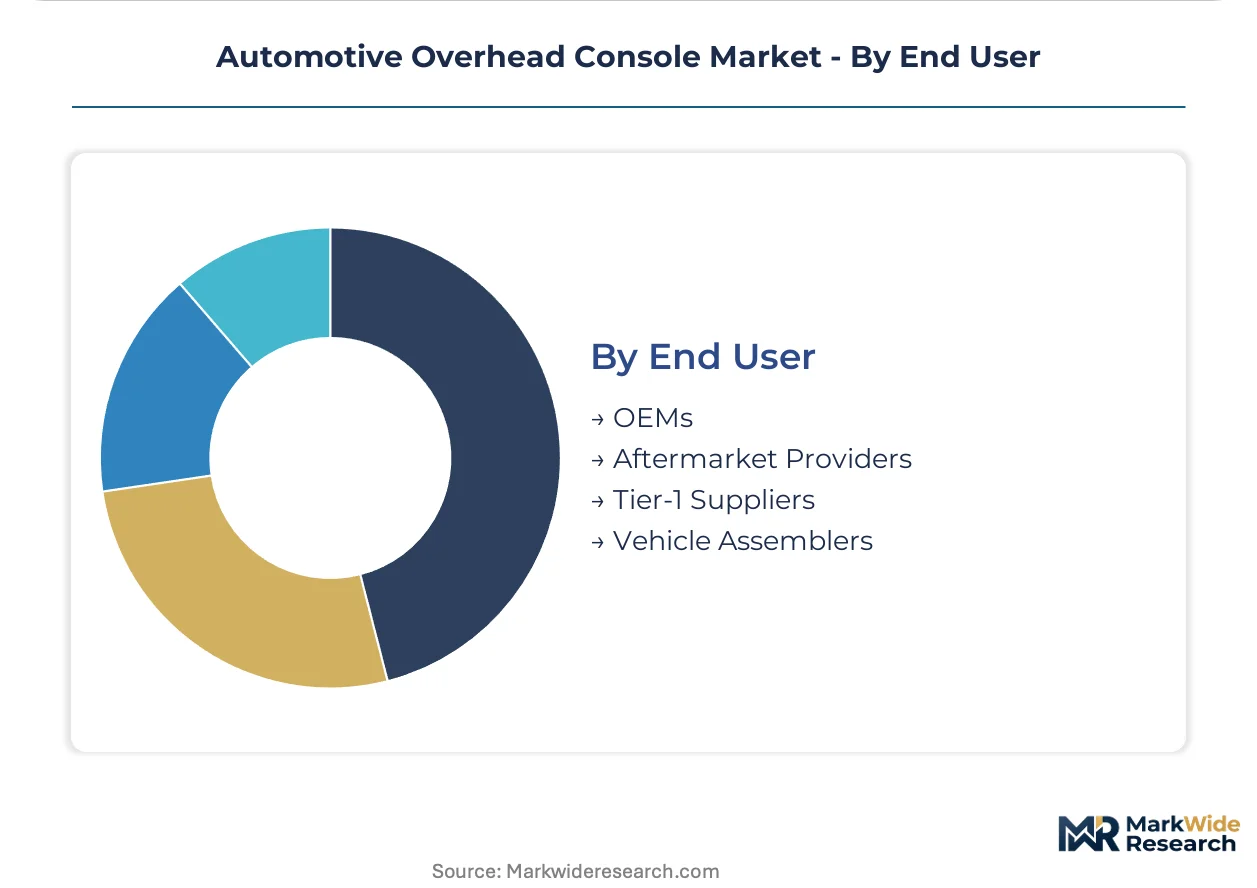
End User:
Supply chain tier positioning and procurement authority concentration determine how console specifications flow from design to assembly.
- OEMs:Direct specification authority rests with vehicle manufacturer engineering teams, particularly in Germany where Stuttgart-based programs increasingly bundle console functionality into total cabin interior platform contracts rather than sourcing modules separately.
- Tier-1 Suppliers:Full-service interior integrators are displacing component specialists in contract negotiations at European and North American OEMs, capturing console specification authority through broader interior platform awards.
- Aftermarket Providers:Replacement and upgrade modules serve vehicle refurbishment and customization markets with reduced regulatory validation requirements.
- Vehicle Assemblers:Contract manufacturing arrangements transfer procurement responsibility to assembly partners in certain emerging market joint ventures.
Dominant procurement channel: Tier-1 Suppliers. Gaining contract authority: OEMs through platform consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Germany, China, and the United States while consumption patterns concentrate in premium automotive markets across Western Europe and East Asia. This geographic split creates distinct supply chain configurations where engineering specification authority and final assembly location often diverge.
Germany
Stuttgart and Munich engineering centers specify integrated overhead systems with sunroof structural interfaces for flagship sedan and SUV programs. EU REACH regulation mandates accelerate supplier migration toward compliant low-VOC substrates and adhesive formulations. The premium automotive cluster around Baden-Württemberg and Bavaria concentrates high-value program awards among full-service interior integrators.
United States
EPA volatile organic compound limits on interior cabin materials compel adhesive and coating reformulations across North American supply chains. NHTSA distraction guidelines shape touchscreen and button interface positioning within driver sightlines. Detroit-area OEM engineering teams bundle overhead console specifications into total cabin interior platform contracts.
China
Domestic EV manufacturers specify wireless charging coils as default overhead module features alongside capacitive touch interfaces. MIIT automotive standards govern electromagnetic compatibility for embedded electronics in cabin modules. The Yangtze River Delta manufacturing corridor concentrates thermoplastic injection molding capacity for both domestic brands and export programs.
India
Production-linked incentive schemes for automotive component manufacturing draw console assembly capacity toward Chennai and Pune industrial corridors. BIS certification requirements govern material safety and electromagnetic emissions for cabin electronics. Domestic OEM procurement teams increasingly specify localized content for mid-size vehicle platforms.
Japan
Luxury vehicle programs mandate capacitive touch architectures with haptic feedback for 2026 model year launches. METI industrial standards influence electronics integration protocols for software-defined cabin features. Kanto-based engineering teams consolidate electronics sourcing among semiconductor-integrated module suppliers.
Automotive Overhead Console Market Vendor Landscape
Top-tier vendors anchor premium platform contracts, while mid-scale specialists compete on tooling efficiency and regional proximity. The vendor base stratifies across three tiers: full-service interior integrators capturing bundled cabin awards, component specialists defending discrete module positions, and regional fabricators serving emerging market joint ventures. Strategic archetypes include electronics-physical integrators, thermoplastic molding scale operators, and lighting technology specialists. Competitive moves concentrate on backward integration into semiconductor sourcing and geographic expansion through joint venture manufacturing.
Among North American full-service integrators, Magna International exemplifies the vertically integrated archetype spanning plastic molding and electronics assembly. Hella GmbH & Co. KGaA occupies a position within the lighting technology specialist tier. Yanfeng Automotive Interiors represents the scale-driven Asia-Pacific manufacturing model. These three entities anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Magna International |
| Hella GmbH & Co. KGaA |
| Grupo Antolin |
| Lear Corporation |
| Visteon Corporation |
| Gentex Corporation |
| Continental AG |
| Toyota Boshoku Corporation |
| Yanfeng Automotive Interiors |
| Others |
Supply Flow & Price Mechanics
Petrochemical resin costs cascade through ABS and polycarbonate formulations into three-tier pricing structures across premium, standard, and economy levels, with German injection molders capturing margin premiums on Class A surface programs while volume producers in China absorb crude oil benchmark volatility.
Pricing Analysis
Margin tightening in standard-grade consoles reflects crude oil price volatility compressing thermoplastic compounders serving high-volume OEM programs. Three-tier pricing structure across premium, standard, and economy levels separates sunroof-integrated modules with structural reinforcement from basic mechanical-switch configurations. Price differentiation traces to certification grade for EPA VOC compliance and customization level for software-defined feature activation. Fleet procurement teams exhibit highest price sensitivity, while German premium OEM engineering centers prioritize technical performance over unit cost.
Supply Chain Analysis
Large-tonnage injection mold fabrication rests on specialty tooling providers concentrated in China and Germany, creating single-source vulnerability for complex Class A surface dies. Raw material flows draw from ABS and polycarbonate resin producers, capacitive touch sensor foundries, and LED packaging houses. Supply chain risk centers on tariff exposure for electronics components crossing Pacific trade lanes. Distribution runs through Tier-1 interior integrators bundling console awards into total cabin platform contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tooling capacity scarcity for precision Class A surface molds props pricing power among qualified suppliers, constraining rapid supply response to demand surges in premium vehicle programs.
For Market Incumbents: Cement platform engineering relationships with Stuttgart and Munich OEM centers through dedicated program co-development teams. Secure captive supply of injection mold fabrication capacity to defend against emerging composite substrate specialists capturing mass-reduction specifications. Prioritize firmware development partnerships to close embedded software competency gaps threatening electronics-physical integration leadership. For New Entrants and Emerging Players: Direct-to-OEM digital sales channels offer bypass routes around entrenched Tier-1 interior integrators in aftermarket refurbishment segments. Target India's Chennai and Pune industrial corridors where PLI incentives reduce capital barriers for console assembly localization. Pursue natural fiber-reinforced thermoplastic formulations as the most penetrable material tier given EU REACH compliance tailwinds. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale electronics-physical integrators in Germany's Baden-Württemberg cluster facing working capital pressure from extended OEM payment terms. Five-to-ten year viability hinges on software-defined cabin architecture capture rates. Monitor Qi wireless charging attachment rate trajectories as inflection indicator for module value-per-unit expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Sourcing | Captures margin pools in capacitive touch and LED driver electronics for premium console programs. |
| Composite Substrate Manufacturing Scale-Up | Positions suppliers for EU REACH-compliant natural fiber-reinforced thermoplastic specifications at Stuttgart OEMs. |
| Over-the-Air Feature Platform Development | Enables recurring revenue streams from ambient lighting and climate interface subscription activation. |
| Joint Venture Manufacturing in India | Accesses PLI scheme incentives while meeting BIS certification requirements for localized content. |
| Sunroof Structural Integration Partnership | Secures high-value program awards through dual-seal architecture expertise for German flagship vehicles. |
Methodological Framework
Independent corroboration across OEM platform engineering directors, Tier-1 interior procurement leads, and injection mold tooling specialists underwrites the qualitative findings. Secondary validation draws from vehicle production databases, IHS Markit registration data, EPA VOC compliance filings, and EU REACH material safety documentation. Bottom-up segment sizing triangulates against top-down OEM program value estimates across the analysis window.
Rate-of-change decomposition separates volume growth from value-per-unit expansion across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs derive from modeled adoption curves for wireless charging and capacitive touch interfaces, overlaid with petrochemical input cost scenarios and regulatory compliance timeline assumptions.
The model holds under stable crude oil benchmark conditions and consistent OEM platform consolidation patterns; deviation in EU REACH enforcement intensity or NHTSA distraction guideline revisions would shift specification timelines. A small set of named triggers warrants ongoing watch: smartphone power standard proliferation rates, composite substrate qualification progress at German OEMs, and India PLI scheme disbursement velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Global Automotive Interiors Market
Automotive Interior & Exterior
Global Automotive Roof Systems Market
Automotive Interior & Exterior
Power Sunroof Market
Automotive Interior & Exterior
Automotive Reconfigurable Body Panel Market
Automotive Interior & Exterior
Impact-Modified PCR Plastics for Automotive Interiors Market
Automotive Interior & Exterior
Automotive Seats Market
Automotive Interior & Exterior
Automotive Electrically Adjustable Outside Rear View Mirror (ORVM) Market
Automotive Interior & Exterior
Automotive Exterior LED Lighting Market
Automotive Interior & Exterior
Automotive Smart Faceplate Market
Automotive Interior & Exterior
India Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Fridge Market
Automotive Interior & Exterior
Automotive Intelligent Rear-View Mirror Market
Automotive Interior & Exterior
Train Seat Materials Market
Automotive Interior & Exterior
Commercial Vehicle Seats Market
Automotive Interior & Exterior
Paint Protection Film Market
Automotive Interior & Exterior
Automotive Smart Dashboard Display Market