
 Malaysia Fire Truck Market | 2026-2036
Malaysia Fire Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Fire Truck Market Outlook
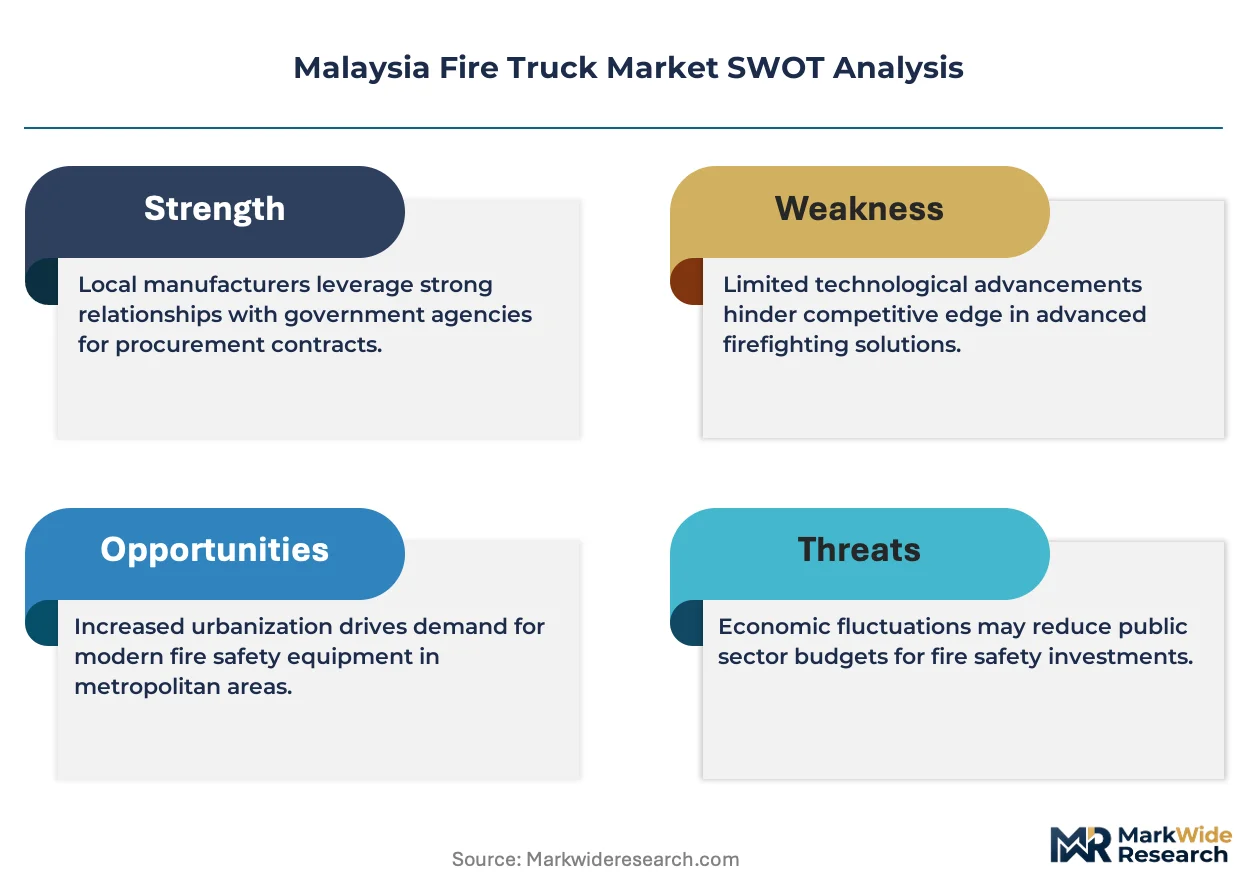
Modular pumper-aerial configurations is shifting procurement patterns among Malaysian fire authorities. Rosenbauer International AG leverages its European certification pedigree to anchor premium tender bids for federal Bomba contracts. Ziegler Group competes through localized assembly partnerships that reduce import duty exposure. Gemilang International dominates domestic bus and specialty vehicle manufacturing, extending that chassis expertise into fire truck platform supply for regional markets.
Fire trucks are purpose-built emergency response vehicles integrating high-pressure pumping systems, water and foam tank assemblies, and extendable aerial ladders or platforms, typically manufactured on heavy-duty commercial chassis with gross vehicle weights exceeding 15 tonnes. Their primary function is to transport firefighters, suppress structural and wildland fires, and enable elevated rescue operations under demanding thermal and load conditions. Pumper trucks occupy the largest volume share given universal deployment across urban and semi-urban stations, while aerial trucks command higher unit margins reflecting complex boom mechanics and stabilization systems. Wildfire trucks represent the fastest-growing product category as Malaysian plantation estates and forest reserves intensify mechanized firefighting preparedness against recurring dry-season haze events.
Bomba Malaysia enforces equipment specifications aligned with NFPA 1901 benchmarks, compelling importers to adapt pump ratings, tank capacities, and electrical system configurations to tropical humidity and monsoon exposure conditions. The Department of Standards Malaysia (DSM) and SIRIM QAS International administer type-approval protocols that filter non-compliant suppliers from government tender eligibility. Stakeholders must monitor evolving green procurement directives from the Ministry of Housing and Local Government, where hybrid or alternative-fuel drivetrain mandates could reshape chassis sourcing decisions within the next procurement cycle.
Market Dynamics
Fleet modernization mandates from Bomba Malaysia are compressing replacement cycles for municipal fire departments across Peninsular Malaysia, forcing chassis suppliers and pump manufacturers to synchronize production with federal procurement calendars rather than discretionary local budgets.
Growth Catalysts
- NFPA 1901 Alignment:Bomba Malaysia's equipment specifications now mirror NFPA 1901 benchmarks, disqualifying non-compliant suppliers from federal tenders and consolidating demand around certified manufacturers.
- Plantation Estate Expansion:Malaysian palm oil and timber conglomerates are mechanizing wildfire response capabilities across Sabah and Sarawak, creating parallel procurement channels outside municipal budgets.
- Klang Valley Urban Density:Concentrated high-rise development in Kuala Lumpur and Petaling Jaya is mandating aerial platform deployments that exceed legacy fleet specifications.
Market Restraints
- Import Duty Exposure:Completely built-up fire trucks from European suppliers face substantial tariff barriers, inflating landed costs for premium pumper-aerial configurations.
- Chassis Supply Concentration:Heavy-duty commercial chassis suitable for 15-tonne GVW fire truck builds depend on a narrow supplier base with extended lead times for right-hand drive configurations.
- Monsoon Corrosion:Tropical humidity and salt-laden coastal atmospheres accelerate electrical system degradation, compressing asset lifespans below temperate-climate assumptions.
Strategic Opportunities
- Sabah and Sarawak Penetration:East Malaysian states maintain older fleet inventories with less stringent tender competition, offering first-mover advantages for localized assembly partnerships.
- Hybrid Drivetrain Mandates:Anticipated green procurement directives from the Ministry of Housing and Local Government could privilege alternative-fuel chassis suppliers in upcoming federal tender cycles.
- Modular Platform Convergence:Standardized pumper-aerial modules that interface with multiple chassis brands are reducing buyer lock-in and enabling multi-source procurement strategies.
Industry Challenges
- SIRIM QAS Certification Timelines:Type-approval protocols for electrical and pump systems impose 6-12 month validation windows that misalign with urgent municipal replacement schedules.
- Specialized Technician Scarcity:Aerial boom hydraulics and electronic stabilization systems require factory-trained service personnel that Malaysian distributors struggle to retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Fire Truck Market |
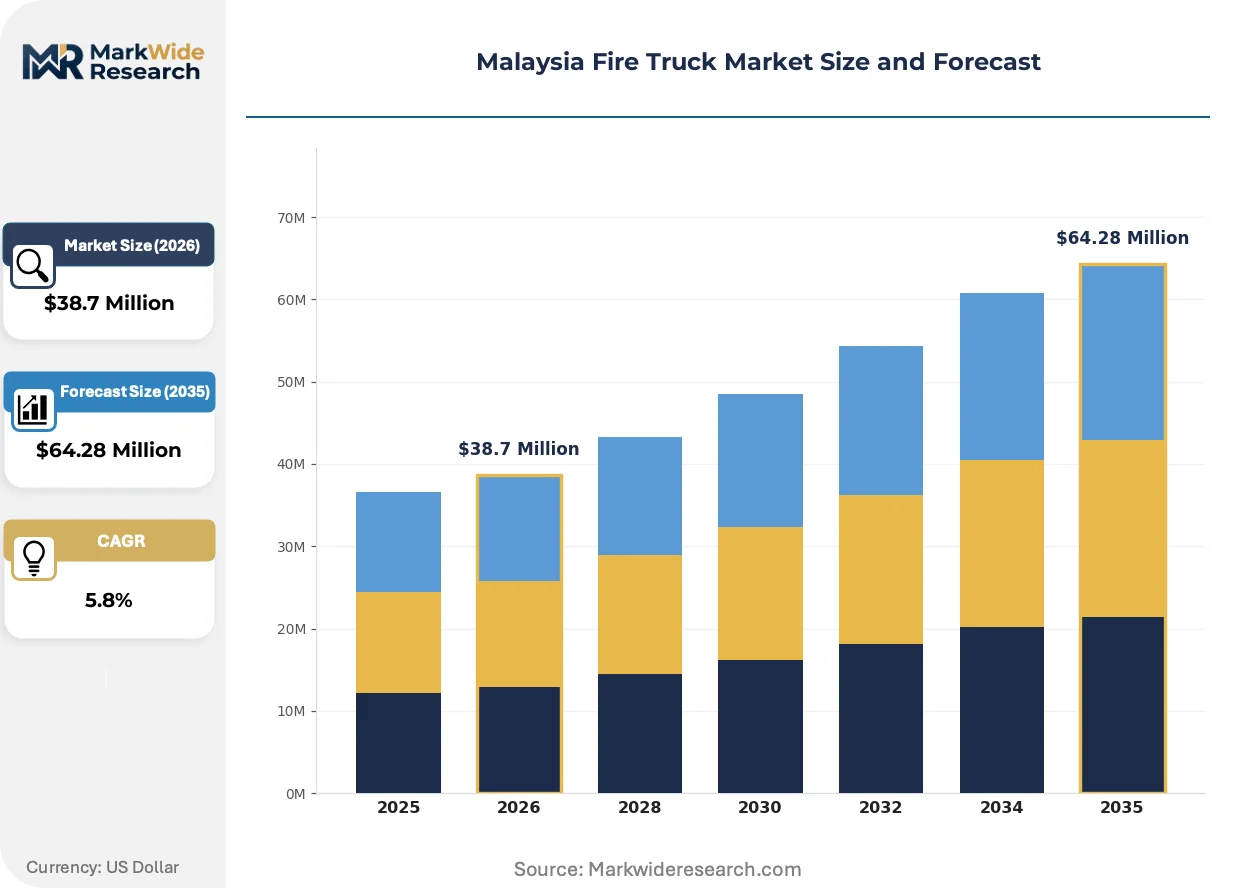
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $64.28 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pumper Trucks, Aerial Trucks, Wildfire Trucks, Tankers End User: Municipal Fire Departments, Industrial Facilities, Oil & Gas Companies, Airport Authorities Technology: Fire Suppression Systems, Communication Systems, Navigation Systems, Vehicle Modifications Distribution Channel: Direct Sales, Online Sales, Dealerships, Tenders |
| Companies Covered | E-ONE Fire Trucks, HME, Inc., Rosenbauer International AG, Bronto Skylift Oy Ab, Ziegler Group, Oshkosh Corporation, Sutphen Corporation, Gemilang International, Magirus GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Fire Truck Market Strategic Shifts
Digitalization of fleet management and predictive maintenance systems is reshaping how Malaysian fire authorities specify new apparatus, with telematics integration now appearing in tender documents as a scored evaluation criterion.
Telematics-enabled pump monitoring systems are integrating real-time pressure, flow rate, and engine diagnostics into centralized fleet management dashboards. Bomba Malaysia's federal divisions are piloting these platforms for condition-based maintenance scheduling. This capability is integrating asset lifecycle data into procurement decisions, compressing replacement timelines for underperforming units.
Malaysia's Department of Standards is incorporating tropical climate amendments into fire truck electrical system certifications, extending SIRIM QAS testing protocols for humidity resistance and monsoon sealing. These requirements are filtering out European suppliers unwilling to redesign harness routing and connector specifications. Aerial platform manufacturers are responding fastest, recognizing Malaysian certification as a gateway to broader ASEAN defense and emergency vehicle markets.
Lease-to-own financing structures are displacing outright purchase models among cash-constrained municipal councils in secondary cities. Malayan Banking and CIMB are structuring 7-year operational leases with maintenance bundling that transfers residual value risk to financiers. This shift is most visible in Johor and Penang, where state governments are consolidating district-level fleet procurement under central leasing authorities to improve credit terms.
Malaysia Fire Truck Market Segmentation
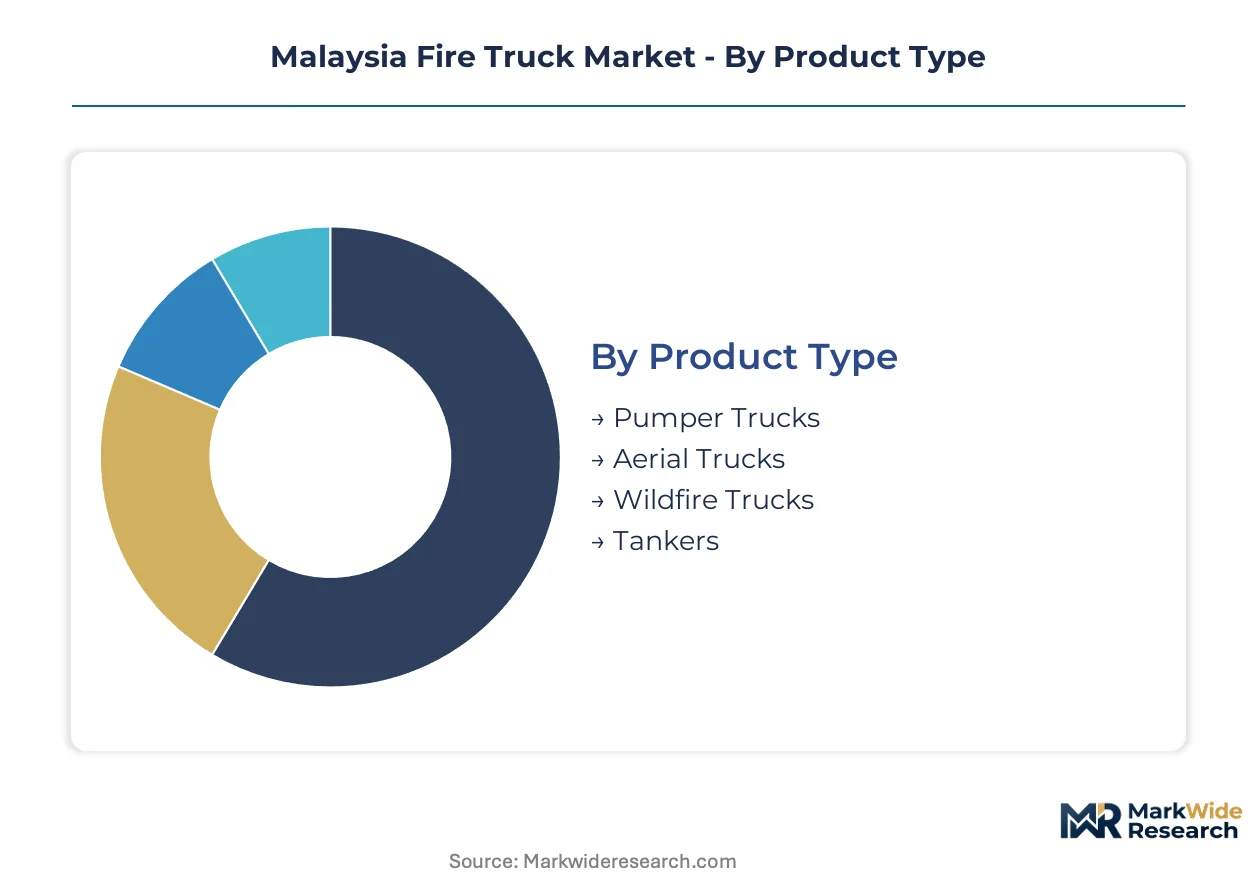
Fire truck procurement in Malaysia diverges sharply across institutional buyers, with Bomba Malaysia's federal specifications creating tiered compliance burdens that reshape supplier access and technical requirements by segment.
Product Type:
Volume concentration and margin profiles separate buyers seeking universal deployment capability from those targeting specialized emergency response.
- Pumper Trucks:These units integrate high-pressure pumping systems, water and foam tank assemblies, and hose storage on heavy-duty chassis exceeding 15 tonnes GVW. Municipal fire departments across Peninsular Malaysia deploy these universally, with Klang Valley stations driving replacement cycles due to high-rise density and industrial zone concentration.
- Aerial Trucks:Extendable boom platforms and stabilization systems enable elevated rescue and suppression operations. Kuala Lumpur and Petaling Jaya authorities mandate these for structures exceeding 30 meters, with complex hydraulics commanding premium unit margins and extended procurement lead times.
- Wildfire Trucks:Off-road chassis with enhanced water capacity and all-terrain mobility serve plantation estates across Sabah and Sarawak.
- Tankers:Bulk water transport units supplement pumper operations in areas with limited hydrant infrastructure.
Volume sits with Pumper Trucks; growth tilts toward Wildfire Trucks.
End User:
Budget authority and compliance stringency fragment procurement patterns across federal, industrial, and commercial operators.
- Municipal Fire Departments:Bomba Malaysia divisions enforce NFPA 1901-aligned specifications through federal tender processes. Fleet modernization mandates compress replacement cycles, forcing synchronization with national procurement calendars rather than discretionary local budgets.
- Industrial Facilities:Manufacturing complexes and logistics hubs operate private brigades with faster purchasing decisions. On-site risk assessments determine pump capacity and foam system requirements, bypassing SIRIM QAS timelines that delay municipal acquisitions.
- Oil & Gas Companies:Petrochemical terminals and offshore supply bases require explosion-proof configurations and specialized foam concentrates.
- Airport Authorities:Malaysia Airports Holdings and private aviation operators maintain aircraft rescue and firefighting (ARFF) fleets with rapid intervention vehicle specifications.
Municipal departments anchor installed base; industrial buyers expand most quickly.
Technology:
Integration depth and certification complexity determine supplier qualification barriers across system categories.
- Fire Suppression Systems:Pump assemblies, foam proportioning equipment, and monitor nozzles constitute core suppression capability. SIRIM QAS protocols now extend humidity resistance testing for electrical harness routing, filtering European suppliers unwilling to redesign for tropical conditions.
- Communication Systems:Radio interoperability and incident command integration enable multi-agency coordination. Bomba Malaysia pilot programs are scoring telematics-enabled diagnostics as tender evaluation criteria, shifting procurement toward digitally integrated platforms.
- Navigation Systems:GPS routing and pre-incident planning software reduce response times in dense urban corridors.
- Vehicle Modifications:Chassis upfitting, body fabrication, and equipment mounting adapt commercial platforms to fire service duty cycles.
Fire Suppression Systems dominate capital allocation; Communication Systems gain share fastest.
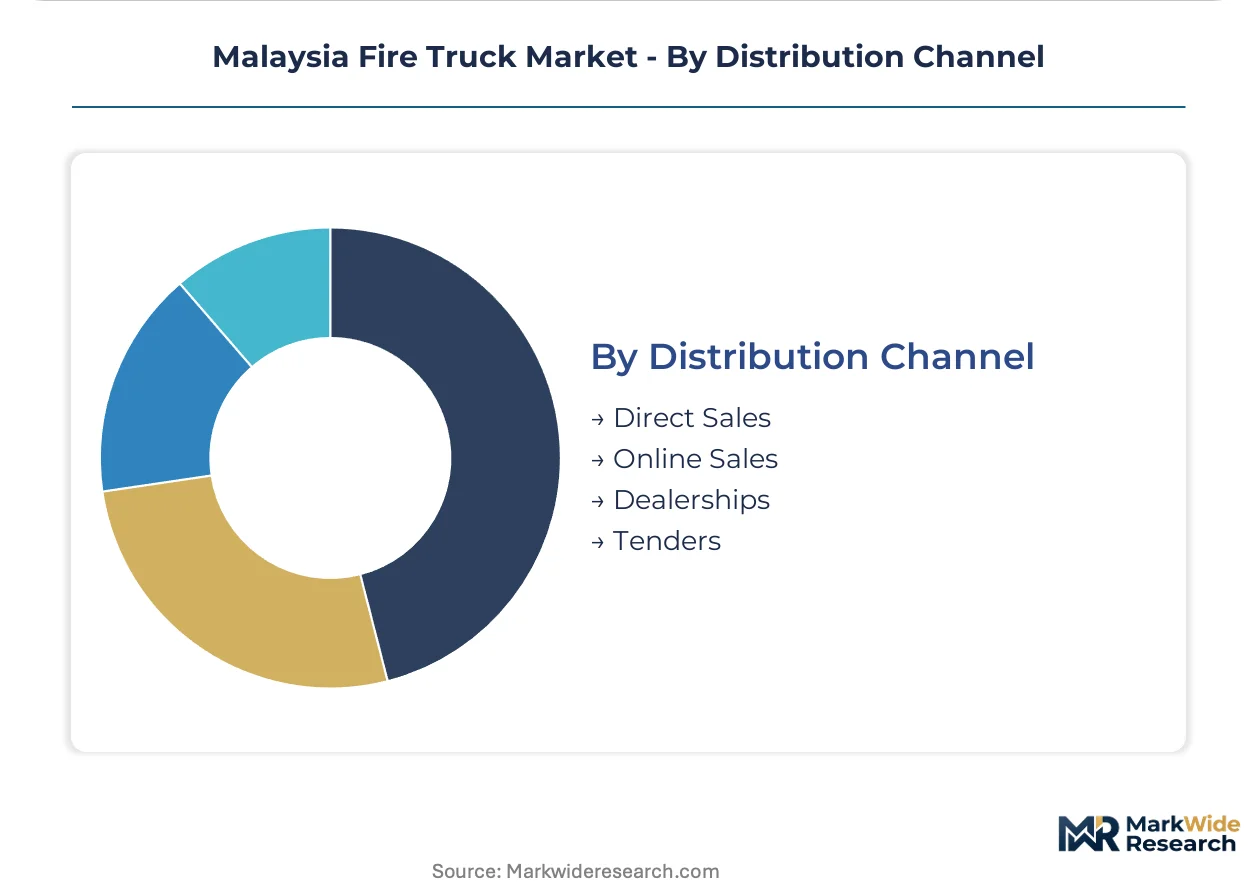
Distribution Channel:
Transaction structure and buyer sophistication shape channel selection across public and private procurement.
- Tenders:Federal and state government acquisitions operate through Bomba Malaysia's centralized bidding processes. NFPA 1901 compliance, SIRIM QAS certification, and local assembly partnerships determine bid competitiveness, with European manufacturers facing tariff exposure on completely built-up units.
- Direct Sales:Industrial buyers and plantation operators negotiate manufacturer relationships directly. Oil palm conglomerates in Sarawak and Sabah leverage volume commitments to secure customized wildfire configurations outside standard municipal specifications.
- Dealerships:Regional distributors provide aftermarket service and parts availability for secondary city fleets.
- Online Sales:Digital platforms facilitate equipment and parts procurement for maintenance operations.
Tenders command value concentration; direct sales climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iskandar Malaysia's special economic zone incentives have concentrated industrial fire protection procurement in southern Johor, while federal infrastructure spending directs municipal fleet investment toward Peninsular Malaysia's urban corridors.
Peninsular Malaysia
Klang Valley municipalities including Kuala Lumpur and Petaling Jaya drive aerial platform demand for high-rise fire suppression. Bomba Malaysia's federal specifications enforce NFPA 1901 alignment through centralized tender processes. Industrial zones in Shah Alam and Port Klang generate parallel procurement from private refinery and logistics operators.
Sabah
Plantation estates across the eastern lowlands mechanize wildfire response capabilities against recurring dry-season haze events. State procurement maintains older fleet inventories with less stringent tender competition than federal channels. Kota Kinabalu's port facilities and palm oil processing clusters anchor specialized industrial brigade formations.
Sarawak
Timber concessions and oil palm conglomerates in Miri and Bintulu create direct sales channels outside municipal budget cycles. State fire services operate with extended replacement timelines, offering first-mover positioning for localized assembly partnerships. Coastal humidity accelerates electrical system degradation, compressing asset lifespans below Peninsular benchmarks.
Johor
Iskandar Malaysia's manufacturing corridors attract industrial facility fire brigades with faster purchasing decisions than federal tenders. Pasir Gudang's petrochemical terminals require explosion-proof configurations and specialized foam systems. State government fleet consolidation under central leasing authorities is visible in Johor Bahru and secondary district stations.
Malaysia Fire Truck Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Malaysia's fire truck procurement channels. The vendor base organizes around three strategic archetypes: European manufacturers leveraging certification pedigree for federal Bomba contracts, regional assemblers reducing import duty exposure through localized partnerships, and domestic chassis specialists extending commercial vehicle expertise into emergency platforms. Dominant competitive moves include strategic partnerships with local distributors and portfolio diversification into modular pumper-aerial configurations.
Among European-based suppliers, Rosenbauer International AG and Ziegler Group occupy positions reflecting differentiated market access strategies. Rosenbauer exemplifies the certification-leverage archetype for premium federal tenders, while Ziegler represents the localized-assembly approach to tariff mitigation. Gemilang International anchors the domestic chassis-specialist tier, extending established commercial vehicle manufacturing capabilities into fire truck platform supply for regional markets.
| Leading Market Players |
|---|
| E-ONE Fire Trucks |
| HME, Inc. |
| Rosenbauer International AG |
| Bronto Skylift Oy Ab |
| Ziegler Group |
| Oshkosh Corporation |
| Sutphen Corporation |
| Gemilang International |
| Magirus GmbH |
| Others |
Value Chain & Pricing Dynamics
Modular pumper-aerial platform standardization is compressing manufacturing economics while redistributing bargaining power toward chassis-agnostic buyers across Malaysian procurement channels. This production-method transition simultaneously erodes premium pricing for integrated systems and rewards suppliers capable of rapid configuration flexibility.
Pricing Analysis
Lead-time premiums dominate transaction economics, with European manufacturers commanding substantial markups for sub-six-month delivery windows against spot-inventory discounts from regional assemblers. Three-tier pricing structure across premium, standard, and economy levels separates NFPA 1901-certified aerial platforms from municipal pumper configurations and refurbished legacy units. Pricing pressure stems from lease-to-own financing proliferation among Johor and Penang municipal councils, compressing upfront margins while extending revenue recognition timelines. Industrial buyers in Pasir Gudang petrochemical corridors exhibit lowest price sensitivity due to explosion-proof specification mandates, whereas secondary-city district stations prioritize total-cost-of-ownership optimization.
Supply Chain Analysis
Domestic-content thresholds under Bomba Malaysia tender evaluation criteria are compelling European manufacturers to establish localized assembly partnerships with Gemilang International and comparable chassis fabricators. Manufacturing concentration centers on Germany, Austria, and Malaysia, with pump assemblies and aerial boom hydraulics drawing from specialized component clusters in Central Europe. Raw material dependencies encompass high-strength steel for aerial structures, aluminum alloys for body fabrication, and specialized electrical harnessing rated for tropical humidity exposure. Single-source vulnerability concentrates in right-hand drive heavy-duty chassis supply, where extended lead times from narrow qualified supplier bases create procurement bottlenecks. Distribution runs through federal tender channels for municipal acquisitions, direct manufacturer relationships for plantation estate operators, and regional dealership networks for aftermarket service.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telematics-enabled predictive maintenance platforms are displacing legacy reactive service models across Malaysian fire authorities, creating asymmetric opportunity windows for digitally integrated suppliers before tender evaluation criteria harden.
For Market Incumbents: Extend certification investment into SIRIM QAS tropical climate amendments to defend federal Bomba contract access against European competitors unwilling to redesign electrical harness routing. Deepen backward integration into chassis supply through Gemilang International partnerships, mitigating import duty exposure that inflates landed costs for completely built-up units. Priority leverage sits with captive maintenance service networks addressing specialized technician scarcity in aerial boom hydraulics. For New Entrants and Emerging Players: Launch via direct sales channels targeting Sabah and Sarawak plantation estates, where wildfire truck demand accelerates outside federal tender competition and state procurement maintains older fleet inventories with less stringent compliance burdens. Prioritize modular platform architectures enabling rapid chassis reconfiguration, penetrating East Malaysian markets before incumbent localization investments mature. White-space concentration sits with hybrid drivetrain development anticipating Ministry of Housing and Local Government green procurement directives. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by European manufacturers seeking Malaysian assembly footholds for ASEAN market access, with secondary liquidity through regional chassis specialist consolidation. Long-term viability favors suppliers with demonstrated SIRIM QAS certification execution and established Bomba Malaysia federal relationships. Signal to monitor: hybrid drivetrain mandate timing from federal green procurement circulars, which would reshape chassis sourcing economics and disqualify pure-play combustion suppliers from upcoming tender cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Localized Assembly Partnership | Gemilang International chassis integration reduces European manufacturer import duty exposure by 15-25 percentage points under ASEAN trade protocols. |
| SIRIM QAS Certification Investment | Tropical climate electrical system validation filters non-compliant suppliers from Bomba Malaysia federal tender eligibility pools. |
| Telematics Platform Integration | Real-time pump diagnostics now score as weighted evaluation criteria in federal division pilot programs. |
| Lease-to-Own Financing Structure | Malayan Banking and CIMB operational leases transfer residual value risk from cash-constrained municipal councils. |
| Wildfire Truck Configuration Development | Off-road chassis specialization captures plantation estate procurement outside municipal budget cycles across Sabah and Sarawak. |
Study Parameters
Document review covered Bomba Malaysia equipment specifications, SIRIM QAS type-approval protocols, and Department of Standards Malaysia regulatory circulars, complemented by interviews with municipal fire department procurement officers, aerial platform maintenance technicians, plantation estate safety managers, and heavy-duty chassis distribution executives. Secondary validation drew from customs import records, federal tender award disclosures, and industrial facility fire brigade formation filings. Bottom-up fleet inventory analysis across Peninsular Malaysia and East Malaysian states was triangulated against top-down manufacturer shipment data.
Cross-referencing historical replacement cycle patterns with expert panel input on NFPA 1901 alignment timelines and green procurement directive probability shaped the analytical framework across the analysis window. Segmentation dimensions encompassed product type, end-user institutional category, technology system integration depth, and distribution channel structure. CAGRs were derived from installed base depreciation schedules, federal modernization mandate pacing, and plantation estate mechanization investment trajectories. Industry-specific inputs included monsoon corrosion degradation rates for electrical asset lifespans and right-hand drive chassis lead time elasticity.
Regulatory implementation delays, hybrid drivetrain mandate timing uncertainty, and chassis supply concentration shocks are the dominant revision risks that could compress or extend forecast trajectories. Forecasts reflect documented assumptions regarding Bomba Malaysia procurement calendar synchronization and SIRIM QAS validation window stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Big Rig Trucks Market
Heavy-Duty Trucks
Europe Medium & Heavy-Duty Truck Rental Market
Heavy-Duty Trucks
Heavy-Truck Composite Component Market
Heavy-Duty Trucks
Fire Trucks Market
Heavy-Duty Trucks
Heavy-Duty Truck Fleet Control Unit Architectures Market
Heavy-Duty Trucks
Bucket Trucks Market
Heavy-Duty Trucks
Automotive High Performance Trucks Market
Heavy-Duty Trucks
High Performance Trucks Market
Heavy-Duty Trucks
Platooning Trucks Market
Heavy-Duty Trucks
Asia Pacific Garbage Truck Bodies Market
Heavy-Duty Trucks
Europe Fire Truck Market
Heavy-Duty Trucks
Global Oversized Cargo Transportation Market
Heavy-Duty Trucks
Dump Truck & Body Market
Heavy-Duty Trucks
United States Tank Trucking Market
Heavy-Duty Trucks
Flatbed Truck Market
Heavy-Duty Trucks
Heavy Duty Truck Wash Market