
 High Performance Trucks Market | 2026-2036
High Performance Trucks Market Size, Share, and Industry Trends Forecast 2026-2036
High Performance Trucks Market Intelligence
Fleet procurement is pivoting toward fewer, larger buyers with centralized specifications. Daimler AG leverages its integrated powertrain manufacturing to capture vocational fleet contracts. Volvo Trucks anchors its position through advanced driver assistance packages tailored for long-haul operators. Paccar Inc competes on service network density, sustaining loyalty among independent owner-operators and regional distributors.
High performance trucks are heavy-duty commercial vehicles engineered for superior power-to-weight ratios, typically delivering torque outputs exceeding 1,000 lb-ft for sustained towing and hauling operations. These vehicles incorporate reinforced chassis architectures, multi-speed automated transmissions, and cooling systems designed for thermal management under peak load cycles. Diesel trucks retain dominant share in vocational segments where range and refueling infrastructure constrain alternatives, while electric trucks attract capital in last-mile and urban utility configurations where duty cycles align with battery economics. The hauling application commands premium pricing due to frame stress requirements and powertrain durability specifications. Telematics integration is reshaping fleet management economics, with real-time diagnostics reducing unplanned downtime across construction and logistics end users.
EPA Phase 3 standards, California Air Resources Board mandates, and EU Euro VII framework proposals are forcing concurrent powertrain redesigns across multiple geographies. Compliance timelines compress development cycles, advantaging manufacturers with captive engine production and software-defined vehicle architectures. Stakeholders must monitor regulatory divergence between North American and European test protocols, as incompatible certification paths threaten platform economics and cross-border fleet standardization.
Market Dynamics
Powertrain electrification timelines are colliding with vocational fleet replacement cycles, forcing manufacturers to serve parallel diesel and electric demand pools through shared chassis architectures.
Growth Catalysts
- EPA Phase 3 Standards:The regulation tightens greenhouse gas limits for heavy-duty vehicles, accelerating fleet turnover toward compliant powertrains in long-haul corridors.
- Construction Material Hauling:Infrastructure investment in the United States, Germany, and China is expanding demand for high-torque vocational trucks with reinforced frame architectures.
- Telematics Integration:Real-time diagnostic systems are reducing unplanned downtime, improving total cost of ownership calculations for logistics operators.
Market Restraints
- Battery Cell Supply Concentration:Cathode material processing clusters in China create input cost volatility and geopolitical exposure for electric truck programs.
- Diesel Powertrain Sunk Costs:Existing service infrastructure and technician training represent structural barriers to alternative fuel adoption in remote hauling routes.
- Range Limitation:Energy density constraints in current battery chemistries restrict electric truck viability to sub-500-mile duty cycles.
Strategic Opportunities
- India Vocational Fleet Modernization:The country's tightening BSVI emission norms and infrastructure build-out create replacement demand for heavy-duty construction trucks.
- Autonomous Convoy Technology:Platooning systems are converging with advanced driver assistance packages to enable driver-reduced operations on designated freight corridors.
- California HVIP Incentives:The voucher program subsidizes electric and hydrogen truck purchases, accelerating zero-emission adoption in drayage and regional distribution.
Industry Challenges
- Powertrain Software Integration:Coordinating engine control modules with battery management systems across hybrid architectures demands scarce embedded systems engineering talent.
- Dual Certification Burden:Divergent EPA and EU test protocols for emissions and fuel consumption force redundant validation cycles on shared global platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Performance Trucks Market |
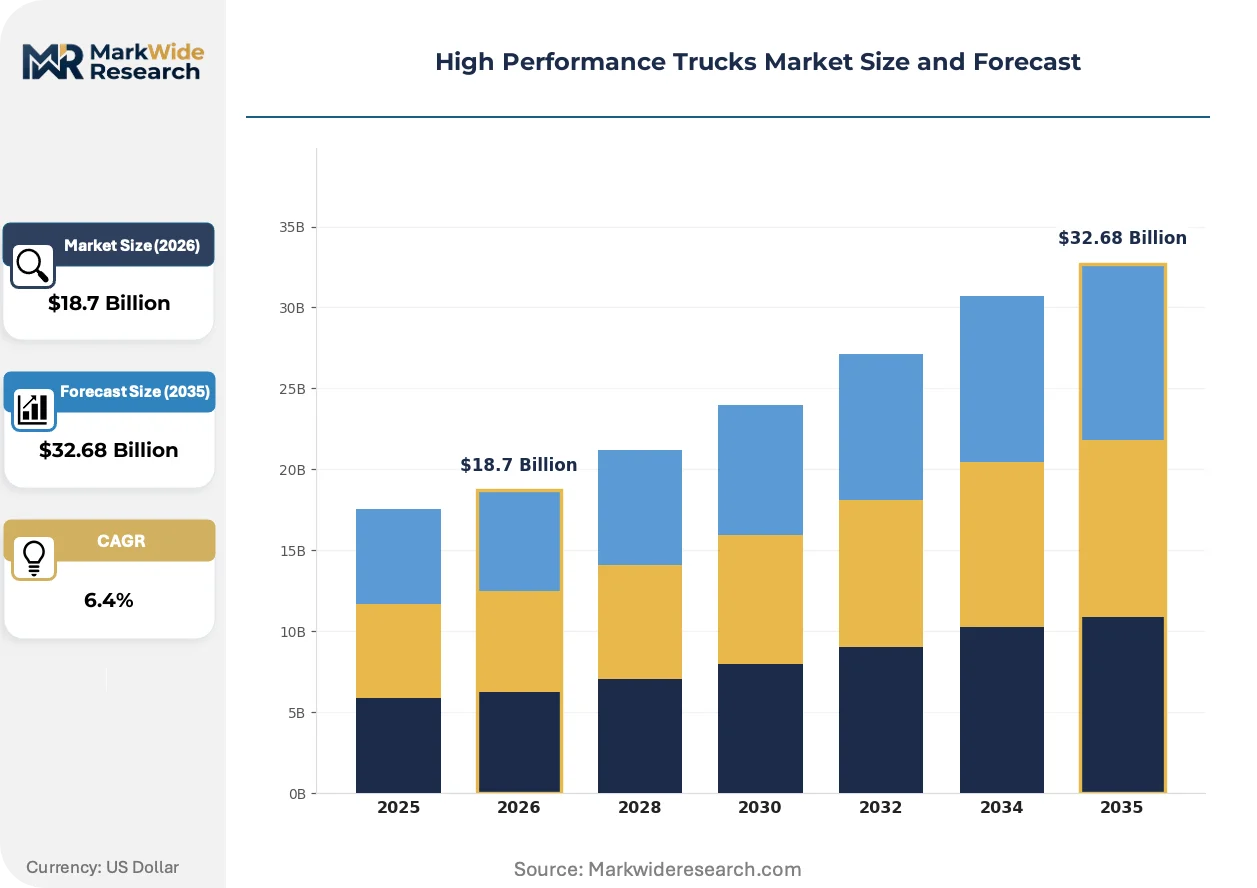
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diesel Trucks, Gasoline Trucks, Hybrid Trucks, Electric Trucks End User: Construction, Agriculture, Logistics, Emergency Services Application: Towing, Hauling, Off-road, Utility Technology: Advanced Driver Assistance Systems, Telematics, Adaptive Cruise Control, Turbocharging |
| Companies Covered | Ford Motor Company, General Motors, Volvo Trucks, Daimler AG, Toyota Motor Corporation, MAN SE, Hennessey Performance, Paccar Inc, Scania AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Performance Trucks Market Strategic Shifts & Innovations
Software-defined vehicle architectures are displacing hardware-centric development cycles, enabling powertrain updates through over-the-air deployment and compressing model-year refresh timelines.
Silicon carbide power electronics are converging with high-voltage battery architectures to improve inverter efficiency in electric drivetrains. Long-haul fleet operators in Germany are piloting 800-volt platforms for reduced charging dwell times. This convergence is compressing the performance gap between diesel and electric torque delivery curves.
California's Advanced Clean Trucks regulation mandates escalating zero-emission sales percentages through 2035. Manufacturers must certify electric variants alongside diesel offerings or face market exclusion. Vocational segments with predictable return-to-base patterns are absorbing compliance volume first.
Fleet procurement is consolidating around lifecycle cost models rather than upfront capital expenditure. Large logistics operators in the United States are unbundling vehicle acquisition from maintenance contracts, pressuring manufacturers to guarantee uptime through service-level agreements. This shift is most visible among e-commerce fulfillment networks with dedicated private fleets.
High Performance Trucks Market Segmentation
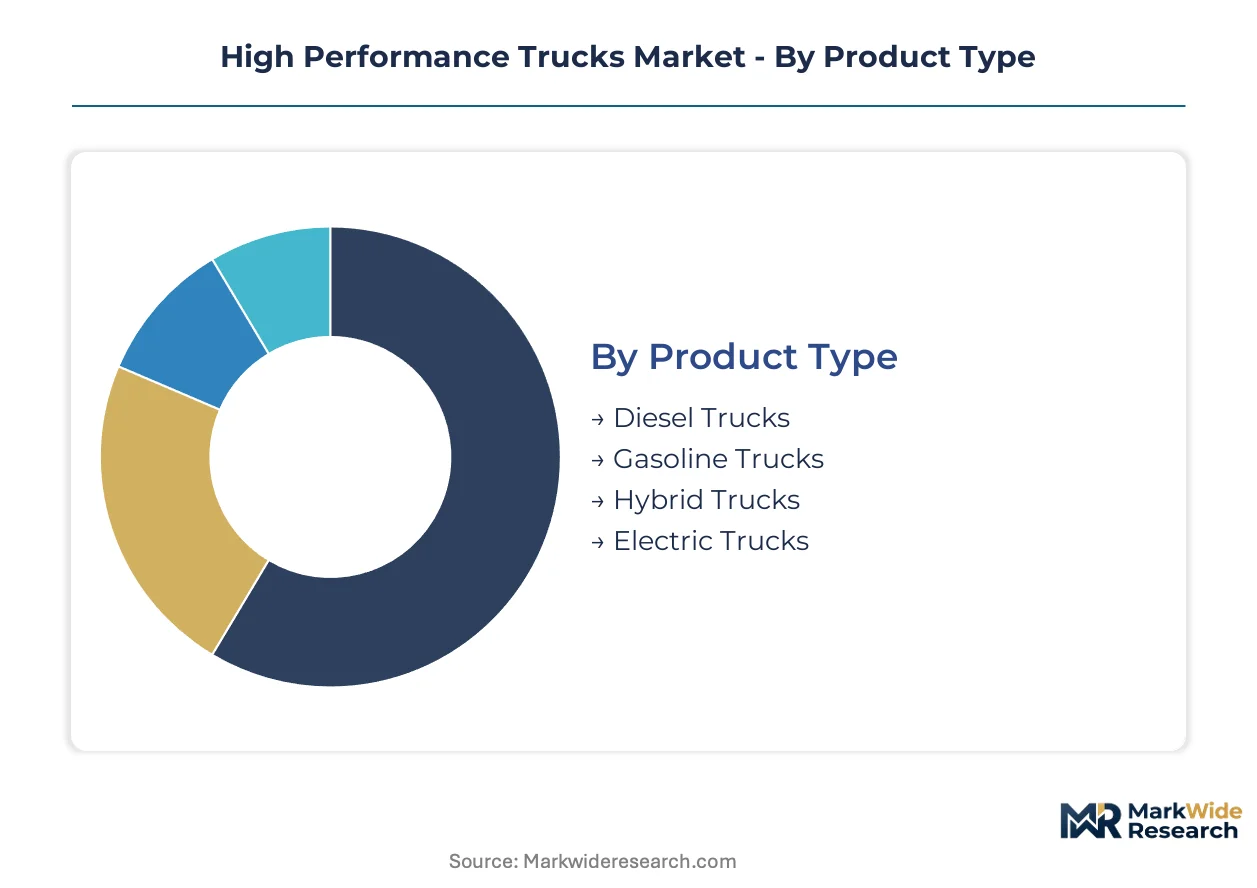
Powertrain heterogeneity and duty-cycle specialization create distinct investment profiles across the high performance trucks landscape. Fleet operators segment procurement by total cost of ownership rather than sticker price alone.
Product Type:
Capital intensity varies dramatically across powertrain architectures, with electric platforms requiring the highest upfront investment in battery packs and thermal management infrastructure.
- Diesel Trucks:Compression-ignition engines with high-pressure common rail injection deliver torque outputs exceeding 1,000 lb-ft for sustained heavy-haul operations. Vocational fleets in the United States and Germany prioritize these platforms for corridors lacking charging infrastructure, though EPA Phase 3 compliance is compressing model lifecycles.
- Electric Trucks:Lithium-ion battery architectures with silicon carbide inverters enable regenerative braking and zero-tailpipe operation. California's Advanced Clean Trucks regulation mandates escalating sales percentages, concentrating demand in drayage and urban utility configurations where return-to-base patterns align with depot charging economics.
- Hybrid Trucks:Parallel powertrain architectures combine downsized diesel engines with electric assist for transient load smoothing. These platforms serve as compliance bridges for fleets navigating uncertain infrastructure buildout timelines.
- Gasoline Trucks:Spark-ignition engines with port or direct fuel injection occupy lighter vocational segments and owner-operator niches where acquisition cost sensitivity outweighs fuel economy optimization.
Diesel trucks absorb the bulk of installed capacity; electric trucks are expanding most quickly.
End User:
Procurement patterns diverge sharply between cyclical capital expenditure sectors and steady-state logistics operators with predictable replacement schedules.
- Logistics:Dedicated private fleets and for-hire carriers specify vehicles through lifecycle cost models, unbundling acquisition from maintenance contracts. E-commerce fulfillment networks in the United States and Germany are consolidating procurement around uptime guarantees and telematics integration.
- Construction:Infrastructure investment in the United States, Germany, and China is expanding demand for high-torque vocational trucks with reinforced frame architectures and multi-speed automated transmissions. Fleet turnover accelerates when public project pipelines swell.
- Agriculture:Seasonal duty cycles and rural refueling infrastructure constraints sustain demand for diesel platforms with field-serviceable components. Procurement concentrates around harvest financing windows.
- Emergency Services:Municipal and specialty vehicle upfitters require chassis with dedicated electrical architectures for auxiliary equipment. Specifications prioritize reliability certifications and rapid parts availability over fuel economy metrics.
Logistics commands the largest revenue pool; construction is climbing the fastest as infrastructure stimulus compounds.
Application:
Frame stress requirements and powertrain durability specifications create tiered pricing structures that separate premium hauling configurations from standard utility platforms.
- Hauling:Reinforced chassis architectures with double-frame rail construction and air-ride suspensions manage peak loads in aggregate and construction material transport. These configurations command premium pricing due to metallurgical specifications and warranty exposure.
- Towing:Fifth-wheel and gooseneck hitch integrations with integrated trailer brake controllers serve heavy-equipment and recreational vehicle markets. Demand concentrates in the United States where consumer towing culture sustains a distinct product category.
- Off-road:Locking differentials, elevated air intakes, and underbody protection packages enable operation on unimproved surfaces. Mining and forestry applications in remote geographies specify these platforms despite higher total cost of ownership.
- Utility:Service body and crane body upfit compatibility drives specifications for municipal and contractor fleets with diverse equipment mounting requirements.
Hauling generates the highest average transaction prices; towing is gaining share fastest as recreational vehicle sales persist.
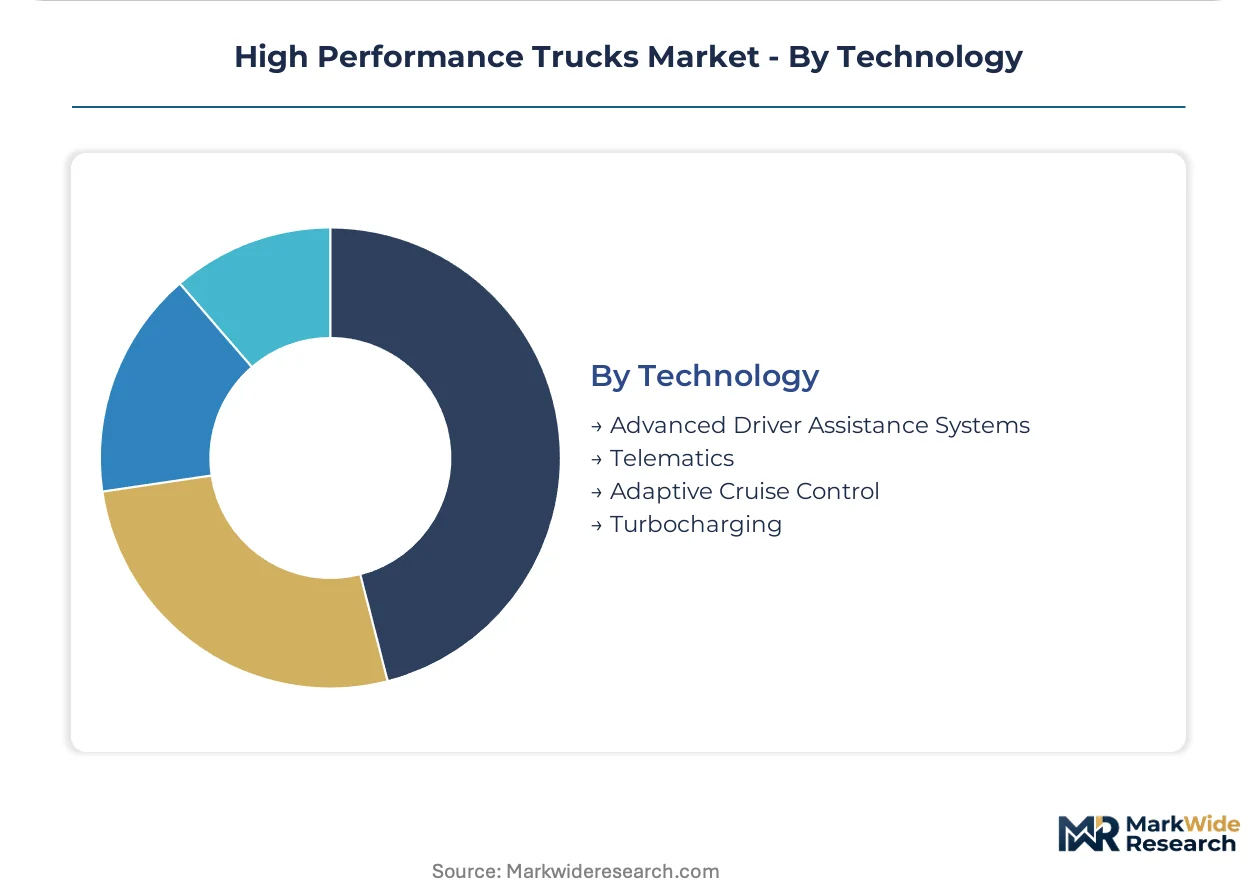
Technology:
Software-defined architectures are displacing hardware-centric development cycles, enabling feature activation through over-the-air deployment and compressing refresh timelines.
- Telematics:Cellular-connected diagnostic systems transmit fault codes and operational parameters to fleet management platforms. Real-time visibility into component health is reducing unplanned downtime for logistics operators with dense vehicle concentrations.
- Advanced Driver Assistance Systems:Sensor fusion architectures combining radar and camera inputs enable collision mitigation and lane-keeping assistance. Long-haul operators in Germany are piloting these packages as precursors to platooning deployment.
- Turbocharging:Variable geometry and twin-scroll turbocharger designs extract power density from downsized engines while maintaining transient response for vocational duty cycles.
- Adaptive Cruise Control:Radar-based following distance management reduces driver fatigue on designated freight corridors and integrates with predictive powertrain control for fuel economy optimization.
Telematics penetration is deepest among large fleet operators; advanced driver assistance systems are expanding most quickly as regulatory pressure for collision avoidance intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet procurement concentrates where infrastructure investment intersects with stringent emission mandates. Three countries absorb the majority of high-performance truck volume.
United States
Logistics operators and construction fleets drive replacement demand across Texas and California freight corridors. EPA Phase 3 greenhouse gas standards compress model-year lifecycles for long-haul diesel configurations. The Dallas-Fort Worth metro anchors vocational fleet procurement, with regional distributors consolidating around telematics-integrated platforms.
Germany
Long-haul operators and construction material haulers specify vehicles through lifecycle cost optimization frameworks. The EU Euro VII framework proposals force concurrent powertrain redesigns across vocational segments. Bavaria's manufacturing belt hosts dense concentrations of fleet service networks and captive engine production facilities.
China
Infrastructure stimulus and mining operations sustain demand for high-torque vocational platforms in western provinces. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate electric truck pilots in port drayage. The Yangtze River Delta cluster concentrates battery-electric truck deployment for urban utility configurations.
India
Construction fleet modernization and BSVI emission compliance create replacement cycles for heavy-duty platforms. The Central Pollution Control Board enforces tightening particulate matter standards that phase out pre-2016 engines. Maharashtra's Mumbai-Pune industrial corridor absorbs premium vocational truck volumes for cement and aggregate hauling.
Japan
Precision logistics and disaster response fleets sustain demand for specialized high-performance configurations. METI promotes hydrogen fuel cell commercialization through designated freight corridor pilots. The Kanto region around Tokyo concentrates urban delivery electrification programs with depot charging infrastructure.
High Performance Trucks Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue electric powertrain specialization and software-defined architectures. The market structures around three tiers: integrated powertrain manufacturers with captive engine production, chassis specialists relying on supplier ecosystems, and technology-focused entrants leveraging battery-electric platforms. Competitive moves concentrate on strategic partnerships for charging infrastructure and geographic expansion into vocational fleet strongholds.
Among integrated manufacturers, Daimler AG and Volvo Trucks anchor the premium tier through vertical control over powertrain and chassis architectures. Paccar Inc represents the distributor-network archetype, competing through service density rather than manufacturing scope. These three entities exemplify divergent strategic positions: captive integration, technology packaging, and aftermarket loyalty.
| Leading Market Players |
|---|
| Ford Motor Company |
| General Motors |
| Volvo Trucks |
| Daimler AG |
| Toyota Motor Corporation |
| MAN SE |
| Hennessey Performance |
| Paccar Inc |
| Scania AB |
| Others |
Cost & Logistics Intelligence
Family-owned vocational fleet operators in the United States and Germany anchor procurement consolidation, compressing distributor margins while rewarding manufacturers with captive powertrain production and dense service networks. Their financing patterns favor lifecycle cost contracting over upfront capital expenditure, forcing pricing discipline upstream through multi-year uptime guarantees and unbundled maintenance agreements.
Pricing Analysis
Volume concentration among large logistics operators splits margin capture away from smaller distributors toward integrated manufacturers with software-defined architectures. Three-tier pricing structure across premium, standard, and economy levels stratifies by powertrain certification grade and telematics bundling intensity. Pricing pressure stems from EPA Phase 3 compliance costs and California's Advanced Clean Trucks mandates, which force redundant platform engineering. Independent owner-operators exhibit highest price sensitivity; dedicated private fleets with e-commerce backing show lowest sensitivity due to uptime-guarantee contracting.
Supply Chain Analysis
Regional distribution centers in Texas, California, and Bavaria operate as hub-and-spoke consolidation points for chassis components and powertrain modules. Manufacturing concentration rests on Germany, China, and the United States for engine blocks, automated transmissions, and axle assemblies. Cathode material processing and silicon carbide wafer production draw from China, South Korea, and Japan. Single-source vulnerability in battery cell supply creates geopolitical exposure for electric truck programs. Distribution runs through captive OEM service networks and independent dealer channels with parts depot satellite coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high performance trucks sector sits in a powertrain transition phase where battery-electric architectures displace diesel dominance in vocational segments with predictable return-to-base duty cycles. Software-defined vehicle platforms enable over-the-air powertrain optimization, compressing traditional hardware refresh economics.
For Market Incumbents: Hedge diesel platform obsolescence by accelerating silicon carbide inverter and 800-volt battery architecture development for long-haul corridors. Secure cathode material offtake agreements in South Korea and Japan to reduce China supply concentration. Defensive consolidation through captive engine production integration protects margin pools against emerging electric-only entrants with asset-light manufacturing models.
For New Entrants and Emerging Players: California's Advanced Clean Trucks regulation opens a window for zero-emission specialist manufacturers to capture drayage and regional distribution volume ahead of incumbent platform diversification. Target port freight corridors with depot charging infrastructure already deployed. Pursue fleet-as-a-service contracting with municipal utility partnerships to bypass upfront capital barriers for vocational fleet operators.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier chassis specialists with established upfitter relationships in India and Southeast Asia construction markets. Long-term viability hinges on software-defined architecture capabilities and charging infrastructure partnership access. Monitor California HVIP voucher utilization rates as the inflection signal for electric truck demand acceleration beyond compliance-driven procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Powertrain Platform Standardization | Shared chassis architectures for diesel, hybrid, and electric variants reduce EPA Phase 3 compliance engineering redundancy across Daimler and Volvo production lines. |
| Battery Supply Agreement | Long-term cathode material contracts with South Korean suppliers mitigate China concentration risk for Paccar's electric truck ramp in California freight corridors. |
| Software-Defined Vehicle Investment | Over-the-air powertrain calibration capabilities compress model-year refresh timelines and enable subscription-based feature activation for logistics fleet operators. |
| Geographic Manufacturing Footprint | Regional assembly expansion in Texas and Bavaria positions manufacturers near construction fleet procurement clusters with reinforced frame specification demand. |
| Charging Infrastructure Partnership | Depot charging network alliances with electric utilities accelerate California drayage fleet electrification under Advanced Clean Trucks compliance timelines. |
Research Approach
Document review covered EPA regulatory filings, California Air Resources Board rulemaking records, EU Euro VII framework proposals, and vehicle production databases, complemented by interviews with fleet procurement directors, OEM platform engineers, Tier 1 supplier account managers, and aftermarket service network heads. Secondary validation drew from SEC 10-K disclosures, customs trade data, and infrastructure investment pipeline reports. Bottom-up demand modeling across powertrain segments triangulated against top-down market sizing from regulatory compliance volume mandates.
Unit shipment and revenue estimates emerged from segment-level penetration curves applied across the projection horizon. Modeling dimensions included powertrain architecture, vocational application intensity, fleet size tier, and regional regulatory cluster. CAGRs were derived from replacement cycle timing, infrastructure stimulus disbursement schedules, and emission mandate phase-in slopes. Forecast inputs incorporated battery cost decline trajectories and charging infrastructure buildout assumptions specific to drayage and construction material hauling corridors.
The model assumes a particular technology adoption path; alternative pathways for hydrogen fuel cell commercialization or solid-state battery deployment would alter the outlook for electric truck penetration in long-haul segments. Forecasts reflect stated assumptions on regulatory enforcement consistency and cathode material supply elasticity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Truck Diagnostic Market
Heavy-Duty Trucks
Mexico Refrigerated Truck Market
Heavy-Duty Trucks
Truck Racks Market
Heavy-Duty Trucks
Truck Headache Rack Market
Heavy-Duty Trucks
Articulated Hauler Market
Heavy-Duty Trucks
US Vacuum Truck Market
Heavy-Duty Trucks
US Tanker Truck Market
Heavy-Duty Trucks
Tipper Truck Market
Heavy-Duty Trucks
Europe Medium & Heavy-Duty Truck Rental Market
Heavy-Duty Trucks
Stacker Truck Market
Heavy-Duty Trucks
Heavy-Duty Truck Dashboard Switch Panel Systems Market
Heavy-Duty Trucks
Heavy-Duty Vehicle Engine Brake Market
Heavy-Duty Trucks
Fire Trucks Market
Heavy-Duty Trucks
Heavy-Truck Composite Component Market
Heavy-Duty Trucks
Full Truck Load (FTL) Market
Heavy-Duty Trucks
Turret Truck Market