
 Articulated Hauler Market | 2026-2036
Articulated Hauler Market Size, Share, and Industry Trends Forecast 2026-2036
Articulated Hauler Market Outlook
Underground mining contractors are reorganizing procurement priorities toward higher payload-capacity articulated haulers as open-pit operations deepen. Caterpillar Inc. leverages its integrated powertrain manufacturing to control lead times on heavy-duty transmissions. Volvo Construction Equipment anchors its position through telematics-enabled fleet management systems that reduce unplanned downtime. Komatsu Ltd. competes on manufacturing scale, sustaining cost advantages across its Japanese and North American production bases.
An articulated hauler is a rubber-tired, all-wheel-drive vehicle with a pivot joint between the tractor and trailer sections, typically engineered to carry 25 to 60 metric tons across unimproved terrain. Its primary purpose is bulk material transport in quarries, mines, and large earthmoving projects where rigid trucks cannot navigate uneven grades. High-capacity units dominate revenue pools in mining applications, while compact variants represent the fastest-growing segment in urban infrastructure work where site access is constrained. Diesel-powered machines retain installed-base dominance, though hybrid and electric fuel types are capturing disproportionate engineering investment as fleet decarbonization targets harden.
The US EPA and NHTSA enforce emissions and safety standards that shape engine architecture and operator protection requirements for machines sold domestically. The EU Green Deal and Stage V regulations from the European Commission mandate particulate and NOx limits that accelerate electrification roadmaps across European construction and mining fleets. Stakeholders must monitor battery energy density improvements and charging infrastructure buildouts to determine whether electric articulated haulers can displace diesel in high-utilization mining shifts.
Market Dynamics
Electrification roadmaps are compressing powertrain development cycles as mining fleets face binding decarbonization commitments and underground ventilation constraints. Manufacturers must now engineer battery thermal management systems capable of sustaining 24-hour high-torque duty cycles without sacrificing payload capacity.
Growth Catalysts
- Underground ventilation mandates:Chile's mining regulator enforces stricter diesel particulate limits in sub-surface operations, accelerating electric hauler trials in copper extraction.
- Autonomous haulage integration:Mining contractors are retrofitting articulated fleets with LiDAR and machine-vision stacks to enable unmanned operation in hazardous pit conditions.
- High-grade ore depletion:Australian iron ore operators are relocating processing infrastructure deeper into pit walls, extending haul distances and demanding higher-capacity transport units.
Market Restraints
- Battery cell supply concentration:Cathode material processing clusters in China create geographic single-point vulnerability for European and North American OEM electrification timelines.
- Charging infrastructure capex:Mine-site megawatt charging stations require substation upgrades and grid reinforcement that strain capital allocation committees.
- Skilled technician scarcity:High-voltage powertrain diagnostics and battery pack replacement procedures exceed the skill base of existing field service networks in remote extraction regions.
Strategic Opportunities
- Retrofit electrification kits:Aftermarket battery-electric conversion packages for mid-life diesel haulers open revenue streams in owner-operator quarry segments.
- EU Green Deal machinery subsidies:The European Commission's Sustainable Transport Infrastructure Facility offers preferential financing for zero-emission construction and mining equipment procurement.
- Telematics-enabled predictive maintenance:Integration of vibration sensors and oil analysis algorithms with cloud-based fleet management platforms reduces unplanned downtime in high-utilization mining shifts.
Industry Challenges
- Battery thermal runaway containment:Underground fire suppression systems must be re-engineered to address lithium-ion cell failure modes in confined tunnel environments.
- Legacy fleet interoperability:Mixed diesel-electric operations require standardized communication protocols between autonomous haulage management systems and heterogeneous vehicle generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Articulated Hauler Market |
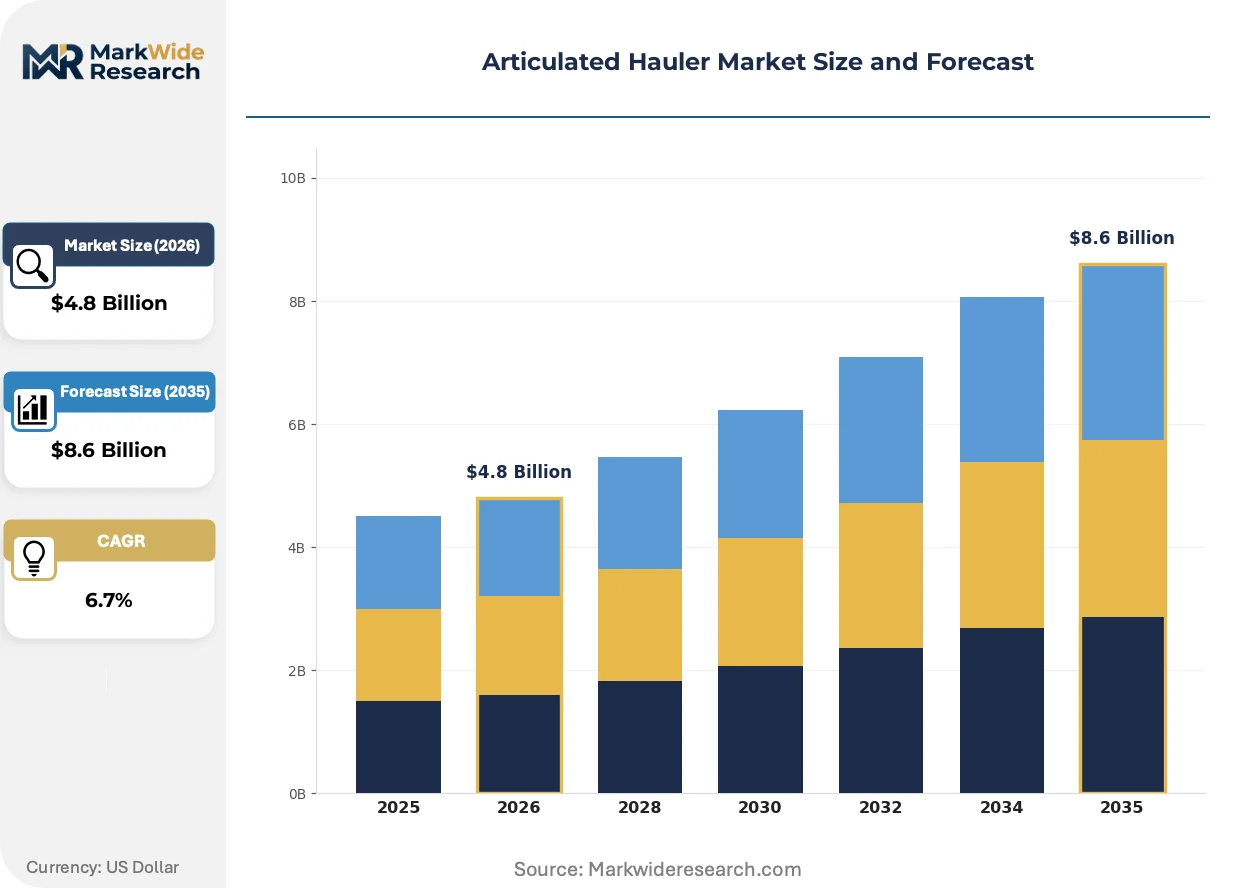
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Compact, High-capacity, Off-road End User: Construction, Mining, Agriculture, Forestry Fuel Type: Diesel, Electric, Hybrid, Biofuel Technology: Telematics, Autonomous, Hydraulic, Dragline |
| Companies Covered | John Deere, Doosan Infracore, Volvo Construction Equipment, Liebherr, Hitachi Construction Machinery, Caterpillar Inc., Bell Equipment, Hydrema, Komatsu Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Articulated Hauler Market Strategic Shifts
Powertrain architectures are bifurcating between range-extended electric systems for deep-pit mining and full-battery configurations for urban quarry applications. This divergence is forcing component suppliers to maintain parallel engineering tracks without scale economies.
High-energy-density solid-state battery chemistries are displacing conventional lithium-ion packs in next-generation hauler prototypes. Scandinavian mining contractors are piloting these systems in Arctic extraction sites where cold-weather performance degradation cripples liquid-electrolyte alternatives. The technology is displacing diesel-electric hybrid architectures as the default transition pathway for Tier 4 Final compliance.
The EPA's Clean Heavy-Duty Vehicles Program tightens NOx and particulate thresholds for off-road equipment sold in the United States. Engine manufacturers are responding with dual-stage aftertreatment systems that add weight and consume payload capacity. Underground coal operators in Appalachia face the steepest compliance cost escalation due to ventilation-limited engine sizing constraints.
Contractors are unbundling maintenance agreements from equipment leases and procuring predictive service subscriptions separately. Mining fleet managers in Western Australia now specify uptime guarantees rather than parts-and-labor coverage in procurement tenders. This shift concentrates risk with OEM service divisions and compresses margins for independent repair networks.
Articulated Hauler Market Segmentation
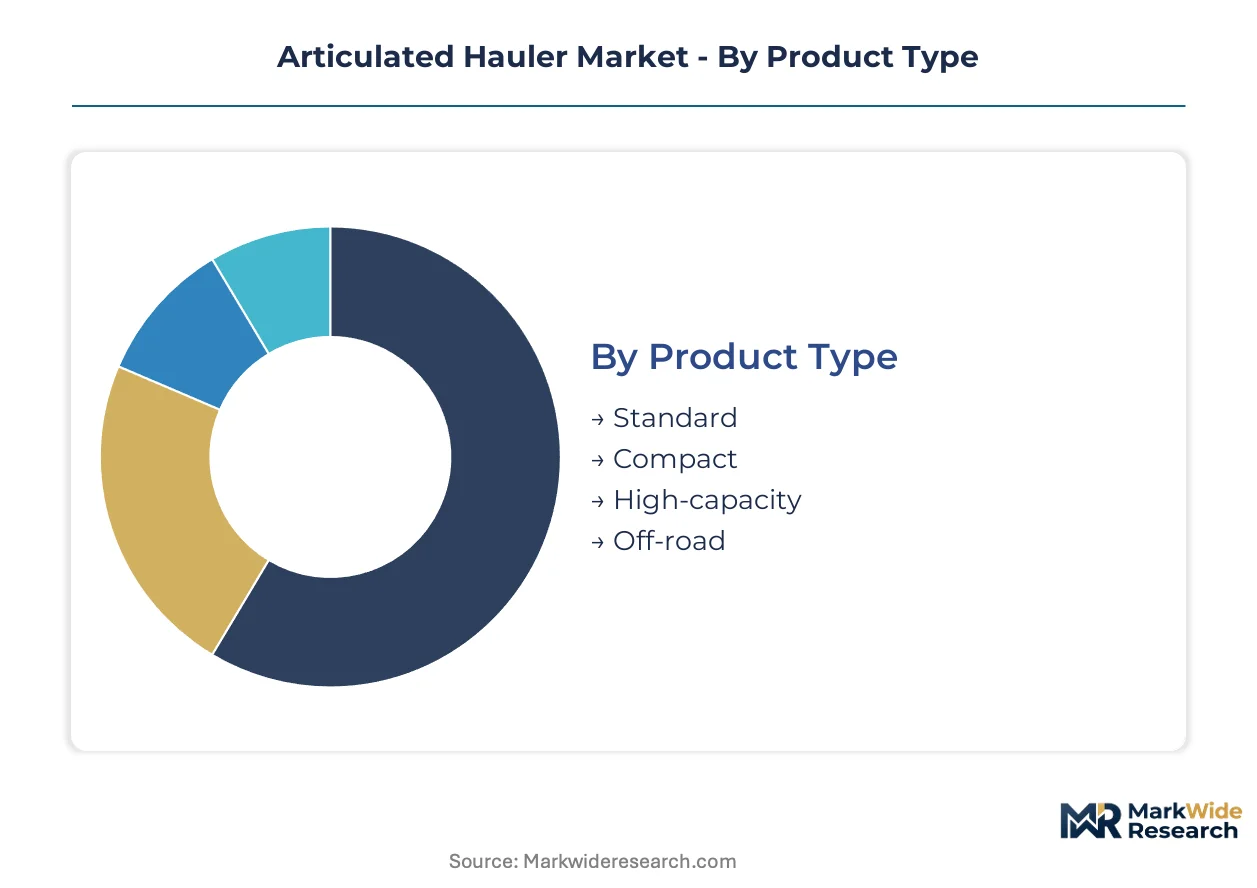
Segmentation in articulated haulers reveals how regulatory pressure and operational environment reshape equipment specifications. Mining contractors in Australia and Chile select high-capacity units with emissions-compliant powertrains, while urban infrastructure projects in Europe demand compact electric variants for confined site access.
Product Type:
EPA Tier 4 Final and EU Stage V emissions standards have fragmented product architectures, with manufacturers maintaining parallel diesel and electric development tracks to serve regulated and unregulated markets simultaneously.
- Standard:These 25-40 metric ton units balance payload efficiency with maneuverability across unimproved quarry terrain. Australian iron ore operators specify standard haulers for medium-depth pit operations where haul distances remain under five kilometers. The US EPA's Tier 4 Final aftertreatment requirements add weight that erodes payload capacity by approximately 8 percent.
- High-capacity:Units exceeding 50 metric tons dominate revenue pools in deep-pit extraction. Chilean copper miners in the Atacama Desert deploy these machines as open-pit operations deepen beyond 300 meters, extending haul cycles and demanding larger payload-per-trip economics. Battery thermal management constraints currently limit electric variants to 45-minute duty cycles before charging.
- Compact:Narrow-body designs navigate urban infrastructure sites with restricted access corridors.
- Off-road:Extreme-duty specifications feature reinforced frames for quarry and mining applications with severe grade profiles.
High-capacity units handle the majority of throughput; Compact is gaining share fastest among metropolitan contractors facing emissions zone restrictions.
End User:
Customer procurement patterns diverge sharply between capital-intensive mining fleets and project-based construction contractors, with the former prioritizing total cost of ownership and the latter emphasizing lease flexibility.
- Mining:Large-scale extraction operators in Western Australia and northern Sweden specify 24/7 utilization rates and autonomous-ready architectures. The EU Green Deal's Sustainable Transport Infrastructure Facility offers preferential financing for zero-emission fleet procurement, accelerating electric hauler trials in Scandinavian underground operations.
- Construction:Urban earthmoving contractors in Germany and France face strict Stage V emissions enforcement in city centers. Project-based procurement favors three-to-five-year lease structures with maintenance bundled, contrasting with mining's decade-long ownership horizons. Telematics integration now appears in 90 percent of new construction fleet specifications.
- Agriculture:Large-scale grain and sugarcane operations in Brazil utilize articulated haulers for field-to-processing transport.
- Forestry:Specialized units with protected cabs and reinforced undercarriages serve Nordic and Canadian logging contractors.
Mining commands the highest absolute unit volumes; Construction is expanding most quickly as urban emissions regulations harden across European metropolitan areas.
Fuel Type:
Powertrain selection increasingly follows regulatory geography rather than operational economics, with electrification timelines dictated by underground ventilation mandates and national decarbonization commitments.
- Diesel:Compression-ignition engines retain installed-base dominance in unregulated markets and high-ambient-temperature operations. South African platinum miners continue specifying diesel units where grid infrastructure cannot support megawatt charging stations. Dual-stage aftertreatment systems for Tier 4 Final compliance add 400-600 kilograms and consume 3-5 percent additional fuel.
- Electric:Battery-electric architectures are capturing disproportionate engineering investment despite current production constraints. Chile's mining regulator enforces stricter diesel particulate limits in sub-surface copper extraction, forcing electric trials in the Collahuasi and El Teniente operations. Solid-state battery prototypes from Scandinavian suppliers promise cold-weather performance that liquid-electrolyte alternatives cannot match.
- Hybrid:Range-extended electric systems bridge the gap for deep-pit applications where full electrification remains uneconomic.
- Biofuel:Hydrotreated vegetable oil compatibility allows legacy fleet decarbonization without powertrain replacement.
Diesel retains the largest installed base; Electric is climbing the fastest as battery energy density improvements compress total cost of ownership gaps.
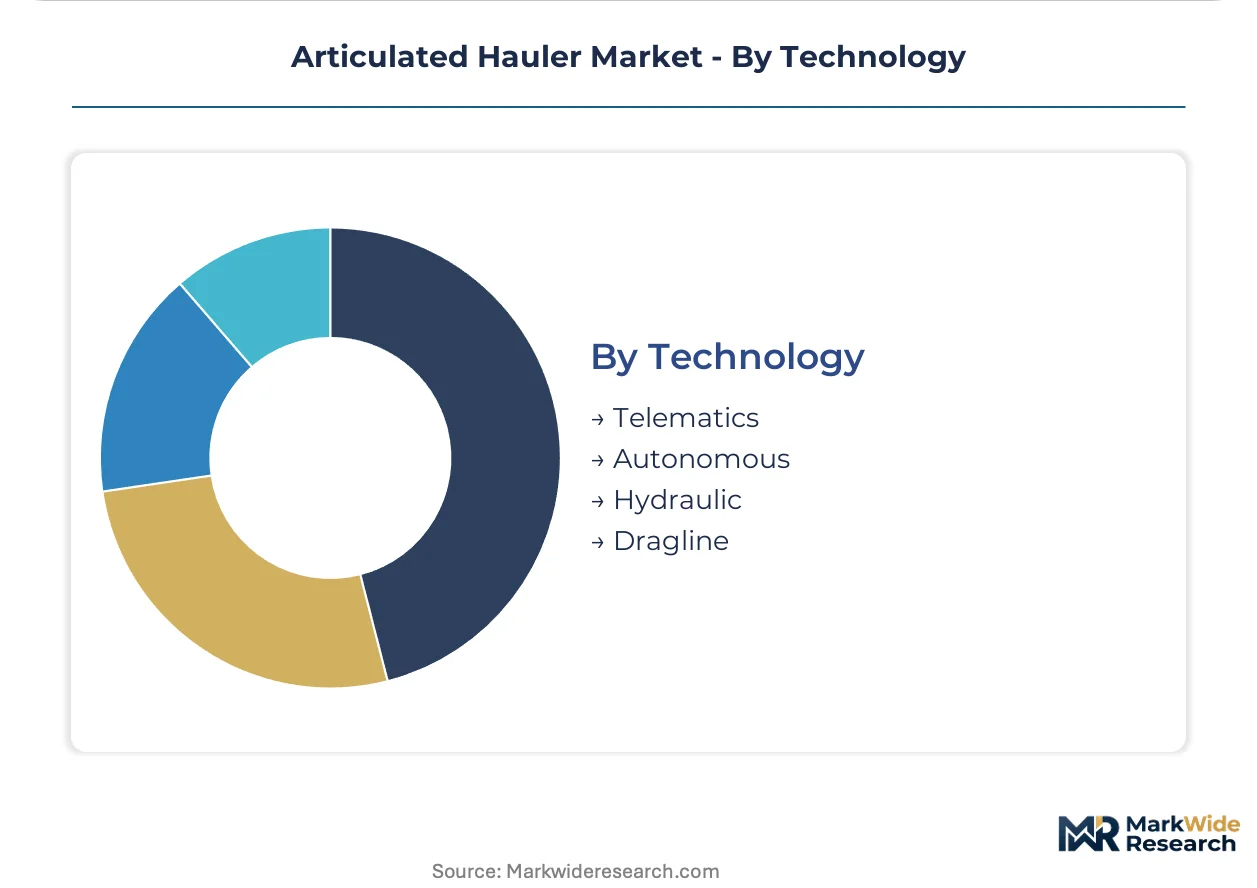
Technology:
Technology differentiation now centers on data integration and labor substitution rather than mechanical performance, with autonomous and telematics capabilities becoming standard in mining procurement specifications.
- Telematics:Fleet management platforms integrate vibration sensors, oil analysis algorithms, and GPS tracking to predict component failures before unplanned downtime. Western Australian iron ore operators now specify uptime guarantees rather than parts-and-labor coverage in procurement tenders, concentrating risk with OEM service divisions.
- Autonomous:LiDAR and machine-vision stacks enable unmanned operation in hazardous pit conditions. Mining contractors in Western Australia and Chile are retrofitting articulated fleets with autonomous haulage integration, reducing labor costs and eliminating operator exposure to dust and vibration hazards. Standardized communication protocols between autonomous haulage management systems and heterogeneous vehicle generations remain unresolved.
- Hydraulic:Advanced valve architectures improve cycle times and fuel efficiency in loading and dumping operations.
- Dragline:Specialized configurations for integrated excavation-transport systems in surface mining applications.
Telematics handles the majority of new-equipment specifications; Autonomous is the fastest mover on share as labor scarcity and safety liability reshape mining procurement priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swedish manufacturers export articulated haulers to Australian mining operators through established Nordic-Pacific trade corridors. Chilean copper extraction sites import high-capacity units from Japanese and European OEMs as pit depths extend beyond 300 meters. German engineering houses supply powertrain components to North American assembly plants facing EPA Tier 4 Final compliance deadlines.
United States
Appalachian underground coal operators face ventilation-limited engine sizing constraints under EPA Clean Heavy-Duty Vehicles Program mandates. The EPA enforces tightened NOx and particulate thresholds that add 400-600 kilograms to dual-stage aftertreatment systems. Mine sites in West Virginia and Kentucky retrofit legacy fleets with telematics-enabled predictive maintenance platforms to offset downtime risks from heavier emissions hardware.
Australia
Western Australian iron ore operators specify 24/7 utilization rates and autonomous-ready architectures for deep-pit extraction. The country's national mining regulator enforces diesel particulate exposure limits that accelerate electric hauler trials in the Pilbara region. Perth-based fleet managers now procure uptime guarantees rather than traditional parts-and-labor coverage, concentrating risk with OEM service divisions.
Germany
Urban earthmoving contractors in metropolitan construction zones demand compact electric variants for confined site access under Stage V emissions enforcement. The EU Green Deal's Sustainable Transport Infrastructure Facility offers preferential financing for zero-emission equipment procurement. Bavarian and North Rhine-Westphalian quarry operators pilot solid-state battery prototypes to bypass cold-weather performance degradation affecting liquid-electrolyte alternatives.
Chile
Copper miners in the Atacama Desert deploy high-capacity units as open-pit operations deepen beyond 300 meters, extending haul cycles and demanding larger payload-per-trip economics. The national mining regulator enforces stricter diesel particulate limits in sub-surface operations, forcing electric trials at Collahuasi and El Teniente. Antofagasta-based extraction contractors retrofit articulated fleets with LiDAR and machine-vision stacks for unmanned operation in hazardous pit conditions.
Sweden
Arctic extraction contractors pilot next-generation hauler prototypes with high-energy-density solid-state battery chemistries where cold-weather performance degradation cripples conventional alternatives. The EU Green Deal mandates accelerate fleet decarbonization timelines across Scandinavian mining corridors. Kiruna and Malmberget underground iron ore operations anchor Nordic demand for battery thermal management systems capable of sustaining 24-hour high-torque duty cycles.
Articulated Hauler Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and service network reach. The vendor base stratifies between integrated powertrain manufacturers controlling transmission lead times and telematics-focused challengers selling uptime guarantees. Three archetypes dominate: diversified heavy-equipment conglomerates with captive engine production, construction machinery specialists leveraging regional service density, and emerging electrification pure-plays commercializing retrofit battery kits. Competitive moves center on M&A for autonomous software stacks and strategic partnerships for battery cell supply security.
Among diversified heavy-equipment conglomerates, Caterpillar Inc. and Komatsu Ltd. occupy positions anchored by integrated manufacturing scale across Japanese and North American production bases. Volvo Construction Equipment exemplifies the telematics-enabled service archetype, while John Deere represents agricultural-industrial crossovers applying field-proven powertrain architectures to mining applications. These three names anchor the competitive structure without exhausting its diversity.
| Leading Market Players |
|---|
| John Deere |
| Doosan Infracore |
| Volvo Construction Equipment |
| Liebherr |
| Hitachi Construction Machinery |
| Caterpillar Inc. |
| Bell Equipment |
| Hydrema |
| Komatsu Ltd. |
| Others |
Value Chain & Pricing Dynamics
EPA Tier 4 Final and EU Stage V emissions certifications gate both supplier qualification and price differentiation simultaneously, forcing OEMs to maintain parallel diesel and electric development tracks that fragment scale economies across regulated and unregulated markets.
Pricing Analysis
Diesel-electric hybrid pricing gaps against full-battery and legacy diesel architectures stratify procurement tiers across mining and construction segments. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling rather than mechanical performance alone. Cost compression in standard diesel units is intensifying because dual-stage aftertreatment hardware adds 400-600 kilograms without commensurate productivity gains. Urban construction contractors exhibit highest price sensitivity due to project-based lease structures, while Australian iron ore operators prioritize uptime guarantees over unit economics.
Supply Chain Analysis
China and South Korea anchor cathode material processing and battery cell fabrication for electric hauler powertrains. Japanese and German engineering houses supply transmission and thermal management components that feed North American and European assembly plants. The supply chain draws from lithium, nickel, and rare earth concentrate streams concentrated in Australia, Chile, and Indonesia. Single-source vulnerability in Chinese cathode processing creates geographic concentration risk for OEM electrification timelines. Distribution runs through manufacturer-direct sales teams for mining fleets and regional equipment dealers serving construction contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The articulated hauler market sits in early-cycle expansion as underground ventilation mandates and fleet decarbonization commitments accelerate electric platform adoption beyond pilot-phase deployment.
For Market Incumbents: Consolidate service network density in Australian and Chilean mining corridors where autonomous retrofit demand concentrates. Lock in battery cell supply agreements with Korean and Japanese suppliers before cathode material shortages extend lead times. Prioritize backward integration into powertrain thermal management systems to defend margin position against emerging electrification pure-plays.
For New Entrants and Emerging Players: Differentiate on aftermarket battery-electric conversion kits targeting mid-life diesel haulers in owner-operator quarry segments. Target Scandinavian underground mining contractors piloting solid-state battery prototypes where cold-weather performance gaps exclude liquid-electrolyte alternatives. Pursue EU Green Deal machinery subsidy qualification as the primary go-to-market credential.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core construction equipment divisions. Five-to-ten-year viability hinges on electrification technology transfer capabilities rather than legacy diesel manufacturing scale. Watch battery energy density improvements at the pack level as the inflection signal determining whether electric haulers displace diesel in 24-hour mining shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures cathode material streams from Korean suppliers for Tier 4 Final compliance timelines. |
| Autonomous Haulage Integration | Enables unmanned operation in Chilean copper pits through LiDAR and machine-vision retrofit stacks. |
| Aftermarket Electrification Kit Launch | Opens revenue streams in European quarry segments facing Stage V emissions zone restrictions. |
| Thermal Management R&D Partnership | Develops solid-state battery prototypes for Arctic extraction sites in Swedish mining corridors. |
| Predictive Maintenance Platform Expansion | Reduces unplanned downtime for Western Australian iron ore operators through vibration sensor integration. |
Study Parameters
The analysis maps diesel, hybrid, and electric powertrain sub-sectors, each validated through fleet managers at Australian iron ore operators, procurement directors at Chilean copper miners, aftermarket service heads at European quarry contractors, and thermal engineering leads at battery suppliers. Primary interviews with these stakeholders combined secondary validation through SEC 10-K filings of listed equipment manufacturers, EPA certification databases, EU Stage V compliance registries, and mining fleet procurement tender documents. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include payload capacity tier, fuel type architecture, end-use application, and regional regulatory cluster. CAGRs derived from regression analysis of historical fleet replacement cycles and forward-looking electrification adoption curves. Industry-specific forecast inputs incorporated battery energy density improvement trajectories and underground ventilation mandate enforcement schedules.
Material uncertainties — battery cell supply disruptions, mining commodity price volatility, and charging infrastructure deployment delays — sit outside the modeled envelope. Forecasts reflect assumptions about sustained regulatory enforcement and OEM electrification investment continuity. Recalibration cycles align with material shifts in battery chemistry commercialization and autonomous haulage technology certification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Digger Derrick Truck Market
Heavy-Duty Trucks
Truck Diagnostic Market
Heavy-Duty Trucks
Global Vocational Truck Market
Heavy-Duty Trucks
Dump Trucks and Mining Trucks Market
Heavy-Duty Trucks
Airport Catering Truck Market
Heavy-Duty Trucks
Global Snow Sweeper Truck Market
Heavy-Duty Trucks
Logging Trucks Market
Heavy-Duty Trucks
Europe Medium & Heavy-Duty Truck Rental Market
Heavy-Duty Trucks
Automotive High Performance Trucks Market
Heavy-Duty Trucks
Dump Truck & Body Market
Heavy-Duty Trucks
Stacker Truck Market
Heavy-Duty Trucks
Poly Trucks Market
Heavy-Duty Trucks
Asia Pacific Garbage Truck Bodies Market
Heavy-Duty Trucks
Dump Trucks Market
Heavy-Duty Trucks
Platooning Trucks Market
Heavy-Duty Trucks
Heavy-Duty Vehicle Engine Brake Market