
 Electric Golf Cart Market | 2026-2036
Electric Golf Cart Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Golf Cart Market Analysis
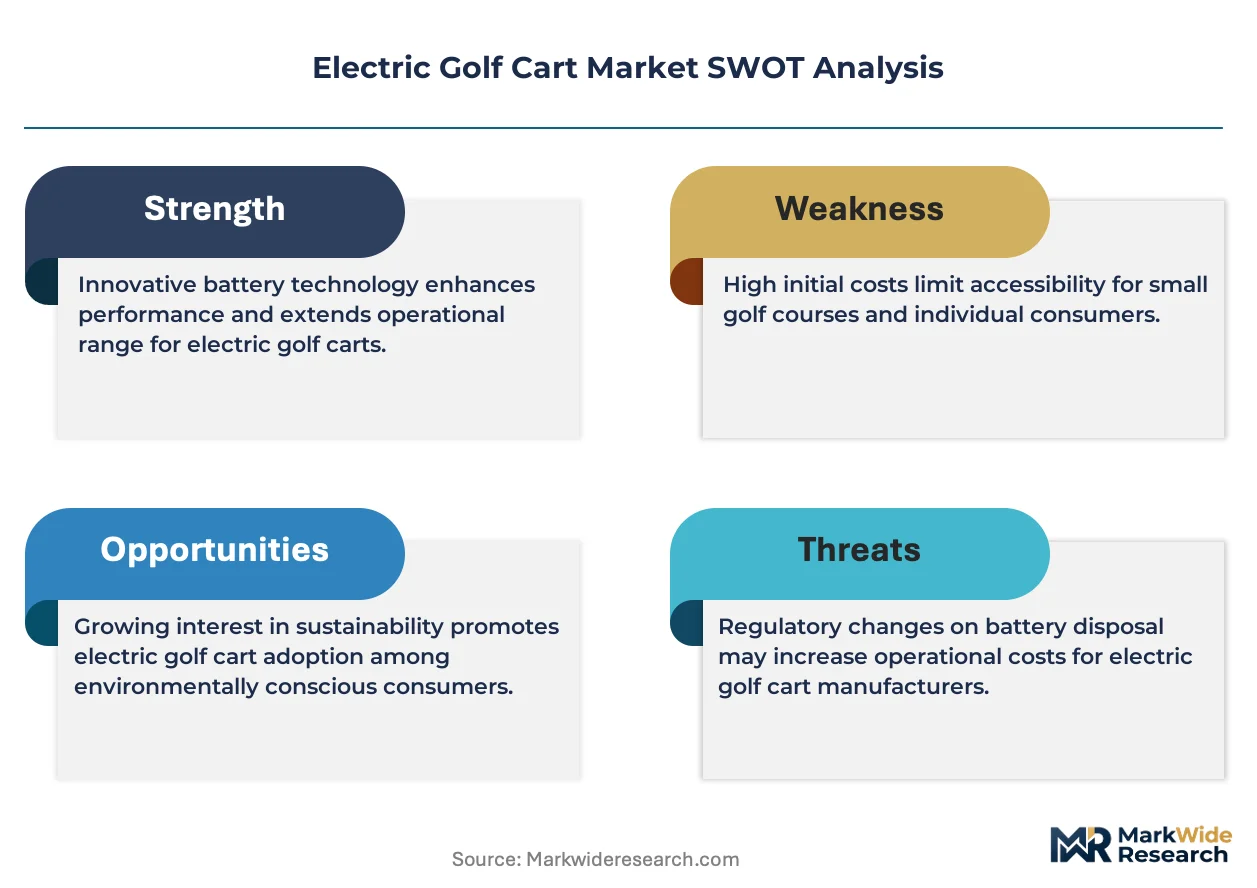
Luxury specification tiers is bifurcating the competitive landscape as buyers demand heated seating, touchscreen dashboards, and extended-range lithium-ion configurations. Club Car leverages its domestic manufacturing footprint to sustain rapid fulfillment for resort and residential community orders. Yamaha Golf-Car Company anchors its position through deep R&D investment in quiet-drive motor technology. E-Z-GO differentiates via proprietary battery management systems that extend operational lifespan across high-cycle fleet deployments.
An electric golf cart is a battery-powered low-speed vehicle typically operating at speeds below 25 mph, constructed on aluminum or steel chassis platforms with DC or AC electric drive systems, and designed primarily for short-distance passenger transport and light utility work in controlled-access environments. Standard golf carts occupy the volume-driven fleet replacement segment, while lithium-ion battery configurations capture accelerating preference due to reduced charging downtime and lower total cost of ownership across commercial operators. Utility golf carts command premium positioning in maintenance and security applications where cargo capacity and all-terrain capability justify higher acquisition spend.
The EPA regulates low-speed vehicle emissions classifications, while NHTSA governs Federal Motor Vehicle Safety Standards for street-legal configurations, and OSHA inspects workplace deployment in commercial and industrial settings. These frameworks collectively push manufacturers toward cleaner drivetrains and documented safety compliance for expanded on-road permissions. Stakeholders must monitor evolving state-level low-speed vehicle statutes and utility rebate programs that could reshape geographic demand patterns and channel economics.
Market Dynamics
The transition from lead-acid to lithium-ion battery chemistry is compressing replacement cycles and reordering supplier economics across fleet procurement channels. Resort operators and residential community managers now prioritize total cost of ownership metrics over upfront acquisition price, forcing manufacturers to restructure pricing and service bundling.
Growth Catalysts
- IRA Clean Vehicle Credits:Federal tax incentives for commercial low-speed vehicle electrification reduce net acquisition costs for US fleet operators, accelerating retirement of internal combustion units in Sun Belt retirement communities.
- Lithium-ion energy density gains:Improved battery chemistry extends daily operational range to 50+ miles, eliminating range anxiety for security patrol and maintenance applications in master-planned developments.
- Master-planned residential developments:Gated community designers in Florida and Arizona are mandating electric vehicle infrastructure, embedding golf cart dependency into site planning and homeowner association bylaws.
Market Restraints
- Lithium carbonate price volatility:Raw material cost swings for cathode production compress battery pack margins and complicate long-term fleet leasing rate structures.
- Domestic battery cell concentration:US pack assemblers remain dependent on imported cylindrical cells, exposing fulfillment timelines to trade policy friction and ocean freight congestion.
- Lead-acid residual infrastructure:Existing charging stations and maintenance training across thousands of golf courses create switching friction that slows lithium-ion penetration in budget-constrained municipal facilities.
Strategic Opportunities
- India gated community expansion:Bangalore and Hyderabad master-planned developments are importing electric low-speed vehicle standards, creating first-mover advantage for manufacturers establishing local assembly partnerships.
- Solar-integrated charging:Photovoltaic canopy installations at resort cart barns enable off-grid charging, reducing peak demand charges and supporting sustainability certification goals.
- Street-legal LSV classification:NHTSA Federal Motor Vehicle Safety Standard 500 compliance opens adjacent neighborhood electric vehicle demand beyond golf course boundaries.
Industry Challenges
- High-voltage technician certification:Fleet maintenance departments lack trained personnel for lithium-ion pack diagnostics and thermal runaway containment, forcing reliance on manufacturer field service networks.
- Multi-year fleet financing alignment:Battery warranty periods and residual value guarantees must match municipal procurement bond cycles, complicating contract structuring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Golf Cart Market |
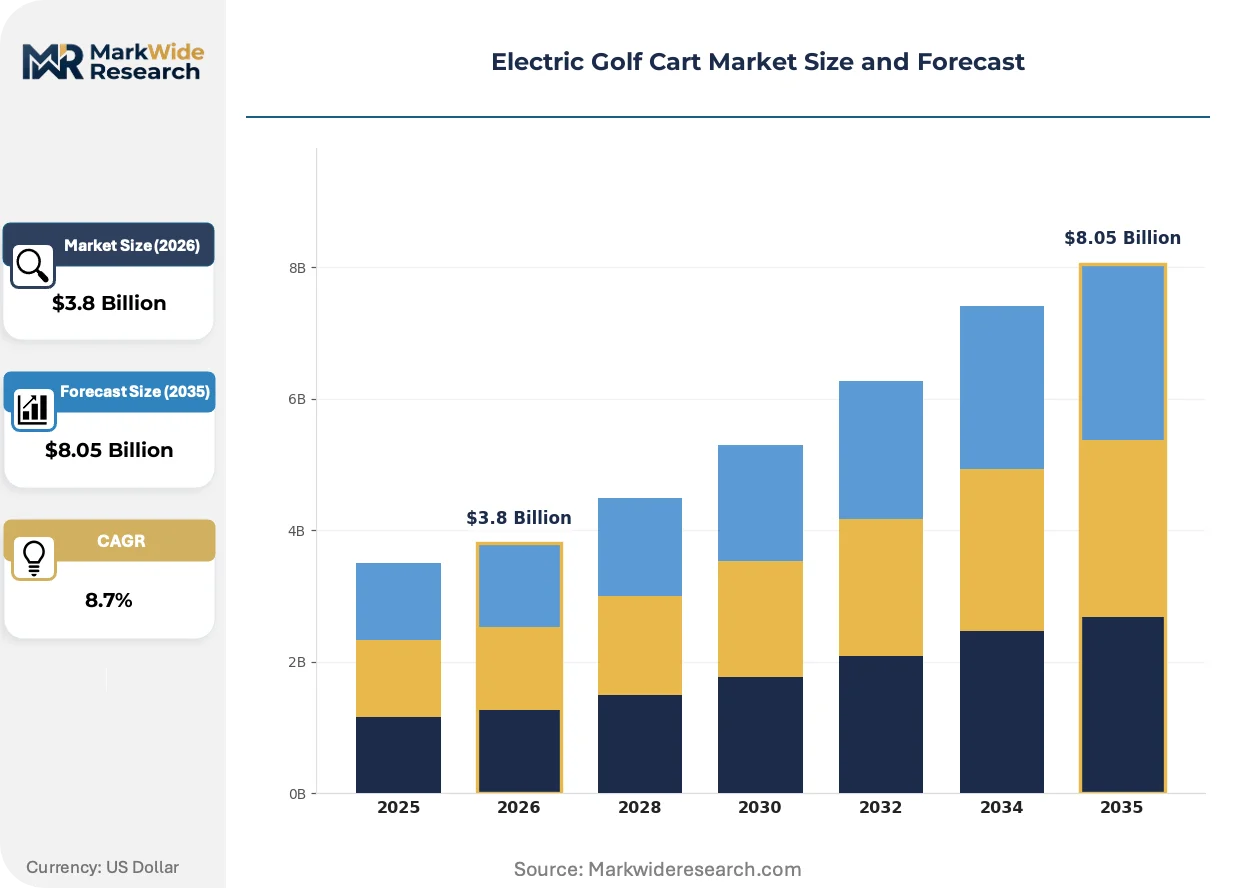
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Golf Carts, Luxury Golf Carts, Utility Golf Carts, 2-Passenger Golf Carts Power Source: Lead-Acid Batteries, Lithium-Ion Batteries, Solar Power, Hybrid Systems End User: Golf Courses, Resorts, Residential Communities, Parks Application: Leisure, Maintenance, Transportation, Security |
| Companies Covered | Club Car, E-Z-GO (Textron Inc.), Yamaha Golf-Car Company, ICON EV, Garia, Evolution EV, Star EV, Polaris GEM, Suzhou Eagle Electric Vehicle Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Golf Cart Market Emerging Trajectories
Connected vehicle architecture and predictive maintenance systems are transforming golf carts from passive transport equipment into data-generating fleet assets. This shift enables outcome-based service relationships and real-time utilization optimization.
Modular battery pack architecture is decomposing the traditional monolithic powertrain design. Resort operators in Arizona are adopting swappable cartridge systems that eliminate downtime during peak season. This topology is compressing the competitive advantage of integrated manufacturers who previously controlled proprietary form factors.
EPA Tier 4 emission standards for small spark-ignition engines are tightening compliance costs for remaining gas-powered fleet operators. The regulatory burden falls heaviest on municipal golf courses with constrained capital budgets, pushing accelerated electrification timelines. California Air Resources Board zero-emission equipment mandates are extending this pressure to landscaping and utility vehicle categories.
Subscription-based fleet management is displacing traditional capital purchase models among multi-property resort operators. Third-party providers now bundle vehicles, charging infrastructure, and predictive maintenance into per-vehicle-month contracts. This transformation is most advanced in Florida retirement community clusters where property management companies consolidate procurement across dozens of affiliated facilities.
Electric Golf Cart Market Segmentation
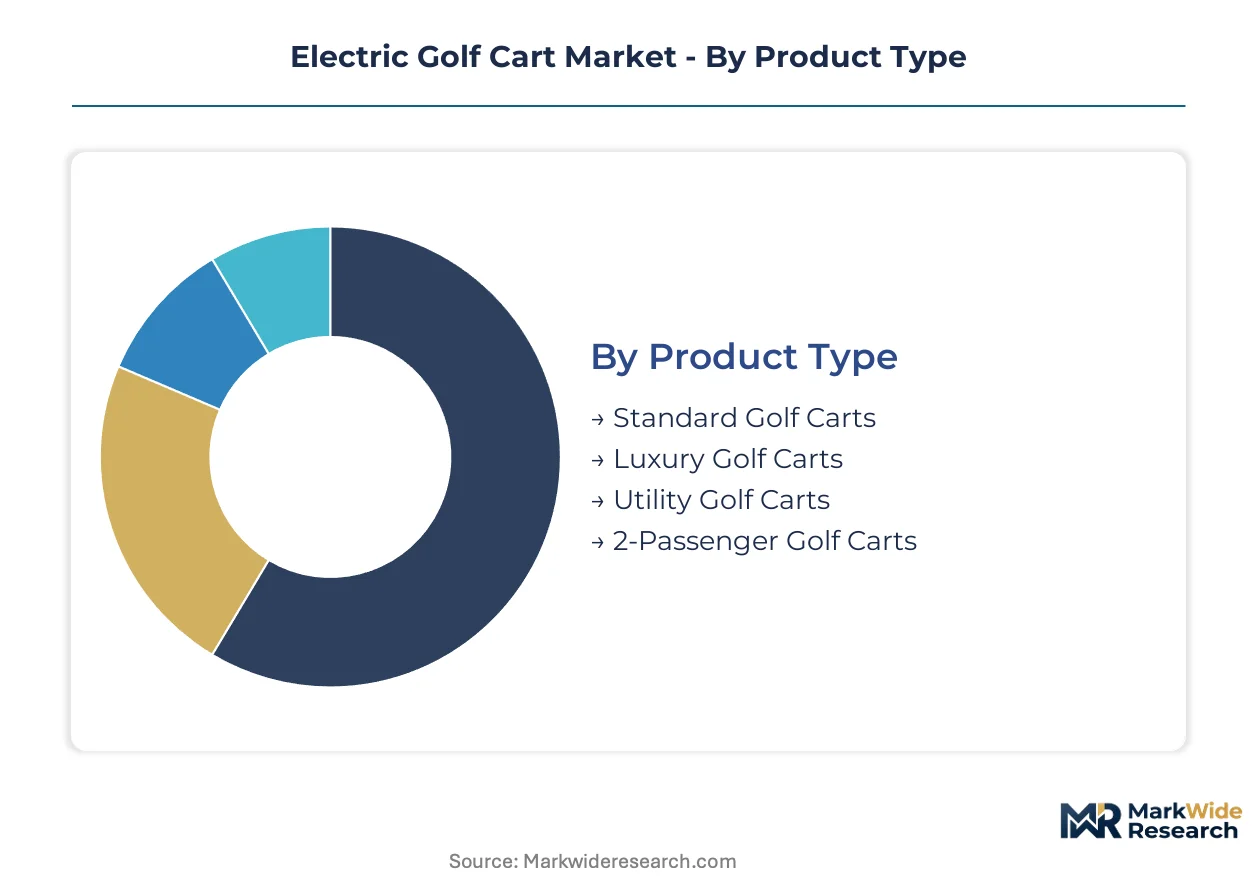
Segmentation reveals how lithium-ion substitution pressure varies dramatically across product tiers and powertrain configurations. Fleet procurement patterns diverge sharply between cost-sensitive municipal operators and premium-focused resort developers, reshaping manufacturer pricing architectures.
Product Type:
Standard golf carts face the most acute substitution threat as lithium-ion packs drop below lead-acid total cost of ownership thresholds, forcing rapid fleet conversion decisions.
- Standard Golf Carts:Aluminum or steel chassis platforms with DC drive systems dominate municipal course procurement. Demand concentrates in Florida retirement community clusters where HOA fleet replacement cycles compress to 5-7 years under IRA credit acceleration.
- Luxury Golf Carts:Heated seating, touchscreen dashboards, and extended-range lithium-ion configurations command 40-60% price premiums. Arizona master-planned developments anchor demand as developers embed amenity differentiation into property marketing.
- Utility Golf Carts:Cargo-rated frames with all-terrain capability serve maintenance and security patrol applications. Industrial parks in Texas and Georgia drive procurement for facility management fleets.
- 2-Passenger Golf Carts:Compact wheelbase designs optimize storage density at urban micro-courses. Japanese market preferences for space efficiency sustain niche import demand.
Standard configurations anchor the volume base while luxury tiers gain share at the steepest rate.
Power Source:
Cost tier stratification separates incumbent lead-acid infrastructure from lithium-ion upgrade economics, with solar and hybrid occupying experimental positioning.
- Lead-Acid Batteries:Flooded-cell technology retains residual share in budget-constrained municipal facilities with existing charging infrastructure. EPA emission compliance costs erode residual competitiveness against electrified alternatives.
- Lithium-Ion Batteries:NMC and LFP chemistries deliver 50+ mile range with 4-hour fast-charge capability. Resort operators in Arizona prioritize these configurations for peak-season utilization maximization.
- Solar Power:Photovoltaic-integrated roof panels extend range 15-25% in high-irradiance climates. Dubai and Saudi Arabia testbed deployments validate thermal management requirements.
- Hybrid Systems:Range-extender genset configurations address charging infrastructure gaps in remote course locations. Australian outback courses sustain limited procurement volume.
Lead-acid chemistry retains installed-base dominance while lithium-ion configurations expand most quickly in new fleet procurement.
End User:
Customer type determines financing structure and service bundling requirements, from municipal bond cycles to subscription-based resort fleet management.
- Golf Courses:Municipal and private facilities drive replacement demand with 8-12 year asset lifecycles. California CARB zero-emission mandates accelerate combustion fleet retirement timelines.
- Resorts:Multi-property operators consolidate procurement through third-party fleet management providers. Florida retirement community clusters advance subscription-based per-vehicle-month contracting.
- Residential Communities:Gated development HOAs mandate electric vehicle infrastructure in site planning. Texas Hill Country and Arizona Sun Belt markets embed cart dependency into homeowner association bylaws.
- Parks:Municipal recreation departments prioritize acquisition cost minimization over operational efficiency. Federal land management agencies pilot solar-integrated configurations for remote access points.
Golf courses sustain the largest installed base while residential communities demonstrate the steepest expansion trajectory.
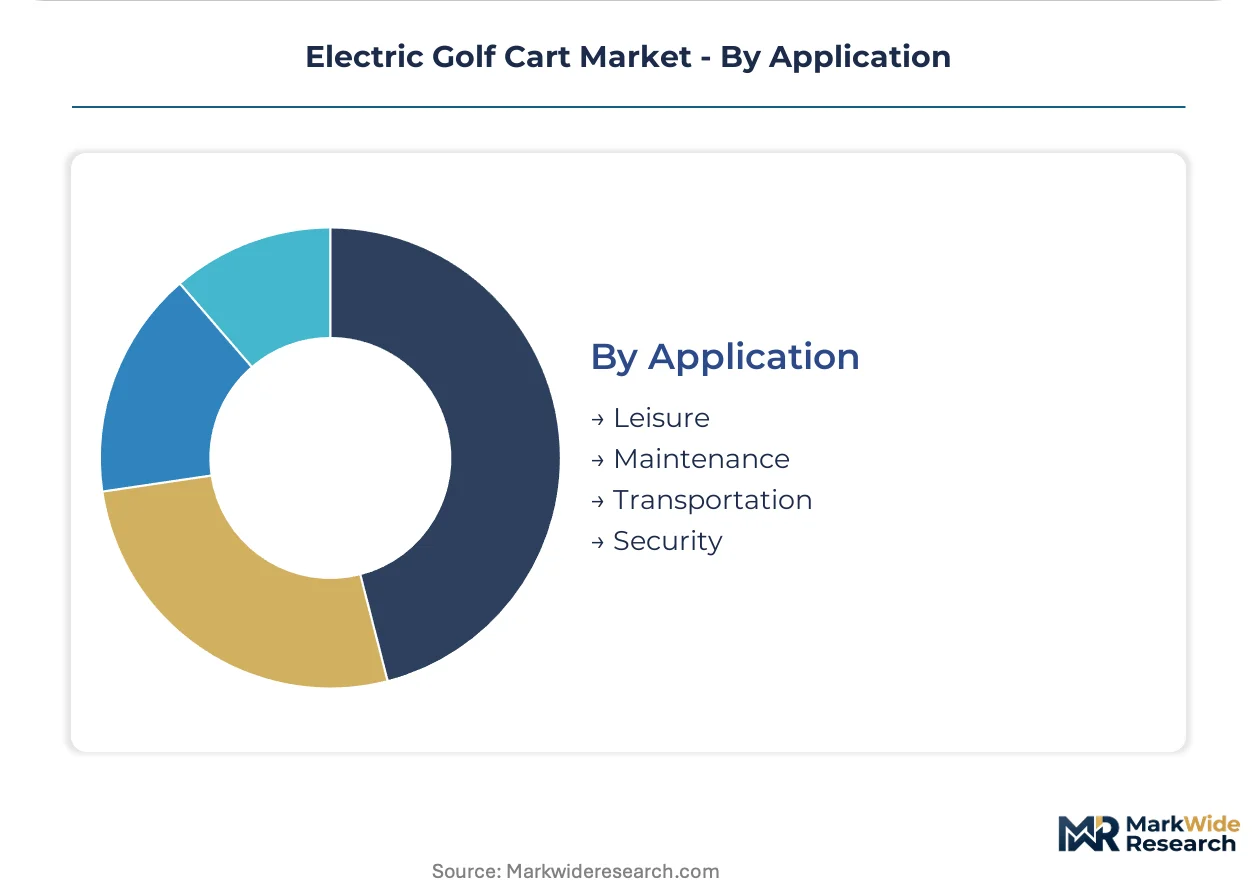
Application:
Functional use case dictates vehicle specification requirements from passenger comfort to cargo capacity and all-terrain capability.
- Leisure:Passenger comfort prioritization drives heated seating and entertainment system integration. Resort amenity differentiation in Scottsdale and Palm Springs sustains premium specification demand.
- Maintenance:Cargo bed configurations with 500-800 lb capacity serve landscaping and facilities operations. EPA Tier 4 compliance costs push municipal operators toward electrified utility platforms.
- Transportation:Street-legal LSV classification under NHTSA FMVSS 500 enables neighborhood electric vehicle deployment. California and Florida lead regulatory permissions for expanded on-road operation.
- Security:Extended-range lithium-ion configurations support 24-hour patrol cycles. Master-planned developments in Texas integrate connected vehicle architecture for real-time incident response.
Leisure applications retain volume concentration while transportation use cases climb the fastest as street-legal permissions expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Assembly capacity clusters in the United States, China, and Mexico, with lithium-ion cell sourcing extending to South Korean and Japanese suppliers. Demand patterns diverge sharply between Sun Belt retirement communities and European leisure tourism circuits.
United States
Florida master-planned developments and Arizona resort clusters drive fleet procurement volume. The Inflation Reduction Act clean vehicle credits compress payback periods for lithium-ion configurations. Dallas-Fort Worth metroplex logistics hubs coordinate distribution to Texas Hill Country gated communities.
China
Domestic golf tourism expansion and export manufacturing sustain dual demand channels. MIIT low-speed vehicle standards govern street-legal classification for neighborhood electric vehicle derivatives. Suzhou industrial corridor hosts pack assembly operations serving Asia-Pacific leisure fleet operators.
Germany
Precision engineering heritage shapes premium specification expectations in leisure tourism applications. EU Green Deal zero-emission equipment mandates accelerate retirement of remaining combustion utility fleets. Bavarian alpine resort operators consolidate procurement through third-party fleet management providers.
Japan
Aging demographic concentration in resort municipalities sustains replacement demand for accessibility-optimized configurations. METI battery safety standards govern thermal management system certification requirements. Kansai region golf course operators pilot connected vehicle architecture for predictive maintenance deployment.
United Arab Emirates
Desert resort developments and master-planned residential communities import electric low-speed vehicle standards from North American markets. Dubai tourism authority sustainability certifications mandate fleet electrification timelines. Abu Dhabi golf precincts deploy solar-integrated charging infrastructure to reduce grid dependency.
Electric Golf Cart Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated manufacturers controlling proprietary battery form factors while Asian fabricators compete on scale economics. The vendor base separates into three strategic tiers: domestic full-line producers with rapid fulfillment networks, European precision specialists serving premium leisure applications, and Chinese scale manufacturers exporting commodity configurations. Consolidation pressure operates through backward integration into battery cell supply and forward integration into subscription-based fleet management services.
Among North American full-line producers, Club Car and E-Z-GO represent the integrated manufacturing archetype with domestic assembly footprints. Yamaha Golf-Car Company anchors the precision engineering tier with Japanese industrial heritage. Suzhou Eagle Electric Vehicle Manufacturing exemplifies the scale-export archetype serving price-sensitive fleet procurement channels across emerging markets.
| Leading Market Players |
|---|
| Club Car |
| E-Z-GO (Textron Inc.) |
| Yamaha Golf-Car Company |
| ICON EV |
| Garia |
| Evolution EV |
| Star EV |
| Polaris GEM |
| Suzhou Eagle Electric Vehicle Manufacturing |
| Others |
Supply Flow & Price Mechanics
EPA emission standards and NHTSA Federal Motor Vehicle Safety Standard 500 certification simultaneously gate supply qualification and stratify price tiers across the electric golf cart market, forcing manufacturers to absorb compliance costs into premium configurations while budget-tier competitors retreat from street-legal segments.
Pricing Analysis
NHTSA FMVSS 500 compliance dictates the pricing tier structure, separating street-legal neighborhood electric vehicles from course-confined alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects lithium-ion battery chemistry grade and connected vehicle architecture inclusion. Price differentiation hinges on certification level and after-sales service bundling. Pricing pressure stems from lithium carbonate cost volatility compressing battery pack margins. Municipal golf courses exhibit highest price sensitivity, while Arizona master-planned developments prioritize total cost of ownership over acquisition cost.
Supply Chain Analysis
Ocean freight congestion on Asia-North America trade lanes disrupts cylindrical lithium-ion cell deliveries to US pack assemblers. Manufacturing concentrates in China, South Korea, and the United States. Raw material dependencies center on lithium carbonate, nickel-manganese-cobalt cathode precursors, and aluminum chassis extrusions. Single-source vulnerability in South Korean cell supply exposes fulfillment timelines to trade policy friction. Distribution runs through Dallas-Fort Worth logistics hubs serving Texas Hill Country gated communities and Florida retirement clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric golf cart market represents a high-growth disruption propelled by IRA clean vehicle credits compressing electrification payback periods below five years for commercial fleet operators.
For Market Incumbents: Consolidate backward integration into lithium-ion cell supply through partnerships with South Korean cathode producers, insulating margins from raw material volatility. Lock in multi-year fleet service contracts with Florida property management companies to defend against subscription-based third-party entrants. Prioritize NHTSA FMVSS 500 certification investment to capture street-legal neighborhood electric vehicle expansion. For New Entrants and Emerging Players: Anchor in India gated community expansion, where Bangalore and Hyderabad master-planned developments import North American electric low-speed vehicle standards without established supplier relationships. Target solar-integrated charging infrastructure as the most penetrable white space, bundling photovoltaic canopy installations with vehicle procurement. Pursue local assembly partnerships to circumvent import duties and accelerate first-mover positioning. For Investors and Strategic Acquirers: California Air Resources Board zero-emission equipment mandates reshape the acquisition landscape, extending electrification timelines to landscaping and utility vehicle categories previously exempt from passenger-car standards. Long-term viability favors manufacturers with captive battery management system IP and subscription-based fleet management capabilities. Monitor lithium carbonate futures curves as the critical inflection signal for margin compression versus expansion cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term cathode offtake contracts with LG Energy Solution or SK On lock in lithium-ion cell availability for Arizona resort fleet deployments. |
| Platform Standardization | Modular battery pack architecture enables swappable cartridge systems that eliminate peak-season downtime for multi-property operators. |
| Charging Infrastructure Partnership | Photovoltaic canopy installations at Dubai resort cart barns reduce grid dependency and support sustainability certification goals. |
| Geographic Manufacturing Footprint | Dallas-Fort Worth assembly proximity compresses delivery timelines to Texas Hill Country gated communities and Florida retirement clusters. |
| Software-Defined Vehicle Investment | Connected vehicle architecture transforms golf carts into data-generating fleet assets enabling predictive maintenance revenue streams. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with fleet procurement managers at resort operators, HOA board members at master-planned developments, and maintenance directors at municipal golf courses; and secondary validation through EPA emission filings, NHTSA FMVSS certification databases, and IRA credit utilization disclosures. Bottom-up unit economics triangulated against top-down market sizing across the projection horizon.
Across the analysis window, forecasts model product type segmentation, power source chemistry tiers, end-user financing structures, and application functional requirements. CAGRs derive from replacement cycle compression rates and lithium-ion penetration trajectories. Forecast inputs incorporate IRA credit phase-out schedules and state-level low-speed vehicle statute evolution.
Material uncertainties — lithium carbonate price spikes, trade policy friction affecting South Korean cell imports, and municipal bond cycle misalignment with battery warranty periods — sit outside the modeled envelope. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Europe Recreational Vehicle Market
Recreational Vehicles
North America Youth ATV and UTV Market
Recreational Vehicles
Saudi Arabia Yacht Charter Market
Recreational Vehicles
United States Luxury Yacht Market
Recreational Vehicles
US Recreational Boating Market
Recreational Vehicles
Kayak Seats Market
Recreational Vehicles
Water Scooter Market
Recreational Vehicles
North America ATV and UTV Market
Recreational Vehicles
Global Segway Consumption Market
Recreational Vehicles
United States RV Rental Market
Recreational Vehicles
Recreational Vehicle Parks and Campgrounds Market
Recreational Vehicles
Segway Market
Recreational Vehicles
North America Recreational Vehicle Market
Recreational Vehicles
Light Car Trailer Market
Recreational Vehicles
US Low Speed Vehicle Market
Recreational Vehicles
Golf Cart Market