
 Automotive OEM Telematics Market | 2026-2036
Automotive OEM Telematics Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive OEM Telematics Market Analysis
Automotive software engineering talent is rotating from infotainment toward embedded systems and V2X protocol development, tightening labor pools for legacy telematics architectures. Robert Bosch GmbH leverages its tier-one supplier relationships to sustain integrated control unit production across European and Asian vehicle programs. Qualcomm Technologies anchors next-generation chipset design for LTE and V2X communication modules, while Harman International differentiates through premium embedded audio-telematics convergence for luxury OEM platforms.
Automotive OEM telematics encompasses the hardware, software, and communication infrastructure that enables real-time data exchange between vehicles, fleet operators, and cloud platforms, typically operating through cellular modems with sub-100-millisecond latency thresholds and AES-256 encryption protocols to support safety-critical and commercial applications. Embedded Systems dominate current OEM fitment programs due to factory-integrated antenna placement and deeper CAN bus access, while V2X Communication represents the fastest-expanding technology segment as infrastructure-to-vehicle protocols mature for intersection safety and traffic harmonization. Fleet Management applications command concentrated margin pools through recurring SaaS revenue structures, whereas Remote Diagnostics is gaining traction among insurance companies seeking usage-based policy frameworks.
NHTSA mandates in the United States, EASA coordination with EU AI Act provisions, and Japan's METI connected vehicle standards collectively shape crash notification timelines, data localization requirements, and cross-border interoperability certifications. OEMs and tier-one suppliers must navigate divergent cybersecurity frameworks across these jurisdictions to maintain market access. Stakeholders should monitor spectrum allocation decisions for C-V2X versus DSRC protocols, as regulatory commitment to either standard will determine hardware refresh cycles and supplier consolidation patterns.
Market Dynamics
The EU AI Act's algorithmic transparency mandates are forcing OEMs to rearchitect their connected vehicle data pipelines, compressing development timelines for safety-critical telematics functions while expanding compliance budgets across European vehicle programs.
Growth Catalysts
- Fleet electrification mandates:Commercial operators in Germany face binding zero-emission vehicle quotas that require embedded telematics for battery state-of-health monitoring and route optimization.
- C-V2X spectrum allocation:The FCC's 5.9 GHz band reconfiguration enables direct vehicle-to-infrastructure communication protocols for intersection collision avoidance in US urban corridors.
- Usage-based insurance frameworks:Japan's METI guidelines standardize driving behavior data formats, allowing insurers to price policies against real-time telematics feeds rather than demographic proxies.
Market Restraints
- Semiconductor supply concentration:Advanced modem chip fabrication clusters in Taiwan create single-point vulnerability for LTE and V2X module procurement across Tier-1 suppliers.
- GDPR data localization friction:Cross-border vehicle data flows between EU member states and third countries face transfer mechanism uncertainties that delay cloud platform deployments.
- DSRC stranded asset risk:Early C-V2X adopters confront hardware obsolescence as infrastructure authorities abandon the competing DSRC protocol standard.
Strategic Opportunities
- India's PLI scheme for automotive electronics:Domestic manufacturing incentives attract telematics control unit assembly, reducing import dependency for mass-market OEMs serving South Asian fleets.
- Predictive maintenance convergence:Integration of edge AI inference with CAN bus diagnostics enables failure prediction 48-72 hours before component degradation triggers downtime.
- Subscription revenue models:Over-the-air feature activation transforms one-time hardware sales into recurring software revenue streams for remote diagnostics and infotainment upgrades.
Industry Challenges
- Embedded systems talent scarcity:Automotive software engineers with V2X protocol expertise command premium compensation, stretching R&D budgets for mid-tier suppliers.
- Multi-jurisdiction certification complexity:OEMs must thread NHTSA crash notification requirements, EASA cybersecurity frameworks, and METI data standards simultaneously for global vehicle platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive OEM Telematics Market |
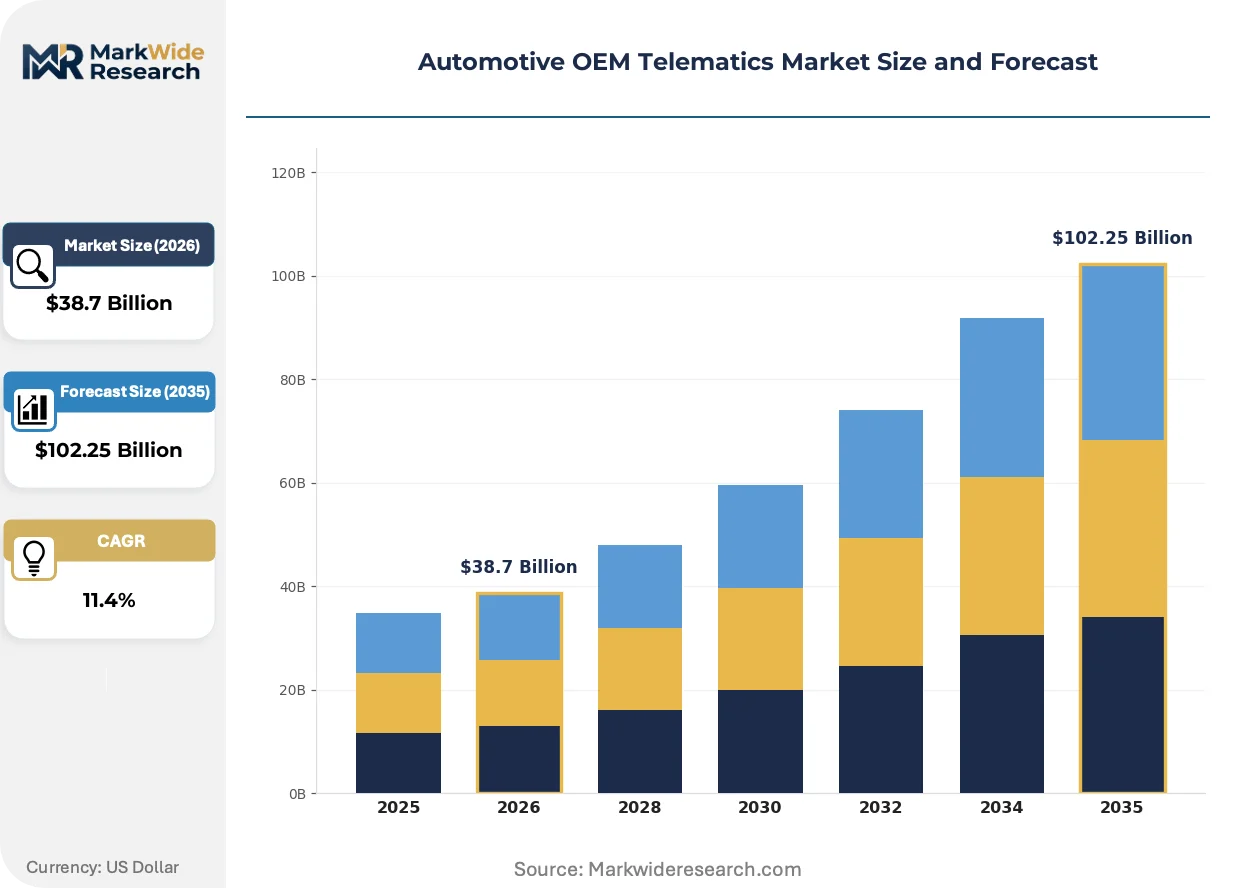
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded Systems, Aftermarket Devices, Hybrid Solutions, Telematics Control Units Technology: GPS, LTE, V2X Communication, Cloud Computing Application: Fleet Management, Vehicle Tracking, Emergency Services, Remote Diagnostics End User: OEMs, Fleet Operators, Insurance Companies, Logistics Providers |
| Companies Covered | AT&T, Robert Bosch GmbH, Verizon Connect, Vodafone Group, Continental AG, Harman International, Qualcomm Technologies, Ford Motor Company, TomTom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive OEM Telematics Market Emerging Trajectories
Edge computing architectures are migrating inference workloads from centralized clouds toward vehicle-mounted control units, reducing latency for safety-critical decisions while complicating software update orchestration across heterogeneous hardware generations.
Containerized software platforms are fragmenting the traditional monolithic telematics stack, allowing OEMs to deploy isolated applications for fleet management, insurance telematics, and predictive maintenance on shared hardware without cross-functional dependencies. Tier-1 suppliers in Germany and Japan are adopting this architecture fastest, compressing integration timelines for new service launches from 18 months to under 6 months.
REACH chemical compliance is extending from manufacturing materials to end-of-life telematics hardware recovery, mandating rare earth element reclamation from embedded modems and antenna assemblies. European dismantlers must now certify recycling rates for lithium, cobalt, and gallium components, adding reverse logistics costs that reshape supplier warranty terms and modular design priorities for control units destined for EU vehicle fitment.
Fleet procurement departments are consolidating vendor relationships, demanding unified platforms that combine telematics hardware, SaaS analytics, and maintenance scheduling under single-contract frameworks. This behavior concentrates purchasing power among operators with 500+ vehicle fleets in the United States and Germany, squeezing margins for point-solution providers while rewarding vertically integrated platform vendors with multi-year subscription commitments.
Automotive OEM Telematics Market Segmentation
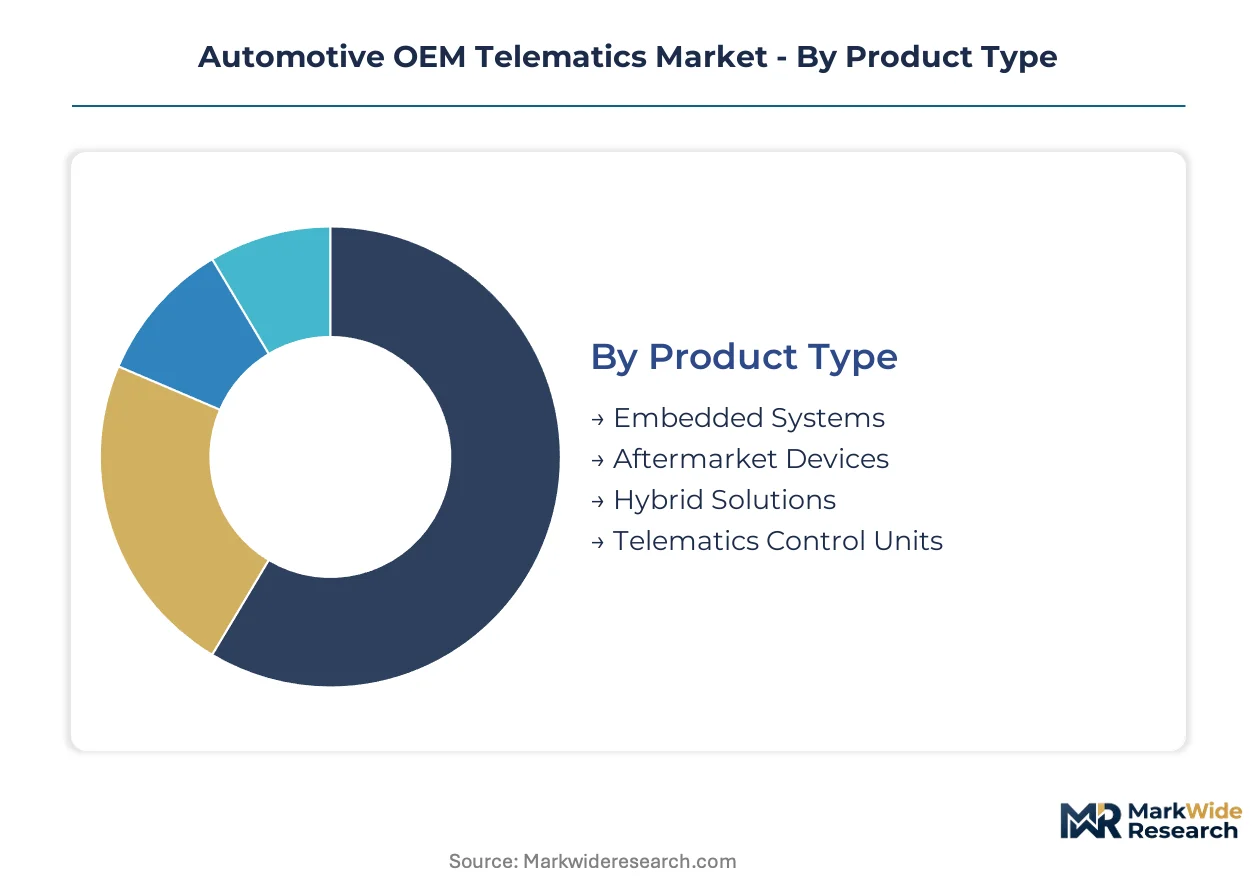
Segmentation in automotive OEM telematics reveals how hardware specifications, connectivity protocols, and customer procurement patterns split margin pools across the value chain. Channel strategy varies sharply between factory-embedded programs and aftermarket retrofit opportunities.
Product Type:
Channel mix splits between factory-floor integration for new vehicle programs and dealer-network retrofit for installed base expansion.
- Embedded Systems:Factory-integrated antenna arrays and CAN bus access enable sub-100-millisecond latency for safety-critical functions. Demand concentrates among German and Japanese OEMs seeking deeper vehicle system integration for autonomous driving readiness.
- Telematics Control Units:Modular hardware platforms combine cellular modems, GPS receivers, and edge processors in single enclosures. Fleet operators in the United States specify these for standardized deployment across mixed-vehicle portfolios, prioritizing supplier interoperability over deep OEM integration.
- Aftermarket Devices:OBD-II port plug-ins serve owner-operators and small fleets requiring rapid deployment without factory authorization.
- Hybrid Solutions:Dual-mode architectures bridge embedded and aftermarket functionality for lease fleet transitions.
Embedded Systems dominate installed base. Telematics Control Units is where expansion concentrates.
Technology:
Cost tiers separate legacy positioning systems from next-generation infrastructure communication protocols.
- V2X Communication:Direct vehicle-to-infrastructure and vehicle-to-vehicle protocols operate in dedicated spectrum bands for intersection collision avoidance. Japan's METI standards and FCC 5.9 GHz reconfigurations are accelerating deployment timelines for urban corridor safety systems.
- Cloud Computing:Centralized data lakes aggregate telematics streams for predictive analytics and over-the-air software orchestration. Insurance companies in Germany and the United States are driving demand for scalable architectures supporting usage-based policy frameworks.
- LTE:Cellular connectivity remains the workhorse for wide-area telemetry transmission.
- GPS:Satellite positioning provides foundational location services across all hardware categories.
LTE anchors current revenue. V2X Communication is climbing the fastest as infrastructure investments mature.
Application:
Volume concentration differs between commercial fleet procurement and consumer-facing safety services.
- Fleet Management:Integrated platforms combine real-time tracking, driver behavior scoring, and maintenance scheduling under recurring SaaS contracts. Logistics providers operating 500-plus vehicle fleets in Germany and the United States are consolidating vendor relationships around unified platform architectures.
- Remote Diagnostics:Edge AI inference on CAN bus data streams enables failure prediction 48-72 hours before component degradation. Insurance companies in Japan are adopting METI-standardized data formats to price policies against actual driving behavior rather than demographic proxies.
- Vehicle Tracking:Location-based services support asset recovery and route optimization for commercial operators.
- Emergency Services:Automatic crash notification systems satisfy NHTSA mandates and EASA coordination requirements.
Fleet Management commands the largest revenue pool. Remote Diagnostics is gaining share fastest as insurance frameworks mature.
End User:
Customer type determines procurement authority and contract structure across the value chain.
- Fleet Operators:Commercial vehicle purchasers with centralized procurement departments negotiate multi-year subscriptions bundling hardware, software, and maintenance. Binding zero-emission vehicle quotas in Germany are accelerating embedded telematics adoption for battery state-of-health monitoring.
- OEMs:Vehicle manufacturers specify telematics architectures during platform development, prioritizing tier-one supplier integration and regulatory compliance across multiple jurisdictions.
- Insurance Companies:Underwriters seek standardized data feeds for usage-based pricing models.
- Logistics Providers:Supply chain operators demand unified visibility across heterogeneous vehicle fleets.
Fleet Operators drive recurring revenue concentration. OEMs control architectural decisions upstream.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA crash notification mandates anchor the United States as the regulatory reference point for connected vehicle architectures, with the FCC's 5.9 GHz spectrum reconfiguration accelerating C-V2X deployment across urban corridors. Fleet electrification quotas in Germany and Japan's METI standardization programs are compressing development timelines for safety-critical telematics functions.
United States
Fleet operators with 500-plus vehicle portfolios are consolidating vendor relationships around unified telematics platforms that bundle hardware, SaaS analytics, and maintenance scheduling. NHTSA mandates dictate automatic crash notification timelines and data format standards for emergency services integration. Detroit-Warren-Dearborn anchors embedded systems engineering, with tier-one suppliers co-locating control unit design teams near OEM platform development centers.
Germany
Commercial operators face binding zero-emission vehicle quotas that require embedded telematics for battery state-of-health monitoring and route optimization across electric truck fleets. EU AI Act algorithmic transparency mandates and GDPR data localization requirements are reshaping cloud platform architectures for connected vehicle programs. Stuttgart and Munich concentrate V2X protocol development, with Robert Bosch GmbH leveraging tier-one supplier relationships across European and Asian vehicle programs.
Japan
Insurance companies are adopting METI-standardized driving behavior data formats to price usage-based policies against real-time telematics feeds rather than demographic proxies. METI connected vehicle standards govern cross-border interoperability certifications and cybersecurity framework alignment with international OEM platforms. Nagoya and Tokyo host edge AI inference development for predictive maintenance convergence with CAN bus diagnostics.
India
Domestic manufacturing incentives under the PLI scheme for automotive electronics are attracting telematics control unit assembly, reducing import dependency for mass-market OEMs serving South Asian commercial fleets. The country's national automotive regulator coordinates with BIS standards for embedded modem certification and electromagnetic compatibility testing. Pune and Chennai cluster control unit manufacturing, with suppliers qualifying for production-linked incentive disbursements through local value-add thresholds.
South Korea
Seoul Capital Area semiconductor fabricators supply advanced modem chipsets for LTE and V2X modules, though Taiwan concentration creates procurement vulnerability for tier-one suppliers. The country's national telecommunications regulator allocates spectrum for C-V2X deployment alongside existing cellular infrastructure. Busan-Ulsan automotive manufacturing corridors integrate embedded telematics into export-oriented vehicle programs for North American and European markets.
Automotive OEM Telematics Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with tier-one automotive suppliers and telecommunications carriers commanding multi-year fleet contracts while point-solution providers face margin compression. The structure rewards backward integration into chipset design and forward integration into SaaS analytics platforms. Two strategic archetypes dominate: vertically integrated platform vendors bundling hardware, software, and connectivity, and specialized component suppliers focused on modem chipsets or edge processors. Competitive moves concentrate on strategic partnerships between tier-one suppliers and cloud infrastructure providers, plus portfolio diversification into predictive maintenance and usage-based insurance data services.
Within the integrated platform tier, Robert Bosch GmbH and Harman International exemplify tier-one supplier archetypes that leverage OEM relationships for factory-floor telematics integration. Among telecommunications-based service providers, AT&T occupies a position representing carrier-led fleet management platforms that bundle cellular connectivity with SaaS analytics. Qualcomm Technologies anchors the semiconductor specialist vector, with its geographic origin in San Diego reflecting the concentration of advanced modem design expertise in United States technology corridors.
| Leading Market Players |
|---|
| AT&T |
| Robert Bosch GmbH |
| Verizon Connect |
| Vodafone Group |
| Continental AG |
| Harman International |
| Qualcomm Technologies |
| Ford Motor Company |
| TomTom |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts between fleet operators and Tier-1 suppliers lock in both modem chipset allocation and predictable per-unit pricing across multi-year vehicle programs, insulating procurement teams from spot-market volatility in Taiwan semiconductor output.
Pricing Analysis
Price spreads between German and Indian telematics control unit assembly run 15-25% after accounting for EU REACH compliance costs and logistics. Three-tier pricing structure across premium, standard, and economy levels separates OEM-integrated embedded systems from modular fleet-specified units and aftermarket OBD-II devices. Cost compression in mid-tier hardware is intensifying because India's PLI scheme attracts competing domestic manufacturers. Small owner-operator fleets exhibit highest price sensitivity, while German commercial operators with electrification mandates prioritize integration depth over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for control unit assemblies sourced from Taiwanese chip fabricators. Advanced modem production concentrates in Taiwan, South Korea, and the United States, with rare earth element dependencies on Chinese gallium and cobalt processing. Single-source vulnerability in 5G baseband design creates procurement risk for Tier-1 suppliers serving global OEM platforms. Distribution runs through authorized dealer networks for factory-embedded fitment and direct enterprise sales for fleet retrofit programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet management SaaS layers expand faster than hardware sales as logistics operators consolidate around unified platform subscriptions bundling analytics, maintenance scheduling, and compliance reporting.
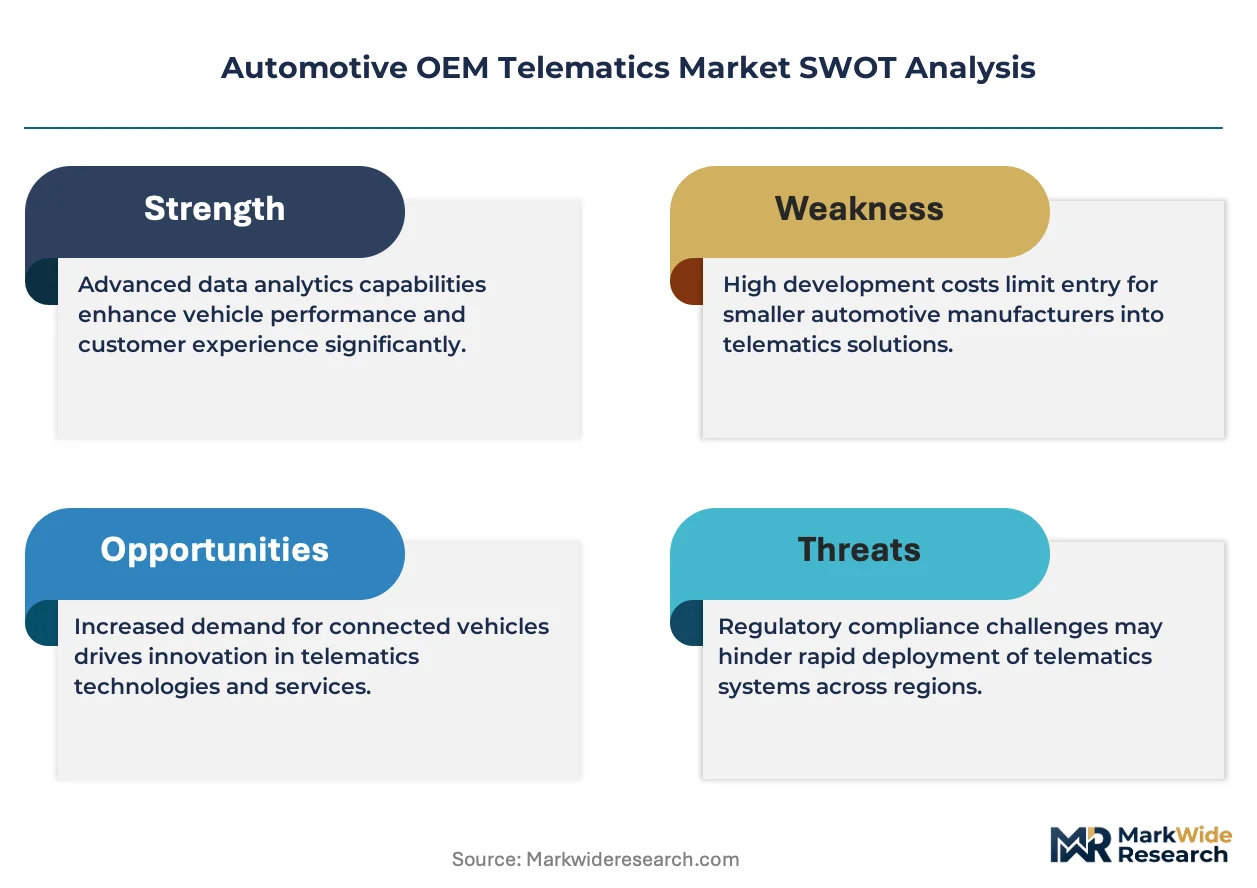
For Market Incumbents: Shield embedded systems margins by deepening captive supply of edge AI processors and securing multi-year C-V2X spectrum licenses ahead of infrastructure deployment waves. Accelerate certification investment for EU AI Act algorithmic transparency to preempt compliance-driven vendor switches by German OEMs. For New Entrants and Emerging Players: Anchor in India's PLI-qualified manufacturing zones to capture cost advantages for mass-market telematics control units serving South Asian commercial fleets. Target insurance telematics data services as the most penetrable segment, leveraging METI-standardized formats to bypass proprietary OEM data silos. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated platform vendors with captive SaaS revenue streams and Tier-1 supplier relationships across multiple OEM programs. Monitor C-V2X versus DSRC protocol commitments by infrastructure authorities as the critical signal for hardware refresh cycle timing and supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Containerized software architectures reduce integration timelines from 18 months to under 6 months for German Tier-1 suppliers. |
| Battery Supply Agreement | Long-term cell procurement secures state-of-health monitoring data streams for electrified fleet telematics platforms. |
| Software-Defined Vehicle Investment | Over-the-air feature activation transforms hardware sales into recurring revenue for remote diagnostics and infotainment upgrades. |
| Geographic Manufacturing Footprint | PLI scheme qualification in Pune and Chennai reduces import dependency for OEMs serving South Asian markets. |
| Charging Infrastructure Partnership | Intersection collision avoidance systems require C-V2X protocol alignment between vehicle modems and roadside units. |
Methodological Framework
Initial hypotheses were tested against primary input from OEM platform engineers, Tier-1 supplier procurement directors, fleet operations managers, and insurance telematics product leads and refined through secondary validation against vehicle production databases, IHS Markit registration data, FCC spectrum allocation filings, and EU regulatory implementation guidance. Bottom-up unit economics triangulated against top-down market sizing across embedded systems, telematics control units, and aftermarket device categories.
Variance decomposition separated volume, price, and mix effects across the projection horizon. Segmentation dimensions modeled include product type, connectivity protocol, application, end user, and regional production cluster. CAGRs were derived from fitted growth curves calibrated to disclosed OEM telematics penetration targets and fleet operator procurement cycle data. Forecast inputs incorporated 5G infrastructure deployment schedules, battery electric vehicle adoption curves, and insurance regulatory framework maturation.
Material uncertainties — semiconductor supply disruptions, spectrum allocation reversals, and cross-border data transfer mechanism invalidations — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as C-V2X infrastructure commitment levels and EU AI Act enforcement precedents evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Commercial Vehicle Telematics Market
Telematics and Infotainment
Automotive Data Monetization Market
Telematics and Infotainment
Global Automotive Remote Diagnostics Market
Telematics and Infotainment
APAC Telematics Market
Telematics and Infotainment
Vehicle Trip Computers Market
Telematics and Infotainment
Connected Car Market
Telematics and Infotainment
Asia-Pacific Automotive Telematics Market
Telematics and Infotainment
Internet of Things Vehicle-To-Vehicle Communication Market
Telematics and Infotainment
Consumer Telematics Market
Telematics and Infotainment
5G V2X Communications Market
Telematics and Infotainment
In-Cabin Lighting-Climate-Audio Synchronized Experience Systems Market
Telematics and Infotainment
Global Car GPS Navigation System Market
Telematics and Infotainment
V2X Communication Module Market
Telematics and Infotainment
Motorcycle Infotainment System Market
Telematics and Infotainment
Asia Pacific Automotive Navigation System Market
Telematics and Infotainment
Advanced Traveller Information System Market