
 Europe Medium and Heavy-Duty Commercial Vehicles Market | 2026-2036
Europe Medium and Heavy-Duty Commercial Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Medium and Heavy-Duty Commercial Vehicles Market Foresight
A chronic shortage of certified electric powertrain technicians is unwinding production schedules at multiple assembly plants. Daimler Truck leverages its in-house battery engineering capacity to shorten development cycles for zero-emission platforms. Volvo Group anchors Nordic market share through dense service networks and cold-climate validation programs. Scania competes on modular architecture that permits rapid powertrain swaps between diesel, hybrid, and fully electric configurations.
Europe medium and heavy-duty commercial vehicles span rigid trucks, tractors, buses, and vans exceeding 3.5 tonnes gross vehicle weight, typically built on ladder-frame chassis with multi-axle configurations and compression-ignition or emerging battery-electric powertrains, designed for sustained high-load operation on continental road networks. Diesel retains dominant installed base across freight corridors, yet electric and CNG fuel types are capturing incremental share in urban logistics and public transport applications where depot charging or biomethane infrastructure exists. The tractor segment concentrates margin pools in long-haul efficiency optimization, while bus procurement tilts toward municipal electrification mandates.
The EU Green Deal, F-Gas Regulation, and Euro VII emission standards collectively tighten CO2 and pollutant thresholds, compelling manufacturers to reengineer thermal management and exhaust aftertreatment systems. EMA and national type-approval bodies enforce divergent compliance timelines that fragment product planning across member states. Fleet operators and OEMs must monitor subsidy phase-out schedules and charging infrastructure build-out rates to time capital deployment across powertrain transitions.
Market Dynamics
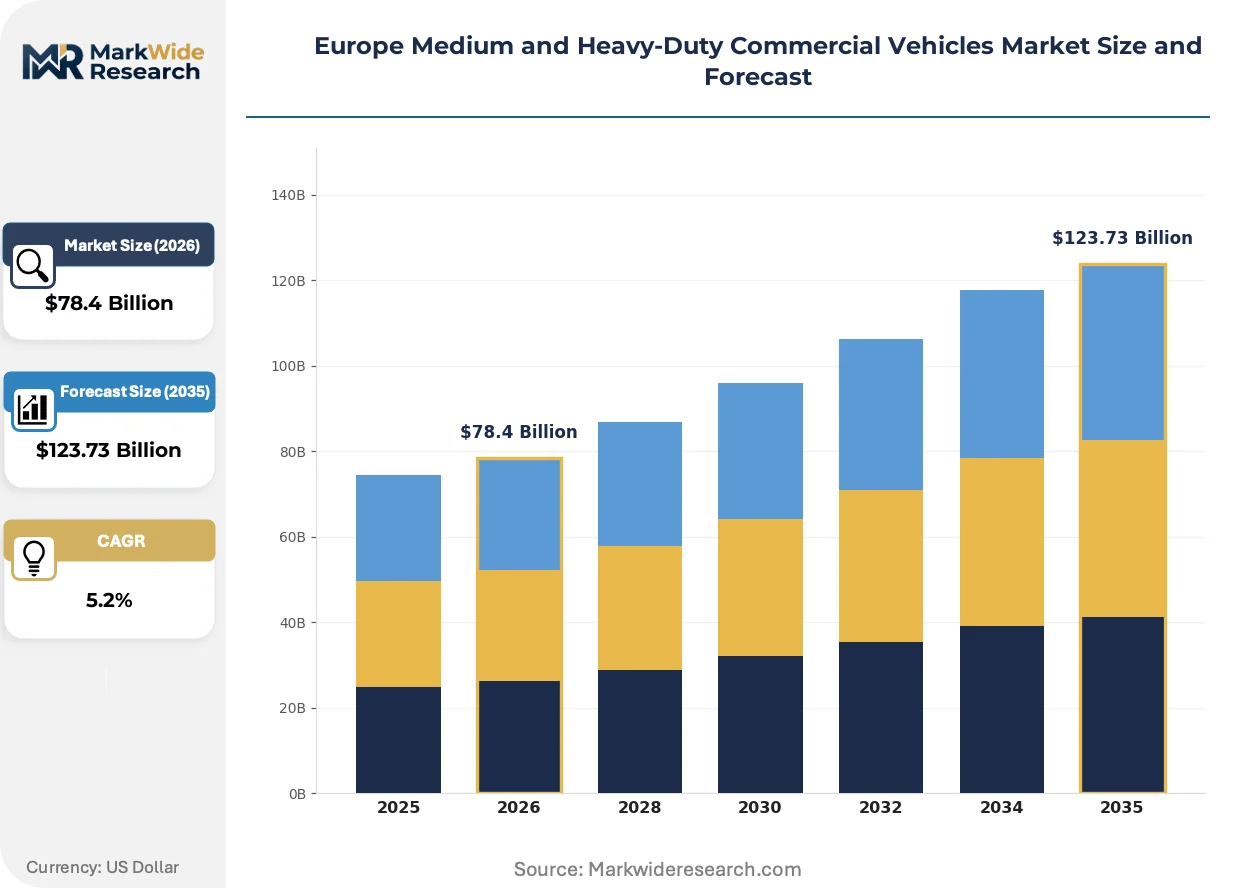
The EU Green Deal and Euro VII emission standards are forcing simultaneous reengineering of thermal management, exhaust aftertreatment, and powertrain architecture across European truck and bus manufacturing.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of hydrofluorocarbon refrigerants accelerates fleet replacement of older cooling systems in refrigerated transport vehicles across Germany and the Netherlands.
- Biomethane infrastructure:CNG refueling networks along Poland's A4 corridor and Spain's Mediterranean freight axis enable cost-competitive low-carbon operations for regional hauliers.
- Rotterdam port electrification:Shore power mandates and charging hub investments concentrate zero-emission truck demand in Europe's largest container throughput node.
Market Restraints
- Battery cell supply concentration:European OEM dependency on Asian cell manufacturers creates procurement bottlenecks and price volatility for electric powertrain programs.
- Copper and rare earth input costs:Magnet materials and high-voltage cabling expose electric truck margins to commodity price swings beyond manufacturer control.
- Grid connection delays:Distribution network operators in France and Italy impose 18-24 month lead times for depot charging infrastructure upgrades, freezing fleet electrification timelines.
Strategic Opportunities
- Romania and Bulgaria corridor development:EU Cohesion Fund infrastructure investments open underpenetrated long-haul markets for efficiency-optimized tractor units.
- Battery-electric urban bus mandates:Municipal procurement rules in Stockholm, Copenhagen, and Amsterdam create guaranteed demand pools for zero-emission chassis platforms.
- Vehicle-to-grid integration:Bidirectional charging protocols enable fleet operators to monetize parked truck batteries as grid stabilization assets in Nordic frequency regulation markets.
Industry Challenges
- High-voltage technician certification gaps:National qualification frameworks lag behind electric powertrain deployment, constraining service network expansion and warranty repair capacity.
- Euro VII homologation complexity:Divergent EMA and member state type-approval timelines fragment product launch sequencing and inventory allocation across markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Medium and Heavy-Duty Commercial Vehicles Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $123.73 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Truck, Bus, Van, Tractor Fuel Type: Diesel, Electric, CNG, Hybrid Application: Logistics, Construction, Public Transport, Freight End User: Fleet Operators, Government, Delivery Services, Construction Companies |
| Companies Covered | Daimler Truck, Volvo Group, Scania, MAN Truck & Bus, IVECO, DAF Trucks, PACCAR Inc, Renault Trucks, Traton SE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Medium and Heavy-Duty Commercial Vehicles Market Shifts & Advancements
Powertrain electrification, regulatory tightening on pollutants, and fleet purchasing model evolution are compressing development cycles and reshaping value capture across the European commercial vehicle value chain.
Silicon carbide inverters are replacing silicon IGBT modules in electric truck drivetrains. Long-haul fleet operators in Germany and the Netherlands are specifying SiC-based power electronics for new tractor orders. This wide-bandgap semiconductor technology is miniaturizing inverter packaging while cutting switching losses, enabling lighter axle-integrated motor configurations.
The EU F-Gas Regulation mandates refrigerant phase-down schedules that collide with Euro VII thermal management requirements. Manufacturers must redesign cab climate systems and battery cooling loops simultaneously. Bus OEMs serving Nordic municipal contracts face the tightest compliance windows, accelerating R&D partnerships with specialist HVAC suppliers.
Leasing structures with embedded charging infrastructure are displacing outright purchase for electric truck procurement. Logistics operators in Belgium and the Netherlands are contracting full-service mobility packages from financial lessors rather than owning assets. This shift concentrates credit risk assessment and residual value forecasting with banking subsidiaries, altering OEM customer relationships from product sales to platform partnerships.
Europe Medium and Heavy-Duty Commercial Vehicles Market Segmentation
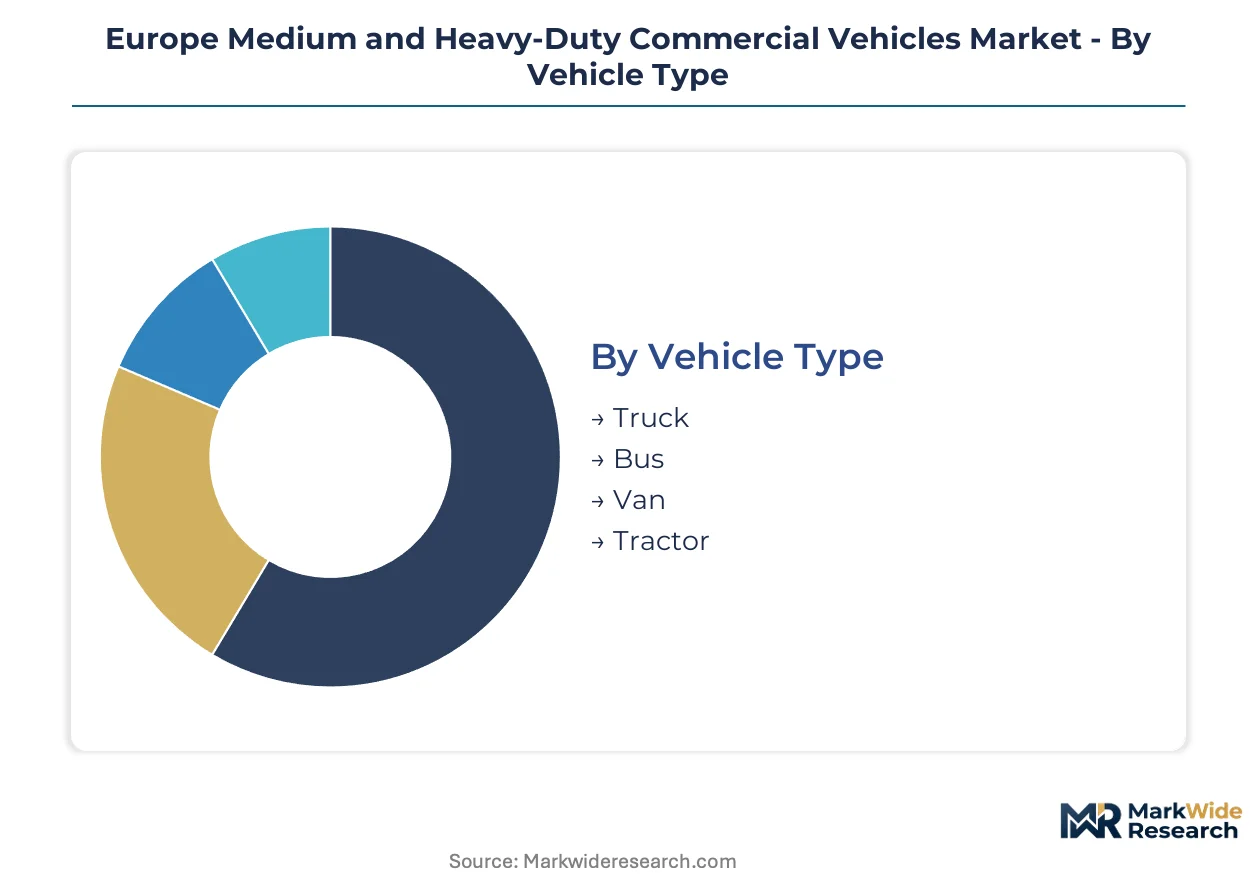
Powertrain transitions and procurement model shifts are fragmenting traditional segment boundaries across European commercial vehicle markets. Fleet operators now specify vehicles through application-specific performance contracts rather than standard product catalogs.
Vehicle Type:
Dealer networks and direct fleet channels carry differentiated product mixes, with rental/leasing intermediaries concentrating volume in standardized tractor configurations while municipal procurement favors purpose-built bus chassis.
- Truck:Rigid chassis configurations dominate urban distribution corridors, with German third-party logistics providers specifying 12-16 tonne models for last-mile consolidation. Euro VII thermal management requirements are extending development cycles for cab-over-engine designs serving Rhine-Ruhr freight clusters.
- Tractor:Articulated units engineered for sustained 40-tonne gross combination weight operation across continental motorway networks. Dutch port operators and Polish long-haul fleets are the primary demand centers, with efficiency optimization driving specification decisions.
- Bus:Low-floor urban and intercity configurations built on dedicated chassis with passenger capacity ranging from 35 to 120 seats. Municipal operators in Stockholm, Copenhagen, and Amsterdam mandate zero-emission variants through procurement rules.
- Van:Box-bodied derivatives between 3.5 and 7.5 tonnes gross vehicle weight serving parcel delivery and light commercial applications. Last-mile electrification is concentrating demand in Belgian and Netherlands urban access zones with emission restrictions.
Truck dominates installed base across European freight corridors. Tractor is where expansion concentrates as fleet operators renew long-haul assets ahead of Euro VII implementation.
Fuel Type:
Margin structures vary sharply across powertrain categories, with diesel retaining aftermarket service revenue density while electric platforms shift value capture toward battery leasing and charging infrastructure.
- Diesel:Compression-ignition engines with exhaust aftertreatment systems meeting Euro VI-E standards, still commanding the majority of heavy-haul registrations. Polish and Romanian fleet operators continue diesel procurement where biomethane infrastructure remains sparse.
- Electric:Battery-electric powertrains with 200-600 kWh pack configurations and depot-dependent charging protocols. Urban bus and delivery van segments in Germany and the Netherlands show steepest adoption curves where grid connections permit fleet-scale installation.
- CNG:Spark-ignition engines operating on compressed natural gas or biomethane blends, prevalent in regional distribution and waste collection fleets. Spain's Mediterranean corridor and Poland's A4 highway network support refueling infrastructure density.
- Hybrid:Parallel or series-electric architectures combining downsized combustion engines with battery buffers for regenerative braking recovery. Municipal bus operators in Alpine regions specify hybrid systems for topography-intensive routes where full electrification remains technically constrained.
Diesel retains the largest installed base. Electric platforms are gaining share fastest where charging infrastructure and subsidy frameworks align.
Application:
Specification requirements diverge across use cases, with logistics applications prioritizing total cost of ownership metrics while construction segments emphasize frame durability and drivetrain torque.
- Logistics:Temperature-controlled and dry freight operations requiring rapid turnaround and predictable maintenance intervals. German parcel networks and Netherlands cold-chain operators specify vehicles through total-cost contracts incorporating fuel and service provisions.
- Freight:Long-haul container and bulk transport between major port hinterlands and inland distribution nodes. Rotterdam port electrification mandates are redirecting procurement toward zero-emission tractor units for short-sea and intermodal connections.
- Construction:All-terrain chassis with reinforced frames, differential locks, and dump or mixer superstructures. Spanish and Italian infrastructure investment cycles drive demand for 6x4 and 8x4 configurations in quarry and earthmoving applications.
- Public Transport:Scheduled urban and suburban passenger services with accessibility mandates and dedicated lane operation. Nordic municipalities enforce the strictest electrification timelines through procurement specifications tied to EU Green Deal targets.
Logistics commands the deepest procurement volume. Public transport is where technology transition concentrates through regulatory mandate.
End User:
Customer scale and sophistication determine channel configuration, with large fleet operators negotiating direct OEM relationships while smaller buyers rely on dealer finance and service bundling.
- Fleet Operators:Multi-hundred vehicle enterprises with centralized procurement functions and in-house maintenance capabilities. German and Polish road freight consolidators specify tractors through framework agreements with embedded residual value guarantees.
- Government:Municipal, regional, and national transport authorities procuring buses and specialized vehicles through tender processes. Stockholm, Copenhagen, and Amsterdam transit authorities structure contracts around availability-based payments rather than asset ownership.
- Delivery Services:Parcel and express operators with high-frequency stop-start duty cycles and depot-based charging potential. Belgian and Netherlands last-mile specialists are transitioning van fleets through leasing structures incorporating charging infrastructure.
- Construction Companies:Project-based contractors acquiring specialized chassis for fixed-term infrastructure deployments. Romanian and Bulgarian EU Cohesion Fund projects are stimulating demand for heavy dump trucks and concrete mixers in corridor development zones.
Fleet operators dominate transaction volume. Government procurement is where zero-emission technology deployment concentrates through mandate-driven replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fleet operators prioritize long-haul tractor efficiency while Dutch buyers concentrate procurement around port electrification mandates. Polish hauliers favor CNG configurations where biomethane infrastructure permits. Nordic municipal authorities enforce the strictest zero-emission bus timelines.
Germany
Rhine-Ruhr logistics corridors drive concentrated demand for 40-tonne tractor units with Euro VII pre-compliance specifications. The EU Green Deal national implementation framework channels subsidies toward fleet renewal programs. Daimler Truck anchors manufacturing in Baden-Württemberg with integrated battery engineering facilities.
Netherlands
Rotterdam port electrification mandates redirect short-sea and intermodal procurement toward zero-emission chassis. The F-Gas Regulation accelerates refrigerated transport fleet replacement schedules. Eindhoven-Brabant logistics clusters concentrate depot charging infrastructure investments.
Poland
A4 corridor freight density sustains CNG tractor demand where biomethane refueling networks achieve coverage. National type-approval timelines under EMA coordination lag Western European implementation. Silesian manufacturing zones supply component assemblies to German OEM final assembly plants.
Sweden
Nordic cold-climate validation programs concentrate battery-electric bus procurement through Stockholm transit authority tenders. Municipal electrification mandates tied to EU Green Deal targets enforce 2030 phase-out timelines for diesel urban fleets. Volvo Group anchors service network density across Scandinavian logistics corridors.
Spain
Mediterranean freight axis development sustains CNG-powered regional distribution vehicle demand. Infrastructure investment cycles under EU Cohesion Fund programs stimulate construction segment chassis procurement. Catalan logistics operators trial hybrid configurations for topography-intensive routes.
Europe Medium and Heavy-Duty Commercial Vehicles Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in European commercial vehicle manufacturing. Daimler Truck, Volvo Group, and Traton SE occupy the consolidated upper tier with captive powertrain engineering and dense service networks. Below them, mid-scale specialists compete on modular architecture flexibility and regional customization. Dominant competitive moves include vertical integration into battery cell supply partnerships and geographic expansion through Eastern European assembly capacity.
Within the integrated tier, Daimler Truck and Volvo Group exemplify full-stack engineering capabilities spanning chassis design through battery management systems. Scania occupies a position emphasizing modular platform architecture that permits rapid powertrain reconfiguration. These three entities anchor the competitive structure through distinct strategic postures: Daimler Truck through in-house battery capacity, Volvo Group through Nordic climate validation leadership, and Scania through configurability-focused product planning.
| Leading Market Players |
|---|
| Daimler Truck |
| Volvo Group |
| Scania |
| MAN Truck & Bus |
| IVECO |
| DAF Trucks |
| PACCAR Inc |
| Renault Trucks |
| Traton SE |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between German OEMs and Asian cell suppliers lock in battery pack pricing visibility while constraining procurement flexibility for European powertrain programs. These contracts tie fleet operators to fixed residual value guarantees across the Euro VII transition window.
Pricing Analysis
Contract-based long-term offtake structures dominate electric tractor and bus procurement, with pricing stratifying across premium battery-electric configurations, standard diesel-Euro VII hybrids, and economy-grade CNG retrofit platforms. Price differentiation hinges on certification tier under EU Green Deal compliance bands and geographic delivery cost to Rotterdam or Rhine-Ruhr logistics clusters. Cost compression in economy diesel segments is intensifying because Polish and Romanian hauliers negotiate volume-scale discounts ahead of biomethane infrastructure build-out. Municipal fleet operators in Stockholm and Amsterdam show least price sensitivity due to availability-based payment structures, while independent Polish regional hauliers exhibit highest sensitivity to per-kilometer fuel cost exposure.
Supply Chain Analysis
Port congestion along the Rotterdam-Singapore trade lane and container availability constraints at Hamburg terminals elevate inbound logistics costs for battery cell and silicon carbide inverter shipments. European OEMs draw from South Korea, China, and Japan for lithium-ion cell supply, with copper busbar and rare earth magnet materials resting on concentrated mining jurisdictions. Single-source vulnerability in cathode active material processing exposes electric powertrain margins to supply interruption. Distribution runs through captive OEM service networks in Germany and the Netherlands, with secondary channel partners handling aftermarket parts in Eastern European corridor markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe medium and heavy-duty commercial vehicles is approaching a platform-economics inflection where vehicle-to-grid interoperability and charging infrastructure bundling reshape value capture from asset ownership to energy-services ecosystems.
For Market Incumbents: Shield core tractor margin pools by accelerating in-house battery engineering capacity in Baden-Württemberg and Lower Saxony production clusters against Asian cell supplier pricing power. Secure channel control through embedded charging infrastructure leasing partnerships with Dutch and Belgian logistics operators, insulating against financial lessor disintermediation. For New Entrants and Emerging Players: Lead with modular retrofit platforms targeting Romania and Bulgaria corridor development zones where EU Cohesion Fund infrastructure investment stimulates demand but incumbent service network density remains thin. Penetrate through battery-electric urban van segments in Belgian last-mile access zones, offering depot charging as a bundled subscription service rather than asset sale. For Investors and Strategic Acquirers: Specialist HVAC engineering firms with F-Gas Regulation compliance capabilities and Euro VII thermal management partnerships represent the most defensible acquisition profile for medium-term exposure. Watch municipal tender award velocity in Nordic capitals as the inflection signal—accelerated Stockholm and Copenhagen zero-emission bus procurement timelines indicate policy commitment durability across the analysis window.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Cell offtake contracts with Korean manufacturers secure powertrain program cost visibility under EU Green Deal targets. |
| Charging Infrastructure Partnership | Depot hub investments in Eindhoven-Brabant clusters enable leasing structure monetization for Dutch fleet operators. |
| Platform Standardization | Modular chassis architectures permit rapid powertrain swaps between diesel, hybrid, and electric configurations. |
| Software-Defined Vehicle Investment | Vehicle-to-grid protocols monetize parked truck batteries as frequency regulation assets in Nordic markets. |
| Geographic Manufacturing Footprint | Eastern European assembly capacity expansion targets Romanian and Bulgarian EU Cohesion Fund corridor projects. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet procurement directors, OEM platform engineers, Tier 1 supplier account managers, and municipal transit authority tender officers. Secondary validation drew from EMA type-approval filings, EU Green Deal implementation progress reports, IHS Markit vehicle registration databases, and national statistics office freight transport surveys. Bottom-up volume builds across powertrain categories were triangulated against top-down macroeconomic demand indicators.
Across the analysis window, projections incorporate powertrain transition velocity, Euro VII compliance cost pass-through assumptions, and charging infrastructure deployment rates by member state. Segmentation dimensions span vehicle class, fuel architecture, application use case, and end-user procurement sophistication. CAGRs were derived from fitted adoption curves calibrated to historical diesel-electric substitution patterns in Nordic municipal bus markets.
Forecasts assume regulatory continuity in EU F-Gas Regulation phase-down schedules and national subsidy frameworks; material policy shifts would require re-modeling. Battery cell supply concentration, grid connection approval delays in France and Italy, and rare earth price volatility represent specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Europe Fire Truck Market
Heavy-Duty Trucks
Dump Trucks and Mining Trucks Market
Heavy-Duty Trucks
Garbage Truck Bodies Market
Heavy-Duty Trucks
Heavy Duty Truck Wash Market
Heavy-Duty Trucks
Global Snow Sweeper Truck Market
Heavy-Duty Trucks
Automotive High Performance Trucks Market
Heavy-Duty Trucks
Hard Tonneau Cover Market
Heavy-Duty Trucks
China Full Truckload Road Freight Transport Market
Heavy-Duty Trucks
Vacuum Truck Market
Heavy-Duty Trucks
Logging Trucks Market
Heavy-Duty Trucks
Truck Racks Market
Heavy-Duty Trucks
Garbage Collection Trucks Market
Heavy-Duty Trucks
Egypt Trucks Market
Heavy-Duty Trucks
United States Refrigerated Trucking Market
Heavy-Duty Trucks
Mexico Refrigerated Truck Market
Heavy-Duty Trucks
Utility Trucks Market