
 Global Garbage Truck Market | 2026-2036
Global Garbage Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Global Garbage Truck Market Analysis
A widening capital-intensity gap between integrated chassis builders and body-only specialists is reorganizing competitive tiers in garbage truck manufacturing. Volvo Group leverages its in-house electric drivetrain development to anchor premium municipal contracts across Scandinavian cities. McNeilus Truck and Manufacturing specializes in automated side-loader bodies that compete on labor-reduction metrics for large waste haulers. Dongfeng Motor Corporation dominates domestic procurement in China through state-favored supply relationships and localized production scale.
Garbage trucks are purpose-built commercial vehicles combining a cab-chassis with hydraulic compaction and lifting mechanisms designed to collect, compress, and transport municipal solid waste; typical compaction ratios reach four-to-one, enabling payloads exceeding twenty tons in heavy-duty configurations. Rear loader configurations retain the largest installed base among vehicle type segments, though side loaders are capturing faster replacement cycles as municipalities automate collection to reduce crew sizes. Electric power source adoption is accelerating fastest where total cost of ownership calculations incorporate carbon pricing and fuel subsidies, while diesel variants still occupy the majority of emerging-market fleets due to lower upfront capital requirements and sparse charging infrastructure.
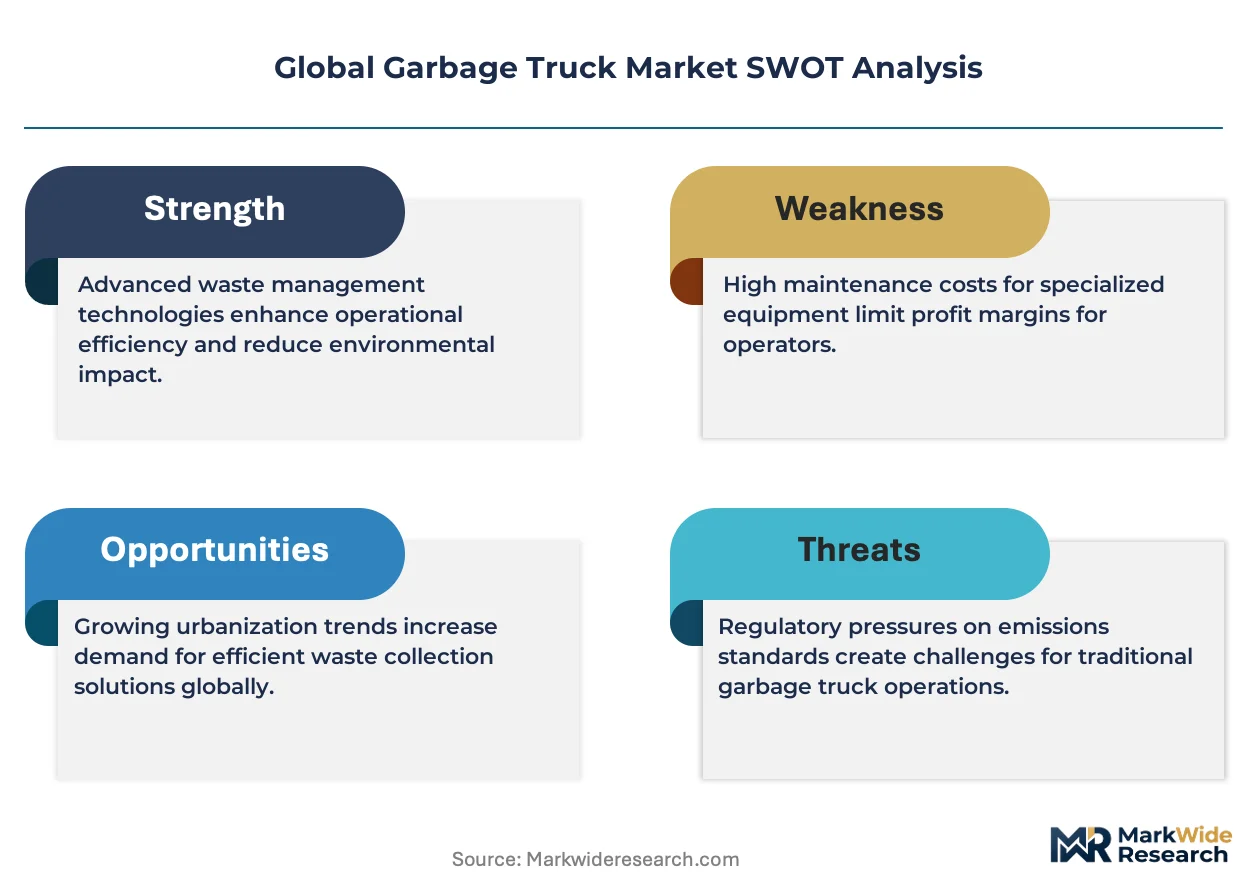
The EPA's Clean Trucks Plan and the EU Green Deal's heavy-duty CO2 standards are forcing simultaneous powertrain transitions across both North American and European procurement channels. China's MIIT enforces new energy vehicle quotas that directly shape Dongfeng and BYD production allocations for domestic sanitation departments. Fleet operators must monitor how divergent subsidy timelines between Washington's IRA commercial vehicle credits and Brussels' F-Gas Regulation on refrigerants in compaction systems alter total cost comparisons across regions.
Market Dynamics
Stringent emissions regulations across multiple continents are forcing synchronous fleet turnover, compressing replacement cycles from fifteen years toward ten as municipalities race to secure zero-emission vehicle allocations before subsidy cliffs expire.
Growth Catalysts
- EU Green Deal heavy-duty CO2 standards:Brussels mandates 45% emission reductions by 2030, compelling German and French sanitation departments to accelerate electric truck procurement timelines.
- Battery energy density improvements:Solid-state cell chemistry advances are extending electric garbage truck range to 200+ kilometers, eliminating route-adequacy concerns for urban operators.
- China's MIIT new energy vehicle quotas:Domestic procurement mandates require 40% NEV penetration in municipal fleets, directly stimulating Dongfeng and BYD production scaling.
Market Restraints
- Lithium and cobalt price volatility:Raw material cost swings of 30-50% annually compress electric powertrain margins and destabilize OEM quoting confidence.
- Charging infrastructure gaps:Sparse depot fast-charging networks in India and Brazil force diesel retention despite regulatory pressure.
- F-Gas Regulation refrigerant restrictions:Brussels phase-down of hydrofluorocarbons complicates compaction system cooling redesign timelines.
Strategic Opportunities
- US Inflation Reduction Act commercial vehicle credits:Washington's $40,000 per-vehicle tax incentive creates arbitrage potential for fleet operators accelerating 2024-2027 purchases.
- Automated side-loader convergence with telematics:Route optimization algorithms paired with single-operator bodies reduce labor costs 25-35% in high-wage markets.
- India's urban sanitation expansion:Smart Cities Mission funding unlocks 15,000+ unit demand across tier-2 municipalities lacking formal waste collection infrastructure.
Industry Challenges
- High-voltage technician scarcity:Electric powertrain maintenance requires certified specialists earning 40% premiums over diesel mechanics, constraining fleet uptime guarantees.
- ISO 26262 functional safety certification:Autonomous lifting mechanism validation extends product development cycles 18-24 months for automated body manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Garbage Truck Market |
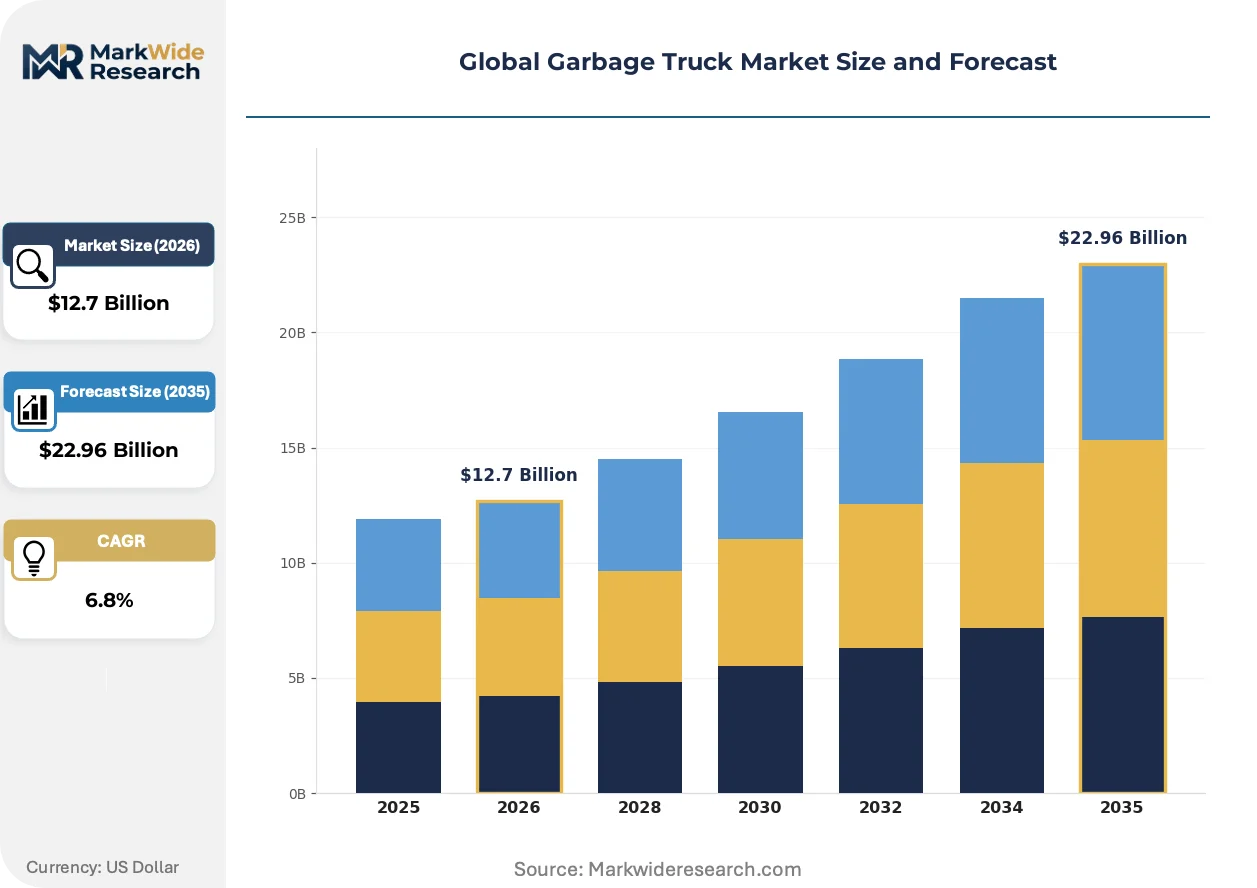
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $22.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Rear Loader, Front Loader, Side Loader, Multi-Body Power Source: Diesel, Electric, Hybrid, Compressed Natural Gas Payload Capacity: Light Duty, Medium Duty, Heavy Duty, Super Duty End User: Municipalities, Waste Management Companies, Contract Haulers, Private Organizations |
| Companies Covered | BYD Company Ltd., Volvo Group, Oshkosh Corporation, Dongfeng Motor Corporation, FULONGMA GROUP Co., Ltd., Heil Environmental, McNeilus Truck and Manufacturing, Mack Trucks, XCMG Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Garbage Truck Market Emerging Trajectories
Garbage truck architecture is bifurcating between software-defined electric platforms and mechanically optimized legacy designs, with data-centric fleet management becoming the primary differentiation vector.
Telematics-integrated compaction control is miniaturizing sensor arrays into load-cell arrays embedded within hydraulic rams. Municipal operators in Scandinavian cities deploy these systems to optimize collection frequency based on real-time bin-fill data. The technology is compressing route planning from weekly schedules toward dynamic dispatch models that cut fuel consumption 12-18%.
EPA's Clean Trucks Plan mandates NOx reductions 60% below current standards for 2027 model year heavy-duty vehicles. Engine manufacturers must deploy selective catalytic reduction systems with doubled urea dosing capacity. California Air Resources Board's Advanced Clean Trucks rule extends these requirements to 50% of sales by 2035, forcing nationwide powertrain portfolio restructuring.
Lifecycle service contracting is displacing capital purchase models among North American waste management conglomerates. Fleet operators now demand guaranteed cost-per-ton performance with OEMs retaining residual value risk. This shift concentrates procurement authority with CFOs rather than municipal engineering departments, privileging suppliers with captive financing arms.
Global Garbage Truck Market Segmentation
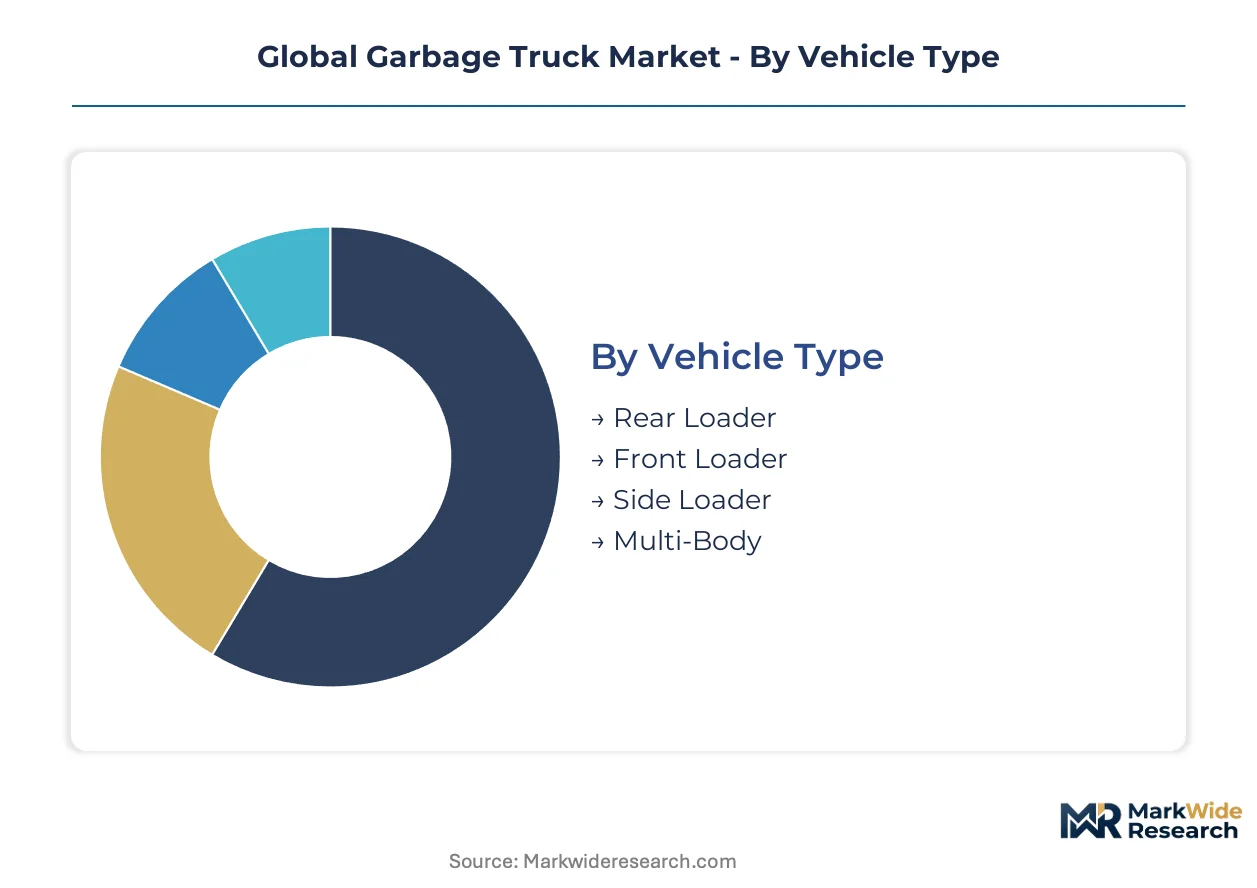
Garbage truck procurement channels diverge sharply by segment, with municipalities favoring integrated chassis-body packages while private haulers prioritize body-only retrofit flexibility. Understanding these channel dynamics reveals where pricing power concentrates and which configurations command premium positioning.
Vehicle Type:
Municipal fleets purchase rear and side loaders through dedicated public procurement channels with multi-year service contracts, while front loaders flow primarily to commercial waste haulers via dealer networks with equipment financing attached.
- Rear Loader:Hydraulic compaction systems mounted behind the cab accommodate manual bag collection with crew sizes of two to three operators. Demand clusters in legacy urban districts across Germany and the northeastern United States where narrow street grids resist automated arm deployment.
- Side Loader:Single-operator automated arm configurations reduce labor costs substantially on residential routes. Scandinavian cities and California municipalities are expanding side loader procurement fastest as union-negotiated crew minimums drive automation economics.
- Front Loader:Roll-off container compatibility dominates commercial and industrial collection. Waste Management Companies in Texas and Florida favor front loaders for construction debris routes.
- Multi-Body:Interchangeable compaction modules enable fleet flexibility across seasonal waste streams. Contract haulers in Australian urban corridors deploy multi-body configurations for event-driven collection spikes.
By volume, Rear Loader leads. By growth pace, Side Loader is ahead.
Power Source:
Cost tier stratification separates diesel variants in price-sensitive emerging markets from electric and CNG configurations in jurisdictions with carbon pricing or clean fleet mandates.
- Diesel:Proven powertrains with established service networks dominate where upfront capital constraints outweigh lifecycle cost considerations. Indian tier-2 municipalities and Brazilian sanitation departments continue diesel procurement despite tightening emission norms.
- Electric:Battery-electric drivetrains from established OEMs now achieve 200+ kilometer range with depot overnight charging. German cities under EU Green Deal compliance timelines are electrifying central district fleets first.
- Hybrid:Diesel-electric architectures bridge range anxiety gaps in suburban routes with stop-and-go collection patterns. Japanese metropolitan governments evaluate hybrid deployments where full electrification infrastructure remains incomplete.
- Compressed Natural Gas:CNG powertrains offer emission reductions without battery supply chain exposure. Southern California air quality management districts favor CNG where renewable natural gas injection supports carbon-neutral claims.
Diesel retains volume leadership. Electric gains share fastest where subsidy stacking applies.
Payload Capacity:
Application intensity determines capacity selection, with route density and waste stream composition driving fleet composition across customer types.
- Light Duty:Sub-10 ton gross vehicle weight suits confined urban cores and historic district access restrictions. Paris arrondissements deploy light duty configurations for narrow medieval street networks.
- Medium Duty:10-16 ton range balances maneuverability with compaction efficiency for standard residential routes. UK county councils standardize on medium duty for mixed urban-suburban collection zones.
- Heavy Duty:16-26 ton configurations maximize payload for dense commercial waste streams. New York City commercial waste zones mandate heavy duty specifications for high-rise corridor service.
- Super Duty:Specialized above-26 ton platforms serve industrial and construction debris markets with reinforced compaction mechanisms. Australian mining camp sanitation contracts specify super duty for remote location efficiency.
Heavy Duty dominates municipal procurement volume. Super Duty expands most quickly in resource extraction corridor servicing.
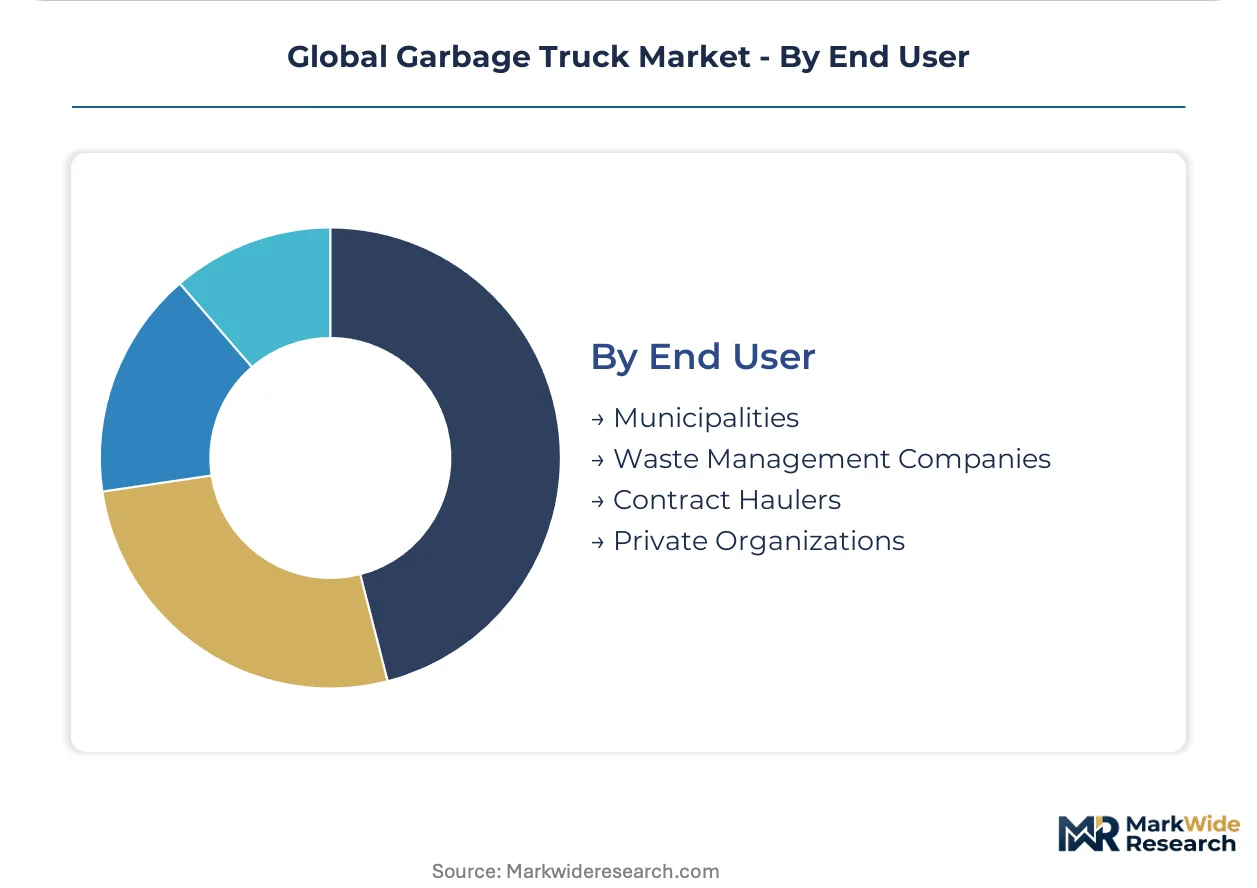
End User:
Customer type shapes contract structure, with municipalities demanding lifecycle service guarantees and private operators prioritizing acquisition flexibility and residual value capture.
- Municipalities:Public sector procurement emphasizes total cost of ownership with performance-based service contracting. German Stadtreinigungsbetriebe negotiate 10-year availability guarantees with penalty clauses.
- Waste Management Companies:Integrated national operators leverage fleet standardization for maintenance economies and driver pool flexibility. Republic Services and WM Inc. specify cross-compatible body interfaces.
- Contract Haulers:Regional operators serving multiple municipal clients demand rapid body swap capability and financing portability. Midwest US contract haulers prioritize dealer network density for uptime assurance.
- Private Organizations:Campus, hospital, and retail estate operators purchase specialized configurations outside municipal procurement frameworks. Saudi Aramco residential compounds specify premium cabin configurations for expatriate district standards.
Municipalities anchor volume demand. Contract haulers are climbing the fastest as service privatization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian tier-2 municipalities exhibit extreme price elasticity, deferring electric procurement until total cost parity arrives, while German Stadtreinigungsbetriebe absorb 40% capital premiums for zero-emission compliance. This demand bifurcation shapes divergent fleet turnover timelines across procurement channels.
United States
Waste Management Inc. and Republic Services dominate fleet standardization through cross-compatible body specifications that reduce maintenance pooling costs. EPA's Clean Trucks Plan mandates 60% NOx reductions for 2027 model year heavy-duty vehicles, forcing selective catalytic retrofits. California's Advanced Clean Trucks rule drives 50% zero-emission sales requirements by 2035, concentrating electric pilot deployments in Los Angeles and San Francisco municipal contracts.
Germany
Stadtreinigungsbetriebe in Berlin and Hamburg negotiate 10-year availability guarantees with penalty clauses tied to route uptime metrics. EU Green Deal heavy-duty CO2 standards mandate 45% emission reductions by 2030, accelerating electric garbage truck procurement in Bavarian and North Rhine-Westphalian sanitation departments. Munich's municipal fleet operator has deployed solid-state battery prototypes across historic district routes with narrow street grids.
China
MIIT new energy vehicle quotas require 40% NEV penetration in municipal fleets, directly shaping procurement allocations for provincial sanitation departments. Dongfeng Motor Corporation leverages state-favored supply relationships to dominate domestic tenders in Wuhan and Shanghai. Beijing-Tianjin-Hebei corridor municipalities prioritize electric deployment for political visibility under dual carbon goals enforcement.
India
Smart Cities Mission funding unlocks 15,000+ unit demand across tier-2 municipalities lacking formal waste collection infrastructure. The country's urban sanitation expansion prioritizes diesel retention due to sparse depot charging networks and 30-50% lithium price volatility exposure. Maharashtra and Gujarat state municipalities concentrate procurement in Mumbai and Ahmedabad industrial corridors where contract hauler privatization accelerates fastest.
Brazil
São Paulo and Rio de Janeiro sanitation departments defer electric transition due to charging infrastructure gaps and currency-driven capital constraints. ANVISA-equivalent municipal regulators enforce tailpipe standards that lag EU and US timelines by 5-7 years. Minas Gerais state mining camp operators specify super-duty configurations for remote location efficiency in resource extraction corridors.
Global Garbage Truck Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where integrated chassis builders command premium municipal contracts while body-only specialists compete on labor-reduction metrics. The market concentrates around three strategic archetypes: in-house electric drivetrain developers, automated side-loader body specialists, and state-favored domestic producers. Dominant competitive moves include strategic partnerships for charging infrastructure access and portfolio diversification into lifecycle service contracting.
Within the integrated chassis-builder tier, Volvo Group and BYD Company Ltd. exemplify technology-forward positioning through captive electric drivetrain development. Among body-only specialists, McNeilus Truck and Manufacturing occupies a position defined by automated lifting mechanism specialization. Dongfeng Motor Corporation anchors the state-favored producer archetype, leveraging localized production scale to secure domestic procurement preferences. These three archetypes represent the primary competitive vectors reshaping contract structures across municipal and commercial waste hauler channels.
| Leading Market Players |
|---|
| BYD Company Ltd. |
| Volvo Group |
| Oshkosh Corporation |
| Dongfeng Motor Corporation |
| FULONGMA GROUP Co., Ltd. |
| Heil Environmental |
| McNeilus Truck and Manufacturing |
| Mack Trucks |
| XCMG Group |
| Others |
Supply Flow & Price Mechanics
ISO 26262 functional safety certification gates both supplier qualification and price stratification in electric garbage truck procurement, forcing body manufacturers to absorb 18-24 month validation cycles that separate premium-tier integrators from commodity chassis assemblers. Municipal buyers in Germany and California now demand certified autonomous lifting mechanisms as baseline specifications, compressing margins for uncertified competitors while rewarding captive electric drivetrain developers with pricing power.
Pricing Analysis
After-sales service contracts now drive lifetime value capture, with lifecycle availability guarantees commanding 15-25% premiums over transactional chassis sales. Three-tier pricing structure across premium, standard, and economy levels reflects divergence in powertrain electrification depth and telematics integration density. Cost compression in battery-electric configurations is intensifying because lithium and cobalt price volatility destabilizes OEM quoting confidence. Waste management companies exhibit lowest price sensitivity due to CFO-driven procurement centralization, while Indian tier-2 municipalities defer electric adoption until total cost parity arrives.
Supply Chain Analysis
Strategic stockpiling of battery cells and high-grade steel dominates inventory strategy as OEMs buffer against lithium price swings of 30-50% annually. Manufacturing concentration centers on China, Germany, and the United States, with Dongfeng and Volvo anchoring regional production clusters. Raw material dependencies tether the industry to lithium carbonate, cobalt sulfate, and specialized hydraulic steel alloys. Single-source vulnerability in solid-state battery cell supply poses structural risk as prototype deployments scale. Distribution runs through municipal procurement channels in Europe and North America, with dealer networks serving private hauler segments in deregulated markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among integrated waste management conglomerates through fleet standardization mandates, fragmenting procurement authority away from municipal engineering departments toward centralized CFO offices.
For Market Incumbents: Fortify captive financing arms to retain residual value risk in lifecycle service contracting, the dominant procurement model displacing capital purchases among North American waste haulers. Deepen backward integration into battery cell supply through offtake agreements with Korean and Chinese producers, buffering margin erosion from raw material volatility. Counter emerging entrant pressure from automated side-loader specialists by embedding telematics platforms that lock in route optimization data exclusivity.
For New Entrants and Emerging Players: Aftermarket high-voltage technician training represents the most penetrable service-layer gap, as electric powertrain maintenance scarcity constrains fleet uptime guarantees for established OEMs. Target contract hauler segments in India's Smart Cities Mission corridors, where privatization accelerates fastest and incumbent service networks remain underdeveloped. Deploy mobile charging infrastructure partnerships as the primary go-to-market angle, circumventing depot infrastructure gaps that delay electric adoption in Brazil and tier-2 Indian municipalities.
For Investors and Strategic Acquirers: EPA's Clean Trucks Plan 2027 compliance deadline reshapes the acquisition landscape by forcing selective catalytic retrofit investments that favor capitalized incumbents over underfunded body-only specialists. Five-to-ten year viability hinges on electric drivetrain integration depth rather than mechanical compaction heritage alone. Acquisition target archetype: mid-cap automated body manufacturers with ISO 26262 certification progress and existing municipal service contracts. Signal to monitor: divergence in IRA commercial vehicle credit utilization rates between integrated fleet operators and fragmented contract hauler bases.
| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Depot fast-charging networks unlock electric route viability in suburban configurations where range anxiety persists. |
| Battery Supply Agreement | Long-term cell offtakes with Korean producers buffer margin compression from lithium price volatility exposure. |
| Lifecycle Service Contracting | Guaranteed cost-per-ton performance shifts procurement authority to CFOs, privileging suppliers with captive financing. |
| Telematics Platform Integration | Real-time compaction control embedded in hydraulic rams enables dynamic dispatch models that cut fuel consumption. |
| Automated Side-Loader Certification | ISO 26262 validation extends development cycles but gates premium municipal contracts in Scandinavian cities. |
Methodological Framework
A spread of perspectives from municipal fleet managers, waste hauler procurement directors, OEM platform engineers, and aftermarket service heads converged on the working assumptions driving volume and value estimates. Primary interviews with sanitation department contract negotiators and integrated operator CFOs combined with secondary validation against EPA regulatory filings, EU Green Deal implementation trackers, MIIT production allocation disclosures, and municipal tender databases. Bottom-up unit deployment modeling triangulated against top-down addressable market sizing across vehicle type, power source, and payload capacity dimensions.
Segmentation dimensions modeled include vehicle configuration, propulsion architecture, gross vehicle weight tier, end-user procurement channel, and regional regulatory cluster throughout the forecast period. CAGRs were derived from replacement cycle compression analysis and subsidy cliff timing across Washington's IRA commercial vehicle credits and Brussels' F-Gas Regulation phase-down schedules. Industry-specific forecast inputs incorporated battery energy density improvement curves and high-voltage technician wage premium trajectories.
Underlying assumptions cover subsidy continuity timelines and raw material price stabilization, with deviation risk concentrated in lithium supply chain disruptions and divergent municipal electrification enforcement across Indian and Brazilian procurement channels. Revision becomes warranted when battery-electric total cost of ownership crosses diesel parity thresholds in price-sensitive emerging markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Car Rental Market
Transportation Services
Europe Refrigerated Truck Rental Market
Transportation Services
Vacuum Truck Rentals Market
Transportation Services
China Vehicle Rental Market
Transportation Services
Bike and Scooter Rental Market
Transportation Services
Scandinavia Car Rental Market
Transportation Services
Corporate Car Sharing Market
Transportation Services
United Arab Emirates Car Rental Market
Transportation Services
Spain Car Rental Market
Transportation Services
India Taxi Market
Transportation Services
Malaysia Car Rental Market
Transportation Services
North America Vehicle Rental Market
Transportation Services
Egypt Ride Hailing Service Market
Transportation Services
Third Party Logistics Services Market
Transportation Services
Online Bus Ticketing Service Market
Transportation Services
Bulk Transportation Services Market