
 Logging Trucks Market | 2026-2036
Logging Trucks Market Size, Share, and Industry Trends Forecast 2026-2036
Logging Trucks Market Analytics
Electrified powertrain architecture is narrowing the operational gap between diesel and zero-emission logging platforms in steep-terrain applications. Freightliner Trucks leverages its integrated Detroit powertrain ecosystem to sustain highway-to-forest transition capability. Kenworth anchors its position through severe-service chassis engineering optimized for off-highway payload cycles. Peterbilt differentiates via aluminum cab construction that reduces tare weight without compromising rollover protection.
Logging trucks are specialized heavy-duty commercial vehicles engineered to transport felled timber from harvest sites to mills or collection points, typically featuring reinforced frames, high-torque axles, and log bunk assemblies rated for extreme load distribution across unpaved gradients. Conventional trucks dominate current fleet composition due to established service networks and parts availability, while forwarder trucks capture expanding share in selective-cutting operations where minimized ground disturbance commands premium pricing. Heavy-duty load capacity classifications concentrate margin pools where axle configurations and suspension ratings determine regulatory compliance and insurance underwriting.
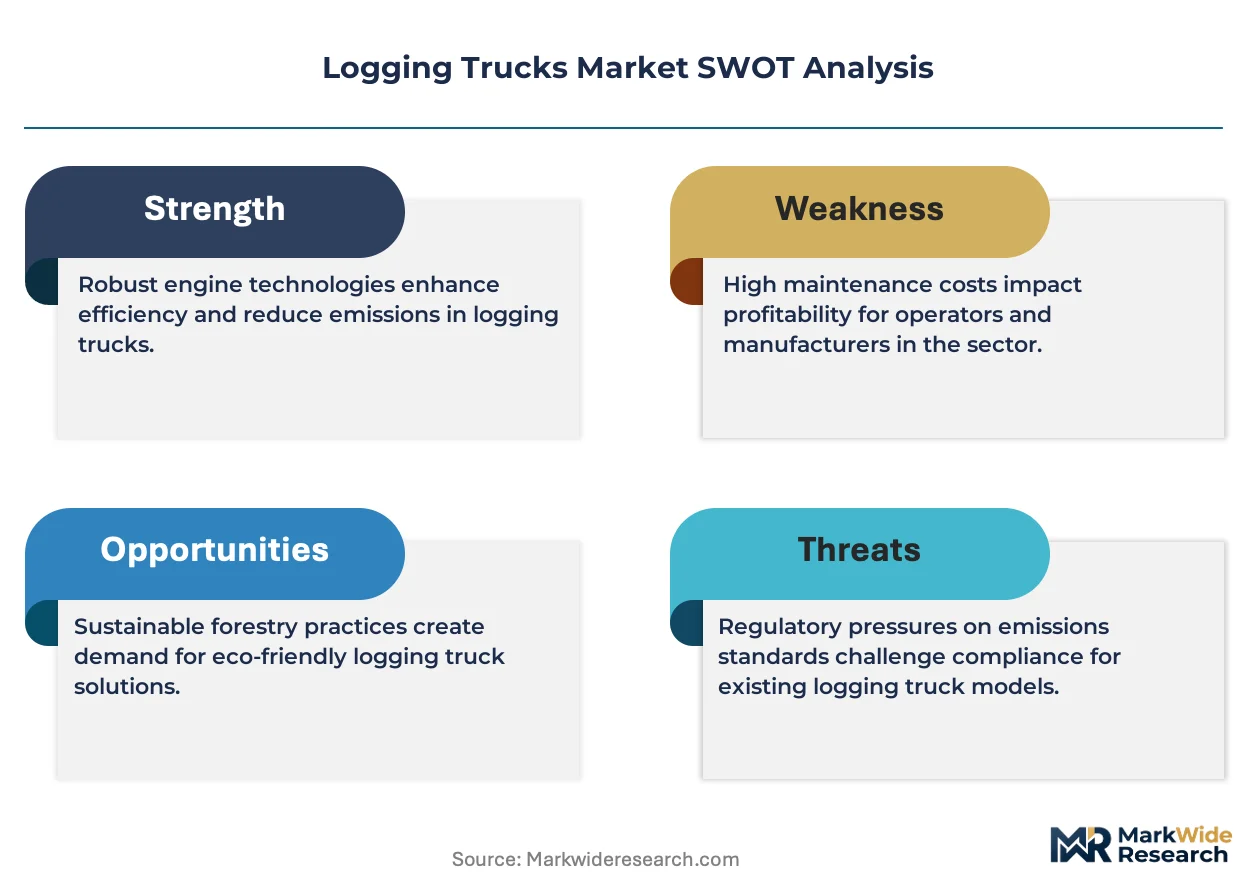
EPA emissions standards and NHTSA greenhouse gas regulations for heavy-duty vehicles directly constrain engine type availability and retrofit economics across North American logging operations. EU F-Gas Regulation and Stage V non-road emission directives from European member states accelerate hybrid engine penetration in Baltic and Scandinavian timber corridors. Fleet operators and OEM program managers must monitor battery-electric range validation under loaded mountain descent cycles where regenerative braking recovery determines total cost of ownership parity.
Market Dynamics
EPA Tier 4 Final emissions mandates are forcing timber harvesting fleets to retire aging diesel powertrains and absorb the capital cost of hybrid-electric replacements before compliance deadlines lock in. This regulatory compression is reshaping fleet replacement cycles and OEM order books simultaneously.
Growth Catalysts
- EU F-Gas Regulation:Nordic forest road electrification infrastructure expansion accelerates battery-electric drivetrain validation in steep-terrain corridors.
- Selective-cutting operations:Forwarder trucks command premium pricing where minimized ground disturbance drives equipment specification.
- Aluminum cab construction:Tare weight reduction without rollover protection compromise enables heavier payload certification.
Market Restraints
- Battery-electric range anxiety:Loaded mountain descent cycles limit regenerative braking recovery predictability for total cost of ownership modeling.
- Service network concentration:Established diesel parts availability concentrates maintenance capability in legacy corridor geographies.
- Highland gradient axle stress:Reinforced frame and high-torque axle specifications inflate unit acquisition cost versus highway-only configurations.
Strategic Opportunities
- Finnish-Swedish timber corridors:Advanced forest electrification infrastructure creates first-mover advantage for zero-emission platform deployment.
- Integrated Detroit powertrain ecosystems:Highway-to-forest transition capability bundles service contracts and residual value guarantees.
- Insurance underwriting differentiation:Heavy-duty load capacity classifications tied to axle configuration enable premium fleet rating tiers.
Industry Challenges
- Regenerative braking calibration:Loaded descent cycle validation requires specialized technician training absent from standard diesel service programs.
- Log bunk assembly standardization:Extreme load distribution ratings vary by jurisdiction, complicating cross-border fleet interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Logging Trucks Market |
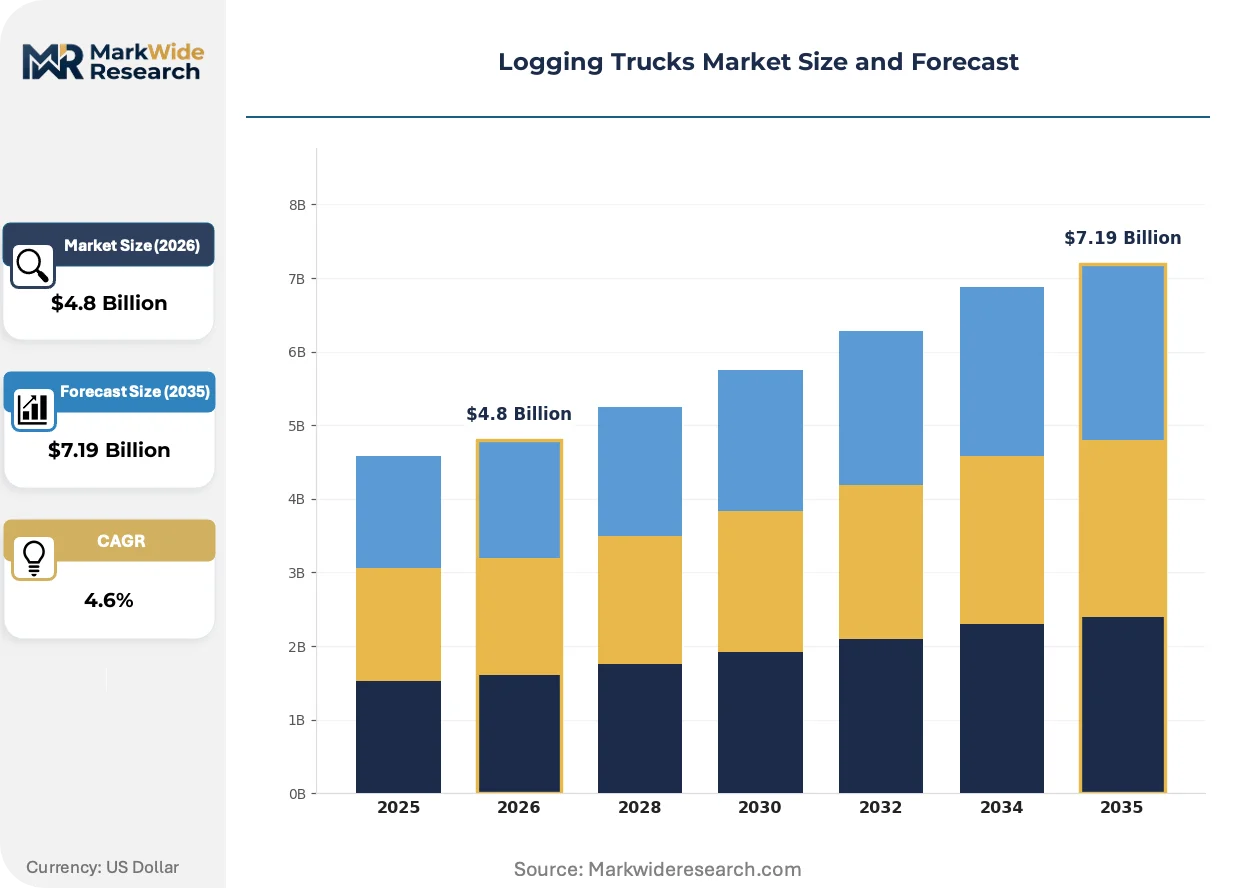
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Truck Type: Conventional Trucks, Forwarder Trucks, Feller Buncher Trucks, Grapple Trucks Load Capacity: Medium Duty, Heavy Duty, Extra Heavy Duty, Specialized Trucks Application Type: Forest Operations, Timber Harvesting, Material Transport, Land Clearing Engine Type: Diesel Engines, Gas Engines, Hybrid Engines, Electric Engines |
| Companies Covered | Freightliner Trucks, DONGFENG Commercial Vehicle, Kenworth, Komatsu, Edison Motors, Peterbilt, Cecor Incorporated, Caterpillar, Mack Trucks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Logging Trucks Market Evolving Landscape
Telematics integration is digitizing fleet management protocols across dispersed harvest sites, compressing the information lag between mill demand signals and woods equipment positioning. This connectivity layer is becoming the primary interface for OEM aftermarket revenue capture.
Sensor-embedded axle assemblies are digitizing real-time load distribution monitoring across unpaved gradients, enabling predictive maintenance scheduling before frame stress fractures propagate. Pacific Northwest fleet operators are adopting these systems fastest where terrain variability maximizes failure cost. The technology is digitizing warranty claim prevention and residual value forecasting simultaneously.
EPA NHTSA greenhouse gas regulations for heavy-duty vehicles are tightening engine type availability and retrofit economics across North American logging operations. Stage V non-road emission directives from European member states accelerate hybrid engine penetration in Baltic timber corridors. Severe-service chassis engineering investments concentrate where regulatory compliance timelines shortest.
Mill-direct procurement contracts are consolidating equipment specification authority away from independent logging contractors toward integrated timber companies with captive maintenance infrastructure. This buyer concentration compresses OEM sales cycle length but intensifies price negotiation leverage. Nordic integrated forestry companies demonstrate this pattern most visibly where vertical timber ownership dominates.
Logging Trucks Market Segmentation
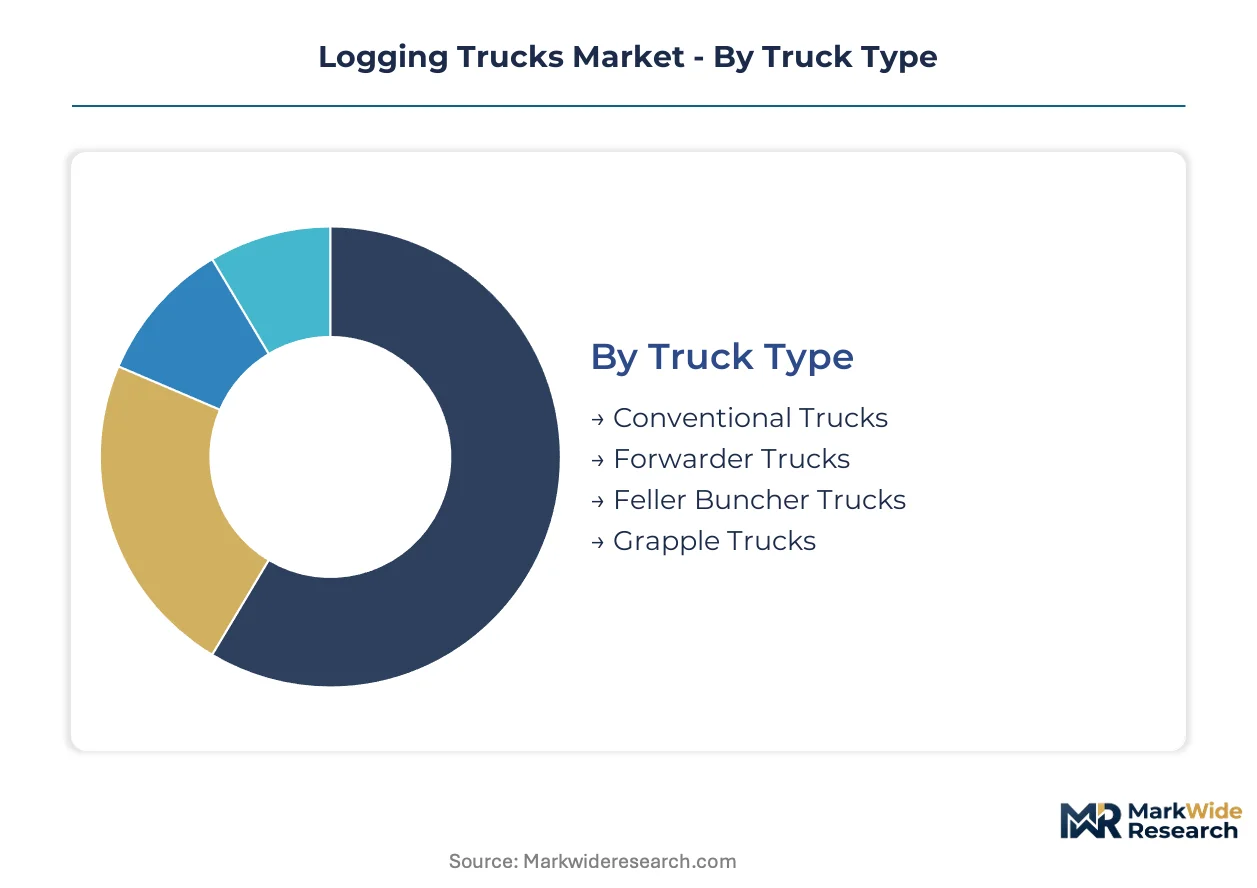
Logging truck specification choices cascade through maintenance contract structures, residual value guarantees, and parts inventory requirements. Fleet operators calibrate segment selection against terrain severity, haul distance, and mill contract terms.
Truck Type:
After-sales service intensity varies sharply across truck type categories, with specialized configurations demanding dedicated technician certification programs and non-standard parts stocking protocols.
- Conventional Trucks:Standard frame-rail architecture accommodates modular log bunk assemblies across multiple axle configurations. Demand concentrates in Pacific Northwest corridor operations where established dealer networks support rapid component turnaround. EPA Tier 4 Final retrofit economics favor replacement over engine overhaul for aging units in this category.
- Forwarder Trucks:Self-loading crane integration and bunk-mounted grapple systems enable single-operator selective cutting with minimized ground disturbance. Nordic integrated forestry companies specify these units for steep-terrain corridors where reduced soil compaction commands premium stumpage pricing. The integrated hydraulic systems demand specialized service contracts absent from conventional truck programs.
- Feller Buncher Trucks:Combined felling and transport capability consolidates equipment counts in high-volume clearcut operations.
- Grapple Trucks:Loader-mounted grapple configurations serve short-haul material transfer between deck and roadside processing sites.
Conventional trucks hold the largest share; momentum sits with forwarder trucks.
Load Capacity:
Cost tier stratification in load capacity segments aligns with insurance underwriting categories and regulatory axle-weight permitting thresholds.
- Heavy Duty:Tri-axle and quad-axle configurations rated for 80,000-120,000 pound gross vehicle weight dominate interstate-permitted timber corridors. Demand concentrates in US Southeast pine belt operations where mill-direct procurement contracts specify payload minimums. NHTSA brake system regulations and state permitting reciprocity agreements shape specification boundaries.
- Extra Heavy Duty:Specialized lowboy and multi-axle configurations exceed standard bridge formula limits through annual overweight permits or designated heavy-haul corridors. Canadian British Columbia interior operations deploy these units for long-distance transport from remote harvest blocks to coastal mills. The permit-dependent operating model requires dedicated compliance staff and route pre-approval workflows.
- Medium Duty:Single and tandem-axle units serve in-forest shuttle operations and small-scale private woodlot harvesting.
- Specialized Trucks:Custom frame modifications and suspension ratings address site-specific terrain constraints beyond standard classification boundaries.
Heavy duty configurations dominate fleet composition; extra heavy duty units are climbing the fastest on permit corridor expansion.
Application Type:
Volume concentration in application segments tracks timber ownership consolidation patterns and vertical integration depth across regional markets.
- Timber Harvesting:Primary transport from stump to mill or concentration yard defines core equipment utilization metrics and depreciation schedules. Demand concentrates in Finnish-Swedish timber corridors where mechanized harvesting exceeds 90% of annual cut volume. EU F-Gas Regulation compliance timelines accelerate fleet replacement cycles in this highest-utilization category.
- Forest Operations:Road construction, slash disposal, and stand establishment support activities require versatile chassis configurations with quick-attachment interfaces. Pacific Northwest integrated timberland owners maintain captive fleets for these functions to control road infrastructure timing. The seasonal demand pattern favors rental and lease structures over ownership.
- Material Transport:Chips, bark, and biomass movement from mill residuals to secondary processing or energy facilities.
- Land Clearing:Conversion harvesting and site preparation for non-forestry land use transitions.
Timber harvesting commands the largest equipment allocation; forest operations are gaining share fastest on infrastructure investment cycles.
Engine Type:
Customer type segmentation in engine categories separates integrated timber companies with captive maintenance infrastructure from independent contractors dependent on dealer service networks.
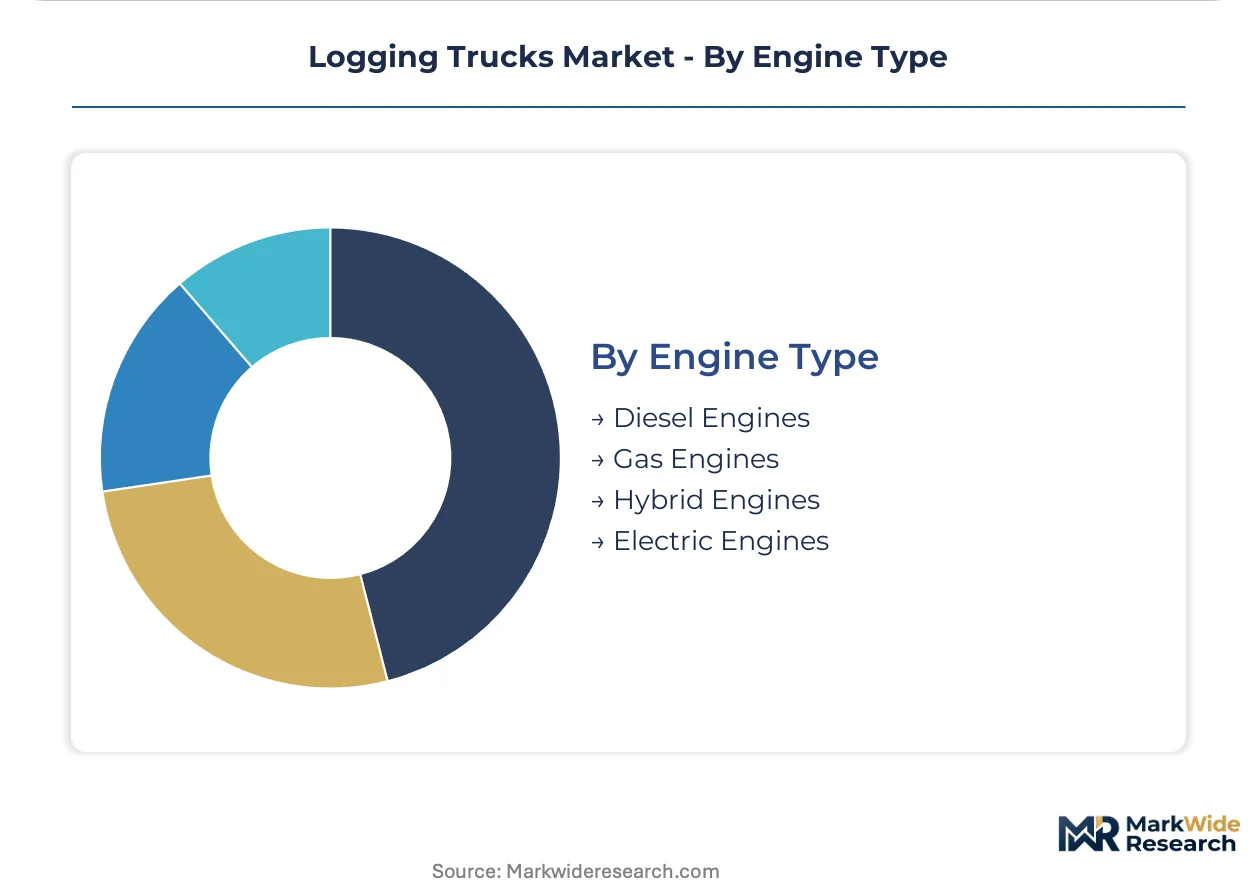
- Diesel Engines:EPA Tier 4 Final and Stage V compliant powertrains retain dominant position through refueling infrastructure ubiquity and technician training depth. Demand concentrates among independent logging contractors in North American markets where service network coverage determines equipment availability. Residual value forecasting models favor proven emission architecture over emerging alternatives.
- Hybrid Engines:Diesel-electric architectures capture regenerative braking energy on loaded descent cycles, reducing fuel consumption in mountainous terrain. Nordic forest road electrification infrastructure enables operational validation in Finnish and Swedish corridor operations. The capital cost premium requires integrated timber company balance sheet capacity or captive lease structures.
- Electric Engines:Battery-electric platforms concentrate in pilot deployments where charging infrastructure and route predictability align.
- Gas Engines:Compressed natural gas and liquefied natural gas alternatives serve niche applications with captive fueling infrastructure.
Diesel engines retain the largest installed base; hybrid engines show the steepest expansion trajectory on regulatory compliance timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated timber companies with captive maintenance infrastructure dominate procurement decisions across major forest economies. Fleet replacement cycles concentrate where EPA Tier 4 Final and EU Stage V compliance deadlines compress capital deployment timelines. Regulatory enforcement intensity varies sharply between jurisdictions with established electrification infrastructure and those dependent on legacy diesel service networks.
United States
Pacific Northwest timber harvesting fleets absorb hybrid powertrain capital costs to meet EPA Tier 4 Final mandates before compliance deadlines lock in. NHTSA greenhouse gas regulations for heavy-duty vehicles constrain engine retrofit economics across dispersed harvest sites. Washington and Oregon corridor operations anchor severe-service chassis demand where steep-terrain axle specifications determine insurance underwriting tiers.
Sweden
Nordic integrated forestry companies deploy battery-electric platforms along electrified forest road corridors where route predictability validates range claims. EU F-Gas Regulation accelerates fleet replacement cycles in mechanized harvesting operations exceeding 90% of annual cut volume. Västerbotten and Norrbotten timber districts concentrate zero-emission pilot deployments where charging infrastructure aligns with stump-to-mill haul patterns.
Canada
British Columbia interior operations deploy extra heavy-duty configurations under annual overweight permits for long-distance transport from remote harvest blocks to coastal mills. Provincial environmental regulations tighten diesel emission thresholds for forest road construction fleets. Vancouver Island and Interior Plateau logging contractors face compressed replacement cycles as federal carbon pricing affects fuel cost structures.
Finland
Finnish-Swedish timber corridors enable first-mover advantage for zero-emission platform deployment through advanced forest electrification infrastructure. EU Stage V non-road emission directives accelerate hybrid engine penetration in Baltic timber operations with shortest regulatory compliance timelines. Kainuu and North Karelia regions concentrate forwarder truck demand where selective-cutting premiums justify specialized hydraulic service contracts.
Germany
Baden-Württemberg and Bavarian forestry cooperatives balance diesel technician availability against EU Green Deal decarbonization timelines for commercial vehicle fleets. KBA type-approval requirements for modified logging configurations complicate cross-border fleet interoperability with Austrian and Czech operations. Black Forest and Alpine foothill terrain drives demand for reinforced frame specifications rated for extreme load distribution gradients.
Logging Trucks Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement hierarchies. The vendor base separates into integrated powertrain ecosystems, severe-service chassis engineers, and aluminum lightweighting specialists. Three archetypes dominate: highway-to-forest transition bundlers, selective-cutting hydraulic integrators, and payload-optimized cab fabricators. Competitive moves concentrate on service contract bundling and residual value guarantee structures rather than unit price competition.
Among North American severe-service specialists, Freightliner Trucks, Kenworth, and Peterbilt anchor distinct positioning vectors. Freightliner occupies the integrated powertrain ecosystem tier through captive engine-transmission alignment. Kenworth exemplifies the severe-service chassis engineering archetype with off-highway payload cycle optimization. Peterbilt represents lightweighting-focused differentiation where aluminum cab construction enables heavier payload certification without rollover protection compromise.
| Leading Market Players |
|---|
| Freightliner Trucks |
| DONGFENG Commercial Vehicle |
| Kenworth |
| Komatsu |
| Edison Motors |
| Peterbilt |
| Cecor Incorporated |
| Caterpillar |
| Mack Trucks |
| Others |
Value Network & Pricing Analysis
British Columbia's interior manufacturing cluster anchors frame and axle assembly capacity, concentrating supplier pricing power across Pacific Northwest procurement corridors. Mill-direct contract consolidation compresses negotiation leverage for independent logging contractors while amplifying volume-based tier advantages for integrated timber companies.
Pricing Analysis
Cost-plus contracts with steel indexation dominate heavy-duty chassis procurement, passing commodity volatility through to fleet operators on quarterly adjustments. Price differentiation rests on EPA Tier 4 Final certification tier and severe-service axle specification grade, with tri-axle configurations commanding premiums over highway-rated alternatives. Pricing pressure intensifies as hybrid powertrain capital costs absorb compliance-driven replacement cycles. Independent contractors exhibit highest price sensitivity due to dealer service dependency, while integrated timber companies leverage captive maintenance infrastructure for standard-tier negotiation.
Supply Chain Analysis
Supplier-financing facilities with 180-day extended terms have become standard for Detroit powertrain ecosystem partners, easing fleet operator capital deployment timing. Component concentration centers on Germany for precision axle assemblies, the United States for EPA-certified engine blocks, and Sweden for aluminum cab fabrications. Raw material dependencies span high-strength steel plate, hydraulic system components, and battery-grade lithium for hybrid architectures. Single-source vulnerability in semiconductor-dependent telematics modules poses structural risk. Distribution runs through OEM-authorized dealer networks with regional parts depot coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection is materializing through integrated Detroit powertrain ecosystems that bundle service contracts, residual value guarantees, and charging infrastructure access into unified procurement frameworks.
For Market Incumbents: Insulate service revenue streams by deepening captive technician certification programs for hybrid regenerative braking calibration, countering emerging electric drivetrain specialists. Anchor parts depot density in Pacific Northwest and Nordic corridor geographies where EPA Tier 4 Final and EU Stage V compliance deadlines compress replacement demand. Prioritize backward integration into aluminum cab fabrication to defend margin position against lightweighting specialists. For New Entrants and Emerging Players: Establish a beachhead in Finnish-Swedish timber corridors where forest road electrification infrastructure validates battery-electric range claims before geographic expansion. Target forwarder truck selective-cutting segments where ground disturbance premiums justify specialized hydraulic service contracts absent from incumbent programs. Pursue mill-direct procurement relationships with integrated timber companies over independent contractor dealer networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors severe-service chassis engineers with EPA Tier 4 Final validation completed and hybrid platform architecture deployed. Long-term viability concentrates on OEMs capturing aftermarket telematics revenue through sensor-embedded axle assemblies with predictive maintenance scheduling. Acquisition targets should demonstrate captive lease structures for hybrid capital cost absorption. Monitor regenerative braking recovery predictability under loaded mountain descent cycles as inflection indicator for total cost of ownership parity timing.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Powertrain Platform Deployment | EPA Tier 4 Final compliance locks in fleet replacement demand across Pacific Northwest corridors. |
| Telematics Integration Partnership | Sensor-embedded axle assemblies digitize warranty prevention for dispersed harvest site operators. |
| Forest Electrification Infrastructure Alliance | Nordic charging corridor expansion validates battery-electric range claims in steep terrain. |
| Aluminum Cab Fabrication Backward Integration | Tare weight reduction enables heavier payload certification without rollover protection compromise. |
| Captive Lease Structure Development | Hybrid capital cost absorption requires integrated timber company balance sheet capacity deployment. |
Research Methodology
Operator-level perspectives from fleet maintenance directors, OEM program managers, mill procurement officers, and forest road electrification infrastructure planners anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through EPA enforcement action databases, EU Stage V type-approval registries, and NHTSA heavy-duty vehicle greenhouse gas compliance filings. Customs data on high-strength steel plate imports, axle assembly trade flows, and battery-electric drivetrain component shipments supplemented demand-side triangulation. Bottom-up fleet replacement cycle analysis and top-down timber harvest volume projections converged on segment-level sizing.
Scenario-bracketing framed low, base, and high cases across the projection horizon without year-specific anchoring. The analytical framework modeled truck type, load capacity classification, application segment, and engine architecture dimensions alongside terrain severity gradients and mill contract structure typologies. CAGRs derived from replacement cycle compression rates tied to regulatory compliance deadlines, fleet age distribution analysis, and electrification infrastructure deployment timelines. Industry-specific inputs included regenerative braking recovery efficiency assumptions and forest road electrification corridor completion schedules.
Sensitivities concentrate around EPA enforcement intensity variations, EU F-Gas Regulation implementation pace, and battery-electric range validation under loaded descent cycles. Forecasts reflect documented assumptions on hybrid capital cost absorption rates and telematics adoption velocity. Macroeconomic softening in timber construction demand, regulatory timeline acceleration, or breakthrough solid-state battery commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
North America Heavy Commercial Vehicle (HCV) TMPS Market
Heavy-Duty Trucks
Global Vocational Truck Market
Heavy-Duty Trucks
Utility Trucks Market
Heavy-Duty Trucks
Heavy-Duty Truck Dashboard Switch Panel Systems Market
Heavy-Duty Trucks
Articulated Dump Trucks Market
Heavy-Duty Trucks
Global Boom Truck Market
Heavy-Duty Trucks
Hydrogen Trucks Market
Heavy-Duty Trucks
Fire Trucks Market
Heavy-Duty Trucks
US Vacuum Truck Market
Heavy-Duty Trucks
China Full Truckload Road Freight Transport Market
Heavy-Duty Trucks
Truck Tank Market
Heavy-Duty Trucks
Full Truckload Transportation Market
Heavy-Duty Trucks
Asia Pacific Garbage Truck Bodies Market
Heavy-Duty Trucks
China Full-Truck-Load (FTL) Market
Heavy-Duty Trucks
Medium and Heavy Duty Commercial Vehicles (MHCV) Market
Heavy-Duty Trucks
Truck Racks Market