
 Europe Light Commercial Vehicle Trailer Market | 2026-2036
Europe Light Commercial Vehicle Trailer Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Light Commercial Vehicle Trailer Market Foresight
Poland is rewriting production economics for European trailer manufacturing with expanding fabrication capacity serving western OEM supply chains. Eduards Trailer Factory leverages its Baltic operations to compete on cost-adjusted delivery times into Scandinavia and Germany. Pongratz Trailer-Group GmbH anchors its position through specialized aluminum construction techniques that reduce unladen weight. UNSINN Fahrzeugtechnik GmbH differentiates via modular payload configurations tailored to parcel delivery operators.
A light commercial vehicle trailer is a towed transport unit with gross vehicle weight rating below 3.5 tonnes, typically constructed from steel or aluminum framing with plywood, composite, or metal skin panels, designed to extend cargo capacity of vans and pickup trucks used in trade, logistics, and service applications. Box trailers lead product type demand due to weather protection requirements in e-commerce parcel distribution, while flatbed variants sustain growth in construction equipment rental channels. Aluminum material adoption accelerates where fuel cost sensitivity intersects with payload maximization needs, though steel dominates price-sensitive agricultural end users.
The EU Green Deal framework and CE marking requirements under the EU trailer type-approval regulation shape product design mandates across member states, with Germany's KBA enforcing brake performance and lighting standards that filter into broader continental compliance. ECHA REACH protocols govern chemical restrictions in surface coatings and adhesive bonding processes used in trailer assembly. Stakeholders must monitor impending Euro 7 emission standards for towing vehicles and their cascading effect on trailer aerodynamics and weight optimization requirements.
Market Dynamics
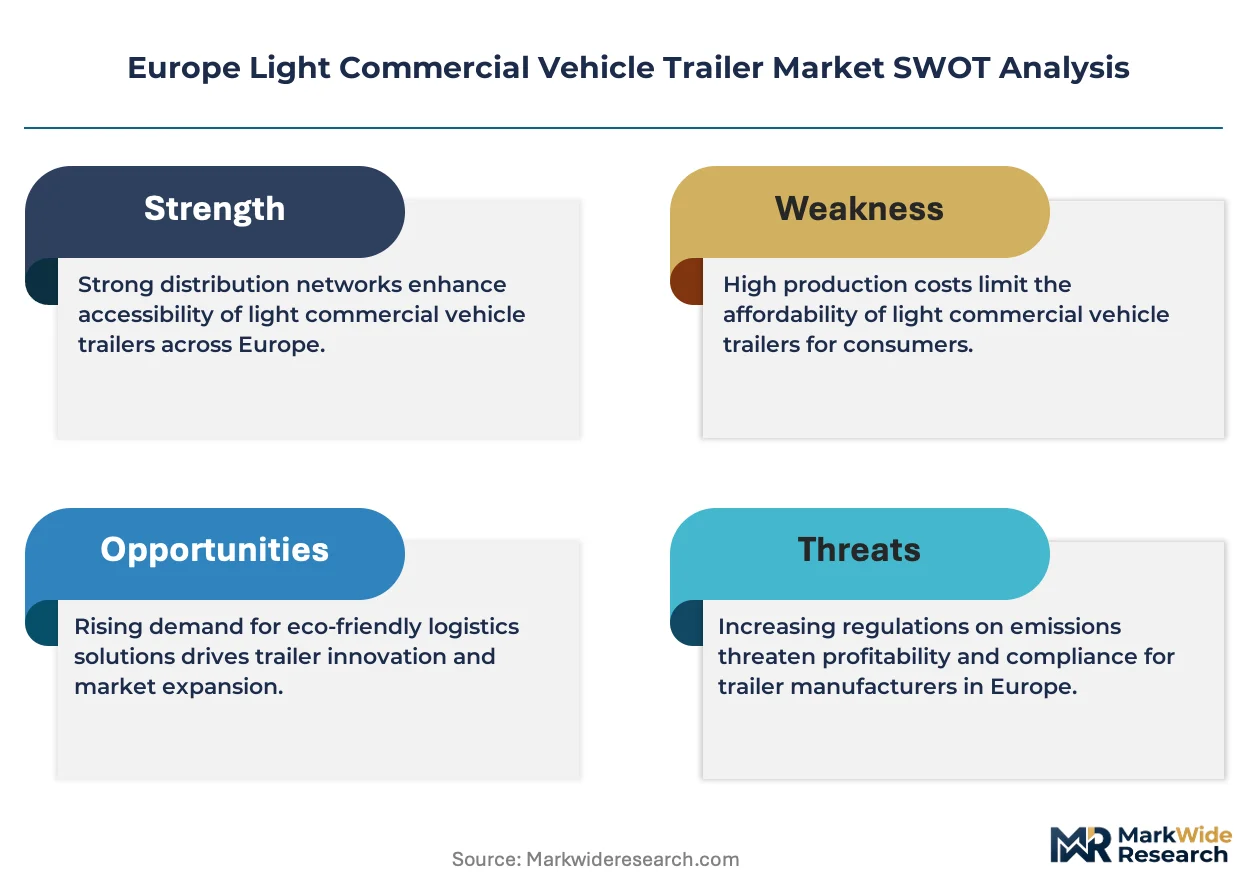
EU Green Deal compliance deadlines are compressing product development cycles across European trailer manufacturing, forcing simultaneous weight reduction and aerodynamic redesign investments before 2035 emission benchmarks take effect.
Growth Catalysts
- Last-mile logistics densification:E-commerce parcel operators across Germany and the Netherlands are expanding trailer fleets to optimize van payload economics in urban delivery zones.
- EU Green Deal framework:CO2 emission standards for light commercial vehicles mandate lighter trailer designs, accelerating aluminum adoption and aerodynamic profiling investments.
- SME fleet modernization:German logistics networks are driving replacement cycles as aging steel trailers face rising fuel cost penalties and maintenance burden.
Market Restraints
- Aluminum input cost volatility:Primary aluminum price swings tied to energy costs in European smelting operations compress margin buffers for mid-tier manufacturers.
- Eastern European supply concentration:Polish fabrication capacity expansion creates geographic dependency risk for western OEM supply chains facing logistics disruption.
- CE marking compliance friction:EU trailer type-approval regulation creates certification timeline bottlenecks that delay product launches by 6-12 months.
Strategic Opportunities
- Scandinavian cold-climate specialization:Insulated box trailer demand in Norway and Sweden remains underpenetrated relative to parcel logistics growth in Nordic e-commerce corridors.
- Modular payload configurations:Parcel delivery operators require rapid reconfiguration between bulk freight and small-package sorting, creating white space for flexible interior architecture.
- Battery-electric towing vehicle convergence:Range sensitivity in electric vans is rendering unladen weight optimization a critical procurement criterion, favoring advanced material suppliers.
Industry Challenges
- Aluminum welding certification scarcity:Qualified technicians for specialized aluminum construction techniques command premium wages and extended recruitment timelines.
- REACH chemical compliance:ECHA protocols governing surface coatings and adhesive bonding require reformulation investments that strain R&D budgets.
- Legacy fleet integration complexity:New lightweight trailers must maintain coupling compatibility with existing van hitch specifications across heterogeneous SME fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Light Commercial Vehicle Trailer Market |
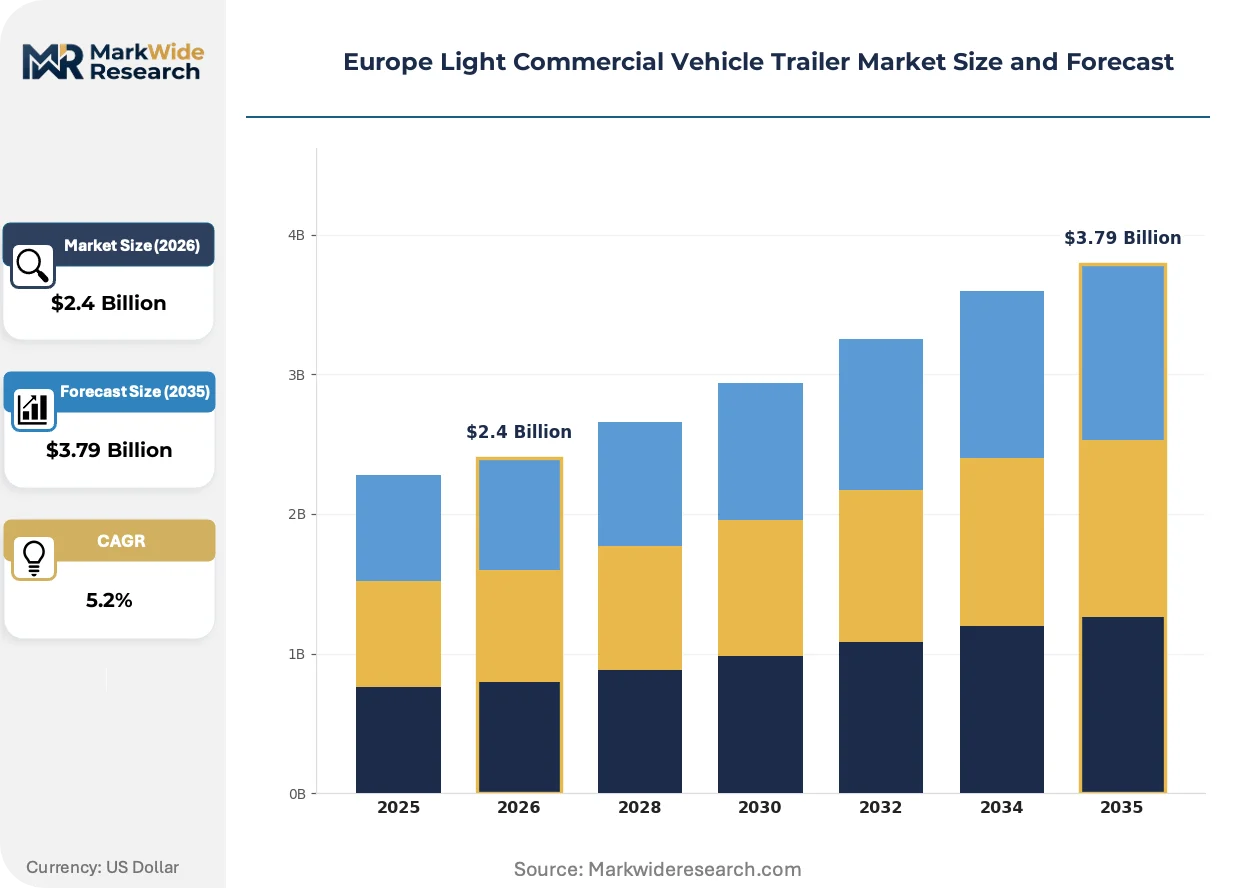
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.79 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flatbed Trailers, Box Trailers, Car Transport Trailers, Dump Trailers Load Capacity: Lightweight, Medium Capacity, Heavy Duty, Ultra-Heavy Duty Material: Aluminum, Steel, Composite, Fiberglass End User: Logistics Companies, Construction Firms, Retail, Agriculture |
| Companies Covered | Eduards Trailer Factory, Pongratz Trailer-Group GmbH, UNSINN Fahrzeugtechnik GmbH, Gaupen, Debon Trailers, wm meyer Fahrzeugbau AG, Trigano Remorques, Vezeko, Ifor Williams Trailers, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Light Commercial Vehicle Trailer Market Shifts & Advancements
Digital load monitoring and predictive maintenance systems are penetrating trailer specification sheets as fleet operators demand asset utilization transparency. Material science advances and regulatory pressure are converging to redefine competitive differentiation.
Composite sandwich panel construction is rendering obsolete traditional plywood flooring in box trailers. Scandinavian rental fleets are specifying glass-reinforced plastic core panels for moisture resistance and payload density. This technology is rendering obsolete the 15-year replacement cycles typical of conventional wood-based construction, compressing fleet turnover to 8-10 year intervals.
REACH chemical restriction protocols are forcing coating system reformulations across European assembly plants. ECHA enforcement of SVHC substance bans in anti-corrosion treatments is redirecting procurement toward water-based and powder-coat alternatives. Agricultural end-use segments in Poland and Romania face the steepest compliance cost absorption due to price-sensitive purchasing patterns.
Leasing penetration is accelerating among German SME logistics operators seeking to offload residual value risk. Traditional equipment finance is yielding to full-service operating leases bundling maintenance and telematics. This shift concentrates procurement authority with national rental fleet managers rather than dispersed owner-operators, compressing vendor negotiation cycles and favoring scale manufacturers.
Europe Light Commercial Vehicle Trailer Market Segmentation
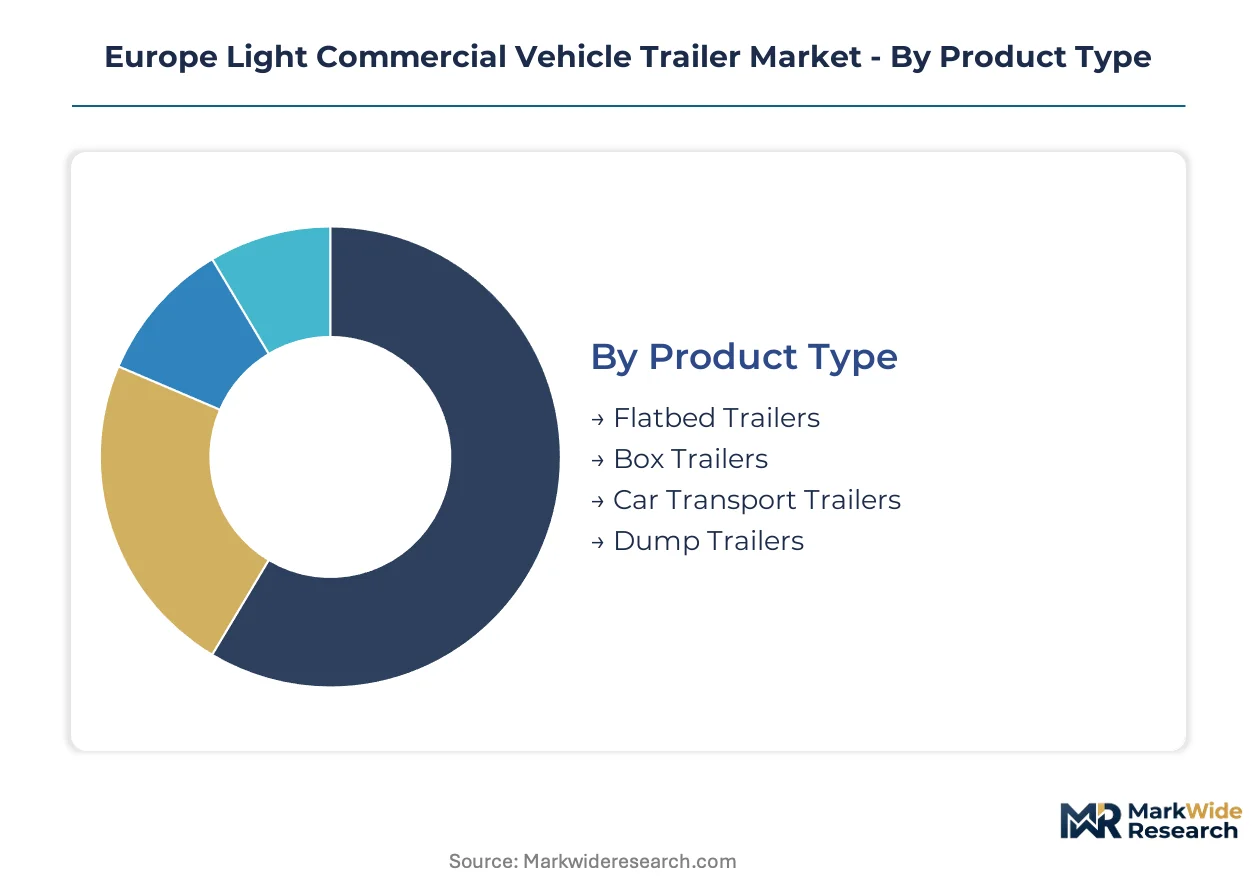
Segmentation in the Europe Light Commercial Vehicle Trailer Market reveals how regulatory pressure and operational economics fragment procurement behavior. Material choices and product configurations diverge sharply between fuel-conscious logistics operators and price-driven agricultural buyers.
Product Type:
Mature configurations dominate established corridors while specialized formats capture emerging application niches.
- Box Trailers:Enclosed cargo compartments with plywood or composite paneling protect weather-sensitive freight. Parcel distribution networks across Germany and the Netherlands specify these for e-commerce last-mile operations where cargo security intersects with aerodynamic efficiency mandates.
- Flatbed Trailers:Open-deck platforms with steel or aluminum framing accommodate irregular loads and rapid loading cycles. Construction equipment rental channels in Poland and Romania sustain demand where payload flexibility outweighs weather protection requirements.
- Car Transport Trailers:Multi-vehicle carriers with hydraulic or fixed-angle loading ramps serve automotive logistics and dealer transfer operations.
- Dump Trailers:Hydraulic lift mechanisms enable bulk material discharge for landscaping and small-scale construction contractors.
Box trailers handle the majority of throughput; flatbed variants are gaining share fastest in equipment rental channels.
Load Capacity:
Procurement patterns stratify sharply between urban delivery constraints and rural payload maximization needs.
- Lightweight:Sub-750 kg unladen designs prioritize towing vehicle compatibility and fuel economy. Battery-electric van operators in Scandinavian cities specify these to preserve range per charge as towing capacity erodes with battery weight.
- Medium Capacity:750-1500 kg gross configurations balance structural durability with maneuverability. German SME logistics networks favor these for mixed freight operations where route flexibility matters.
- Heavy Duty:Reinforced chassis designs approaching the 3.5 tonne regulatory threshold serve construction material transport.
- Ultra-Heavy Duty:Specialized frames at the regulatory limit address agricultural machinery and dense freight consolidation.
Medium capacity units anchor fleet procurement volumes; lightweight specifications are expanding most quickly in electric vehicle towing applications.
Material:
Cost tier positioning separates premium aluminum offerings from commodity steel alternatives across customer segments.
- Aluminum:Extruded and welded alloy construction reduces unladen weight. Fuel-sensitive logistics operators in Germany and the Netherlands absorb premium pricing to maximize payload density and comply with EU Green Deal trajectory requirements.
- Steel:Conventional mild and high-strength steel framing dominates price-sensitive agricultural and construction segments. Polish and Romanian buyers prioritize acquisition cost over lifecycle fuel savings.
- Composite:Glass-reinforced plastic sandwich panels replace plywood in moisture-critical applications.
- Fiberglass:Molded skin panels serve specialized weatherproofing and corrosion resistance requirements.
Steel retains volume leadership in unit terms; aluminum is climbing the fastest on value share as fleet operators electrify.
End User:
Customer type determines specification complexity and procurement channel preferences across the continent.
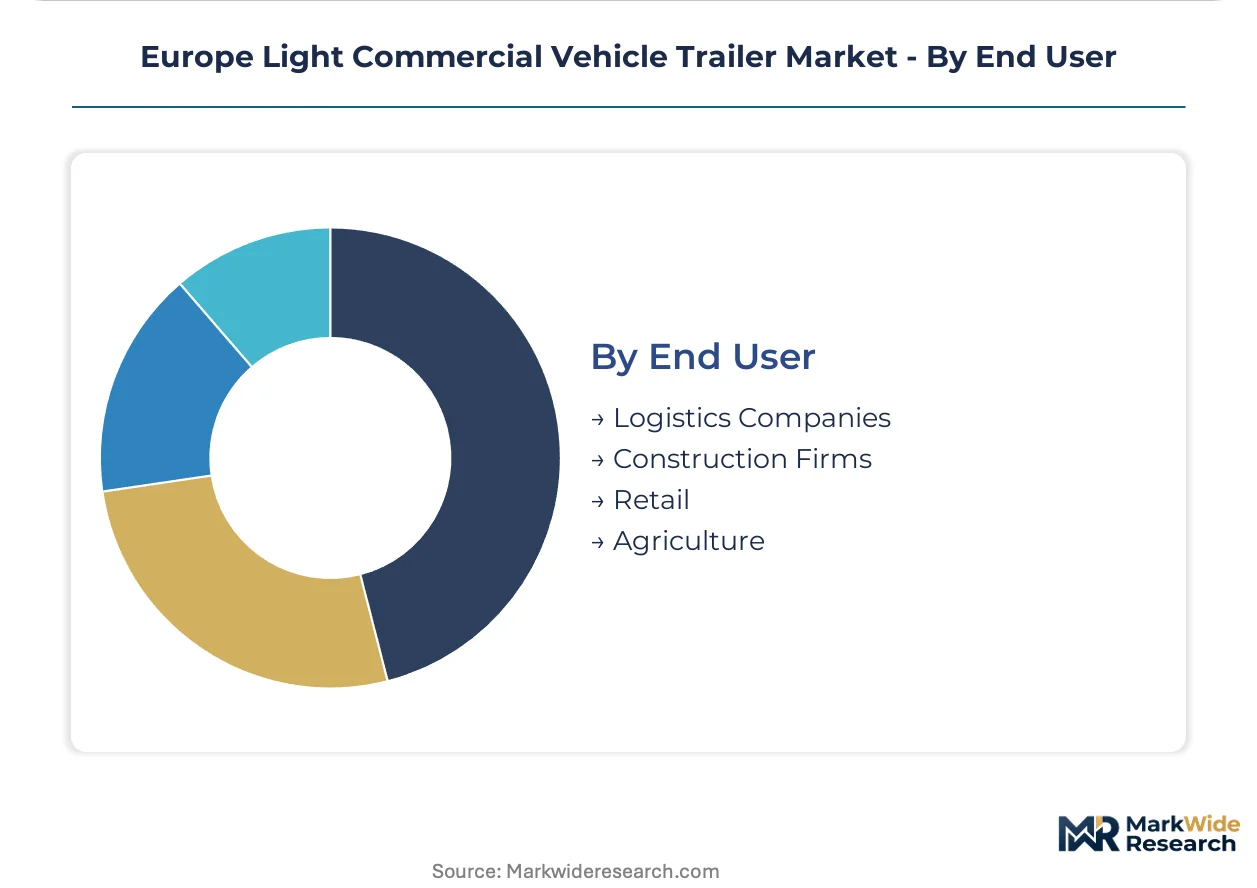
- Logistics Companies:Parcel and freight operators demand telematics-ready trailers with modular interior architecture. Last-mile densification in Dutch and German urban corridors drives replacement cycles toward lighter, connected assets.
- Construction Firms:Equipment rental and material transport users prioritize durability and coupling compatibility with mixed vehicle fleets. Polish rental yards specify flatbed variants for cross-border equipment positioning.
- Retail:Distribution center operators and franchise networks require standardized configurations for supplier compliance.
- Agriculture:Smallholders and cooperatives in Eastern Europe favor basic steel construction with minimal electronic content.
Logistics companies concentrate procurement authority; construction rental channels show the steepest expansion trajectory in fleet size.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Kraftfahrt-Bundesamt anchors type-approval enforcement across Europe, filtering brake performance and lighting standards into broader continental compliance frameworks for light commercial vehicle trailers.
Germany
Dense SME logistics networks in North Rhine-Westphalia and Bavaria drive replacement cycles as aging steel trailers face fuel cost penalties. The KBA enforces stringent brake performance standards that manufacturers must satisfy before CE marking authorization. Manufacturing clusters around Munich and Stuttgart concentrate aluminum fabrication capacity serving domestic parcel operators.
Poland
Expanding fabrication capacity in Lower Silesia and Greater Poland serves western OEM supply chains with cost-adjusted delivery advantages. Polish operations compete on proximity-to-market positioning for Scandinavian and German customers. The country's industrial zones attract trailer component suppliers seeking labor cost arbitrage within EU regulatory boundaries.
Netherlands
E-commerce parcel densification in the Randstad corridor accelerates fleet modernization toward lightweight, aerodynamic configurations. Dutch urban delivery zones impose strict vehicle dimension constraints that favor sub-750 kg unladen trailer specifications. Rotterdam's logistics hub anchors cross-border equipment positioning into Belgian and German distribution networks.
Sweden
Cold-climate specialization creates demand for insulated box trailers in Nordic e-commerce corridors where moisture resistance trumps acquisition cost sensitivity. Swedish fleet operators prioritize composite sandwich panel construction to combat plywood degradation in freeze-thaw cycles. Manufacturing activity concentrates in southern industrial zones serving Oslo and Copenhagen metropolitan areas.
France
Construction equipment rental channels in Île-de-France and Auvergne-Rhône-Alpes sustain flatbed trailer demand where payload flexibility outweighs weather protection requirements. French regulators align with EU Green Deal trajectory requirements while maintaining distinct national roadworthiness inspection protocols. Lyon-based fabricators serve cross-border equipment rental positioning into Switzerland and Italy.
Europe Light Commercial Vehicle Trailer Market Competitive Landscape
Specialized aluminum fabricators and diversified multi-product manufacturers split the market along material-technology lines. The vendor base concentrates in German engineering clusters and Polish cost-optimized zones, creating geographic tiering around regulatory proximity and labor arbitrage. Three archetypes dominate: aluminum-weight-optimization specialists, steel-volume producers serving price-sensitive agricultural segments, and modular-configuration engineers targeting parcel logistics. Capacity expansion in Polish fabrication zones and strategic partnerships between western OEMs and eastern suppliers represent the dominant competitive moves reshaping procurement geography.
Within the aluminum-specialist tier, Pongratz Trailer-Group GmbH exemplifies weight-reduction engineering capabilities, while UNSINN Fahrzeugtechnik GmbH occupies a position defined by modular payload architecture. Eduards Trailer Factory represents Baltic-based cost positioning serving Scandinavian and German supply chains with compressed delivery timelines. These three GmbH and Factory-structured entities anchor distinct strategic positions without overlapping archetype claims.
| Leading Market Players |
|---|
| Eduards Trailer Factory |
| Pongratz Trailer-Group GmbH |
| UNSINN Fahrzeugtechnik GmbH |
| Gaupen |
| Debon Trailers |
| wm meyer Fahrzeugbau AG |
| Trigano Remorques |
| Vezeko |
| Ifor Williams Trailers |
| Others |
Supply & Pricing Matrix
Lower Silesia's expanding fabrication capacity is compressing delivery timelines into German logistics corridors, granting Polish suppliers pricing leverage over western OEMs while aluminum input cost volatility erodes margin buffers for mid-tier manufacturers dependent on energy-intensive European smelting operations.
Pricing Analysis
Geographic price spreads between Polish steel-framed units and German aluminum designs reflect material-grade stratification rather than pure logistics arbitrage. Three-tier pricing structure across premium, standard, and economy levels segments procurement: aluminum specialists command fuel-economy premiums from Dutch parcel operators, while Romanian agricultural buyers absorb steel's commodity positioning. Cost compression in the mid-tier is intensifying because REACH compliance investments are redirecting coating procurement toward water-based alternatives. Agricultural end-users in Poland and Romania exhibit the highest price sensitivity, whereas Scandinavian cold-climate operators prioritize moisture-resistant composite specifications over acquisition cost.
Supply Chain Analysis
Contract manufacturing concentrates in Eduards Trailer Factory's Baltic operations and Pongratz Trailer-Group GmbH's specialized aluminum facilities, with Polish foundries anchoring volume production for western OEM supply chains. Geographic supply concentration spans Poland, Germany, and Sweden, with raw material dependencies drawing from European aluminum smelters, Scandinavian timber and composite panel suppliers, and German steel mills. Single-source vulnerability around qualified aluminum welding technicians creates recruitment bottlenecks that strain capacity expansion timelines. Distribution runs through national rental fleet managers consolidating SME procurement authority, compressing vendor negotiation cycles toward scale manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Light Commercial Vehicle Trailer Market operates as a defensive-moat arena where KBA brake performance standards and CE marking type-approval requirements create regulatory entrenchment that protects incumbent positions against unqualified challengers.
For Market Incumbents: Entrench position by deepening backward integration into aluminum extrusion capabilities to offset smelter energy cost volatility, while accelerating certification investments ahead of Euro 7 emission standard cascades that will tighten aerodynamic and weight optimization mandates. Channel control through exclusive leasing partnerships with German SME logistics networks protects against rental fleet manager consolidation. For New Entrants and Emerging Players: Insulated box trailer demand in Norwegian and Swedish e-commerce corridors represents the most penetrable entry point, as moisture-resistant composite construction requirements favor specialized engineering over scale manufacturing. Modular payload configurations for parcel delivery operators offer a second white-space target where rapid interior reconfiguration between bulk freight and small-package sorting commands specification premiums. A go-to-market angle anchored in battery-electric van range optimization addresses unmet procurement criteria among Scandinavian urban fleets. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial parent companies with underoptimized trailer divisions lacking aluminum fabrication expertise or telematics integration capabilities. Long-term viability across the analysis window hinges on material science positioning and regulatory compliance infrastructure rather than pure manufacturing scale. Aluminum welding certification scarcity and REACH coating reformulation capabilities signal acquisition value; monitor Polish capacity utilization rates and KBA type-approval queue lengths as inflection indicators for competitive intensity shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Aluminum Fabrication Capacity Expansion | Polish cluster investments compress delivery timelines into German logistics corridors while capturing EU Green Deal compliance premiums. |
| REACH-Compliant Coating System Reformulation | ECHA SVHC enforcement redirects procurement toward water-based alternatives, eliminating agricultural-tier competitors from premium segments. |
| Modular Interior Architecture Development | Parcel delivery operators in Randstad and North Rhine-Westphalia specify rapid reconfiguration capabilities for mixed freight operations. |
| Telematics-Ready Trailer Specification | German SME logistics networks demand asset utilization transparency, concentrating procurement authority with connected fleet suppliers. |
| Scandinavian Cold-Climate Specialization | Insulated composite construction for Nordic e-commerce corridors commands moisture-resistance premiums over commodity steel alternatives. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with trailer manufacturing executives, fleet procurement managers at German logistics SMEs, aluminum welding technicians, and ECHA compliance officers; and secondary validation drawing from KBA type-approval databases, EU trailer registration statistics, European aluminum smelter energy cost disclosures, and REACH SVHC substance restriction updates. Bottom-up unit shipment modeling by product type, material, and end-user segment was triangulated against top-down market value estimates derived from manufacturer revenue disclosures and rental fleet capitalization patterns.
Forecast inputs considered EU Green Deal emission benchmark trajectories, battery-electric van adoption curves across the projection horizon, and segmentation dimensions spanning product configuration, load capacity tier, material technology, and end-user procurement channel. CAGRs were derived from elasticity-adjusted demand modeling that weighted fuel cost sensitivity against acquisition price trade-offs, with aluminum input cost volatility and CE marking approval timelines incorporated as scenario variables.
Stress conditions across aluminum price bands, REACH enforcement intensity, and Polish logistics disruption probability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions around KBA regulatory stability and SME fleet modernization cyclicality. Quarterly review of KBA type-approval queue lengths, European smelter energy cost indices, and rental fleet telematics penetration rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Compact Utility Vehicles Market
Commercial Vehicles
Truck-Mounted Road Sweeper Market
Commercial Vehicles
Philippines Commercial Vehicles Market
Commercial Vehicles
Japan Commercial Vehicles Market
Commercial Vehicles
Heavy-Duty Trucks Market
Commercial Vehicles
Semi-Tractor Trailer Market
Commercial Vehicles
Global Timber Trailer Market
Commercial Vehicles
Global Commercial Vehicle Fuel Tank Market
Commercial Vehicles
Commercial Vehicle (CV) Active Power Steering Market
Commercial Vehicles
Peru Commercial Vehicle Market
Commercial Vehicles
Industrial Vehicles Market
Commercial Vehicles
Global Commercial Vehicles Market
Commercial Vehicles
Tank Car Market
Commercial Vehicles
Southeast Asia Box Truck Market
Commercial Vehicles
Commercial Truck Use APU Market
Commercial Vehicles
Commercial Vehicle Driveline Support Bearings Market