
 US Vacuum Truck Market | 2026-2036
US Vacuum Truck Market Size, Share, and Industry Trends Forecast 2026-2036
US Vacuum Truck Market Insights
EPA enforcement of Clean Water Act discharge rules is consolidating demand around higher-capacity vacuum extraction systems. Vactor Manufacturing leverages its chassis integration expertise to dominate municipal sewer cleaning contracts. Federal Signal Corporation anchors its position through specialized product lines for hazardous material response. GapVax Inc. competes aggressively in the mid-market combination unit segment.
Vacuum trucks are heavy-duty commercial vehicles equipped with high-powered suction systems, typically generating airflow from 3,000 to 5,500 cubic feet per minute and mounted on dedicated chassis with debris tanks ranging from 3 to 15 cubic yards capacity. These systems serve primary industrial purposes including liquid waste removal, hydro-excavation, and environmental remediation where mechanical digging poses contamination risks. Liquid waste vehicle types lead unit shipments due to persistent municipal sewer infrastructure maintenance cycles, while combination units represent the fastest-growing configuration as operators seek fleet flexibility across oilfield and construction applications. Industrial cleaning applications command premium pricing through specialized corrosion-resistant tank specifications and explosion-proof electrical systems.
EPA, OSHA, and DOT regulations collectively shape vacuum truck specifications through emissions standards, worker exposure limits, and hazardous materials transport requirements. OSHA confined space entry rules mandate particular blower configurations and filtration systems for municipal sewer operations. Fleet operators must monitor evolving EPA Phase 2 greenhouse gas standards for heavy-duty vehicles and assess electric power source viability against current diesel-dominant payload economics.
Market Dynamics
EPA Phase 2 greenhouse gas standards for heavy-duty vehicles are forcing fleet operators to reassess diesel-dominant payload economics against emerging electric powertrain configurations, reshaping capital allocation across municipal and oilfield procurement cycles.
Growth Catalysts
- Municipal sewer infrastructure cycles:Persistent maintenance obligations across aging underground networks drive recurring fleet replacement schedules. Cities prioritize combination units for operational flexibility.
- OSHA confined space entry mandates:Worker exposure limits for hazardous atmospheres require upgraded blower configurations and HEPA filtration systems on sewer cleaning vehicles.
- Hydro-excavation substitution:Mechanical digging restrictions near buried utilities accelerate demand for non-destructive vacuum extraction methods in construction corridors.
Market Restraints
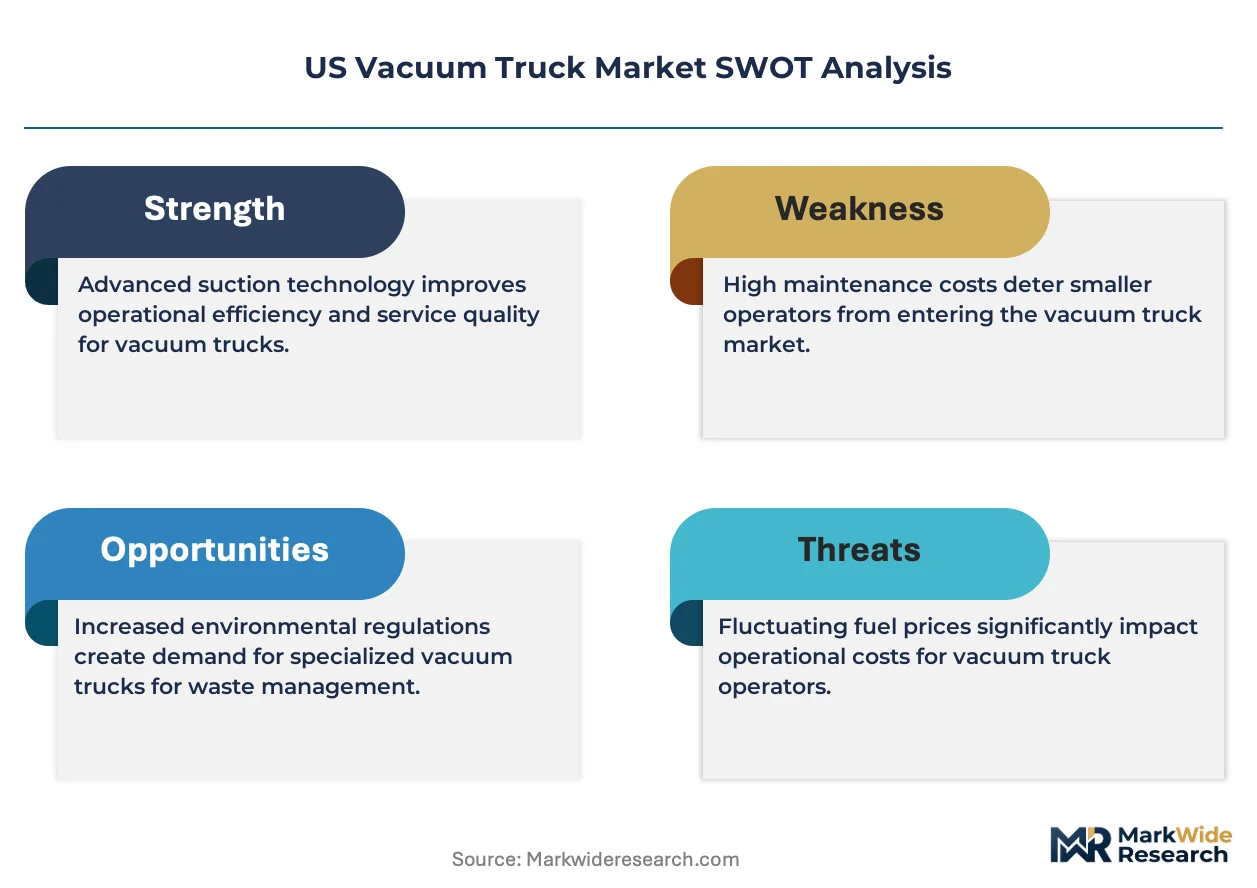
- Steel and aluminum input volatility:Debris tank fabrication costs fluctuate with commodity pricing, compressing margin visibility for chassis-integrated manufacturers.
- Specialized technician scarcity:Vacuum system diagnostics and hydrostatic pump repair require certified mechanics that remain concentrated in Gulf Coast service hubs.
- DOT hazardous materials transport friction:Driver endorsement requirements and route restrictions add operational overhead to liquid waste logistics.
Strategic Opportunities
- Appalachian shale basin expansion:Pennsylvania and Ohio drilling activity creates underpenetrated demand for mobile vacuum extraction in midstream pipeline construction.
- EPA wastewater discharge tightening:Stricter effluent standards position high-capacity vacuum trucks as essential compliance infrastructure for industrial pretreatment programs.
- Telematics and fleet optimization convergence:Real-time tank level monitoring and route algorithms reduce idle time for municipal operators managing distributed sewer networks.
Industry Challenges
- Electric powertrain integration complexity:Battery weight penalties reduce payload capacity, forcing trade-offs between range and debris tank volume that diesel platforms avoid.
- Corrosion-resistant tank certification timelines:Specialized coatings for chemical waste applications require extended testing protocols that delay new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Vacuum Truck Market |
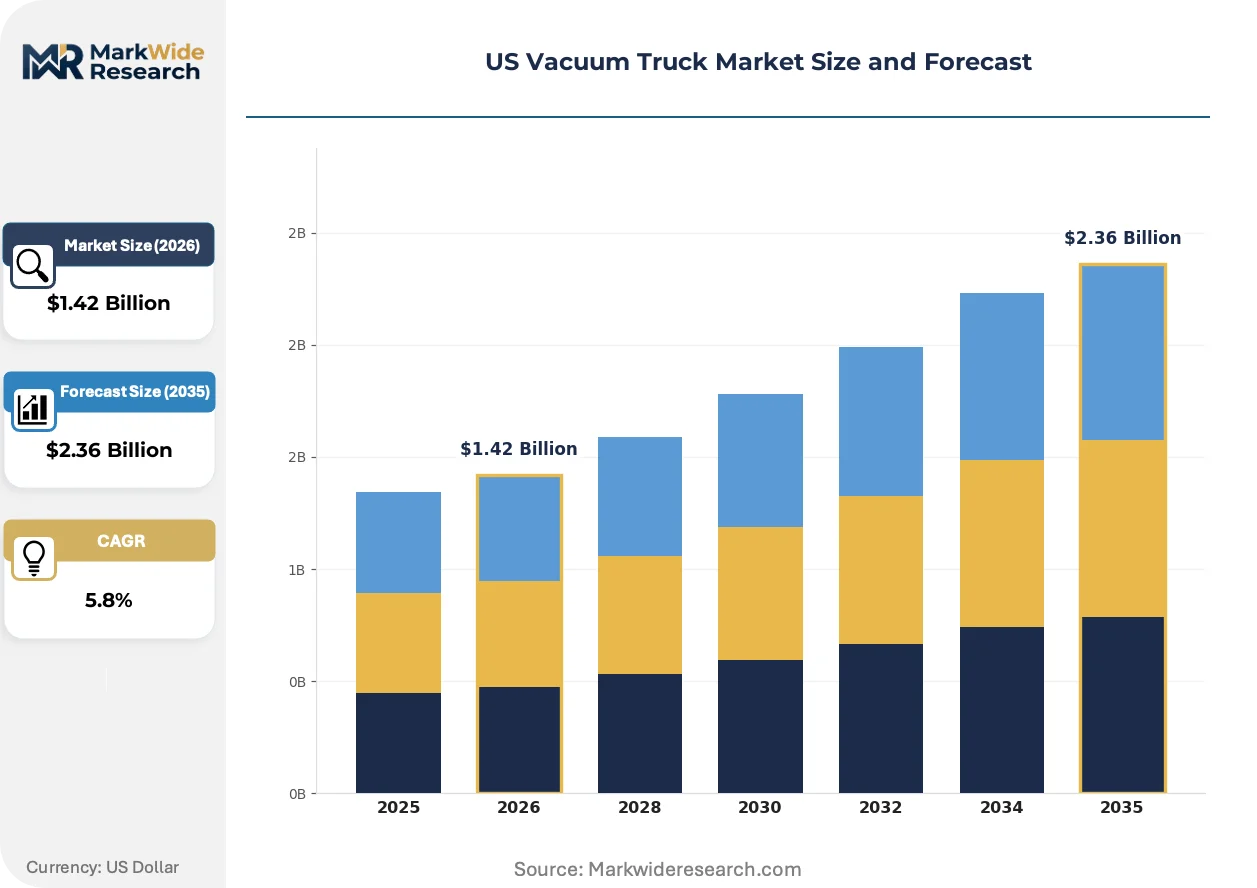
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Industrial Cleaning, Oil & Gas Services, Sewage Management, Construction Debris Vehicle Type: Liquid Waste, Dry Waste, Combination Units, Special Purpose End User: Municipalities, Environmental Services, Construction Companies, Industrial Facilities Power Source: Diesel Engine, Electric Motor, Hybrid Systems, Gasoline Engine |
| Companies Covered | Vactor Manufacturing Inc., Super Products LLC, Federal Signal Corporation, Sewer Equipment Co. of America, GapVax Inc., Vac-Con Inc., Hi-Vac Corporation, Vacall Industries, Keith Huber Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Vacuum Truck Market Trends and Innovations
Equipment specifications are pivoting toward modular architectures that accommodate rapid reconfiguration between liquid waste and dry material handling, driven by fleet operators seeking asset utilization across seasonal demand cycles.
Telematics-enabled predictive maintenance is absorbing diagnostic functions previously performed at service depots. Municipal fleet managers in Texas and Louisiana deploy remote monitoring to schedule blower rebuilds before field failures occur. This capability is absorbing traditional aftermarket service revenue into software subscription models.
EPA enforcement of Clean Water Act discharge rules is tightening extraction efficiency requirements for industrial pretreatment programs. Facilities in the Permian Basin must demonstrate capture rates that favor higher-capacity vacuum systems over legacy equipment. Manufacturers respond with sealed tank designs that reduce vapor escape during material transfer.
Service contracting patterns are consolidating around multi-year fleet management agreements. Large municipal utilities in the Northeast and Great Lakes regions bundle vehicle procurement with operator training and maintenance outsourcing. Equipment suppliers respond with dedicated account teams that embed specifications directly into municipal capital improvement plans.
US Vacuum Truck Market Segmentation
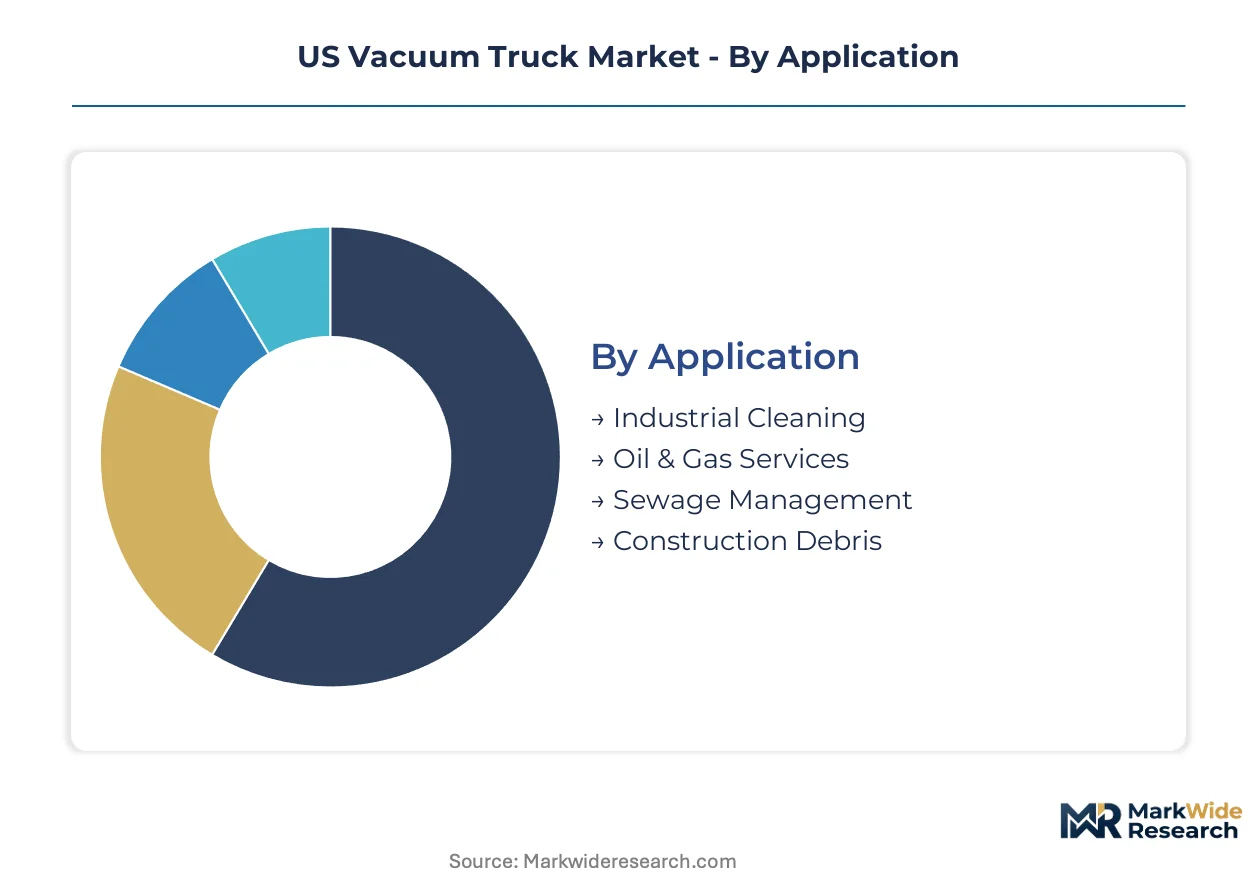
Vacuum truck procurement patterns diverge sharply between high-volume municipal replacement cycles and premium-priced specialized configurations. Fleet managers weigh payload capacity against regulatory compliance when matching vehicle specifications to operational requirements.
Application:
Volume leadership sits with routine infrastructure maintenance, while premium pricing concentrates in hazardous material handling where OSHA exposure limits apply.
- Industrial Cleaning:Corrosion-resistant tank specifications and explosion-proof electrical systems define equipment configurations. Chemical plants along the Texas Gulf Coast drive demand for specialized blower systems that handle volatile organic compound recovery.
- Oil & Gas Services:Hydro-excavation dominates Permian Basin drilling support as mechanical digging restrictions expand around buried pipelines. Fleet operators favor combination units that switch between liquid extraction and dry material handling across completion and workover cycles.
- Sewage Management:Municipal sewer maintenance programs anchor replacement demand through predictable capital budgeting cycles.
- Construction Debris:Non-residential building activity generates intermittent demand for high-capacity debris removal.
Mature deployment sits with Sewage Management. Newer deployment is concentrated in Oil & Gas Services.
Vehicle Type:
Cost tier separation runs from standardized liquid waste platforms to engineered special-purpose builds with extended lead times.
- Liquid Waste:Dedicated chassis with sealed tank designs dominate municipal procurement. EPA wastewater discharge standards in Louisiana and Texas favor these units for industrial pretreatment compliance.
- Combination Units:Modular architectures accommodate rapid reconfiguration between wet and dry handling. Appalachian shale basin operators in Pennsylvania and Ohio deploy these for seasonal flexibility across drilling and pipeline construction cycles.
- Dry Waste:Cyclone filtration systems handle construction debris and industrial powder recovery.
- Special Purpose:Custom-engineered configurations address nuclear decommissioning and asbestos abatement.
Volume concentration rests with Liquid Waste. Margin expansion is climbing the fastest in Combination Units.
End User:
Customer procurement sophistication separates centralized municipal fleet managers from fragmented construction subcontractor purchasing.
- Municipalities:Multi-year fleet management agreements bundle vehicle procurement with operator training. Northeast utilities embed specifications directly into capital improvement plans with dedicated supplier account teams.
- Environmental Services:Hazardous waste contractors face DOT endorsement requirements and route restrictions that add operational overhead. These specialists command premium pricing for emergency response capabilities.
- Construction Companies:Project-based purchasing cycles create demand volatility tied to federal infrastructure spending.
- Industrial Facilities:Captive maintenance fleets prioritize uptime availability over capital cost minimization.
Procurement standardization is highest with Municipalities. Contracting flexibility is expanding most quickly with Environmental Services.
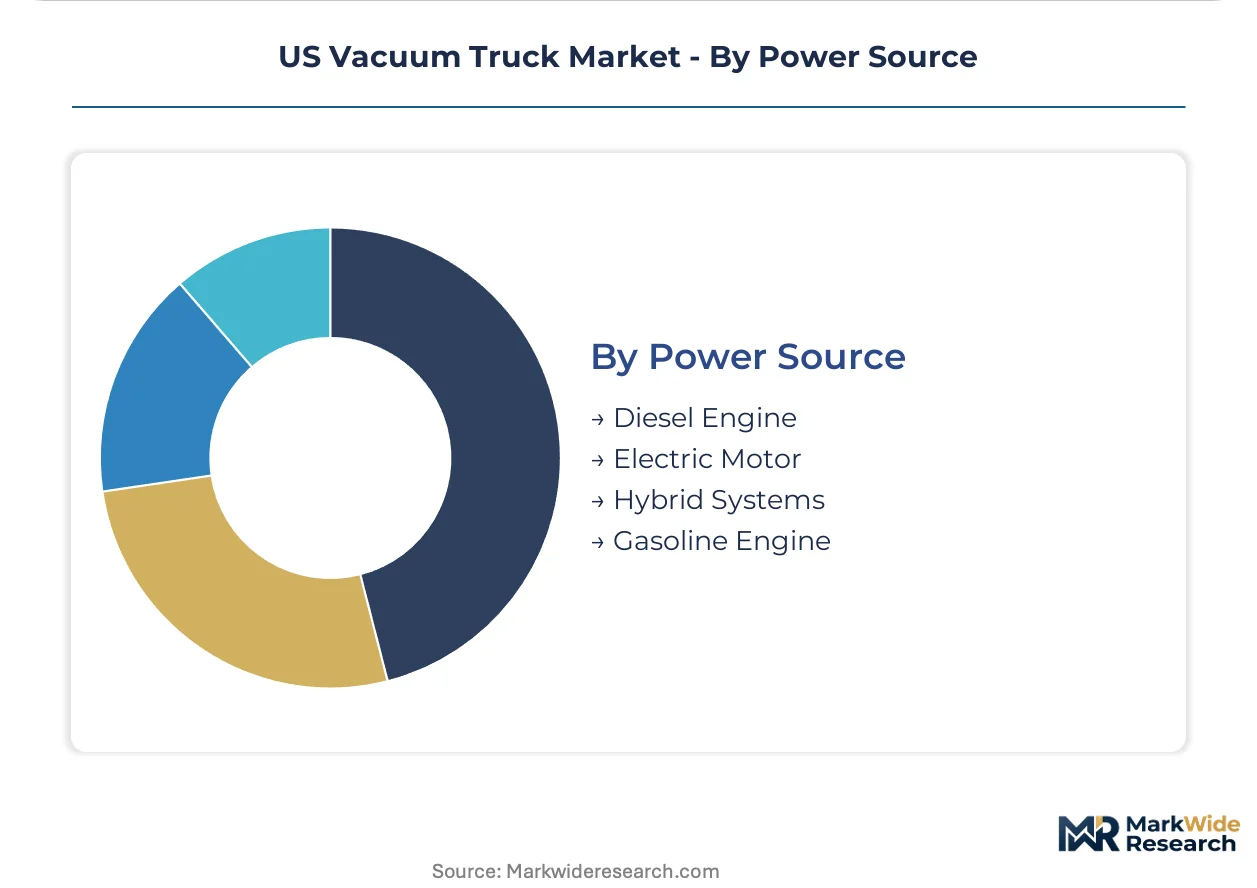
Power Source:
Technology maturity separates diesel-dominant payload economics from emerging electric configurations with battery weight penalties.
- Diesel Engine:Established service networks and refueling infrastructure support heavy-duty applications. EPA Phase 2 greenhouse gas standards are forcing reassessment of long-term fleet economics despite current payload advantages.
- Electric Motor:Zero-emission mandates in California and New York municipal contracts drive pilot deployments. Battery weight reduces debris tank capacity, creating trade-offs between range and operational utility.
- Hybrid Systems:Dual-power architectures address range anxiety while enabling zero-emission zone compliance.
- Gasoline Engine:Light-duty applications in suburban landscaping and pool maintenance segments.
Installed base concentration remains with Diesel Engine. Regulatory pressure is accelerating fastest around Electric Motor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin spanning West Texas and southeastern New Mexico anchors North American vacuum truck deployment. EPA enforcement of Clean Water Act discharge rules concentrates procurement around higher-capacity extraction systems in this corridor.
Texas Gulf Coast
Refinery maintenance cycles and chemical plant turnarounds drive recurring demand for corrosion-resistant tank specifications. OSHA confined space entry mandates require upgraded blower configurations for Houston-area industrial cleaning contractors. Port Arthur and Baytown host dense clusters of environmental service providers managing volatile organic compound recovery operations.
Louisiana Industrial Corridor
Midstream pipeline construction and offshore platform decommissioning sustain hydro-excavation demand along the Mississippi River corridor. EPA wastewater discharge standards for industrial pretreatment programs favor sealed tank designs in Baton Rouge and Lake Charles. Specialized fleet operators concentrate in Lafayette serving oilfield service logistics.
Appalachian Basin
Pennsylvania and Ohio shale drilling activity generates underpenetrated demand for mobile vacuum extraction in midstream pipeline construction. Combination units provide seasonal flexibility across drilling and completion cycles in Pittsburgh and Youngstown metropolitan areas. Municipal utilities in the region are adopting telematics-enabled fleet optimization for distributed sewer network management.
California Central Valley
Agricultural wastewater management and food processing effluent handling sustain liquid waste vehicle procurement in Fresno and Bakersfield. Zero-emission mandates in municipal contracts are driving pilot deployments of electric powertrain configurations despite battery weight penalties. The state's Air Resources Board regulations are accelerating reassessment of diesel-dominant payload economics.
Northeast Corridor
Aging sewer infrastructure in Boston, New York, and Philadelphia metropolitan areas drives predictable replacement cycles for municipal fleet managers. Multi-year fleet management agreements bundle vehicle procurement with operator training and maintenance outsourcing. EPA enforcement of combined sewer overflow consent decrees positions high-capacity vacuum trucks as essential compliance infrastructure.
US Vacuum Truck Market Competitive Landscape
The competitive structure tilts toward chassis-integrated manufacturers with municipal contracting expertise. Market concentration remains moderate with distinct tier separation between specialized hazardous material handlers and standardized liquid waste platforms. Two strategic archetypes dominate: vertically integrated builders controlling tank fabrication and blower assembly, and modular system integrators sourcing components across supplier networks. Competitive moves center on multi-year fleet management agreement capture and telematics-enabled service bundling.
Among established US-based fabricators, Vactor Manufacturing Inc., Federal Signal Corporation, and GapVax Inc. occupy differentiated positions within the supplier ecosystem. Vactor Manufacturing represents the chassis integration archetype with deep municipal sewer cleaning contract penetration. Federal Signal Corporation exemplifies diversification across specialized product lines for hazardous material response. GapVax Inc. sits within the aggressive mid-market segment, competing on combination unit flexibility for oilfield and construction applications. These three anchors illustrate how competitive positioning fragments across procurement sophistication tiers rather than consolidating around scale advantages.
| Leading Market Players |
|---|
| Vactor Manufacturing Inc. |
| Super Products LLC |
| Federal Signal Corporation |
| Sewer Equipment Co. of America |
| GapVax Inc. |
| Vac-Con Inc. |
| Hi-Vac Corporation |
| Vacall Industries |
| Keith Huber Corporation |
| Others |
Pricing and Supply Chain Analysis
EPA Phase 2 greenhouse gas standards gate both qualified supply and premium-tier pricing access, as chassis-integrated manufacturers must certify emissions-compliant powertrains to bid municipal contracts while bearing compliance costs that stratify fleet procurement tiers.
Pricing Analysis
Asset utilization guarantees anchor value-based pricing for municipal fleet operators, with multi-year service agreements bundling equipment procurement, operator training, and predictive maintenance subscriptions. Price differentiation separates corrosion-resistant tank specifications for Texas Gulf Coast chemical plants from standardized liquid waste platforms. Cost compression in mid-market combination units intensifies as GapVax and comparable fabricators compete on reconfiguration speed. Construction subcontractors exhibit highest price sensitivity due to project-based purchasing cycles, while industrial facilities prioritize uptime availability over capital minimization.
Supply Chain Analysis
Refurbishment flows for hydrostatic pumps and blower assemblies concentrate service revenue in Gulf Coast hubs, creating reverse-logistics dependencies that tether aftermarket profitability to technician density. Chassis fabrication draws from Michigan and Indiana automotive supplier networks, while specialized tank coatings source from Ohio and Pennsylvania chemical processors. Single-source vulnerability sits with high-pressure vacuum blower castings from limited domestic foundries. Distribution runs through manufacturer-direct account teams for municipal utilities and regional equipment dealers serving fragmented construction segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA emissions compliance deadlines force consolidation as smaller fabricators lack capital to certify electric-hybrid powertrains, eliminating marginal competitors from municipal bidding pools.
For Market Incumbents: Extend telematics-enabled service bundling to absorb traditional aftermarket revenue from independent repair shops. Capture multi-year fleet management agreements in the Northeast Corridor by embedding specifications directly into municipal capital improvement plans. Electric powertrain integration complexity threatens chassis-integrated manufacturers unable to trade payload capacity for range. For New Entrants and Emerging Players: The mid-market price-point gap between Vactor's premium municipal platforms and economy liquid waste units offers entry space for Appalachian Basin-focused combination unit specialists. Pennsylvania and Ohio shale drilling corridors present the most penetrable geography, with seasonal flexibility demands unmet by incumbent Gulf Coast service logistics. Target environmental services contractors through hazardous material response certification partnerships. For Investors and Strategic Acquirers: California Air Resources Board zero-emission mandate enforcement is the leading indicator that electric powertrain viability will separate viable acquisition targets from stranded asset risks. Five-to-ten-year viability favors vertically integrated fabricators controlling tank fabrication and blower assembly. Monitor EPA wastewater discharge standard tightening in the Permian Basin as signal for high-capacity vacuum system demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Remote tank monitoring absorbs depot diagnostic revenue into software subscriptions for Texas municipal fleets. |
| Chassis-Backward Integration | In-house tank fabrication insulates margin visibility from steel and aluminum commodity volatility. |
| Electric Powertrain Certification | EPA Phase 2 compliance unlocks California and New York municipal contract eligibility despite payload trade-offs. |
| Multi-Year Fleet Management Agreements | Bundled procurement with operator training locks replacement cycles and excludes spot-market competitors. |
| Appalachian Basin Service Expansion | Pennsylvania and Ohio pipeline construction demand reduces Permian Basin revenue concentration risk. |
Research Methodology
Document review covered EPA enforcement actions, OSHA confined space entry guidance, and municipal capital improvement plans, complemented by interviews with fleet managers at Texas and Louisiana utilities, chassis procurement leads at specialized manufacturers, and aftermarket service heads at Gulf Coast repair hubs. Secondary validation drew from DOT hazardous materials transport filings, state air resources board regulatory dockets, and industrial pretreatment program compliance records. Bottom-up unit shipment estimates triangulated against top-down fleet replacement cycle analysis.
Segment-level outputs across the projection horizon reflect modeled interactions between vehicle type, application intensity, and power source transition pathways. The analytical framework incorporated chassis-integrated versus modular system integrator cost structures, regional shale drilling activity indices, and municipal sewer infrastructure age distributions. CAGRs derived from replacement cycle velocity and regulatory compliance deadline clustering rather than extrapolated trend fitting.
Inputs from EPA regulatory filing databases and state procurement record systems were available through the study window; gaps in electric powertrain pilot deployment performance data introduce uncertainty bands around zero-emission adoption trajectories. Forecasts reflect assumptions regarding OSHA enforcement consistency and commodity input stability. Practitioners should monitor California Air Resources Board zero-emission mandate expansion signals and Appalachian Basin drilling permit volumes for early demand inflection indicators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
US Tanker Truck Market
Heavy-Duty Trucks
High Performance Trucks Market
Heavy-Duty Trucks
Dump Truck & Body Market
Heavy-Duty Trucks
Europe Fire Truck Market
Heavy-Duty Trucks
United States Refrigerated Trucking Market
Heavy-Duty Trucks
Big Rig Trucks Market
Heavy-Duty Trucks
Automotive High Performance Trucks Market
Heavy-Duty Trucks
Global Boom Truck Market
Heavy-Duty Trucks
Utility Trucks Market
Heavy-Duty Trucks
Europe Medium and Heavy-Duty Commercial Vehicles Market
Heavy-Duty Trucks
Stacker Truck Market
Heavy-Duty Trucks
Truck Diagnostic Market
Heavy-Duty Trucks
Logging Trucks Market
Heavy-Duty Trucks
Global Snow Sweeper Truck Market
Heavy-Duty Trucks
Articulated Dump Trucks Market
Heavy-Duty Trucks
Middle East Refrigerated Truck Market