
 Functional Carbohydrates Market | 2026-2036
Functional Carbohydrates Market Size, Share, and Industry Trends Forecast 2026-2036
Functional Carbohydrates Market Intelligence
Sports nutrition is restructuring demand patterns across the functional carbohydrates landscape as athletes and active consumers shift from simple sugars to gut-friendly prebiotic fibers in recovery products. Kerry Group leverages its integrated taste and nutrition platforms to supply customized prebiotic blends to beverage manufacturers. BENEO GmbH sustains its position through specialized chicory root extraction capabilities centered in Belgium and Chile. Cargill, Incorporated anchors North American supply with broad starch modification expertise spanning resistant dextrins and soluble fibers.
Functional carbohydrates comprise non-digestible oligosaccharides, resistant starches, and specialty polysaccharides that resist hydrolysis by human digestive enzymes and instead undergo bacterial fermentation in the colon, yielding short-chain fatty acids and promoting selective gut microbiota proliferation. These ingredients typically achieve prebiotic status at daily intake thresholds of 3-8 grams and serve primarily as sugar reducers, texture modifiers, and digestive health agents in processed foods. Inulin and oligofructose dominate current volume flows due to established extraction infrastructure and broad GRAS recognition, while resistant starch attracts accelerating investment as food manufacturers pursue clean-label fiber enrichment without sensory compromise. Polydextrose occupies a narrower but defensible niche in reduced-calorie confectionery where bulking functionality intersects with minimal glycemic impact.
The FDA's evolving dietary fiber definition under Nutrition Facts Label modernization continues to reshape which isolated and synthetic carbohydrates qualify for fiber declarations on U.S. packaged foods. EFSA's health claims framework in Europe restricts prebiotic marketing to substantiated strain-specific outcomes, compelling manufacturers to invest in clinical validation. Health Canada and FSANZ in Australia maintain parallel but non-identical approval pathways for novel fiber ingredients, fragmenting regulatory access costs. Stakeholders must monitor pending determinations on resistant starch type 4 classifications and decide whether to front-load clinical trials or prioritize jurisdictions with established monograph recognition.
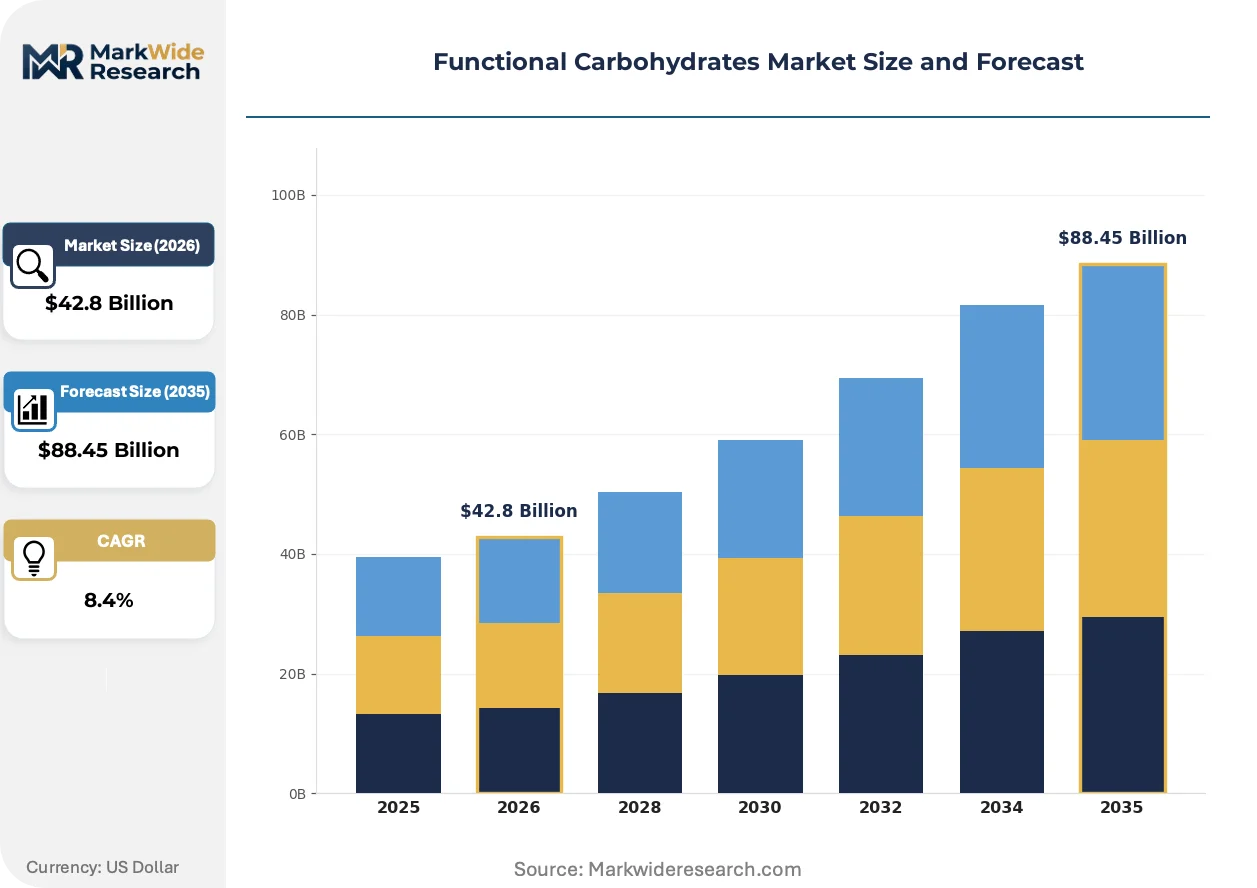
Market Dynamics
Prebiotic fiber qualification disputes under evolving FDA and EFSA definitions are forcing manufacturers to revalidate ingredient portfolios and redirect clinical investment toward resistant starch type 4 and novel oligosaccharide categories.
Growth Catalysts
- EU Food Information to Consumers Regulation:Tightened prebiotic labeling requirements in Europe are accelerating clinical substantiation investments and favoring suppliers with existing strain-specific dossiers.
- Sports nutrition formulation:Recovery beverage manufacturers are integrating chicory root-derived inulin and oligofructose at 3-8 gram functional thresholds to replace maltodextrin in clean-label positioning.
- Mannheim-Hamburg processing corridor:Concentrated ingredient tolling infrastructure in southwestern and northern Germany enables just-in-time prebiotic blending for Central European beverage brands.
Market Restraints
- Chicory root supply concentration:Overreliance on Belgian and Chilean chicory cultivation exposes processors to climate volatility and currency fluctuation in raw inulin extraction.
- Resistant starch sensory limitations:Type 2 and type 3 resistant starches introduce gritty texture and off-flavors in beverage applications, constraining clean-label adoption.
- EFSA health claims substantiation:Strain-specific outcome requirements restrict marketing language and extend time-to-market for novel prebiotic candidates without existing clinical packages.
Strategic Opportunities
- India FSSAI novel fiber pathway:Emerging regulatory clarity on resistant dextrin and soluble corn fiber approvals opens formulation partnerships with domestic processed food manufacturers.
- Precision fermentation oligosaccharides:Microbial production platforms for human milk oligosaccharide analogues converge with enzymatic modification to bypass agricultural feedstock constraints.
- Direct-to-practitioner distribution:Functional medicine clinicians and registered dietitians are becoming prescription channels for clinical-grade prebiotic supplements bypassing conventional retail.
Industry Challenges
- Clinical trial design expertise:Shortage of gastroenterology-focused contract research organizations with microbiome sequencing capabilities delays EFSA-compliant dossier preparation.
- Legacy ERP integration:Batch tracking and allergen segregation requirements for prebiotic isolates strain manufacturing execution systems designed for commodity starch operations.
- IP thickets around extraction:Patent clusters covering chicory root hot-water extraction and enzymatic hydrolysis create licensing complexity for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional Carbohydrates Market |
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $88.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inulin, Oligofructose, Resistant Starch, Polydextrose Application: Nutraceuticals, Food & Beverages, Dietary Supplements, Animal Feed End User: Food Manufacturers, Health-conscious Consumers, Pharmacies, Nutritional Companies Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Specialty Shops |
| Companies Covered | Kerry Group, BENEO GmbH, Cargill, Incorporated, Ingredion Incorporated, Archer-Daniels-Midland Company, DuPont Danisco, Tate & Lyle PLC, Evonik Industries AG, Roquette Frères, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional Carbohydrates Market Strategic Shifts & Innovations
Enzymatic modification and precision bioprocessing are fragmenting the historical dominance of agricultural extraction, enabling synthetic biology entrants to compete on purity and supply security rather than scale economics alone.
Continuous enzymatic hydrolysis of starch substrates is decentralizing prebiotic oligosaccharide production away from concentrated chicory root processing facilities toward distributed bioreactor installations at beverage manufacturing sites. Mid-sized functional drink brands in the United States and Germany are piloting in-house resistant dextrin production to secure supply continuity and reduce working capital tied to imported inulin inventories. This distributed manufacturing model compresses logistics costs and enables real-time formulation adjustments based on seasonal microbiome trend data.
EFSA's evolving interpretation of "beneficial physiological effect" for prebiotic health claims is narrowing permissible marketing language to strain-specific, dose-dependent outcomes with measurable biomarker endpoints. Manufacturers must now commission human intervention studies demonstrating selective Bifidobacterium or Lactobacillus proliferation at declared serving levels rather than relying on general fermentability data. Reduced-calorie confectionery and clinical nutrition segments face the steepest compliance burdens, with several legacy polydextrose formulations requiring reformulation or claim retirement across European markets.
Certification-driven procurement is fragmenting buyer concentration as retail and foodservice accounts impose third-party microbiome testing and carbon footprint verification on prebiotic suppliers. Sourcing managers at German and Dutch retail chains now require ISO 22000 certification combined with lifecycle assessment documentation for chicory root supply chains. This behavioral shift favors vertically integrated processors with captive agricultural operations and in-house analytical capabilities over toll manufacturers dependent on spot-market feedstocks.
Functional Carbohydrates Market Segmentation
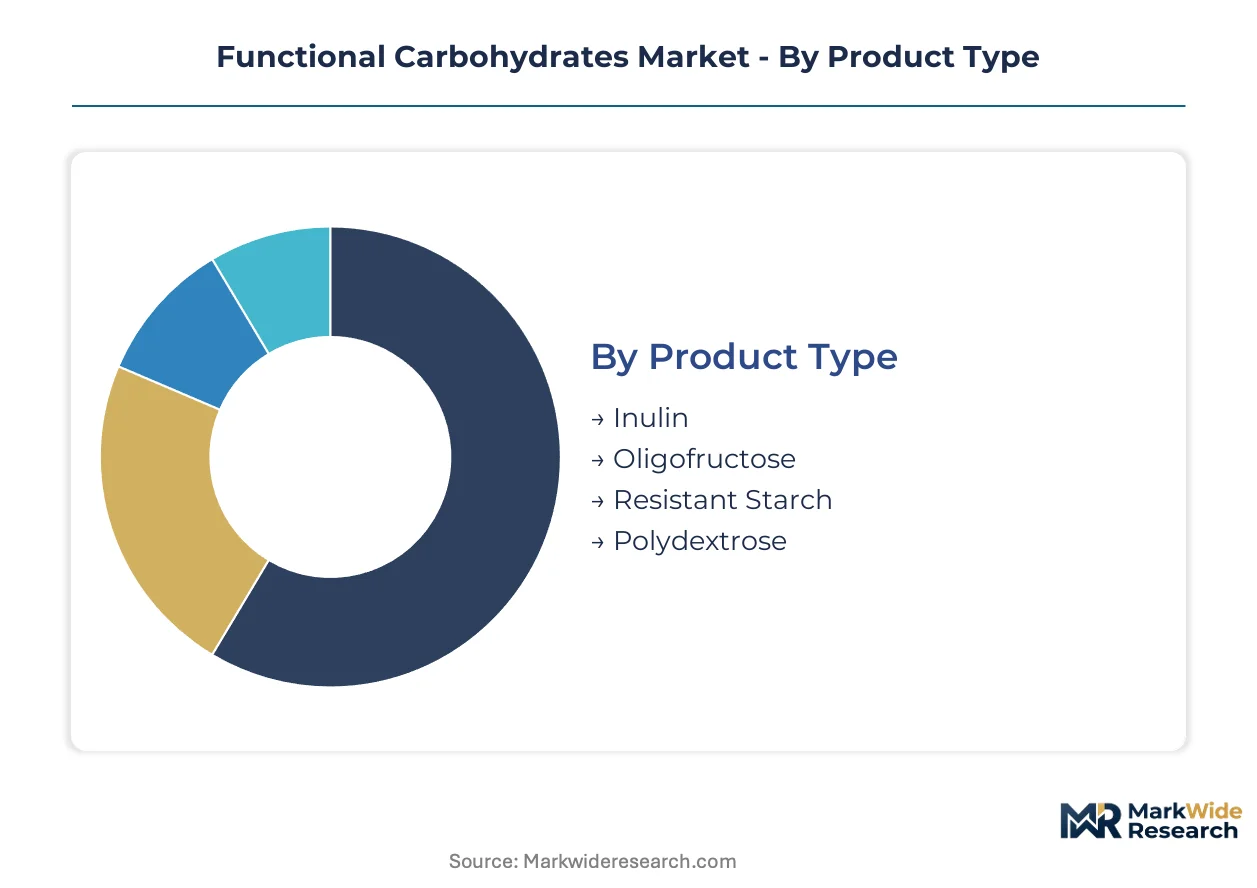
Functional carbohydrates demand fragments across four distinct segmentation axes, each reflecting divergent technical specifications, regulatory pathways, and procurement behaviors. Buyers prioritize fermentability profiles in nutraceutical applications while food manufacturers optimize for sensory masking and clean-label positioning.
Product Type:
Cost tier separates commodity-grade inulin from premium resistant starch variants requiring clinical substantiation investments.
- Inulin:Long-chain fructan extracted from chicory root through hot-water diffusion, achieving prebiotic thresholds at 5-8 gram daily intake. German beverage manufacturers in the Mannheim corridor source this grade for clean-label sugar reduction in functional drinks, though Belgian supply concentration creates currency exposure.
- Resistant Starch:Physically or chemically modified starch fractions resisting small-intestine hydrolysis, categorized as RS2 through RS4 by structural type. Type 4 chemically modified variants attract accelerating investment from U.S. processors seeking FDA fiber qualification under evolving Nutrition Facts Label definitions.
- Oligofructose:Short-chain fructooligosaccharide with enhanced solubility and faster fermentation kinetics than inulin.
- Polydextrose:Synthetic glucose polymer serving bulking functions in reduced-calorie confectionery with minimal glycemic impact.
Inulin leads volumes today; resistant starch is gaining share fastest.
Application:
Volume concentration shifts toward sports nutrition as athletes abandon maltodextrin for gut-friendly recovery formulations.
- Food & Beverages:Integration into dairy alternatives, baked goods, and functional beverages requiring texture modification alongside fermentable fiber content. Kerry Group supplies customized prebiotic blends to North American beverage brands pursuing EFSA-compliant health claims.
- Nutraceuticals:Clinical-grade prebiotic formulations targeting digestive health outcomes with strain-specific Bifidobacterium proliferation endpoints. EFSA's tightened interpretation of "beneficial physiological effect" forces manufacturers toward human intervention studies with measurable biomarkers.
- Dietary Supplements:Capsule and powder formats for direct-to-practitioner distribution through functional medicine channels.
- Animal Feed:Gut health optimization in livestock production, particularly poultry and swine operations seeking antibiotic alternatives.
Food and beverages dominates current offtake; nutraceuticals presents the steepest expansion trajectory.
End User:
Procurement sophistication varies sharply between multinational food manufacturers and fragmented health-conscious consumers.
- Food Manufacturers:Large-scale processors with dedicated R&D functions evaluating prebiotic ingredients against dual criteria of sensory performance and regulatory claim eligibility. These buyers impose ISO 22000 certification and lifecycle assessment documentation on suppliers.
- Nutritional Companies:Specialized formulators of clinical nutrition and medical foods requiring batch-level microbiome testing and allergen segregation protocols.
- Health-conscious Consumers:Individual purchasers prioritizing front-of-pack prebiotic claims and third-party certifications over technical specifications.
- Pharmacies:Retail dispensaries stocking practitioner-recommended prebiotic supplements with documented strain-specific outcomes.
Food manufacturers command the largest volume contracts; nutritional companies are expanding procurement most aggressively.
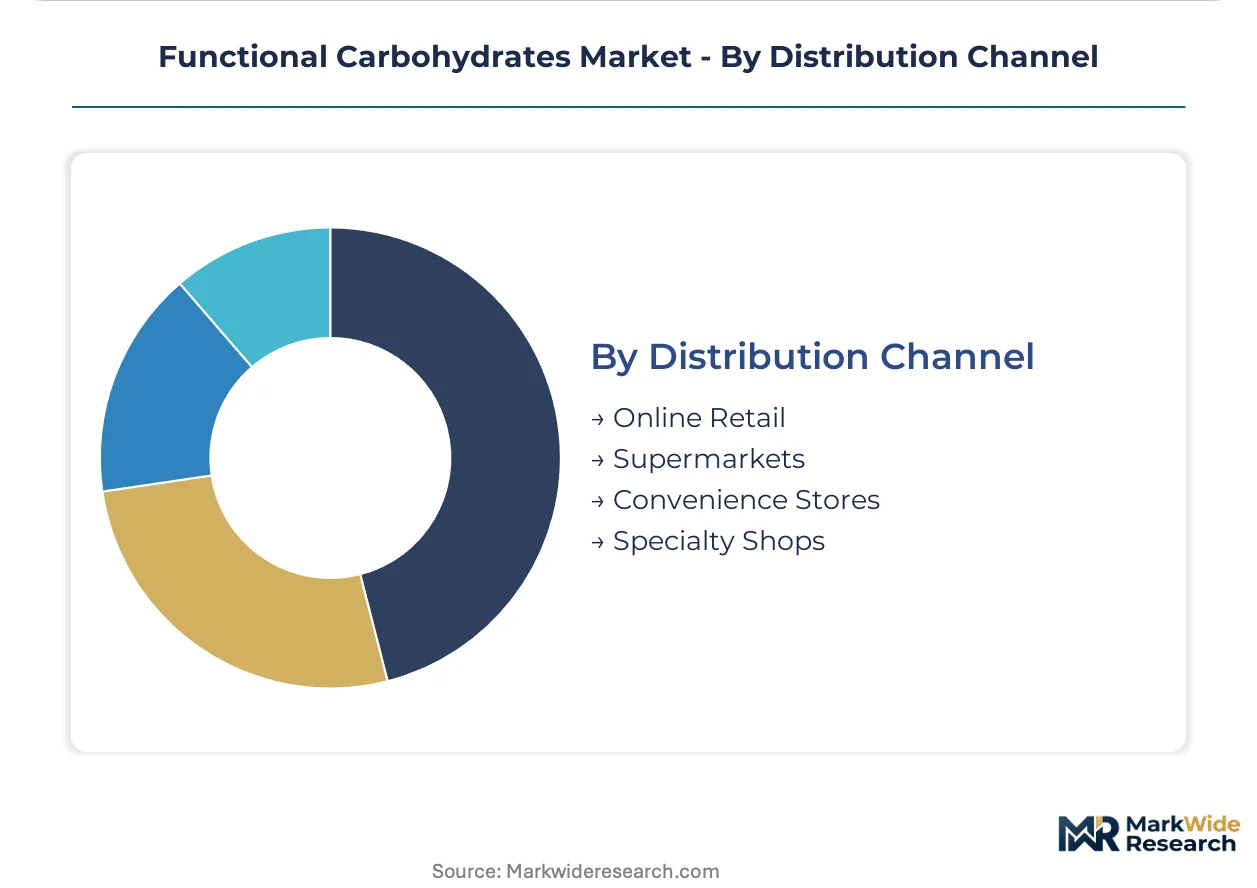
Distribution Channel:
Margin structure inverts between high-touch specialty shops and automated online fulfillment.
- Online Retail:Direct-to-consumer platforms enabling subscription-based prebiotic supplement replenishment with personalized microbiome trend data integration. German and Dutch consumers demonstrate highest penetration of digitally native functional nutrition brands.
- Specialty Shops:Independent health food retailers and functional medicine clinics providing education-intensive prebiotic counseling. These channels bypass conventional retail markups while requiring supplier investment in practitioner training programs.
- Supermarkets:Mass-market retail with standardized shelf placement and price-competitive positioning of mainstream inulin-fortified products.
- Convenience Stores:Limited functional carbohydrate presence restricted to single-serve probiotic-prebiotic combination beverages.
Online retail captures the fastest-growing transaction volume; specialty shops retain premium pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between FDA fiber qualification pathways and EFSA health claims substantiation costs is redirecting clinical investment toward jurisdictions with established monograph recognition. Manufacturers front-load trials in markets with pre-approved fiber definitions while delaying entry where novel ingredient dossiers face extended review timelines.
United States
Sports nutrition brands in the Pacific Northwest and Texas are integrating resistant dextrin into clean-label recovery beverages at 3-8 gram functional thresholds. FDA's evolving dietary fiber definition under Nutrition Facts Label modernization compels processors to revalidate resistant starch type 4 classifications. Cargill anchors North American supply from Minnesota-based starch modification facilities serving beverage manufacturers nationwide.
Germany
Mannheim and Hamburg concentrate Europe's prebiotic tolling infrastructure, enabling just-in-time blending for Central European functional drink brands. EFSA's tightened interpretation of "beneficial physiological effect" forces manufacturers toward human intervention studies with measurable Bifidobacterium proliferation endpoints. BENEO GmbH sustains chicory root extraction capabilities centered in Belgium with German distribution dominance.
China
Domestic processed food manufacturers in the Yangtze River Delta are expanding resistant dextrin partnerships with international suppliers. SAMR's evolving novel food ingredient approvals create parallel but non-identical pathways to FDA and EFSA frameworks. Zhengzhou and Shanghai host concentrated enzymatic modification facilities decentralizing production away from agricultural extraction centers.
India
FSSAI's emerging regulatory clarity on resistant dextrin and soluble corn fiber approvals opens formulation partnerships with domestic nutraceutical manufacturers. Maharashtra and Gujarat-based food processors pilot prebiotic fortification in traditional dairy alternatives and baked goods. Mumbai-Pune corridor attracts toll manufacturing investment for Central Asian export markets.
Brazil
São Paulo-state food manufacturers integrate inulin from Belgian and Chilean supply chains into reduced-sugar confectionery and dairy applications. ANVISA's health claims framework restricts prebiotic marketing to substantiated outcomes, compelling clinical validation investments. Campinas and São Paulo metropolitan area concentrate ingredient blending infrastructure for Latin American distribution.
Functional Carbohydrates Market Key Industry Players
Strategic partnerships dominate the current landscape as processors secure captive supply of chicory root and enzymatic modification capabilities. The vendor base clusters around three tiers: integrated taste-and-nutrition platforms, specialized agricultural extraction specialists, and distributed bioreactor operators. Two archetypes define competitive positioning—vertically integrated processors with captive agricultural operations, and technology licensors enabling distributed manufacturing. Capacity expansion in resistant starch type 4 and precision fermentation oligosaccharides represents the dominant investment vector.
Within the integrated platform tier, Kerry Group and Cargill, Incorporated exemplify scale-driven supply security through backward integration into starch modification and global distribution networks. BENEO GmbH occupies a specialized position representing agricultural extraction expertise centered on chicory root supply chains. These three anchors illustrate divergent pathways—taste-and-nutrition integration, commodity-scale processing, and botanical specialization—without requiring uniform strategic postures across the competitive set.
| Leading Market Players |
|---|
| Kerry Group |
| BENEO GmbH |
| Cargill, Incorporated |
| Ingredion Incorporated |
| Archer-Daniels-Midland Company |
| DuPont Danisco |
| Tate & Lyle PLC |
| Evonik Industries AG |
| Roquette Frères |
| Others |
Cost & Logistics Intelligence
Family-owned Belgian chicory processors and Chilean agricultural cooperatives anchor raw inulin supply, transmitting crop volatility directly into long-term contract pricing for European beverage manufacturers seeking supply security.
Pricing Analysis
Distributor margins compress pricing transparency as ingredient tollers in Mannheim and Hamburg layer blending fees onto Belgian-sourced inulin before final delivery to German functional drink brands. Three-tier pricing structure across clinical-grade, food-grade, and feed-grade certification levels separates nutraceutical premiums from commodity inulin. Cost compression in standard-grade inulin is intensifying because Brazilian and Indian processors are expanding enzymatic modification capacity. Nutraceutical manufacturers demonstrate lowest price sensitivity due to strain-specific health claim substantiation requirements, while mass-market confectionery buyers negotiate aggressively on volume.
Supply Chain Analysis
Dual-sourcing requirements from Kerry Group and Cargill force beverage manufacturers to qualify both Belgian chicory root and U.S. corn-derived resistant dextrin suppliers simultaneously. Supply concentrates in Belgium, Chile, and the United States for raw inulin extraction and starch modification feedstocks. Processing draws from chicory root cultivation, enzymatic hydrolysis equipment, and microbiome testing laboratories. Single-source vulnerability in Belgian hot-water extraction infrastructure exposes buyers to climate-related crop failures. Distribution runs through specialized ingredient distributors with cold-chain capabilities for live culture co-formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EFSA's tightened strain-specific health claim requirements are accelerating clinical validation investments and favoring suppliers with existing dossier libraries.
For Market Incumbents: Hedge chicory root concentration by securing enzymatic modification partnerships in India and China, while accelerating resistant starch type 4 capacity additions in Minnesota to offset Belgian supply risk. Defend margin position through backward integration into precision fermentation platforms for human milk oligosaccharide analogues. For New Entrants and Emerging Players: Direct-to-practitioner digital channels offer the lowest competitive density for clinical-grade prebiotic supplements, bypassing retail markups and enabling subscription-based microbiome trend services. Target India's FSSAI-resistant dextrin pathway as the most penetrable regulatory opening, partnering with Maharashtra-based dairy processors for traditional product fortification. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap enzymatic modification specialists with SAMR pre-approvals in China but without EFSA dossier completion. Long-term viability hinges on clinical trial infrastructure ownership rather than commodity extraction scale. Watch FDA resistant starch type 4 fiber qualification determinations as the signal for portfolio reallocation toward chemically modified variants.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Infrastructure Investment | Human intervention studies with Bifidobacterium endpoints satisfy EFSA's evolving health claims framework. |
| Backward Integration into Precision Fermentation | Microbial production platforms bypass agricultural feedstock constraints for human milk oligosaccharide analogues. |
| EFSA Dossier Completion | Strain-specific outcome documentation enables premium positioning in European nutraceutical channels. |
| India FSSAI Partnership Development | Regulatory clarity on resistant dextrin approvals opens formulation partnerships with domestic processed food manufacturers. |
| Distributed Bioreactor Installation | In-house resistant dextrin production at beverage sites compresses logistics costs and enables real-time formulation adjustments. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with prebiotic ingredient procurement managers, regulatory affairs directors at functional beverage brands, enzymatic modification facility operators, and clinical research organization microbiome specialists. Secondary validation draws from FDA Nutrition Facts Label guidance documents, EFSA health claims register entries, FSSAI novel food ingredient notifications, and customs trade data for chicory root and modified starch imports. Bottom-up volume estimates from application-level consumption data triangulate against top-down manufacturer capacity disclosures.
Rate-of-change decomposition separates volume growth from price evolution across the analysis window, with segmentation modeling across product type, application, end user, and distribution channel dimensions. CAGRs derive from fitted trend analysis incorporating regulatory approval timelines, capacity expansion announcements, and substitution elasticity estimates between inulin and resistant starch variants. Industry-specific inputs include EFSA health claim substantiation cost curves and enzymatic modification yield improvements from continuous processing technology.
EFSA regulatory reinterpretation, FDA fiber qualification delays, and precision fermentation yield breakthroughs are the dominant revision risks to modeled outcomes. Deviation in EFSA's "beneficial physiological effect" interpretation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Middle East Protein Market
Nutritional Supplements
Fitness Cookies Market
Nutritional Supplements
Asia-Pacific Digestive Enzymes Market
Nutritional Supplements
Vegetable Capsules Market
Nutritional Supplements
Nutrient Dense Food Products Market
Nutritional Supplements
Japan Dietary Supplements Market
Nutritional Supplements
Diet Shakes Market
Nutritional Supplements
Liuweidihuang Market
Nutritional Supplements
Nutraceutical Flexible Packaging Market
Nutritional Supplements
North America Protein Market
Nutritional Supplements
Chewable Energy Tablet Market
Nutritional Supplements
Global Collagen Peptides Market
Nutritional Supplements
Chia-Based Protein Market
Nutritional Supplements
Natural Immune Booster Market
Nutritional Supplements
Europe Botanical Supplements Market
Nutritional Supplements
Mineral Supplements Market