
 Asia-Pacific Digestive Enzymes Market | 2026-2036
Asia-Pacific Digestive Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Digestive Enzymes Market Insights
Aftermarket service revenue from enzyme stability consulting is narrowing as manufacturers internalize formulation expertise. Abbott Laboratories leverages its diagnostic heritage to anchor hospital procurement channels across Southeast Asia. DSM sustains technology leadership through specialized lipase variants for high-fat dietary applications. Otsuka Holdings dominates Japanese prescription-grade pancreatin supply through tight clinic network control.
Digestive enzymes comprise protein catalysts that hydrolyze macronutrients into absorbable subunits, with industrial preparations typically standardized to specific activity units per milligram for lipase, protease, and amylase fractions. Pancreatin formulations command premium positioning in hospital settings due to their multi-enzyme synergy and established clinical validation. The dietary supplements end user segment captures accelerating growth as India's PLI scheme for nutraceuticals attracts domestic manufacturing investment. Online retail distribution channels reshape competitive dynamics by enabling direct-to-consumer brands to bypass traditional pharmacy gatekeepers.
Japan's PMDA maintains stringent stability-testing protocols for enzyme activity claims, while China's NMPA enforces dual carbon goals that pressure energy-intensive fermentation facilities toward process redesign. Australia's TGA and South Korea's MFDS impose divergent labeling requirements that fragment regional product standardization. Stakeholders must monitor how India's CDSCO evolves its enzyme-specific monographs under revised nutraceutical regulations.
Market Dynamics
China's NMPA dual carbon mandates are forcing fermentation facilities across the region toward process redesign, compressing supply timelines while elevating capital requirements for enzyme manufacturers serving dietary supplement and pharmaceutical channels.
Growth Catalysts
- India's PLI scheme for nutraceuticals:Domestic manufacturing investment is accelerating as Mumbai and Hyderabad hubs expand production capacity for enzyme-based supplements. CDSCO's evolving monographs under revised nutraceutical regulations provide clearer pathways for product registration.
- Online retail channel expansion:Direct-to-consumer brands are bypassing traditional pharmacy gatekeepers across Southeast Asia, reshaping competitive dynamics and enabling faster market entry for specialized formulations.
- Prescription-grade pancreatin validation:Hospital procurement channels in Japan sustain premium positioning through PMDA's stringent stability-testing protocols, anchoring clinical-grade demand.
Market Restraints
- Fermentation energy costs:China's dual carbon goals pressure energy-intensive production facilities toward capital-heavy process redesign, elevating unit economics for lipase and protease fractions.
- Regional labeling fragmentation:Australia's TGA and South Korea's MFDS impose divergent requirements that obstruct product standardization across ASEAN trade corridors.
- Plant-based enzyme substitution:Microbial and fungal-derived alternatives are capturing share in over-the-counter segments, compressing margins for traditional animal-source pancreatin suppliers.
Strategic Opportunities
- Vietnam and Indonesia underpenetration:Rising middle-class expenditure on preventive health creates whitespace for enzyme supplement brands before regulatory frameworks fully mature.
- High-fat dietary lipase variants:Specialized formulations for ketogenic and regional high-oil cuisines enable premium positioning in South Korea and urban China.
- MFDS fast-track pathways:South Korea's streamlined approval for functional health ingredients accelerates time-to-market for novel enzyme complexes targeting metabolic health claims.
Industry Challenges
- Formulation expertise scarcity:Manufacturers struggle to recruit enzymologists capable of optimizing multi-enzyme synergy for stability across tropical supply chains.
- Cross-border certification timelines:Divergent TGA, MFDS, and NMPA testing protocols extend product launch cycles by twelve to eighteen months for regional rollouts.
- Legacy distributor relationship management:Traditional pharmacy networks resist margin compression from direct-to-consumer brands, creating channel conflict in Thailand and Philippines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Digestive Enzymes Market |
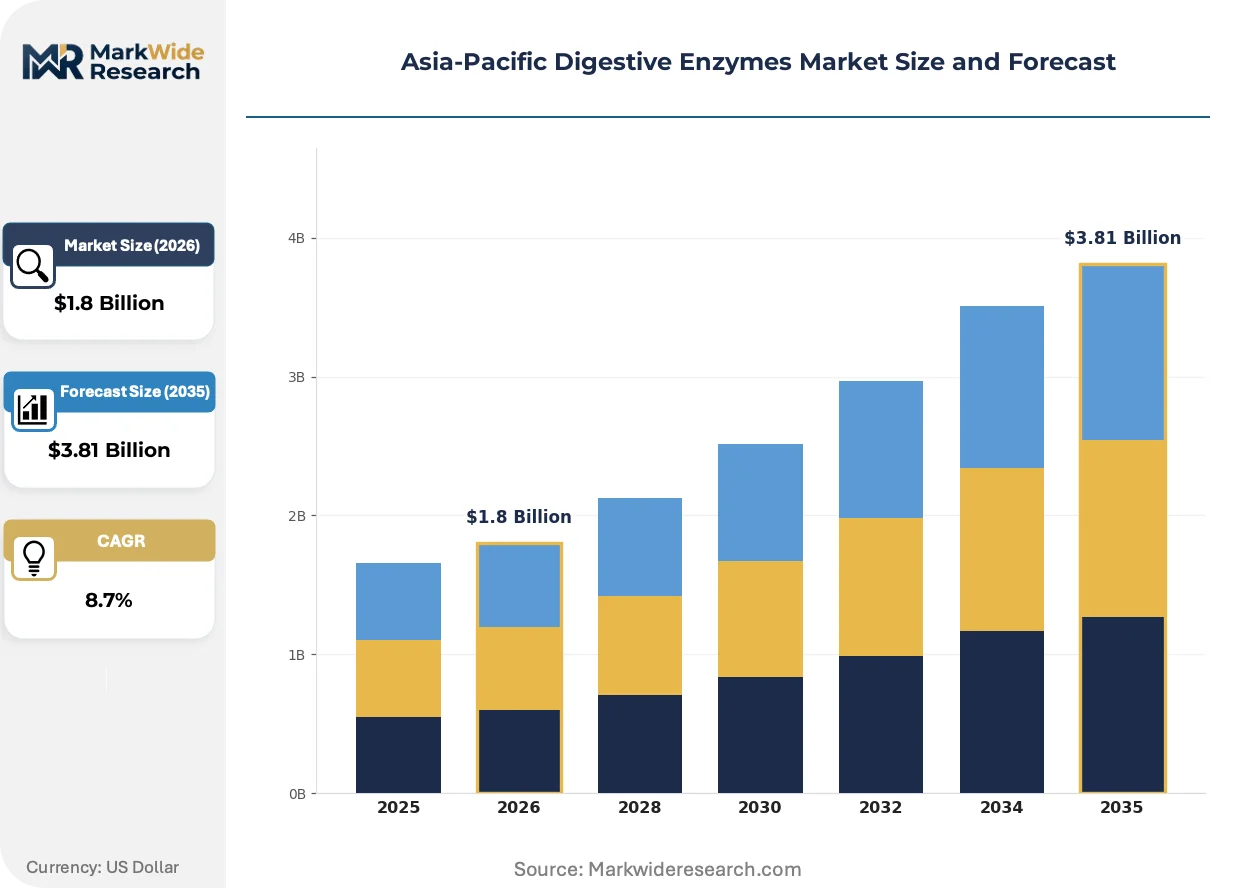
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pancreatin, Amylase, Lipase, Protease End User: Hospitals, Clinics, Homecare, Dietary Supplements Formulation: Tablets, Capsules, Powders, Liquid Distribution Channel: Online Retail, Pharmacies, Supermarkets, Health Stores |
| Companies Covered | Abbott Laboratories, Nestlé Health Science, Bayer AG, Amway, Herbalife Nutrition Ltd., Otsuka Holdings Co., Ltd., NOW Foods, Amano Enzyme, DSM, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Digestive Enzymes Market Trends and Innovations
Bioprocess engineering and distribution architecture are converging to redefine how enzyme activity is preserved, validated, and delivered across Asia-Pacific's fragmented regulatory terrain.
Immobilized enzyme technology is hybridizing batch fermentation with continuous processing, enabling real-time activity adjustment during manufacturing. Dietary supplement manufacturers in India and China are piloting these systems to reduce yield variability. The approach is compressing quality assurance cycles while elevating capital intensity for mid-scale producers.
PMDA's stability-testing protocols for enzyme activity claims are tightening documentation requirements for temperature excursion data across shelf-life studies. Japanese prescription-grade manufacturers must now submit accelerated degradation modeling under revised guidelines. Hospital procurement channels are responding by consolidating supplier lists toward vertically integrated producers with captive analytical capabilities.
Subscription-based replenishment models are displacing one-time pharmacy purchases for chronic digestive support regimens. Direct-to-consumer brands leverage telehealth partnerships in Australia and South Korea to capture recurring revenue streams. This shift is most visible among urban professionals aged 35-50 seeking personalized gut health protocols without clinic visits.
Asia-Pacific Digestive Enzymes Market Segmentation
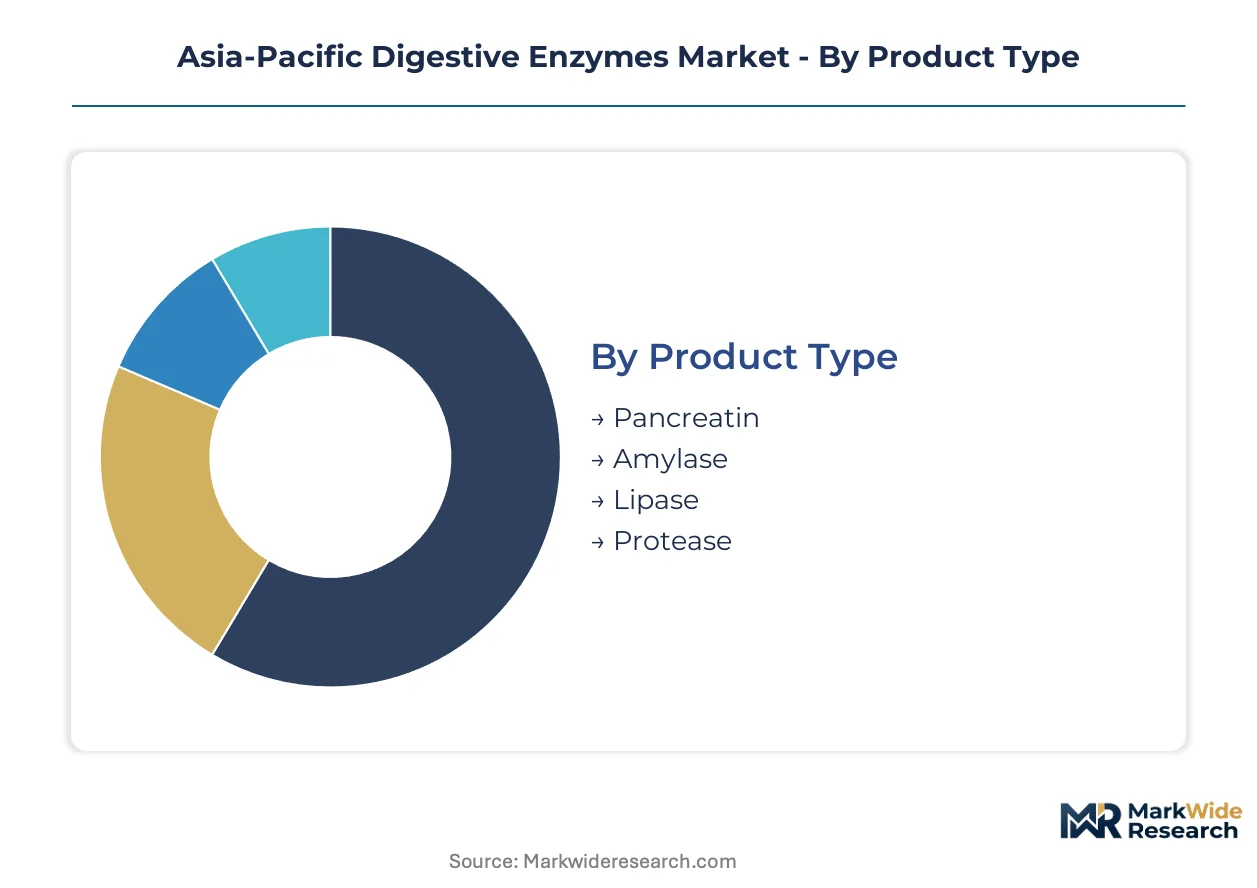
Enzyme activity specifications, stability requirements, and procurement channel economics fragment the Asia-Pacific landscape into distinct commercial battlegrounds. Manufacturers optimize formulations around regional regulatory tolerances and end-user price sensitivity rather than pursuing uniform global SKUs.
Product Type:
The use-case spectrum spans acute clinical intervention through daily metabolic support, with activity-unit standardization determining reimbursement eligibility and retail positioning.
- Pancreatin:Multi-enzyme complexes derived from porcine pancreas deliver standardized lipase, protease, and amylase activity ratios. Hospital procurement channels across Japan and Australia favor these formulations for malabsorption syndromes, though PMDA and TGA stability-testing protocols elevate analytical compliance costs. Established volume favors pancreatin; emerging adoption favors lipase isolates.
- Lipase:Isolated triglyceride-hydrolyzing enzymes command premium positioning in ketogenic diet support and high-fat regional cuisines. South Korea's MFDS fast-track pathways for functional health ingredients accelerate novel lipase complex registrations targeting metabolic health claims.
- Amylase:Starch-digesting enzymes dominate over-the-counter carbohydrate support formulations in India and Southeast Asia.
- Protease:Protein-hydrolyzing fractions address sports nutrition and recovery applications through direct-to-consumer channels.
Clinical validation depth separates prescription-grade from wellness-positioned offerings.
End User:
Procurement authority concentration varies sharply across institutional, retail, and self-directed consumption contexts.
- Dietary Supplements:India's PLI scheme for nutraceuticals attracts domestic manufacturing investment toward Mumbai and Hyderabad production hubs. CDSCO's evolving monographs under revised nutraceutical regulations provide clearer registration pathways for enzyme-based health products. Established volume favors dietary supplements; emerging adoption favors homecare.
- Hospitals:Multi-enzyme pancreatin formulations anchor procurement through diagnostic heritage relationships and established clinical protocols.
- Clinics:Prescription-grade supply in Japan flows through tight clinic network control anchored by PMDA registration requirements.
- Homecare:Chronic digestive support regimens shift toward subscription-based replenishment models leveraging telehealth partnerships in Australia and South Korea.
Channel conflict intensifies as direct-to-consumer brands bypass traditional pharmacy gatekeepers.
Formulation:
Stability engineering and patient compliance economics drive format selection across tropical supply chains and aging demographics.
- Capsules:Enteric-coated gelatin shells protect enzyme activity from gastric denaturation while enabling precise dosing. NMPA registration requirements for enzyme-based health products in China continue tightening purity benchmarks for capsule excipients. Established volume favors capsules; emerging adoption favors tablets.
- Tablets:Compressed formulations with disintegration-time optimization address cost-sensitive segments in India and Indonesia.
- Powders:Bulk formats serve pediatric and dysphagia populations through flexible dosing protocols.
- Liquid:Ready-to-use solutions capture institutional and acute care settings requiring rapid administration.
Temperature excursion tolerance distinguishes premium from economy tier positioning.
Distribution Channel:
Margin structure and consumer education burden determine viable pathways for specialized versus commodity enzyme offerings.
- Online Retail:Direct-to-consumer platforms enable bypass of traditional pharmacy gatekeepers across Southeast Asia, compressing launch timelines for specialized formulations. Subscription-based replenishment models capture recurring revenue from urban professionals aged 35-50 seeking personalized gut health protocols. Established volume favors online retail; emerging adoption favors health stores.
- Pharmacies:Legacy distributor relationships in Thailand and Philippines resist margin compression from digital entrants.
- Supermarkets:Mass-market penetration requires simplified messaging and price positioning accessible to casual wellness consumers.
- Health Stores:Specialized retail formats in Australia and urban China cater to premium-positioned enzyme complexes with clinical-adjacent positioning.
Regulatory labeling divergence across TGA, MFDS, and NMPA jurisdictions fragments product standardization for multi-channel distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across the Asia-Pacific digestive enzymes landscape, with Indian nutraceutical buyers exhibiting acute cost sensitivity while Japanese hospital procurement channels absorb substantial premiums for prescription-grade stability validation.
China
NMPA dual carbon mandates are forcing fermentation facilities toward energy-intensive process redesign, elevating capital requirements for domestic manufacturers. The regulator's tightening purity benchmarks for enzyme-based health products compress supply timelines while filtering smaller producers from dietary supplement channels. Yangtze River Delta production clusters around Shanghai face acute pressure to retrofit anaerobic digestion systems.
Japan
PMDA's stringent stability-testing protocols anchor premium positioning for prescription-grade pancreatin through hospital procurement channels. The regulator's revised guidelines now mandate accelerated degradation modeling submissions, consolidating supplier lists toward vertically integrated producers. Kanto region manufacturers around Tokyo maintain tight clinic network control for clinical-grade enzyme distribution.
India
CDSCO's evolving monographs under revised nutraceutical regulations are attracting domestic manufacturing investment through the PLI scheme. Mumbai and Hyderabad production hubs are expanding capacity for enzyme-based supplements as registration pathways clarify. The country's national pharmaceutical regulator is tightening documentation standards for tropical stability claims.
South Korea
MFDS fast-track pathways for functional health ingredients are accelerating novel lipase complex registrations targeting metabolic health claims. Urban professionals aged 35-50 are driving subscription-based replenishment models through telehealth partnerships. Seoul Capital Area manufacturers specialize in high-fat dietary variants for ketogenic applications.
Australia
TGA labeling requirements diverge from regional standards, fragmenting product standardization for ASEAN trade corridor access. Health stores in New South Wales and Victoria cater to premium-positioned enzyme complexes with clinical-adjacent positioning. The national therapeutic regulator's stability documentation demands exceed Southeast Asian benchmarks.
Asia-Pacific Digestive Enzymes Market Competitive Landscape
Pharmaceutical heritage conglomerates and specialized enzyme technology houses split the market along prescription-grade versus wellness-positioned vectors. The competitive structure tiers around clinical validation depth, with hospital procurement channels consolidating toward multi-enzyme pancreatin suppliers while direct-to-consumer brands fragment over-the-counter segments. Three archetypes dominate: diagnostic-anchored hospital suppliers, fermentation-technology specialists, and nutraceutical-scale commodity producers. Strategic moves concentrate on backward integration into captive analytical capabilities and geographic expansion through telehealth partnerships.
Among diagnostic-anchored conglomerates, Abbott Laboratories exemplifies the hospital procurement channel archetype through its Southeast Asia diagnostic heritage relationships. DSM occupies a position within the fermentation-technology specialist tier, with its specialized lipase variants representing premium positioning for high-fat dietary applications. Otsuka Holdings Co., Ltd. anchors the prescription-grade supply archetype through its tight Japanese clinic network control and PMDA registration compliance.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Nestlé Health Science |
| Bayer AG |
| Amway |
| Herbalife Nutrition Ltd. |
| Otsuka Holdings Co., Ltd. |
| NOW Foods |
| Amano Enzyme |
| DSM |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Yangtze River Delta fermentation facilities is elevating unit economics for lipase and protease fractions while compressing margins for mid-scale manufacturers serving dietary supplement channels across China and India.
Pricing Analysis
Aftermarket enzyme stability consulting revenue is narrowing as manufacturers internalize formulation expertise. Three-tier pricing structure across premium, standard, and economy levels separates prescription-grade pancreatin validated under PMDA protocols from commodity over-the-counter amylase formulations. Cost compression in standard-tier capsules is intensifying because India's PLI scheme attracts domestic manufacturing investment. Dietary supplement buyers in Mumbai and Hyderabad production hubs exhibit acute price sensitivity, while Japanese hospital procurement channels absorb substantial premiums for clinical-grade stability documentation.
Supply Chain Analysis
Contract-manufacturing concentration among Yangtze River Delta fermentation houses and Mumbai nutraceutical CMs anchors regional enzyme production capacity. Geographic supply concentration centers on China, India, and Japan, with porcine pancreas sourcing and specialized lipase strain development as critical inputs. Single-source vulnerability in animal-derived pancreatin supply creates exposure to NMPA purity benchmark tightening. Distribution runs through hospital procurement channels in Japan, direct-to-consumer platforms in Southeast Asia, and legacy pharmacy networks in Thailand and Philippines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored by regulatory entrenchment, where PMDA and NMPA registration requirements create switching costs that protect incumbent positions.
For Market Incumbents: Insulate prescription-grade positioning by deepening backward integration into captive analytical capabilities for accelerated degradation modeling under revised PMDA guidelines. Add fermentation capacity in Hyderabad to capture PLI scheme benefits before CDSCO monographs fully crystallize. Plant-based enzyme substitution threatens animal-source pancreatin margins; counter through multi-enzyme synergy patents.
For New Entrants and Emerging Players: Establish a beachhead in Vietnam and Indonesia preventive health whitespace before MFDS-style regulatory frameworks mature. Target subscription-based replenishment models for urban professionals aged 35-50 in South Korea and Australia through telehealth partnerships. Bypass legacy pharmacy gatekeepers via direct-to-consumer platforms with specialized lipase variants for ketogenic applications.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across fermentation-technology specialists as NMPA dual carbon mandates force process redesign. Five-to-ten year viability favors vertically integrated producers with hospital procurement channel control and in-house stability validation. Watch MFDS fast-track pathway utilization rates as inflection signal for functional health ingredient premiumization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Fermentation | Yangtze River Delta facilities secure supply continuity under NMPA dual carbon compliance pressure. |
| PMDA Stability-Testing Protocol Investment | Accelerated degradation modeling capability consolidates Japanese hospital procurement channel access. |
| Direct-to-Consumer Platform Launch | Subscription models bypass Thailand pharmacy gatekeepers for urban professional gut health segments. |
| Specialized Lipase Variant Development | High-fat dietary formulations capture premium positioning in South Korea ketogenic applications. |
| Telehealth Partnership Expansion | Recurring revenue streams anchor chronic digestive support regimens in Australian homecare. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with regulatory affairs leads at NMPA-registered manufacturers, CDSCO filing specialists, hospital procurement managers across Southeast Asia, and dietary supplement brand managers; and secondary validation through NMPA enzyme registration filings, CDSCO nutraceutical monograph drafts, PMDA stability guideline revisions, and customs trade data for porcine pancreatin imports. Bottom-up volume triangulation against top-down category spend estimates anchored projection integrity.
Forecast inputs span product type segmentation across pancreatin, lipase, amylase, and protease fractions; end-user categories including dietary supplements, hospitals, clinics, and homecare; and formulation formats from enteric-coated capsules through liquid preparations. CAGRs were derived through regression analysis of historical regulatory approval velocity and manufacturing capacity expansion announcements. Industry-specific inputs incorporate PLI scheme utilization rates and MFDS fast-track pathway completion timelines.
Stress conditions across NMPA dual carbon compliance costs, CDSCO monograph revision scope, and plant-based substitution adoption curves were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory timeline stability and fermentation yield consistency. Quarterly review of NMPA registration queue depth and MFDS functional health ingredient approval velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Europe Dietary Supplements Market
Nutritional Supplements
Milk Powder for Pregnant Women Market
Nutritional Supplements
Digestive Health Supplements Market
Nutritional Supplements
Japan Dietary Supplements Market
Nutritional Supplements
Global Nootropics Brain Supplements Market
Nutritional Supplements
Pet Dietary Supplements Market
Nutritional Supplements
Energy Gel Products Market
Nutritional Supplements
Health Supplementary Food OEM and ODM Market
Nutritional Supplements
Red Ginseng Market
Nutritional Supplements
Algae Omega 3 Market
Nutritional Supplements
Natural Immune Booster Market
Nutritional Supplements
Europe Omega-3 Products Market
Nutritional Supplements
Lutein Market
Nutritional Supplements
Europe Feed Prebiotics Market
Nutritional Supplements
Middle East and Africa Omega-3 Products Market
Nutritional Supplements
Pulse Protein Market