
 Nutraceutical Flexible Packaging Market | 2026-2036
Nutraceutical Flexible Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Nutraceutical Flexible Packaging Market Analytics
Polyethylene terephthalate films are consolidating their position against conventional multilayer structures in mid-volume nutraceutical runs, cutting unit costs while preserving oxygen barrier performance. Amcor plc leverages its global film extrusion network to supply pharmaceutical-grade laminates with validated stability data. Berry Global anchors North American capacity through blown film operations calibrated to FDA-compliant dietary supplement specifications. Mondi Group competes on kraft-paper-based flexible formats that target brands seeking plastic reduction narratives without sacrificing moisture protection.
Nutraceutical flexible packaging denotes engineered multilayer films, foils, and papers formed into collapsible primary containers, typically achieving oxygen transmission rates below 0.1 cc per square meter per day to protect oxidation-sensitive bioactive compounds such as omega-3 fatty acids and probiotic cultures. Pouches dominate volume across powdered supplements and gummy vitamins, while sachets capture the fastest expansion in single-dose liquid and powder formats distributed through direct-to-consumer channels. Biodegradable materials remain nascent in share but concentrate margin pools among European brands responding to ECHA-guided sustainability commitments.
FDA 21 CFR Part 177 governs indirect food contact substances in laminate adhesives and coatings, while the EU F-Gas Regulation pressures converters to eliminate hydrofluorocarbon-based foaming agents in insulation films used during cold-chain distribution of temperature-sensitive nutraceuticals. ISO 15378 certification for medicinal product packaging now functions as a de facto market-access threshold for contract manufacturers serving pharmaceutical-owned supplement lines. Stakeholders must monitor evolving state-level extended producer responsibility laws in California and New York, as these will reshape cost allocation between converters and brand owners.
Market Dynamics
The EU Packaging and Packaging Waste Regulation mandates escalating recycled content thresholds for flexible plastics, forcing converters to re-engineer multilayer barrier films while preserving oxygen transmission performance below 0.1 cc per square meter per day for oxidation-sensitive bioactives.
Growth Catalysts
- Sports nutrition pouch demand:Single-serve formats for protein powders and pre-workout blends expand shelf presence in United States convenience retail and direct-to-consumer subscription channels.
- F-Gas Regulation compliance:The EU phase-down of hydrofluorocarbon foaming agents accelerates adoption of alternative insulation films for cold-chain distribution of temperature-sensitive probiotics and omega-3 formulations.
- ISO 15378 certification:Pharmaceutical-owned supplement lines now require medicinal-grade packaging validation, creating qualified supplier scarcity that benefits certified contract manufacturers.
Market Restraints
- Recycled resin quality variance:Post-consumer polyethylene feedstock exhibits inconsistent melt flow indices, complicating coextrusion of oxygen barrier layers meeting FDA 21 CFR Part 177 indirect food contact standards.
- Blown film capacity concentration:North American pharmaceutical-grade laminate supply clusters among three integrated converters, creating single-source risk for mid-volume dietary supplement brands.
- Biodegradable barrier limitations:Polylactic acid and PHA films fail to achieve sub-0.5 cc oxygen transmission rates without aluminum oxide metallization, restricting use in probiotic sachets.
Strategic Opportunities
- California EPR implementation:State-level extended producer responsibility laws will reallocate end-of-life packaging costs, favoring converters with established mechanical recycling partnerships over import-dependent competitors.
- Kraft-paper hybrid formats:European brands seeking plastic reduction narratives drive development of fiber-based pouches with moisture-resistant bio-coatings, commanding 15-25% price premiums over conventional laminates.
- Personalized vitamin subscriptions:Daily-dose sachet automation lines enable micro-batch production for algorithm-compounded supplement regimens, opening contract packaging revenue streams.
Industry Challenges
- Adhesive migration validation:FDA 21 CFR Part 177.1390 compliance testing for laminate solvents requires 18-24 month stability protocols, delaying new product launches.
- Blown film technician scarcity:Pharmaceutical-grade extrusion operators with FDA audit experience command 40% wage premiums, constraining capacity expansion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nutraceutical Flexible Packaging Market |
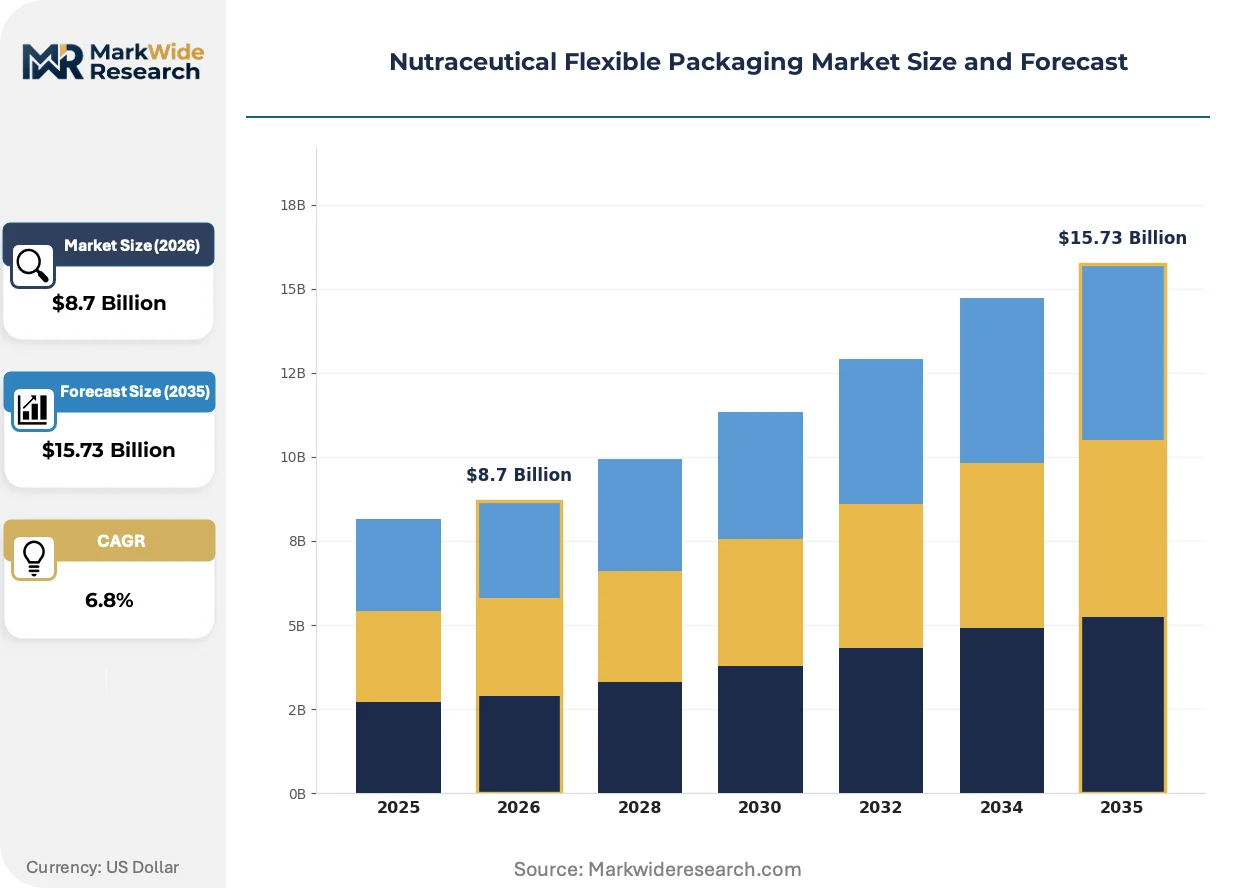
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pouches, Bags, Sachets, Wraps Material: Plastic, Paper, Aluminum, Biodegradable Closure Type: Zip Lock, Heat Seal, Screw Cap, Spout End User: Pharmaceuticals, Dietary Supplements, Food Industry, Others |
| Companies Covered | ProAmpac, Alpha Packaging, Amcor plc, Sonoco Products Company, Graham Packaging Company, Berry Global, Flex-pack, Constantia Flexibles, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nutraceutical Flexible Packaging Market Evolving Landscape
Material science advances and regulatory stringency are compressing development cycles for oxygen-barrier laminates while opening premium positioning for plastic-alternative formats that satisfy both performance and sustainability verification requirements.
Monomaterial polyethylene terephthalate films is overtaking conventional ethylene vinyl alcohol copolymer multilayers in mid-volume nutraceutical runs. Dietary supplement brands in the United States adopt these structures to streamline mechanical recycling streams without sacrificing shelf stability for gummy vitamins. The shift is overtaking legacy converter margins built on proprietary adhesive formulations and complex delamination processes.
REACH substance restriction proposals target per- and polyfluoroalkyl substances in grease-resistant coatings used on flexible packaging for oil-based softgels. The European Chemicals Agency evaluation forces reformulation of heat-seal layers before 2027 sunset dates. German and French contract packagers now specify fluorine-free alternatives in tender documents, ahead of formal mandate adoption.
Direct-to-consumer subscription fulfillment is compressing order-to-delivery expectations for single-dose sachet formats. Sports nutrition brands bypass traditional distribution warehouses, instead integrating pouch converting lines with pick-and-pack automation in regional micro-fulfillment centers. This pattern concentrates demand in United States metropolitan corridors with same-day delivery infrastructure.
Nutraceutical Flexible Packaging Market Segmentation
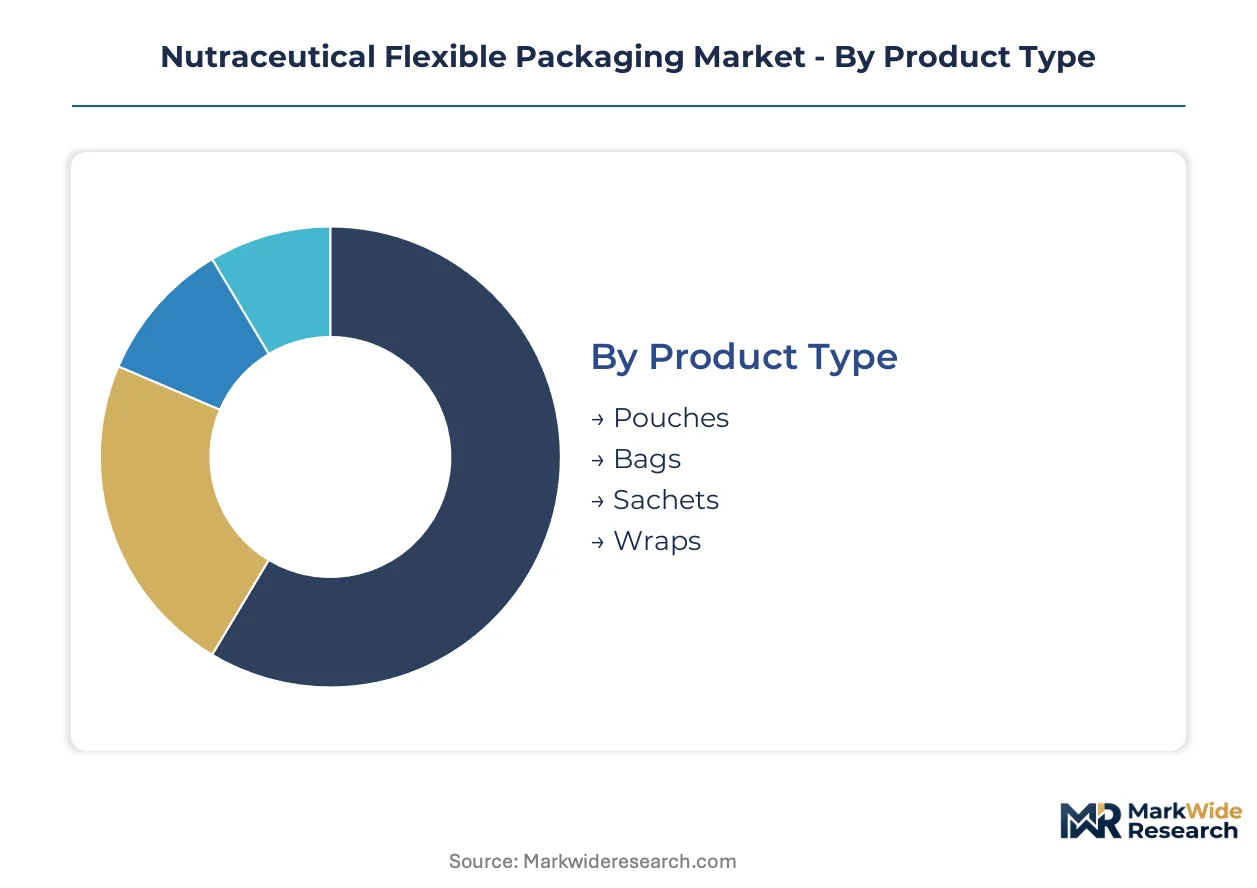
Segmentation in nutraceutical flexible packaging reveals how capital allocation, regulatory compliance, and shelf-life engineering concentrate margin capture across distinct technical specifications. Each dimension carries divergent tooling requirements and barrier performance thresholds that reshape supplier selection criteria.
Product Type:
Capital intensity escalates sharply with automation integration and barrier complexity, placing pouch and sachet lines at opposite ends of the investment spectrum.
- Pouches:Multilayer laminate structures with resealable zipper integration dominate powdered supplements and gummy vitamins. United States sports nutrition brands drive volume through stand-up formats with oxygen transmission rates below 0.1 cc per square meter per day.
- Sachets:Single-serve aluminum-laminate strips achieve sub-0.05 cc oxygen barriers for probiotic cultures. Direct-to-consumer subscription channels in metropolitan United States corridors absorb the fastest capacity additions for daily-dose personalization.
- Bags:Gusseted side-seal configurations handle bulk powder fills with reduced unit economics compared to preformed pouches.
- Wraps:Flow-wrapped formats serve cost-sensitive tablet and capsule bundling with minimal barrier specifications.
Most installed capacity flows through Pouches. Expansion is steepest in Sachets.
Material:
Raw material sourcing strategies divide converters between petroleum-dependent scale players and specialty suppliers pursuing plastic reduction certifications.
- Plastic:Polyethylene terephthalate monomaterials are displacing ethylene vinyl alcohol multilayers in mid-volume United States runs. Mechanical recycling compatibility and validated stability data from pharmaceutical-grade extrusion networks secure converter margins.
- Biodegradable:Polylactic acid and polyhydroxyalkanoate films command 15-25% price premiums among European brands responding to ECHA-guided sustainability commitments. Barrier limitations without aluminum oxide metallization restrict probiotic applications.
- Aluminum:Foil laminates maintain dominance in oxidation-sensitive omega-3 and probiotic formats requiring absolute light and oxygen exclusion.
- Paper:Kraft-paper hybrid formats with bio-based moisture coatings target plastic reduction narratives while preserving shelf stability for dry powder supplements.
Plastic substrates carry the heaviest capital equipment burden. Biodegradable lines are climbing the fastest as European EPR mandates tighten.
Closure Type:
End-use consumption patterns dictate closure engineering, with resealability and child-resistance features driving differentiation in premium supplement positioning.
- Zip Lock:Press-to-close interlocking strips enable multi-dose convenience for protein powders and pre-workout blends in United States convenience retail. Tooling amortization favors high-volume runs above 10 million units annually.
- Heat Seal:Induction and impulse sealing systems dominate pharmaceutical-owned supplement lines requiring ISO 15378-validated integrity. FDA 21 CFR Part 177 adhesive migration testing extends qualification timelines.
- Spout:Fitment insertion equipment demands specialized rotary placement systems for liquid nutraceutical dispensing.
- Screw Cap:Rigid closure integration with flexible bodies serves family-size formats in mass-market retail channels.
Heat Seal infrastructure represents the largest installed base. Zip Lock capacity is expanding most quickly alongside sports nutrition pouch demand.
End User:
Customer certification requirements create tiered supplier qualification barriers, with pharmaceutical-owned lines imposing the steepest technical and audit standards.
- Dietary Supplements:Sports nutrition and personalized vitamin subscription services in the United States absorb premium flexible packaging volumes. Brands specify validated stability data and FDA-compliant laminate specifications.
- Pharmaceuticals:Pharmaceutical-owned supplement lines mandate ISO 15378 certification and 18-24 month adhesive migration validation protocols. Qualified supplier scarcity benefits certified contract manufacturers with established audit experience.
- Food Industry:Functional food crossovers with nutraceutical claims operate under less stringent barrier specifications than pharmaceutical grades.
- Others:Veterinary nutraceuticals and cosmetic-nutraceutical hybrids occupy niche specification bands with limited dedicated capacity.
Dietary Supplements channel the majority of qualified capacity. Pharmaceuticals are gaining share fastest as pharmaceutical conglomerates acquire supplement brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates the highest flexible packaging volumes for nutraceutical applications, with metropolitan corridors from New Jersey to Southern California hosting integrated converting and fulfillment infrastructure for sports nutrition and personalized vitamin subscription services.
United States
Sports nutrition brands and direct-to-consumer vitamin subscriptions absorb premium pouch and sachet capacity. FDA 21 CFR Part 177 governs indirect food contact substances in laminate adhesives, forcing 18-24 month validation protocols. The New Jersey-to-Philadelphia corridor anchors pharmaceutical-grade extrusion operations supplying FDA-compliant dietary supplement specifications.
Germany
Contract packagers for European supplement brands drive demand for kraft-paper hybrid formats with bio-based moisture coatings. The EU F-Gas Regulation accelerates phase-down of hydrofluorocarbon foaming agents in cold-chain insulation films. The Rhine-Ruhr industrial cluster hosts converters re-engineering multilayer barrier films to meet escalating recycled content thresholds under the EU Packaging and Packaging Waste Regulation.
China
Domestic dietary supplement consumption and export-oriented contract manufacturing expand flexible packaging throughput. SAMR oversight of food contact materials intensifies testing requirements for laminate structures. The Yangtze River Delta manufacturing belt concentrates blown film operations serving both domestic nutraceutical brands and international pharmaceutical-owned supplement lines.
India
Ayurvedic and protein supplement categories drive pouch adoption in urban retail and e-commerce channels. FSSAI regulations on food-grade packaging materials tighten compliance burdens for imported laminate structures. The Mumbai-Pune industrial corridor hosts emerging converting capacity targeting mid-volume dietary supplement runs with cost-optimized polyethylene terephthalate monomaterials.
United Kingdom
Plastic reduction narratives among premium supplement brands accelerate specification of fiber-based flexible formats. REACH substance restriction proposals on per- and polyfluoroalkyl substances force reformulation of grease-resistant coatings before 2027 sunset dates. The Midlands manufacturing region anchors contract packaging operations serving algorithm-compounded personalized vitamin regimens.
Nutraceutical Flexible Packaging Market Competitive Landscape
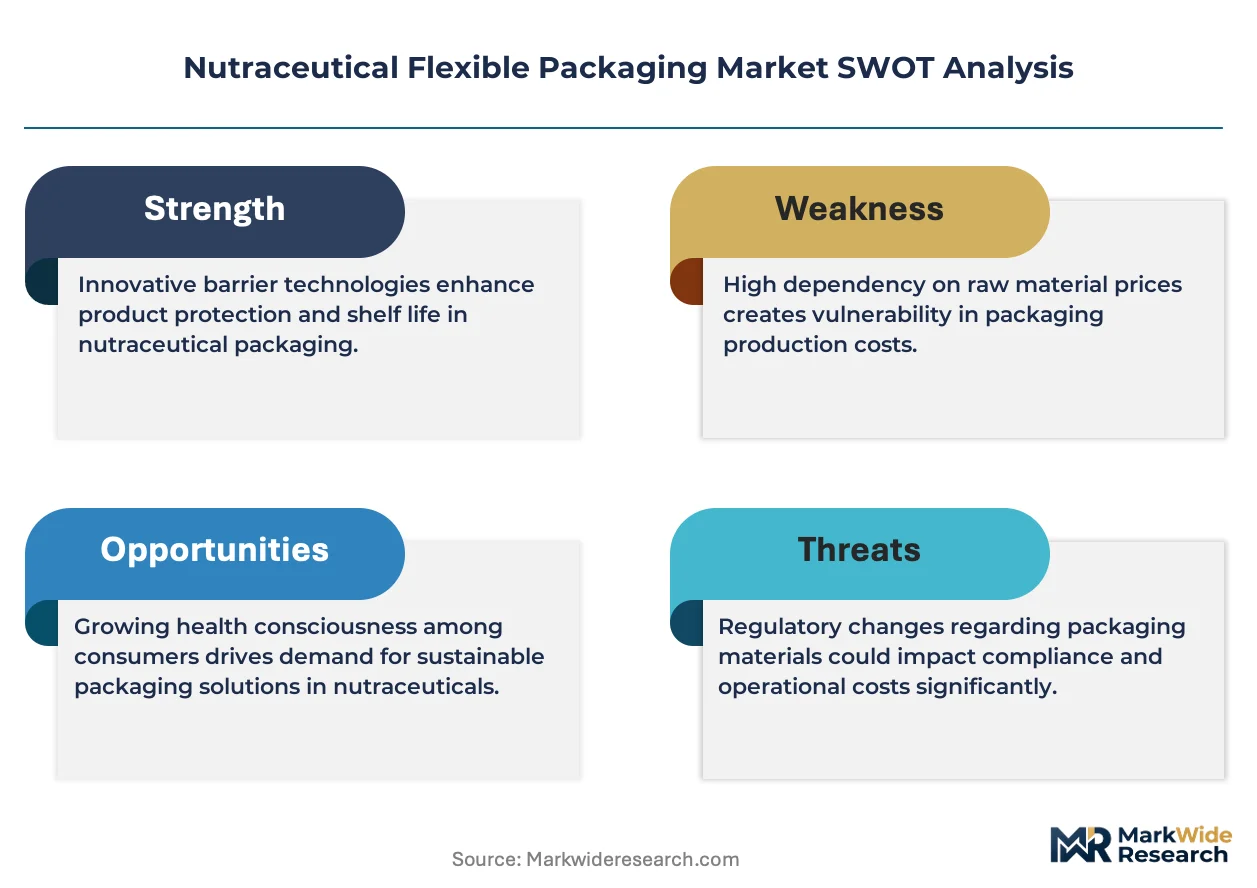
Capacity expansion dominates the current landscape as converters race to install pharmaceutical-grade extrusion lines before qualified supplier scarcity worsens. The market structure consolidates around three integrated North American players with FDA audit experience, while European and Asian specialists compete on sustainability certifications and cost-optimized monomaterials. Two strategic archetypes prevail: scale-driven integrated converters with global film extrusion networks, and niche specialists commanding price premiums for plastic-alternative formats. M&A activity and geographic licensing agreements represent the dominant competitive moves, with pharmaceutical conglomerate acquisitions of supplement brands driving ISO 15378 certification requirements downstream.
Among integrated global converters, Amcor plc and Berry Global exemplify the scale-driven archetype with established pharmaceutical-grade laminate supply networks. Mondi Group occupies a position within the sustainability-specialist tier, representing converters competing on fiber-based and plastic-reduction formats for European brand owners. These three anchors illustrate how competitive positioning stratifies between volume-scale FDA compliance and premium sustainability narratives.
| Leading Market Players |
|---|
| ProAmpac |
| Alpha Packaging |
| Amcor plc |
| Sonoco Products Company |
| Graham Packaging Company |
| Berry Global |
| Flex-pack |
| Constantia Flexibles |
| Mondi Group |
| Others |
Value Network & Pricing Analysis
Pharmaceutical-grade polyethylene terephthalate resin costs cascade through three pricing tiers as converters pass FDA validation expenses downstream to dietary supplement brands and pharmaceutical-owned lines.
Pricing Analysis
Input-cost pass-through from post-consumer recycled polyethylene feedstock drives pricing stratification across premium, standard, and economy tiers. ISO 15378 certification commands 15-25% premiums over FDA-compliant laminates lacking medicinal-grade validation. Pricing pressure stems from recycled resin quality variance complicating oxygen barrier coextrusion. Mid-volume dietary supplement brands exhibit highest price sensitivity, while pharmaceutical conglomerates absorb certification premiums without volume negotiation.
Supply Chain Analysis
Specialty adhesive and metallized film supply rests on German chemical producers, Japanese foil converters, and United States blown film operators with FDA audit experience. Pharmaceutical-grade extrusion capacity clusters in the New Jersey-to-Philadelphia corridor, the Rhine-Ruhr industrial cluster, and the Yangtze River Delta manufacturing belt. Single-source vulnerability concentrates among three integrated North American converters qualified for ISO 15378 supplement lines. Distribution runs through regional micro-fulfillment centers in United States metropolitan corridors with same-day delivery infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in certified contract manufacturing as pharmaceutical conglomerate acquisitions of supplement brands drive ISO 15378 qualification premiums upstream.
For Market Incumbents: Extend pharmaceutical-grade extrusion capacity ahead of qualified supplier scarcity worsening. Secure backward integration into metallized film supply to defend against Japanese foil converter concentration. Invest in FDA 21 CFR Part 177 adhesive migration validation capabilities to capture 18-24 month qualification timelines as a competitive moat.
For New Entrants and Emerging Players: Capture kraft-paper hybrid format demand from European brands seeking plastic reduction narratives without ECHA substance restriction exposure. Target German and French contract packagers specifying fluorine-free heat-seal layers ahead of 2027 REACH sunset dates. Lead with bio-based moisture coating partnerships to bypass petroleum-dependent scale player dominance.
For Investors and Strategic Acquirers: Consolidation pressure builds where pharmaceutical-grade extrusion operators with FDA audit experience command 40% wage premiums and constrain capacity expansion timelines. Five-to-ten-year viability favors converters with established mechanical recycling partnerships ahead of California and New York extended producer responsibility implementation. Watch ISO 15378 certification backlog as the inflection signal for qualified supplier scarcity pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 15378 Certification Investment | Pharmaceutical-owned supplement lines mandate medicinal-grade validation, creating qualified supplier scarcity premiums. |
| Monomaterial PET Film Conversion | United States dietary supplement brands adopt recyclable structures to streamline mechanical recycling streams. |
| Kraft-Paper Hybrid Format Development | European EPR mandates drive 15-25% price premiums for fiber-based pouches with bio-based coatings. |
| Micro-Fulfillment Center Integration | Sports nutrition brands compress order-to-delivery timelines through regional pouch converting and pick-and-pack automation. |
| Fluorine-Free Coating Reformulation | ECHA REACH proposals on per- and polyfluoroalkyl substances force heat-seal layer redesign before 2027 deadlines. |
Research Methodology
Multiple input streams — converter operations executives, dietary supplement brand procurement leads, pharmaceutical regulatory affairs directors, and flexible packaging R&D heads — were reconciled against FDA 21 CFR Part 177 filings, EU Packaging and Packaging Waste Regulation impact assessments, ECHA substance restriction proposals, and customs trade data for polyethylene terephthalate and ethylene vinyl alcohol copolymer imports. Bottom-up capacity modeling across blown film and cast film extrusion lines was triangulated with top-down demand estimation from sports nutrition and personalized vitamin subscription shipment volumes.
Data-stream reconciliation anchored volume and value outputs across the analysis window through segmentation by product type, material substrate, closure mechanism, end-user certification tier, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating EPR mandate implementation timelines, ISO 15378 certification adoption rates, and direct-to-consumer channel penetration in United States metropolitan corridors.
Recycled content threshold acceleration, adhesive migration validation timeline extensions, and pharmaceutical conglomerate acquisition activity are the dominant revision risks to modeled outputs. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Middle East and Africa Amino Acid in Dietary Supplements Market
Nutritional Supplements
Plant Sterol Supplements Market
Nutritional Supplements
China Collagen Peptides Market
Nutritional Supplements
Germany Whey Protein Market
Nutritional Supplements
Global Reishi Mushroom Extracts Market
Nutritional Supplements
Vitamin K2 Market
Nutritional Supplements
Global Oncology Nutrition Market
Nutritional Supplements
Food Grade Beta-Alanine Market
Nutritional Supplements
Global Nutraceuticals Product Market
Nutritional Supplements
Africa Beta Glucan Market
Nutritional Supplements
Bone Broth Protein Market
Nutritional Supplements
Mediterranean Metabolic Syndrome Support Ingredient Packs Market
Nutritional Supplements
Mineral Supplements Market
Nutritional Supplements
Liquid Dietary Supplements Market
Nutritional Supplements
Europe Meal Replacement Products Market
Nutritional Supplements
Andro Supplements Market