
 Middle East Protein Market | 2026-2036
Middle East Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Protein Market Foresight
Halal-certification-grade protein tiers is reorganizing procurement standards across Middle East supply chains. Almarai Company anchors dairy protein distribution through its vertically controlled cold-chain network spanning the Gulf Cooperation Council. Cargill leverages its Red Sea port-adjacent processing assets to compete in textured vegetable protein supply to Egyptian and Saudi food manufacturers. Kerry Group specializes in enzyme-modified dairy proteins for regional infant formula producers, occupying a technical niche above commodity whey suppliers.
Protein encompasses nitrogenous macromolecules composed of amino acid chains linked by peptide bonds, with biological functionality determined by tertiary structure, digestibility-corrected amino acid score, and protein efficiency ratio. The Middle East protein complex serves nutritional fortification, muscle maintenance, and metabolic enzyme production across human and animal systems. Dairy protein retains margin dominance in Saudi Arabia and the UAE due to per-capita consumption traditions and state dairy subsidies, while plant-based protein is gaining fastest in UAE retail channels driven by flexitarian urban demographics. Food processing applications command the largest volume share, though health supplements extract premium pricing from affluent consumers in Dubai and Riyadh.
SFDA in Saudi Arabia and MOHAP in the UAE enforce halal integrity and nutritional claim verification, compelling importers to maintain segregated supply chains and third-party certification. The F-Gas Regulation's Middle East analogs are pressuring cold-chain protein logistics toward lower-global-warming-potential refrigerants, raising capital requirements for distributors. Stakeholders must monitor whether Egypt's national food security authority introduces parallel halal-certification mandates that would fragment import compliance across North African and Gulf markets.
Market Dynamics
Halal-certification mandates from SFDA and MOHAP are restructuring procurement protocols across Middle East protein supply chains, forcing importers to maintain segregated logistics networks and third-party verification systems that raise operational complexity.
Growth Catalysts
- SFDA Nutritional Labeling Alignment:Saudi Arabia's tightened ingredient disclosure requirements are accelerating demand for high-grade protein isolates with verified amino acid profiles in food processing applications.
- Food Security Programs:Government-backed domestic processing capacity expansion in Saudi Arabia's Riyadh-Jeddah corridor is pulling investment toward localized whey and casein production facilities.
- Flexitarian Demographics:Urban consumer segments in Dubai and Abu Dhabi are driving retail channel growth for pea and fava bean protein isolates in functional beverages and meat analogs.
Market Restraints
- Halal Supply Chain Segregation:MOHAP and SFDA requirements for dedicated processing lines and logistics networks impose capital intensity on distributors serving both halal and conventional markets.
- Dairy Input Cost Volatility:Regional dependence on imported feed grains for dairy herds exposes whey and casein processors to global commodity price swings.
- Technical Limitation in Plant Protein Functionality:Current extrusion technologies for textured vegetable protein fail to replicate the mouthfeel and binding properties required by traditional Middle Eastern meat applications.
Strategic Opportunities
- Egyptian Processing Expansion:Port-adjacent facilities near the Suez Canal offer export positioning toward North African and Levantine markets with underdeveloped local protein manufacturing.
- Enzyme-Modified Dairy Proteins:Infant formula manufacturers across the Gulf are seeking hydrolyzed whey proteins with reduced allergenicity, creating technical differentiation opportunities above commodity suppliers.
- Cold-Chain Refrigerant Transition:F-Gas Regulation analogs pressing logistics providers toward lower-global-warming-potential systems create first-mover advantage for distributors with upgraded fleet assets.
Industry Challenges
- Halal Certification Timeline Compression:Third-party verification bodies face backlog pressures as import volumes surge, delaying product launches for manufacturers dependent on fresh certification cycles.
- Technical Talent Scarcity:Protein chemistry specialists with expertise in enzyme modification and extrusion processing command premium compensation, constraining mid-tier processor expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Protein Market |
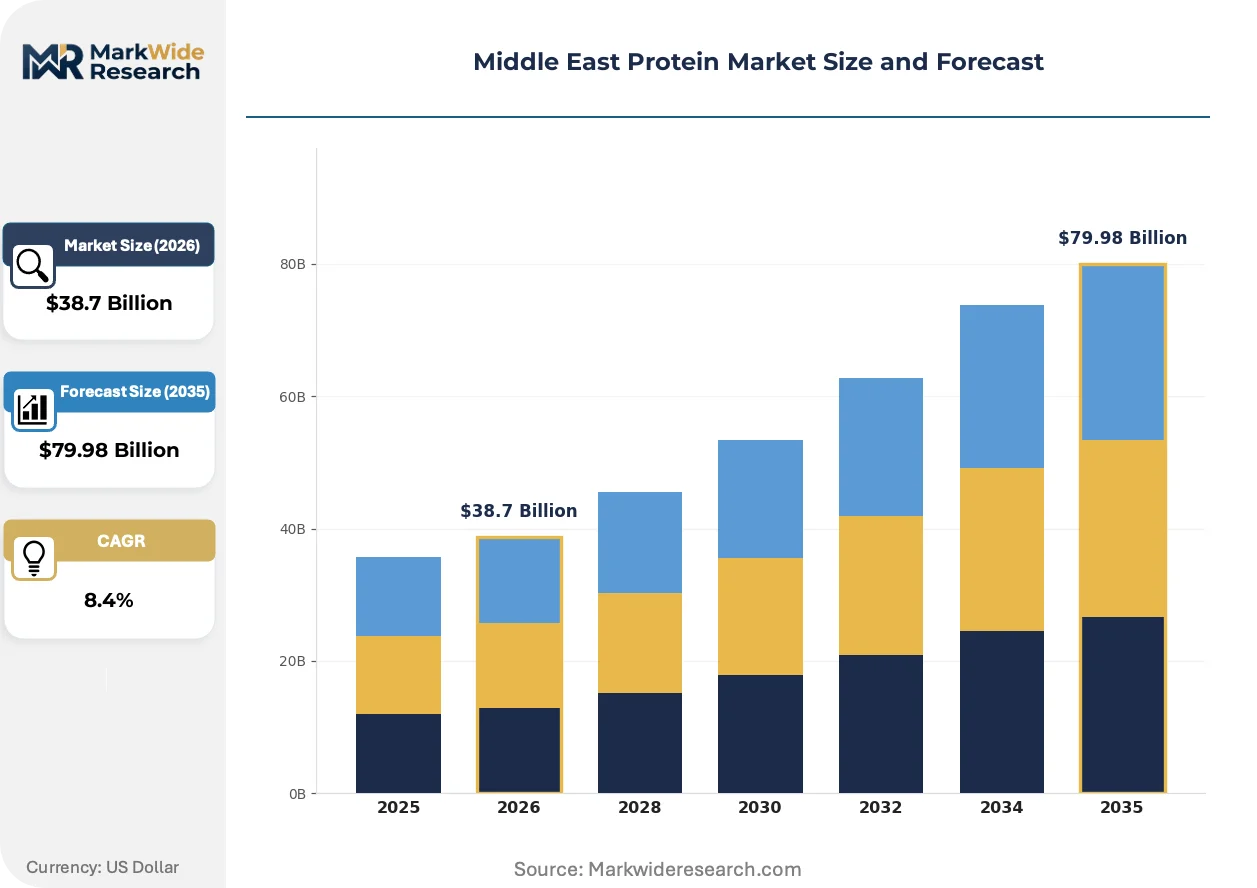
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meat, Dairy, Plant-Based, Seafood End User: Food Industry, Feed Industry, Retail, Health Supplements Distribution Channel: Online Retail, Supermarkets, Wholesalers, Convenience Stores Application: Food Processing, Nutritional Products, Dietary Supplements, Animal Feed |
| Companies Covered | DSM-Firmenich, Almarai Company, Cargill, Fonterra Co-operative Group, Nestlé, Kerry Group, BASF, MEGGLE, Archer Daniels Midland Company, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Protein Market Shifts & Advancements
Precision fermentation and cellular agriculture platforms are entering pilot phases across Gulf research institutes, while regulatory frameworks for novel protein sources remain under development by national food safety authorities.
Precision fermentation for dairy protein analogs is decomposing the traditional whey supply chain structure. Biotech startups in Abu Dhabi and Riyadh are scaling pilot facilities to produce casein and whey proteins without animal agriculture. Food manufacturers are evaluating these inputs for bakery and confectionery applications where functional properties outweigh cost premiums.
SFDA's alignment with Codex Alimentarius standards for protein quality claims is tightening permissible nutritional marketing. Manufacturers must now substantiate PDCAAS and DIAAS scores through third-party testing before packaging assertions. Infant formula and sports nutrition segments in Saudi Arabia are reformulating products to meet the elevated evidentiary threshold.
Direct procurement relationships between food manufacturers and specialized protein ingredient suppliers are displacing traditional distributor intermediaries. Large Saudi dairy processors and UAE-based meat alternative brands are establishing captive supply agreements with European and North American isolate producers. This channel compression is most visible in Dubai's free zone trading hubs where bulk importers are losing volume to contracted direct shipments.
Middle East Protein Market Segmentation
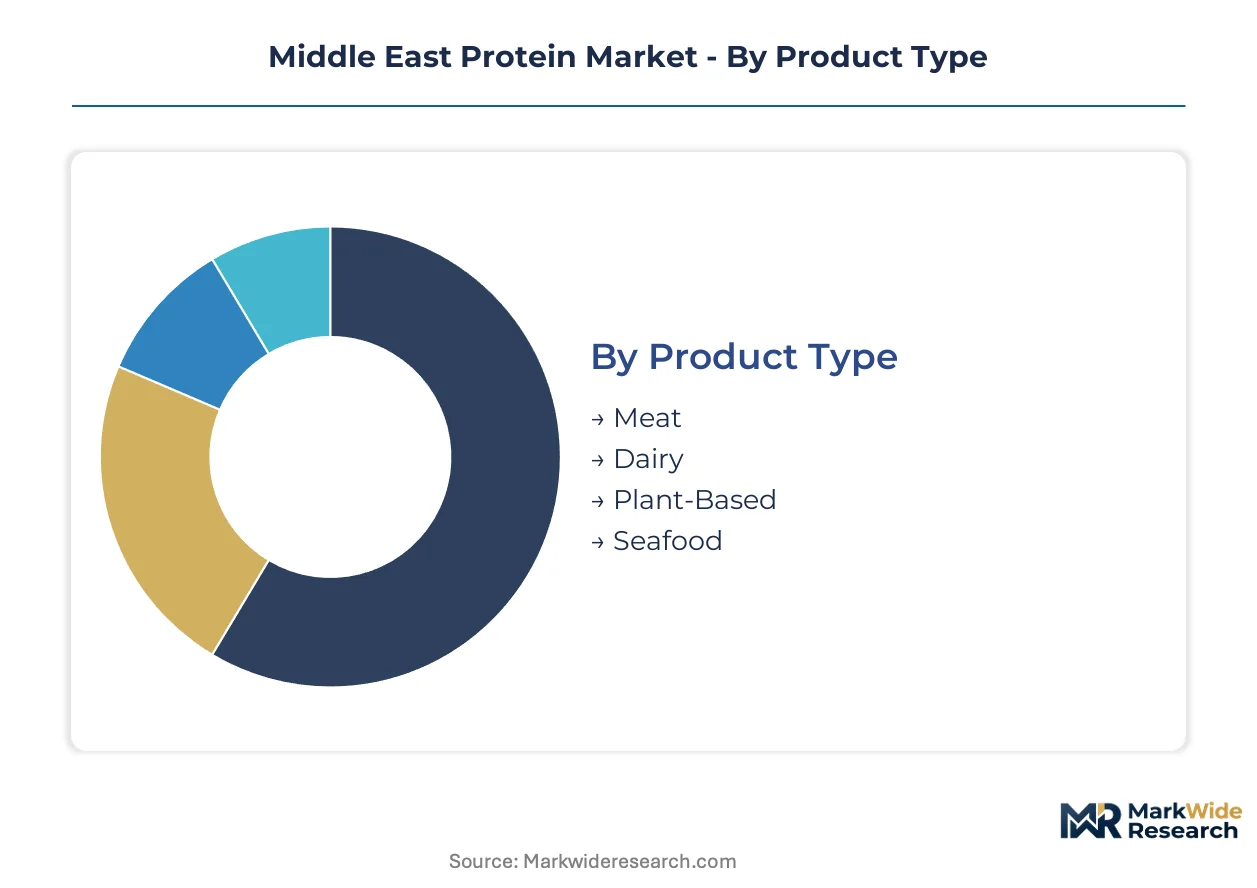
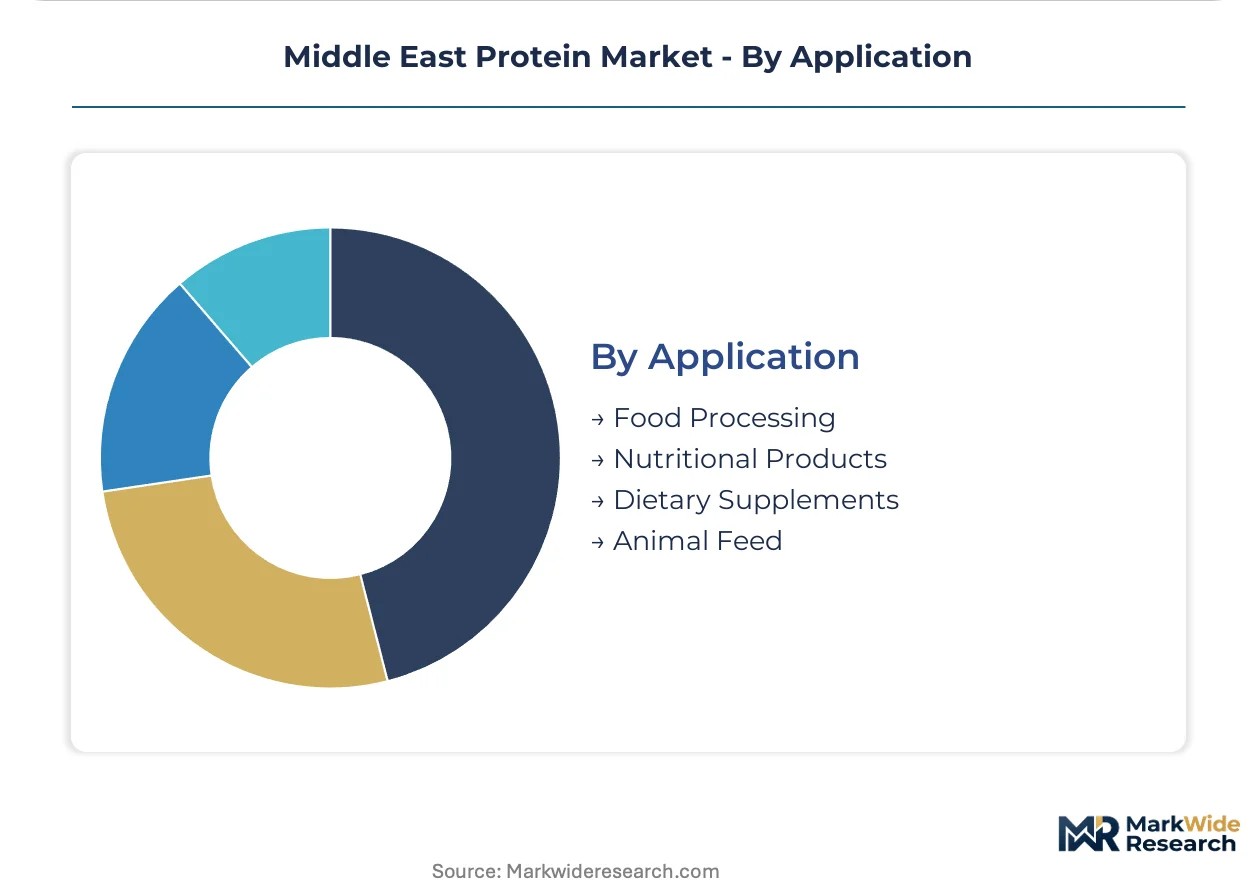
Segmentation in the Middle East protein market reflects divergent regulatory pressures and consumption patterns across halal-certified supply chains. Product categories face distinct SFDA and MOHAP compliance pathways, while distribution channels stratify around cold-chain capabilities and urban retail density.
Product Type:
SFDA's halal integrity mandates and MOHAP's nutritional labeling standards create tiered compliance burdens that reshape margin structures across protein categories.
- Dairy:Whey and casein isolates dominate Saudi procurement through state-subsidized processing infrastructure. Riyadh-Jeddah corridor facilities pull volume toward domestic whey concentrate production as food security programs expand captive supply.
- Plant-Based:Pea and fava bean proteins are gaining fastest in UAE retail channels. Dubai's flexitarian demographics and Abu Dhabi's biotech pilot facilities accelerate isolate demand for meat analogs and functional beverages.
- Meat:Traditional halal slaughter compliance dominates Gulf procurement, with segregated processing lines required for export certification.
- Seafood:Aquaculture-derived proteins from Egyptian Red Sea farms supply North African markets with lower logistics costs than distant imports.
Dairy handles the majority of throughput; plant-based is expanding most quickly on share.
End User:
Cost tier stratification separates commodity-scale buyers from premium-priced specialized segments across the value chain.
- Food Industry:Saudi dairy processors and UAE meat alternative manufacturers drive bulk isolate procurement through direct supplier contracts. SFDA-aligned nutritional claims require verified amino acid profiling for packaged goods.
- Health Supplements:Sports nutrition and infant formula extract premium pricing in Dubai and Riyadh. Hydrolyzed whey proteins with reduced allergenicity command technical premiums above commodity grades.
- Feed Industry:Poultry and aquaculture operations in Egypt and Saudi Arabia source soy and fish meal alternatives amid global commodity volatility.
- Retail:Urban supermarkets and hypermarkets in Abu Dhabi and Jeddah stock branded protein isolates for home consumption.
Food industry absorbs the largest volume share; health supplements deliver the steepest margin expansion.
Distribution Channel:
Channel selection hinges on cold-chain refrigerant compliance and last-mile urban density across Gulf metropolitan corridors.
- Supermarkets:Dubai's Majid Al Futtaim and Saudi Arabia's BinDawood anchor retail protein distribution with halal-certified segregated shelving and temperature-controlled display infrastructure.
- Wholesalers:Jebel Ali and King Abdullah Port free zones consolidate bulk imports for redistribution to Egyptian and Levantine markets.
- Online Retail:Noon and Amazon.ae expand direct-to-consumer protein isolate sales with same-day delivery in UAE urban centers.
- Convenience Stores:Limited cold-chain capacity restricts ambient protein bar and powder SKUs in smaller-format retail.
Wholesalers manage the bulk of import throughput; online retail is climbing the fastest on customer acquisition.
Application:
Application mix correlates with PDCAAS and DIAAS scoring requirements under Codex-aligned SFDA standards.
- Food Processing:Bakery and confectionery manufacturers in Saudi Arabia and the UAE reformulate with enzyme-modified dairy proteins to meet elevated evidentiary thresholds for quality claims.
- Nutritional Products:Infant formula producers across the Gulf seek hydrolyzed whey with technical specifications exceeding commodity supplier capabilities.
- Dietary Supplements:Sports nutrition brands in Dubai's free zones target affluent consumers with isolate-based formulations.
- Animal Feed:Egyptian aquaculture and Saudi poultry operations substitute imported soy with regional protein meals.
Food processing commands the dominant volume position; nutritional products are gaining share fastest on technical premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Middle East protein trade flows reflect a structural import dependency for high-grade isolates, with domestic processing capacity expanding fastest in Saudi Arabia and the UAE while Egypt positions as a re-export hub toward North African markets.
Saudi Arabia
SFDA nutritional labeling alignment and food security programs are accelerating whey concentrate production in the Riyadh-Jeddah corridor. State-subsidized dairy infrastructure pulls investment toward captive supply chains for infant formula and sports nutrition manufacturers. Domestic processors are scaling enzyme-modification capabilities to meet elevated evidentiary thresholds for quality claims.
United Arab Emirates
MOHAP's halal integrity mandates and flexitarian urban demographics in Dubai and Abu Dhabi are reorganizing procurement toward pea and fava bean isolates. Free zone trading hubs at Jebel Ali consolidate direct supplier contracts that bypass traditional distributor intermediaries. Biotech pilot facilities in Abu Dhabi are advancing precision fermentation platforms for dairy protein analogs.
Egypt
Port-adjacent processing assets near the Suez Canal offer export positioning toward Levantine and North African markets with underdeveloped local manufacturing. The national food security authority is evaluating parallel halal-certification mandates that would fragment import compliance across regional markets. Red Sea aquaculture operations supply lower-cost seafood proteins to domestic and export channels.
Qatar
Food security strategies are diversifying protein sourcing beyond traditional Gulf supply corridors toward direct contracts with European and North American isolate producers. Cold-chain infrastructure investments support premium health supplement distribution for affluent consumer segments. Regulatory alignment with GCC standardization bodies streamlines cross-border halal certification.
Middle East Protein Market Competitive Landscape
Listed leaders compete with private specialists across halal certification tiers and cold-chain capabilities, producing a bifurcated structure where scale-driven commodity suppliers face technical specialists in enzyme modification and precision fermentation. Market participants organize around three archetypes: vertically integrated dairy processors with captive distribution networks, multinational ingredient suppliers with port-adjacent regional assets, and biotech specialists advancing novel protein platforms. Dominant competitive moves include direct procurement relationships that displace distributor intermediaries, and capacity expansion in enzyme-modified dairy proteins for infant formula applications.
Within the vertically integrated tier, Almarai Company exemplifies the Gulf-based processor archetype with controlled cold-chain networks spanning the GCC. Cargill and Kerry Group represent multinational ingredient suppliers leveraging regional processing assets and technical specialization respectively. DSM-Firmenich occupies a position bridging commodity supply and precision fermentation innovation for next-generation protein platforms.
| Leading Market Players |
|---|
| DSM-Firmenich |
| Almarai Company |
| Cargill |
| Fonterra Co-operative Group |
| Nestlé |
| Kerry Group |
| BASF |
| MEGGLE |
| Archer Daniels Midland Company |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Saudi dairy processors and European whey concentrate suppliers lock in both supply access and price visibility across the Riyadh-Jeddah corridor. These arrangements insulate domestic infant formula manufacturers from spot market volatility in global dairy commodities while embedding halal-certification costs into contracted tiers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in Middle East protein procurement. Price differentiation hinges on halal-certification grade and volume scale, with SFDA-verified isolates commanding substantial premiums over conventional grades. Pricing pressure stems from feed grain import costs that transmit volatility into domestic whey production. Small-scale health supplement distributors exhibit the highest price sensitivity, while multinational infant formula producers absorb premiums for technical-grade hydrolyzed proteins.
Supply Chain Analysis
Container availability constraints on Asia-Gulf trade lanes are elevating inbound logistics costs for pea and fava bean isolate shipments into Jebel Ali. Geographic supply concentration centers on New Zealand and Australia for dairy proteins, Canada and France for pea isolates, and India for soy derivatives. Raw material dependencies encompass imported feed grains for regional dairy herds, specialized enzyme stocks for hydrolysis processing, and high-purity nitrogen for protein extraction. Single-source vulnerability pervades precision fermentation input supply. Distribution runs through vertically integrated dairy processors with captive cold-chain networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat structure where regulatory entrenchment around halal certification creates persistent barriers to unqualified entrants. SFDA and MOHAP mandates impose switching costs that cement incumbent positions.
For Market Incumbents: Consolidate procurement relationships through backward integration into Red Sea port-adjacent processing assets. Expand enzyme-modification capacity in the Riyadh-Jeddah corridor to capture technical premiums from infant formula reformulation. Precision fermentation startups threaten traditional whey supply structures; preemptive capacity reservation with biotech pilot facilities in Abu Dhabi secures optionality. For New Entrants and Emerging Players: Anchor in Egyptian aquaculture-derived protein segments where halal-certification mandates remain under development. Target port-adjacent processing for Levantine re-export markets with lower incumbent density. Direct supplier contracts with Dubai free zone meat alternative brands bypass entrenched distributor networks. For Investors and Strategic Acquirers: Capital is best deployed toward enzyme-modification specialists with existing SFDA verification and captive hospital channel access. Long-term viability rests on technical differentiation above commodity whey supply. Watch for Egypt's national food security authority introducing parallel halal-certification mandates as the inflection signal for compliance fragmentation across North African markets.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Investment | SFDA verification unlocks Saudi Arabia's state-subsidized dairy procurement channels. |
| Precision Fermentation Scale-Up | Abu Dhabi pilot facilities decompose traditional animal agriculture supply structures. |
| Port-Adjacent Processing Expansion | Suez Canal positioning captures North African re-export volume with lower logistics costs. |
| Direct Supplier Contracting | Dubai free zone manufacturers bypass traditional distributor intermediaries for isolate procurement. |
| Cold-Chain Refrigerant Transition | F-Gas Regulation analogs favor distributors with lower-global-warming-potential fleet assets. |
Research Methodology
Desk research of customs trade databases, SFDA regulatory filings, and GCC agricultural ministry reports preceded structured interviews with dairy processing plant managers, infant formula procurement leads, halal certification body technical directors, and cold-chain logistics operators. Primary fieldwork across Riyadh, Dubai, and Cairo validated secondary data on import volumes and processing capacity. Bottom-up facility-level capacity estimates triangulated against top-down trade flow analysis.
Variance decomposition across product type, end-user segment, distribution channel, and application dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segmented volume trajectories incorporated dairy herd expansion rates under Saudi food security programs, flexitarian demographic shifts in UAE urban centers, and precision fermentation pilot scale-up timelines. Feed grain import price indices and halal-certification body capacity constraints fed industry-specific forecast inputs.
Underlying assumptions cover sustained SFDA-MOHAP regulatory alignment, stable GCC-Swiss dairy trade relations, and gradual Egyptian halal-certification mandate development, with deviation risk concentrated in feed commodity volatility and novel protein regulatory approval timelines. Practitioners should keep alternative scenarios live as Egypt's certification stance and precision fermentation cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Oyster Shell Calcium Market
Nutritional Supplements
Asia-Pacific Arachidonic Acid Market
Nutritional Supplements
Natural Colostrum Supplements Market
Nutritional Supplements
Sleep Gummies Market
Nutritional Supplements
Europe Dietary Supplements Market
Nutritional Supplements
Garcinia Cambogia Extract Market
Nutritional Supplements
Europe Botanical Supplements Market
Nutritional Supplements
Coral Calcium Market
Nutritional Supplements
Complete Nutrition Products Market
Nutritional Supplements
Green Tea Supplements Market
Nutritional Supplements
South America Whey Protein Market
Nutritional Supplements
Prickly Pear Seed Oil Nutricosmetic Bases Market
Nutritional Supplements
Horehound Supplement Market
Nutritional Supplements
Bone Supplements Market
Nutritional Supplements
Japan Dietary Supplements Market
Nutritional Supplements
Sea Moss Supplements Market