
 Chewable Energy Tablet Market | 2026-2036
Chewable Energy Tablet Market Size, Share, and Industry Trends Forecast 2026-2036
Chewable Energy Tablet Market Insights
Premium caffeine-free formulations is unwinding legacy commodity positioning in chewable energy tablets. Glanbia leverages its dairy-derived protein infrastructure to anchor sports nutrition applications. PepsiCo competes through convenience retail penetration and mass-market brand recognition. NOW Foods specializes in clean-label ingredient sourcing for health-conscious consumers.
Chewable energy tablets are compressed oral-delivery systems containing caffeine, B-vitamins, amino acids, or herbal extracts in a rapidly dissolving matrix designed for sublingual absorption and immediate effect. Manufacturing employs direct compression or wet granulation to preserve thermolabile actives while achieving disintegration under 30 seconds. Caffeine-based and electrolyte-infused product types command the largest volume pools due to established efficacy data and athlete familiarity. Sports nutrition and cognitive enhancement applications are capturing margin expansion as consumers trade up from sugary energy drinks to portable, dose-controlled formats.
FDA oversees caffeine labeling and GRAS determinations for stimulant-containing supplements in the United States, while EFSA enforces maximum caffeine thresholds and novel food assessments across European markets. China's SAMR requires blue-hat registration for functional food-health products, creating a bifurcated compliance burden for multinational suppliers. Stakeholders must monitor evolving stimulant caps and novel ingredient approval pathways as regulatory divergence between major markets intensifies formulation complexity and regional portfolio fragmentation.
Market Dynamics
Regulatory divergence between FDA, EFSA, and SAMR caffeine thresholds is fragmenting formulation portfolios and forcing manufacturers to maintain parallel product lines for major markets. This compliance burden concentrates competitive advantage with multinationals possessing dedicated regulatory affairs infrastructure.
Growth Catalysts
- Sublingual absorption technology:Compressed matrix designs achieving sub-30-second disintegration are capturing athlete segments seeking faster onset than liquid energy drinks.
- China's blue-hat registration pathway:SAMR's functional food-health product framework is legitimizing chewable formats in Asia's largest consumer market.
- Airport and transit retail expansion:C-store penetration in Germany and United States transportation hubs is normalizing impulse purchase of portable energy formats.
Market Restraints
- Caffeine input cost volatility:Synthetic caffeine supply from Chinese API manufacturers faces periodic export restriction uncertainty.
- Thermolabile active degradation:B-vitamin and herbal extract stability during wet granulation compresses manufacturing yield rates.
- Energy drink substitution threat:Established RTD brands with sunk distribution investments maintain shelf-space dominance in mass retail.
Strategic Opportunities
- India's underpenetrated fitness sector:FSSAI's emerging sports nutrition guidelines create first-mover positioning for clean-label entrants.
- Cognitive enhancement pivot:L-theanine and nootropic stacking applications are opening white space beyond traditional athletic use cases.
- Direct-to-clinic channel innovation:Sports medicine and corporate wellness programs represent high-margin institutional procurement avenues.
Industry Challenges
- Formulation chemist talent scarcity:Rare expertise in rapid-disintegration matrices with thermolabile stability commands premium compensation.
- Dual-registration timeline compression:Parallel FDA GRAS and EFSA novel food assessments extend time-to-market for innovative actives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chewable Energy Tablet Market |
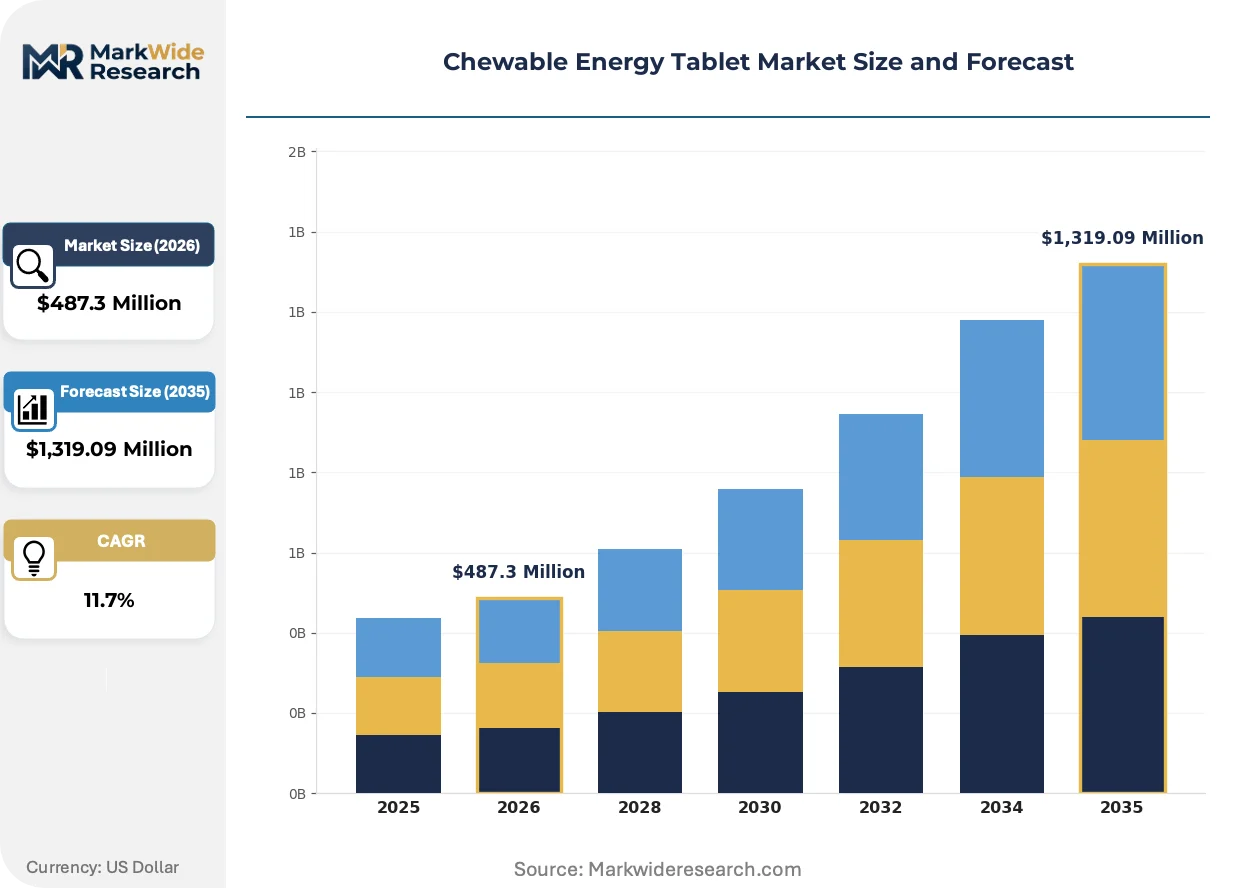
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamin-Enriched, Caffeine-Based, Electrolyte-Infused, Herbal Extract, Amino Acid, Natural Sweetener Application: Sports Nutrition, Cognitive Enhancement, Weight Management, Endurance Support, Immunity Boost, Stress Relief End User: Athletes, Students, Office Employees, Military Personnel, Outdoor Adventurers, Seniors Distribution Channel: Retail Pharmacies, E-Commerce Platforms, Fitness Centers, Health Stores, Convenience Outlets, Direct Sales |
| Companies Covered | Glanbia, Herbalife Nutrition, PepsiCo, Amway, GNC Holdings, Abbott, Nature’s Bounty, NOW Foods, Vitabiotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chewable Energy Tablet Market Trends and Innovations
Delivery system miniaturization and clean-label ingredient substitution are compressing legacy formulation paradigms. Manufacturers now compete on absorption speed and label transparency rather than caffeine dosage alone.
Effervescent-to-chewable format migration is miniaturizing packaging footprints and reducing shipping costs for direct-to-consumer channels. Sports nutrition subscription services are adopting these tablets as anchor products in monthly replenishment boxes. The structural consequence is collapsing minimum order quantities and enabling micro-brand entry.
EFSA's novel food assessment timelines are extending approval windows for botanical extracts and fermented amino acids. European manufacturers are responding by prioritizing GRAS-affirmed ingredients with established safety dossiers. This regulatory friction is diverting R&D investment toward synthetic analogs with clearer approval pathways.
Corporate procurement departments are unbundling energy drink vending contracts in favor of subsidized chewable tablet dispensers. Facility managers in United States tech campuses and German manufacturing plants are piloting these programs to reduce sugar exposure liability. The shift is most visible in employer wellness mandates requiring portable, dose-controlled stimulant options.
Chewable Energy Tablet Market Segmentation
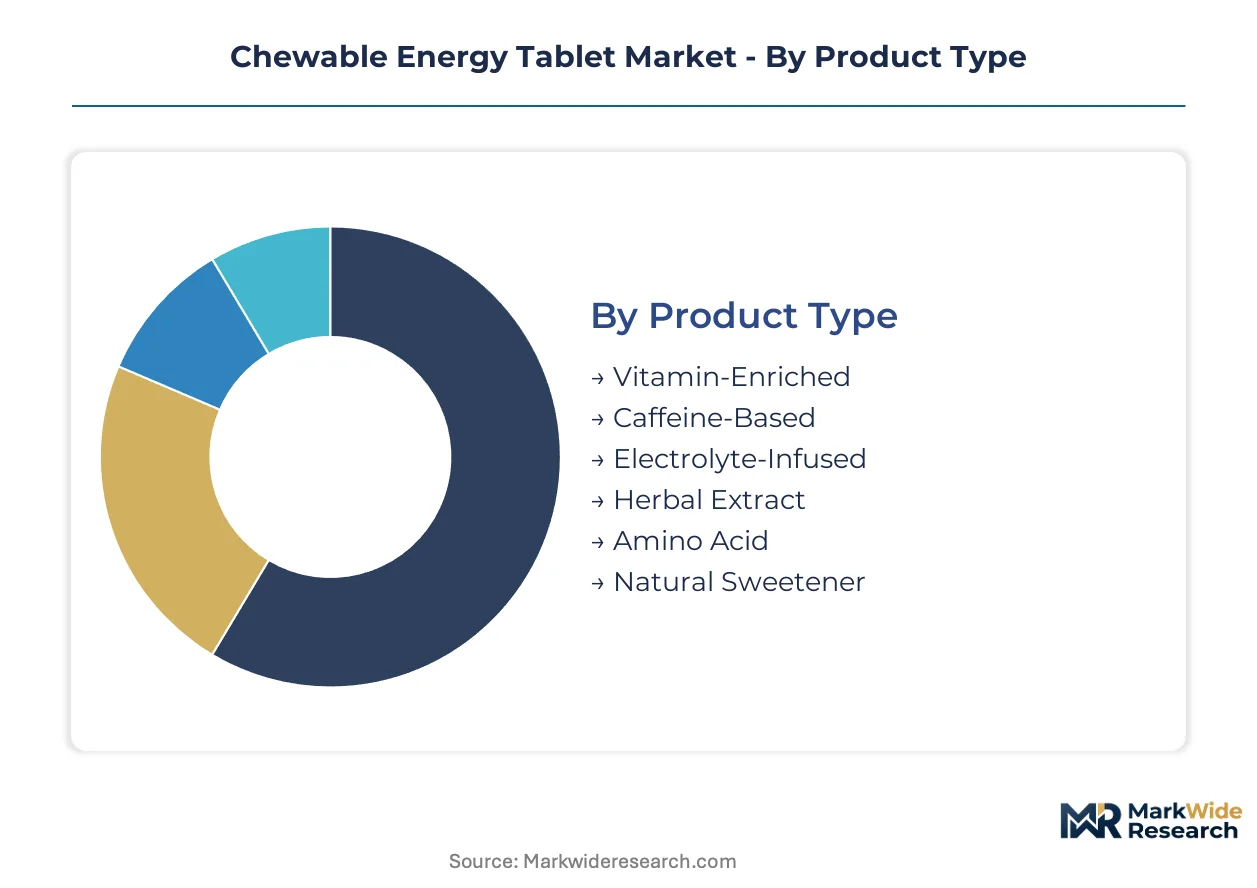
Chewable energy tablets fragment across formulation chemistry, use case specificity, and channel access economics. Manufacturers must align R&D investment with segment-specific absorption speed requirements and regulatory compliance burdens.
Product Type:
Caffeine-based and electrolyte-infused formats dominate United States and German export volumes, while vitamin-enriched variants concentrate in domestic Chinese consumption under SAMR blue-hat registration.
- Caffeine-Based:Compressed matrices deliver 50-200mg caffeine doses with sub-30-second buccal disintegration. Demand clusters with pre-workout protocols in United States CrossFit affiliates and German Bundesliga training facilities, constrained by FDA and EFSA stimulant caps that force regional formulation divergence.
- Electrolyte-Infused:Sodium-potassium matrices target thermoregulatory support without diuretic loading. Marathon runners in Boston and Berlin constitute the core install base, with summer heat waves driving acute replenishment cycles.
- Vitamin-Enriched:B-complex and D3 fortification for daily micronuturance.
- Herbal Extract:Ginseng and ashwagandha formulations for adaptogenic positioning.
- Amino Acid:BCAA and beta-alanine matrices for muscle protein synthesis signaling.
- Natural Sweetener:Stevia and monk fruit substitution for sugar-free labeling claims.
Caffeine-based holds the largest share; momentum sits with electrolyte-infused as endurance sports participation climbs fastest.
Application:
Cost tiering separates premium nootropic stacks from commodity energy replacement, with sports nutrition commanding formulation sophistication and cognitive enhancement driving margin expansion.
- Sports Nutrition:Pre-, intra-, and post-exercise timing protocols with electrolyte-carbohydrate co-delivery. United States collegiate athletic departments and German Olympic training centers standardize procurement around NSF Certified for Sport specifications.
- Cognitive Enhancement:L-theanine, tyrosine, and choline bitartrate stacking for sustained attention. Silicon Valley tech campuses and London financial trading floors pilot corporate dispensing programs.
- Weight Management:Thermogenic and appetite suppression positioning.
- Endurance Support:Ultra-distance event pacing with gradual caffeine release.
- Immunity Boost:Zinc and vitamin C fortification for travel-related consumption.
- Stress Relief:GABA and L-theanine combinations for cortisol modulation.
Sports nutrition captures the deepest volume; cognitive enhancement shows the steepest expansion trajectory as employer wellness mandates proliferate.
End User:
Volume concentrates with institutional procurement channels serving athletes and military personnel, while students and office employees drive direct-to-consumer subscription growth.
- Athletes:Dose-precision requirements across weight-class sports and anti-doping compliance. NCAA programs and Ironman competitors maintain the strictest third-party certification standards.
- Office Employees:Afternoon energy replacement without coffee disruption. Manhattan and Frankfurt finance districts show highest per-capita consumption of caffeine-free variants.
- Students:Exam-period acute demand with price sensitivity.
- Military Personnel:Operational readiness specifications with shelf-stability requirements.
- Outdoor Adventurers:Ultralight backpacking and expedition formats.
- Seniors:B12 absorption support with swallowing difficulty accommodation.
Athletes anchor procurement volume; office employees are gaining share fastest through employer-subsidized dispensing.
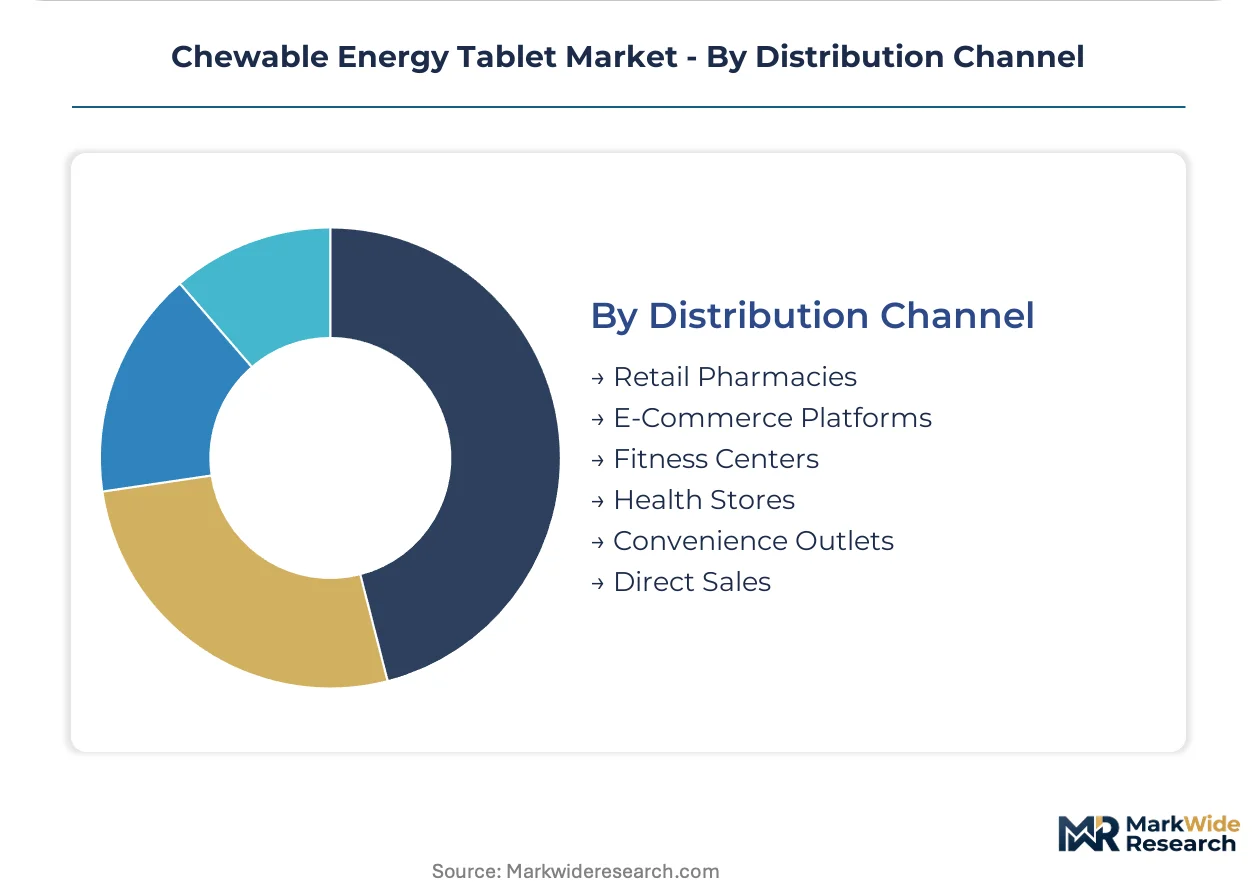
Distribution Channel:
Channel margin structures vary threefold, with fitness centers capturing highest per-unit economics and e-commerce platforms compressing customer acquisition costs through subscription bundling.
- E-Commerce Platforms:Direct-to-consumer subscriptions with flavor rotation and auto-replenishment algorithms. Amazon and specialized sports nutrition sites dominate United States and German markets, while Tmall and JD.com control Chinese access.
- Fitness Centers:Point-of-sale impulse placement with trainer endorsement. Equinox and Life Time in the United States, McFit in Germany, and SuperMonkey in China maintain exclusive brand partnerships.
- Retail Pharmacies:Pharmacist consultation attachment for senior and clinical positioning.
- Health Stores:Clean-label curation for ingredient-conscious consumers.
- Convenience Outlets:Airport and transit hub single-serve formats.
- Direct Sales:Multi-level marketing with personalized dosing protocols.
E-commerce platforms hold the largest share; fitness centers concentrate momentum through trainer-mediated trial conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chewable energy tablet manufacturing clusters around sports nutrition infrastructure and functional food regulatory pathways. Demand intensity tracks fitness sector maturity and employer wellness program adoption across national markets.
United States
Fitness center penetration and corporate campus dispensing programs drive procurement volume. FDA caffeine labeling requirements and GRAS determinations shape formulation standards. CrossFit affiliates in Austin and collegiate athletic departments in California standardize around NSF Certified for Sport specifications.
Germany
Bundesliga training facilities and endurance event participation anchor electrolyte-infused demand. EFSA maximum caffeine thresholds and novel food assessments constrain stimulant-based portfolios. Berlin and Munich fitness chains pilot employer-subsidized dispensing programs for manufacturing sector workers.
China
SAMR blue-hat registration legitimizes functional food-health positioning for domestic brands. SuperMonkey fitness studios in Shanghai and Beijing drive trainer-mediated trial conversion. Pearl River Delta contract manufacturers supply compressed matrix capacity for export markets.
India
FSSAI sports nutrition guideline development creates first-mover positioning for clean-label entrants. Marathon participation growth in Mumbai and Bangalore drives acute replenishment demand. Domestic pharmaceutical manufacturers leverage API infrastructure for caffeine sourcing.
United Kingdom
City of London trading floors and tech campuses pilot cognitive enhancement dispensing programs. MHRA borderline product classifications create compliance complexity for stimulant-containing formats. Manchester and Birmingham fitness chains expand private-label chewable ranges.
Chewable Energy Tablet Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics. Dairy-derived protein specialists and beverage multinationals occupy distinct capability zones with limited direct overlap. Three archetypes dominate: sports nutrition pure-plays with certification infrastructure, mass-market CPG conglomerates with retail penetration, and direct-sales operators with personalized dosing protocols. Capacity expansion and portfolio diversification represent the dominant competitive moves as participants seek cross-archetype positioning.
Within the sports nutrition tier, Glanbia and NOW Foods exemplify divergent sourcing strategies—one anchored in dairy-derived protein infrastructure, the other in clean-label ingredient curation. PepsiCo occupies the mass-market convenience vector through retail shelf-space dominance. These three represent the structural fault lines between premium certification-driven positioning and commodity impulse-purchase economics.
| Leading Market Players |
|---|
| Glanbia |
| Herbalife Nutrition |
| PepsiCo |
| Amway |
| GNC Holdings |
| Abbott |
| Nature's Bounty |
| NOW Foods |
| Vitabiotics |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts for synthetic caffeine API lock in both supply access and price visibility for United States and German manufacturers, insulating procurement teams from Chinese export restriction volatility while compressing margin flexibility for spot-market buyers.
Pricing Analysis
EFSA and FDA caffeine thresholds dictate the pricing tier structure across European and North American markets. Three-tier pricing structure across premium, standard, and economy levels separates NSF Certified for Sport formulations from conventional dietary supplements and private-label commoditized tablets. Cost compression in economy tiers is intensifying because Chinese API manufacturers face periodic export license uncertainty. Students and price-sensitive direct-to-consumer subscribers exhibit highest price sensitivity, while collegiate athletic departments and military procurement show lowest sensitivity due to compliance mandates.
Supply Chain Analysis
China and India anchor global synthetic caffeine API production, with Pearl River Delta contract manufacturers supplying compressed matrix capacity for export markets. Formulation draws from caffeine anhydrous, B-vitamin premixes, and rapid-disintegration excipients as core inputs. Single-source vulnerability concentrates in Chinese API supply, where export restriction announcements trigger acute procurement scrambling. Distribution runs through direct-to-consumer e-commerce platforms and fitness center point-of-sale networks as dominant downstream structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chewable energy tablets function as a service-attach opportunity where subscription-based flavor rotation and auto-replenishment algorithms expand faster than standalone hardware transactions.
For Market Incumbents: Fortify regulatory affairs infrastructure to manage parallel FDA GRAS and EFSA novel food assessment timelines, compressing time-to-market for innovative actives. Deepen backward integration into dairy-derived protein and clean-label ingredient sourcing to defend against commodity spot-price volatility. Certification investment in NSF Certified for Sport and blue-hat registration capabilities anchors channel control against emerging clean-label entrants. For New Entrants and Emerging Players: Differentiate on cognitive enhancement stacking with L-theanine and nootropic combinations, targeting underpenetrated employer wellness dispensing programs in United States tech campuses and German manufacturing plants. India's FSSAI guideline development creates the most penetrable geography for first-mover clean-label positioning. Direct-to-clinic channel innovation through sports medicine partnerships offers the strongest go-to-market angle for premium margin capture. For Investors and Strategic Acquirers: Sports nutrition pure-plays with dedicated certification infrastructure and established trainer-mediated trial conversion represent the highest-conviction acquisition target archetype. Long-term viability hinges on regulatory divergence management capability and subscription retention economics rather than commodity volume scale. The signal to watch is corporate wellness mandate proliferation accelerating employer-subsidized dispensing program adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Blue-Hat Registration Investment | SAMR approval unlocks China's functional food-health product channel for domestic brand legitimacy. |
| Subscription Platform Integration | Auto-replenishment algorithms with flavor rotation compress customer acquisition costs for micro-brands. |
| Certification Infrastructure Expansion | NSF Certified for Sport and Informed Sport accreditations secure collegiate and Olympic procurement channels. |
| Direct-to-Clinic Channel Development | Sports medicine and corporate wellness programs represent high-margin institutional procurement avenues. |
| Nootropic Stack Formulation | L-theanine and adaptogenic combinations open white space beyond traditional athletic use cases. |
Research Methodology
Operator-level perspectives from formulation chemists, regulatory affairs directors, fitness center procurement managers, and sports nutrition brand managers anchored the qualitative base. Primary interviews combined with secondary validation from FDA GRAS notices, EFSA novel food assessment databases, SAMR blue-hat registration filings, and customs trade records. Bottom-up segment sizing and top-down macro constraint triangulation ensured cross-verification.
Sensitivity analysis around caffeine input cost volatility and regulatory approval timeline compression informed the analytical framework across the analysis window. Segmentation dimensions modeled include formulation chemistry, use case specificity, end user archetype, and channel access economics. CAGRs derived from historical volume trajectories and penetration elasticity assumptions, with specific inputs from endurance sports participation growth and employer wellness mandate adoption curves.
Material uncertainties — stimulant cap revisions, API export restrictions, and novel ingredient approval delays — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and fitness sector participation trends. Recalibration cycles align with material shifts in caffeine threshold regulations and corporate wellness program proliferation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Middle East and Africa Nutraceutical Excipients Market
Nutritional Supplements
Japan Protein Market
Nutritional Supplements
Calcium Malate Market
Nutritional Supplements
Postbiotic Supplements Market
Nutritional Supplements
Global Reishi Mushroom Extracts Market
Nutritional Supplements
Global Liver Health Supplements Market
Nutritional Supplements
Longevity and Anti-Aging Brain Health Supplements Market
Nutritional Supplements
Weight Loss Supplements Market
Nutritional Supplements
Indonesia Beauty Supplements Market
Nutritional Supplements
Global General Well-Being Dietary Supplements Market
Nutritional Supplements
Royal Jelly Market
Nutritional Supplements
Vitamins Gummies Market
Nutritional Supplements
Fish Collagen Peptides Market
Nutritional Supplements
Nutritional Lipids Market
Nutritional Supplements
Natural Vitamin E Product Market
Nutritional Supplements
Global Egg Protein Market