
 Diet Shakes Market | 2026-2036
Diet Shakes Market Size, Share, and Industry Trends Forecast 2026-2036
Diet Shakes Market Outlook
Aftermarket service revenue from personalized nutrition coaching and subscription replenishment programs is tilting margin pools away from one-time product sales toward recurring consumer relationships. Abbott Laboratories leverages its clinical nutrition heritage to anchor hospital discharge and home-care channels. Herbalife Nutrition Ltd. sustains a distributor-driven model that dominates direct-to-consumer engagement in emerging markets. Nestlé S.A. competes through manufacturing scale and retail shelf presence across mass-market grocery networks.
Diet shakes constitute formulated beverages or powders delivering controlled macronutrient profiles, typically containing 15-30 grams of protein per serving alongside vitamins, minerals, and fiber, manufactured through spray-drying or aseptic liquid processing for weight management and nutritional supplementation. Meal replacement formulations lead volume due to their positioning as complete nutrition solutions, while ready-to-drink formats capture the fastest growth trajectory driven by convenience-seeking Busy Professionals. Powder segments occupy mature margin structures sustained by bulk purchasing and home preparation habits among Fitness Enthusiasts.
The FDA governs structure-function claims and good manufacturing practice compliance for dietary supplements sold in the United States, while the EMA and EFSA frameworks across Europe enforce novel food ingredient assessments and health claim substantiation that constrain rapid product iteration. These regulatory architectures elevate barriers for new entrants lacking clinical validation infrastructure and compel established manufacturers to maintain dedicated regulatory affairs functions. Stakeholders must monitor evolving positions on artificial sweeteners and protein sourcing disclosures as consumer litigation and class-action exposure intensifies.
Market Dynamics
The FDA's updated nutrition labeling requirements are compressing formulation cycles and forcing manufacturers to rebuild product architectures around clean-label positioning, redirecting R&D spend toward natural sweetener systems and transparent protein sourcing.
Growth Catalysts
- Clean-label mandates:The FDA's revised Supplement Facts panel rules are compelling reformulation investments that create first-mover advantages for compliant portfolios.
- Hospital discharge protocols:Clinical nutrition handoff programs in the United States are embedding diet shakes into post-acute care pathways.
- Ready-to-drink processing:Aseptic liquid manufacturing lines are capturing convenience-driven consumption occasions previously lost to foodservice alternatives.
Market Restraints
- Whey protein concentrate volatility:Dairy input costs fluctuate with New Zealand and European Union milk powder auction cycles, compressing gross margins unpredictably.
- Supply concentration:Spray-drying capacity clusters in the Netherlands and Germany, creating single-point vulnerability for powder-format brands.
- Regulatory friction:EFSA's novel food ingredient assessments delay European launches by 18-24 months versus United States timelines.
Strategic Opportunities
- Subscription replenishment channels:Direct-to-consumer auto-ship models bypass retail slotting fees and capture lifetime value data.
- Plant protein convergence:Pea-rice protein blending with precision fermentation is opening allergen-free positioning for pediatric and senior segments.
- India's FSSAI framework:Standardized health claim pathways are reducing entry friction for clinically validated formulations in urban metros.
Industry Challenges
- Regulatory affairs talent scarcity:Qualified professionals capable of navigating simultaneous FDA, EFSA, and FSSAI submissions command premium compensation.
- Clean-label certification timelines:Non-GMO Project and USDA Organic verifications extend go-to-market schedules by 8-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diet Shakes Market |
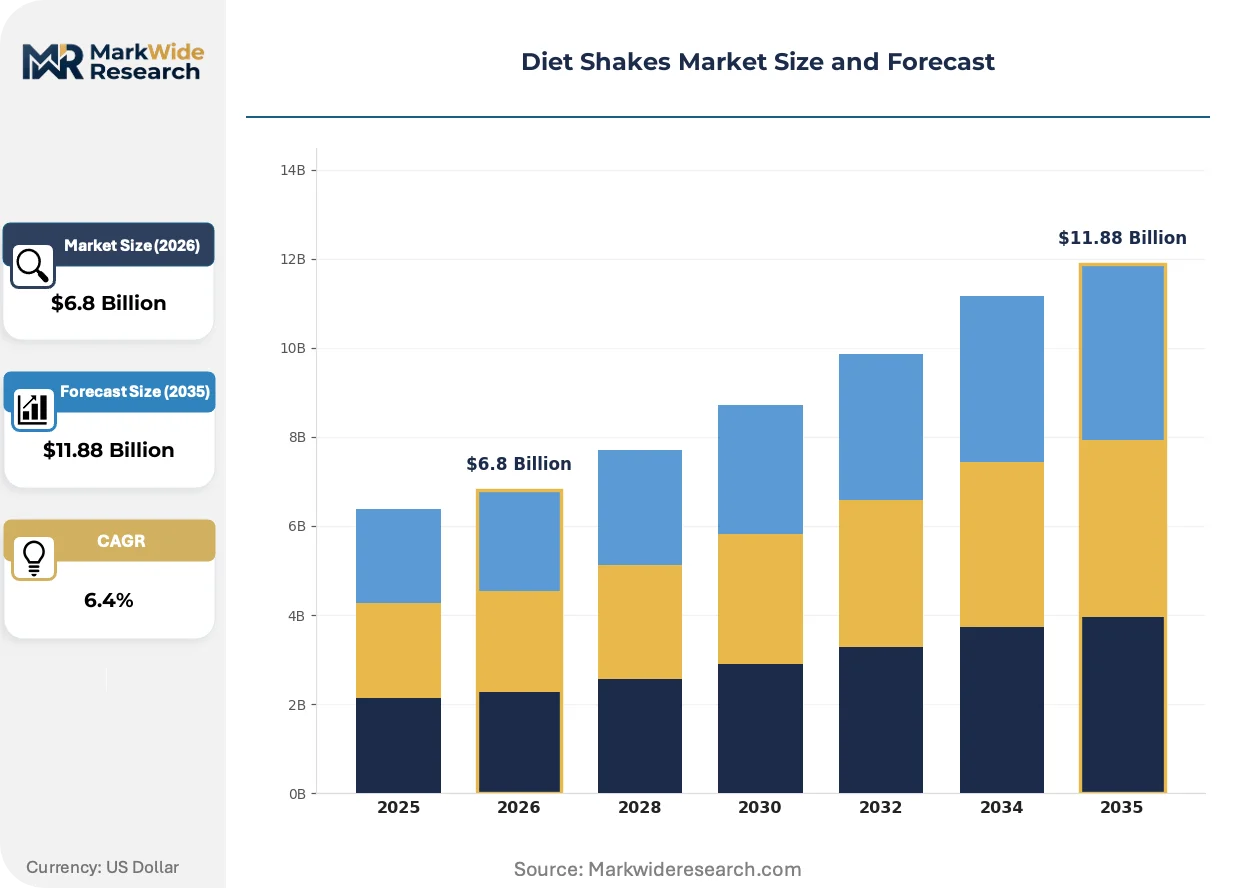
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meal Replacement, Protein Shakes, Nutritional Supplements, Ready-to-Drink Form: Powder, Liquid, Bar, Ready Mix End User: Fitness Enthusiasts, Weight Watchers, Busy Professionals, Health Conscious Consumers Flavor: Chocolate, Vanilla, Strawberry, Others |
| Companies Covered | Herbalife Nutrition Ltd., Nestlé S.A., Abbott Laboratories, Glanbia plc, Kellanov, Kellogg Company, Unilever, Medifast, Inc., Soylent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diet Shakes Market Strategic Shifts
Personalized nutrition platforms are collapsing the traditional segmentation between medical foods and wellness products, forcing manufacturers to build modular formulation systems that reconfigure macronutrient ratios at batch scale.
Precision fermentation-derived proteins are collapsing the cost structure of leucine-rich formulations previously dependent on animal isolates. Fitness Enthusiasts in the United States are adopting these alternatives at rates exceeding 40% trial penetration in coastal metros. The technology is collapsing the premium pricing umbrella that sustained whey protein dominance for two decades.
REACH's microplastic restriction proposals are compelling packaging transitions toward monomaterial flexible films and aluminum bottles. European Union manufacturers face 2026 compliance deadlines that require capital redeployment from formulation to container engineering. Ready-to-drink formats in Germany and France absorb the highest compliance cost burden due to single-serve unit volumes.
Busy Professionals are consolidating purchases through employer-sponsored wellness stipends rather than discretionary retail selection. Human resources benefit platforms in the United States are disintermediating traditional grocery and pharmacy channels. This behavior concentrates most visibly in technology sector employers with distributed workforces spanning Austin, Seattle, and Denver metros.
Diet Shakes Market Segmentation
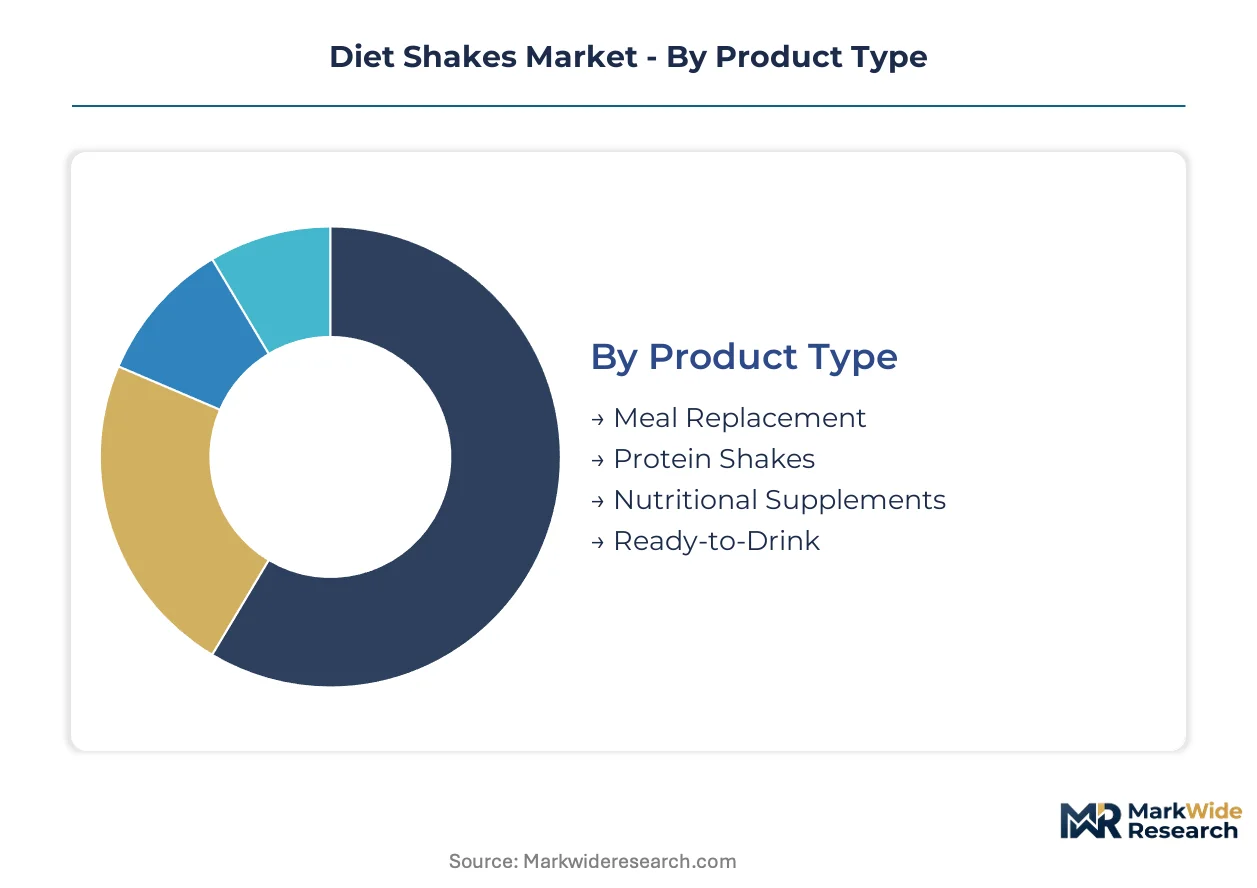
Segmentation in diet shakes reveals how formulation architecture and consumption context determine channel strategy. Manufacturers must align production capabilities with distinct preparation rituals, nutritional goals, and purchasing behaviors across consumer archetypes.
Product Type:
Maturity gradients separate established nutrition categories from emerging functional formats, with reimbursement pathways and clinical validation requirements shaping competitive moats.
- Meal Replacement:Complete macronutrient profiles delivering 400-600 calories per serving with vitamin fortification meet FDA medical food criteria. Weight Watchers in the United States drive recurring subscription demand through portion-controlled programming integrated with digital coaching platforms.
- Protein Shakes:Leucine-optimized formulations targeting 20-40g protein per serving support muscle protein synthesis for resistance training protocols. Fitness Enthusiasts concentrate purchases through specialty retail and direct-to-consumer channels, with precision fermentation alternatives gaining trial in coastal United States metros.
- Nutritional Supplements:Micronutrient-dense formulations bridge dietary gaps for restricted eating patterns. Health Conscious Consumers seek third-party certifications for contaminant screening and bioavailability claims.
- Ready-to-Drink:Aseptically processed single-serve beverages eliminate preparation friction for on-premise consumption. Busy Professionals absorb the highest per-unit pricing for workplace and transit occasions.
Meal Replacement retains volume leadership; Ready-to-Drink holds the steepest expansion curve.
Form:
Processing intensity and shelf stability requirements create divergent capital deployment profiles across manufacturing footprints.
- Powder:Spray-dried concentrates enable bulk purchasing economics and extended ambient storage. Fitness Enthusiasts sustain mature margin structures through multi-serving container purchases and home blending rituals.
- Liquid:Aseptic filling lines demand higher upfront capital but command price premiums for immediate consumption. Busy Professionals in the United States consolidate purchases through employer wellness stipend programs.
- Bar:Extruded and enrobed formats compete with whole food snacks through portability positioning. Weight Watchers integrate portion-controlled bars into structured meal planning protocols.
- Ready Mix:Pre-portioned single-serve sachets bridge powder economy with liquid convenience. Health Conscious Consumers trial formulations before committing to bulk containers.
Powder dominates manufacturing throughput; Liquid captures the highest value per serving.
End User:
Customer archetypes fragment distribution strategy between clinical handoff programs, performance retail, and mass-market grocery networks.
- Fitness Enthusiasts:Protein-centric purchasers prioritize amino acid completeness and digestibility metrics. Specialty retailers and direct-to-consumer subscription models concentrate engagement in United States metropolitan fitness corridors.
- Weight Watchers:Structured program participants demand precise caloric transparency and behavioral tracking integration. Hospital discharge protocols in the United States embed meal replacement into post-acute care pathways for bariatric and metabolic patients.
- Busy Professionals:Time-constrained consumers trade preparation control for grab-and-go accessibility. Employer-sponsored wellness platforms in technology sector hubs disintermediate traditional retail selection.
- Health Conscious Consumers:Ingredient scrutiny drives clean-label certification requirements and transparent supply chain disclosures. Non-GMO Project and USDA Organic verifications extend consideration sets beyond conventional performance positioning.
Weight Watchers anchor institutional procurement; Busy Professionals expand the addressable occasion set.
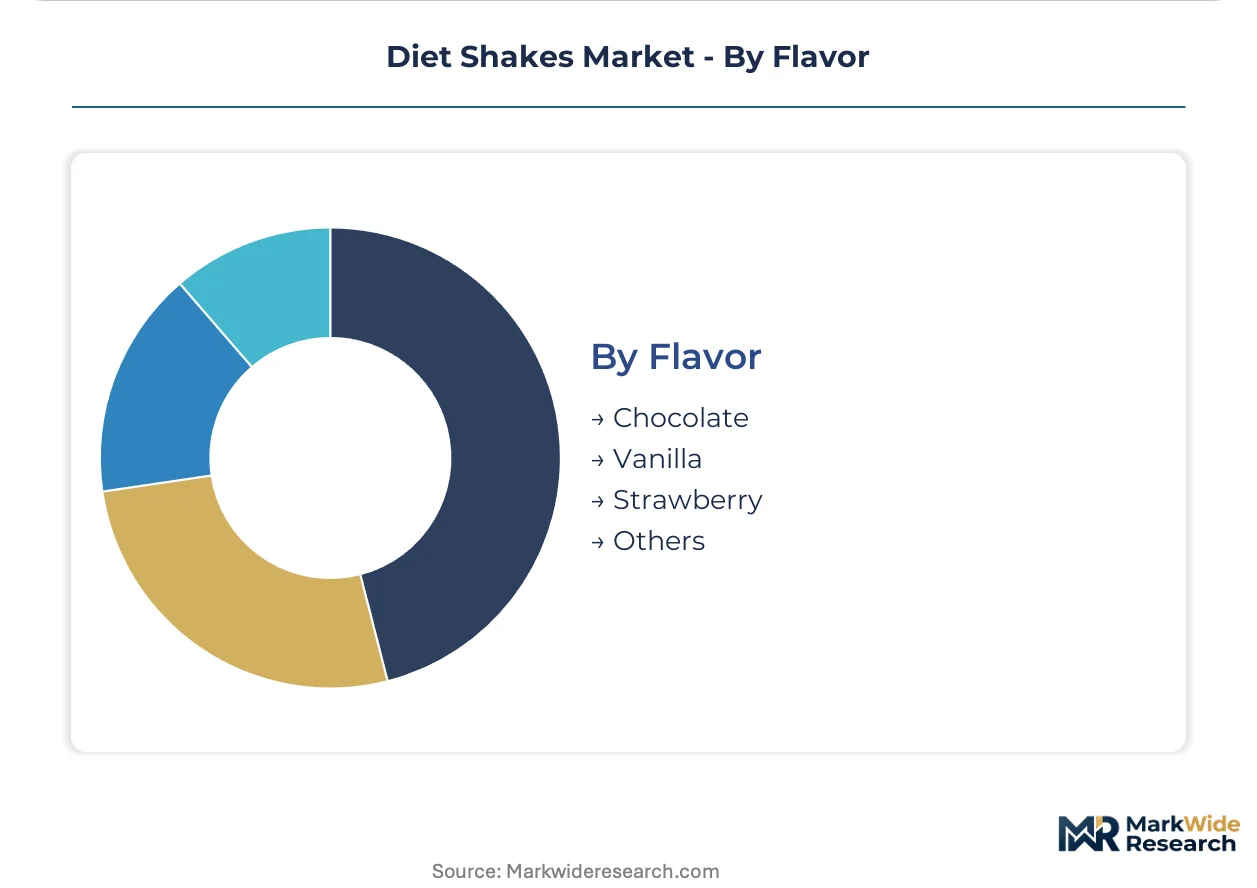
Flavor:
Formulation stability and masking technology determine which taste profiles can support functional ingredient loads without compromising sensory acceptance.
- Chocolate:Cocoa matrix masks vegetal off-notes from plant protein isolates and fiber fortification. United States consumers demonstrate highest repeat purchase rates for chocolate-dominant SKUs across powder and liquid formats.
- Vanilla:Neutral base enables customization through fresh fruit or nut butter additions in home preparation. Fitness Enthusiasts favor vanilla for blending flexibility in post-workout recovery routines.
- Strawberry:Fruit flavor systems require acid-stable protein emulsions to prevent precipitation. Health Conscious Consumers perceive strawberry as a cleaner-label alternative to artificial chocolate flavoring.
- Others:Emerging profiles including coffee, peanut butter, and seasonal limited editions test elasticity of core consumer loyalty. Specialty retailers curate rotating flavor assortments to drive foot traffic and subscription retention.
Chocolate sustains the broadest household penetration; Others generates the highest trial-to-discovery conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across consumption contexts: employer-subsidized channels in the United States absorb premium positioning, while emerging market penetration depends on sachet economics and distributor margin compression.
United States
Employer wellness stipends and hospital discharge protocols drive institutional procurement at price points retail channels cannot match. The FDA's updated Supplement Facts panel rules compress formulation cycles for domestic manufacturers. Austin, Seattle, and Denver technology corridors concentrate distributed workforce demand through HR benefit platforms.
Germany
REACH microplastic restriction deadlines force packaging capital redeployment toward monomaterial films and aluminum bottles. EFSA novel food assessments delay product launches versus United States timelines. Spray-drying capacity clusters in the Netherlands and Germany create single-point vulnerability for powder-format brands serving Central European markets.
India
Urban metro demand concentrates among Health Conscious Consumers seeking clinically validated formulations at accessible price points. The FSSAI framework standardizes health claim pathways, reducing entry friction for compliant manufacturers. Maharashtra and Karnataka host emerging contract manufacturing infrastructure for regional brand development.
China
SAMR oversight of functional food claims elevates clinical validation requirements for positioning beyond basic nutrition. Dual carbon goals pressure manufacturing footprints toward renewable energy sourcing. Yangtze River Delta and Pearl River Delta clusters dominate aseptic liquid processing capacity for ready-to-drink formats.
Brazil
Distributor-driven models dominate direct-to-consumer engagement in emerging market tiers where retail infrastructure remains fragmented. ANVISA pharmaceutical-grade manufacturing standards create compliance moats for domestic producers. São Paulo anchors both production gravity and consumption concentration for meal replacement formulations.
Diet Shakes Market Competitive Environment
Clinical nutrition heritage and mass-market manufacturing scale split the market between institutional channel anchoring and retail shelf dominance. The structure concentrates around three strategic archetypes: hospital discharge program integrators, direct-to-consumer distributor networks, and grocery network scale players. Competitive moves center on subscription replenishment channel construction and precision fermentation protein sourcing partnerships.
Within the clinical heritage tier, Abbott Laboratories occupies a position anchored by hospital discharge protocol integration. Among mass-market scale players, Nestlé S.A. exemplifies manufacturing footprint leverage across grocery networks. Herbalife Nutrition Ltd. sits within the distributor-driven archetype that dominates emerging market direct-to-consumer engagement. These three entities represent divergent channel strategies rather than direct product competition.
| Leading Market Players |
|---|
| Herbalife Nutrition Ltd. |
| Nestlé S.A. |
| Abbott Laboratories |
| Glanbia plc |
| Kellanov |
| Kellogg Company |
| Unilever |
| Medifast, Inc. |
| Soylent |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in European spray-drying facilities is compressing toll-manufacturing rates and forcing powder-format suppliers toward volume-commitment contracts that lock in pricing floors for multi-year horizons.
Pricing Analysis
Subscription replenishment revenue from personalized nutrition coaching and auto-ship programs tilts lifetime value calculations away from transactional retail sales toward recurring consumer relationships. Three-tier pricing structure across premium, standard, and economy levels separates clinically validated medical food formulations from mass-market wellness positioning and value-oriented private label alternatives. Cost compression in whey protein concentrate inputs is intensifying because New Zealand milk powder auction volatility transmits unpredictably through formulation costs. Health Conscious Consumers demonstrate highest price sensitivity due to ingredient certification requirements, while Busy Professionals absorb premium positioning through employer wellness stipend channels.
Supply Chain Analysis
Export-control restrictions on precision fermentation-derived protein technologies limit technology transfer to contract manufacturing partners in emerging markets, constraining local production scale-up. Supply concentrates in the Netherlands, Germany, and New Zealand for spray-dried powder inputs, while aseptic liquid processing capacity clusters in China and the United States. Raw material dependencies center on dairy protein isolates, plant protein concentrates, and natural sweetener systems. Single-source vulnerability in European spray-drying infrastructure creates concentration risk for powder-format brands. Distribution runs through direct-to-consumer subscription platforms, hospital discharge protocols, and mass-market grocery networks with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified regulatory affairs professionals capable of navigating simultaneous FDA, EFSA, and FSSAI submissions command premium compensation, creating a structural bottleneck that favors incumbents with established compliance infrastructure.
For Market Incumbents: Build certification moats through accelerated Non-GMO Project and USDA Organic verifications that extend competitor go-to-market timelines by 8-12 months. Expand backward integration into precision fermentation protein sourcing to collapse input cost structures and defend margin position against whey protein volatility. Anchor hospital discharge protocol relationships through clinical nutrition heritage to create switching costs for metabolic and bariatric patient segments.
For New Entrants and Emerging Players: Establish a beachhead in India's urban metro markets where FSSAI framework standardization reduces entry friction for clinically validated formulations. Target employer-sponsored wellness stipend channels in United States technology corridors as the most penetrable distribution pathway bypassing retail slotting fees. Lead with plant protein convergence positioning using pea-rice blends to capture allergen-sensitive pediatric and senior segments underserved by incumbent dairy-centric portfolios.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription replenishment platforms with integrated personalized nutrition coaching capabilities that generate lifetime value data and reduce customer acquisition costs. Long-term viability favors manufacturers with modular formulation systems capable of reconfiguring macronutrient ratios at batch scale to collapse medical food and wellness product segmentation. Acquisition target archetypes include precision fermentation protein technology holders and direct-to-consumer subscription infrastructure with established auto-ship retention rates. Monitor REACH microplastic restriction compliance timelines as inflection indicator for packaging capital redeployment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Collapses leucine-rich protein cost structures previously dependent on animal isolates. |
| Subscription Platform Buildout | Captures lifetime value data and bypasses retail slotting fees through auto-ship models. |
| Clean-Label Certification Acceleration | Creates 8-12 month competitive moats through Non-GMO Project and USDA Organic verifications. |
| Hospital Discharge Protocol Integration | Embeds meal replacement into post-acute care pathways for bariatric and metabolic patients. |
| Monomaterial Packaging Transition | Addresses REACH microplastic deadlines through aluminum bottles and flexible film engineering. |
Study Parameters
A standing panel of regulatory affairs directors, contract manufacturing executives, hospital nutrition service managers, and direct-to-consumer subscription platform operators provided ongoing calibration against market developments. Primary interviews with formulation scientists, flavor masking specialists, and spray-drying facility engineers combined with secondary validation through FDA Supplement Facts panel filings, EFSA novel food assessment databases, FSSAI health claim registries, and customs trade data on protein concentrate imports. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Scenario-bracketing around regulatory timeline variations and input cost volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, form, end user archetype, and flavor profile alongside regional regulatory cluster differentiation. CAGRs derived from volume-weighted average growth trajectories incorporating precision fermentation adoption curves, employer wellness stipend penetration rates, and hospital discharge protocol expansion assumptions.
Sensitivities concentrate around FDA enforcement discretion on structure-function claims, EFSA assessment backlog durations, and New Zealand milk powder auction cycle amplitude. Forecasts reflect documented assumptions on clean-label mandate compliance timelines and subscription retention rate stability. Material shifts in REACH microplastic restriction implementation or precision fermentation regulatory classification would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Dietary Supplements Market
Nutritional Supplements
Europe Amino Acid in Dietary Supplements Market
Nutritional Supplements
Phytoceramide Supplement Market
Nutritional Supplements
Liquid Dietary Supplements Market
Nutritional Supplements
Energy Gel Products Market
Nutritional Supplements
Microencapsulated Fish Oil Market
Nutritional Supplements
Organic Whey Protein Market
Nutritional Supplements
Spirulina Powder Market
Nutritional Supplements
Lactates Market
Nutritional Supplements
Global Nutraceutical Ingredients Market
Nutritional Supplements
Vegan Supplements Market
Nutritional Supplements
Multivitamin and Mineral Supplements Market
Nutritional Supplements
Andro Supplements Market
Nutritional Supplements
Middle East and Africa Amino Acid in Dietary Supplements Market
Nutritional Supplements
Folic Acid Market
Nutritional Supplements
Folate Market