
 Algae Supplements Market | 2026-2036
Algae Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Algae Supplements Market Analysis
REACH compliance is hardening the cost-of-entry calculus for European algae supplement suppliers, forcing smaller cultivators to invest in toxicology dossiers or exit the market. DSM-Firmenich AG leverages its decades of astaxanthin fermentation expertise to sustain premium positioning across pharmaceutical-grade applications. Cyanotech Corporation anchors its competitive stance through controlled Hawaiian cultivation of Haematococcus pluvialis for natural astaxanthin extraction. Corbion competes via industrial-scale photobioreactor operations that deliver consistent spirulina biomass for fortified food formulations.
Algae supplements comprise dried, processed, or extracted biomass from photosynthetic microalgae and cyanobacteria species, typically standardized to protein content exceeding 50% by dry weight or specific carotenoid concentrations such as astaxanthin at 2.5-5.0% extract potency, serving primarily as nutrient-dense inputs for human dietary fortification and functional nutrition. Spirulina dominates volume flows due to its established GRAS status and lower cultivation cost structure, while chlorella commands margin premiums tied to its cracked-cell processing requirements and detoxification positioning among health enthusiasts. Powder formulations occupy the largest share of commercial throughput, though gummies are gaining shelf space as brands target younger demographics seeking palatable delivery formats.
The US FDA maintains Current Good Manufacturing Practice enforcement for dietary supplements containing algae ingredients, while the European Food Safety Authority evaluates novel food applications for emerging strains such as Schizychytrium sp. omega-3 oils. India's Food Safety and Standards Authority mandates heavy metal testing for imported spirulina under its nutraceutical regulations, creating compliance friction for Southeast Asian suppliers. Stakeholders must monitor evolving Novel Food catalog expansions and adapt strain portfolios to jurisdictions with faster regulatory pathways.
Market Dynamics
EFSA's Novel Food authorization process is tightening compliance requirements for algae-derived ingredients, forcing cultivators to invest in toxicology dossiers or exit the European market entirely. This regulatory hardening is compressing supplier margins while accelerating consolidation among mid-tier producers lacking dedicated regulatory affairs capabilities.
Growth Catalysts
- Clean-label sports nutrition:Athletes seeking plant-based omega-3 alternatives are pulling algae-derived EPA/DHA into pre-workout and recovery formulations, bypassing fish oil supply chain volatility.
- REACH compliance infrastructure:Large-scale photobioreactor operators with established toxicology dossiers are capturing shelf space as smaller competitors withdraw from EU distribution.
- Spirulina GRAS status:The US FDA's established safety recognition enables rapid formulation cycles for fortified foods and beverages, accelerating time-to-market versus novel strain approvals.
Market Restraints
- Input cost volatility:Nitrogen and phosphorus fertilizer prices for open-pond spirulina cultivation fluctuate with agricultural commodity cycles, compressing margins for non-integrated producers.
- Supply concentration risk:Premium astaxanthin extraction depends on controlled Haematococcus pluvialis cultivation in specific climatic zones, creating geographic single-point-of-failure exposure.
- Technical limitation:Chlorella's rigid cell wall requires energy-intensive cracking processes to release bioavailable nutrients, adding processing cost that powder formats struggle to recover.
Strategic Opportunities
- Gummy delivery formats:Brands targeting younger demographics are displacing tablet and capsule formats with palatable, flavor-masked algae gummies in convenience retail channels.
- Pharmaceutical-grade astaxanthin:Fermentation-derived carotenoids with documented oxidative stability profiles are penetrating ophthalmology and dermatology adjacencies beyond nutrition.
- India nutraceutical regulations:FSSAI's mandatory heavy metal testing for imported spirulina creates first-mover advantage for domestic cultivators with certified clean biomass.
Industry Challenges
- Phycology talent scarcity:Strain optimization and contamination control require specialized algae cultivation expertise that outpaces university pipeline output.
- Photobioreactor capex intensity:Closed-system cultivation for pharmaceutical-grade biomass demands substantial upfront capital for LED arrays and sterile processing infrastructure.
- Novel Food timeline compression:EFSA's 18-24 month safety evaluation window delays revenue realization for emerging Schizochytrium omega-3 oil variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Algae Supplements Market |
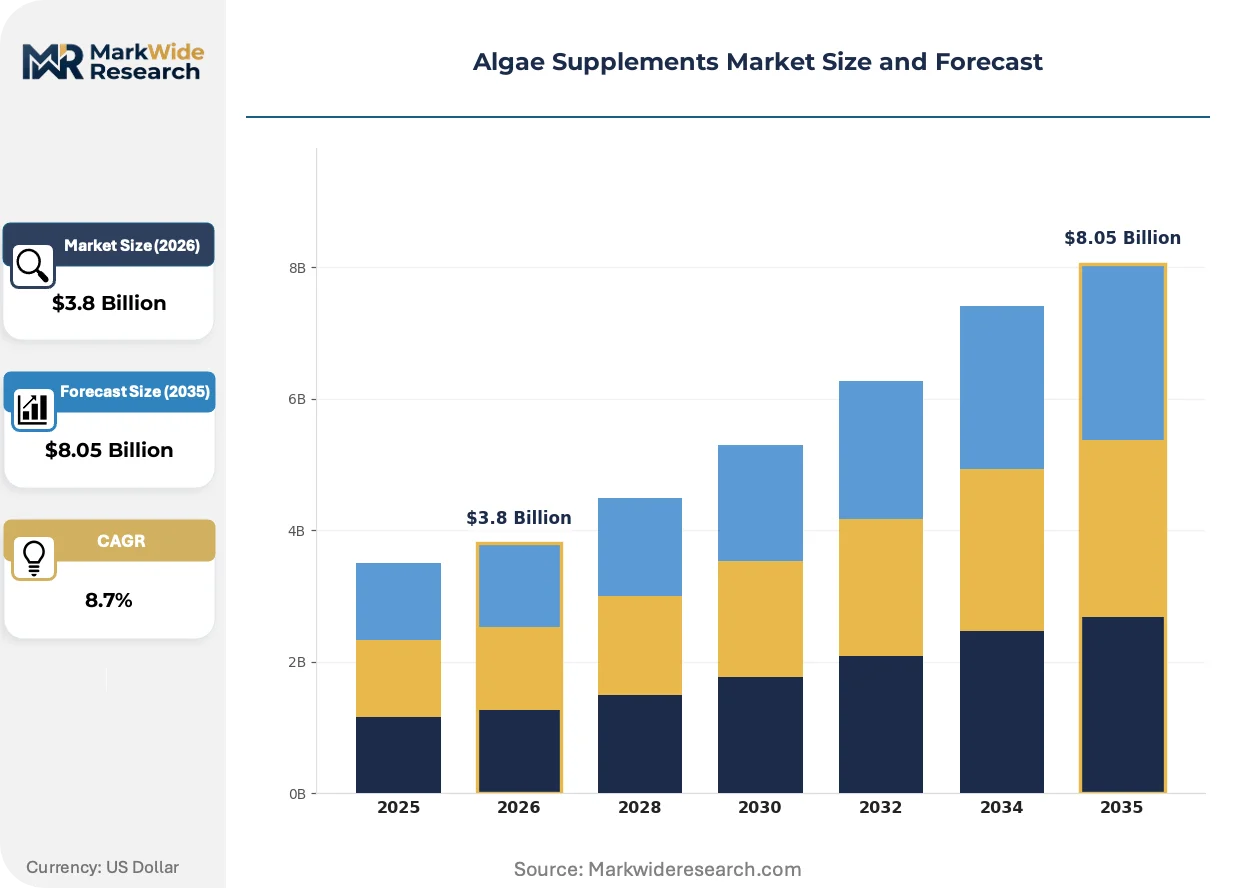
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spirulina, Chlorella, Aphanizomenon, Klamath End User: Health Enthusiasts, Athletes, Vegan Consumers, Nutraceutical Industry Formulation: Pills, Powders, Gummies, Liquid Extracts Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Fitness Centers |
| Companies Covered | Cyanotech Corporation, DSM-Firmenich AG, Corbion, Parry Nutraceuticals, Far East Bio-Tec Co., Ltd, Algatechnologies, Allmicroalgae, Earthrise Nutritional, AlgaeCal Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Algae Supplements Market Emerging Trajectories
Algae supplement production is converging with precision fermentation and advanced extraction technologies, compressing traditional cultivation-to-capsule timelines while raising purity thresholds. These shifts are redrawing competitive boundaries between agricultural and pharmaceutical-grade suppliers.
Cell disruption technology is integrating ultrasonic-assisted extraction with enzymatic pre-treatment to improve bioactive yield from rigid-walled microalgae. Nutraceutical formulators in Germany and the Netherlands are adopting these hybrid systems to reduce solvent use and meet clean-label positioning requirements. The technology is integrating pharmaceutical-grade purity standards into mainstream supplement manufacturing, compressing the historical quality gap between food and drug applications.
EFSA's expanding Novel Food catalog is accelerating strain commercialization pathways for omega-3-rich Schizochytrium and Isochrysis species previously confined to aquaculture feed. The regulatory clarity is redirecting R&D investment from open-pond commodity spirulina toward high-value lipid profiles with documented cardiovascular endpoints. Specialty oil processors in Denmark and Spain are responding by commissioning dedicated fermentation capacity ahead of anticipated positive opinions.
Direct-to-consumer subscription models are displacing traditional pharmacy and health food retail distribution for premium algae products. Digital-native brands in the United States and United Kingdom are bundling personalized omega-3 testing with recurring astaxanthin or spirulina deliveries, capturing lifetime value through adherence data. This channel pivot is most visible among athletic and biohacker demographics willing to pay premium pricing for traceable, single-origin biomass with third-party certificates of analysis.
Algae Supplements Market Segmentation
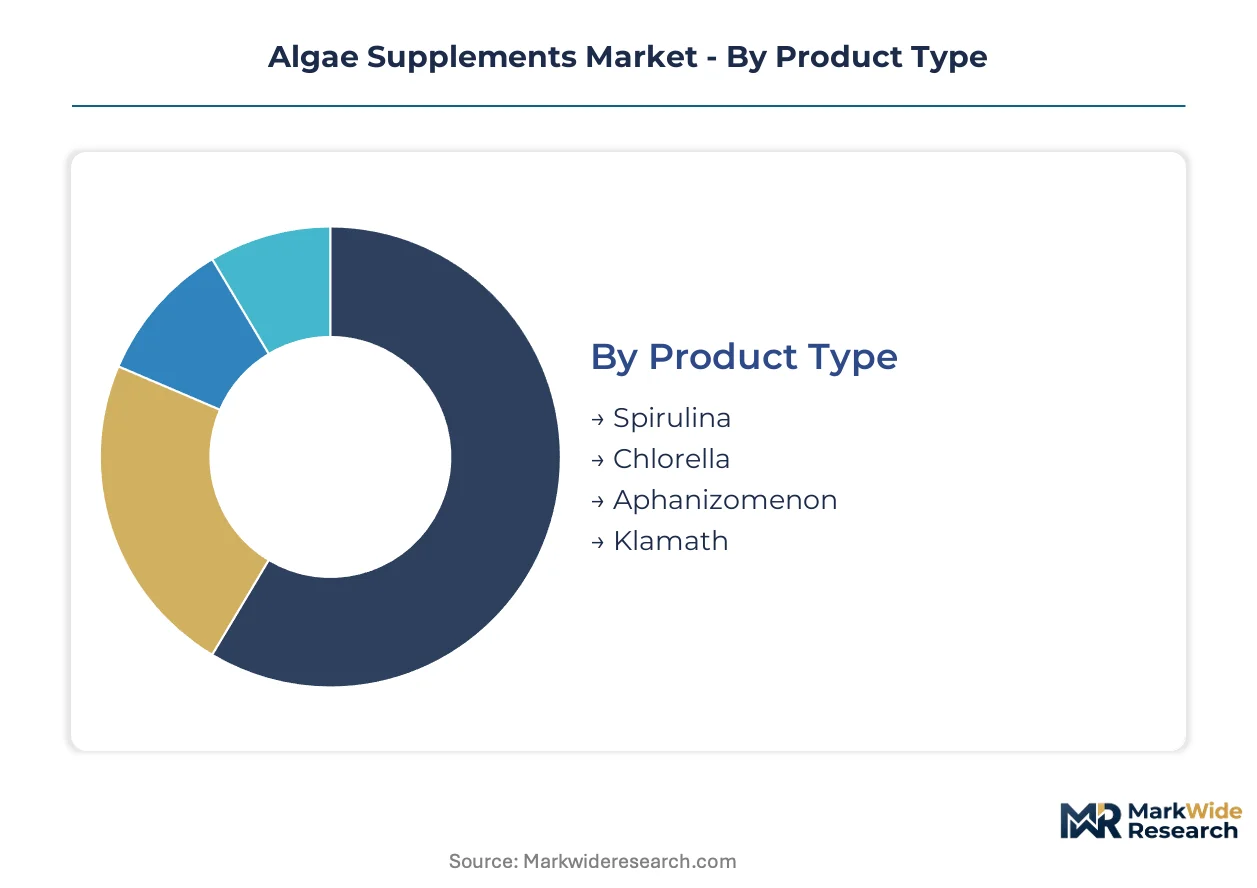
Algae supplement segmentation reveals distinct technology-performance tradeoffs across biomass species, with cell wall architecture and cultivation scalability determining cost structures and bioavailability profiles. Formulation and channel choices increasingly separate mass-market penetration from premium positioning in functional nutrition.
Product Type:
Cell wall rigidity and cultivation system requirements differentiate species economics, with open-pond versus photobioreactor infrastructure driving margin stratification.
- Spirulina:Cyanobacteria biomass with established GRAS status enables rapid formulation cycles. Demand concentrates in US fortified food applications where FDA safety recognition accelerates time-to-market versus novel strain approvals.
- Chlorella:Rigid cell wall demands energy-intensive cracking for nutrient bioavailability. German and Dutch clean-label consumers absorb premium pricing for detoxification positioning despite processing cost premiums.
- Aphanizomenon:Wild-harvested Klamath Lake biomass carries geographic provenance cachet.
- Klamath:Single-origin blue-green algae targets neurocognitive wellness segments with traceable sourcing narratives.
Mature deployment sits with Spirulina. Newer deployment is concentrated in Chlorella.
End User:
Protein completeness requirements and omega-3 conversion efficiency separate recreational wellness consumers from performance-optimized buyers.
- Health Enthusiasts:General wellness positioning emphasizes micronutrient density and immune support claims. Powder formats dominate this segment due to dosing flexibility and cost efficiency in daily supplementation routines.
- Athletes:Plant-based EPA/DHA demand pulls algae omega-3 into pre-workout and recovery formulations. Sports nutrition brands in Germany and the United Kingdom specify third-party tested astaxanthin for oxidative stress modulation.
- Vegan Consumers:DHA bioequivalence to fish oil drives substitution decisions.
- Nutraceutical Industry:Bulk biomass procurement for finished product manufacturing.
Volume concentrates with Health Enthusiasts. Margin expansion is steepest with Athletes.
Formulation:
Delivery technology determines bioaccessibility and compliance adherence across demographic cohorts with divergent swallowing preferences and taste sensitivity.
- Pills:Standardized dosing and extended shelf stability serve pharmacy and professional channel distribution. Tablet compression accommodates high-potency chlorella extracts where volume per unit limits gummy feasibility.
- Powders:Bulk throughput leader enabling beverage fortification and customizable dosing. German clean-label brands leverage powder flexibility for smoothie additive positioning with minimal excipient disclosure.
- Gummies:Palatability-driven format gaining shelf space among younger demographics.
- Liquid Extracts:Rapid absorption claims target biohacker and clinical wellness segments.
Production scale favors Powders. Format innovation is accelerating in Gummies.
Distribution Channel:
Certificate of analysis transparency and subscription mechanics separate digital-native customer acquisition from traditional retail throughput.
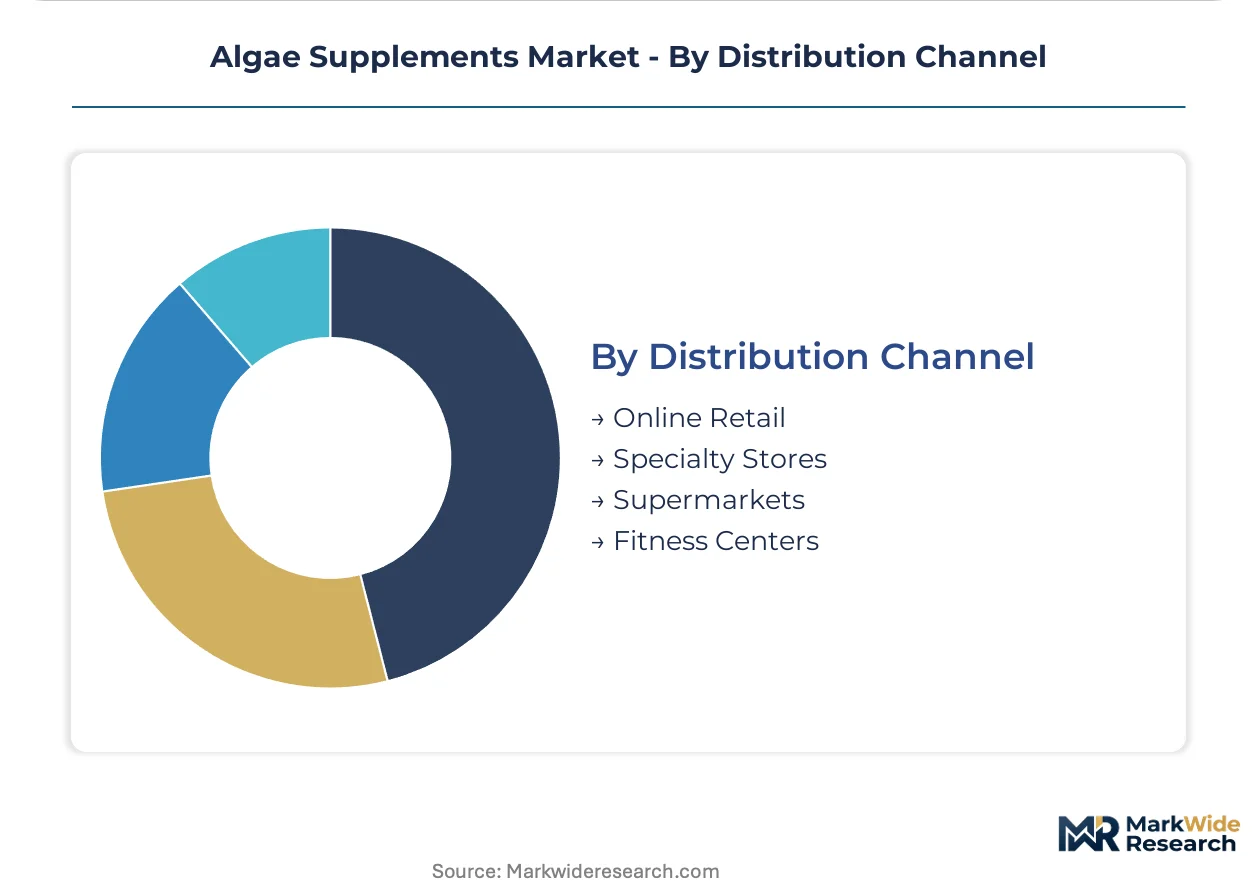
- Online Retail:Direct-to-consumer subscription models capture lifetime value through personalized omega-3 testing bundles. US and UK digital-native brands leverage third-party COA disclosure to justify premium pricing for single-origin biomass.
- Specialty Stores:Staff consultation and category education support complex product differentiation. Netherlands and German health food retailers emphasize EFSA Novel Food compliance verification for emerging Schizochytrium omega-3 oils.
- Supermarkets:Mass-market spirulina placement in functional food aisles.
- Fitness Centers:Point-of-workout availability for immediate consumption occasions.
Established penetration sits with Specialty Stores. Channel expansion is climbing fastest in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for algae supplements concentrates in Germany, where clean-label supplement penetration runs deepest among Western European consumers. Athletes in the United States and United Kingdom pull plant-based omega-3 into sports nutrition formulations, while regulatory friction in India creates domestic cultivation advantages.
Germany
Health enthusiasts and vegan consumers drive spirulina and chlorella consumption through pharmacy and health food channels. EFSA's Novel Food authorization process tightens compliance requirements for emerging Schizochytrium omega-3 oils. The Hamburg-Berlin corridor hosts specialty retailers emphasizing EFSA compliance verification for lipid-based supplements.
United States
Sports nutrition brands specify third-party tested astaxanthin for oxidative stress modulation among athletic demographics. The FDA maintains Current Good Manufacturing Practice enforcement for dietary supplements containing algae ingredients. California cultivators leverage GRAS recognition for rapid formulation cycles in fortified beverage applications.
United Kingdom
Digital-native brands bundle personalized omega-3 testing with recurring algae deliveries to biohacker and athletic segments. REACH compliance infrastructure requirements filter smaller competitors from EU distribution channels. London-based direct-to-consumer operators capture lifetime value through subscription adherence data.
India
FSSAI mandates heavy metal testing for imported spirulina, creating compliance friction for Southeast Asian suppliers. Domestic cultivators with certified clean biomass capture first-mover advantage in nutraceutical procurement. Tamil Nadu and Gujarat production clusters scale photobioreactor capacity for export-grade biomass.
Netherlands
Clean-label consumers absorb chlorella premiums for detoxification positioning despite processing cost premiums. Dutch regulators align with EFSA frameworks for novel strain safety evaluations. Rotterdam-Amsterdam logistics hubs facilitate omega-3 oil processing for fortified food manufacturers.
Algae Supplements Market Vendor Landscape
European producers anchor one tier through regulatory compliance infrastructure; Asian specialists hold cost-advantaged cultivation positions. The vendor base stratifies across pharmaceutical-grade fermentation operators, open-pond commodity cultivators, and digital-native brand aggregators. Three archetypes dominate: large-scale photobioreactor operators with toxicology dossiers, wild-harvested biomass specialists with geographic provenance narratives, and direct-to-consumer subscription platforms with testing integration. Competitive moves center on capacity expansion for closed-system cultivation and strategic partnerships for strain optimization.
Within the fermentation-derived carotenoid tier, DSM-Firmenich AG exemplifies premium positioning through decades of astaxanthin expertise. Cyanotech Corporation anchors the natural extraction archetype through controlled Hawaiian cultivation operations. Corbion occupies the industrial-scale photobioreactor position for consistent spirulina biomass supply. These three represent distinct competitive vectors: pharmaceutical-grade purity, geographic single-origin sourcing, and commodity-scale reliability.
| Leading Market Players |
|---|
| Cyanotech Corporation |
| DSM-Firmenich AG |
| Corbion |
| Parry Nutraceuticals |
| Far East Bio-Tec Co., Ltd |
| Algatechnologies |
| Allmicroalgae |
| Earthrise Nutritional |
| AlgaeCal Inc. |
| Others |
Supply Flow & Price Mechanics
Agricultural nitrogen and phosphorus fertilizer indices cascade directly into open-pond spirulina cultivation economics, compressing margins for non-integrated producers while rewarding photobioreactor operators with captive nutrient recycling systems. This input cost volatility stratifies pricing power across cultivation tiers, with closed-system biomass commanding sustainable premiums over commodity-grade alternatives.
Pricing Analysis
Volume concentrates in commodity spirulina powders where price competition runs deepest among open-pond cultivators, while margin expansion accrues to pharmaceutical-grade astaxanthin extracts with documented oxidative stability profiles. Price differentiation hinges on EFSA Novel Food compliance certification and third-party heavy metal testing protocols that German clean-label buyers mandate. Pricing pressure stems from REACH toxicology dossier requirements that smaller European suppliers cannot absorb, forcing exits that temporarily stabilize mid-tier contract rates. Health enthusiasts in mass-market channels exhibit highest price sensitivity, whereas sports nutrition formulators absorb premiums for single-origin Hawaiian or certified Indian biomass with traceable certificates of analysis.
Supply Chain Analysis
Photobioreactor LED arrays and sterile processing infrastructure rest on Japanese and German precision engineering suppliers, with fermentation-grade stainless steel vessels drawing from Danish and Dutch specialty fabricators. Raw material dependencies include nitrogen fertilizers sourced from agricultural commodity markets, phosphorus from Moroccan and Chinese phosphate rock processors, and carbon dioxide feedstock from industrial gas suppliers. Supply chain risk centers on geographic single-point-of-failure exposure for premium Haematococcus pluvialis cultivation concentrated in specific Hawaiian climatic zones. Distribution runs through direct-to-consumer subscription platforms capturing lifetime value alongside traditional pharmacy and health food retail channels in Germany and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA's Novel Food authorization process functions as a cost-of-compliance moat, consolidating market position among cultivators with dedicated regulatory affairs capabilities and toxicology dossier infrastructure while marginalizing smaller competitors lacking such investment capacity.
For Market Incumbents: Deepen photobioreactor capacity in Tamil Nadu and Gujarat production clusters to exploit FSSAI heavy metal testing requirements that disadvantage imported Southeast Asian spirulina. Invest in ultrasonic-assisted cell disruption technology to reduce chlorella processing costs that currently erode powder format margins. Defend against digital-native subscription brands by integrating personalized omega-3 testing bundles into existing direct-to-consumer platforms. For New Entrants and Emerging Players: The premium-to-economy price gap in pharmaceutical-grade astaxanthin creates entry opportunity for fermentation-derived alternatives with documented stability profiles. Target sports nutrition formulators in the United Kingdom seeking plant-based EPA/DHA alternatives to volatile fish oil supply chains. Pursue white-label gummy manufacturing partnerships with established flavor-mask technology providers to bypass capital-intensive photobioreactor buildouts. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier European cultivators with partial EFSA dossier completion but insufficient capital to reach authorization, particularly in the Hamburg-Berlin corridor specialty retail hub. Long-term viability favors operators with backward integration into nutrient recycling and captive carbon dioxide supply. Watch for EFSA positive opinions on Schizochytrium omega-3 oil variants as inflection signal redirecting R&D investment flows.| Strategic Initiative | Industry Significance |
|---|---|
| Photobioreactor Capacity Expansion | Tamil Nadu and Gujarat clusters scale export-grade biomass production with FSSAI-compliant heavy metal controls. |
| EFSA Novel Food Dossier Investment | Regulatory approval pathway for Schizochytrium omega-3 oils accelerates strain commercialization in Denmark and Spain. |
| Direct-to-Consumer Subscription Launch | Digital-native brands in London capture lifetime value through personalized omega-3 testing adherence data. |
| Ultrasonic Cell Disruption Technology Adoption | German and Dutch formulators reduce solvent use while meeting clean-label positioning requirements. |
| Backward Integration into Nutrient Recycling | Captive nitrogen and phosphorus recovery insulates margins from agricultural commodity price cycles. |
Methodological Framework
Trade databases, EFSA Novel Food application registers, and FSSAI import inspection records formed the secondary backbone, supplemented by SEC filings from publicly listed cultivation technology providers and customs data tracking spirulina biomass flows. Primary interviews with photobioreactor operations directors, regulatory affairs specialists at European supplement brands, pharmacy category buyers in Germany, and sports nutrition formulators in the United Kingdom validated secondary findings. Bottom-up cultivation capacity estimates triangulated against top-down demand projections from end-use segment analysis.
Bottom-up modeling anchored forecasts in named production cluster capacities across Tamil Nadu, Gujarat, Hamburg-Berlin corridor, and Hawaiian controlled cultivation zones, while top-down validation assessed clean-label penetration rates and sports nutrition formulation trends. Segmentation dimensions included species type, cell wall processing requirements, formulation technology, and distribution channel mechanics across the projection horizon. CAGRs derived from trajectory fitting to historical authorization timelines and cultivation capacity commissioning cycles, with algae oil extraction yield improvements and LED energy efficiency gains as key technology inputs.
Underlying measurement precision varies by segment; established spirulina powder flows through GRAS-recognized channels carry tighter precision than emerging Schizochytrium omega-3 oil variants pending EFSA evaluation. Forecasts reflect assumptions around regulatory authorization timelines, nutrient input cost stabilization, and photobioreactor technology maturation that could revise projections if EFSA accelerates Novel Food evaluations or agricultural commodity volatility intensifies. A small set of triggers—EFSA opinion publication dates, FSSAI enforcement intensity on heavy metal testing, and LED array cost curves—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
South America Nutricosmetics Market
Nutritional Supplements
Sea Moss Supplements Market
Nutritional Supplements
Global Nutraceuticals Product Market
Nutritional Supplements
Vegan Vitamins and Supplements Market
Nutritional Supplements
Global Algal DHA and ARA Market
Nutritional Supplements
North America Collagen-Based Supplements Market
Nutritional Supplements
Europe Omega-3 Products Market
Nutritional Supplements
Vegan Protein Market
Nutritional Supplements
Water Soluble Vitamin and Mineral Feed Supplements Market
Nutritional Supplements
Prenatal Supplements Market
Nutritional Supplements
Bovine Collagen Peptide Market
Nutritional Supplements
Global Multivitamin Capsules and Tablets Market
Nutritional Supplements
Vitamin Shot Market
Nutritional Supplements
North America Omega-3 Products Market
Nutritional Supplements
Native Whey Protein Market
Nutritional Supplements
Melatonin Supplements Market