
 Natural Immune Booster Market | 2026-2036
Natural Immune Booster Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Immune Booster Market Outlook
Subscription-based replenishment programs is pivoting how natural immune boosters reach households, converting one-time supplement purchases into recurring revenue streams with predictable lifetime value. Dabur India Ltd. leverages its Ayurvedic heritage and pharmacy networks across South Asia to sustain brand loyalty in herbal supplements. Gaia Herbs anchors its competitive position through vertically integrated organic cultivation in North Carolina. NOW Foods competes on manufacturing scale and private-label capacity, supplying multiple retail tiers with standardized potency guarantees.
A natural immune booster comprises bioactive compounds derived from botanical extracts, microbial cultures, vitamins, and trace minerals formulated to modulate innate and adaptive immune responses, typically standardized to marker compounds such as polysaccharide content or colony-forming units. These formulations serve preventive health applications in consumer wellness, sports nutrition, and clinical adjuvant protocols where evidence-backed immunomodulation supports reduced infection susceptibility. Herbal supplements occupy the largest revenue pool due to centuries of traditional use and established regulatory pathways, while probiotics represents the fastest-expanding category as microbiome science validates strain-specific immune mechanisms. Gummies is displacing capsules among adult and senior consumer segments as palatability drives compliance rates in daily regimens.
The FDA's Current Good Manufacturing Practice regulations and NDI notification requirements enforce identity, purity, and strength documentation for all domestic supplement manufacturing, raising compliance costs but filtering marginal suppliers from shelf access. EFSA's ongoing health claim assessments in Europe demand randomized controlled trial evidence for immunity-related marketing, redirecting R&D investment toward clinical validation rather than formulation innovation alone. India's FSSAI and CDSCO jointly oversee Ayurvedic product licensing under the AYUSH ministry, creating a dual-track regulatory environment that both protects traditional knowledge and imposes modern quality benchmarks. Stakeholders must monitor evolving substantiation standards across jurisdictions to determine where clinical trial investment yields sustainable market access versus regulatory exclusion.
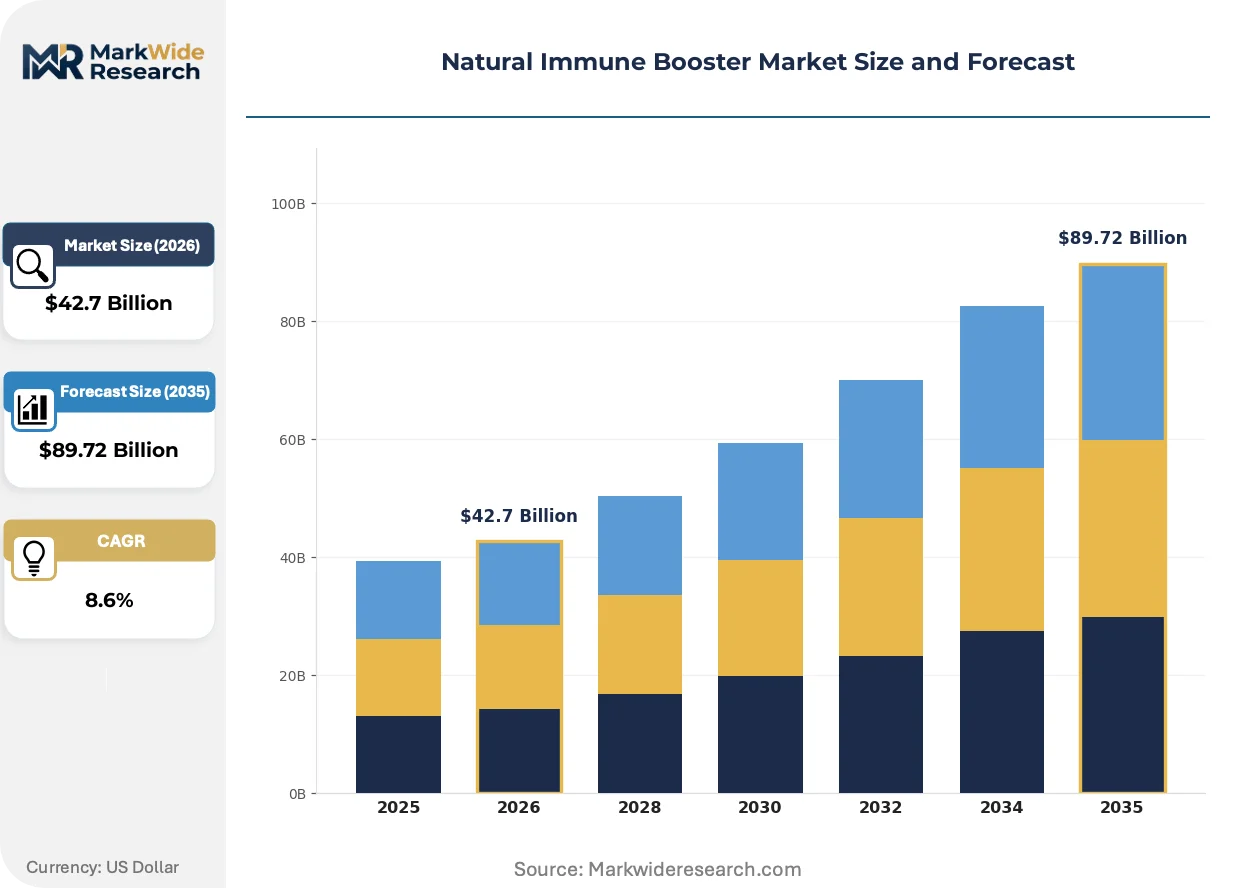
Market Dynamics
Subscription-based replenishment programs are restructuring distribution economics in natural immune boosters, converting episodic purchases into recurring revenue streams with measurable lifetime value and inventory predictability for manufacturers.
Growth Catalysts
- EFSA Health Claim Assessments:The European Food Safety Authority's tightening evidentiary standards for immunity-related marketing claims are redirecting R&D investment toward randomized controlled trials, creating sustainable competitive moats for substantiated formulations.
- Microbiome Science Validation:Strain-specific immune mechanisms documented in peer-reviewed research are accelerating probiotic category expansion beyond digestive health into systemic immunomodulation applications.
- Germany Pharmacy Channel Concentration:Consumer trust in pharmacy-dispensed probiotics and herbal supplements in German-speaking markets is driving premium pricing power and repeat purchase rates unmatched by mass retail channels.
Market Restraints
- FDA New Dietary Ingredient Notifications:The notification requirement for novel botanical extracts and microbial strains imposes documentation burdens that filter marginal suppliers from domestic shelf access and extend product development timelines.
- Organic Cultivation Input Volatility:Weather-dependent yields for echinacea, elderberry, and astragalus root concentrates create raw material cost instability for vertically integrated herb suppliers.
- Clinical Validation Cost Burden:Randomized controlled trials required for regulatory-compliant immunity claims demand capital commitments that disadvantage mid-tier formulators lacking pharmaceutical partnerships.
Strategic Opportunities
- India AYUSH Ministry Dual-Track Licensing:The FSSAI and CDSCO joint oversight framework protects traditional Ayurvedic knowledge while imposing modern quality benchmarks, creating protected market access for heritage brands with documented manufacturing lineage.
- Gummies Format Adult Penetration:Palatability-driven compliance improvements in daily regimens among senior and working-age adult segments are opening formulation differentiation beyond traditional capsules and tablets.
- Sports Nutrition Adjuvant Protocols:Evidence-backed immunomodulation for infection susceptibility reduction is expanding addressable demand into athletic performance and recovery applications with higher per-unit pricing tolerance.
Industry Challenges
- Polysaccharide Standardization Expertise:Marker compound quantification for botanical extracts requires analytical chemistry capabilities that concentrate among specialized contract laboratories, creating quality control bottlenecks for emerging brands.
- Cross-Jurisdictional Substantiation Mapping:Divergent evidentiary requirements between FDA, EFSA, and India's AYUSH frameworks force parallel clinical investment strategies with uncertain returns in any single geography.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Immune Booster Market |
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $89.72 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Supplements, Vitamins, Probiotics, Minerals Form: Capsules, Powders, Liquids, Gummies Distribution Channel: Online Retail, Health Stores, Pharmacies, Supermarkets Consumer Segment: Adults, Children, Seniors, Athletes |
| Companies Covered | Dabur India Ltd., Garden of Life, Amway Corporation, Gaia Herbs, Nature's Way, Herbalife Nutrition Ltd., NOW Foods, Himalaya Wellness, Blackmores Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Immune Booster Market Strategic Shifts
Digital health integration and personalized nutrition platforms are reconfiguring how immune booster formulations reach consumers, shifting from mass-market SKUs toward algorithm-matched supplement stacks with biometric feedback loops.
Direct-to-consumer microbiome testing paired with strain-specific probiotic recommendations is decentralizing immune health management from clinical settings into home-based monitoring ecosystems. Wellness platforms in North American and European markets are integrating stool analysis results with automated supplement subscription fulfillment. This decentralization of diagnostic authority is compressing the traditional physician-pharmacy-consumer triad into platform-mediated relationships.
India's FSSAI notification requirements for Ayurvedic product licensing under AYUSH ministry oversight are harmonizing traditional knowledge documentation with pharmaceutical-grade manufacturing standards. Domestic formulators must now submit evidence of marker compound consistency alongside classical textual references. Herbal supplement exporters to European markets are responding by investing in in-house chromatography capabilities rather than relying on third-party certificates.
Palatability engineering in gummy formats is displacing capsule compliance barriers among adult demographics previously resistant to daily supplement regimens. German pharmacy chains are expanding private-label gummy offerings across vitamin D, zinc, and elderberry combinations. Senior consumers in urban clusters demonstrate measurably higher adherence rates when taste masking eliminates the swallowing friction associated with traditional delivery forms.
Natural Immune Booster Market Segmentation
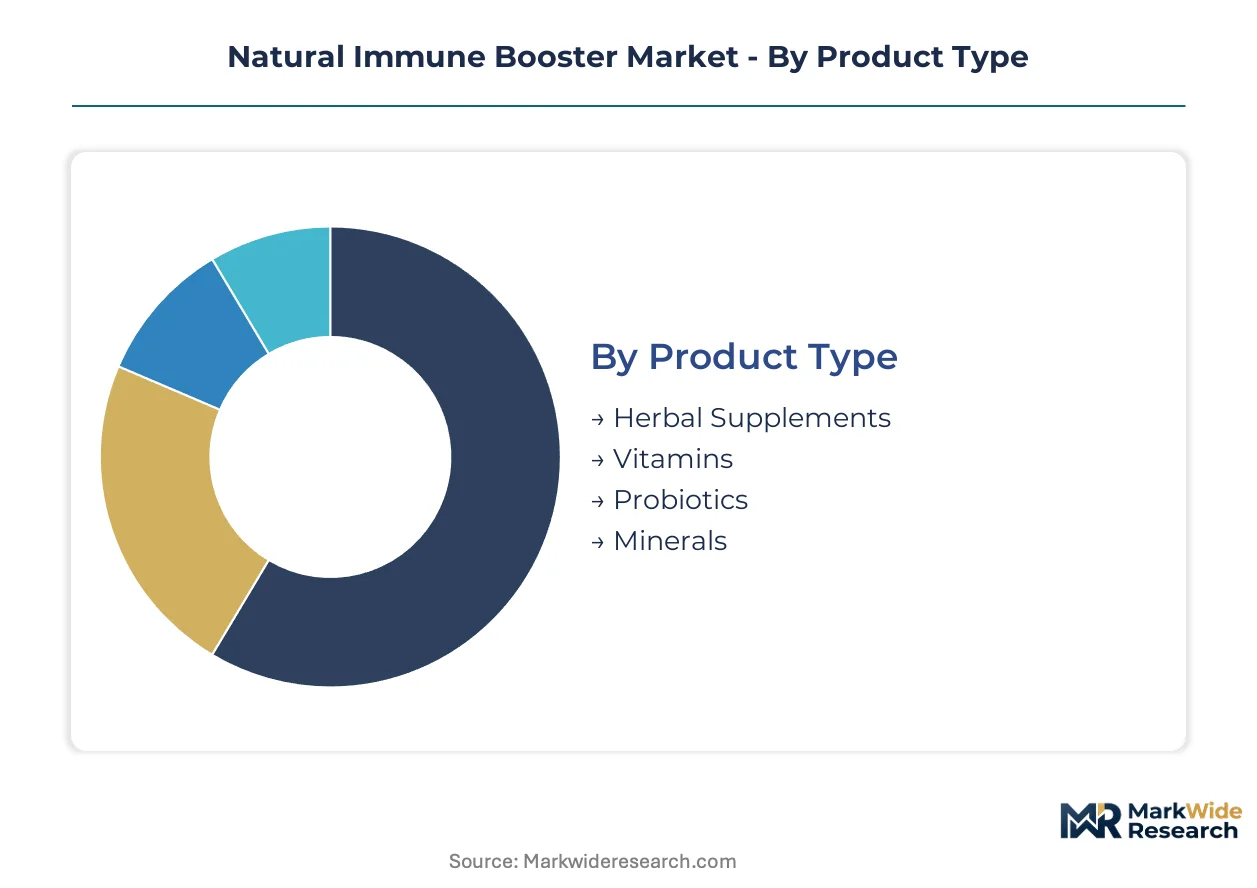
Segmentation in natural immune boosters reveals divergent margin structures and regulatory exposure across delivery formats and channel strategies. Formulators targeting pharmacy networks face substantiation burdens that mass-market online sellers circumvent, creating tiered competitive arenas with distinct capital requirements.
Product Type:
Volume concentration favors established botanical categories with centuries of traditional use, while premium pricing power clusters around microbiome-targeted innovations with clinical validation.
- Herbal Supplements:Standardized botanical extracts from echinacea, elderberry, and astragalus root deliver polysaccharide and flavonoid compounds with documented immunomodulatory effects. Pharmacy-channel demand in Germany and Austria sustains premium positioning for heritage formulations with AYUSH ministry documentation in India.
- Probiotics:Strain-specific microbial cultures modulate systemic immune responses through gut-associated lymphoid tissue activation. Microbiome testing platforms in North American markets are accelerating personalized probiotic matching with subscription-based replenishment models.
- Vitamins:Liposomal and micellar delivery technologies enhance bioavailability of fat-soluble immune modulators.
- Minerals:Chelated zinc and selenium formulations address trace element deficiencies linked to impaired lymphocyte function.
Mature deployment sits with Herbal Supplements. Newer deployment is concentrated in Probiotics.
Form:
Palatability engineering is restructuring adult compliance patterns and reordering manufacturing investment priorities across delivery technologies.
- Gummies:Gelatin and pectin matrices mask bitter botanical compounds while enabling precise dosing of vitamins and minerals. Senior consumers in urban German clusters demonstrate measurably higher adherence rates compared to traditional swallowable formats.
- Capsules:Two-piece hard gelatin and vegetarian shells protect acid-sensitive probiotics from gastric degradation. Sports nutrition applications favor enteric-coated variants for systemic delivery of anti-inflammatory botanicals.
- Powders:Bulk formats serve functional food fortification and clinical adjuvant protocols requiring dose titration.
- Liquids:Tincture and suspension formats accommodate pediatric populations and dysphagia patients.
Volume leadership remains with Capsules. Gummies are climbing the fastest among adult demographics.
Distribution Channel:
Channel selection determines regulatory scrutiny intensity and consumer trust transfer mechanisms in immune health purchasing decisions.
- Pharmacies:Licensed dispensaries in German-speaking markets command price premiums through pharmacist consultation and insurance reimbursement pathways. EFSA health claim substantiation requirements filter unsubstantiated competitors from shelf access.
- Online Retail:Direct-to-consumer platforms leverage microbiome test integration and algorithm-driven subscription stacks. FDA NDI notification gaps in e-commerce enforcement create asymmetric competitive pressure on domestic manufacturers.
- Health Stores:Specialty retailers emphasize organic certification and vertically integrated supply chain transparency.
- Supermarkets:Mass retail placement demands economies of scale and private-label manufacturing partnerships.
Trust concentration centers on Pharmacies. Subscription velocity is expanding most quickly through Online Retail.
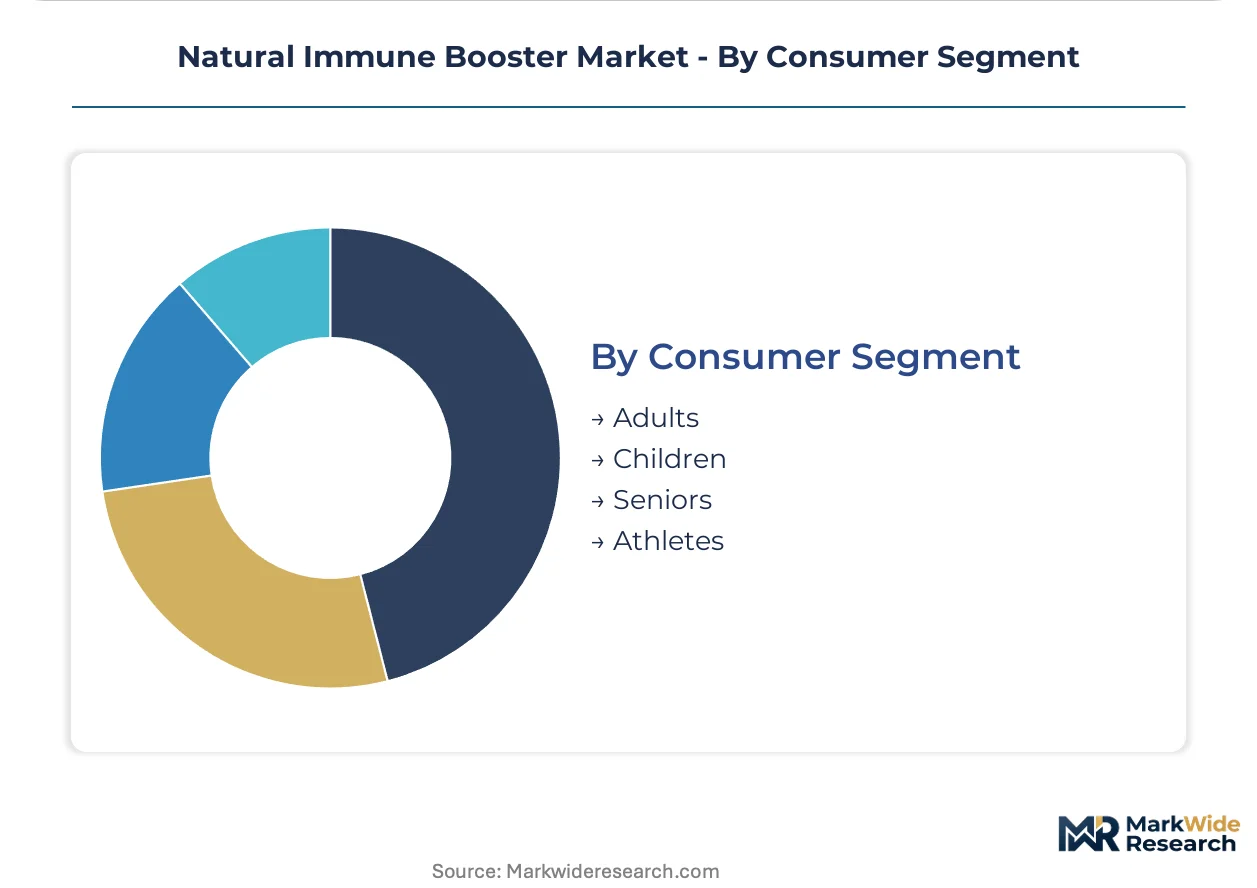
Consumer Segment:
Demographic targeting aligns formulation complexity with infection susceptibility profiles and compliance capability variations.
- Seniors:Declining immune senescence drives demand for zinc, vitamin D, and polysaccharide-rich botanicals with anti-inflammatory properties. Gummy formats eliminate swallowing barriers that previously truncated regimen adherence.
- Athletes:Training load immunosuppression creates demand for evidence-backed infection prevention with higher per-unit pricing tolerance. Sports nutrition brands integrate immune stacks into recovery protocol bundles.
- Adults:Working-age preventive health spending concentrates in subscription-based replenishment programs.
- Children:Pediatric formulations prioritize palatability and allergen exclusion with parental safety verification.
Premium pricing tolerance peaks with Athletes. Gaining share fastest among Seniors due to format innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of botanical raw materials concentrates in India and China, while consumption clusters in Germany and the United States where pharmacy and direct-to-consumer channels command premium pricing. Regulatory divergence between FDA notification requirements and EFSA substantiation standards fragments market access strategies.
Germany
Pharmacy-channel probiotics and herbal supplements sustain premium positioning unmatched by mass retail. EFSA health claim assessments enforce randomized controlled trial evidence for immunity marketing, filtering unsubstantiated competitors from licensed dispensary shelves. Berlin and Munich clusters host vertically integrated herb suppliers serving German-speaking markets with documented polysaccharide standardization.
United States
Subscription-based replenishment programs and microbiome testing platforms accelerate direct-to-consumer penetration among working-age adults. FDA New Dietary Ingredient notification requirements impose documentation burdens that extend development timelines for novel botanical extracts. North Carolina's organic cultivation belt anchors Gaia Herbs' vertically integrated supply chain for pharmacy and specialty retail distribution.
India
AYUSH ministry dual-track licensing protects traditional Ayurvedic knowledge while imposing FSSAI quality benchmarks on domestic and export formulations. Heritage brands leverage documented manufacturing lineage to sustain pharmacy network loyalty across South Asia. Maharashtra and Gujarat industrial corridors concentrate contract manufacturing capacity for standardized herbal extracts targeting European compliance.
China
Traditional Chinese medicine ingredient cultivation supplies global demand for astragalus root and polysaccharide-rich botanical concentrates. NMPA oversight of health food registration creates parallel substantiation pathways distinct from Western regulatory frameworks. Zhejiang and Yunnan provinces host extraction facilities serving both domestic TCM practitioners and export markets seeking marker compound documentation.
Australia
TGA listing requirements for complementary medicines enforce manufacturing quality standards that support export credibility into Southeast Asian markets. Blackmores Limited exemplifies heritage brand positioning through pharmacy and practitioner channels. Sydney and Melbourne clusters concentrate regulatory consulting expertise guiding clinical trial design for EFSA-aligned substantiation.
Natural Immune Booster Market Competitive Environment
Top-tier vendors anchor pharmacy and practitioner channels with substantiated formulations, while mid-tier competitors compete on manufacturing scale and private-label capacity. The vendor base stratifies across heritage Ayurvedic houses, vertically integrated organic cultivators, and contract manufacturers supplying multiple retail tiers. Three archetypes dominate: documentation-heavy heritage brands, backward-integrated herb suppliers, and scale-driven private-label formulators. Competitive moves concentrate on clinical validation partnerships and subscription platform integration.
Within the heritage Ayurvedic tier, Dabur India Ltd. and Himalaya Wellness exemplify brands leveraging documented manufacturing lineage and pharmacy network density. Gaia Herbs occupies a position among vertically integrated organic cultivators with captive North Carolina production. NOW Foods represents scale-driven manufacturing specialists supplying standardized potency guarantees across retail tiers. These three anchors illustrate divergent capital allocation strategies between clinical substantiation, supply chain control, and manufacturing throughput.
| Leading Market Players |
|---|
| Dabur India Ltd. |
| Garden of Life |
| Amway Corporation |
| Gaia Herbs |
| Nature's Way |
| Herbalife Nutrition Ltd. |
| NOW Foods |
| Himalaya Wellness |
| Blackmores Limited |
| Others |
Value Chain & Pricing Dynamics
Polysaccharide concentrate costs for elderberry and astragalus root extracts cascade through three-tier pricing structures across premium, standard, and economy levels, with German pharmacy networks commanding 40-60% markups over mass retail channels due to EFSA substantiation requirements and pharmacist consultation value.
Pricing Analysis
Margin tightening in mid-tier formulations reflects FDA New Dietary Ingredient notification burdens that extend development timelines and concentrate R&D spending among capitalized players. Price differentiation separates pharmacy-dispensed heritage brands with AYUSH documentation from direct-to-consumer entrants lacking clinical validation. Cost-down pressure on economy-tier private-label suppliers accelerates as supermarket buyers consolidate procurement around manufacturing scale guarantees. Athletes demonstrate lowest price sensitivity due to per-unit pricing tolerance for infection prevention protocols, while senior gummy consumers prioritize palatability over cost optimization.
Supply Chain Analysis
Returns of expired botanical inventory from German pharmacy chains flow back to North Carolina and Maharashtra extraction facilities for marker compound recovery and reformulation. Raw material sourcing draws from Zhejiang province astragalus cultivation, Yunnan polysaccharide-rich botanical corridors, and Gujarat contract manufacturing clusters. Single-source vulnerability concentrates in weather-dependent organic herb yields where echinacea and elderberry harvest volatility creates input cost instability. Distribution runs through pharmacy networks in German-speaking markets, direct-to-consumer subscription platforms in North America, and AYUSH-licensed dispensaries across South Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clinical validation cost burdens and tightening EFSA substantiation standards are forcing marginal formulators toward exit or acquisition, consolidating competitive position among heritage brands and vertically integrated cultivators with documented manufacturing lineage.
For Market Incumbents: Hedge against microbiome testing platform disintermediation by integrating subscription-based replenishment programs with captive strain-specific probiotic development. Defensive consolidation moves include acquiring specialized contract laboratories for polysaccharide standardization capabilities and deepening backward integration into organic cultivation belts to secure marker compound consistency against weather-driven yield volatility. For New Entrants and Emerging Players: Enter via gummy format innovation targeting senior compliance gaps in urban German clusters where palatability engineering commands premium positioning unmatched by swallowable alternatives. White-space targets include sports nutrition adjuvant protocols for training load immunosuppression and algorithm-matched supplement stacks paired with at-home microbiome testing platforms in North American direct-to-consumer channels. For Investors and Strategic Acquirers: EFSA health claim assessment rejections for unsubstantiated immunity marketing is the leading indicator that clinical validation partnerships will separate viable acquisition targets from stranded assets. Long-term viability over the next decade hinges on documented randomized controlled trial evidence and AYUSH ministry licensing lineage. Target acquisition archetypes include vertically integrated organic cultivators with captive North Carolina or Zhejiang production and specialized contract laboratories with chromatography capabilities for marker compound quantification.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Validation Partnership | Randomized controlled trial investment creates sustainable competitive moats against EFSA rejection risk. |
| Backward Integration into Cultivation | Captive organic herb production in North Carolina or Zhejiang secures polysaccharide supply against weather volatility. |
| Subscription Platform Integration | Algorithm-matched replenishment programs convert episodic purchases into recurring revenue with predictable lifetime value. |
| Gummy Format R&D Investment | Palatability engineering eliminates swallowing barriers and drives senior adherence rates above traditional capsules. |
| AYUSH Licensing Documentation | FSSAI quality benchmarks combined with classical textual references protect traditional knowledge while enabling European export compliance. |
Study Parameters
Independent corroboration across regulatory affairs directors at heritage Ayurvedic houses, pharmacy procurement managers in German-speaking markets, and contract manufacturing executives in Maharashtra and Gujarat underwrites the qualitative findings. Primary interviews with EFSA health claim assessment consultants, FDA compliance officers, and microbiome testing platform operators combined with secondary validation from AYUSH ministry licensing databases, FSSAI notification records, and EFSA scientific opinion archives. Bottom-up segmentation modeling triangulates against top-down market sizing from customs trade data and pharmacy channel audit records.
Comparable-period anchoring to historical subscription velocity and pharmacy-channel replenishment patterns structures the projection horizon across product type, delivery format, distribution channel, and consumer segment dimensions. CAGRs derive from growth driver elasticity modeling calibrated to preventive healthcare spending trends and microbiome science publication velocity. Forecast inputs include strain-specific probiotic clinical trial pipelines, gummy format manufacturing capacity expansion announcements, and EFSA health claim assessment queue backlogs.
Revisions become necessary when EFSA substantiation standards tighten beyond current randomized controlled trial evidence thresholds, when FDA NDI notification enforcement gaps in e-commerce channels close abruptly, or when organic cultivation yields collapse due to extreme weather events in concentrated growing regions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Argentina Nutraceuticals Market
Nutritional Supplements
Bone Meal Supplement Market
Nutritional Supplements
Nutritional Supplements Market
Nutritional Supplements
Medium Chain Triglyceride (MCT) Food Market
Nutritional Supplements
CBD Nutraceuticals Market
Nutritional Supplements
Medicinal Mushroom Supplement Market
Nutritional Supplements
Plant Based Iron Supplements Market
Nutritional Supplements
Global Elderly Nutrition Market
Nutritional Supplements
Europe Meal Replacement Products Market
Nutritional Supplements
Diet Pills Market
Nutritional Supplements
Global Ashwagandha Extract Market
Nutritional Supplements
Vegan Protein Powder Market
Nutritional Supplements
Immunity Boosting Food Market
Nutritional Supplements
Olive Supplements Market
Nutritional Supplements
Oral Immunostimulant Market
Nutritional Supplements
Vegan Supplements Market