
 Europe Botanical Supplements Market | 2026-2036
Europe Botanical Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Botanical Supplements Market Foresight
Pharmacy retail channels across Europe is narrowing as a trusted gatekeeper for botanical supplement access, with regulatory verification replacing open-shelf credibility. NOW Foods leverages its manufacturing scale to sustain pharmacy shelf presence in German-speaking markets. Glanbia plc anchors its position through backward integration into botanical raw material sourcing. Zein Pharma differentiates via specialization in standardized herbal extracts that meet EFSA monograph requirements.
Europe botanical supplements comprise plant-derived preparations containing bioactive compounds such as alkaloids, polyphenols, and terpenoids, extracted through solvent-based or supercritical CO2 methods and formulated for oral delivery to support physiological function or nutritional status. Herbal extracts command the deepest margin pools due to standardization complexity and clinical substantiation requirements, while capsules lead volume through convenience-driven adoption among older adults. Online retail channels represent the fastest-growing distribution vector as direct-to-consumer verification tools replace traditional pharmacy consultation.
EFSA novel food assessments, REACH compliance for extraction solvents, and EU Green Deal traceability mandates collectively elevate compliance costs while filtering out unverified suppliers. EMA herbal monographs provide the reference framework that German and French national regulators use to approve pharmacy-distributed indications. Stakeholders must monitor whether EFSA expands botanical health claim approvals beyond the current restrictive list, as this determination will reshape which ingredient categories achieve mass-market scale.
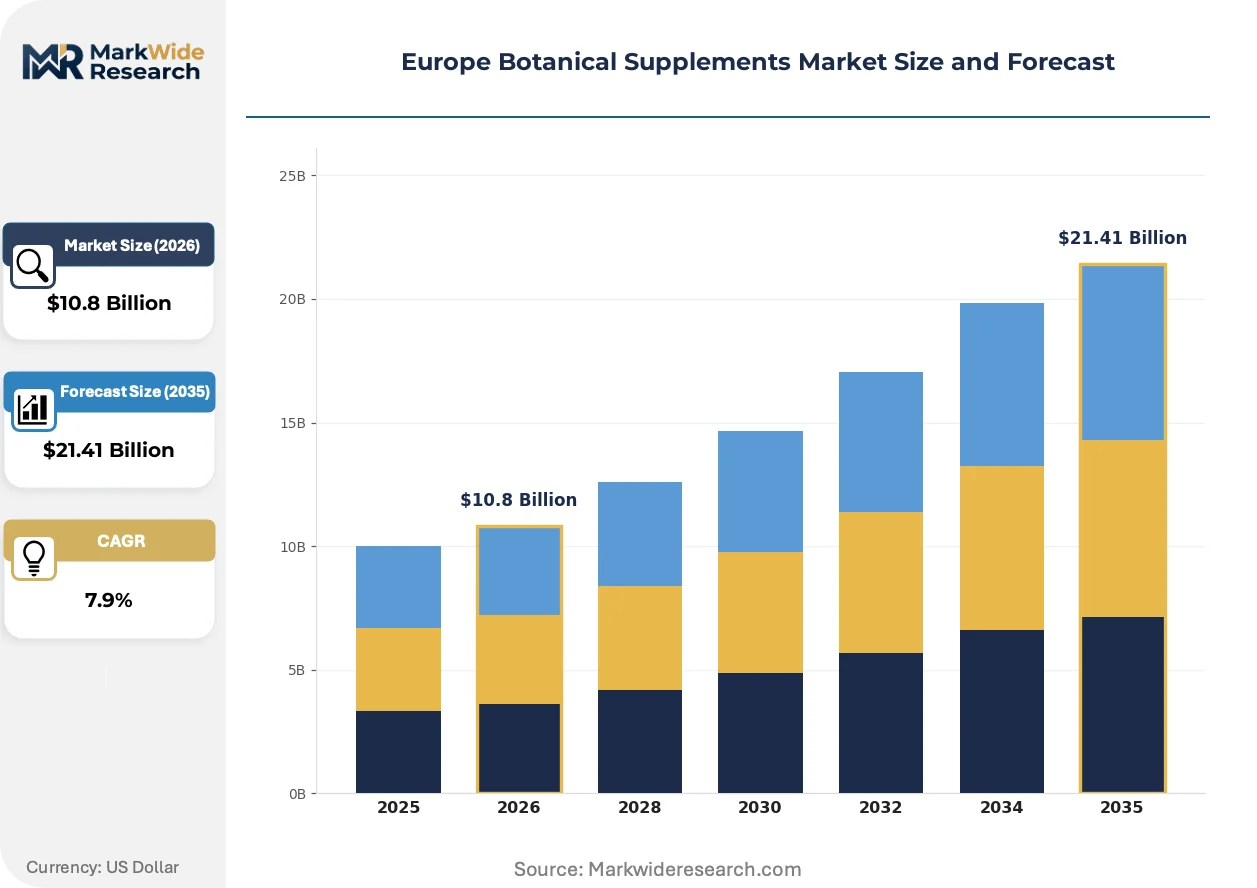
Market Dynamics
EFSA novel food assessments and EU Green Deal traceability mandates are compressing supplier margins while elevating pharmacy-channel credibility as the dominant gatekeeper for verified botanical access across the continent.
Growth Catalysts
- Preventive wellness pivot:Health enthusiasts across Germany and France are redirecting spending from reactive care toward daily botanical regimens, expanding pharmacy-distributed SKUs beyond traditional herbal indications.
- EMA herbal monograph harmonization:National regulators in German-speaking markets now reference centralized efficacy standards, accelerating cross-border product registration and reducing duplicate clinical substantiation costs.
- Supercritical CO2 extraction scale-up:Equipment manufacturers in Italy and Spain are deploying larger-capacity systems, cutting per-unit solvent residue testing burdens and unlocking terpenoid-rich extract categories for mass-market formulation.
Market Restraints
- Wild-harvested raw material volatility:Climate stress on Alpine and Mediterranean growing regions is compressing supply windows for standardized St. John's Wort and milk thistle, forcing contract renegotiations mid-season.
- REACH solvent compliance layering:ECHA registration requirements for ethanol and hexane extraction media are adding documentation costs that disproportionately burden small-batch artisanal producers.
- Synthetic nootropic substitution:Lab-derived cognitive enhancers with faster onset claims are capturing share among younger demographics in Nordic markets, pressuring ginkgo and bacopa volume.
Strategic Opportunities
- Polish and Romanian pharmacy network expansion:Underdeveloped herbal supplement penetration in Eastern European pharmacy chains offers first-mover positioning before EFSA health claim harmonization raises competitive barriers.
- CSRD-driven ingredient storytelling:Corporate sustainability reporting mandates are creating procurement premiums for suppliers with blockchain-verified organic certification and regenerative agriculture partnerships.
- Telehealth-integrated subscription models:German digital health platforms are bundling personalized botanical protocols with remote practitioner consultations, bypassing traditional pharmacy foot traffic dependence.
Industry Challenges
- Phytochemical standardization talent scarcity:Analytical chemists capable of HPLC method development for complex polyphenol matrices command premium salaries that mid-tier extract houses struggle to match.
- Novel food approval timeline compression:EFSA's 18-24 month safety assessment queue for non-traditional botanicals is freezing innovation pipelines and accelerating working capital burn for R&D-heavy portfolios.
- Multi-jurisdiction labeling fragmentation:Divergent national health claim interpretations between France's ANSM and Germany's BfArM force SKU proliferation, complicating pan-European inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Botanical Supplements Market |
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $21.41 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Extracts, Essential Oils, Powders, Capsules End User: Health Enthusiasts, Athletes, Older Adults, Consumers Form: Liquid, Solid, Powder, Gel Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores |
| Companies Covered | Himalaya Wellness Latvia SIA, Gaia Herbs Farm, GNC Holdings, NOW Foods, Zein Pharma, Glanbia plc, Ricola, Nutraceutical International Corporation, Givaudan, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Botanical Supplements Market Shifts & Advancements
Digital verification infrastructure and precision extraction technologies are compressing traditional quality assurance timelines while redirecting consumer trust from physical pharmacy consultation toward algorithmic transparency tools.
Supercritical CO2 extraction systems with integrated online analytics are rendering obsolete batch-based solvent residue testing protocols that previously required third-party laboratory turnaround. German contract manufacturers are adopting these platforms to secure pharmacy chain supply agreements demanding real-time certificate-of-analysis access. The technology is rendering obsolete the 7-14 day quality hold periods that previously constrained just-in-time production scheduling.
EU Green Deal deforestation-free supply chain regulations are mandating geolocation verification for all harvested botanical raw materials entering European formulation facilities. EFSA enforcement timelines are compressing supplier onboarding windows and forcing backward integration into traceable cultivation partnerships. French and Italian extract houses are responding by acquiring direct equity stakes in Moroccan and Bulgarian growing cooperatives.
Direct-to-consumer verification apps are displacing pharmacist-mediated ingredient education as the primary trust mechanism for first-time buyers. Nordic consumers increasingly scan QR-linked blockchain records before purchase, bypassing retail staff consultation entirely. This behavioral pivot is most pronounced in Swedish and Danish online channels, where subscription retention correlates with transparency tool engagement rather than brand heritage.
Europe Botanical Supplements Market Segmentation
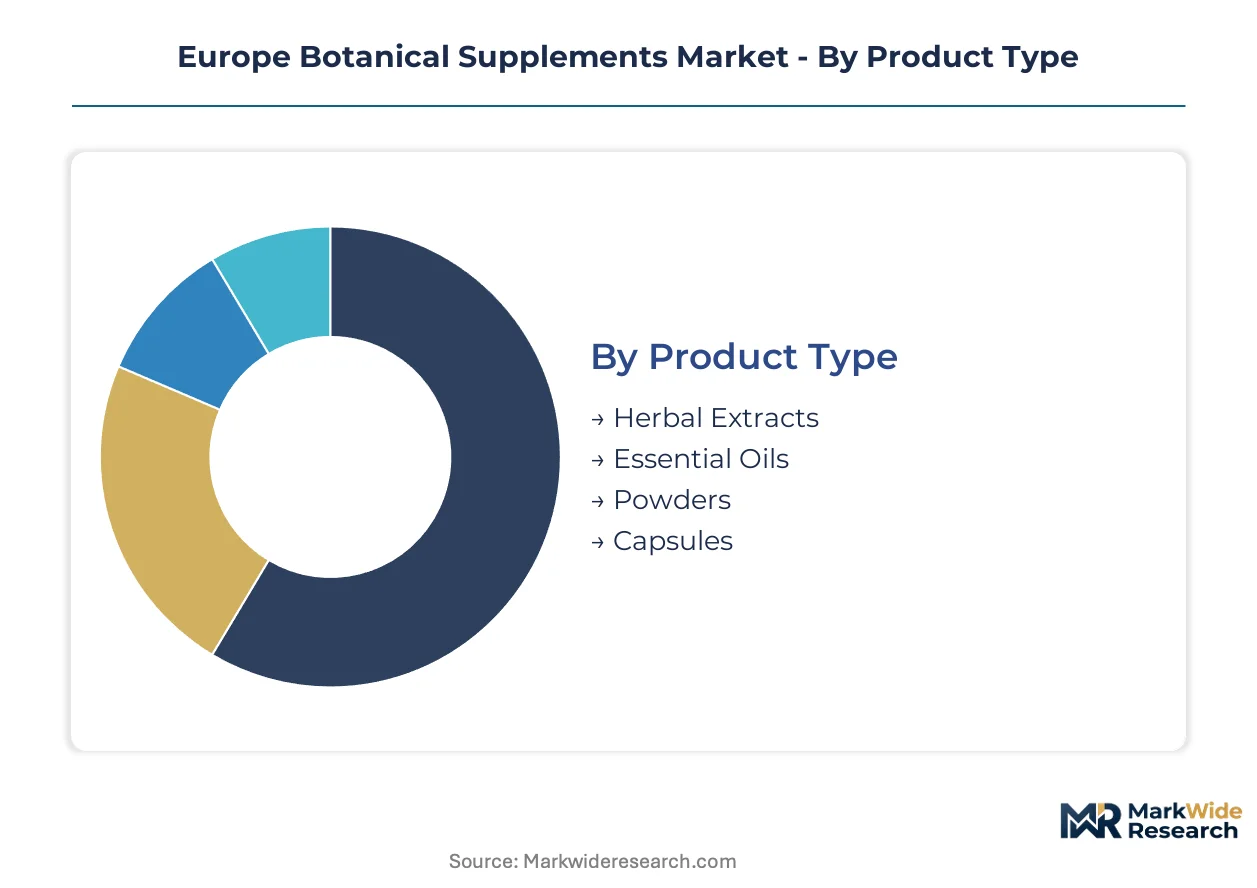
Botanical supplement segmentation in Europe reflects divergent regulatory pathways and consumer trust mechanisms. Product format and channel choice determine compliance burden and margin structure across national markets.
Product Type:
Mature standardized formats dominate pharmacy shelf space while emerging delivery systems capture direct-to-consumer growth.
- Herbal Extracts:Concentrated bioactive preparations standardized to specific alkaloid or polyphenol content through HPLC-verified methods. German and French pharmacy networks concentrate demand for EMA-monographed extracts as prescribers seek clinically substantiated alternatives. REACH compliance for residual solvents elevates production costs and filters artisanal suppliers from pharmacy distribution.
- Capsules:Gelatin or hydroxypropyl methylcellulose shells containing dried botanical powders or standardized extracts. Older adult consumers across Italy and Spain drive volume through convenience-driven adherence to daily regimens. EFSA novel food assessments for non-traditional botanicals slow innovation pipelines for capsule line extensions.
- Essential Oils:Steam-distilled or cold-pressed volatile compounds for aromatherapeutic and topical applications.
- Powders:Milled raw botanical material or spray-dried extracts for flexible dosing and functional food integration.
Herbal extracts handle the majority of throughput; capsules are the fastest mover on share.
End User:
Customer archetypes span preventive wellness adopters to condition-specific seekers with distinct channel preferences and price sensitivity profiles.
- Health Enthusiasts:Proactive consumers integrating botanicals into daily preventive protocols without diagnosed conditions. Nordic markets concentrate this cohort where digital health platforms bundle personalized subscriptions with telehealth consultations. EFSA health claim restrictions force reliance on brand trust and transparency tools rather than approved indications.
- Older Adults:Age-related consumers seeking mobility, cognitive, and cardiovascular support through pharmacy-vetted products. German pharmacy chains capture this segment through pharmacist-mediated consultation and insurance-adjacent positioning. Supercritical CO2 extraction scale-up enables terpenoid-rich formulations targeting inflammation management.
- Athletes:Performance-oriented consumers prioritizing recovery and adaptogenic support with batch-tested certification requirements.
- Consumers:General purchasers responding to mass-market marketing and retail availability without segment-specific health positioning.
Older adults handle the majority of throughput; health enthusiasts are expanding most quickly.
Form:
Physical state determines stability requirements, bioavailability claims, and manufacturing equipment investment across contract manufacturing networks.
- Liquid:Tinctures, syrups, and liposomal suspensions offering rapid absorption claims and flexible dosing. Italian contract manufacturers concentrate production for pharmacy-distributed pediatric and geriatric lines where swallowing difficulties drive format preference. EMA herbal monograph liquid dosage form specifications harmonize cross-border registration requirements.
- Solid:Tablets, caplets, and compressed forms requiring excipient compatibility and dissolution profile optimization. Spanish manufacturing clusters leverage equipment scale for pan-European private label supply to supermarket chains. CSRD reporting mandates pressure solid form producers to document supply chain geolocation verification.
- Powder:Bulk material for compounding, functional food integration, or consumer-measured dosing.
- Gel:Semi-solid preparations for topical delivery and buccal absorption applications.
Solid forms handle the majority of throughput; liquid preparations are gaining share fastest.
Distribution Channel:
Channel structure reflects the tension between regulatory verification and convenience-driven purchasing behavior across European markets.
- Pharmacies:Licensed dispensaries with pharmacist consultation and EMA-monographed product access. German-speaking markets concentrate pharmacy-distributed botanical sales where national regulators reference centralized efficacy standards. EU Green Deal traceability mandates elevate credibility for pharmacy-sourced products with documented supply chain verification.
- Online Retail:Direct-to-consumer platforms with algorithmic personalization and blockchain transparency tools. Swedish and Danish consumers drive this channel where QR-linked verification replaces retail staff consultation entirely. Subscription retention correlates with transparency tool engagement rather than traditional brand heritage.
- Supermarkets:Mass-market retail with limited shelf space for commoditized single-ingredient products.
- Specialty Stores:Health food and organic retail with curated assortments targeting informed botanical purchasers.
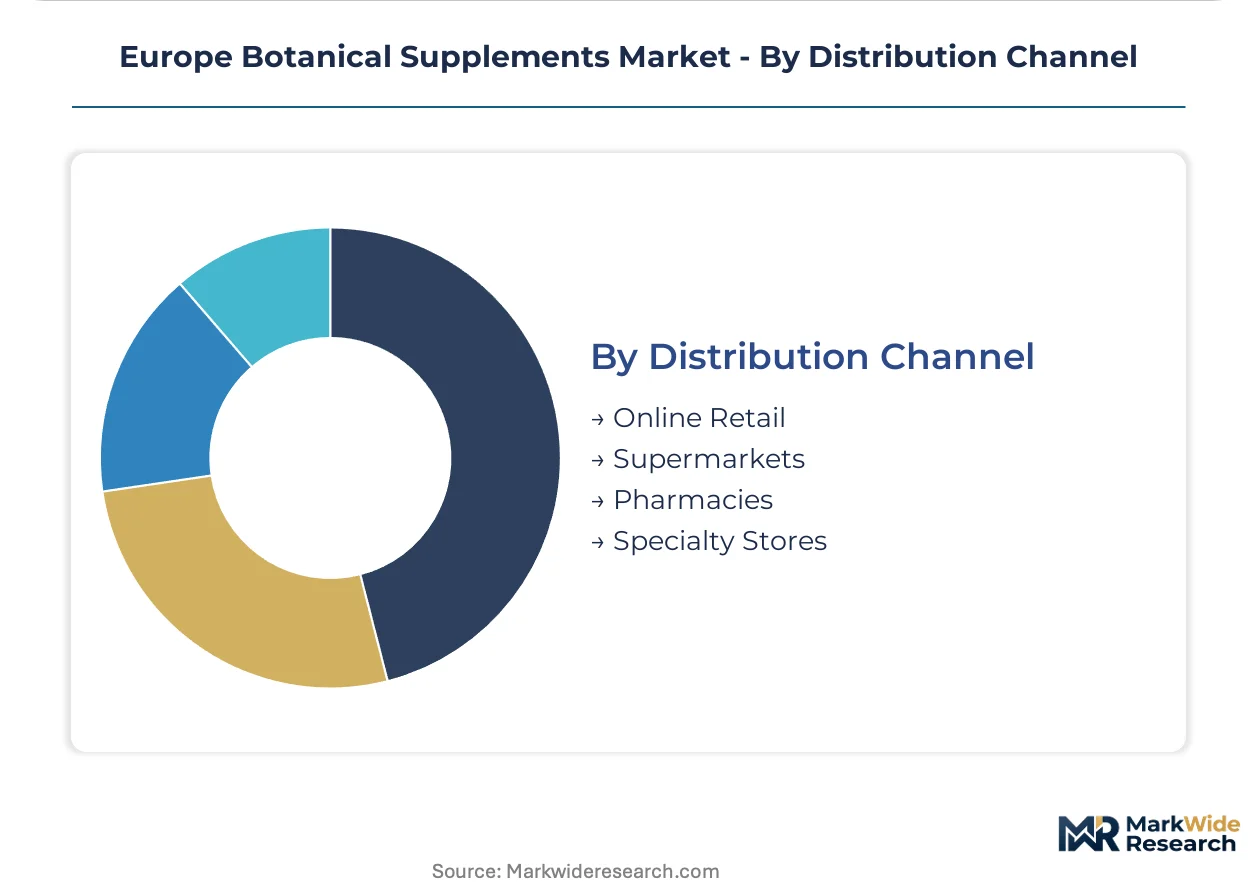
Pharmacies handle the majority of throughput; online retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine Corridor freight network underwrites Germany's dominance in botanical supplement distribution, connecting Dutch ports to Swiss and Italian manufacturing clusters with refrigerated capacity for temperature-sensitive extracts.
Germany
Pharmacy chains in Bavaria and North Rhine-Westphalia drive demand for EMA-monographed extracts as preventive wellness protocols displace reactive care. BfArM enforces centralized efficacy standards that accelerate cross-border registration for pharmacy-distributed products. Contract manufacturers around Frankfurt deploy supercritical CO2 systems with integrated analytics to secure real-time certificate-of-analysis access for pharmacy supply agreements.
France
ANSM labeling requirements create compliance premiums for standardized herbal extracts targeting older adults in the Île-de-France region. The EU Green Deal deforestation-free regulations mandate geolocation verification for Moroccan argan and Bulgarian rosehip entering French formulation facilities. Lyon-based extract houses acquire equity stakes in Mediterranean growing cooperatives to secure traceable supply.
Italy
Italian contract manufacturers concentrate liquid dosage production in Lombardy and Emilia-Romagna for pharmacy-distributed pediatric and geriatric lines. EMA herbal monograph specifications for liquid forms harmonize cross-border registration with German-speaking markets. Turin equipment suppliers deploy larger-capacity supercritical CO2 systems that cut per-unit solvent residue testing burdens for terpenoid-rich extracts.
Sweden
Digital health platforms in Stockholm and Gothenburg bundle personalized botanical subscriptions with telehealth consultations, bypassing traditional pharmacy dependence. GDPR-compliant transparency apps displace pharmacist-mediated education as the primary trust mechanism for first-time buyers. Malmö logistics clusters support Nordic direct-to-consumer fulfillment with blockchain-verified supply chain documentation.
Poland
Underdeveloped herbal supplement penetration in Warsaw and Kraków pharmacy chains offers first-mover positioning before EFSA health claim harmonization raises barriers. CSRD reporting mandates create procurement premiums for suppliers with regenerative agriculture partnerships. Poznan manufacturing zones attract German contract manufacturers seeking lower-cost HPLC method development capacity for polyphenol standardization.
Europe Botanical Supplements Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: multinational ingredient houses with backward integration into raw material sourcing, mid-scale extract specialists with EFSA monograph compliance capabilities, and regional pharmacy distributors with localized registration expertise. Dominant competitive moves include geographic expansion into underpenetrated Eastern European pharmacy networks and technology licensing for supercritical CO2 extraction scale-up.
Among the named participants, Himalaya Wellness Latvia SIA occupies a position within the regional distribution archetype, leveraging Baltic logistics access for pan-European pharmacy penetration. NOW Foods exemplifies the scale-driven manufacturing tier with sustained pharmacy shelf presence in German-speaking markets. Zein Pharma and Glanbia plc represent contrasting specialization strategies: the former sits within the standardized extract tier with EFSA monograph alignment, while the latter anchors the backward-integrated ingredient house archetype through captive raw material sourcing.
| Leading Market Players |
|---|
| Himalaya Wellness Latvia SIA |
| Gaia Herbs Farm |
| GNC Holdings |
| NOW Foods |
| Zein Pharma |
| Glanbia plc |
| Ricola |
| Nutraceutical International Corporation |
| Givaudan |
| Others |
Supply & Pricing Matrix
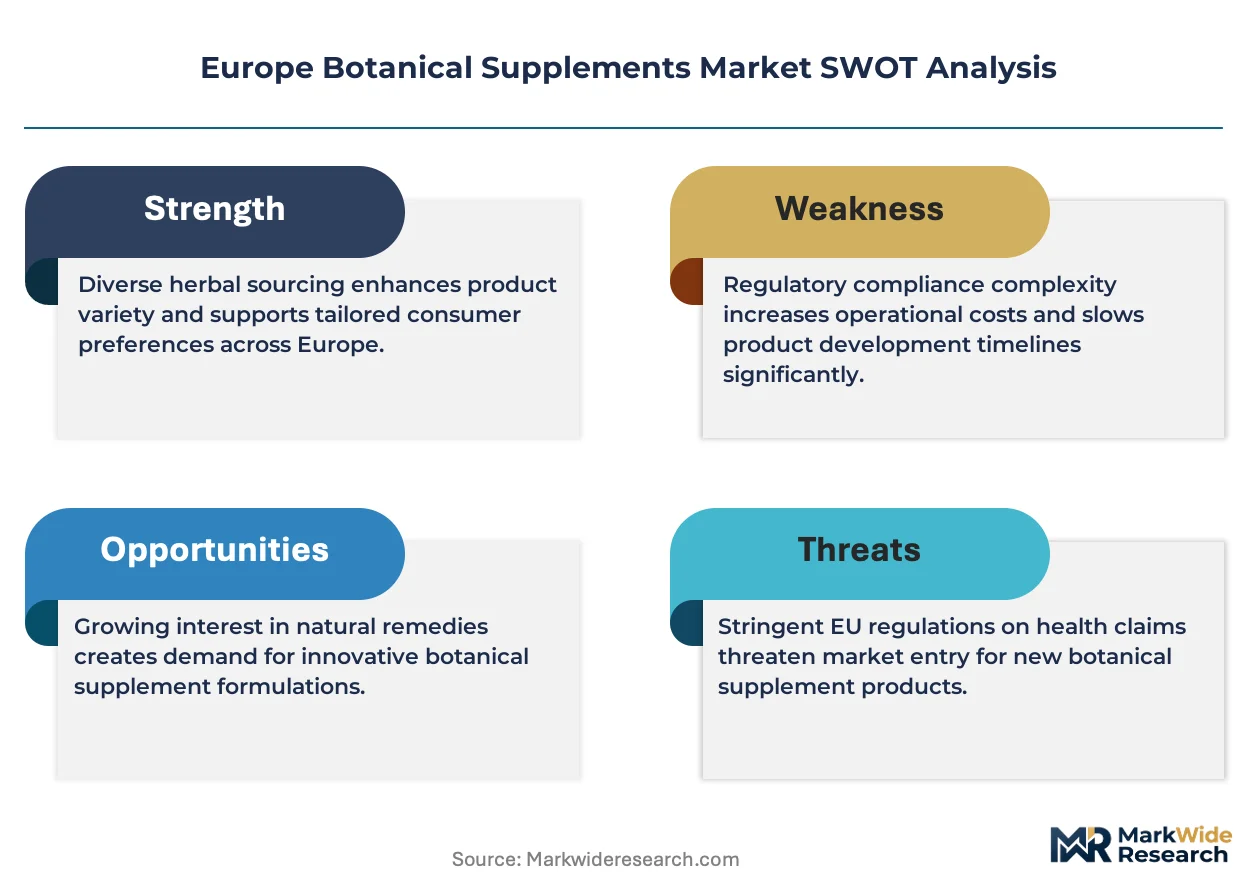
Wild-harvested raw material volatility in Alpine and Mediterranean growing regions compresses supply windows for standardized botanicals while simultaneously widening spreads between pharmacy-certified premium tiers and unverified economy alternatives. REACH solvent compliance layering and EU Green Deal traceability mandates force dual sourcing investments that reshape cost structures across German, Italian, and French formulation networks.
Pricing Analysis
Volume-discount tiering structures stratify across pharmacy-distributed EMA-monographed extracts, direct-to-consumer subscription bundles, and supermarket commoditized single-ingredient lines. Price differentiation hinges on EFSA novel food certification status and supercritical CO2 extraction verification, with pharmacy channels commanding substantial premiums for real-time certificate-of-analysis access. Cost compression in economy tiers intensifies as Polish and Romanian contract manufacturers scale HPLC method development capacity. Health enthusiasts in Nordic markets exhibit lowest price sensitivity due to telehealth-integrated subscription loyalty, while mass-market supermarket purchasers drive aggressive commoditization.
Supply Chain Analysis
Contract manufacturing concentrates among Frankfurt-area supercritical CO2 specialists, Lombardy liquid dosage formulators, and Poznan-based analytical chemistry houses. Geographic supply concentration centers on Morocco for argan, Bulgaria for rosehip, and Alpine zones for St. John's Wort and milk thistle. Raw material dependencies rest on wild-harvested botanicals, ethanol and hexane extraction media, and gelatin or hydroxypropyl methylcellulose capsule shells. Single-source vulnerability from climate-stressed Alpine harvests threatens mid-season contract stability. Distribution runs through German pharmacy chains, Swedish direct-to-consumer platforms, and pan-European online retail fulfillment clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as German pharmacy chains consolidate procurement and Nordic digital health platforms aggregate subscription demand, fragmenting traditional supplier pricing leverage.
For Market Incumbents: Entrench pharmacy shelf presence through backward integration into traceable Moroccan and Bulgarian growing cooperatives before EFSA health claim harmonization raises competitive barriers. Secure supercritical CO2 equipment licensing agreements with Turin manufacturers to lock in terpenoid-rich extraction capacity. Synthetic nootropic substitution in Nordic markets threatens ginkgo and bacopa volume; counter with EMA-monographed liquid formulations for geriatric adherence. For New Entrants and Emerging Players: Establish a beachhead in Polish and Romanian pharmacy networks where herbal supplement penetration remains underdeveloped and EFSA compliance costs have not yet filtered out smaller competitors. Target Warsaw and Kraków distribution partnerships before national regulators reference centralized efficacy standards. Deploy blockchain-verified organic certification as the primary go-to-market angle to capture CSRD-driven procurement premiums from sustainability-mandated buyers. For Investors and Strategic Acquirers: EFSA novel food approval timeline compression reshapes the acquisition landscape toward mid-scale extract houses with existing EMA monograph alignment and queued safety assessments. Long-term viability favors specialists with captive cultivation equity and integrated analytics platforms over pure-play distributors. Monitor EFSA health claim expansion decisions as the critical inflection signal for which ingredient categories achieve mass-market scale.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Traceable Cultivation | French and Italian extract houses acquire Moroccan cooperative equity to satisfy EU Green Deal geolocation mandates. |
| Supercritical CO2 Equipment Scale-Up | Turin manufacturers deploy larger-capacity systems cutting solvent residue testing burdens for German pharmacy supply agreements. |
| Telehealth-Integrated Subscription Launch | Stockholm digital health platforms bundle personalized botanical protocols with remote consultations bypassing pharmacy dependence. |
| Eastern European Pharmacy Network Expansion | First-mover positioning in Warsaw and Kraków chains captures share before EFSA harmonization raises barriers. |
| Blockchain-Verified Certification Program | CSRD reporting mandates create procurement premiums for suppliers with regenerative agriculture partnerships and QR-linked transparency. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EFSA novel food registers, EMA herbal monograph databases, and EU Green Deal implementation guidance. Primary interviews engaged pharmacy chain procurement directors, supercritical CO2 equipment manufacturers, botanical extract house regulatory affairs leads, and Nordic digital health platform operators. Secondary validation drew from REACH compliance filings, CSRD sustainability reports, and customs trade data for raw material flows. Bottom-up segment sizing triangulates against top-down market value reconstructions.
Forecast inputs include preventive wellness spending shifts, EFSA approval queue dynamics, supercritical CO2 adoption rates, and pharmacy channel consolidation patterns across the projection horizon. Segmentation dimensions span product format, end-user archetype, physical form, and distribution channel with regulatory pathway overlays. CAGRs derive from regression analysis against historical pharmacy sales audit data and subscription platform growth trajectories. Wild-harvest yield volatility and REACH solvent documentation burdens factor as industry-specific forecast modifiers.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary health spending, eurozone logistics costs, or Alpine climate patterns would shift the trajectory. Forecasts reflect documented assumptions regarding EFSA enforcement timelines and EMA monograph harmonization progress. Quarterly review of pharmacy sales velocity, novel food approval queue depth, and wild-harvest contract renegotiation frequency is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Brazil Whey Protein Market
Nutritional Supplements
Bone Supplements Market
Nutritional Supplements
Nutraceutical Supplements Market
Nutritional Supplements
Nutritional Oil Powder Market
Nutritional Supplements
Mediterranean Metabolic Syndrome Support Ingredient Packs Market
Nutritional Supplements
Vitamins and Minerals Market
Nutritional Supplements
Zinc Supplement Market
Nutritional Supplements
Global Adaptogens Market
Nutritional Supplements
Global Nutraceutical Ingredients Market
Nutritional Supplements
North America Immune Health Supplements Market
Nutritional Supplements
Europe Collagen Peptides Market
Nutritional Supplements
Multi Nutritional Supplement Market
Nutritional Supplements
North America Memory Supplements Market
Nutritional Supplements
Ready-To-Use Therapeutic Food Market
Nutritional Supplements
Choline Market
Nutritional Supplements
GLP-1 Diet Food Market