
 Vegetable Capsules Market | 2026-2036
Vegetable Capsules Market Size, Share, and Industry Trends Forecast 2026-2036
Vegetable Capsules Market Analytics
Aftermarket formulation services is reshaping margin distribution across the vegetable capsules value chain. Lonza Group leverages its integrated excipient-to-capsule platform to capture higher-margin custom development work. Catalent anchors North American pharmaceutical outsourcing demand through specialized HPMC capsule lines. Suheung dominates soft-gel vegetable alternatives in Asian nutraceutical supply chains.
Vegetable capsules are shell-delivery systems composed of plant-derived polymers such as hydroxypropyl methylcellulose or pullulan, formed through dip-molding processes to encase powders, granules, or liquids for oral administration. Hard capsules lead pharmaceutical volumes due to compatibility with high-speed filling equipment and established dissolution profiles. Hydroxypropyl methylcellulose material grades command premium positioning as manufacturers seek titanium dioxide-free alternatives under evolving EU pigment regulations. Dietary supplements represent the fastest-growing application as clean-label positioning drives brand switching from animal-derived shells.
FDA dietary supplement cGMP standards, EMA stability testing guidelines for hydrophilic polymers, and REACH chemical registration requirements collectively elevate barrier-to-entry for new vegetable capsule entrants. These frameworks shape raw material qualification timelines, compel migration from synthetic colorants, and restrict certain modified starches in European pharmaceutical applications. Stakeholders must monitor evolving pharmacopeial harmonization between USP-NF and EP monographs for plant-derived shell performance specifications.
Market Dynamics
EMA stability testing guidelines for hydrophilic polymers are forcing pharmaceutical contract manufacturers to abandon gelatin shells and requalify entire product lines around HPMC and pullulan alternatives, compressing formulation timelines and concentrating demand among pre-qualified vegetable capsule suppliers.
Growth Catalysts
- REACH chemical registration:European manufacturers face mandatory migration from titanium dioxide colorants, accelerating demand for TiO2-free HPMC grades that vegetable capsule specialists have already commercialized.
- Clean-label dietary supplements:Brand owners in Germany and France are switching shell materials to capture vegan positioning premiums in mass-market retail channels.
- High-speed filling compatibility:Hard vegetable capsules now match gelatin dissolution profiles on Bosch and IMA lines, removing the final technical barrier to conversion at pharmaceutical scale.
Market Restraints
- Modified starch restrictions:EMA pharmacopeial standards exclude certain potato and tapioca derivatives from pharmaceutical-grade shell formulations, narrowing raw material options.
- Hydroxypropyl methylcellulose supply concentration:Pharmaceutical-grade HPMC production clusters in China and India, exposing converters to freight cost volatility and customs processing delays.
- Gelatin cost arbitrage:Bovine and porcine shell materials retain 15-30% price advantages in emerging markets, slowing vegetable adoption outside regulated jurisdictions.
Strategic Opportunities
- Soft-gel vegetable alternatives:Carrageenan and starch-based soft shells remain underdeveloped versus hard capsules, creating white space for first-movers in liquid nutraceutical delivery.
- USP-NF and EP monograph harmonization:Convergence of American and European pharmacopeial standards will simplify dual-market registration for compliant shell suppliers.
- Direct-to-consumer subscription channels:Personalized supplement brands are bypassing traditional wholesale distribution, creating demand for small-batch capsule customization.
Industry Challenges
- Dip-molding process engineering:Vegetable polymer rheology requires tighter temperature and humidity control than gelatin, demanding specialized technician training that outpaces vocational program output.
- Cross-functional regulatory expertise:Few professionals combine polymer chemistry, pharmaceutical cGMP, and REACH compliance knowledge, elongating product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegetable Capsules Market |
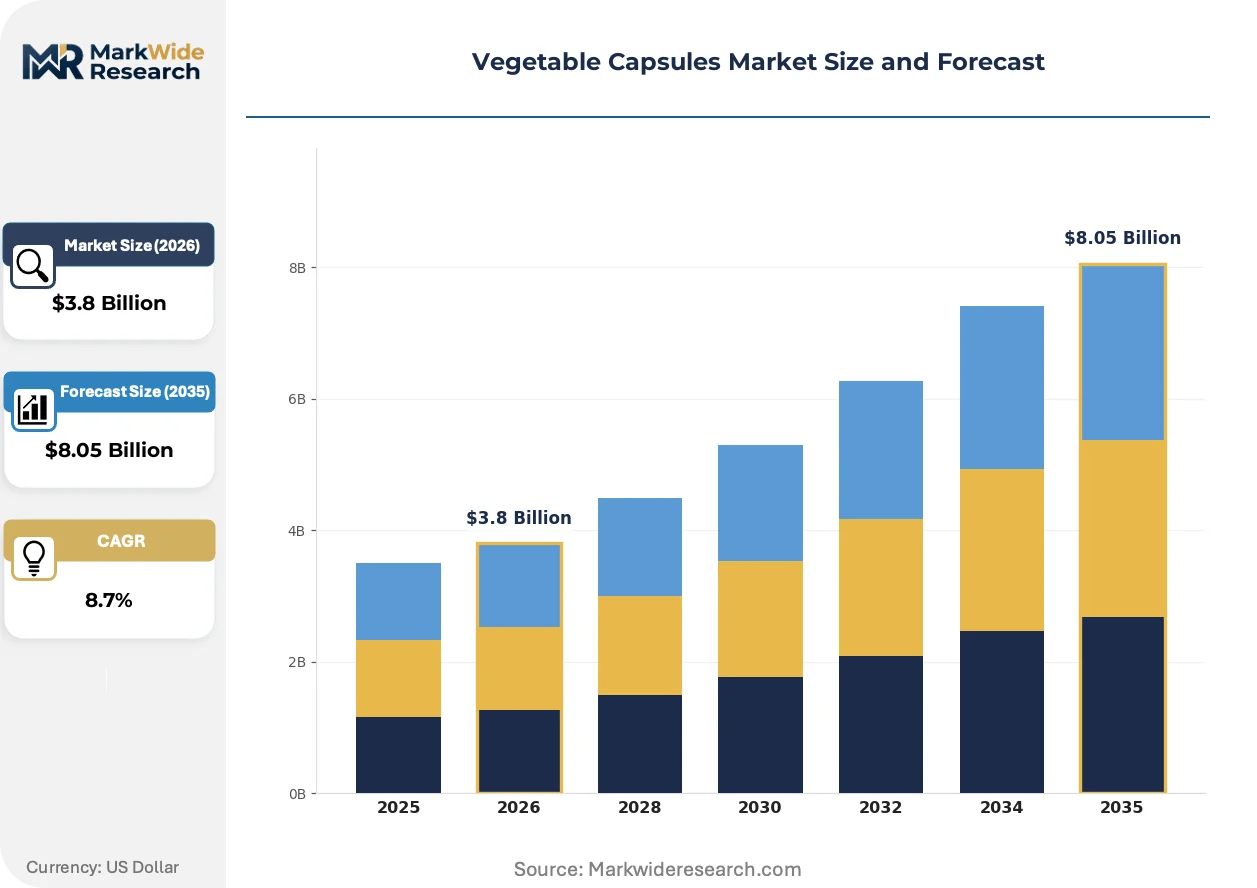
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Capsules, Soft Capsules, Liquid Capsules, Gelatin Capsules Material: Pullulan, Hydroxypropyl Methylcellulose, Starch, Cellulose Application: Dietary Supplements, Pharmaceuticals, Nutraceuticals, Food Industry End User: Retail Consumers, Healthcare Professionals, Pharmaceutical Companies, Manufacturers |
| Companies Covered | CapsCanada, Tianjin Sinocaps Biotech, Lonza Group, Suheung, Shandong Healsee Capsule, Catalent, Natural Capsules, Nitta Gelatin, Associated Capsules, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegetable Capsules Market Evolving Landscape
Digital twin technology is virtualizing quality assurance workflows across capsule manufacturing, compressing batch release timelines while tightening variance control. This shift is redistributing competitive advantage toward suppliers with integrated data infrastructure.
Continuous manufacturing platforms are virtualizing traditional batch-based dip-molding operations. Lonza and Catalent have piloted real-time viscosity monitoring systems that adjust shell wall thickness dynamically. Pharmaceutical quality teams are adopting these lines to reduce in-process testing overhead and accelerate stability study initiation.
EU Green Deal chemical sustainability requirements are tightening disclosure obligations for polymer supply chains. Manufacturers must now document carbon intensity and water usage across HPMC precursor production. German pharmaceutical clusters are responding by qualifying suppliers with certified mass-balance accounting, while converters in Italy face delayed raw material approvals.
Brand-owner consolidation in dietary supplements is compressing supplier negotiation cycles. Large retailers like dm-drogerie markt and Holland & Barrett are consolidating capsule procurement under direct contracts with converters, displacing traditional distributor intermediaries. This concentration is most visible in the Netherlands and United Kingdom, where private-label supplement volumes have concentrated among three buying groups.
Vegetable Capsules Market Segmentation
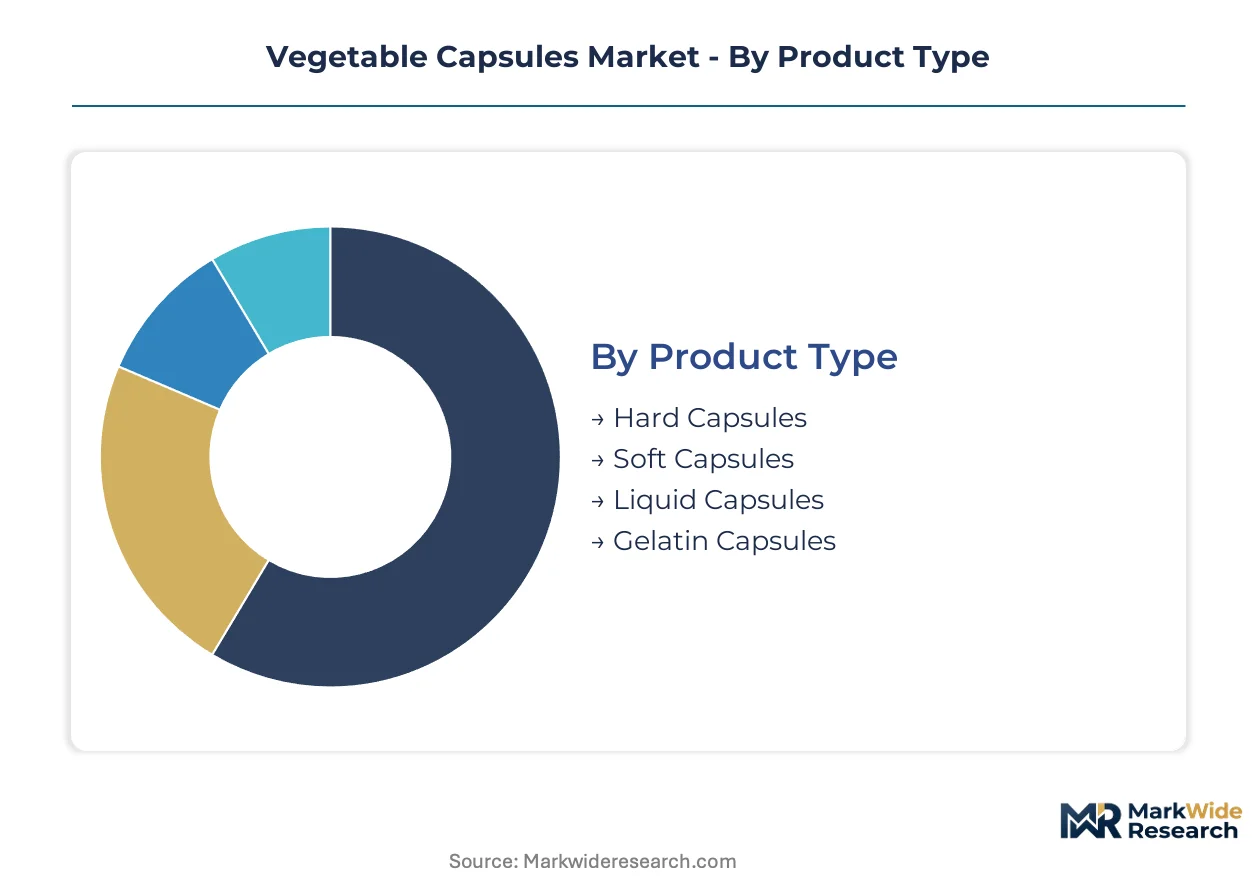
Vegetable capsule suppliers must align product configurations with distinct technical requirements across pharmaceutical, nutraceutical, and food-grade applications. Material selection and shell architecture determine compatibility with high-speed filling equipment, dissolution profiles, and regulatory compliance pathways.
Product Type:
Cost tier differentiation separates high-volume pharmaceutical formats from specialized delivery systems commanding formulation premiums.
- Hard Capsules:Two-piece HPMC or pullulan shells formed through dip-molding and precision trimming. Pharmaceutical contract manufacturers in Germany's Rhineland-Palatinate cluster specify these for compatibility with Bosch and IMA high-speed lines under tightening EMA stability guidelines.
- Soft Capsules:Single-piece shells formed via rotary die encapsulation, typically employing carrageenan or modified starch bases. Asian nutraceutical supply chains concentrate demand here for omega-3 and lipid-based delivery where liquid fill volumes dominate.
- Liquid Capsules:Specialized hard-shell variants engineered for non-aqueous liquid fills without leakage.
- Gelatin Capsules:Animal-derived reference standard being displaced by vegetable alternatives in regulated markets.
Hard capsules command the established base. The steepest expansion runs through soft capsules as lipid-based nutraceutical formulations multiply.
Material:
Application requirements drive material selection, with pharmaceutical-grade specifications narrowing viable polymer sources.
- Hydroxypropyl Methylcellulose:Semisynthetic cellulose ether delivering precise dissolution control and mechanical stability. EMA pigment regulations accelerating TiO2-free HPMC adoption across European pharmaceutical applications where titanium dioxide colorants face mandatory phase-out.
- Pullulan:Fungal-derived polysaccharide offering superior oxygen barrier properties and premium clarity. Japanese nutraceutical brands specify pullulan for high-value probiotic and enzyme formulations demanding extended shelf stability.
- Starch:Potato and tapioca derivatives restricted under EMA pharmacopeial standards for pharmaceutical-grade applications.
- Cellulose:Unmodified plant fiber base for economy-tier dietary supplement applications.
Hydroxypropyl methylcellulose anchors current pharmaceutical procurement. Pullulan is gaining share fastest as clean-label positioning intensifies.
Application:
Customer type determines regulatory burden and margin structure across the value chain.
- Dietary Supplements:Clean-label positioning drives brand switching from gelatin shells in German and French mass-market retail. Vegan certification premiums justify 15-25% shell cost differentials for products targeting dm-drogerie markt and Holland & Barrett private-label programs.
- Pharmaceuticals:FDA cGMP and EMA stability testing requirements elevate qualification barriers. Contract manufacturers must revalidate entire product lines when converting from gelatin, compressing timelines and concentrating demand among pre-qualified vegetable capsule suppliers.
- Nutraceuticals:Functional food-drug hybrid positioning requiring dual regulatory navigation.
- Food Industry:Flavor encapsulation and controlled-release applications with lower technical barriers.
Pharmaceuticals represent the revenue foundation. Dietary supplements are expanding most quickly as direct-to-consumer subscription channels proliferate.
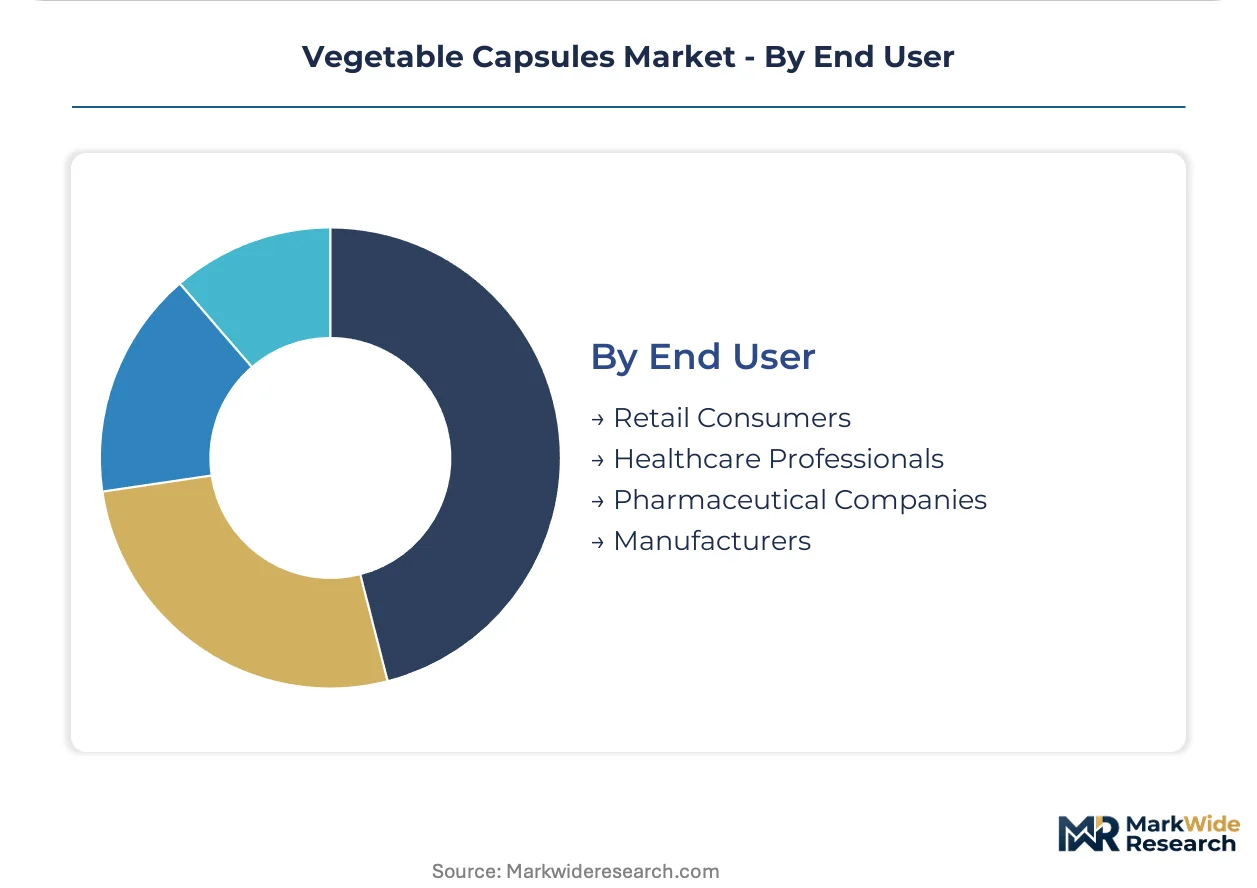
End User:
Volume concentration and procurement sophistication separate institutional buyers from fragmented retail demand.
- Pharmaceutical Companies:Integrated quality systems demanding batch-level traceability, stability data packages, and REACH-compliant supply chain documentation. Procurement consolidation among top-20 global pharma firms has compressed supplier qualification cycles to 18-24 months.
- Manufacturers:Contract encapsulation specialists serving multiple brand owners with flexible batch sizing. These intermediaries are consolidating in the Netherlands and United Kingdom as private-label supplement volumes concentrate among three buying groups.
- Healthcare Professionals:Compounding pharmacies and specialty clinicians with small-batch customization needs.
- Retail Consumers:Individual purchasers through e-commerce and specialty health channels.
Pharmaceutical companies control the premium tier. Manufacturers are climbing the fastest as outsourcing trends deepen across the nutraceutical sector.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Switzerland absorb 20-35% shell cost premiums for REACH-compliant documentation, while Indian and Brazilian contract manufacturers remain anchored to gelatin economics where bovine-derived alternatives trade at steep discounts.
Germany
EMA stability testing deadlines are compressing requalification timelines for Rhineland-Palatinate pharmaceutical clusters. The country's federal pharmaceutical regulator enforces titanium dioxide phase-out schedules that predate broader EU mandates. Capsule converters in Ludwigshafen and Mainz now source exclusively from pre-qualified HPMC suppliers to maintain Bosch line throughput under tighter pigment regulations.
United States
FDA dietary supplement cGMP enforcement is elevating documentation burdens for contract manufacturers migrating from gelatin. The agency's 2023 guidance on hydrophilic polymer dissolution testing created compliance templates now copied by Health Canada. New Jersey and North Carolina nutraceutical hubs concentrate demand for small-batch HPMC customization serving direct-to-consumer subscription brands.
China
Pharmaceutical-grade HPMC precursor production clusters in Shandong and Jiangsu provinces, exposing European converters to freight volatility and customs processing delays. The National Medical Products Administration harmonizes vegetable capsule monographs with USP-NF standards to accelerate export registration. Domestic dietary supplement brands in Hangzhou and Guangzhou are switching from gelatin to capture clean-label positioning in cross-border e-commerce channels.
India
Modified starch restrictions under CDSCO pharmaceutical-grade specifications are narrowing formulation options for domestic capsule converters. The country's national pharmaceutical regulator excludes certain tapioca derivatives from shell applications, pushing manufacturers toward cellulose ether alternatives. Hyderabad and Ahmedabad encapsulation specialists now serve European contract manufacturing demand through REACH-compliant supply chain documentation.
Japan
Pullulan-derived shells command premium positioning for probiotic and enzyme formulations demanding extended oxygen barrier properties. The Pharmaceuticals and Medical Devices Agency maintains distinct dissolution testing protocols that elongate registration timelines for imported HPMC grades. Osaka-based nutraceutical brands specify fungal-derived polysaccharides for high-value applications where shelf stability justifies material cost differentials.
Vegetable Capsules Market Competitive Landscape
Capability concentration sits with integrated excipient-to-capsule platforms; scale advantage sits with high-volume contract manufacturing specialists serving multiple brand owners. The market structure separates three tiers: multinational platform operators with polymer chemistry integration, regional encapsulation specialists with flexible batch sizing, and commodity converters competing on unit economics. Dominant competitive moves include backward integration into pharmaceutical-grade HPMC precursor production and geographic expansion through distributor displacement in consolidated retail procurement channels.
Within the integrated platform tier, Lonza Group and Catalent exemplify capability concentration through captive excipient supply and real-time viscosity monitoring systems. Suheung occupies a position bridging Asian nutraceutical demand with soft-gel vegetable alternative development. Among China-based specialists, Tianjin Sinocaps Biotech and Shandong Healsee Capsule represent scale-driven manufacturing archetypes serving export contract manufacturing demand.
| Leading Market Players |
|---|
| CapsCanada |
| Tianjin Sinocaps Biotech |
| Lonza Group |
| Suheung |
| Shandong Healsee Capsule |
| Catalent |
| Natural Capsules |
| Nitta Gelatin |
| Associated Capsules |
| Others |
Value Network & Pricing Analysis
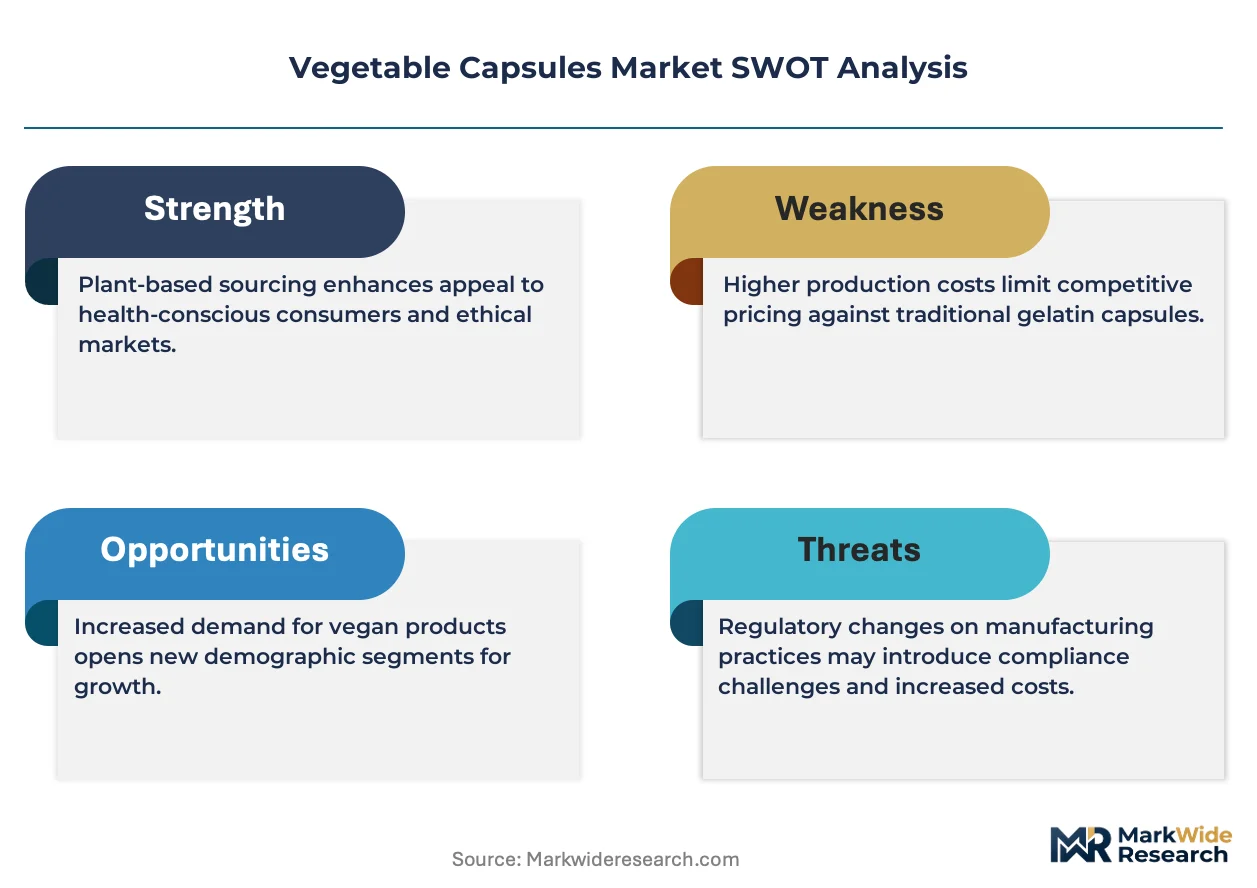
Shandong province's pharmaceutical-grade HPMC precursor concentration anchors downstream pricing power for European capsule converters facing REACH-compliant documentation premiums. Contract manufacturers in Germany's Rhineland-Palatinate cluster absorb 20-35% shell cost markups to secure batch-level traceability and stability data packages from pre-qualified suppliers.
Pricing Analysis
After-sales formulation services and extended stability testing contracts drive lifetime value for integrated platform operators. Three-tier pricing structure across pharmaceutical-grade, nutraceutical-certified, and economy dietary supplement levels separates buyers by documentation burden and dissolution precision. Cost compression in economy-tier cellulose shells is intensifying because Indian contract manufacturers compete on unit economics for unregulated export markets. Pharmaceutical companies show least price sensitivity given requalification costs, while direct-to-consumer supplement brands negotiate aggressively on volume.
Supply Chain Analysis
Upstream cellulose ether feedstock production clusters in China, India, and select European chemical hubs. Vegetable capsule manufacturing draws from pharmaceutical-grade HPMC precursors, pullulan fungal fermentation outputs, and modified starch derivatives restricted under EMA pharmacopeial standards. Single-source vulnerability runs through Shandong and Jiangsu province concentration where customs processing delays propagate downstream. Distribution runs through direct procurement contracts with consolidated retail buying groups displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA stability guideline enforcement constitutes a regulatory inflection disrupting gelatin incumbent positions while accelerating vegetable capsule adoption curves across pharmaceutical contract manufacturing.
For Market Incumbents: Insulate market position through backward integration into pharmaceutical-grade HPMC precursor production and captive supply of TiO2-free colorant alternatives. Lonza Group's integrated excipient-to-capsule platform demonstrates how real-time viscosity monitoring systems defend against emerging Asian scale players. Certification investment in REACH-compliant mass-balance accounting separates premium tier positioning from commodity competition. For New Entrants and Emerging Players: Establish a beachhead in soft-gel vegetable alternatives where carrageenan and starch-based liquid delivery systems remain underdeveloped versus hard capsule saturation. Asian nutraceutical supply chains present the most penetrable geography given omega-3 formulation demand and Suheung's limited regional competition. Direct-to-consumer subscription channel partnerships offer go-to-market velocity bypassing consolidated retail procurement gatekeepers. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational chemical conglomerates with underutilized pharmaceutical polymer divisions and legacy gelatin capsule assets requiring conversion capital. Long-term viability centers on regulatory compliance infrastructure rather than manufacturing scale alone. Monitor EMA pigment regulation harmonization timing as inflection indicator for accelerated requalification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into HPMC Precursor Production | Captive supply of pharmaceutical-grade cellulose ether reduces dependency on Shandong concentration and customs volatility. |
| REACH-Compliant Mass-Balance Certification | German pharmaceutical clusters now require documented carbon intensity across polymer supply chains for raw material approval. |
| Soft-Gel Vegetable Alternative Development | Carrageenan and starch-based liquid shells address white space in lipid-based nutraceutical delivery formats. |
| Direct-to-Consumer Subscription Channel Partnerships | Personalized supplement brands bypass Holland & Barrett and dm-drogerie markt procurement consolidation. |
| Real-Time Viscosity Monitoring System Deployment | Continuous manufacturing platforms compress batch release timelines and reduce in-process testing overhead. |
Research Methodology
Desk research of EMA stability guideline documentation, FDA cGMP enforcement records, and REACH chemical registration databases preceded structured interviews with pharmaceutical contract manufacturing executives, capsule converter procurement leads, polymer chemistry R&D directors, and dietary supplement brand managers. Bottom-up volume modeling from identified production facilities was cross-validated against top-down demand estimates derived from Bosch and IMA high-speed line deployment data.
Assumptions held fixed across the projection horizon include EMA titanium dioxide phase-out schedules and USP-NF pharmacopeial harmonization trajectories, while variables such as freight cost volatility and customs processing efficiency were stress-tested. Segmentation dimensions encompassed shell architecture, material grade tier, application regulatory burden, and regional pharmaceutical cluster concentration. CAGRs were derived from elasticity-adjusted demand curves incorporating clean-label brand switching propensity and requalification timeline compression.
Stress conditions across HPMC precursor supply disruption severity, EMA guideline enforcement acceleration, and gelatin cost arbitrage persistence in emerging markets were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against pharmaceutical excipient customs trade data and high-speed filling equipment order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Global Adaptogens Market
Nutritional Supplements
Pregnenolone Supplements Market
Nutritional Supplements
North America Collagen Supplements Market
Nutritional Supplements
Canada Nutraceuticals Market
Nutritional Supplements
Liquid Dietary Supplements Market
Nutritional Supplements
Hydrolyzed Whey Protein Market
Nutritional Supplements
Lion's Mane Market
Nutritional Supplements
Mushroom Powders Market
Nutritional Supplements
Postbiotic Supplements Market
Nutritional Supplements
Lipid Nutrition Market
Nutritional Supplements
GLP-1 Meal Replacement Market
Nutritional Supplements
Vegan Protein Supplements Market
Nutritional Supplements
South America Collagen Supplements Market
Nutritional Supplements
Microalgae DHA Market
Nutritional Supplements
Stress Relief Supplements Market
Nutritional Supplements
USA Prenatal Vitamin Supplements Market