
 Chicory Roots Market | 2026-2036
Chicory Roots Market Size, Share, and Industry Trends Forecast 2026-2036
Chicory Roots Market Outlook
Functional beverage demand is hardening as the dominant demand pull for chicory-derived inulin and roasted extracts. COSUCRA leverages its Belgian extraction infrastructure to supply prebiotic fiber to European dairy alternative brands. BENEO anchors supply contracts with North American beverage companies seeking clean-label sugar reduction. Südzucker competes through integrated sugar-to-fiber diversification, while Cargill Incorporated extends its ingredient portfolio with chicory-based texturizers for bakery applications.
Chicory root comprises approximately 15-20% inulin by fresh weight, a fructan polysaccharide extracted through hot water diffusion and refined via spray-drying or enzymatic hydrolysis for food-grade prebiotic applications. The root serves primarily as an industrial feedstock for soluble dietary fiber, coffee substitutes, and natural flavoring compounds. Roasted chicory commands premium positioning in the beverage channel where coffee alternative formulations drive margin pools, while chicory extract leads volume growth in dietary supplements as FDA GRAS recognition expands formulation flexibility. Raw chicory remains a mature, price-sensitive supply tier serving regional processors with limited refinement capacity.
FDA GRAS notifications and EU Novel Food catalog entries govern inulin inclusion thresholds in fortified foods across North America and Europe, while EFSA health claim authorizations shape prebiotic marketing permissions in EU member states. The EU F-Gas Regulation indirectly pressures extraction facilities to adopt lower-emission drying technologies, raising capital requirements for new market entrants. Stakeholders must monitor evolving fiber intake recommendations from WHO and national health agencies, as these guidelines directly influence consumer willingness to pay for prebiotic-enriched products and determine which application segments warrant capacity expansion.
Market Dynamics
Clean-label formulation mandates from EFSA and FDA are compressing synthetic additive pipelines and redirecting R&D budgets toward prebiotic fiber integration in functional beverages and dairy alternatives.
Growth Catalysts
- EFSA Health Claim Authorizations:Prebiotic marketing permissions in EU member states enable premium positioning for inulin-fortified yogurts and beverages. Belgian and Dutch processors leverage this regulatory clarity to secure long-term supply contracts with multinational dairy brands.
- Hot Water Diffusion Extraction:This refining technology yields food-grade inulin with minimal chemical residue, satisfying clean-label procurement criteria from North American beverage manufacturers. Spray-drying and enzymatic hydrolysis variants now dominate commercial-scale operations.
- Coffee Alternative Formulations:Roasted chicory extracts command margin premiums in specialty beverage channels as caffeine-free positioning attracts wellness-oriented consumers. Belgian roasting infrastructure supports contract manufacturing for private-label coffee substitute brands.
Market Restraints
- EU F-Gas Regulation Compliance:Extraction facilities face capital-intensive retrofits to adopt lower-emission drying technologies, raising barriers for new market entrants and squeezing margins at mid-scale processors.
- Chicory Root Supply Concentration:Established cultivation clusters in Belgium and the Netherlands create geographic dependency risk for multinational buyers seeking diversified sourcing portfolios.
- Fructan Substitution Threat:Jerusalem artichoke and agave-derived inulins compete on price in commodity dietary supplement applications, pressuring raw chicory pricing in volume-driven segments.
Strategic Opportunities
- Underpenetrated Asian Markets:Japan's FOSHU regulatory pathway and South Korea's MFDS functional food frameworks remain underexploited by European chicory processors. Local partnership models with regional dairy conglomerates unlock formulation trials.
- Precision Fermentation Convergence:Integration of enzymatic hydrolysis with bioreactor-based fructan synthesis enables customized molecular weight profiles for targeted gut microbiome applications. Biotechnology firms and ingredient suppliers are co-developing next-generation prebiotic platforms.
- Direct-to-Consumer Supplement Channels:E-commerce platforms bypass traditional foodservice distribution, allowing branded inulin producers to capture margin pools previously absorbed by ingredient brokers. Subscription models for personalized gut health regimens concentrate in Germany and the United Kingdom.
Industry Challenges
- Novel Food Dossier Preparation:EU regulatory timelines for new inulin applications extend 18-24 months, requiring dedicated regulatory affairs capacity and upfront investment without guaranteed approval outcomes.
- Legacy Equipment Retrofit Complexity:Conventional sugar extraction facilities attempting backward integration into chicory fiber production face incompatible processing parameters and yield optimization gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chicory Roots Market |
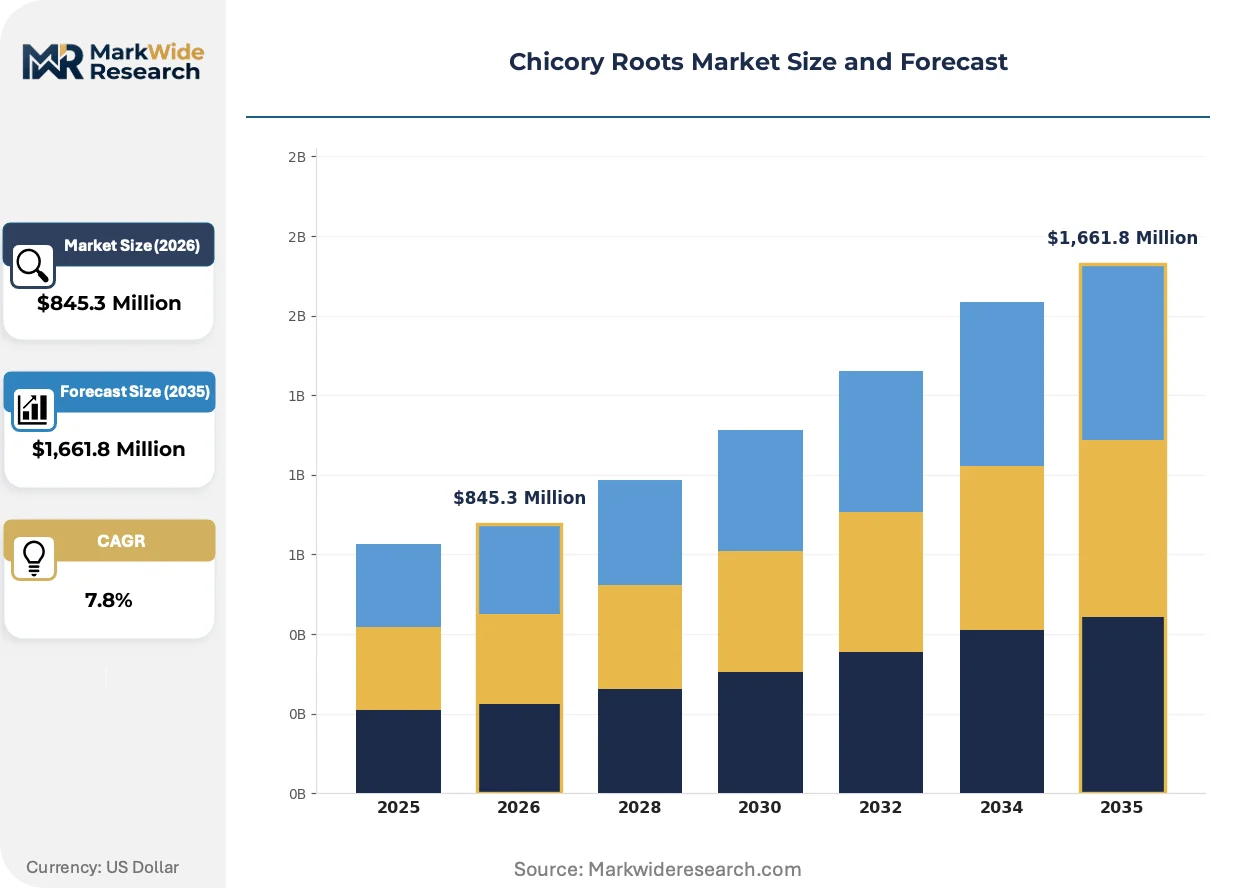
| Market Size in 2026 | $845.3 Million |
| Market Size in 2035 | $1,661.8 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Chicory, Chicory Powder, Chicory Extract, Roasted Chicory End User: Food & Beverage, Pharmaceuticals, Nutraceuticals, Cosmetics Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales Application: Beverages, Dietary Supplements, Bakery Products, Food Flavoring |
| Companies Covered | COSUCRA, BENEO, Cargill Incorporated, Delecto Foods Pvt Ltd, Sensus, Südzucker, Pioneer Chicory, PMV Nutrient Products Pvt Ltd, Farmvilla Food Industries Pvt Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chicory Roots Market Strategic Shifts
Enzymatic refinement technologies and regulatory harmonization efforts are compressing synthetic fiber displacement timelines while opening new application vectors in personalized nutrition and clinical foodservice.
Enzymatic hydrolysis systems for molecular weight-specific inulin production are consolidating control over premium prebiotic segments. Pharmaceutical-grade dietary supplement manufacturers in Germany and Switzerland adopt these systems to meet pharmacopeial monograph specifications. The technology is consolidating high-margin positions away from commodity spray-dried extracts by enabling targeted fermentation substrate applications.
REACH registration requirements for novel extraction solvents are tightening purity verification protocols across European processing facilities. Industrial consequence includes accelerated phase-out of legacy petrochemical-based purification aids in favor of aqueous and enzymatic methods. Belgian and Dutch extraction hubs respond by retrofitting diffusion lines to eliminate solvent residues entirely, securing supply chain access to EFSA-authorized health claim products.
Buyer concentration among multinational beverage conglomerates is compressing supplier negotiation leverage and elongating payment terms for mid-tier chicory processors. Contract manufacturing agreements now bundle inulin supply with technical formulation support, displacing spot-market transactions. This pattern concentrates most visibly in North American dairy alternative launches where single-source prebiotic partnerships lock out competing fiber suppliers for 3-5 year windows.
Chicory Roots Market Segmentation
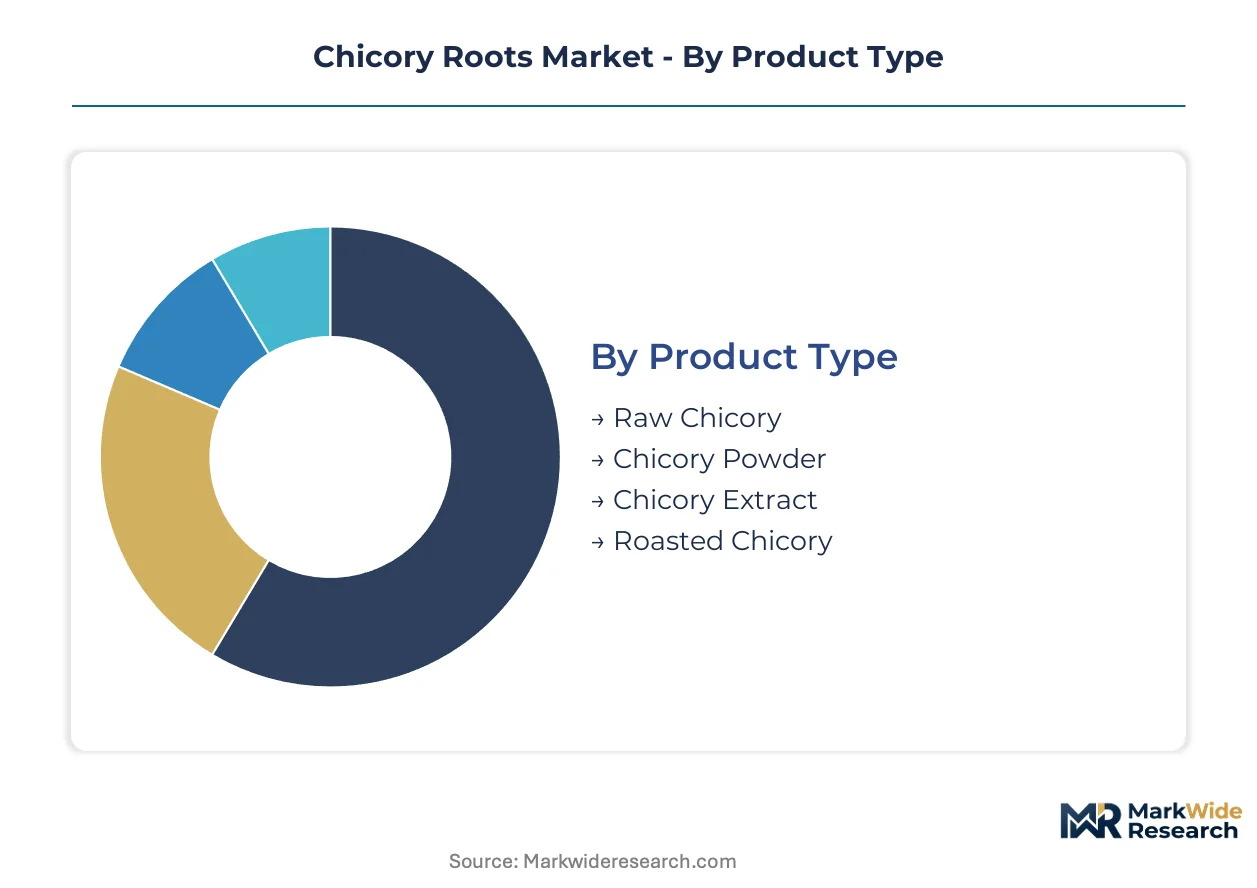
Chicory root segmentation reveals divergent margin profiles across refinement tiers. Raw material supply chains serve commodity processors while extracted inulin and roasted derivatives capture premium positioning in functional formulations.
Product Type:
Volume concentrates in minimally processed grades, but premium extraction technologies command superior returns through pharmaceutical and beverage applications.
- Chicory Extract:Hot water diffusion yields food-grade inulin with 15-20% fructan concentration by fresh root weight. Belgian processors supply European dairy alternative brands seeking EFSA-authorized prebiotic health claims.
- Roasted Chicory:Thermal processing develops Maillard reaction compounds for coffee substitute formulations. North American beverage manufacturers leverage caffeine-free positioning to access wellness-oriented retail channels.
- Raw Chicory:Field-dried roots serve regional processors with limited refinement infrastructure.
- Chicory Powder:Milled intermediate grade bridges commodity supply and formulated ingredient applications.
Today's leader: Chicory Extract. Tomorrow's challenger: Roasted Chicory.
End User:
Application sophistication determines procurement specifications and regulatory burden across customer categories.
- Food & Beverage:Multinational dairy and alternative beverage brands drive contract volume through clean-label prebiotic integration. FDA GRAS recognition enables formulation flexibility in fortified yogurts and functional drinks.
- Nutraceuticals:Dietary supplement manufacturers in Germany and Switzerland adopt pharmacopeial-grade inulin for gut health positioning. Subscription e-commerce models concentrate consumer acquisition spend in direct-to-consumer channels.
- Pharmaceuticals:Clinical nutrition applications require molecular weight-specific fructan profiles.
- Cosmetics:Prebiotic skin care formulations represent emerging demand from Korean and Japanese beauty brands.
Food & Beverage holds current volume dominance. Nutraceuticals climb fastest on personalized gut health positioning.
Distribution Channel:
Channel selection reflects buyer scale and technical service requirements rather than pure price optimization.
- Direct Sales:Technical formulation support bundles with multi-year supply agreements lock out competing fiber suppliers. North American dairy alternative launches favor single-source prebiotic partnerships spanning 3-5 year contract windows.
- Online Retail:E-commerce platforms enable branded inulin producers to bypass ingredient brokers and capture margin pools through subscription-based gut health regimens.
- Supermarkets:Mass retail channels serve consumer-packaged coffee substitute brands.
- Specialty Stores:Premium organic and health food retailers curate roasted chicory for wellness positioning.
Direct Sales anchors industrial procurement. Online Retail expands most quickly on D2C supplement growth.
Application:
End-use differentiation separates commodity fiber sales from value-added functional positioning.
- Beverages:Coffee alternative formulations command margin premiums through caffeine-free wellness positioning. Belgian roasting infrastructure supports contract manufacturing for private-label brands targeting North American specialty retail.
- Dietary Supplements:Prebiotic capsules and powders concentrate demand in German and UK subscription channels. Enzymatic hydrolysis enables molecular weight customization for targeted microbiome applications.
- Bakery Products:Cargill Incorporated extends chicory-based texturizers for clean-label reformulation of traditional wheat applications.
- Food Flavoring:Natural bittering compounds serve craft beverage and confectionery applications.
Beverages lead on margin capture. Dietary Supplements gain share fastest through precision fermentation convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting chicory processing investments toward jurisdictions with established Novel Food approval pathways and lower emission-compliance costs. Belgium and the Netherlands leverage pre-existing extraction infrastructure to capture contract manufacturing flows from North American beverage brands seeking EFSA-authorized health claim positioning.
Belgium
Functional beverage contract manufacturing drives procurement volumes for inulin-rich extracts. EFSA health claim authorizations enable premium positioning in dairy alternative formulations. The Flanders region hosts concentrated extraction facilities serving multinational food brands with clean-label prebiotic integration.
Netherlands
Dairy alternative launches from Rotterdam-based food conglomerates accelerate demand for food-grade inulin. EU F-Gas Regulation compliance pressures drive retrofit adoption of lower-emission drying technologies at processing plants. The Gelderland province anchors integrated supply chains linking field cultivation to spray-drying refinement.
United States
FDA GRAS recognition for inulin expands formulation flexibility in fortified yogurts and functional drinks. Clean-label procurement mandates from beverage manufacturers redirect R&D budgets toward prebiotic fiber sourcing. Midwest agricultural processors explore backward integration into chicory cultivation to secure captive supply.
Germany
Subscription-based gut health regimens concentrate consumer acquisition spend in direct-to-consumer inulin channels. REACH registration requirements for extraction solvents tighten purity verification protocols at processing facilities. Bavarian dietary supplement manufacturers adopt pharmacopeial-grade specifications for targeted microbiome applications.
India
Regional processors with limited refinement capacity source raw chicory for commodity fiber applications. FSSAI regulatory frameworks for functional foods remain underdeveloped relative to EU and US pathways. Maharashtra-based food ingredient distributors bridge supply gaps for bakery and confectionery manufacturers.
Chicory Roots Market Competitive Environment
Capacity expansion dominates the current landscape as established processors retrofit diffusion lines to eliminate solvent residues entirely. The market structure concentrates around integrated agribusiness conglomerates with captive cultivation networks and specialized extraction technology providers. Three archetypes define competitive positioning: Belgian-Dutch integrated processors with EFSA-authorized health claim access, North American ingredient conglomerates with FDA GRAS leverage, and Indian regional processors serving price-sensitive commodity tiers. Portfolio diversification and geographic expansion constitute the dominant competitive moves, with players bundling inulin supply with technical formulation support to secure multi-year contracts.
Within the integrated processor tier, COSUCRA and BENEO exemplify archetypes leveraging Belgian extraction infrastructure to anchor supply relationships with European dairy alternative brands. Cargill Incorporated occupies a position representing North American ingredient conglomerate diversification into chicory-based texturizers. Südzucker sits within the sugar-to-fiber diversification archetype, competing through backward integration into prebiotic raw material sourcing.
| Leading Market Players |
|---|
| COSUCRA |
| BENEO |
| Cargill Incorporated |
| Delecto Foods Pvt Ltd |
| Sensus |
| Südzucker |
| Pioneer Chicory |
| PMV Nutrient Products Pvt Ltd |
| Farmvilla Food Industries Pvt Ltd |
| Others |
Value Chain & Pricing Dynamics
Hot water diffusion energy costs cascade from Belgian and Dutch processing facilities through three distinct pricing tiers, with EFSA-authorized health claim premiums separating pharmaceutical-grade inulin from commodity spray-dried extracts and raw field-dried roots.
Pricing Analysis
Distributor margin compression in European channels separates EFSA-certified inulin premiums from uncertified commodity grades. Three-tier pricing structure across premium, standard, and economy levels reflects certification status, molecular weight specificity, and volume scale. Cost compression in mid-tier spray-dried extracts is intensifying because Jerusalem artichoke substitution erodes raw chicory bargaining power. Nutraceutical manufacturers in Germany exhibit lowest price sensitivity; Indian regional processors with limited refinement capacity show highest sensitivity.
Supply Chain Analysis
Return flows of spent extraction biomass to agricultural feedstock cycles remain underdeveloped across Belgian and Dutch processing hubs. Field cultivation concentrates in Belgium, the Netherlands, and northern France; extraction infrastructure draws from these clusters. Raw material dependencies rest on chicory root supply, natural gas for drying operations, and enzymatic hydrolysis catalysts. Single-source vulnerability from concentrated Belgian-Dutch processing creates geographic risk. Distribution runs through direct technical-service contracts for multinational beverage brands and spot-market transactions for commodity tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in chicory derivatives hinges on enzymatic hydrolysis cost-down trajectories and health claim premium capture in pharmaceutical-grade segments.
For Market Incumbents: Lock in multi-year formulation partnerships with North American dairy alternative brands before precision fermentation substitutes mature. COSUCRA and BENEO should extend Belgian extraction capacity to capture EFSA health claim premiums, while retrofitting diffusion lines to eliminate solvent residues secures REACH-compliant supply access. Fructan substitution from Jerusalem artichoke and agave represents the primary margin threat. For New Entrants and Emerging Players: Enter via South Korean MFDS and Japanese FOSHU regulatory pathways where European processors remain underrepresented. Direct-to-consumer subscription channels in Germany and the United Kingdom offer the most penetrable entry point, with personalized gut health regimens enabling margin capture outside commodity broker networks. Local partnership models with Asian dairy conglomerates unlock formulation trial access. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale processors face EU F-Gas Regulation retrofit burdens without capital reserves. Long-term viability favors integrated processors with captive cultivation and EFSA-authorized health claim portfolios. Acquisition targets include Belgian-Dutch extraction specialists with enzymatic hydrolysis capabilities. Practitioners should monitor precision fermentation cost curves and Asian regulatory harmonization progress for inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Hydrolysis Capacity Expansion | Enables molecular weight customization for pharmaceutical-grade inulin specifications demanded by German supplement manufacturers. |
| EFSA Health Claim Authorization Investment | Unlocks premium positioning in European dairy alternative formulations through prebiotic marketing permissions. |
| Backward Integration into Cultivation | Secures captive chicory root supply for processors facing geographic concentration risk in Belgian-Dutch clusters. |
| Asian Regulatory Partnership Development | Establishes FOSHU and MFDS pathway access for European processors seeking diversification beyond saturated Western markets. |
| Direct-to-Consumer Channel Launch | Bypasses ingredient broker margin absorption through subscription-based gut health regimens concentrated in German and UK markets. |
Study Parameters
Bottom-up beverage and nutraceutical demand modeling reconciled against top-down extraction capacity tracking forms the analytical core of this study. Primary interviews with plant managers at Belgian and Dutch processing facilities, procurement leads at North American dairy alternative brands, regulatory affairs specialists navigating EFSA Novel Food pathways, and technical R&D directors at enzymatic hydrolysis equipment suppliers combined with secondary validation from EU Novel Food catalog entries, FDA GRAS notification filings, ECHA REACH registration databases, and customs trade flow records. Triangulation between consumption-side projections and supply-side installed capacity ensures coherence across volume estimates.
Input-output matrices map chicory root cultivation yields through extraction recovery rates to finished inulin and roasted product volumes across the projection horizon. Segmentation dimensions modeled include product refinement tier, end-use application, distribution channel structure, and regional regulatory cluster. CAGRs derive from trend extrapolation of functional beverage procurement patterns and prebiotic fiber adoption curves in dietary supplements. Forecast inputs incorporate EU F-Gas Regulation compliance timelines and precision fermentation substitution threat assessments.
The model holds under stable EFSA health claim authorization frameworks and continued FDA GRAS recognition for inulin; deviation in Asian regulatory harmonization or breakthrough precision fermentation cost reductions would shift volume trajectories. Practitioners should monitor enzymatic hydrolysis equipment deployment rates and Asian partnership announcement velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Japan Plant Protein Market
Plant Based Food
Organic Pea Protein Market
Plant Based Food
Africa Soy Beverages Market
Plant Based Food
Vegan Spaghetti Market
Plant Based Food
Global Isolate Organic Soy Protein Market
Plant Based Food
Plant Based Meal Kit Market
Plant Based Food
Dandelion Root Extract Market
Plant Based Food
United States Rice Protein Market
Plant Based Food
Vegan Cookies Market
Plant Based Food
US Plant-Based Meat Market
Plant Based Food
North America Textured Vegetable Protein Market
Plant Based Food
Meat Substitutes Market
Plant Based Food
Global Tofu Market
Plant Based Food
Middle East and Africa Meat Substitute Market
Plant Based Food
Global Organic Soy Protein Market
Plant Based Food
Europe Plant-Based Food and Beverage Market