
 Liuweidihuang Market | 2026-2036
Liuweidihuang Market Size, Share, and Industry Trends Forecast 2026-2036
Liuweidihuang Market Insights
Aftermarket service revenue from practitioner training and diagnostic protocol licensing is reshaping how value accrues in the Liuweidihuang supply chain. Tong Ren Tang leverages its imperial pharmacy heritage to command premium positioning in hospital formulary negotiations. Beijing Tianshili Pharmaceutical anchors its position through backward integration into cultivated Rehmannia plantations in Henan province. Huqingyutang Pharmaceutical specializes in aqueous extraction methods that preserve glycoside stability for liquid preparations.
Liuweidihuang is a classical Chinese medicinal formulation comprising six botanical components—Rehmannia glutinosa, Cornus officinalis, Dioscorea opposita, Alisma orientalis, Poria cocos, and Moutan cortex—processed through decoction, concentration, and either alcohol precipitation or spray-drying to yield standardized extracts with specified polysaccharide and iridoid glycoside content. The formulation functions primarily as a kidney and liver tonifier prescribed for yin deficiency patterns manifesting as tidal fever, night sweats, and lumbar weakness. Powder and granule formats dominate hospital procurement due to dosing precision and formulary compliance, while liquid extracts capture growing nutraceutical demand in health shops where consumers prioritize bioavailability claims. Capsule segments remain niche, constrained by gelatin compatibility issues with hygroscopic herbal extracts and higher unit economics that limit pharmacy reimbursement coverage.
China's NMPA enforces Good Manufacturing Practice for Pharmaceutical Products (GMP) certification and botanical DNA barcoding requirements that elevate compliance costs for smaller extractors. The country's Pharmacopoeia Commission revises monograph specifications periodically, directly impacting acceptable heavy metal thresholds and pesticide residue limits for exported formulations. Stakeholders must monitor how China's dual carbon goals reshape energy-intensive spray-drying operations and whether SAMR expands health claim restrictions on e-commerce platforms.
Market Dynamics
China's NMPA has tightened botanical DNA barcoding requirements under revised Traditional Chinese Medicine regulations, forcing extractors to revalidate supply chains and hospital formularies to reassess vendor qualification protocols.
Growth Catalysts
- Hospital TCM Department Expansion:China's tertiary hospitals are establishing dedicated traditional Chinese medicine wings that standardize Liuweidihuang in chronic kidney disease protocols, creating institutional demand pull.
- Revised Pharmacopoeia Standards:The Pharmacopoeia Commission's elevated iridoid glycoside specifications are pushing manufacturers toward aqueous extraction methods that yield premium-grade extracts.
- Yangtze River Delta Clustering:Concentrated procurement from Shanghai and Jiangsu province hospital networks generates economies of scale in granule production.
Market Restraints
- Rehmannia Cultivation Volatility:Henan province weather patterns and soil depletion create raw material cost instability that compresses extractor margins.
- GMP Certification Barriers:Smaller workshops in Anhui and Sichuan provinces lack capital to meet NMPA spray-drying facility standards, concentrating supply among state-affiliated manufacturers.
- Gelatin Extract Compatibility:Hygroscopic herbal powders degrade standard capsule shells, limiting format diversification and pharmacy reimbursement eligibility.
Strategic Opportunities
- Practitioner Training Licensing:Diagnostic protocol certification programs create recurring revenue streams independent of physical product sales.
- Liquid Extract Nutraceutical Channel:Health shops in Guangdong province are adopting bioavailability-positioned tinctures for direct-to-consumer segments.
- Dual Carbon Energy Transition:SAMR incentives for solar-powered spray-drying operations offer compliance cost offsets for early adopters.
Industry Challenges
- Botanical Authentication Expertise Gap:Shortage of technicians trained in DNA barcoding and heavy metal testing protocols delays batch release timelines.
- Cross-Provincial Formulary Harmonization:Divergent hospital procurement standards between Jiangsu and Zhejiang create inventory fragmentation and working capital strain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liuweidihuang Market |
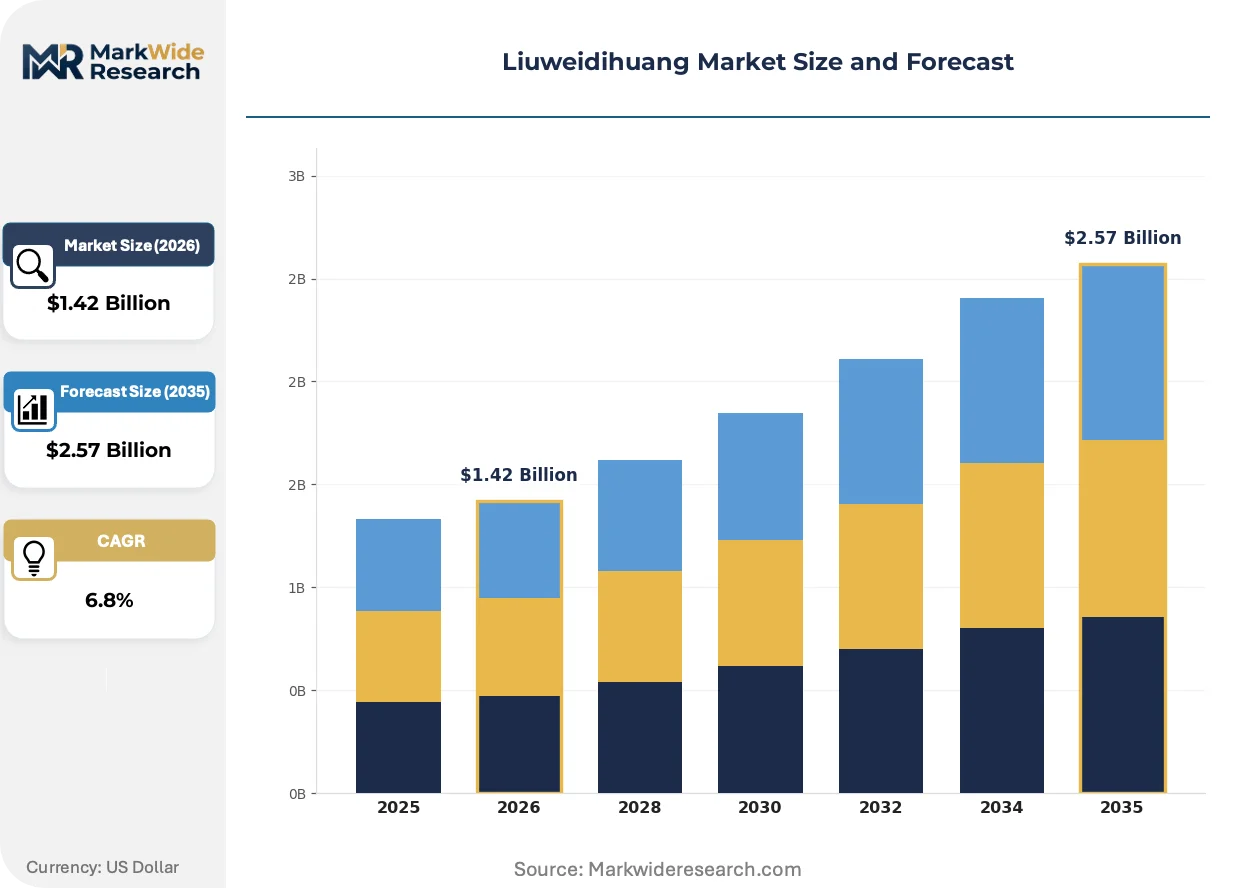
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Extract, Powder, Granules, Capsules Application: Traditional Medicine, Nutraceuticals, Dietary Supplements, Herbal Products End User: Hospitals, Pharmacies, Health Shops, Online Retailers Distribution Channel: Direct Sales, E-commerce, Wholesalers, Retail Outlets |
| Companies Covered | Tong Ren Tang, Beijing Tianshili Pharmaceutical, Beijing Lei Gong Tang Pharmaceutical, Shanxi Datong Pharmaceutical, Jilin Zixin Pharmaceutical, Guangzhou Chen Li Ji, Huqingyutang Pharmaceutical, Sichuan Baili Pharmaceutical, Beijing Dongcheng District Yiling Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liuweidihuang Market Trends and Innovations
Digital traceability systems and extraction technology advances are compressing quality assurance cycles while regulatory tightening reshapes competitive positioning around compliance depth rather than scale alone.
Near-infrared spectroscopy coupled with blockchain batch tracking is digitizing quality verification workflows. Large hospital TCM departments in Shanghai and Nanjing are mandating real-time provenance documentation for formulary inclusion. This technology stack is digitizing supplier qualification from a periodic audit exercise into a continuous monitoring architecture that disadvantages smaller extractors lacking IT infrastructure.
China's SAMR has expanded health claim restrictions on e-commerce platforms, prohibiting unverified yin deficiency treatment assertions in product listings. Third-party marketplace operators must now validate TCM practitioner endorsements before permitting sales. Liquid extract sellers targeting direct-to-consumer channels face the steepest compliance burden as they lack hospital formulary credibility to substitute for marketing claims.
Retail pharmacy chains are unbundling practitioner consultation from product dispensing, creating separate revenue lines for diagnostic services. Consumers in Hangzhou and Suzhou are purchasing Liuweidihuang granules only after paid TCM constitution assessments, shifting margin capture toward service providers. This behavioral pivot is most pronounced in urban centers where health insurance covers diagnostic but not over-the-counter herbal expenditures.
Liuweidihuang Market Segmentation
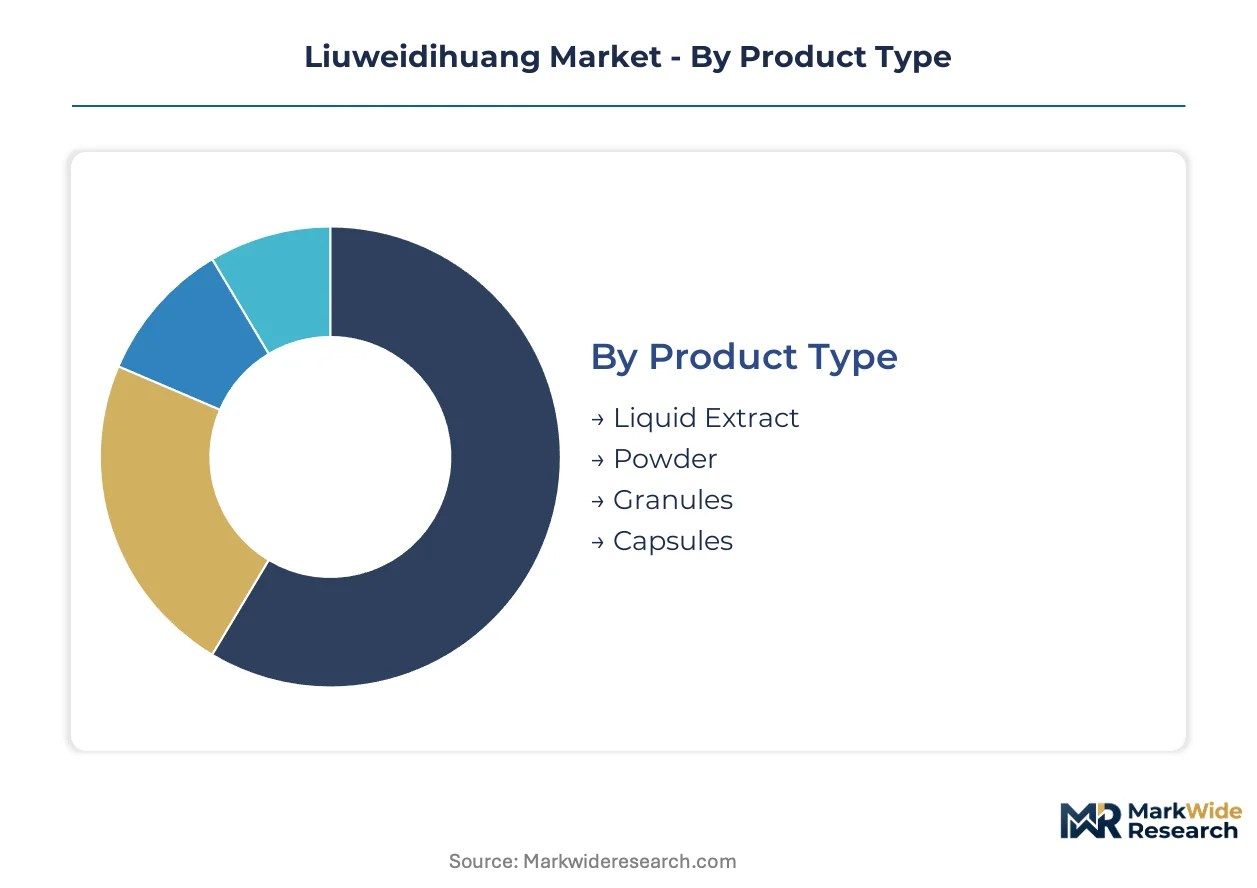
Segmentation in the Liuweidihuang market reveals how formulation format, procurement channel, and end-user sophistication create divergent margin structures. Manufacturers must align production capabilities with the technical and regulatory demands of each segment cluster.
Product Type:
After-sales service intensity varies sharply across formats, with liquid extracts requiring stability monitoring and granule formats demanding dosing protocol training for hospital staff.
- Granules:Spray-dried aqueous extracts standardized to specified polysaccharide and iridoid glycoside content enable precise dosing in hospital TCM departments. Shanghai and Jiangsu province hospital networks drive procurement concentration as tertiary facilities establish dedicated traditional Chinese medicine wings with formulary compliance requirements.
- Powder:Finely milled botanical blends processed through decoction and concentration yield cost-effective bulk preparations. Hospital procurement in the Yangtze River Delta dominates demand, though hygroscopic degradation risks constrain inventory holding periods and necessitate climate-controlled logistics.
- Liquid Extract:Aqueous extraction methods preserving glycoside stability serve nutraceutical channels in Guangdong province health shops where bioavailability claims attract direct-to-consumer purchasers.
- Capsules:Gelatin shell compatibility issues with hygroscopic herbal extracts limit pharmacy reimbursement coverage and relegate this format to niche positioning.
Granules hold the largest share; momentum sits with liquid extracts as health shops expand bioavailability-positioned tincture offerings.
Application:
Application segments stratify by regulatory pathway intensity, with traditional medicine facing Pharmacopoeia Commission monograph compliance and nutraceuticals navigating SAMR health claim restrictions.
- Traditional Medicine:Kidney and liver tonification protocols in hospital TCM departments require NMPA GMP certification and botanical DNA barcoding documentation. China's tertiary hospitals anchor demand as chronic kidney disease treatment standards incorporate Liuweidihuang formulations.
- Nutraceuticals:Direct-to-consumer positioning in health shops emphasizes yin deficiency pattern support, though SAMR prohibits unverified treatment assertions on e-commerce platforms.
- Dietary Supplements:Over-the-counter positioning in retail pharmacy chains faces reimbursement gaps that push margin capture toward bundled diagnostic services.
- Herbal Products:Multi-botanical formulations incorporating Liuweidihuang as a base extract serve compounding practitioners requiring batch-to-batch consistency.
Traditional medicine commands the revenue base; nutraceuticals are expanding most quickly as health shops unbundle consultation from dispensing.
End User:
End user concentration reflects China's healthcare infrastructure hierarchy, with hospitals and retail pharmacies operating under divergent procurement and reimbursement frameworks.
- Hospitals:TCM department expansion in tertiary facilities generates institutional demand with stringent vendor qualification protocols including real-time provenance documentation.
- Pharmacies:Retail chains in Hangzhou and Suzhou are separating diagnostic services from product dispensing, shifting margin structures toward practitioner consultation fees.
- Health Shops:Guangdong province outlets capture growing consumer segments prioritizing bioavailability claims and direct access to liquid extract formats.
- Online Retailers:Third-party marketplace operators face SAMR mandates to validate TCM practitioner endorsements before permitting sales.
Hospitals dominate procurement volume; health shops are gaining share fastest as consumer self-selection expands.
Distribution Channel:
Channel configuration determines compliance burden allocation, with direct sales absorbing qualification costs and e-commerce platforms facing intensified health claim scrutiny.
- Direct Sales:Manufacturer-to-hospital relationships centralize botanical authentication and heavy metal testing documentation within state-affiliated producers.
- E-commerce:Platform operators must navigate SAMR restrictions on yin deficiency treatment assertions, with liquid extract sellers facing the steepest validation requirements.
- Wholesalers:Cross-provincial inventory movement between Jiangsu and Zhejiang encounters formulary harmonization gaps that fragment working capital deployment.
- Retail Outlets:Physical pharmacy chains in the Yangtze River Delta maintain the deepest inventory positions for granule and powder formats.
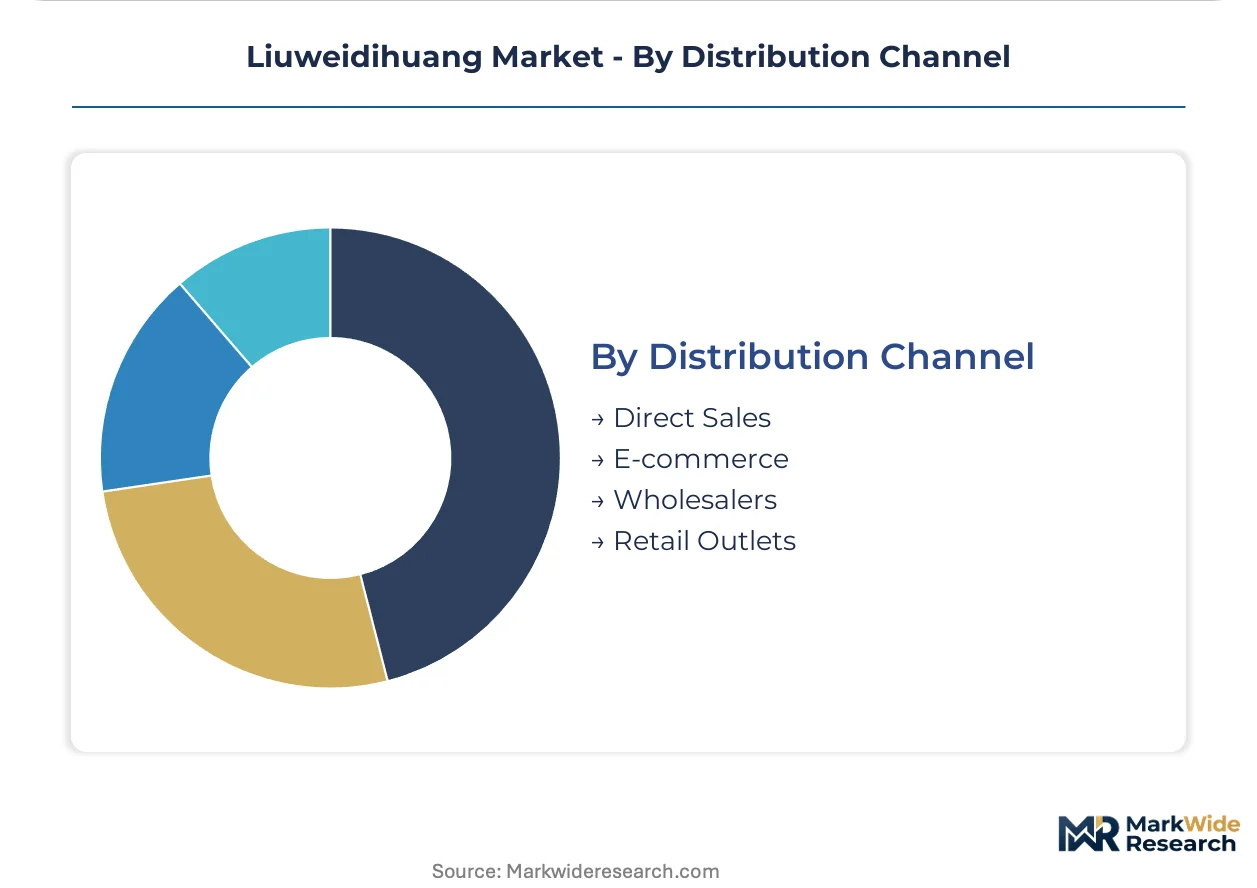
Direct sales retain the largest share; e-commerce channels show the steepest expansion trajectory as digital traceability systems mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes Liuweidihuang predominantly through hospital TCM departments with formulary compliance requirements, while Southeast Asian markets favor retail nutraceutical channels with bioavailability positioning. This consumption-mix differential shapes divergent regulatory burdens and margin structures across geographies.
China
Tertiary hospitals in Shanghai and Jiangsu province drive institutional procurement of granule formats with NMPA GMP certification and DNA barcoding documentation. The Pharmacopoeia Commission's revised iridoid glycoside specifications are forcing extractors toward aqueous extraction methods. The Yangtze River Delta clustering generates economies of scale in spray-dried production, with real-time provenance documentation now mandatory for formulary inclusion.
Japan
Specialty kampo medicine clinics in Tokyo and Osaka prescribe Liuweidihuang derivatives for chronic fatigue and menopausal syndromes, creating demand for standardized extract powders. PMDA oversight of traditional medicine imports requires heavy metal and pesticide residue testing aligned with Japanese Pharmacopoeia standards. The Kansai region's herbal medicine distributors maintain inventory positions for practitioner compounding.
South Korea
MFDS-regulated hanbang clinics in Seoul and Busan incorporate Liuweidihuang into kidney-tonifying protocols for diabetic nephropathy patients. The country's national health insurance system covers TCM prescriptions, anchoring hospital channel dominance. Daegu-Gyeongbuk province hosts extraction facilities serving both domestic formularies and export markets.
Vietnam
Traditional medicine shops in Hanoi and Ho Chi Minh City retail liquid extract formats to consumers self-treating yin deficiency symptoms without practitioner consultation. The Ministry of Health's tightened import documentation for botanical raw materials is elevating compliance costs for Chinese-sourced formulations. Northern border provinces witness informal cross-border trade in unprocessed Rehmannia.
Singapore
TCM wellness centers in the central business district prescribe Liuweidihuang for executive stress and sleep disorders, with HSA registration required for all imported finished products. The Health Sciences Authority's traditional medicine regulatory framework mandates stability testing for liquid preparations. Retail pharmacy chains in Orchard Road stock granule formats targeting affluent health-conscious consumers.
Liuweidihuang Market Competitive Landscape
Capability concentration sits with heritage manufacturers possessing imperial pharmacy credentials and cultivated raw material estates; scale advantage sits with state-affiliated producers with hospital formulary relationships. The market structures around three tiers: heritage brands commanding premium positioning, integrated pharmaceutical groups with backward cultivation control, and regional extractors serving provincial hospital networks. Dominant competitive moves include diagnostic protocol licensing to capture service revenue and solar-powered spray-drying facility investments to secure dual carbon compliance offsets.
Within the heritage-tier, Tong Ren Tang and Huqingyutang Pharmaceutical occupy positions anchored by centuries-old brand equity and aqueous extraction specialization. Beijing Tianshili Pharmaceutical exemplifies the integrated archetype through upstream control over cultivated Rehmannia plantations. These three manufacturers represent distinct strategic postures: brand premiumization, supply chain captivity, and format-specific technical differentiation.
| Leading Market Players |
|---|
| Tong Ren Tang |
| Beijing Tianshili Pharmaceutical |
| Beijing Lei Gong Tang Pharmaceutical |
| Shanxi Datong Pharmaceutical |
| Jilin Zixin Pharmaceutical |
| Guangzhou Chen Li Ji |
| Huqingyutang Pharmaceutical |
| Sichuan Baili Pharmaceutical |
| Beijing Dongcheng District Yiling Pharmaceutical |
| Others |
Pricing and Supply Chain Analysis
Spray-dryer undercapacity in Henan province is compressing extractor margins and forcing hospital procurement officers toward long-term offtake contracts with state-affiliated manufacturers who maintain captive Rehmannia estates. This utilization squeeze simultaneously elevates spot-market premiums for uncontracted granule volumes and accelerates backward integration investments among heritage brands seeking supply security.
Pricing Analysis
Long-term offtake agreements dominate hospital TCM department procurement, with annual volume commitments securing preferential iridoid glycoside grade specifications and bundled diagnostic protocol licensing. Price differentiation rests on NMPA GMP certification tier and cultivated versus wild-sourced Rehmannia provenance. Cost compression in standard-grade powder formats is intensifying because Anhui province workshops lack capital to meet revised spray-drying facility standards. Retail pharmacy chains exhibit the highest price sensitivity due to reimbursement gaps, while tertiary hospital formularies prioritize batch consistency over unit cost.
Supply Chain Analysis
Rehmannia glutinosa cultivation concentrates in Henan province, with secondary sourcing from Shanxi and Anhui provinces filling seasonal shortfalls. The supply chain draws from Cornus officinalis orchards in Shandong, Dioscorea opposita tuber networks in Henan, and Alisma orientalis marsh farms in Fujian. Single-source vulnerability in authenticated botanical DNA barcoding expertise delays batch release timelines during peak procurement windows. Distribution runs through direct manufacturer-to-hospital relationships for granule formats, while liquid extracts reach health shops via provincial pharmaceutical wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards manufacturers who internalize botanical authentication capabilities that smaller extractors cannot replicate, creating durable margin protection for incumbents with in-house DNA barcoding laboratories and cultivated raw material estates.
For Market Incumbents: Insulate formulary positioning by acquiring Rehmannia cultivation assets in Henan province before soil depletion accelerates raw material cost volatility. Deepen aqueous extraction technical capabilities to meet Pharmacopoeia Commission iridoid glycoside specifications that disqualify alcohol-precipitation competitors. Prioritize solar-powered spray-drying facility investments to capture SAMR dual carbon incentives and secure compliance cost offsets unavailable to carbon-intensive rivals. For New Entrants and Emerging Players: Build out liquid extract production capabilities targeting Guangdong province health shops where bioavailability-positioned tinctures face less formulary scrutiny than hospital procurement channels. Establish practitioner training certification programs as recurring revenue streams independent of physical product sales. Partner with retail pharmacy chains in Hangzhou and Suzhou to bundle diagnostic constitution assessments with granule dispensing, capturing margin migration toward service-based revenue. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among heritage manufacturers with imperial pharmacy brand equity and diagnostic protocol licensing portfolios. Long-term viability hinges on regulatory compliance depth rather than scale alone, favoring acquisition targets with established NMPA GMP certification and real-time provenance documentation infrastructure. Watch for SAMR expansion of health claim restrictions on e-commerce platforms as an inflection indicator that would accelerate consolidation toward hospital-direct channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivated Rehmannia | Captive supply from Henan province plantations insulates against weather-driven raw material cost spikes. |
| Diagnostic Protocol Licensing | Practitioner certification programs generate recurring revenue independent of physical Liuweidihuang sales. |
| Solar-Powered Spray-Drying Investment | SAMR dual carbon incentives offer compliance cost offsets unavailable to carbon-intensive competitors. |
| Aqueous Extraction Technology Upgrade | Preserves glycoside stability to meet Pharmacopoeia Commission iridoid specifications that disqualify legacy methods. |
| Blockchain Provenance Documentation | Shanghai and Nanjing hospital formularies now mandate real-time batch tracking for vendor qualification. |
Research Methodology
A standing panel of TCM department heads, hospital procurement managers, botanical extraction technical directors, and retail pharmacy chain category buyers provided ongoing calibration against secondary validation from NMPA GMP certification databases, Pharmacopoeia Commission monograph revisions, and SAMR regulatory filings. Primary fieldwork combined structured interviews with granule and liquid extract manufacturers, Rehmannia cultivation estate operators, and health shop proprietors in the Yangtze River Delta and Guangdong province. Bottom-up demand modeling from hospital formulary procurement records was triangulated against top-down value estimates derived from provincial pharmaceutical distribution data.
Scenario bracketing around NMPA enforcement intensity and dual carbon transition pace anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include formulation format, procurement channel, end-user type, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to historical procurement volume trajectories and elasticity-adjusted price evolution, incorporating iridoid glycoside specification tightening and e-commerce health claim restriction scenarios as demand-shifting inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by state-affiliated manufacturers or abrupt SAMR platform enforcement would shift outcomes materially. Cross-checking against NMPA GMP certification renewal rates and hospital TCM department budget allocation trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Japan Protein Market
Nutritional Supplements
Bovine Collagen Peptide Market
Nutritional Supplements
France Whey Protein Market
Nutritional Supplements
North America Digestive Health Supplements Market
Nutritional Supplements
Europe Dietary Supplements Market
Nutritional Supplements
Canada Nutraceuticals Market
Nutritional Supplements
Pet Dietary Supplements Market
Nutritional Supplements
Microalgae DHA Market
Nutritional Supplements
Nutritional Lipids Market
Nutritional Supplements
Micronutrient Powders (Mnps) Market
Nutritional Supplements
Protein Powder Market
Nutritional Supplements
Tea Tree Oil Market
Nutritional Supplements
Plant Based Iron Supplements Market
Nutritional Supplements
Global General Well-Being Dietary Supplements Market
Nutritional Supplements
Asia Pacific Nutraceuticals Market
Nutritional Supplements
US Nutraceuticals Market