
 Mineral Supplements Market | 2026-2036
Mineral Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Mineral Supplements Market Intelligence
The FDA's updated Good Manufacturing Practices for dietary supplements is realigning the cost-of-entry calculus for new mineral supplement entrants, forcing smaller brands to invest in third-party certification or exit the market entirely. Bayer AG leverages its pharmaceutical heritage to sustain consumer trust in quality-assured mineral formulations across mass retail channels. Glanbia PLC anchors its position through backward integration into dairy-derived mineral extraction, securing captive supply for its sports nutrition portfolio.
Mineral supplements are concentrated or chelated inorganic compounds—typically carbonates, citrates, or bisglycinates—delivering essential elements such as calcium, magnesium, zinc, and iron to correct dietary deficiencies or support physiological functions including bone mineralization, enzymatic catalysis, and oxygen transport. Calcium formulations occupy the largest volume share due to established osteoporosis prevention protocols, while zinc segments are registering the fastest growth trajectory as immune-modulation claims gain clinical validation. Powder and liquid forms are expanding share among pediatric and geriatric populations where swallowing difficulties limit tablet uptake, redirecting margin pools toward flexible-delivery specialists.
The FDA enforces Current Good Manufacturing Practice regulations for dietary supplements under 21 CFR Part 111, mandating identity testing, purity verification, and contamination controls that elevate production costs but filter out substandard competitors. FTC advertising substantiation requirements further constrain marketing claims, compelling brands to invest in clinical evidence before promoting mineral-specific health outcomes. Stakeholders must monitor evolving FDA enforcement priorities around New Dietary Ingredient notifications, as the agency's posture on novel mineral chelates and delivery technologies will determine which product architectures secure sustained market access.
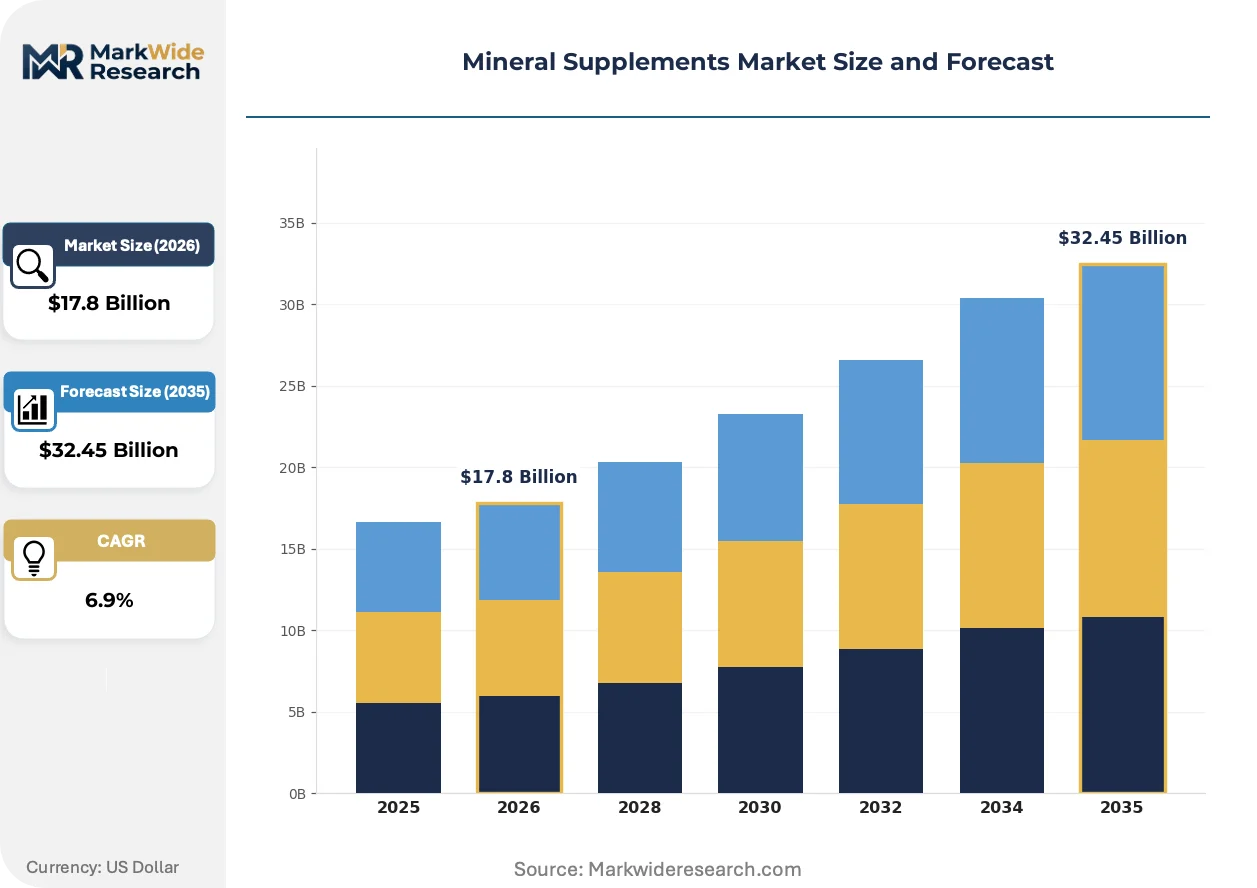
Market Dynamics
The FDA's updated Good Manufacturing Practices under 21 CFR Part 111 are restructuring entry economics by mandating identity testing and contamination controls that smaller mineral supplement brands cannot absorb without third-party certification partnerships.
Growth Catalysts
- Preventive healthcare protocols:Osteoporosis screening programs in the United States and Japan are institutionalizing calcium supplementation as standard-of-care, embedding mineral products into routine clinical workflows rather than discretionary wellness spending.
- 21 CFR Part 111 enforcement:The FDA's intensified facility inspections and warning letter campaigns are filtering out substandard manufacturers, concentrating volume among quality-compliant suppliers and elevating category trust indices.
- Athlete nutrition specialization:Sports nutrition formulators are incorporating chelated zinc and magnesium into recovery protocols, creating dedicated SKU architectures that command shelf space distinct from general wellness positioning.
Market Restraints
- Raw material concentration:High-purity mineral carbonate supply clusters in China and India, exposing formulators to export licensing volatility and geopolitical friction in critical input sourcing.
- FTC substantiation costs:The Federal Trade Commission's requirement for clinical evidence supporting immune-modulation claims forces brands to absorb multi-year study timelines before market entry, compressing ROI horizons.
- Tablet-to-liquid substitution:Pediatric and geriatric swallowing difficulties are accelerating demand for alternative delivery formats, stranding capital invested in high-speed tablet press infrastructure.
Strategic Opportunities
- Direct-to-consumer channel maturation:Subscription wellness platforms in the United States are capturing recurring revenue streams through personalized mineral regimens based on at-home deficiency testing.
- EU Green Deal alignment:The European Union's sustainable packaging mandates are creating first-mover advantages for brands deploying biodegradable sachets and algae-derived capsule shells ahead of compliance deadlines.
- Precision fermentation convergence:Biotechnology firms are engineering microbial strains for bioavailable mineral chelate production, potentially displacing traditional mining-dependent extraction with controlled fermentation outputs.
Industry Challenges
- Analytical chemistry talent scarcity:Identity testing protocols under 21 CFR Part 111 require mass spectrometry and chromatography expertise that contract laboratories struggle to staff at scale.
- Legacy ERP integration:Batch record digitization for FDA audit trails demands capital outlays that mid-tier manufacturers face difficulty financing without dilutive equity raises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mineral Supplements Market |
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $32.45 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium, Magnesium, Zinc, Iron Form: Tablets, Capsules, Powders, Liquids End User: Adults, Children, Pregnant Women, Athletes Distribution Channel: Online Retail, Pharmacies, Supermarkets, Health Stores |
| Companies Covered | Abbott, Bayer AG, Amway, Nestlé, Herbalife International of America, Inc., Pfizer Inc., Glanbia PLC, dsm-firmenich, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mineral Supplements Market Strategic Shifts & Innovations
Mineral supplement delivery technologies are fragmenting traditional tablet dominance as bioavailability science and demographic swallowing constraints reshape formulation priorities across pediatric, geriatric, and athletic segments.
Liposomal encapsulation technology is decentralizing absorption efficiency advantages once concentrated in intravenous clinical settings. Functional medicine practitioners and high-performance athletic programs are adopting liposomal magnesium and zinc at accelerating rates. This delivery architecture is decentralizing margin capture from conventional tablet manufacturers toward specialty formulators with nanoscale processing capabilities.
The European Food Safety Authority's novel food ingredient approval pathways are tightening evidentiary requirements for mineral chelates not consumed in significant quantities before 1997. EFSA's 150-day safety assessment timelines are delaying European market entry for Asian-manufactured bisglycinate complexes. Sports nutrition brands are responding by front-loading toxicology studies and establishing European Union reference laboratories for preemptive dossier preparation.
Subscription-based replenishment models are displacing episodic retail purchasing among mineral supplement consumers. Direct-to-consumer platforms are capturing recurring revenue through algorithmic dosing adjustments based on seasonal deficiency patterns and activity-level tracking. This behavioral shift is most visible in the United States, where wellness-as-a-service platforms have achieved double-digit household penetration in coastal metropolitan markets.
Mineral Supplements Market Segmentation
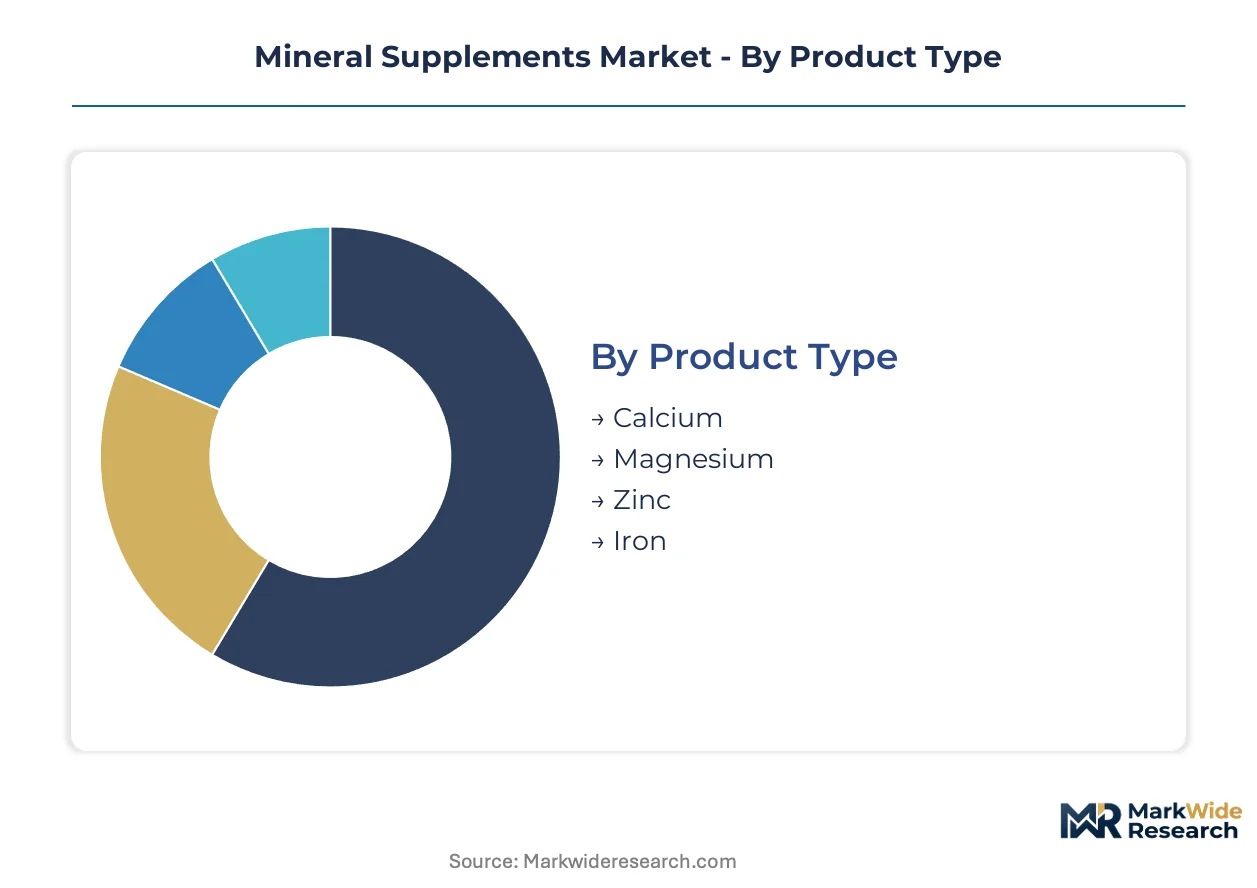
Mineral supplement segmentation reveals divergent capital requirements across formulation technologies and delivery architectures. Equipment intensity varies dramatically between high-speed tablet presses and precision liquid bottling lines, reshaping which players can compete across product categories.
Product Type:
Calcium and zinc formulations demand the heaviest upfront investment in granulation and chelation infrastructure, while iron production requires specialized oxidation-controlled environments that elevate facility costs.
- Calcium:Carbonate and citrate salts dominate volume, with osteoporosis prevention protocols in the United States and Japan embedding these formulations into clinical workflows. Mass-market positioning concentrates demand among geriatric populations and postmenopausal women, though absorption variability drives ongoing bioavailability R&D spending.
- Zinc:Bisglycinate and picolinate chelates command premium positioning as immune-modulation claims gain clinical traction among athletic programs and functional medicine practitioners. Sports nutrition brands are capturing margin through dedicated recovery SKUs that separate zinc from general multivitamin positioning.
- Magnesium:Glycinate and malate forms target sleep and neuromuscular applications, with powder formats gaining share among biohacking communities.
- Iron:Ferrous bisglycinate addresses tolerability concerns that limit traditional sulfate uptake, particularly among pregnant women and anemia protocols.
Most installed capacity flows through Calcium. Expansion is steepest in Zinc.
Form:
Tablet manufacturing requires the most substantial fixed-asset deployment, with high-speed rotary presses and coating lines representing seven-figure capital commitments that liquid and powder specialists can avoid.
- Tablets:Film-coated and effervescent variants retain dominance in mass retail channels, though swallowing difficulties among pediatric and geriatric populations are eroding share. Bayer AG and legacy pharmaceutical players leverage existing press infrastructure to defend cost positions.
- Liquids:Liposomal encapsulation technology is decentralizing absorption advantages once concentrated in clinical settings, with nanoscale processing capabilities becoming the new competitive moat. Functional medicine practitioners and high-performance athletic programs are driving uptake of liposomal magnesium and zinc.
- Capsules:Two-piece gelatin and pullulan shells offer dose flexibility for mineral combinations, with algae-derived alternatives emerging under EU Green Deal packaging mandates.
- Powders:Bulk tubs and single-serve sachets capture sports nutrition and pediatric segments where dosing customization matters.
Tablets still move the highest absolute volumes. Liquids are climbing the fastest as delivery technology investments mature.
End User:
Athletes and pregnant women represent the most specialized formulation requirements, demanding third-party certification and contaminant testing that general adult products can bypass.
- Athletes:NSF Certified for Sport and Informed Sport protocols mandate batch-tested mineral chelates free from banned substances, creating certification costs that filter out smaller suppliers. Chelated zinc and magnesium recovery formulations command dedicated shelf space distinct from general wellness positioning.
- Pregnant Women:Iron and folate combinations require teratogenicity screening and trimester-specific dosing architectures that elevate regulatory compliance burdens.
- Adults:Preventive healthcare protocols in the United States are embedding calcium and vitamin D combinations into routine clinical recommendations.
- Children:Gummy and liquid formats dominate, with palatability engineering representing a distinct R&D competency from adult tablet formulation.
Adults constitute the broadest installed base. Athletes are gaining share fastest as performance nutrition mainstreams.
Distribution Channel:
Online retail and health stores demand the most sophisticated inventory and personalization infrastructure, while supermarkets and pharmacies rely on established logistics relationships rather than technology investment.
- Online Retail:Subscription wellness platforms in the United States are capturing recurring revenue through algorithmic dosing adjustments based on at-home deficiency testing and activity-level tracking. Direct-to-consumer brands bypass retail margin stacking but absorb customer acquisition costs.
- Health Stores:Staff-trained environments support premium mineral chelate education, with practitioner-exclusive lines maintaining price integrity away from mass-market discounting.
- Pharmacies:Pharmacist recommendation protocols in Japan and the United States drive calcium and iron uptake alongside prescription workflows.
- Supermarkets:Price-competitive private label calcium and multimineral products dominate shelf space, with limited SKU breadth compared to specialized channels.
Pharmacies and supermarkets still handle the most physical volume. Online retail is expanding most quickly as subscription models achieve household penetration in coastal metropolitan markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biochemists and formulation scientists cluster in Switzerland and the United States, anchoring premium mineral chelate development. Quality assurance specialists concentrate in Germany and Japan, supporting cGMP audit infrastructure. These talent distributions shape where regulatory-compliant production scales fastest.
United States
Preventive healthcare spending and direct-to-consumer wellness brands accelerate mineral supplement uptake. FDA enforcement of 21 CFR Part 111 mandates identity testing and contamination controls that elevate production costs. The Greater Boston corridor hosts contract analytical laboratories specializing in mass spectrometry for mineral identity verification.
Germany
Pharmaceutical-grade manufacturing heritage supports premium mineral formulation exports. EFSA novel food approval pathways tighten evidentiary requirements for mineral chelates not consumed before 1997. The Rhine-Main region concentrates encapsulation technology providers serving EU-wide supplement brands.
China
High-purity mineral carbonate supply clusters expose formulators to export licensing volatility. SAMR dietary supplement registration requirements intensify documentation burdens for imported mineral products. The Yangtze River Delta houses precipitation-grade calcium carbonate facilities supplying global tablet manufacturers.
Japan
Osteoporosis screening programs institutionalize calcium supplementation as standard-of-care. PMDA and METI coordination enforces strict specifications for mineral content labeling and stability testing. The Kansai region maintains traditional precipitation facilities for pharmaceutical-grade magnesium oxide production.
India
Ayurveda-mineral convergence creates distinct formulation categories outside Western pharmacopeia standards. FSSAI quality standards for health supplements mandate heavy metal testing that filters out unorganized sector producers. Gujarat's pharmaceutical zones export iron and zinc formulations to African and Southeast Asian markets.
Mineral Supplements Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across mineral supplement manufacturing. The market structure tiers between mass-market pharmaceutical heritage players and emerging direct-to-consumer formulators. Three archetypes dominate: pharmaceutical-heritage conglomerates with existing cGMP infrastructure, dairy-integrated nutrition specialists with captive mineral extraction, and digital-native wellness brands bypassing retail margin stacking. Competitive moves concentrate on third-party certification partnerships and backward integration into mineral salt supply.
Among pharmaceutical-heritage conglomerates, Bayer AG and Pfizer Inc. occupy positions leveraging existing quality assurance infrastructure and mass retail channel relationships. Glanbia PLC exemplifies the dairy-integrated archetype, securing captive mineral supply through upstream control over extraction processes. These three companies represent distinct strategic postures: quality-assured mass distribution, supply chain verticality, and scale-driven manufacturing efficiency.
| Leading Market Players |
|---|
| Abbott |
| Bayer AG |
| Amway |
| Nestlé |
| Herbalife International of America, Inc. |
| Pfizer Inc. |
| Glanbia PLC |
| dsm-firmenich |
| Sanofi |
| Others |
Cost & Logistics Intelligence
Liposomal encapsulation technology adoption is simultaneously elevating production cost thresholds and concentrating manufacturing capability among nanoscale processing specialists with pharmaceutical-grade cleanroom infrastructure. This delivery-method transition rewards brands with captive fermentation or spray-drying assets while marginalizing conventional tablet manufacturers.
Pricing Analysis
Bundled certification-plus-product offerings command substantial premiums over unbundled mineral salts. Three-tier pricing structure across pharmaceutical-grade, practitioner-exclusive, and mass-market economy levels stratifies by third-party testing depth and bioavailability claims. Pricing pressure stems from direct-to-consumer subscription models compressing per-unit margins through recurring revenue optimization. Mass-market supermarket buyers exhibit highest price sensitivity, while functional medicine practitioners and athletic programs prioritize absorption efficiency over cost.
Supply Chain Analysis
Analytical chemistry talent scarcity in China and India constrains high-purity mineral carbonate production scaling despite abundant raw ore deposits. Precipitation-grade calcium carbonate and bisglycinate complexes draw from Yangtze River Delta and Gujarat pharmaceutical zones, with ferrous salts and zinc oxide resting on Indian export licensing stability. Single-source vulnerability concentrates in Chinese export permit volatility for pharmaceutical-grade inputs. Distribution runs through direct-to-consumer platforms and health store networks, bypassing traditional wholesale pharmaceutical distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mineral supplements market compounds steadily as preventive healthcare protocols institutionalize daily supplementation across aging demographics. FDA enforcement of 21 CFR Part 111 creates durable competitive moats for quality-compliant incumbents.
For Market Incumbents: Deepen backward integration into chelated mineral salt production to secure supply continuity amid Chinese export licensing friction. Expand NSF Certified for Sport and Informed Sport certification coverage to defend shelf space against emerging direct-to-consumer brands. Prioritize liposomal processing capacity additions in Switzerland or the Greater Boston corridor where analytical talent clusters. For New Entrants and Emerging Players: Begin with pediatric liquid formats or geriatric powder sachets where swallowing difficulties have eroded incumbent tablet dominance. Target subscription wellness platforms in coastal United States metropolitan markets with algorithmic dosing personalization. Pursue practitioner-exclusive distribution through functional medicine networks before attempting mass retail placement. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier contract manufacturers with underutilized cGMP capacity and pending 21 CFR Part 111 compliance investments. Long-term viability hinges on bioavailability technology differentiation rather than commodity mineral sourcing. Monitor FDA warning letter issuance rates as inflection indicator for competitive consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Third-Party Certification Investment | NSF Certified for Sport and USP verification separate premium positioning from unverified competitors in athletic channels. |
| Backward Integration into Mineral Salt Production | Captive bisglycinate and picolinate manufacturing insulates margin from Chinese export licensing volatility. |
| Liposomal Processing Capacity Expansion | Nanoscale encapsulation capabilities capture shifting demand from tablet-averse pediatric and geriatric populations. |
| Direct-to-Consumer Platform Launch | Subscription algorithms bypass retail margin stacking and capture recurring revenue in United States coastal markets. |
| Precision Fermentation Partnership | Microbial strain engineering for bioavailable chelates potentially displaces mining-dependent extraction with controlled biotech outputs. |
Research Approach
Multiple input streams — formulation scientist interviews, quality assurance director discussions, contract laboratory manager conversations, and health store buyer consultations — were reconciled against FDA warning letter databases, EFSA novel food approval registers, and United States customs import records. Secondary validation drew from 21 CFR Part 111 inspection data, sports nutrition brand SEC filings, and European encapsulation technology patent filings. Bottom-up SKU-level volume estimates and top-down category spend analysis were cross-referenced for convergence.
Historical volume trajectories were cross-referenced against panel input from procurement leads at sports nutrition brands and pharmacy chain category managers. The analytical framework segmented by mineral type, delivery form, end-user archetype, and distribution channel across the analysis window. CAGRs were derived from regression-weighted growth rate synthesis. Forecast inputs incorporated 21 CFR Part 111 enforcement intensity projections and direct-to-consumer subscription penetration curves.
Several conditions sit outside the modeled scope, including unforeseen FDA enforcement priority shifts around New Dietary Ingredient notifications and precision fermentation technology commercialization timelines. Forecasts assume sustained preventive healthcare protocol adoption in the United States and Japan. Material deviation in Chinese export licensing policy or liposomal manufacturing equipment lead times warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Non-Fish Omega 3 Supplements Market
Nutritional Supplements
Lion's Mane Market
Nutritional Supplements
Australia Protein Market
Nutritional Supplements
Liuweidihuang Market
Nutritional Supplements
Global Reishi Mushroom Extracts Market
Nutritional Supplements
Europe Nutrition and Supplements Market
Nutritional Supplements
South Africa Nutraceuticals Market
Nutritional Supplements
Microencapsulated Fish Oil Market
Nutritional Supplements
Immunity Boosting Food Market
Nutritional Supplements
Diet Shakes Market
Nutritional Supplements
Dietary Fiber Gummies Market
Nutritional Supplements
France Whey Protein Market
Nutritional Supplements
Mushroom Powders Market
Nutritional Supplements
Cod Liver Oil Market
Nutritional Supplements
Nutraceutical Supplements Market
Nutritional Supplements
Australia Nutraceuticals Market