
 Dairy Flavors Market | 2026-2036
Dairy Flavors Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy Flavors Market Analysis
Natural dairy extracts and fermented flavor precursors is hardening as the preferred base material over synthetic esters and aldehydes in premium formulation. Kerry Group leverages its integrated dairy supply chain to control raw material quality from farm to flavor house. dsm-firmenich anchors its position through deep biotechnology expertise in enzyme-modified cheese concentrates. Synergy Flavors competes by specializing in regional taste profiles tailored to European and North American palates.
Dairy flavors comprise concentrated taste-active compounds derived from milk, cream, butter, or cheese through enzymatic hydrolysis, fermentation, or thermal processing, typically standardized at specific fold strengths to deliver consistent flavor intensity in finished goods. Cheddar and mozzarella flavor concentrates dominate volume due to their ubiquity in snack seasoning and ready-meal applications, while cream cheese profiles capture expanding margin pools in dessert and bakery segments. Food manufacturers represent the most structurally important end-user channel, absorbing bulk volumes for industrial-scale production of yogurts and cheese spreads where flavor consistency directly impacts brand equity.
The FDA governs flavor labeling under 21 CFR 101.22, requiring clear distinction between natural and artificial dairy-derived ingredients, while EFSA evaluates novel flavor substances through its Flavouring Group Evaluation program. The EU Green Deal's Farm to Fork strategy pressures suppliers to document sustainable sourcing across dairy supply chains. Stakeholders must monitor evolving enzymatic processing standards and clean-label certification requirements as purchasing criteria tighten across retail and foodservice channels.
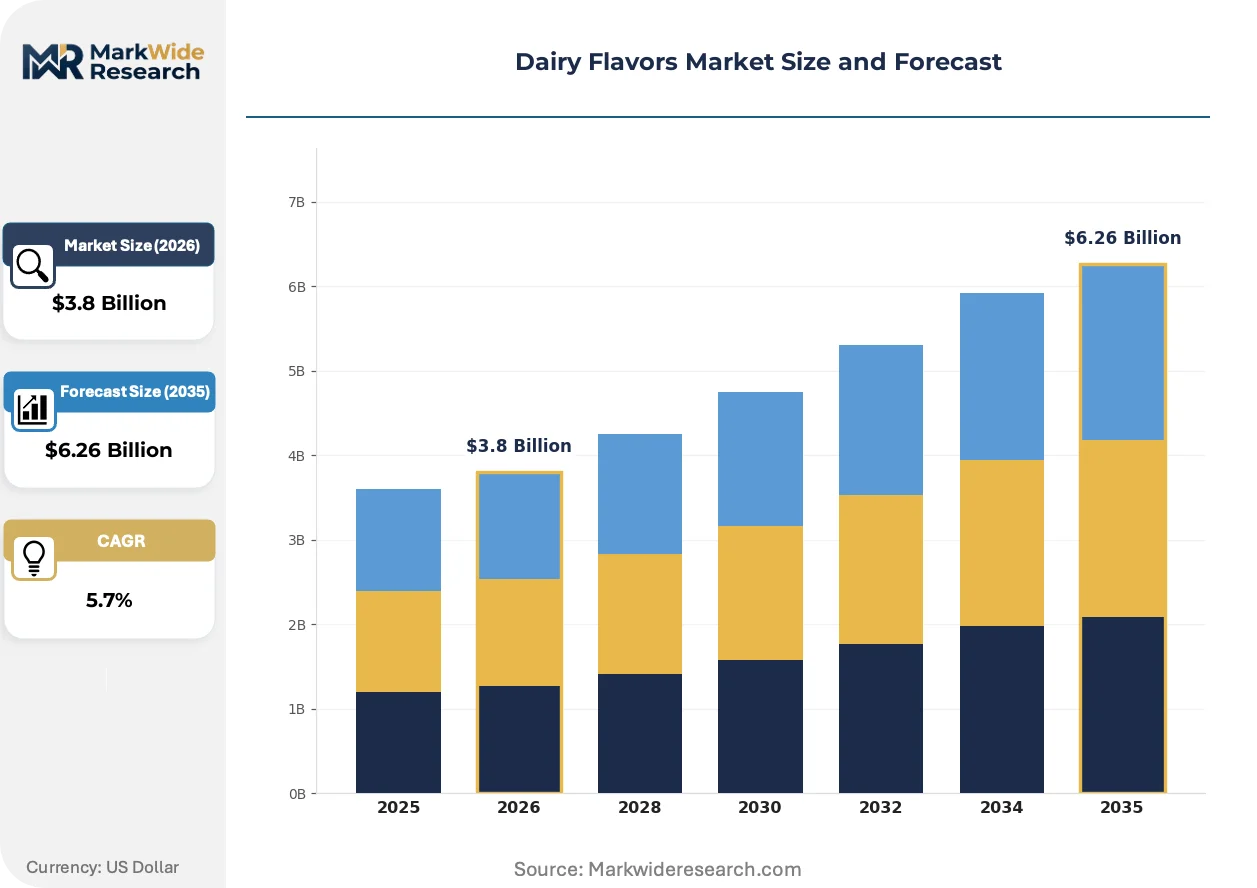
Market Dynamics
Clean-label formulation mandates from the FDA and EFSA are compressing synthetic flavor acceptance while enzyme-modified dairy concentrates capture formulation share from artificial esters across North American and European food manufacturing.
Growth Catalysts
- EFSA Flavouring Group Evaluation:Accelerated safety clearance for novel dairy-derived substances expands the approved ingredient palette for European dairy flavor houses.
- Plant-based dairy alternatives:Food manufacturers seek authentic dairy taste profiles in oat, almond, and soy bases without animal-derived inputs, opening new formulation service contracts.
- Enzymatic hydrolysis:Precision enzyme engineering reduces production cycle times for concentrated cheese and butter notes while improving flavor fidelity.
Market Restraints
- Milk powder commodity volatility:Input cost swings for skim milk solids and whey permeates compress margin predictability for flavor concentrate producers.
- Supply concentration in Wisconsin and Netherlands:Raw dairy material sourcing clusters in two dominant geographies, exposing buyers to regional climate and logistics disruptions.
- 21 CFR 101.22 compliance burden:Natural versus artificial labeling distinctions require extensive documentation, slowing new product introduction timelines.
Strategic Opportunities
- India FSSAI clean-label pathway:Emerging regulatory alignment with Western standards creates first-mover positioning for exporters into India's processed food sector.
- Fermented flavor precursors:Controlled microbial fermentation generates complex umami and sulfur notes unattainable through thermal processing alone.
- Direct-to-foodservice distribution:Bypassing traditional ingredient distributors, flavor houses build captive relationships with restaurant chains and ghost kitchen operators.
Industry Challenges
- Flavor chemist talent scarcity:Specialized expertise in dairy protein hydrolysis and Maillard reaction control commands premium compensation, constraining R&D expansion.
- ISO 22000 certification timelines:Food safety management system audits for multi-site production networks delay market entry by six to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy Flavors Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cheddar, Mozzarella, Cream Cheese, Gouda Application: Dairy Desserts, Yogurts, Cheese Spreads, Sauces End User: Food Manufacturers, Restaurants, Retailers, Bakers Flavor Profile: Sweet, Savory, Spicy, Herbal |
| Companies Covered | Edlong Corporation, Bluegrass Ingredients, Kerry Group, Jeneil Biotechnology, Butter Buds Inc., International Flavors & Fragrances, Inc., Synergy Flavors, dsm-firmenich, McCormick & Company, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy Flavors Market Emerging Trajectories
Biotechnology-enabled flavor production is displacing traditional extraction methods while regulatory transparency requirements reshape how dairy-derived ingredients are sourced, labeled, and marketed across international supply chains.
Precision fermentation for dairy proteins is consolidating as the dominant production modality for authentic flavor precursors without animal agriculture. Specialty flavor houses in Denmark and California are commissioning commercial-scale bioreactors to produce casein and whey protein hydrolysates. This biotechnology shift is consolidating control over taste-active peptide sequences that previously required ton-scale milk processing.
The EU Green Deal's Farm to Fork strategy mandates documented sustainable sourcing across dairy supply chains entering European food manufacturing. EFSA now requires lifecycle assessment data for novel flavor substances seeking safety clearance. Small and mid-sized flavor suppliers without traceability infrastructure face exclusion from branded food manufacturer approved vendor lists.
Food manufacturers are unbundling flavor procurement from consolidated ingredient distributors, establishing direct technical partnerships with specialized dairy flavor houses. This disintermediation concentrates purchasing power among CPG brands with sufficient volume to justify dedicated formulation collaboration. The United States exhibits the most pronounced shift, where clean-label priorities have compressed tolerance for distributor-mandated minimum order quantities and generic product portfolios.
Dairy Flavors Market Segmentation
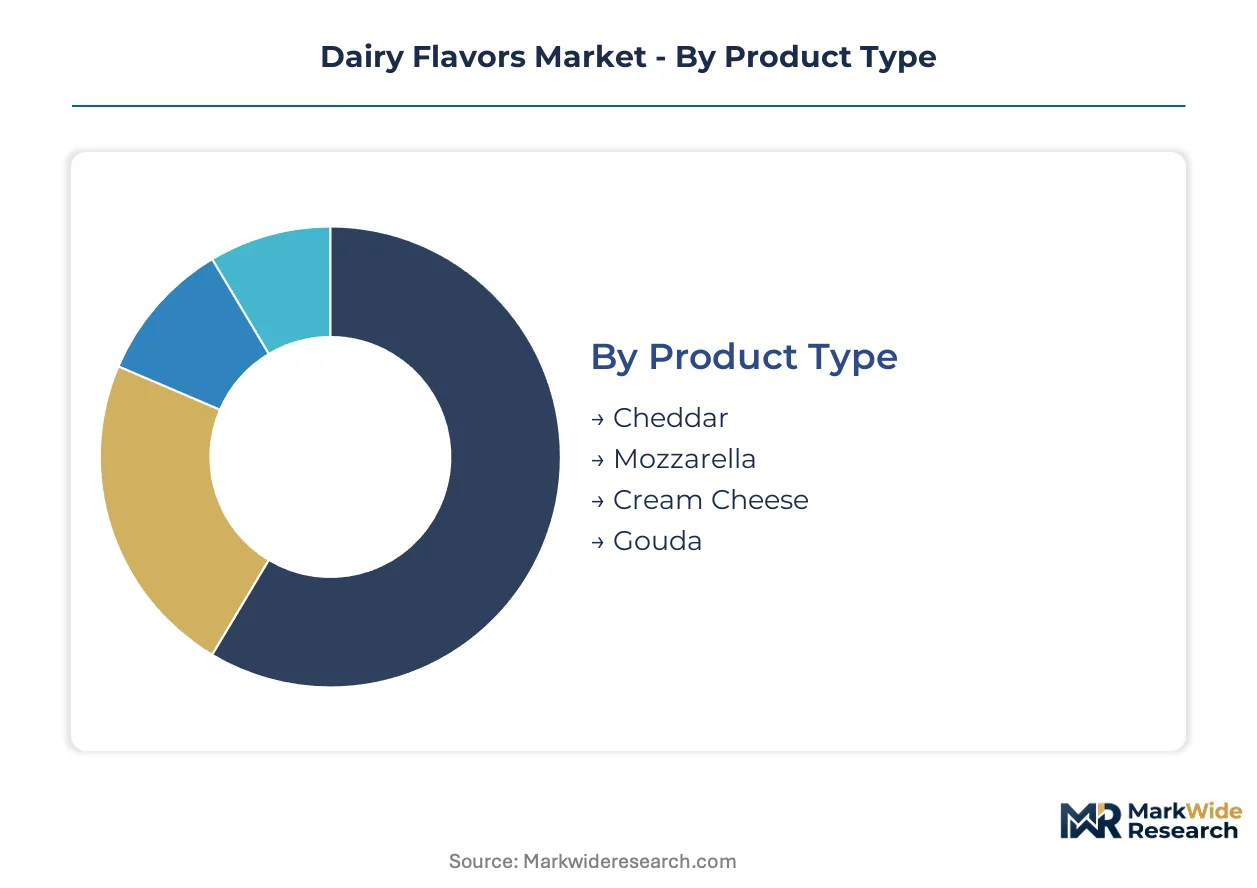
Dairy flavor procurement patterns diverge sharply between commodity-scale industrial buyers and specialized artisan producers, with formulation complexity and volume thresholds determining supplier selection criteria across each segment cluster.
Product Type:
Standardization dominates cheddar and mozzarella concentrates where fold-strength specifications enable bulk interchangeability, while cream cheese and gouda profiles command premium positioning through proprietary enzymatic processing protocols.
- Cheddar:Enzyme-modified concentrates standardized at 10x to 20x fold strength deliver consistent sharpness notes for snack seasoning applications. Food manufacturers in the United States absorb bulk volumes for processed cheese spreads where flavor consistency protects brand equity.
- Mozzarella:Mild, milky flavor precursors derived from lipolysis-controlled cream bases replicate fresh curd characteristics. Demand concentrates in pizza chain manufacturing and frozen ready-meal production where stretch and melt visualization must pair with authentic taste.
- Cream Cheese:Lactic acid fermentation profiles with controlled diacetyl generation serve dessert and bakery formulation. Premium positioning reflects extended culture times.
- Gouda:Caramelized note development through controlled Maillard reaction produces aged cheese characteristics without prolonged curing.
Most installed capacity flows through cheddar. Expansion is steepest in cream cheese.
Application:
Volume concentration in yogurt and cheese spread manufacturing contrasts with margin capture in dessert and sauce applications where flavor differentiation commands formulation service premiums.
- Dairy Desserts:Cream-forward profiles with vanilla and caramel topnotes mask off-flavors in reduced-fat ice cream bases. European manufacturers lead clean-label formulation.
- Yogurts:Fruit-compatible dairy notes must survive high-acid fermentation without protein precipitation. Greek-style applications require concentrated butterfat character.
- Cheese Spreads:Processed cheese analogs depend on emulsifying salt systems paired with sharp cheddar concentrates for flavor impact.
- Sauces:Heat-stable cheese flavors for retort and aseptic processing demand specialized encapsulation to prevent fat separation.
Volume leadership sits with yogurts. Margin expansion is most pronounced in dairy desserts.
End User:
Procurement scale separates national food manufacturers with captive technical collaboration from fragmented foodservice operators purchasing through distributor intermediaries.
- Food Manufacturers:Industrial-scale dairy and snack producers specify custom concentrate blends with documented supply chain traceability for EFSA compliance.
- Restaurants:Chain operators with centralized procurement bypass distributors for direct flavor house relationships on signature sauce formulations.
- Retailers:Private-label dairy programs demand cost-optimized standard concentrates with rapid formulation turnaround.
- Bakers:Artisan and industrial bakeries source cream cheese profiles for frosting and filling applications with clean-label certification requirements.
Purchasing power concentrates among food manufacturers. Disintermediation is advancing fastest in restaurant chains.
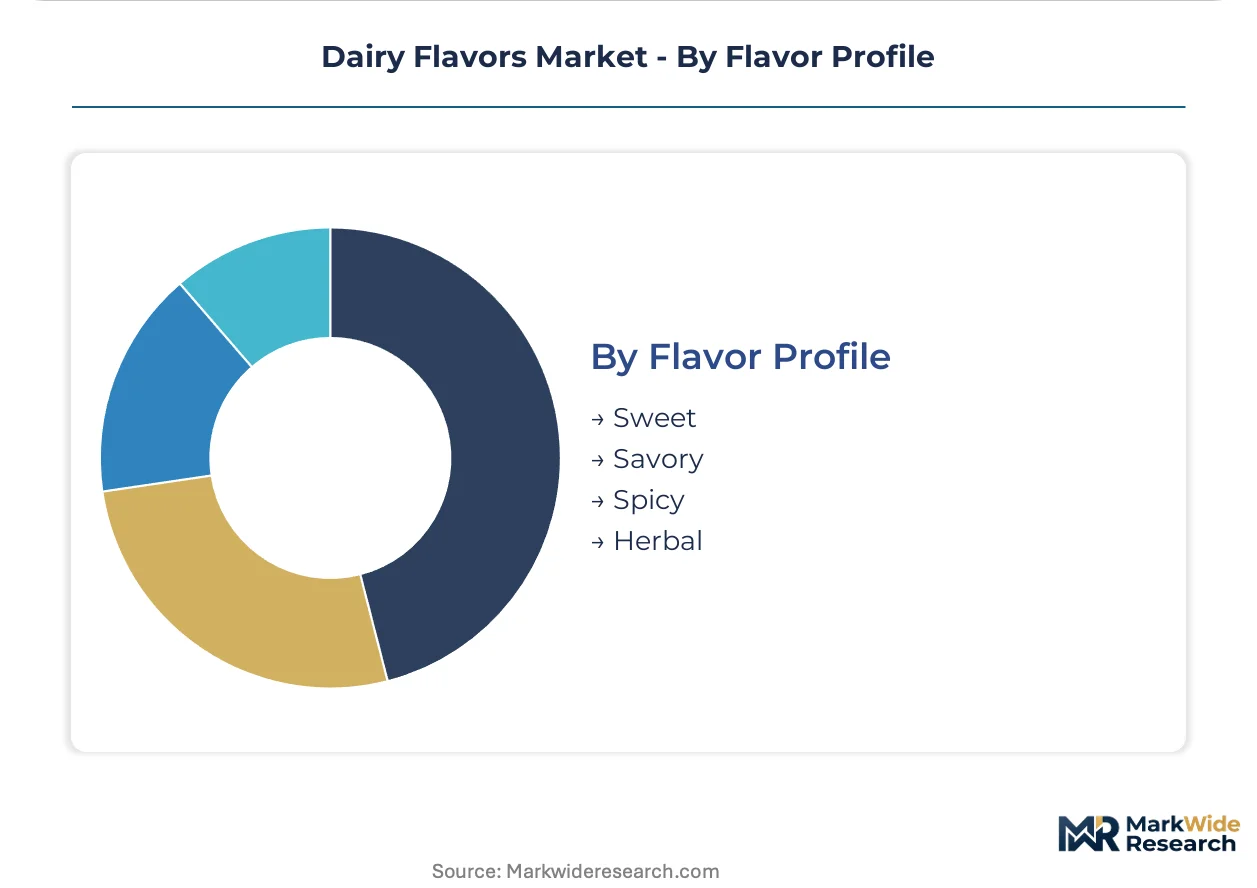
Flavor Profile:
Sweet and savory categories absorb technical investment while spicy and herbal profiles remain niche applications with limited supplier competition.
- Sweet:Lactose-derived caramelization and maltol enhancement replicate cooked milk and butterscotch notes for dessert applications.
- Savory:Umami peptide concentrates from enzyme-hydrolyzed casein deliver aged cheese depth without sodium load.
- Spicy:Pepper and chili oil emulsions in dairy bases serve ethnic sauce and dip formulations with limited standardization.
- Herbal:Dill, chive, and garlic compound flavors target cream cheese and sour cream applications with seasonal demand fluctuation.
Technical resources concentrate in savory. Emerging application growth is strongest in herbal profiles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wisconsin's dairy processing corridor anchors the global supply network for enzyme-modified cheese concentrates and cultured butter derivatives. The United States absorbs the largest share of premium flavor concentrates as CPG brands accelerate clean-label reformulation timelines. European regulatory pressure through EFSA's Flavouring Group Evaluation program is redrawing competitive access requirements across multiple jurisdictions.
United States
Clean-label mandates from the FDA under 21 CFR 101.22 are compressing synthetic flavor volumes as major yogurt and snack manufacturers specify documented natural dairy provenance. The agency's tightened distinction requirements between natural and artificial declarations extend new product introduction timelines by four to six months. Wisconsin and California dairy processing clusters concentrate enzymatic hydrolysis capacity for cheddar and cream cheese concentrates serving national food manufacturing networks.
Germany
Precision fermentation startups in Bavaria and Baden-Württemberg are commissioning bioreactor capacity for casein-derived flavor precursors as dairy protein alternatives gain formulation share. The EU Green Deal's Farm to Fork strategy mandates lifecycle assessment documentation for all novel flavor substances seeking EFSA safety clearance. Cologne and Hamburg harbor zones concentrate import logistics for whey permeates and milk solids feeding Central European flavor houses.
India
FSSAI alignment with Western clean-label standards is opening formulation service contracts for exporters targeting India's processed cheese and dessert segments. The regulator's emerging pathway for natural flavor certification creates first-mover positioning advantages for documented supply chain traceability. Maharashtra and Gujarat dairy cooperatives are expanding spray-drying capacity for standardized milk powders feeding regional flavor concentrate production.
Netherlands
EFSA's accelerated Flavouring Group Evaluation timelines are expanding the approved ingredient palette for Dutch flavor houses serving pan-European food manufacturing. The country's national food safety authority enforces strict enzymatic processing documentation under EU novel food regulations. Wageningen University research clusters anchor biotechnology partnerships for controlled microbial fermentation generating complex umami notes.
Denmark
Precision fermentation specialists in the Copenhagen-Arhus corridor are consolidating control over taste-active peptide sequences through commercial-scale bioreactor commissioning. Danish regulators enforce among Europe's most stringent sustainability documentation requirements for dairy-derived ingredients under national climate targets. Scandinavian flavor houses leverage regional enzyme engineering expertise to reduce production cycle times for concentrated butter and cheese notes.
Dairy Flavors Market Vendor Landscape
Capacity expansion dominates the current landscape as biotechnology-enabled production displaces traditional extraction methods across tier-one suppliers. The vendor base concentrates around integrated dairy processors with captive raw material supply, mid-sized regional specialists with enzymatic expertise, and precision fermentation entrants with bioreactor assets. Three strategic archetypes define positioning: upstream-integrated flavor houses controlling farm-to-flavor supply chains, biotechnology specialists leveraging enzyme-modified processing protocols, and regional taste profile experts tailoring formulations to local palates. M&A activity and direct-to-foodservice distribution partnerships represent the dominant competitive vectors reshaping channel relationships.
Among integrated dairy processors, Kerry Group and dsm-firmenich exemplify the upstream-control archetype through supply chain integration and biotechnology expertise respectively. Synergy Flavors occupies a specialist position within the regional-tailoring tier, focusing formulation development on European and North American taste preferences. These three entities represent divergent competitive vectors: captive raw material security, precision enzyme engineering capabilities, and palate-specific customization services.
| Leading Market Players |
|---|
| Edlong Corporation |
| Bluegrass Ingredients |
| Kerry Group |
| Jeneil Biotechnology |
| Butter Buds Inc. |
| International Flavors & Fragrances, Inc. |
| Synergy Flavors |
| dsm-firmenich |
| McCormick & Company, Inc. |
| Others |
Supply Flow & Price Mechanics
Flavor chemist concentration in Wisconsin and the Netherlands compresses labor-cost differentials into premium-to-economy pricing spreads across enzyme-modified concentrate tiers. Regional wage gaps between these specialized biotechnology corridors and emerging dairy processing zones in India widen formulation service premiums by certification grade.
Pricing Analysis
Input-cost pass-through from milk powder commodity volatility compresses margin predictability for flavor concentrate producers. Three-tier pricing structure across premium enzyme-modified, standard thermal-processed, and economy synthetic ester levels separates formulation complexity tiers. Price differentiation hinges on EFSA natural certification status and volume scale commitments from food manufacturers. Pricing pressure stems from skim milk solids cost swings, with retailers exhibiting highest price sensitivity versus national CPG brands prioritizing supply security.
Supply Chain Analysis
Single-source vulnerability sits with Wisconsin and Netherlands dairy processing clusters that anchor global enzyme-modified concentrate production. Raw material sourcing draws from United States, Netherlands, and India for standardized milk powders and whey permeates. Supply chain risk centers on regional climate disruption exposure across these dual geographies. Distribution runs through traditional ingredient distributors facing disintermediation pressure from direct-to-foodservice channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in premium enzyme-modified tiers as precision fermentation reduces production cycle costs. Biotechnology-enabled flavor houses capture formulation service premiums through documented EFSA compliance and clean-label certification.
For Market Incumbents: Extend captive raw material security through backward integration into regional dairy cooperatives in Maharashtra and Gujarat. Lock in multi-year offtake agreements with precision fermentation startups before bioreactor capacity tightens. Certification investment in ISO 22000 multi-site audits defends distributor relationships against direct-to-foodservice disintermediation.
For New Entrants and Emerging Players: Launch via direct technical partnerships with ghost kitchen operators and regional restaurant chains bypassing consolidated distributors. White-space concentration sits in fermented flavor precursors for plant-based dairy alternatives where established houses lack microbial fermentation expertise. Target India's processed cheese segment through FSSAI clean-label pathway alignment with documented supply chain traceability.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized regional specialists with enzymatic processing protocols but limited traceability infrastructure. Long-term viability favors precision fermentation assets with commercial-scale bioreactor commissioning and taste-active peptide IP. The signal to watch is EFSA Flavouring Group Evaluation acceleration timelines expanding approved ingredient palettes for biotechnology-enabled entrants.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Bioreactor commissioning in Denmark and California consolidates control over casein-derived flavor precursors without animal agriculture. |
| Direct-to-Foodservice Distribution | Bypassing traditional ingredient distributors builds captive relationships with restaurant chains and ghost kitchen operators. |
| EFSA Clean-Label Certification | Lifecycle assessment documentation under EU Green Deal Farm to Fork strategy secures branded food manufacturer approved vendor status. |
| Backward Integration into Dairy Cooperatives | Captive supply of standardized milk powders from Wisconsin and Netherlands clusters insulates against commodity volatility. |
| Regional Taste Profile Specialization | Tailored formulation development for European and North American palates captures premium positioning in dessert and bakery segments. |
Methodological Framework
Bottom-up food manufacturer demand modeling reconciled against top-down dairy processing capacity tracking forms the analytical core of this study. Primary interviews with flavor chemists, procurement leads at CPG brands, regulatory affairs specialists, and dairy cooperative managers combined with secondary validation from FDA 21 CFR filings, EFSA Flavouring Group Evaluation databases, EU Green Deal documentation, and trade data from dairy processing associations. Triangulation between supply-side capacity announcements and end-use procurement patterns ensures consistency across volume estimates.
Input-output matrix framing connects enzymatic hydrolysis capacity by product type to downstream application demand across yogurt, cheese spread, dessert, and sauce segments. Segmentation dimensions modeled include flavor profile, end-user archetype, and regional regulatory cluster across the projection horizon. CAGRs derive from elasticity-adjusted demand curves incorporating clean-label substitution rates and precision fermentation adoption timelines. Forecast inputs include EFSA evaluation timelines and FSSAI regulatory alignment progress.
Several conditions sit outside the modeled scope, including abrupt FDA labeling requirement changes, precision fermentation regulatory reclassification, and extreme milk powder commodity price shocks. Forecasts reflect documented assumptions about biotechnology adoption curves and clean-label certification penetration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
US Flavors Market
Flavorings and Food Additives
Feed Flavors and Sweeteners Market
Flavorings and Food Additives
Quillaia Extracts Market
Flavorings and Food Additives
Asia-Pacific Food Flavor Market
Flavorings and Food Additives
China Food Flavor and Enhancer Market
Flavorings and Food Additives
Flavoring Agents Market
Flavorings and Food Additives
North America Licorice Extract Market
Flavorings and Food Additives
Shelf-Stable Mezze Fermentation Ingredient Systems Market
Flavorings and Food Additives
Europe Food Flavor Market
Flavorings and Food Additives
Oil Soluble Flavors Market
Flavorings and Food Additives
Savory Extract Market
Flavorings and Food Additives
Nature Identical Flavorings Market
Flavorings and Food Additives
Mandarin Oil Market
Flavorings and Food Additives
Ginkgo Biloba Extract Market
Flavorings and Food Additives
Chokeberry Extract Market
Flavorings and Food Additives
Carotenoids Pigment Market