
 North America Protein Market | 2026-2036
North America Protein Market Size, Share, and Industry Trends Forecast 2026-2036
North America Protein Market Analytics
Modular protein dosing formats are restructuring how buyers configure their nutrition regimens across powder, bar, and capsule combinations. Cargill Incorporated leverages its North American agricultural supply base to secure consistent soy and pea protein feedstock volumes. Kerry Group PLC differentiates through flavor-masked protein systems that expand palatability in plant-based applications. Glanbia PLC dominates whey protein isolate production through its Idaho and Wisconsin processing infrastructure.
North America protein encompasses amino acid chains derived from dairy, legume, and oilseed sources, typically processed through enzymatic hydrolysis or mechanical fractionation to achieve protein concentrations between 80% and 95% by dry weight, serving primarily as macronutrient fortification in consumer packaged goods and clinical nutrition. Whey protein occupies the largest revenue pool due to its complete amino acid profile and established sports nutrition demand, while pea protein generates the fastest growth trajectory as food manufacturers reformulate to meet clean-label expectations. Powder form commands manufacturing scale advantages, though bar format captures premium shelf positioning in convenience retail channels.
USDA oversees protein content verification in meat and dairy derivatives, while FDA governs structure-function claims in nutritional supplements under DSHEA, and both frameworks push suppliers toward analytical testing investments. Health Canada and PMRA coordinate cross-border allergen labeling standards that affect import compliance for U.S. exporters. Stakeholders must monitor evolving positions on novel protein sources such as precision-fermented ingredients across federal and provincial regulatory dockets.
Market Dynamics
Sports nutrition procurement has concentrated purchasing power among a handful of brands, forcing ingredient suppliers to reconfigure production schedules around bulk isolate contracts rather than diversified portfolios.
Growth Catalysts
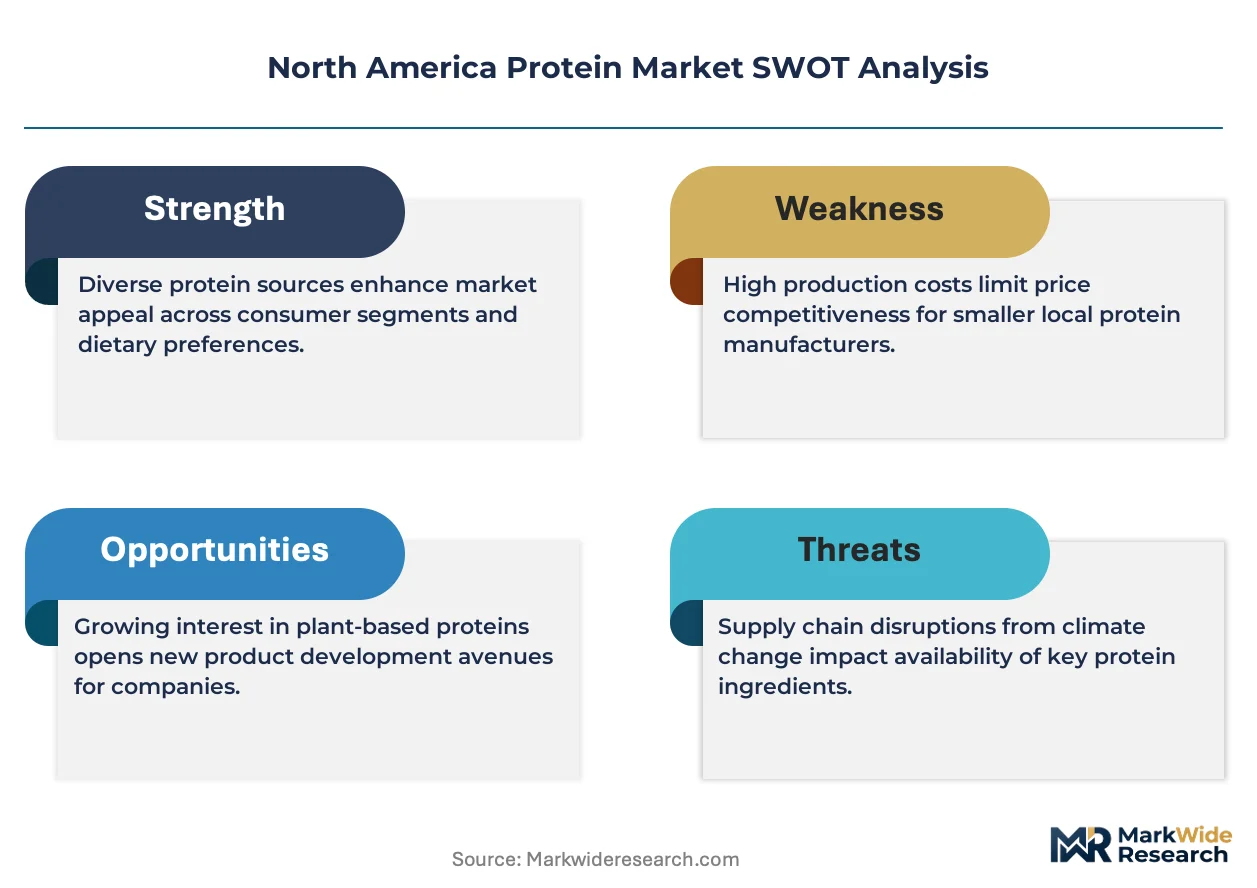
- USDA Protein Content Verification Mandates:Federal labeling requirements for meat and dairy derivatives compel manufacturers to invest in analytical testing infrastructure, raising barriers for non-compliant imports and consolidating demand toward certified domestic suppliers.
- Precision Fermentation Infrastructure:Novel protein production platforms utilizing microbial hosts are attracting venture deployment in California's functional food corridor, creating alternative supply pathways beyond traditional agriculture.
- Texas Sports Nutrition Manufacturing Cluster:Concentrated contract manufacturing capacity in the Dallas-Fort Worth metroplex enables rapid formulation-to-shelf cycles for emerging brands seeking turnkey production partnerships.
Market Restraints
- Dairy Input Cost Volatility:Whey protein isolate production remains tethered to fluid milk commodity cycles, with Idaho and Wisconsin processing margins compressing during feed price spikes.
- Cross-Border Allergen Labeling Friction:Health Canada and PMRA coordinate standards that diverge from FDA thresholds, creating compliance duplication for U.S. exporters serving Canadian sports nutrition channels.
- Plant Protein Functionality Ceiling:Pea protein isolate exhibits solubility and emulsion limitations in high-moisture applications, constraining clean-label reformulation in ready-to-drink beverage categories.
Strategic Opportunities
- Mexico Underpenetrated Functional Food Channel:Convenience retail and pharmacy distribution for protein-fortified products remains fragmented relative to U.S. density, offering first-mover positioning in urban centers.
- DSHEA Structure-Function Claim Pathways:FDA's existing framework for nutritional supplements enables clinical positioning of protein isolates for recovery applications with substantiation investments.
- Modular Dosing Format Convergence:Powder-bar-capsule combination regimens are creating subscription-based direct-to-consumer platforms that bypass traditional retail slotting constraints.
Industry Challenges
- Third-Party Certification Timeline Compression:NSF International and Informed Sport verification queues extend 4-6 months, delaying product launches for brands targeting collegiate and professional athletic procurement.
- Flavor-Masked Protein System Integration:Masking off-notes in high-loading plant protein applications requires reformulation cycles that strain R&D bandwidth at mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Protein Market |
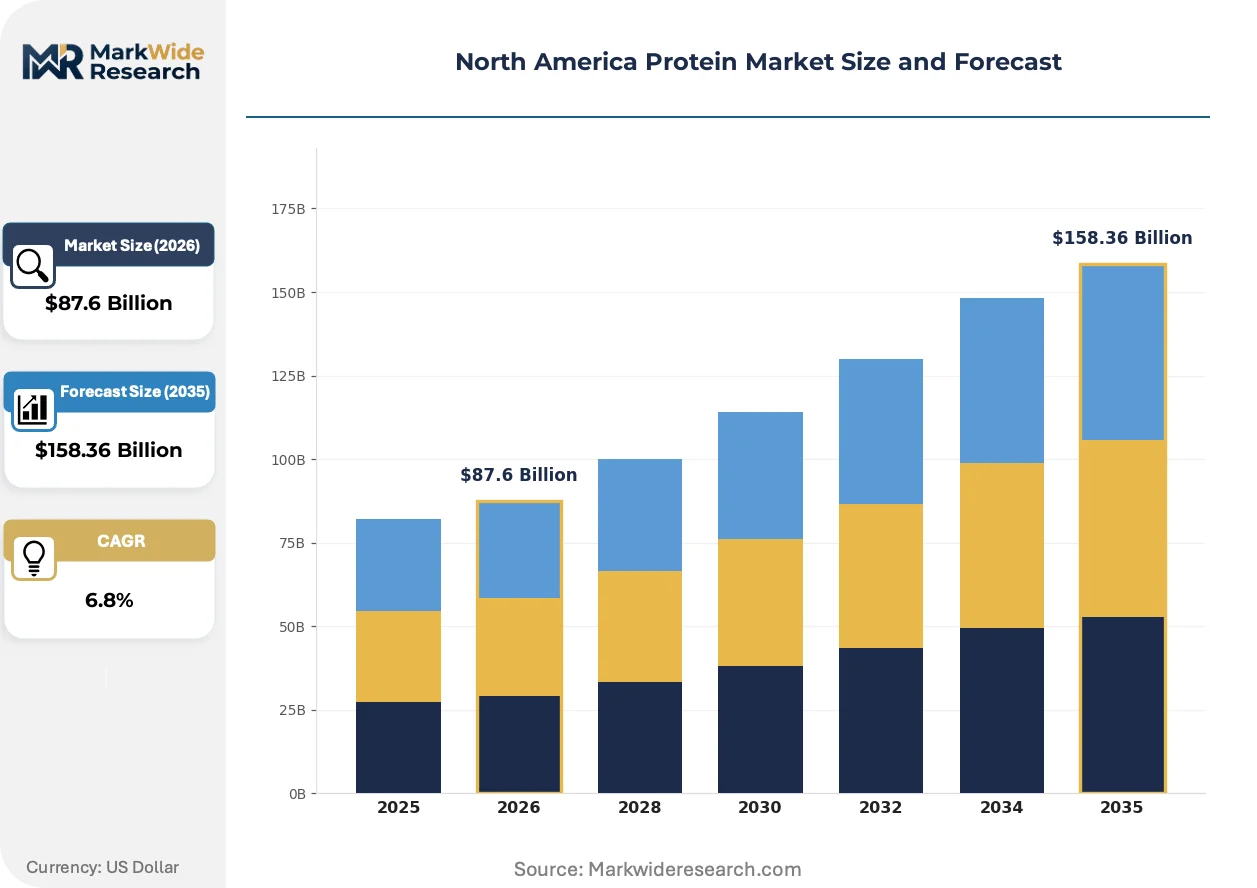
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein Protein, Soy Protein, Pea Protein End User: Health Clubs, Nutritional Supplements, Food Industry, Sports Nutrition Form: Powder, Bar, Liquid, Capsule Distribution Channel: Online Retail, Supermarkets, Fitness Centers, Health Stores |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Bunge Limited, Kerry Group PLC, Roquette Frères, CHS Inc, International Flavors & Fragrances Inc, Glanbia PLC, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Protein Market Evolving Landscape
Enzymatic processing advances and regulatory positioning strategies are redefining competitive advantage in protein ingredient supply. Manufacturers now compete on bioavailability claims and clean-label credentials rather than commodity pricing alone.
Precision fermentation-derived whey proteins are expanding into sports nutrition formulations previously reserved for dairy-isolate supply chains. Early-adopter brands in California's functional food corridor are piloting these ingredients for sustainability narrative differentiation. This technology is expanding into premium positioning tiers where conventional supply chain traceability carries reputational risk.
FDA's evolving enforcement posture on structure-function claims under DSHEA is tightening substantiation requirements for recovery and performance positioning. Manufacturers must now maintain clinical trial documentation or face warning letter exposure. Sports nutrition brands targeting collegiate athletic programs are most affected, with several reformulating claims to stay within general wellness safe harbors.
Direct-to-consumer subscription models are displacing traditional retail replenishment cycles for protein powder purchasers. Specialty e-commerce platforms offer personalized dosing configurations and flavor rotation programs that brick-and-mortar cannot replicate. This shift concentrates most visibly in Texas and California metropolitan markets where delivery logistics density supports next-day fulfillment guarantees.
North America Protein Market Segmentation
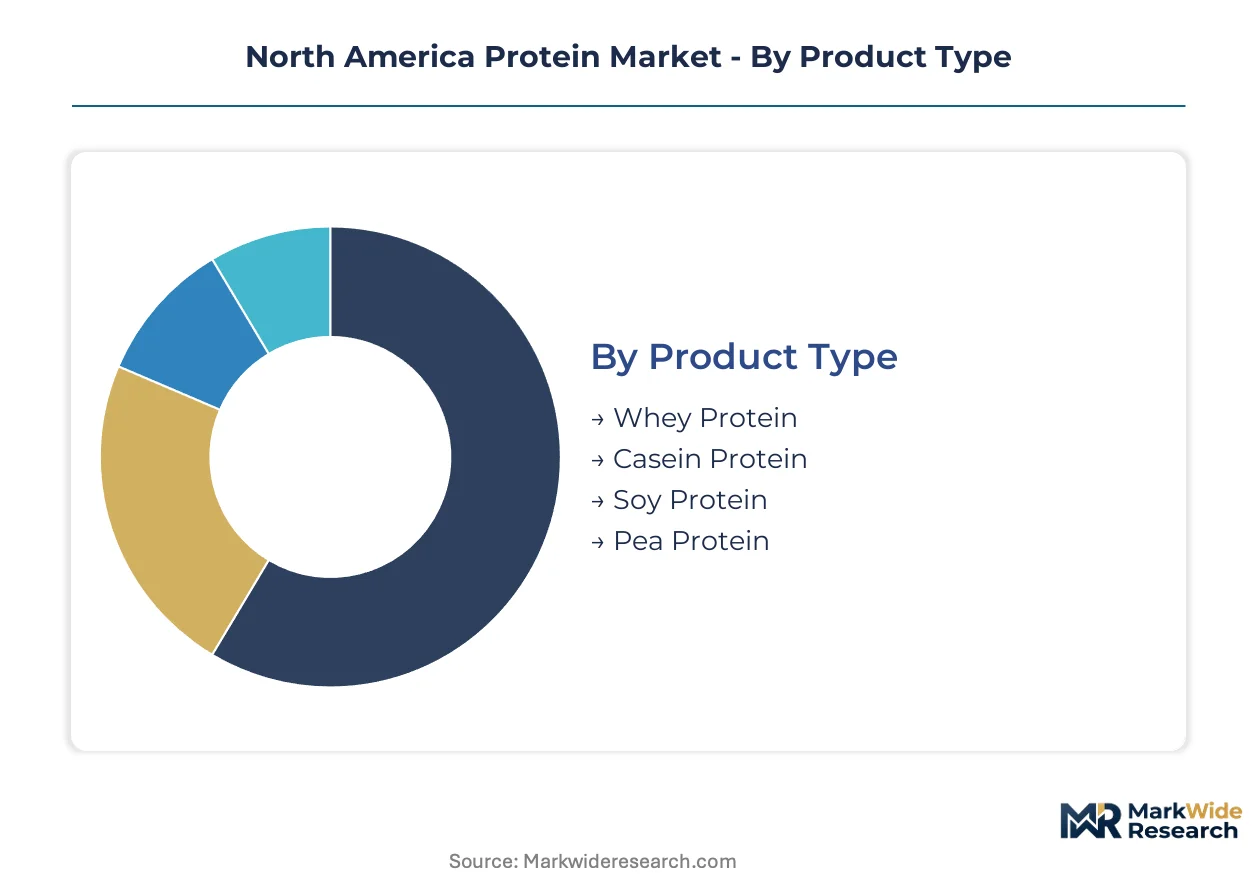
Protein procurement decisions in North America hinge on functional specifications, regulatory positioning, and channel economics. Buyers configure portfolios across dairy-derived and plant-based inputs based on amino acid completeness, allergen profile, and clean-label credentials.
Product Type:
Buyers prioritize amino acid completeness and digestibility scores when selecting protein sources for formulation.
- Whey Protein:Complete amino acid profile with rapid absorption kinetics drives sports nutrition procurement. Demand concentrates in Texas sports nutrition manufacturing hubs where isolate-grade specifications dominate bulk contracting.
- Pea Protein:Hypoallergenic positioning and sustainable cultivation narrative attract clean-label reformulators. California's functional food corridor leads adoption as brands seek dairy-free alternatives with substantiated environmental claims.
- Casein Protein:Slow-release kinetics suit overnight recovery applications in clinical nutrition segments.
- Soy Protein:Cost-efficient complete protein serves food industry fortification with established GRAS status.
Volume sits with whey protein; growth tilts toward pea protein.
End User:
Application-specific performance requirements determine protein specification and certification investment.
- Sports Nutrition:NSF International and Informed Sport verification requirements drive isolate-grade procurement from Idaho and Wisconsin processing infrastructure. Collegiate athletic programs mandate third-party certification, compressing supplier qualification timelines.
- Food Industry:Clean-label reformulation pressures push manufacturers toward plant-based isolates with neutral flavor profiles. Bakery and snack applications demand heat-stable emulsion properties.
- Nutritional Supplements:FDA DSHEA structure-function claim substantiation requires clinical documentation for recovery positioning.
- Health Clubs:On-site retail captures impulse replenishment with single-serve powder sachets and ready-to-drink formats.
Revenue concentrates in sports nutrition; reformulation momentum favors food industry applications.
Form:
Manufacturing scale and margin structure vary sharply across delivery formats.
- Powder:Bulk production economies and flexible dosing support subscription direct-to-consumer models. Texas and California metropolitan markets sustain next-day fulfillment density for personalized flavor rotation programs.
- Bar:Premium shelf positioning in convenience retail commands higher per-unit margins despite complex extrusion and coating requirements.
- Liquid:Aseptic processing investments limit supplier pool for ready-to-drink protein beverages.
- Capsule:Encapsulation throughput suits amino acid isolates and collagen peptides in clinical nutrition.
Scale advantages accumulate in powder; margin expansion targets bar formats.
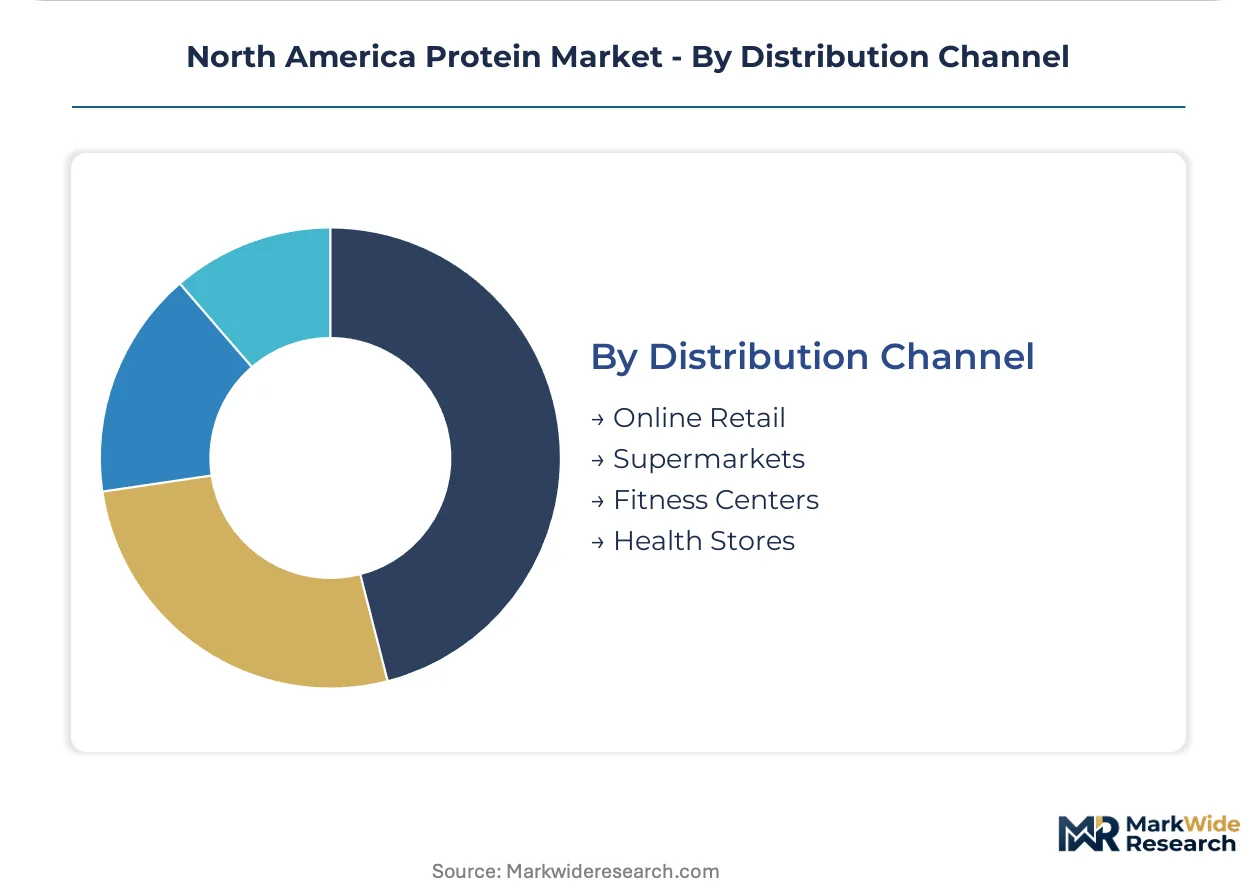
Distribution Channel:
Channel selection determines brand control, margin retention, and consumer data access.
- Online Retail:Direct-to-consumer platforms bypass slotting fees and enable subscription-based replenishment cycles. Specialty e-commerce operators offer modular dosing configurations unavailable through brick-and-mortar.
- Supermarkets:Mass-market penetration requires trade promotion investment and retailer-specific packaging formats.
- Health Stores:Educated staff and sampling programs support premium positioning for novel protein sources.
- Fitness Centers:Proximity to consumption occasion drives impulse purchase velocity for single-serve formats.
Customer acquisition costs favor online retail; trial conversion rates peak in health stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in the United States while consumption patterns distribute across all three North American economies. Canada supplies raw agricultural inputs and precision fermentation research infrastructure. Mexico presents underdeveloped functional food channels with concentrated urban demand pockets.
United States
Texas hosts the dominant sports nutrition manufacturing cluster in the Dallas-Fort Worth metroplex, enabling rapid formulation-to-shelf cycles for emerging brands. FDA DSHEA structure-function claim enforcement tightens substantiation requirements for recovery positioning. Idaho and Wisconsin processing infrastructure anchors whey protein isolate production for bulk isolate contracts.
California
The functional food corridor drives adoption of precision fermentation-derived proteins and clean-label plant-based alternatives. USDA protein content verification mandates compel analytical testing investments from manufacturers seeking federal compliance. Venture deployment in microbial host platforms creates alternative supply pathways beyond traditional agricultural sourcing.
Texas
Contract manufacturing density supports turnkey production partnerships for direct-to-consumer subscription brands. State-level agricultural policy maintains competitive feedstock access for dairy-derived protein processors. Metropolitan delivery logistics density sustains next-day fulfillment guarantees for personalized flavor rotation programs.
Canada
Health Canada and PMRA coordinate cross-border allergen labeling standards that create compliance friction for U.S. exporters. Prairie agricultural regions supply consistent soy and pea protein feedstock volumes to North American processors. Ontario and Quebec concentrate clinical nutrition research institutions driving casein protein applications.
Mexico
Urban centers in Mexico City and Guadalajara present fragmented convenience retail and pharmacy distribution for protein-fortified products. The country's national food safety regulator maintains evolving standards for novel protein source approval. Northern border states facilitate cross-border manufacturing partnerships serving U.S. sports nutrition brands seeking cost-advantaged production.
North America Protein Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across ingredient supply and finished product manufacturing. The vendor base organizes around three strategic archetypes: agricultural processors with captive raw material access, flavor and formulation technology providers, and dairy cooperative-backed protein isolators. Capacity expansion and portfolio diversification represent the dominant competitive moves as players respond to clean-label reformulation pressures and sports nutrition procurement consolidation.
Within the agricultural processing tier, Cargill Incorporated and Archer Daniels Midland Company exemplify scale-driven feedstock security models. Kerry Group PLC occupies a position among formulation technology specialists, while Glanbia PLC anchors the dairy-derived isolate segment. These three entities collectively represent the structural spectrum from upstream agricultural control through downstream application expertise.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Bunge Limited |
| Kerry Group PLC |
| Roquette Frères |
| CHS Inc |
| International Flavors & Fragrances Inc |
| Glanbia PLC |
| Ingredion Incorporated |
| Others |
Value Network & Pricing Analysis
Captive whey protein isolate production in Idaho and Wisconsin anchors pricing power for dairy-derived suppliers, while outsourced pea protein sourcing from prairie agricultural regions exposes manufacturers to commodity volatility and margin compression. This integration divergence separates bulk isolate contract holders from clean-label reformulators competing on certification tier rather than volume scale.
Pricing Analysis
Margin tightening in isolate-grade whey reflects fluid milk commodity cycles tethering processing economics to feed price spikes. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and amino acid completeness, with NSF International verification commanding substantial premia. Cost-down pressure on plant-based isolates accelerates because solubility limitations in high-moisture applications force reformulation investments. Sports nutrition brands exhibit lowest price sensitivity due to third-party certification mandates, while food industry fortification buyers prioritize cost efficiency.
Supply Chain Analysis
Dual-sourcing requirements from collegiate athletic programs and major sports nutrition brands mandate multi-supplier qualification across Idaho, Wisconsin, and California processing infrastructure. Raw material dependencies center on fluid milk volumes, prairie-grown yellow peas, and soybeans from Midwest agricultural regions. Single-source vulnerability concentrates in precision fermentation platforms where California's functional food corridor hosts nascent microbial host production. Distribution runs through direct-to-consumer subscription platforms in Texas and California metropolitan markets, bypassing traditional retail slotting fees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive dairy processing infrastructure determines isolate supply security and pricing power. Players pursue upstream control over fluid milk volumes and downstream direct-to-consumer channel ownership as decisive competitive levers.
For Market Incumbents: Deepen captive whey protein isolate capacity in Idaho and Wisconsin to defend against precision fermentation substitutes eroding dairy-derived market share. Accelerate third-party certification queue management through dedicated NSF International and Informed Sport relationship investment, compressing supplier qualification timelines that currently extend 4-6 months. For New Entrants and Emerging Players: FDA's DSHEA structure-function claim framework in the United States opens a window for clinical positioning of novel protein isolates with substantiation investments in recovery applications. Target Mexico's fragmented convenience retail and pharmacy distribution in Mexico City and Guadalajara, deploying turnkey production partnerships through Texas contract manufacturing clusters as the go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by agricultural conglomerates seeking flavor-masked protein system technology or precision fermentation infrastructure. Long-term viability favors vertically integrated processors with captive raw material access and established third-party certification relationships. Watch precision fermentation scale-up timelines as the inflection indicator for dairy-isolate substitution risk.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | California venture deployment in microbial host platforms creates alternative supply pathways beyond traditional agriculture. |
| Third-Party Certification Investment | NSF International and Informed Sport verification reduces collegiate athletic procurement qualification timelines. |
| Direct-to-Consumer Channel Buildout | Texas and California subscription platforms bypass retail slotting fees and capture consumer data for personalized dosing. |
| Flavor-Masked Protein System Development | Kerry Group PLC's technology expands palatability in high-loading plant protein applications for clean-label reformulation. |
| Mexico Distribution Partnership | Urban center convenience retail expansion captures first-mover positioning in underpenetrated functional food channels. |
Research Methodology
USDA protein content verification databases, FDA DSHEA structure-function claim filings, and Health Canada allergen labeling standards formed the secondary backbone for regulatory positioning analysis. Primary interviews with sports nutrition brand procurement directors, whey protein isolate plant managers in Idaho and Wisconsin, and California precision fermentation venture capitalists validated supply chain concentration patterns. Bottom-up volume modeling from individual processing facility capacities combined with top-down trade flow analysis across North American customs data for triangulation.
Bottom-up segmentation modeling tracked whey protein, pea protein, casein protein, and soy protein volumes by powder, bar, liquid, and capsule formats across sports nutrition, food industry, nutritional supplements, and health club end uses. CAGRs were derived from historical trajectory analysis and forward projection of precision fermentation adoption curves, fluid milk commodity cycles, and clean-label reformulation momentum in bakery and snack applications.
The model assumes a particular technology adoption path for precision fermentation-derived proteins; alternative pathways for microbial host platform scale-up would alter the outlook for dairy-isolate demand trajectories. Deviation in FDA enforcement posture on DSHEA substantiation requirements or feed price spike severity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Bovine Lactoferrin Market
Nutritional Supplements
Ferrous Fumarate Market
Nutritional Supplements
Krill Oil Market
Nutritional Supplements
Conjugated Linoleic Acid Market
Nutritional Supplements
Micellar Casein Market
Nutritional Supplements
Food Grade Beta-Alanine Market
Nutritional Supplements
Dietary Supplements Market
Nutritional Supplements
Astragalus Propinquus Market
Nutritional Supplements
Testosterone Booster Supplements Market
Nutritional Supplements
Arabinogalactan Powder Market
Nutritional Supplements
Europe Collagen Peptides Market
Nutritional Supplements
Spirulina Extract Market
Nutritional Supplements
Global Ashwagandha Extract Market
Nutritional Supplements
Indonesia Beauty Supplements Market
Nutritional Supplements
Global Reishi Mushroom Extracts Market
Nutritional Supplements
Isoleucine Market