
 Australia Food Enzymes Market | 2026-2036
Australia Food Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Food Enzymes Market Outlook
Ingredient formulation services is rewriting margin distribution across the value chain. Novozymes leverages its global strain development platform to supply tailored amylase blends to Australian millers. Kerry Group anchors its position through captive bakery application labs in Melbourne and Sydney. DSM competes on thermostable protease portfolios designed for UHT dairy streams.
Food enzymes comprise proteinaceous biocatalysts, typically operating at temperatures between 30°C and 60°C and pH ranges of 4.0 to 8.0, that accelerate specific biochemical reactions in raw and processed food matrices without becoming consumed in the reaction. These catalysts reduce processing time, improve yield recovery, and enable cleaner label declarations by replacing chemical additives. Amylase dominates volume throughput in beverage processing and bakery applications where starch liquefaction determines production efficiency. Lipase exhibits the fastest expansion in dairy products, particularly for flavor development in specialty cheese and reduced-fat formulations where fat modification replaces hydrogenation. Powder form retains the largest share among enzyme deliveries due to extended shelf stability and freight economics, though liquid concentrates gain traction in high-throughput beverage lines where dosing precision matters.
Food Standards Australia New Zealand (FSANZ) governs enzyme permissibility through the Australia New Zealand Food Standards Code, while the Therapeutic Goods Administration (TGA) intersects where enzyme products blur into nutraceutical claims. FSANZ processing aid classifications determine whether enzyme residues trigger mandatory label disclosure, directly steering manufacturer preference toward GRAS-listed or approved biocatalysts. The Australian Competition and Consumer Commission (ACCC) monitors anti-competitive conduct in enzyme supply agreements, particularly where sole-source contracts lock small bakeries into inflexible pricing. Stakeholders must track FSANZ proposal drafts on novel enzyme sources and assess how TGA border determinations affect imported enzyme formulations with dual-use positioning.
Market Dynamics
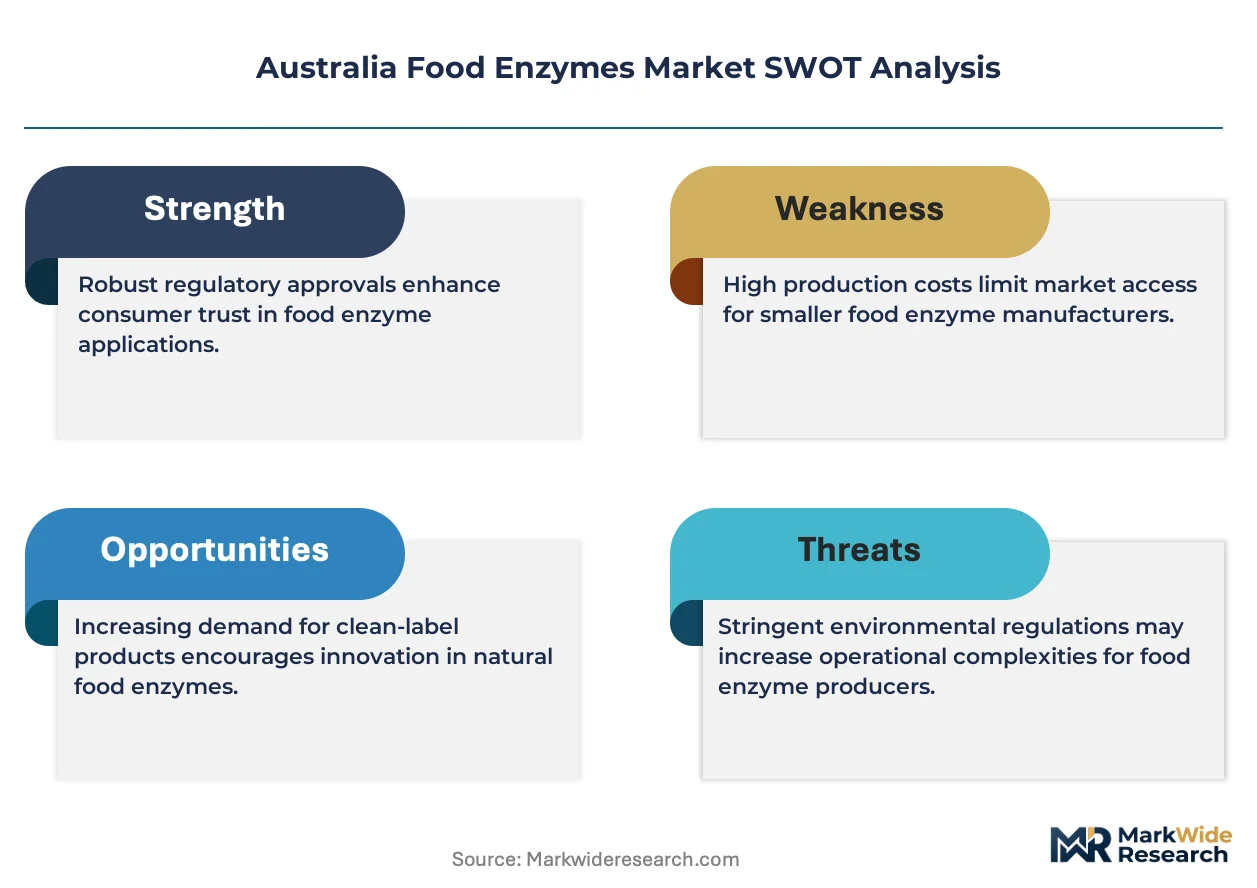
FSANZ processing aid classifications are compressing additive declarations across Australian bakery and dairy manufacturing, redirecting formulation budgets toward biocatalyst solutions that bypass mandatory label disclosure requirements.
Growth Catalysts
- FSANZ Code Processing Aid Exemptions:Enzyme residues classified as processing aids eliminate mandatory label declarations, steering manufacturers toward biocatalyst substitution for chemical additives in clean-label product lines.
- Victoria-New South Wales Manufacturing Clusters:Concentrated baking and dairy processing infrastructure in these states generates localized demand density for tailored enzyme formulations and technical service proximity.
- Thermostable Protease Advances:Next-generation heat-stable biocatalysts enable UHT dairy stream processing without thermal degradation, expanding enzyme applicability in extended-shelf-life milk production.
Market Restraints
- Strain Development Cost Concentration:Proprietary microbial strain platforms remain controlled by a narrow supplier base, limiting Australian manufacturers' bargaining leverage on amylase and lipase pricing.
- TGA Border Determination Uncertainty:Dual-use enzyme formulations with nutraceutical positioning face unpredictable classification reviews, delaying import clearance and commercialization timelines.
- Protein Input Volatility:Fermentation feedstock costs for industrial enzyme production fluctuate with agricultural commodity cycles, compressing margin stability for domestic distributors.
Strategic Opportunities
- Western Australia Dairy Expansion:Emerging specialty cheese production in the state's southwest corridor presents underpenetrated territory for lipase-based flavor development systems.
- ACCC Anti-Competitive Monitoring:Regulatory scrutiny of sole-source supply contracts creates openings for alternative enzyme suppliers to displace incumbent lock-in arrangements among regional bakeries.
- Liquid Concentrate Dosing Systems:High-throughput beverage lines in Queensland are adopting precision liquid enzyme delivery, displacing powder handling infrastructure and opening technical service revenue streams.
Industry Challenges
- Fermentation Bioprocess Engineering Talent:Shortage of specialized technicians for industrial-scale biocatalyst production limits domestic manufacturing expansion and strains technical support capacity.
- Novel Enzyme Source Approval Timelines:FSANZ proposal drafts on emerging microbial strains create regulatory lag, extending time-to-market for next-generation formulations by 18-24 months.
- Legacy Powder Handling Infrastructure:Bakeries with sunk capital in dry-blend systems face integration friction when transitioning to liquid concentrate dosing platforms requiring line reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Food Enzymes Market |
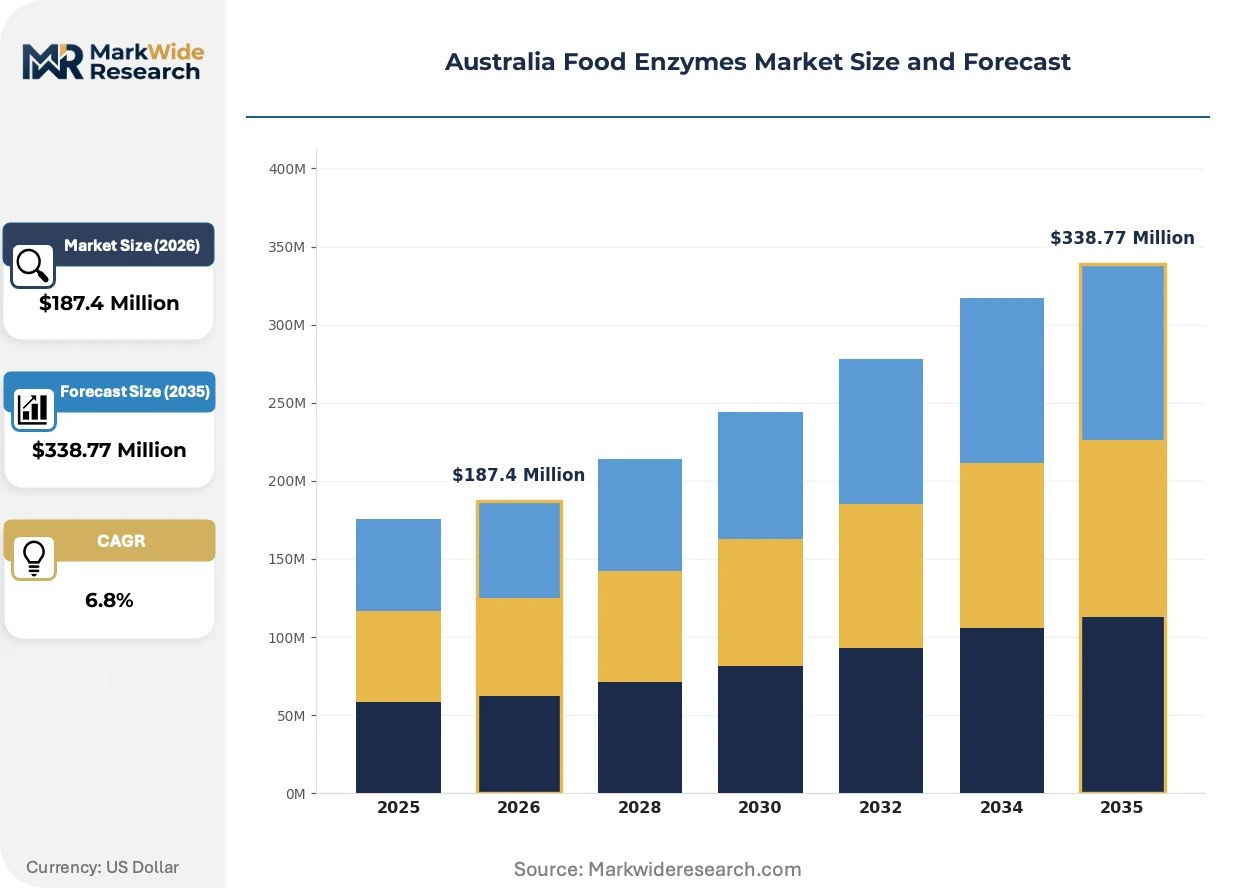
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Enzyme Type: Amylase, Protease, Lipase, Cellulase Application: Beverage Processing, Dairy Products, Bakery, Confectionery Form: Liquid, Powder, Granulate, Tablets End User: Food Manufacturers, Beverage Producers, Ingredient Suppliers, Restaurants |
| Companies Covered | Novozymes, Biocatalyst Ltd, Puratos Group, Chr. Hansen Holding A/S, AB Enzymes, Deltagen, Kerry Group, DSM, DuPont de Nemours Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Food Enzymes Market Strategic Shifts
Biocatalyst engineering and regulatory classification frameworks are converging to reshape how Australian food manufacturers approach ingredient declarations and process efficiency targets.
Precision fermentation-derived enzymes are collapsing cost structures for specialty lipase production. Artisan cheese makers in Tasmania and Victoria are adopting these biocatalysts at accelerating rates. The technology is collapsing the price premium that previously separated commodity dairy processing from specialty flavor development applications.
FSANZ proposal drafts on novel enzyme sources are tightening pre-market safety assessment requirements. Industrial users must now submit extended toxicological data packages for microbial strains not previously approved in the Australia New Zealand Food Standards Code. Small-to-mid-sized enzyme distributors serving regional bakeries face disproportionate compliance burden relative to global suppliers with established regulatory affairs infrastructure.
Clean-label certification programs are redirecting procurement evaluation criteria toward additive-free positioning. Major Australian retail chains are tightening supplier qualification standards, displacing chemical leavening and emulsifier systems with enzyme-based alternatives in private-label bakery lines. This pattern concentrates most visibly in Melbourne and Sydney metropolitan manufacturing zones where retail concentration enables rapid specification cascading through contract bakeries.
Australia Food Enzymes Market Segmentation
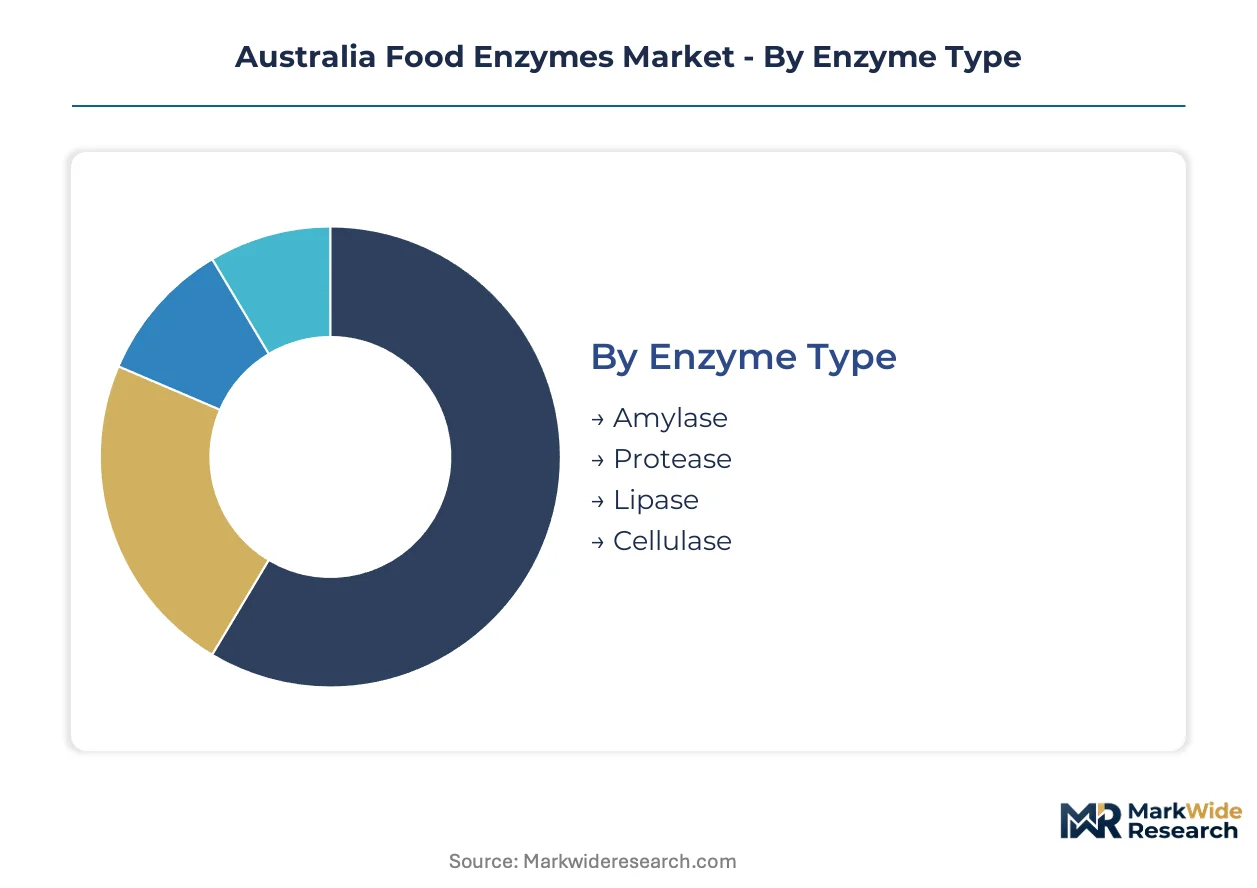
Enzyme selection in Australian food manufacturing hinges on process temperature profiles, label declaration requirements under FSANZ processing aid classifications, and existing handling infrastructure. Segmentation reveals how formulation priorities diverge across Victoria's baking clusters versus Queensland's beverage corridors.
Enzyme Type:
Biocatalyst selection spans starch modification, protein hydrolysis, fat restructuring, and fiber breakdown applications across Australian food processing.
- Amylase:Catalytic proteins targeting alpha-1,4-glycosidic bonds in starch polymers, operating optimally between 50°C and 70°C with calcium ion cofactor requirements. Victorian millers and Sydney contract bakeries absorb rising volumes for dough conditioning and anti-staling applications where FSANZ processing aid exemptions eliminate additive label declarations.
- Lipase:Triacylglycerol hydrolases enabling position-specific fat modification and flavor ester generation in controlled moisture environments. Southwest Western Australia specialty cheese producers and reduced-fat dairy formulators in New South Wales are accelerating procurement as precision fermentation collapses production cost premiums.
- Protease:Peptide bond cleavage biocatalysts classified by endo- or exo-activity patterns and pH optima.
- Cellulase:Complex enzyme systems degrading beta-1,4-glucan linkages in plant cell wall matrices.
The dominant share belongs to amylase, while lipase is closing the gap fastest.
Application:
End-use concentration tracks manufacturing infrastructure density across Australian states.
- Beverage Processing:Starch liquefaction and juice clarification operations in Queensland's high-throughput lines. Liquid concentrate dosing systems displace powder handling where precision matters.
- Dairy Products:UHT milk processing and specialty cheese flavor development. Thermostable protease advances enable extended-shelf-life production without thermal degradation.
- Bakery:Dough strengthening and crumb softening across Melbourne and Sydney metropolitan zones. Clean-label certification programs redirect procurement toward additive-free positioning.
- Confectionery:Invert sugar production and texture modification in sugar-confectionery manufacturing.
Bakery commands volume leadership, though beverage processing is expanding most quickly.
Form:
Physical delivery format selection reflects freight economics, shelf stability requirements, and dosing precision needs.
- Powder:Spray-dried or lyophilized enzyme preparations with extended ambient stability. Retains largest delivery share due to freight economics and established dry-blend infrastructure across regional bakeries.
- Liquid:Concentrated aqueous or glycerol-based formulations enabling precision dosing. Queensland beverage lines and high-throughput dairy processors adopt for automated injection systems requiring line reconfiguration investment.
- Granulate:Agglomerated particles reducing dust exposure and improving flow characteristics.
- Tablets:Compressed solid dosage forms for controlled-release or specific unit-dose applications.
Powder maintains installed base dominance, while liquid is gaining share fastest.
End User:
Customer type determines technical service intensity and contract structure preferences.
- Food Manufacturers:Integrated bakery and dairy processors with captive formulation capabilities. Victoria-New South Wales manufacturing clusters generate localized demand density for tailored technical service proximity.
- Beverage Producers:Juice, brewing, and soft drink operations requiring high-volume, consistent enzyme activity. Procurement concentrates in Queensland and New South Wales production corridors.
- Ingredient Suppliers:Distributors and premix blenders serving smaller manufacturing accounts.
- Restaurants:Limited direct procurement, primarily through prepared ingredient channels.
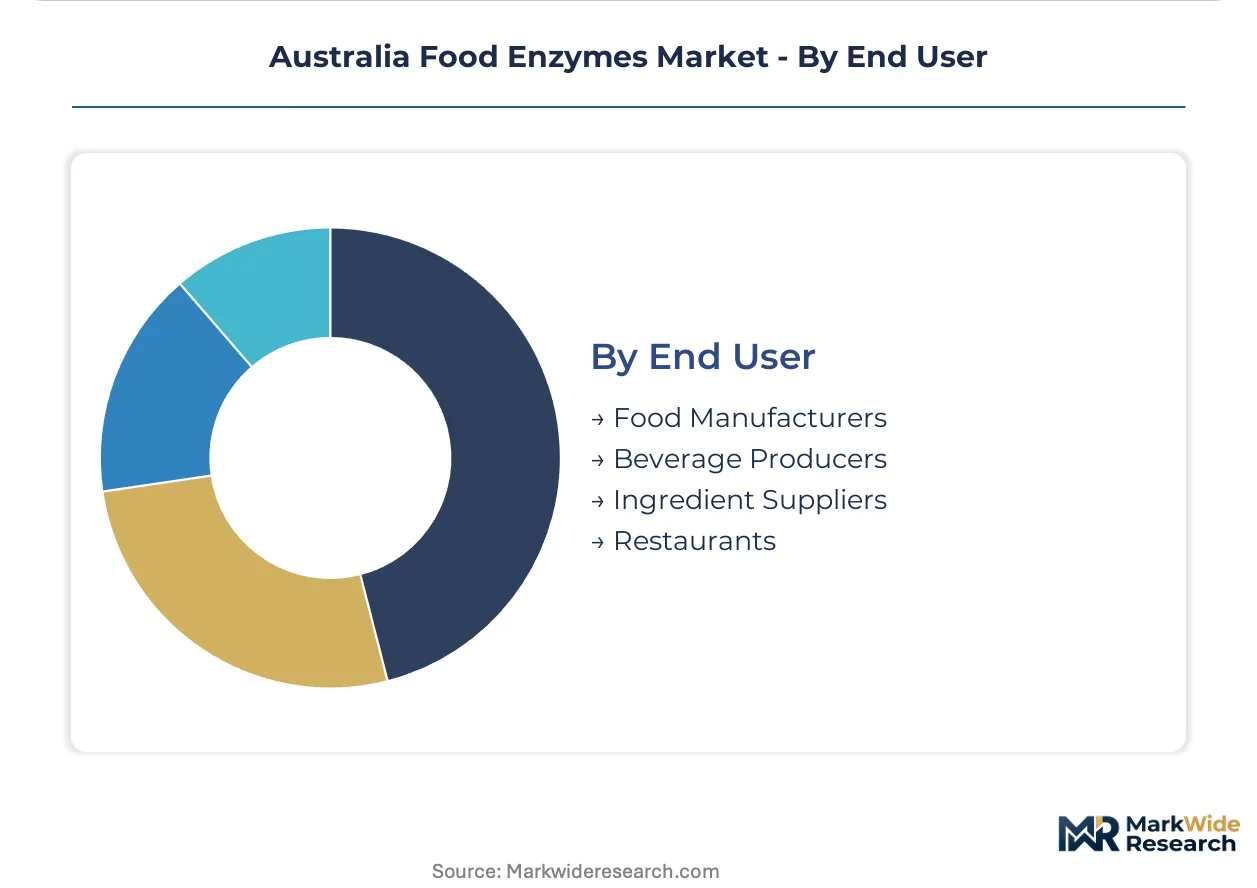
Food manufacturers absorb the dominant volume share, while beverage producers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across Australian states. Victoria and New South Wales buyers absorb premium enzyme formulations with minimal volume pushback. Western Australia and Queensland manufacturers exhibit higher substitution sensitivity toward commodity biocatalyst grades.
New South Wales
Sydney metropolitan contract bakeries drive concentrated amylase procurement for clean-label bread lines. FSANZ processing aid exemptions eliminate additive declarations, redirecting formulation budgets toward biocatalyst solutions. The Parramatta-Ryde manufacturing corridor hosts the densest cluster of industrial baking operations in Australia.
Victoria
Melbourne's integrated dairy processors absorb rising thermostable protease volumes for UHT milk streams. The state's fermentation bioprocess engineering talent shortage limits domestic manufacturing expansion. The Laverton-Derrimut industrial zone anchors specialty cheese production using precision fermentation-derived lipase systems.
Queensland
High-throughput beverage lines in Brisbane and the Gold Coast adopt liquid concentrate dosing systems for starch liquefaction precision. The state's sugar milling infrastructure generates localized demand for invertase and amylase in fermentation applications. Bundaberg's distilling corridor concentrates industrial ethanol biocatalyst procurement.
Western Australia
Southwest specialty cheese producers accelerate lipase adoption as precision fermentation collapses cost premiums. The state's isolation from eastern manufacturing clusters elevates freight economics sensitivity in enzyme procurement decisions. Margaret River dairy operations represent the fastest-expanding biocatalyst demand node outside Victoria and New South Wales.
South Australia
Adelaide's wine processing sector drives pectinase and cellulase demand for juice clarification and maceration control. The state's smaller manufacturing base limits technical service proximity, forcing reliance on distributor networks. Barossa Valley operations concentrate enzyme procurement for premium red wine production.
Australia Food Enzymes Market Competitive Environment
Capability concentration sits with global strain development platforms; scale advantage sits with integrated formulation service networks. The vendor base separates into three functional tiers: proprietary microbial platform holders, application-technical service integrators, and regional distribution specialists. Two dominant competitive moves define current positioning: captive bakery application lab expansion and thermostable protease portfolio diversification.
Within the global platform tier, Novozymes anchors proprietary strain development supply to Australian millers. Kerry Group exemplifies the integrated service model through captive application infrastructure in Melbourne and Sydney. DSM occupies a position in thermostable biocatalyst portfolios designed for UHT dairy streams. These three entities represent distinct competitive archetypes without overlapping functional positioning.
| Leading Market Players |
|---|
| Novozymes |
| Biocatalyst Ltd |
| Puratos Group |
| Chr. Hansen Holding A/S |
| AB Enzymes |
| Deltagen |
| Kerry Group |
| DSM |
| DuPont de Nemours Inc. |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Novozymes' proprietary microbial strain platforms determines both pricing tier spreads and supply chain shape across Australian food enzyme procurement. This concentration elevates technical service bundling as the primary price discriminator while compressing margin flexibility for regional distributors serving Victoria and New South Wales bakery clusters.
Pricing Analysis
Technical service revenue tiers drive lifetime value across Australian enzyme supply contracts. Three-tier pricing structure across premium, standard, and economy levels separates global platform holders with captive application labs from regional distributors with limited formulation support. Price differentiation rests on FSANZ processing aid certification status and volume scale commitments from Melbourne and Sydney metropolitan manufacturers. Pricing pressure stems from precision fermentation cost compression in specialty lipase production, forcing legacy suppliers to absorb margin erosion. Small-to-mid-sized regional bakeries exhibit highest price sensitivity, while integrated dairy processors in Victoria absorb premium thermostable protease formulations with minimal volume pushback.
Supply Chain Analysis
Fermentation feedstock sourcing from Denmark, the Netherlands, and the United States anchors upstream enzyme production for Australian market supply. Industrial biocatalyst manufacturing draws from agricultural protein inputs, specialized microbial culture media, and precision fermentation bioreactor capacity concentrated with global platform holders. Single-source vulnerability intensifies where proprietary strain patents lock Australian manufacturers into inflexible long-term offtake arrangements. Distribution runs through Kerry Group's captive application infrastructure in Melbourne and Sydney, supplemented by regional distributor networks serving South Australia and Western Australia dairy corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against chemical additive reformulation as FSANZ processing aid classifications redirect manufacturer budgets toward biocatalyst alternatives. Incumbents must navigate chemical leavening system revivals that threaten enzyme-based clean-label positioning in contract bakery segments.
For Market Incumbents: Pre-empt displacement by precision fermentation entrants through captive strain development partnerships with Australian research institutions. Lock in sole-source supply contracts with Parramatta-Ryde and Laverton-Derrimut manufacturing clusters before ACCC anti-competitive scrutiny intensifies. Vertical integration into liquid concentrate dosing system technical service revenue protects margin position against commodity biocatalyst price erosion.
For New Entrants and Emerging Players: Pursue white-space expansion in Western Australia's southwest specialty cheese corridor where lipase adoption accelerates and incumbent technical service proximity remains weakest. Target Queensland beverage processing lines adopting precision liquid enzyme delivery systems requiring line reconfiguration investment. Lead with FSANZ regulatory affairs capabilities as differentiated go-to-market positioning against established global suppliers.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors application-technical service integrators with captive formulation infrastructure. Long-term viability over the next decade hinges on regulatory affairs scale and strain development platform control rather than commodity distribution reach. Watch FSANZ proposal draft timelines on novel enzyme sources as the critical inflection signal for next-generation formulation commercialization windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Application Lab Expansion | Kerry Group's Melbourne and Sydney facilities anchor technical service differentiation for bakery enzyme procurement. |
| Precision Fermentation Scale-Up | Specialty lipase cost compression collapses price premiums separating commodity from flavor development applications. |
| Thermostable Protease Portfolio Diversification | DSM's heat-stable biocatalyst advances enable UHT dairy stream processing without thermal degradation risks. |
| Regulatory Affairs Infrastructure Investment | FSANZ proposal draft navigation capabilities determine time-to-market for novel microbial strain approvals. |
| Liquid Concentrate Dosing System Deployment | Queensland beverage line automation creates technical service revenue streams displacing powder handling infrastructure. |
Study Parameters
Operator-level perspectives from bakery formulation managers, dairy processing engineers, FSANZ regulatory affairs specialists, and enzyme distributor procurement heads anchored the qualitative base. Primary field engagement combined structured interviews with secondary validation against FSANZ proposal draft documentation, ACCC enforcement determinations on anti-competitive conduct, and Therapeutic Goods Administration border classification rulings. Trade data from Australian Bureau of Statistics import records and fermentation feedstock customs declarations supplemented demand-side triangulation. Bottom-up enzyme volume estimates from Victoria and New South Wales manufacturing clusters converged with top-down market sizing across the analysis window.
Scenario-bracketing framed the analytical approach across enzyme type, application, form, and end-user segmentation dimensions. CAGRs derived from regression analysis against historical procurement patterns and projected FSANZ regulatory timeline impacts. Industry-specific forecast inputs incorporated precision fermentation cost curve trajectories and thermostable protease technical performance advances in UHT dairy processing. Volume and value outputs reflect triangulated cross-validation between supplier shipment data and end-user consumption surveys throughout the projection horizon.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity cycles and fermentation feedstock pricing would shift the trajectory. Forecasts reflect documented assumptions regarding FSANZ processing aid classification stability and TGA border determination consistency. Cross-checking against Australian Competition and Consumer Commission enforcement patterns on sole-source supply contracts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Protein Ingredient Market
Food Additives and Ingredients
Food Additives Market
Food Additives and Ingredients
Food and Beverages Color Fixing Agents Market
Food Additives and Ingredients
Beta Agonist Feed Additive Market
Food Additives and Ingredients
Global Crystalline Maltitol Market
Food Additives and Ingredients
United Kingdom Food Emulsifier Market
Food Additives and Ingredients
Argentina Food Colorants Market
Food Additives and Ingredients
Argentina Food Additives Market
Food Additives and Ingredients
Bakery Enzymes Market
Food Additives and Ingredients
Western Europe Food Phosphate Market
Food Additives and Ingredients
Fruit Ripening Agents Market
Food Additives and Ingredients
Egg Stabilizer Market
Food Additives and Ingredients
North America Food Starch Market
Food Additives and Ingredients
Chocolate Wax Market
Food Additives and Ingredients
Microencapsulated Phytosterols Market
Food Additives and Ingredients
Fish-Free Omega-3 Ingredients Market