
 Textural Food Ingredients Market | 2026-2036
Textural Food Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Textural Food Ingredients Market Outlook
Food formulation chemist expertise is collapsing across mid-tier ingredient houses, forcing suppliers to automate recipe development or outsource to contract research organizations. Cargill leverages its integrated starch-protein pipeline to deliver tailored texturizer blends for plant-based meat analogues. Kerry Group plc anchors European supply through specialized emulsifier manufacturing in Ireland and the Netherlands. Ingredion Incorporated competes on clean-label corn and tapioca-derived solutions that bypass synthetic additive stigma.
Textural food ingredients comprise hydrocolloids, starches, proteins, and emulsifiers that modify viscosity, gelation, mouthfeel, and stability in processed foods, typically functioning at concentrations between 0.1% and 5% by weight depending on the target rheological profile. These ingredients serve industrial food manufacturing by enabling shelf-stable formulations, fat replacement, and sensory consistency across production batches. Thickeners and stabilizers command the deepest margin pools as they require precise molecular weight distribution and thermal stability that commodity suppliers struggle to replicate. Emulsifiers represent the fastest-growing category as high-protein and plant-based formulations demand interfacial stability that natural lecithin and synthetic esters provide. Texturizers in powder form dominate procurement volumes for dry-mix applications in bakery goods and instant sauces where storage stability and dosing precision matter.
FDA GRAS determinations and USDA organic certification requirements shape ingredient acceptance timelines and label claim validity for suppliers targeting North American food manufacturers. EFSA novel food assessments and EU Food Information to Consumers regulations constrain product introduction cycles and mandate detailed allergen and additive disclosures across European markets. FSSAI standards in India and GB national food safety norms in China add further compliance layers for multinational suppliers operating across jurisdictions. Stakeholders must monitor evolving clean-label definitions and regional enforcement intensity to prioritize formulation investments and geographic registration spending.
Market Dynamics
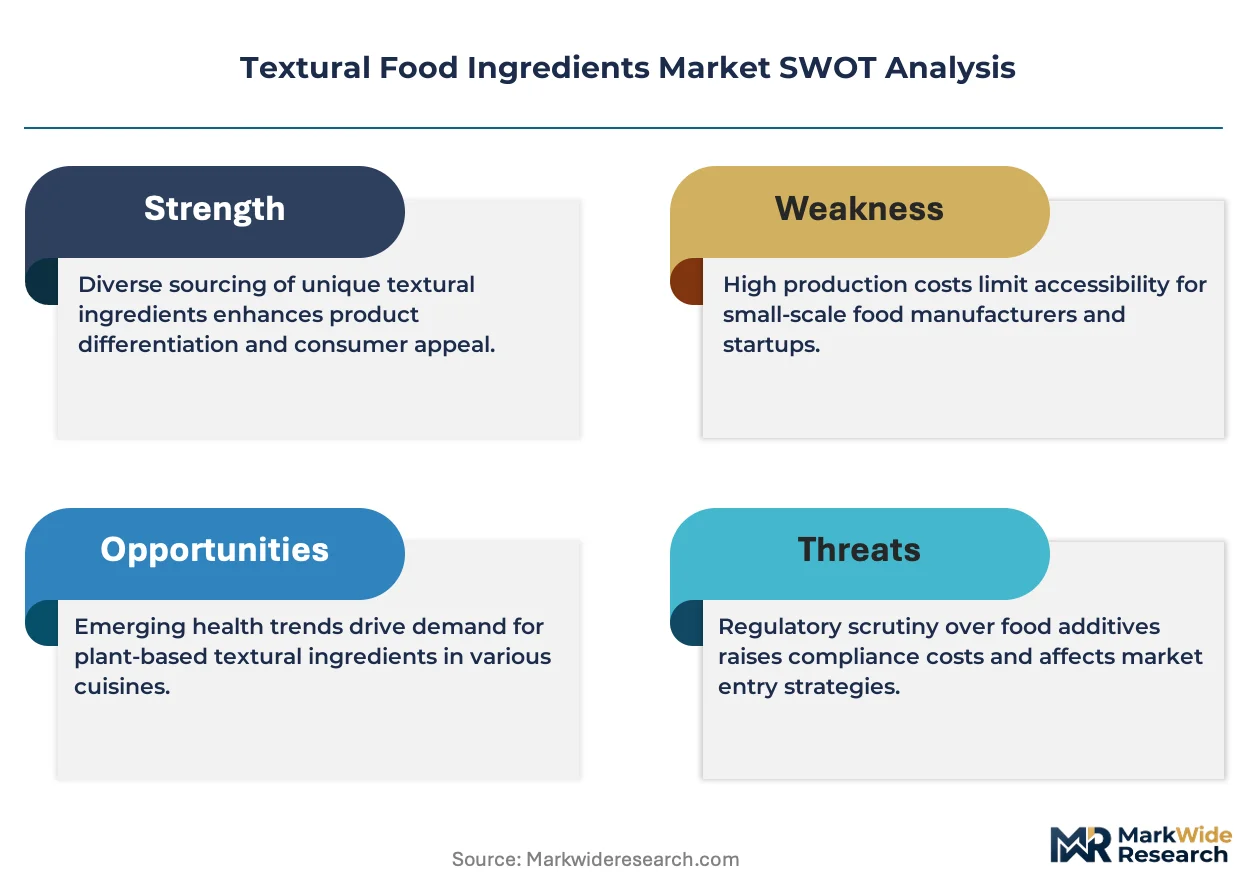
Clean-label reformulation mandates from major retail chains are compressing development cycles for texturizer suppliers, forcing simultaneous reformulation of viscosity, stability, and mouthfeel without synthetic additive portfolios.
Growth Catalysts
- USDA Organic Certification:Accelerating adoption of certified organic hydrocolloids in dairy alternatives as processors chase shelf placement premiums in natural retail channels.
- Plant-based meat analogues:Surging demand for tailored starch-protein texturizer systems that replicate animal muscle fiber alignment and bite resistance.
- India:FSSAI modernization of food additive standards is opening pathways for imported clean-label texturizers in processed snack manufacturing.
Market Restraints
- Cassava root price volatility:Tapioca starch supply from Southeast Asian processors faces climate-driven yield compression, squeezing margin structures for clean-label thickeners.
- Technical limitation:Natural emulsifiers lack the thermal stability and HLB precision of synthetic esters, restricting their deployment in UHT-processed beverages and retort applications.
- Regulatory friction:EFSA novel food assessments impose 18-24 month timelines for new hydrocolloid sources, delaying European market entry for innovative seaweed-derived texturizers.
Strategic Opportunities
- Precision fermentation-derived proteins:Convergence of biotechnology and food formulation is enabling custom-designed texturizers with programmed gelation temperatures and shear-thinning profiles.
- Direct-to-manufacturer digital platforms:B2B ingredient marketplaces are disintermediating traditional distributor networks, allowing mid-tier bakeries to access customized texturizer blends previously reserved for multinational accounts.
- Brazil:ANVISA streamlining of food additive approvals is creating first-mover advantages for suppliers establishing local technical service laboratories.
Industry Challenges
- Formulation chemist scarcity:Retiring expertise in hydrocolloid synergy mapping is forcing suppliers to rebuild capabilities through apprenticeship programs or CRO partnerships.
- Multijurisdictional certification timelines:Simultaneous pursuit of FDA GRAS, EFSA novel food, and FSSAI approvals strains regulatory affairs bandwidth and delays revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textural Food Ingredients Market |
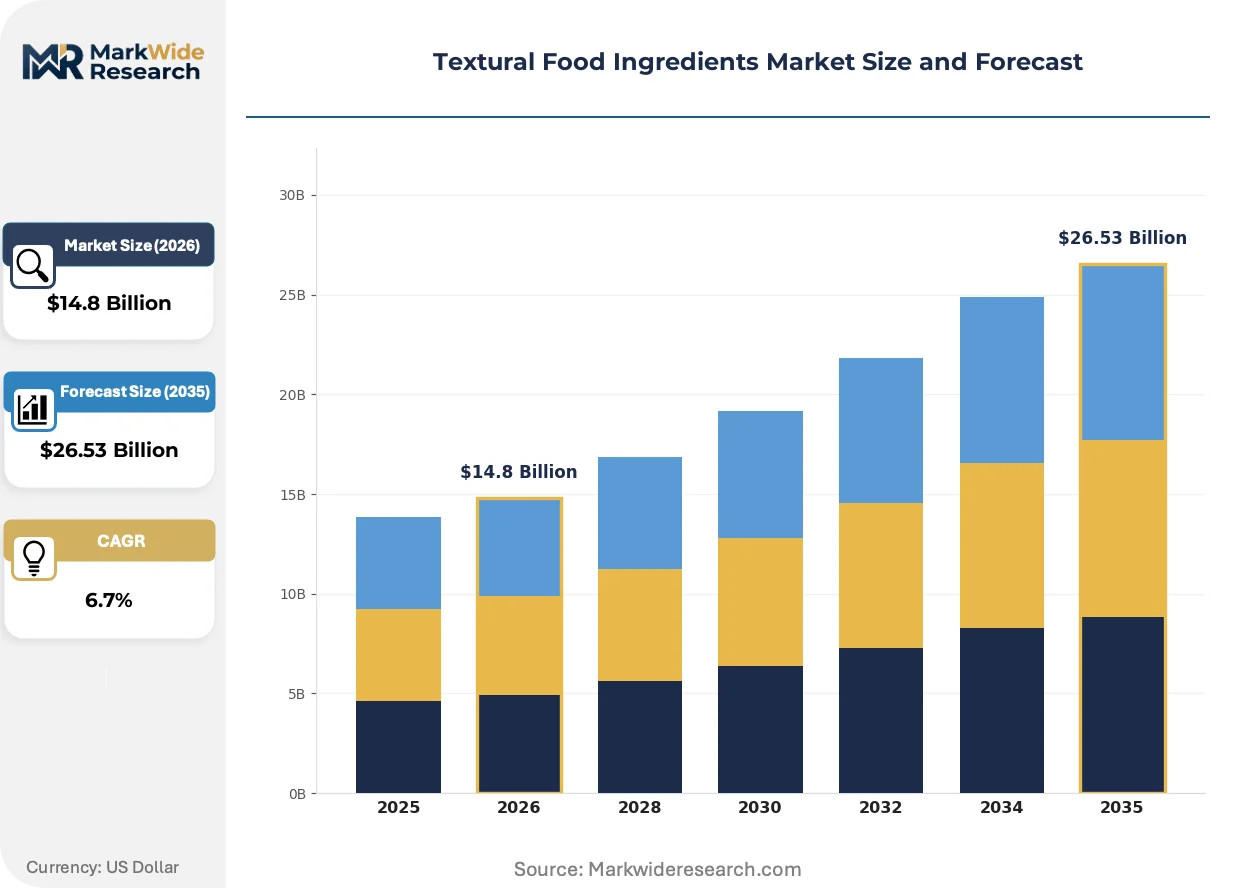
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Texturizers, Thickeners, Stabilizers, Emulsifiers Application: Dairy Products, Bakery Goods, Sauces, Snacks End User: Food Manufacturers, Retailers, Restaurants, Cafes Form: Powder, Liquid, Granular, Gel |
| Companies Covered | Cargill, Archer Daniels Midland Company, Ingredion Incorporated, Kerry Group plc, International Flavors & Fragrances Inc., Tate & Lyle, DuPont de Nemours Inc., CP Kelco, Ajinomoto Co. Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textural Food Ingredients Market Strategic Shifts
Bioprocessing advances and regulatory transparency mandates are reconfiguring how texturizers are sourced, validated, and deployed across formulation laboratories.
Cell-cultured collagen and precision-fermented proteins are bifurcating the texturizer landscape into commodity hydrocolloids and high-performance functional ingredients. Large-scale meat processors are piloting these biomanufactured alternatives for texture modulation in hybrid products. This technological split is compressing R&D timelines for traditional suppliers while opening premium pricing tiers for biotechnology-enabled entrants.
EFSA's updated Food Information to Consumers regulations are mandating granular disclosure of additive functions and origins on European labels. Processors reformulating for compliance are stripping synthetic emulsifiers from ingredient decks and accelerating validation of lecithin and plant-derived alternatives. Bakery and confectionery segments in Germany and France are absorbing the highest compliance costs as they retrofit legacy formulations.
Ingredient sourcing decisions now hinge on carbon footprint verification and deforestation-free supply chain documentation. Food manufacturers in the Netherlands and United Kingdom are requiring Scope 3 emissions data from texturizer suppliers, with tapioca and palm-derived ingredients facing heightened scrutiny. This behavioral pivot is favoring vertically integrated starch processors with captive agriculture operations and certified sustainable sourcing.
Textural Food Ingredients Market Segmentation
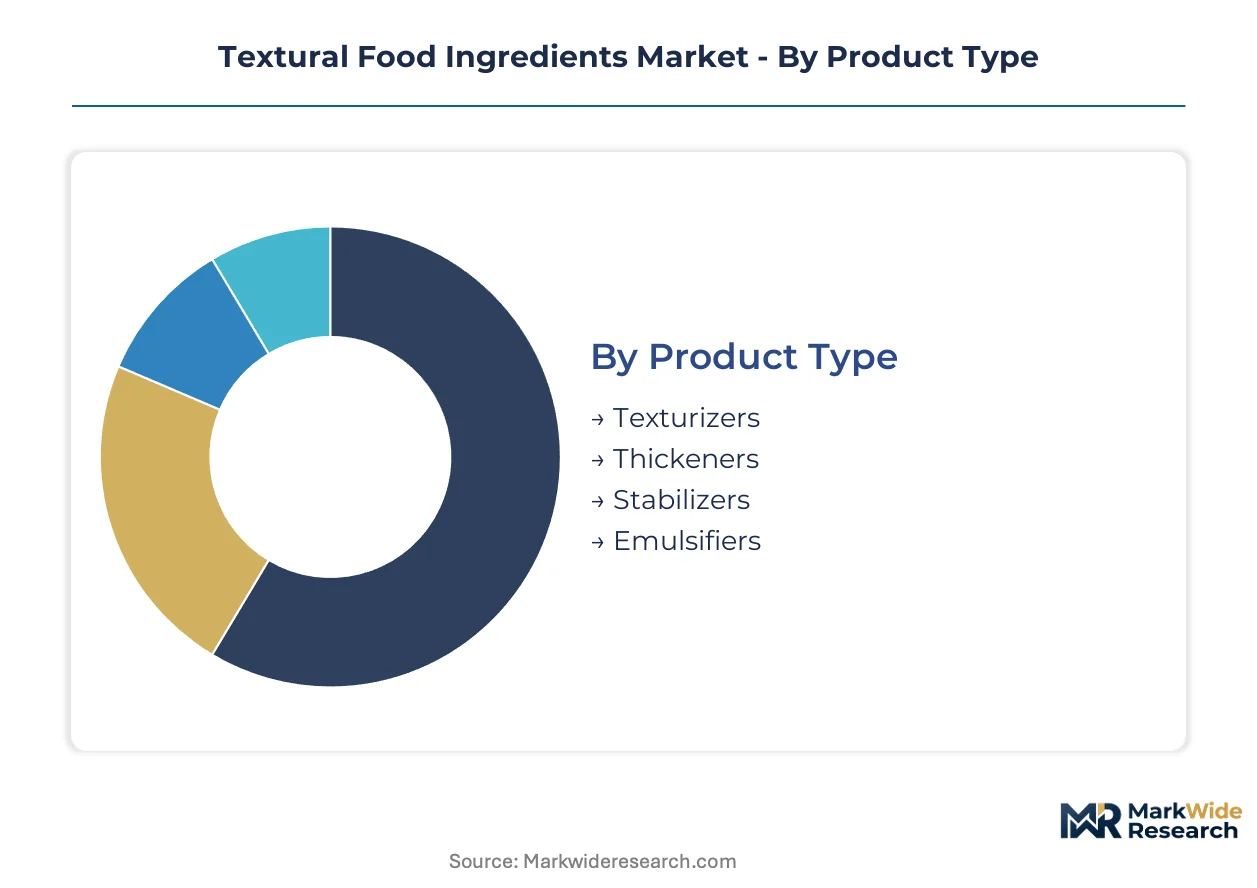
Textural food ingredients serve divergent technical requirements across processing environments. Segment boundaries reflect formulation complexity thresholds and procurement scale rather than commodity interchangeability.
Product Type:
Domestic production dominates thickeners and stabilizers for North American dairy processors. Export-led demand concentrates in emulsifiers shipped to European bakery manufacturers seeking clean-label alternatives.
- Texturizers:Starch-protein blends and hydrocolloid systems modify mouthfeel and structural integrity in plant-based meat analogues. Large-scale food processors in the United States drive bulk procurement of customized systems for controlled gelation temperatures.
- Thickeners:Modified and native starches from corn and tapioca sources adjust viscosity in sauces and dairy applications. Southeast Asian climate pressures on cassava root supply are compressing margin structures for clean-label variants.
- Stabilizers:Xanthan gum and locust bean gum prevent syneresis in frozen desserts.
- Emulsifiers:Lecithin and synthetic esters enable interfacial stability in high-protein beverages.
Thickeners command the established base. The steepest expansion runs through emulsifiers.
Application:
Cost tier separation is pronounced: premium organic certification commands shelf placement premiums in natural retail channels, while economy formulations serve institutional foodservice.
- Dairy Products:Yogurt, ice cream, and plant-based milk alternatives require precise control over gelation and freeze-thaw stability. USDA organic certification is accelerating adoption of certified hydrocolloids in dairy alternatives chasing natural channel premiums.
- Bakery Goods:Bread, cakes, and pastries depend on emulsifiers for crumb structure and shelf-life extension. EFSA Food Information to Consumers regulations are forcing synthetic emulsifier replacement with lecithin alternatives in German and French reformulations.
- Sauces:Viscosity modification in pourable and spoonable formats.
- Snacks:Texture control in extruded and coated products.
Dairy products anchor volume demand. Bakery goods are gaining share fastest.
End User:
Customer type determines specification intensity: multinational food manufacturers demand batch-to-batch rheological consistency, while independent restaurants prioritize cost and ease of incorporation.
- Food Manufacturers:Industrial-scale processors formulate for shelf stability and sensory consistency across production batches. Retiring formulation chemist expertise is forcing automation of recipe development or outsourcing to contract research organizations.
- Retailers:Private-label brands specify clean-label ingredient decks for consumer transparency.
- Restaurants:Chain operators seek pre-hydrated systems for kitchen efficiency.
- Cafes:Specialty beverage preparation drives demand for cold-soluble texturizers.
Food manufacturers represent the dominant procurement channel. Retailers are climbing the fastest as private-label penetration deepens.
Form:
Supply concentration varies by physical state: powder processing clusters around Midwest corn belt facilities, while liquid emulsifier production concentrates near coastal port infrastructure for export efficiency.
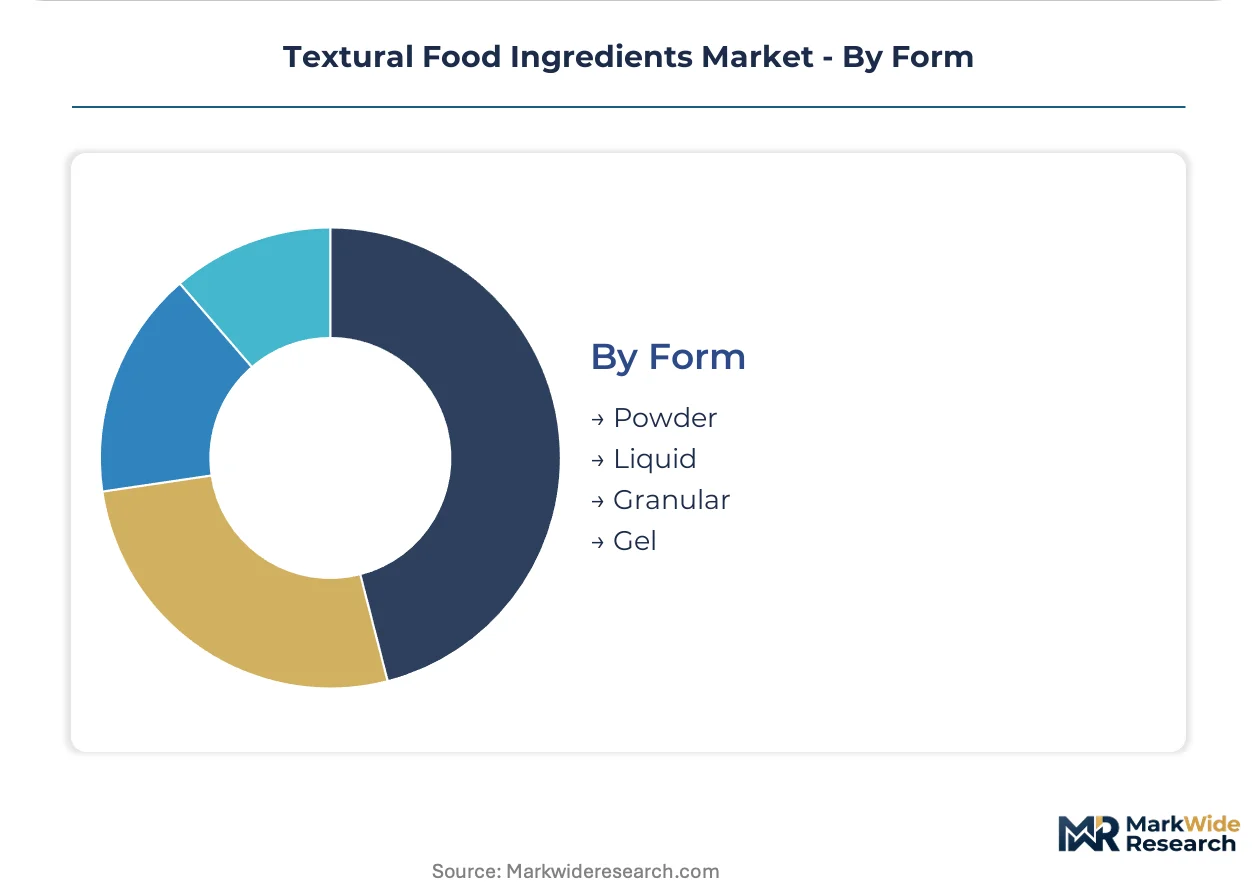
- Powder:Dry-mix applications in bakery goods and instant sauces require storage stability and dosing precision. Powdered texturizers dominate procurement volumes where controlled hydration kinetics matter.
- Liquid:Pre-dispersed hydrocolloids and emulsifier concentrates eliminate hydration latency in continuous processing. UHT beverage manufacturers favor liquid formats despite higher transport costs.
- Granular:Intermediate dissolution rate for controlled hydration in meat processing.
- Gel:Pre-hydrated systems for immediate functionality in cold-process applications.
Powder forms hold the incumbent position. Liquid formats are expanding most quickly in high-throughput beverage operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA GRAS determinations and USDA organic certification requirements anchor the United States as the dominant geography for textural food ingredient demand. Large-scale food processors in the Midwest corn belt drive bulk procurement of customized texturizer systems. Regional dynamics diverge sharply across regulatory jurisdictions and agricultural supply bases.
United States
Midwest dairy processors and plant-based meat manufacturers generate concentrated demand for starch-protein texturizer blends. FDA updated GRAS notification requirements are reshaping ingredient approval pathways for novel hydrocolloid sources. Chicago and Minneapolis-St. Paul industrial corridors host formulation laboratories where retiring chemist expertise is forcing automation investment.
Germany
EFSA Food Information to Consumers regulations mandate granular additive disclosure on bakery and confectionery labels. German manufacturers are stripping synthetic emulsifiers from legacy formulations and accelerating lecithin validation. The Cologne-Düsseldorf food processing cluster absorbs the highest compliance retrofit costs in European reformulation cycles.
India
FSSAI modernization of food additive standards is opening pathways for imported clean-label texturizers in processed snack manufacturing. Domestic dairy alternatives and instant sauce producers drive hydrocolloid adoption. Mumbai-Pune and Ahmedabad industrial zones concentrate procurement volumes for dry-mix applications.
Brazil
ANVISA streamlining of food additive approvals is creating first-mover advantages for suppliers establishing local technical service laboratories. São Paulo-based meat processors and beverage manufacturers demand interfacial stability solutions for high-protein formulations. The Campinas research corridor anchors biotechnology-enabled texturizer pilot programs.
Netherlands
Scope 3 emissions verification requirements from Dutch and British food manufacturers are reshaping sourcing decisions for tapioca and palm-derived ingredients. Rotterdam port infrastructure supports liquid emulsifier import and re-export efficiency. Wageningen food science clusters drive carbon footprint documentation standards across European supply chains.
Textural Food Ingredients Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the textural food ingredients sector. Integrated agribusiness conglomerates with captive starch-protein pipelines compete against specialized emulsifier manufacturers and biotechnology-enabled precision fermentation entrants. Two strategic archetypes dominate: vertically integrated agricultural processors controlling raw material supply, and functional ingredient specialists commanding premium pricing through clean-label certification. Competitive moves concentrate on M&A to secure formulation chemist capabilities and strategic partnerships with contract research organizations to compress development cycles.
Among integrated agricultural processors, Cargill and Archer Daniels Midland Company represent the scale-driven archetype with upstream control over corn and oilseed supply chains. Ingredion Incorporated occupies a position within the clean-label specialization tier, while Kerry Group plc exemplifies the European functional ingredient specialist model. These three companies anchor the competitive structure without exhausting its diversity.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Kerry Group plc |
| International Flavors & Fragrances Inc. |
| Tate & Lyle |
| DuPont de Nemours Inc. |
| CP Kelco |
| Ajinomoto Co. Inc. |
| Others |
Value Chain & Pricing Dynamics
Midwest corn belt starch processing capacity utilization above 85% creates scale economies that compress unit costs for modified starches while establishing price floors that smaller tapioca processors in Southeast Asia cannot match. This concentration dynamic forces clean-label suppliers to absorb margin compression or differentiate through USDA organic certification premiums.
Pricing Analysis
Geographic price spreads between US Gulf Coast corn-derived texturizers and Southeast Asian tapioca alternatives have widened as Thai cassava root yields face climate-driven volatility. Three-tier pricing structure across premium organic-certified, standard food-grade, and economy industrial-grade levels separates procurement channels. Pricing pressure stems from FSSAI modernization in India accelerating import competition in processed snack applications. Food manufacturers represent the least price-sensitive segment due to batch-to-batch consistency requirements, while independent bakeries exhibit highest sensitivity to hydrocolloid cost swings.
Supply Chain Analysis
Inventory cycles for powdered hydrocolloids now stretch 8-12 weeks longer than pre-pandemic baselines as Southeast Asian processors rebuild buffer stocks after monsoon disruptions. Supply concentrates in the United States for corn and potato starches, Thailand and Vietnam for tapioca derivatives, and China for xanthan gum fermentation capacity. Raw material dependencies include cassava root, corn wet-milling byproducts, and seaweed biomass for carrageenan extraction. Single-source vulnerability runs through Thai tapioca starch exports facing recurring flood risk. Distribution runs through Midwest bulk terminals for domestic dairy processors and Rotterdam liquid emulsifier hubs for European bakery re-export.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for formulation support now generate recurring revenue streams that outpace commodity ingredient sales growth, transforming supplier relationships from transactional supply to embedded R&D partnerships.
For Market Incumbents: Secure captive supply of organic-certified corn and tapioca through backward integration into Midwest farming cooperatives and Southeast Asian processing joint ventures. Invest in precision fermentation capabilities before biotechnology-enabled texturizers displace commodity hydrocolloids in plant-based meat applications. Cargill's integrated starch-protein pipeline demonstrates how upstream control defends margin position against price volatility. For New Entrants and Emerging Players: Anchor in Brazilian meat processing corridors where ANVISA streamlining reduces regulatory barriers for novel emulsifier introductions. Target mid-tier US bakeries through B2B digital platforms that bypass traditional distributor markups. White-space opportunity concentrates in cold-soluble texturizers for specialty beverage cafes lacking technical hydration infrastructure. For Investors and Strategic Acquirers: Contract research organizations with hydrocolloid synergy mapping capabilities represent the most defensible acquisition archetype as formulation chemist scarcity intensifies. Long-term viability hinges on biotechnology convergence displacing extraction-based texturizers within the next decade. Watch FDA GRAS notification timelines for novel seaweed-derived hydrocolloids as inflection signal for clean-label ingredient valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Corn Supply | USDA certification premiums capture natural retail channel shelf placement. |
| Precision Fermentation Scale-Up | Custom-designed proteins bypass climate-driven agricultural commodity volatility. |
| Technical Service Laboratory Expansion | Brazil ANVISA proximity accelerates novel additive approval cycles. |
| B2B Digital Platform Launch | Direct manufacturer access disintermediates traditional distributor networks. |
| Carbon Footprint Verification Program | Scope 3 documentation satisfies Dutch and British manufacturer sourcing mandates. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA GRAS notifications, EFSA novel food assessments, FSSAI additive standards, and trade customs data for hydrocolloid imports. Formulation chemists at ingredient houses, procurement directors at multinational food manufacturers, regulatory affairs specialists, and contract research organization technical leads provided qualitative inputs. Bottom-up demand modeling across dairy, bakery, and plant-based meat applications triangulates against top-down supply capacity assessments for corn, tapioca, and fermentation-derived texturizers.
Segmentation dimensions modeled include product type (texturizers, thickeners, stabilizers, emulsifiers), application (dairy, bakery, sauces, snacks), form (powder, liquid, granular, gel), and end-user scale (multinational manufacturers, retailers, foodservice). CAGRs derive from weighted average growth across these segments incorporating USDA organic adoption curves, EFSA regulatory compliance retrofit cycles, and precision fermentation technology maturation timelines. Input assumptions include cassava root yield projections and clean-label reformulation mandates from major retail chains.
Material uncertainties — climate-driven agricultural commodity shocks, biotechnology regulatory reclassification, and formulation chemist labor market tightness — sit outside the modeled envelope. Forecasts reflect assumptions about continued clean-label momentum and stable GRAS notification processing timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Egg Phosphatidylcholine Market
Ingredients
Rose Hips Extract Market
Ingredients
Kairomones Market
Ingredients
Coconut Cream Powder Market
Ingredients
United States Whey Protein Ingredients Market
Ingredients
Canola Oil Market
Ingredients
Textured Soy Flour Market
Ingredients
Europe Pea Starch Market
Ingredients
Millet Protein Market
Ingredients
South America Plant Protein Ingredients Market
Ingredients
Vegetable Extract Market
Ingredients
Barley Flake Market
Ingredients
Shortening Powder Market
Ingredients
Bean Pasta Market
Ingredients
Medium Chain Triglyceride (MCT) Oil Market
Ingredients
Mexico Avocado Oil Market