
 Fuel Oxygenate Market | 2026-2036
Fuel Oxygenate Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Oxygenate Market Intelligence
Long-term supply contracts with embedded quality assurance services is hardening the competitive landscape for fuel oxygenates. LyondellBasell leverages its significant production scale and integrated chemical operations to serve large-volume gasoline markets. In contrast, SABIC differentiates through its strategic feedstock access and logistical advantages in the Middle East. Evonik Industries specializes in producing high-purity ether-based oxygenates for premium fuel applications.
Fuel oxygenates are organic compounds containing oxygen added to fuel to enhance combustion efficiency. These are typically alcohols like ethanol or ethers such as Methyl Tertiary-Butyl Ether (MTBE), which contain an ether group bonded to two alkyl groups. Their primary purpose is to increase the oxygen content of gasoline, leading to a more complete burn and a reduction in harmful tailpipe emissions like carbon monoxide. Ethanol and MTBE constitute the largest product segments by volume, while gasoline additive applications remain the dominant end-use for these compounds.
The market operates within a strict regulatory framework defined by national and regional environmental policies. The US EPA's requirements for reformulated gasoline and the EU's Renewable Energy Directive directly influence blending mandates. Similarly, China's GB standards for vehicle emissions and fuel quality compel refiners to use oxygenates. Producers must now decide between supplying commodity-grade volumes for regulated markets or investing in specialized oxygenates for emerging sectors like sustainable aviation fuel.
Market Dynamics
The central dynamic in the fuel oxygenate market is the global regulatory push for cleaner transportation fuels. This pressure, exemplified by policies from the US EPA and the EU, forces refiners to incorporate oxygenates, creating sustained, mandate-driven demand for compounds like ethanol and MTBE.
Growth Catalysts
- Stringent Emissions Standards:Regulations like the US EPA's reformulated gasoline program and the EU's Renewable Energy Directive require specific oxygen content in fuel, directly compelling the use of oxygenates to reduce carbon monoxide and other harmful emissions.
- Fuel Quality Upgrades:National programs, particularly China's GB standards, mandate higher quality gasoline for its large vehicle fleet, creating massive, concentrated demand for octane-enhancing oxygenates like MTBE to meet performance and environmental targets.
- Engine Efficiency Demands:The automotive sector's adoption of downsized, turbocharged engines requires higher-octane fuels to prevent knocking and maximize performance, sustaining demand for oxygenates as a critical component in premium gasoline formulations.
Market Restraints
- Electric Vehicle Substitution:The accelerating adoption of battery electric vehicles presents a long-term existential threat, as EVs completely eliminate the demand for gasoline and, by extension, the fuel oxygenates blended within it.
- Regulatory Bans and Phase-Outs:Environmental and health concerns, such as MTBE's potential for groundwater contamination, have led to outright bans in several US states and other regions, fragmenting the market and creating supply chain complexities.
- Feedstock Price Volatility:The profitability of oxygenate production is directly tied to the fluctuating costs of raw materials, such as corn for ethanol or natural gas and isobutylene for MTBE, creating margin pressure for producers.
Strategic Opportunities
- Sustainable Aviation Fuel:The aviation industry's pursuit of decarbonization opens a significant new application area for bio-based oxygenates and ethers as blendstocks for sustainable aviation fuel (SAF), moving beyond traditional road transport.
- Emerging Market Adoption:As developing economies in Southeast Asia and Africa begin to implement more stringent fuel quality and emissions standards, they represent new, underpenetrated markets for commodity and specialty oxygenates.
- High-Performance Formulations:Growing demand for premium and high-performance fuels creates an opportunity for producers of high-purity ethers like Ethyl Tertiary-Butyl Ether (ETBE) and isooctane, which command higher prices.
Industry Challenges
- Logistical Hurdles:The hygroscopic nature of ethanol requires segregated transportation and storage infrastructure to prevent water contamination in pipelines and tanks, adding significant cost and complexity compared to traditional gasoline components.
- Capital-Intensive Production:Building new world-scale oxygenate plants or retrofitting existing refineries to produce different types of ethers or alcohols requires substantial capital investment and long lead times for construction and commissioning.
- Compliance Fragmentation:Producers must navigate a complex and divergent web of blending mandates, product specifications, and sustainability certifications across different countries and even sub-national jurisdictions, increasing compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Oxygenate Market |
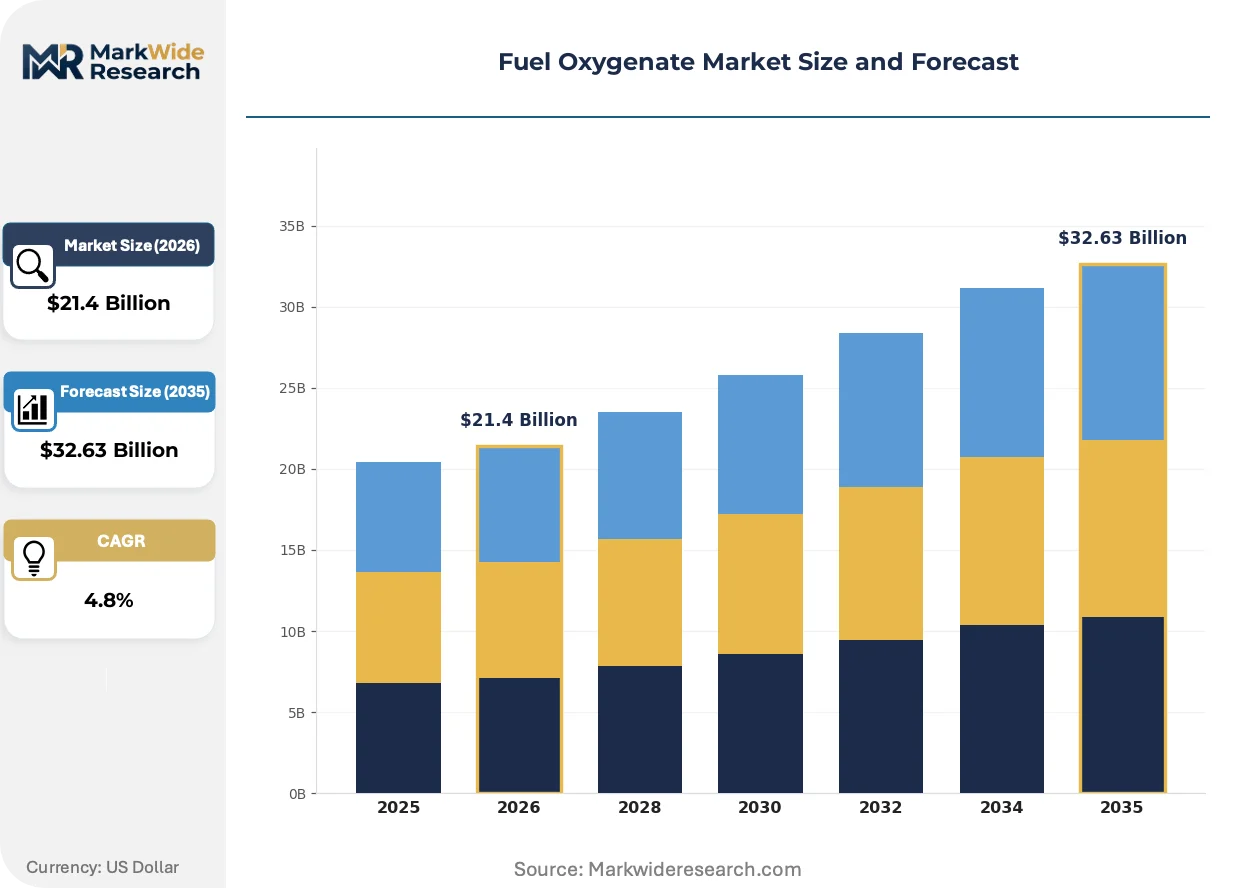
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $32.63 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Methyl Tertiary-Butyl Ether, Ethyl Tertiary-Butyl Ether, Methanol, Ethanol, Tertiary Amyl Methyl Ether Application: Gasoline Additive, Diesel Blending, Aviation Fuel, Marine Fuel, Industrial Fuel End User: Refineries, Fuel Distributors, Transport Fleet Operators, Marine Operators, Aviation Services Distribution Channel: Direct Sales, Distributors, Online Channels, Fuel Retailers |
| Companies Covered | Evonik Industries, Fluor Corporation, LyondellBasell, Panjin Heyun Industrial Group Co., Ltd., PETRONAS Chemicals Group Berhad, ProTec International, Qatar Fuel Additives Company, Royal Dutch Shell, Saudi Basic Industries Corporation (SABIC), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Oxygenate Market Strategic Shifts & Innovations
The market's evolution is defined by a shift from meeting basic regulatory mandates to leveraging oxygenates for enhanced performance and sustainability. This transition is driven by the development of bio-based alternatives and a growing focus on the entire lifecycle impact of fuel components.
Bio-ethers, derived from renewable feedstocks like bio-ethanol, function as drop-in oxygenates that reduce both tailpipe emissions and lifecycle carbon footprints. Refiners and fuel blenders are adopting these compounds to simultaneously meet renewable fuel obligations and octane enhancement needs. The development of these advanced molecules is unifying the previously separate goals of improving air quality and advancing climate objectives within a single fuel additive.
China's "dual carbon" policy framework is directly influencing regional production and trade flows. The country's progressively stricter GB standards for fuel quality compel domestic refiners to secure vast, long-term supplies of oxygenates to meet higher blend rate requirements. The ether-based oxygenate segment, particularly MTBE, is most impacted, as its blending properties are highly favored by Chinese refiners for compatibility with existing logistics.
Fuel blenders are increasingly sourcing oxygenates based on specific performance attributes rather than just commodity volume and price. This change disrupts the traditional supply model for MTBE and ethanol, creating openings for chemical specialists that provide high-purity ethers for premium gasoline. This behavior is most prominent in the European automotive market, where advanced engines demand fuels with superior anti-knock properties.
Fuel Oxygenate Market Segmentation
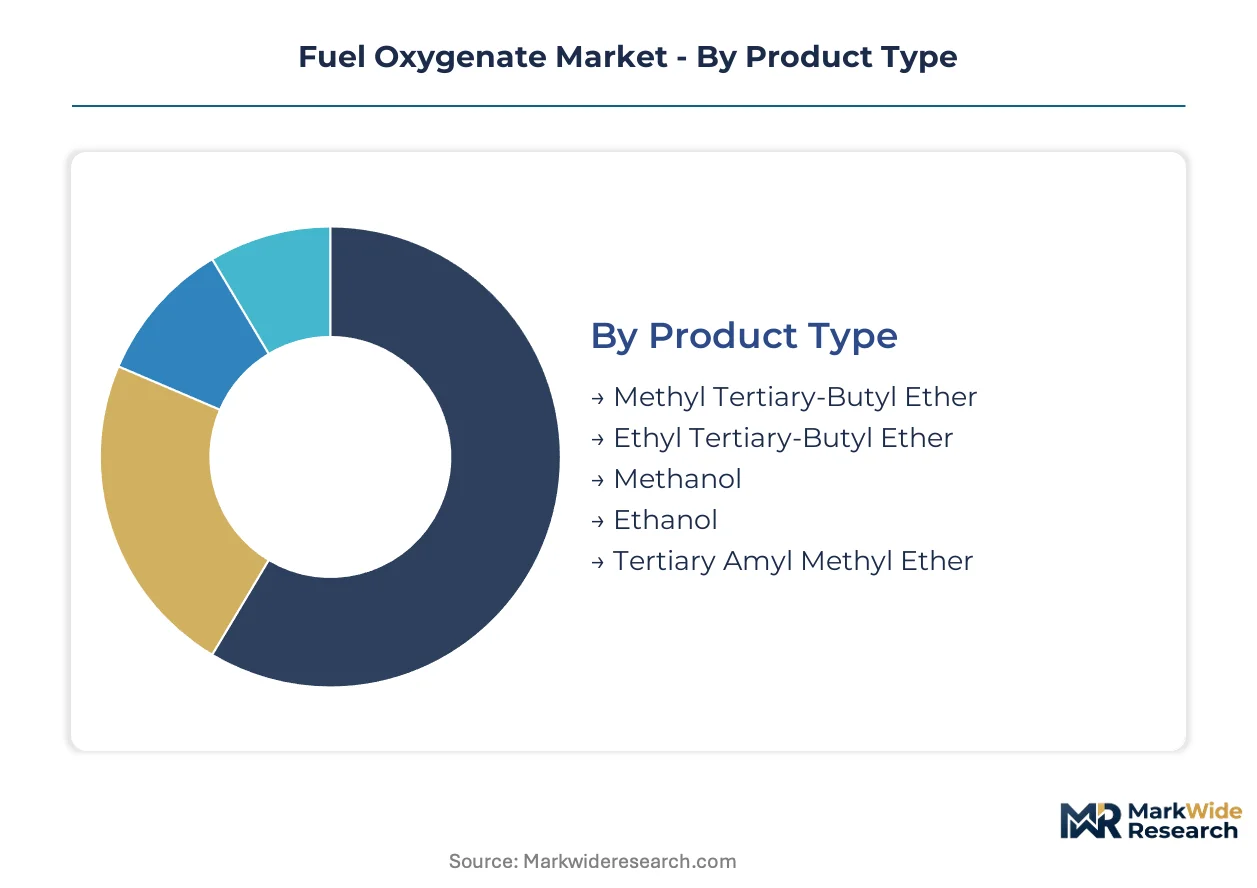
The fuel oxygenate market segmentation clarifies how different compounds, applications, and distribution channels shape industry dynamics. Understanding these distinct segments helps producers align their offerings with specific regulatory requirements and evolving end-user demands. This detailed breakdown highlights areas of concentration and growth within the broader market.
Product Type:
Supply concentration for fuel oxygenates often dictates product type availability, influencing regional blending practices and regulatory compliance across various markets.
- Methyl Tertiary-Butyl Ether (MTBE):This ether-based compound enhances octane and reduces carbon monoxide emissions. Demand concentrates heavily in China, driven by national fuel quality upgrade programs and compatibility with existing logistics.
- Ethanol:A bio-based alcohol, ethanol increases fuel oxygen content and serves as a renewable fuel component. Its primary demand stems from gasoline additive applications in countries with strong biofuel blending mandates like the United States.
- Ethyl Tertiary-Butyl Ether (ETBE):This high-purity ether, derived from ethanol, offers superior anti-knock properties for premium gasoline formulations.
- Methanol:A simple alcohol, methanol can be blended into gasoline, but its use is more restricted due to compatibility and energy density concerns.
- Tertiary Amyl Methyl Ether (TAME):TAME is an octane enhancer and oxygenate, often used in conjunction with MTBE to improve gasoline properties.
Today's leader: Ethanol. Tomorrow's challenger: Bio-ethers.
Application:
Application-specific requirements drive the formulation and demand for various fuel oxygenates, directly impacting market volumes and product specifications.
- Gasoline Additive:Fuel oxygenates are primarily used as additives in gasoline to improve combustion efficiency and reduce harmful tailpipe emissions. This application dominates demand due to global mandates for cleaner transportation fuels.
- Aviation Fuel:Bio-based oxygenates and ethers are emerging as critical blendstocks for sustainable aviation fuel (SAF), supporting the aviation industry's decarbonization goals. This segment represents a significant strategic opportunity.
- Diesel Blending:Some oxygenates can be blended into diesel to improve cetane numbers and reduce particulate matter emissions.
- Marine Fuel:Oxygenates can contribute to cleaner burning marine fuels, addressing environmental regulations in international shipping.
- Industrial Fuel:Certain industrial processes utilize oxygenate-blended fuels for specific combustion characteristics or emissions control.
Gasoline additive applications represent the fastest-growing trajectory.
End User:
The diverse requirements of end-user types directly influence the procurement strategies and preferred oxygenate specifications across the value chain.
- Refineries:These entities are primary consumers, blending oxygenates into gasoline and other fuels to meet regulatory standards and enhance product performance. Refineries often seek long-term supply contracts for commodity-grade volumes.
- Fuel Distributors:These operators manage the logistics and supply of fuel products, requiring oxygenates that are compatible with existing infrastructure and regional specifications. Their demand is driven by retail and commercial fuel needs.
- Transport Fleet Operators:Operators of large vehicle fleets are increasingly focused on fuel efficiency and emissions reduction, driving demand for high-quality oxygenate-blended fuels.
- Marine Operators:Shipping companies require specialized fuel formulations to comply with international maritime emissions regulations.
- Aviation Services:Airlines and aviation fuel suppliers are exploring bio-based oxygenates for sustainable aviation fuel blends to meet decarbonization targets.
Refineries are currently the largest consumer segment, while aviation services are gaining share fastest.
Distribution Channel:
The volume and nature of oxygenate transactions define the structure of their distribution channels, from bulk industrial sales to specialized retail supply.
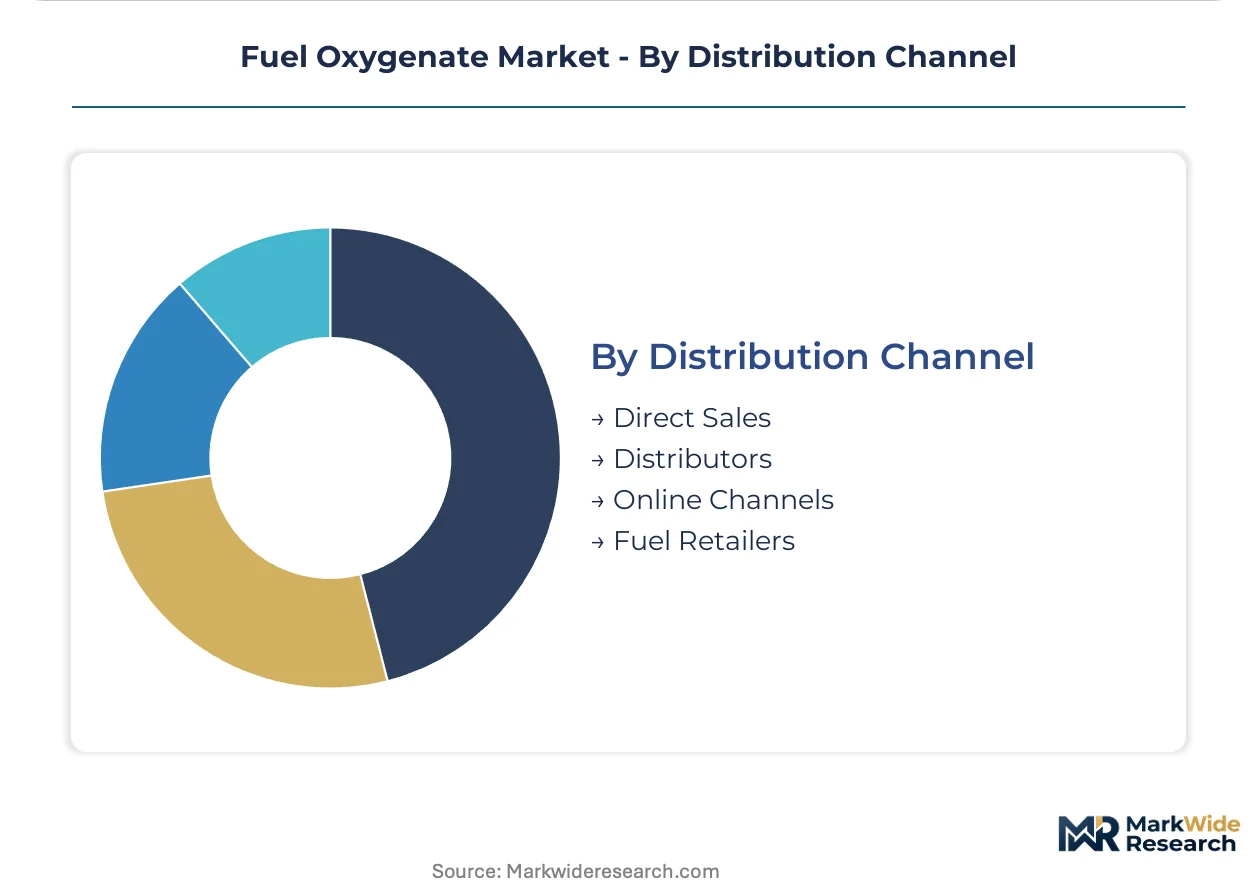
- Direct Sales:Producers engage in direct sales with large-volume buyers like refineries and major fuel blenders, often involving long-term contracts and dedicated logistics. This channel is critical for commodity-grade oxygenates.
- Distributors:Specialized distributors manage regional supply chains, providing oxygenates to smaller blenders, industrial users, and niche markets. They offer logistical flexibility and market reach.
- Online Channels:Emerging for certain specialty chemicals, online platforms facilitate procurement for smaller-volume, high-purity oxygenates.
- Fuel Retailers:While not directly distributing oxygenates, retailers sell the final blended fuel products to consumers, representing the ultimate point of sale.
Direct sales currently dominate volume, but distributors show the steepest expansion trajectory for specialized products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's fuel quality upgrades drive significant Methyl Tertiary-Butyl Ether (MTBE) demand, contrasting with the United States where ethanol blending mandates dominate the oxygenate market. This regional divergence reflects varied regulatory priorities and available feedstock resources for fuel oxygenate production. European nations also prioritize high-purity ethers for premium fuel formulations.
China
China's vast vehicle fleet and national fuel quality upgrade programs create massive demand for octane-enhancing oxygenates. The GB standards for vehicle emissions compel refiners to secure long-term supplies of MTBE. Refineries in the Yangtze River Delta region are particularly impacted by these requirements, driving investment in blending infrastructure.
United States
The United States market is primarily driven by biofuel blending mandates, favoring ethanol as a renewable fuel component. The US EPA's requirements for reformulated gasoline directly influence oxygenate content. States like Iowa and Nebraska, major corn-producing regions, anchor significant ethanol production capacity.
Germany
Germany's automotive sector demands high-performance fuels, creating a niche for high-purity ether-based oxygenates like Ethyl Tertiary-Butyl Ether (ETBE). EU's Renewable Energy Directive promotes bio-based fuel components, influencing blending practices. Chemical parks in the Rhine-Ruhr area specialize in producing advanced fuel additives for the European market.
Saudi Arabia
Saudi Arabia benefits from strategic feedstock access, positioning it as a key producer of MTBE for global markets. The country's integrated petrochemical complexes leverage abundant natural gas resources for oxygenate synthesis. Industrial cities like Jubail host large-scale chemical operations, exporting significant volumes to Asia.
Brazil
Brazil's fuel oxygenate market is uniquely shaped by its extensive sugarcane industry, making ethanol a primary fuel component. National policies strongly support ethanol production and consumption as a renewable energy source. São Paulo state, a major agricultural hub, leads the nation in bioethanol production and distribution.
Fuel Oxygenate Market Key Industry Players
Top-tier vendors anchor the global fuel oxygenate market, while a diverse set of regional and specialized players address specific blending needs. The industry exhibits a tiered structure, with large integrated chemical producers dominating commodity volumes and specialty chemical firms focusing on high-purity applications. Strategic archetypes include feedstock-advantaged producers, integrated refinery operators, and high-purity specialists. Capacity expansion and strategic partnerships remain dominant competitive moves across the landscape, alongside portfolio diversification into bio-based alternatives.
Within the integrated chemical producers, LyondellBasell and Saudi Basic Industries Corporation (SABIC) represent companies leveraging significant scale and strategic feedstock access. LyondellBasell utilizes its extensive production capabilities to serve large-volume gasoline markets globally. SABIC differentiates through its advantageous position in the Middle East, ensuring logistical efficiency for its oxygenate products. Evonik Industries occupies a distinct position as a specialist, producing high-purity ether-based oxygenates tailored for premium fuel applications in demanding automotive markets.
| Leading Market Players |
|---|
| Evonik Industries |
| Fluor Corporation |
| LyondellBasell |
| Panjin Heyun Industrial Group Co., Ltd. |
| PETRONAS Chemicals Group Berhad |
| ProTec International |
| Qatar Fuel Additives Company |
| Royal Dutch Shell |
| Saudi Basic Industries Corporation (SABIC) |
| Others |
Cost & Logistics Intelligence
The EU's Renewable Energy Directive gates qualified supply and premium-tier pricing access for bio-based fuel oxygenates. This mandate drives demand for certified sustainable products, influencing market pricing across Europe.
Pricing Analysis
Capacity additions in Saudi Arabia are reshaping price floors for commodity-grade MTBE. The dominant pricing model remains contract-based long-term offtake, especially for refineries seeking stable supply. Price differentiation stems from quality grade and geographic delivery cost, with premium formulations commanding higher prices. Pricing softness reflects persistent feedstock price volatility, particularly for ethanol. Refineries are the least price-sensitive buyers due to regulatory compliance, while smaller blenders exhibit higher price sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with specific feedstock suppliers for bio-based oxygenates. Geographic supply concentration for MTBE relies heavily on China and Saudi Arabia, leveraging their petrochemical complexes. Raw material dependencies include corn for ethanol, and natural gas or isobutylene for MTBE production. Logistics chokepoints, particularly for ethanol's hygroscopic nature, represent a structural risk. Distribution runs through direct sales channels for large-volume refinery contracts and specialized distributors for regional markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with the US EPA's reformulated gasoline program driving sustained demand. Regulatory shifts continually reshape product specifications and market access.
For Market Incumbents: Deploy portfolio diversification into bio-based alternatives to mitigate long-term EV substitution risk. Incumbents should secure long-term feedstock contracts to stabilize margins against commodity price volatility. Invest in specialized production capabilities for high-purity ethers, targeting premium fuel applications in demanding automotive markets. Strategic partnerships with sustainable aviation fuel developers can open new growth avenues.
For New Entrants and Emerging Players: Specialized distributors offer a clear entry point for new entrants targeting niche applications. Focus on developing bio-ethers as blendstocks for sustainable aviation fuel, capitalizing on the aviation industry's decarbonization goals. The premium fuel segment in Europe, with its demand for superior anti-knock properties, represents a penetrable market. Emphasize sustainability certifications and performance attributes as a go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for specialty chemical producers because compliance fragmentation creates regional market opportunities. Long-term viability for oxygenate investments spans a 5-10 year window, driven by persistent regulatory mandates and emerging SAF demand. Target acquisition archetypes include mid-sized firms with proprietary bio-ether technologies or strategic logistical assets in high-growth regions. The signal to watch is increasing investment in dedicated SAF blending infrastructure by major refiners.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Bio-ethers | This expands supply for sustainable aviation fuel, addressing emerging decarbonization mandates. |
| Long-term Supply Agreement with Refiners | This secures stable demand for commodity oxygenates, underpinning production scale and market share. |
| Joint Venture for Feedstock Sourcing | This mitigates raw material price volatility, enhancing margin stability for oxygenate producers. |
| Green Manufacturing Transition | This aligns production with EU Green Deal objectives, attracting environmentally conscious buyers. |
| Product Development for High-Purity Ethers | This addresses engine efficiency demands in the European automotive market, capturing premium value. |
Research Approach
Bottom-up gasoline additive modeling reconciled against top-down oxygenate production tracking forms the analytical core of this study. Primary interviews with refinery procurement leads, chemical plant managers, fuel distributors, and automotive engineers provided qualitative insights. Secondary validation drew from US EPA reports, EU Renewable Energy Directive documents, China's GB standards, and global trade data. This approach ensures robust triangulation.
An input-output matrix underpins the forecast framework, modeling volume and value across the analysis window. Segmentation dimensions include product type, application, end-user, distribution channel, and regional regulatory clusters. Compound annual growth rates were derived from historical trends and projected market drivers. Key industry-specific inputs cover global vehicle fleet growth, biofuel blending mandates, and SAF production targets.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to electric vehicle adoption rates and feedstock price volatility. Forecasts reflect assumptions on regulatory stability and technological advancements. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
United Arab Emirates Fuel Station Market
Fuels
South America Commercial Aircraft Aviation Fuel Market
Fuels
Global Wood Gas Generator Market
Fuels
Marine Fuel Optimization Market
Fuels
Wood Pellet Market
Fuels
China LNG Bunkering Market
Fuels
Gasoline Market
Fuels
LPG Vaporizer Market
Fuels
Japan Bunker Fuel Market
Fuels
Europe Firewood Market
Fuels
Global Industrial Burner Market
Fuels
Petroleum Fuel Dyes Sales Market
Fuels
Commercial Aircraft Aviation Fuel Market
Fuels
Iso-Octane Market
Fuels
Global Fuel Ethanol Market
Fuels
Middle-East and Africa Bunker Fuel Market