
 North America Electric Vehicle Charging Cable Market | 2026-2036
North America Electric Vehicle Charging Cable Market Size, Share, and Industry Trends Forecast 2026-2036
North America Electric Vehicle Charging Cable Market Analytics
Software-defined power management is decoupling cable hardware from charging network control, turning standalone conductors into subscription-linked infrastructure nodes. TE Connectivity Ltd. leverages its sensor-integrated cable architectures to capture recurring diagnostics revenue across Electrify America and EVgo networks. HUBER+SUHNER AG anchors North American DC fast charging deployments through its specialized high-amperage cooling technology. Leoni AG competes on manufacturing scale, sustaining cost advantages in Level 2 residential cable production.
North America electric vehicle charging cables are shielded conductor assemblies rated for continuous current loads from 32 amperes in Level 1 configurations to over 500 amperes in liquid-cooled ultra-fast systems, engineered to withstand thermal cycling and mechanical flexing across thousands of plug-in events. CCS Combo 1 dominates connector architecture across non-Tesla networks, with Type 1 legacy stock declining as automakers standardize on the combined charging system. DC Fast Charging cable assemblies command premium positioning due to integrated thermal management and active cooling requirements, while residential Level 2 segments compete on copper commodity exposure and installation labor efficiency.
NHTSA Federal Motor Vehicle Safety Standard No. 305 governs high-voltage isolation in charging cables, while Underwriters Laboratories UL 2251 and CSA Group C22.2 No. 282 shape product access across the United States and Canada respectively. Transport Canada's EV infrastructure investment program and state-level zero-emission vehicle mandates in California, New York, and Quebec are tightening cable durability and interoperability specifications. Stakeholders must monitor emerging megawatt charging system standards and their implications for conductor gauge, thermal management, and connector lifecycle design.
Market Dynamics
Fleet electrification mandates across California, New York, and Quebec are compressing procurement cycles for DC fast charging infrastructure, forcing cable manufacturers to accelerate certification timelines while scaling liquid-cooled production lines.
Growth Catalysts
- Zero-Emission Vehicle Mandates:California's Advanced Clean Trucks regulation and Quebec's zero-emission vehicle standard obligate commercial fleet operators to electrify, driving concentrated demand for high-amperage charging cable assemblies.
- NHTSA-Transport Canada Harmonization:Unified EV supply equipment standards between the United States and Canada are collapsing dual-certification costs, accelerating cross-border deployment of CCS Combo 1 cable systems.
- Copper-Nickel Conductor Alloys:Advanced metallurgy is extending thermal cycling lifespans in DC fast charging cables, reducing replacement frequency for highway corridor operators.
Market Restraints
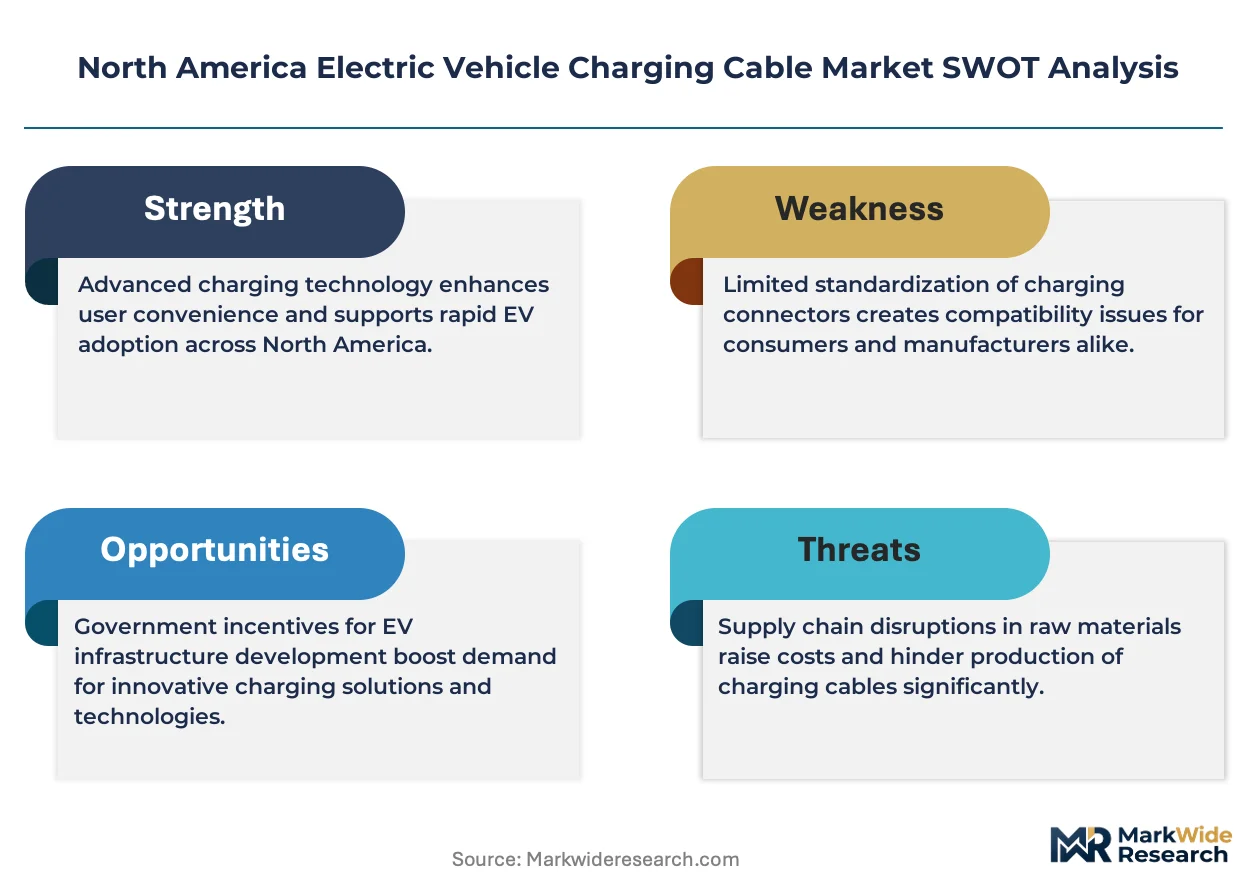
- Copper Price Volatility:Raw material exposure in conductor production compresses margins unpredictably, forcing cable assemblers to absorb commodity swings or pass costs to charging network operators.
- Supply Concentration in Ontario Manufacturing:Insulated cable production clusters in the Toronto-Waterloo corridor, creating vulnerability to localized labor disruptions or logistics bottlenecks.
- CCS-NACS Connector Divergence:Competing charging interface standards fragment inventory requirements, forcing cable manufacturers to maintain dual production lines without guaranteed volume for either.
Strategic Opportunities
- Texas Triangle Commercial Corridors:Underpenetrated interstate freight routes connecting Dallas, Houston, and San Antonio present whitespace for megawatt-capable cable deployment ahead of federal corridor electrification funding.
- Vehicle-to-Grid Integration:Bidirectional charging protocols are creating demand for reinforced cable architectures capable of sustained reverse power flow, opening premium product tiers.
- IRA Manufacturing Tax Credits:Domestic content incentives under the Inflation Reduction Act are subsidizing North American cable assembly reshoring, reducing landed cost disadvantages against Asian competitors.
Industry Challenges
- High-Voltage Safety Certification Bottlenecks:UL 2251 and CSA C22.2 No. 282 testing queue backlogs extend product launch timelines by six to nine months, freezing working capital in pre-certified inventory.
- Liquid Cooling System Integration Complexity:Thermal management module compatibility across charger OEM platforms requires proprietary adapter engineering, fragmenting cable design standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Electric Vehicle Charging Cable Market |
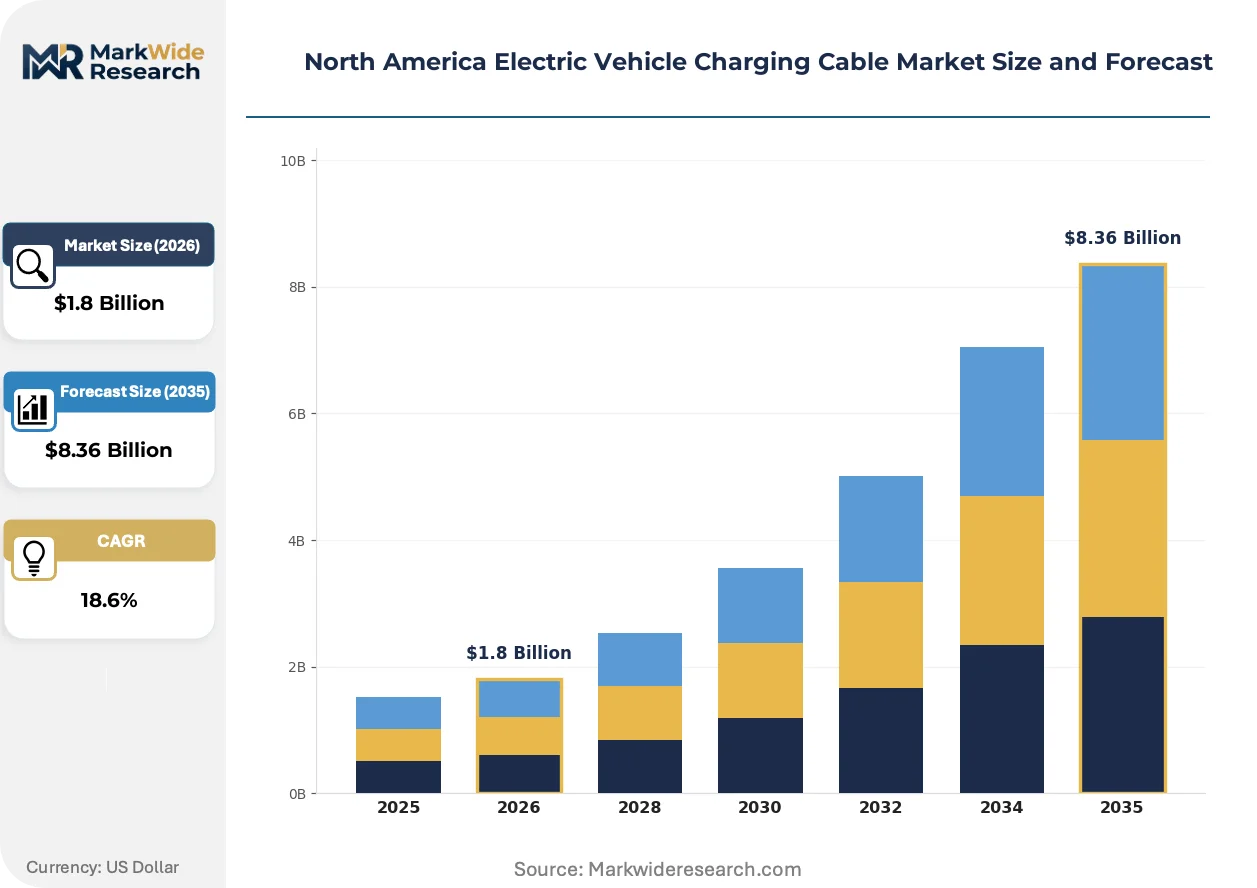
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Type 1, Type 2, CHAdeMO, CCS Combo 1, Tesla Charging Level: Level 1, Level 2, DC Fast Charging, Ultra-Fast Charging Application: Residential Charging, Commercial Charging, Fleet Charging, Public Charging Stations End User: Individual Consumers, Commercial Operators, Government Agencies, Fleet Owners, Property Managers |
| Companies Covered | HUBER+SUHNER AG, TE Connectivity Ltd., Leoni AG, Aptiv PLC, Nexans S.A., Sumitomo Electric Industries, Ltd., Sinbon Electronics Co., Ltd., Coroplast Fritz Müller GmbH & Co. KG, Philatron Wire & Cable, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Electric Vehicle Charging Cable Market Evolving Landscape
Software-defined charging architectures are decoupling power electronics from passive cable components, transforming hardware suppliers into recurring-revenue service nodes. This shift compresses traditional equipment margins while opening diagnostics and predictive maintenance revenue streams.
Silicon carbide power semiconductors are unifying thermal management and power conversion functions within charging cable controllers. Fleet operators across the I-5 corridor from San Diego to Seattle are adopting SiC-integrated cable systems to reduce cooling loop complexity. This unification is compressing the physical footprint of DC fast charging dispensers, enabling higher-density installation in urban retail parking structures.
The Inflation Reduction Act's domestic content bonus credit is reshaping supply chain geography for EV charging equipment. Cable assemblers must now source North American copper and domestic connector housings to qualify charging station deployments for full tax credits. Heavy-duty fleet charging projects in Illinois and Ohio are most affected, with developers requalifying suppliers mid-procurement to secure financing.
Charging network operators are consolidating procurement through master service agreements with integrated hardware-software vendors. Independent cable manufacturers face exclusion from direct bidding, forced instead to supply through white-label arrangements with charging system integrators. This consolidation is most visible in Electrify America's national network refresh and EVgo's fleet-focused hub deployments across the Southwest.
North America Electric Vehicle Charging Cable Market Segmentation
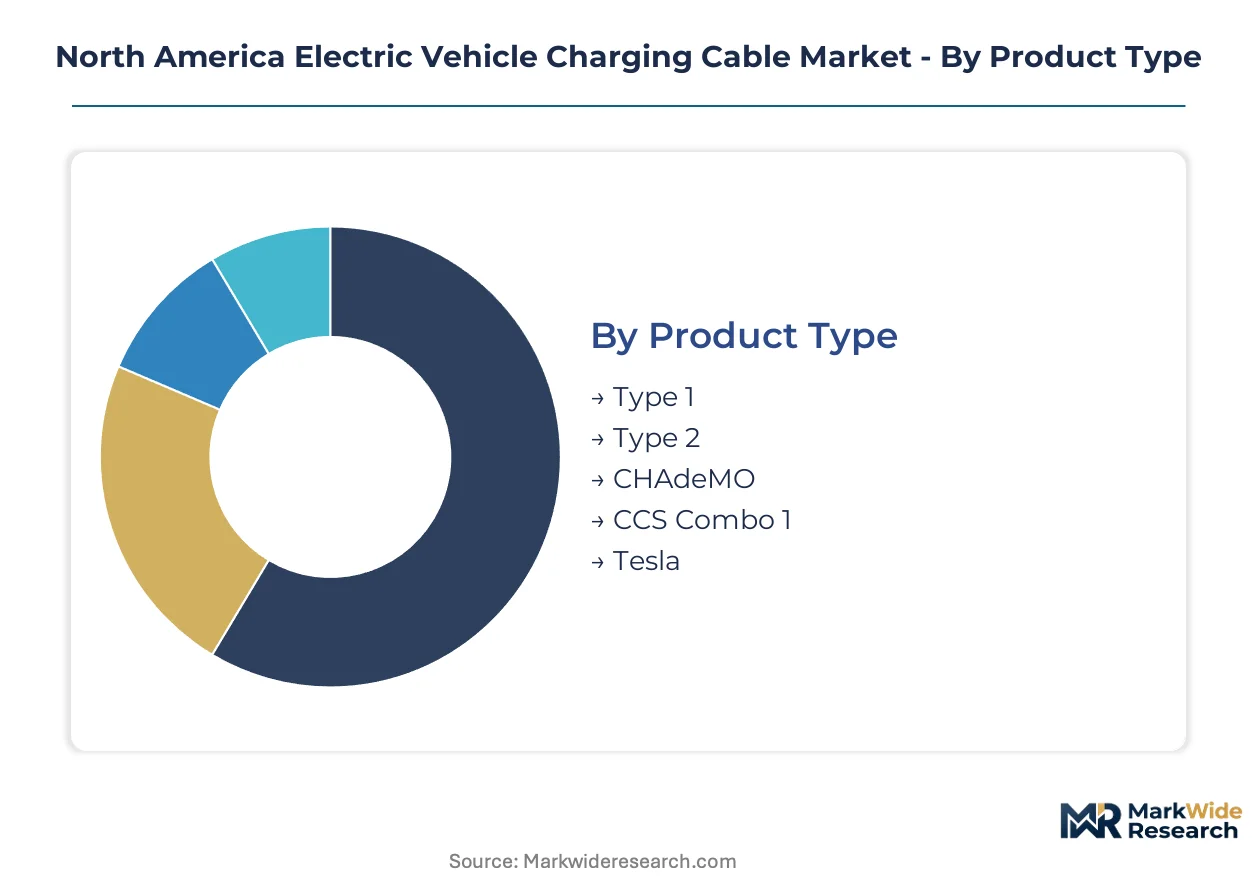
Charging cable segmentation in North America reflects competing connector standards, divergent power architectures, and distinct procurement patterns across residential, commercial, and fleet use cases. Each dimension shapes manufacturing scale, certification requirements, and margin structures differently.
Product Type:
Connector architecture determines interoperability boundaries across charging networks and automaker ecosystems.
- Type 1:Legacy single-phase connector rated for Level 1 and Level 2 charging up to 80 amperes. Demand concentrates in early-model EV retrofits and secondary vehicle markets across the US Midwest, constrained by CCS standardization mandates in California and Quebec.
- Type 2:European-standard three-phase connector with limited North American deployment, primarily serving imported commercial vehicle fleets and cross-border corridor equipment in Ontario. IEC 62196 compliance requirements fragment procurement volumes.
- CHAdeMO:Japanese DC fast charging standard supporting bidirectional power flow. Nissan Leaf fleet operators in Oregon and Washington sustain replacement cable demand, though new installations have stalled outside existing corridor commitments.
- CCS Combo 1:Combined charging system integrating AC and DC pins into a single connector housing. Electrify America, EVgo, and ChargePoint network expansions across Texas and California drive concentrated procurement of liquid-cooled CCS cable assemblies rated for 350kW+ delivery.
- Tesla:Proprietary connector architecture transitioning to NACS standard designation. Supercharger network licensing agreements with Ford, General Motors, and Rivian are forcing third-party cable manufacturers to engineer NACS-compatible variants for non-Tesla vehicle integration.
CCS Combo 1 leads on scale; NACS leads on momentum.
Charging Level:
Power delivery tiers segment manufacturing by thermal management intensity and conductor gauge requirements.
- Level 1:Standard 120V residential charging delivering 1.4 to 1.9 kilowatts through 16-ampere conductors. Apartment dwellers in dense urban markets like New York City and Toronto sustain steady replacement demand for damaged or degraded portable cables.
- Level 2:240V infrastructure delivering 3.3 to 19.2 kilowatts, dominating workplace and multi-unit dwelling installations. Property managers across Florida and Arizona are standardizing on 48-ampere hardwired configurations to maximize available electrical capacity.
- DC Fast Charging:Direct current systems bypassing onboard converters, delivering 50 to 350 kilowatts. Highway corridor operators along I-95 and I-80 are prioritizing 150kW CCS installations to minimize grid interconnection costs while serving current-generation EVs.
- Ultra-Fast Charging:Liquid-cooled systems exceeding 350 kilowatts toward megawatt capability. Prototype deployments at Texas Triangle freight hubs and California port facilities are testing 500-ampere conductor architectures for heavy-duty electric truck compatibility.
Level 2 dominates installation volume; Ultra-Fast commands the steepest expansion trajectory.
Application:
Use case segmentation determines duty cycle intensity and corresponding durability specifications.
- Residential Charging:Single-family home and garage installations with intermittent daily use. Homeowners in suburban Phoenix and Dallas markets are upgrading from portable Level 1 cables to wall-mounted Level 2 units, driving replacement cycle compression.
- Commercial Charging:Workplace, retail, and hospitality installations serving employee and customer vehicles. Corporate campus operators in Seattle and Austin are procuring dual-port dispensers with integrated cable management systems to reduce vandalism and weather exposure.
- Fleet Charging:Depot-based infrastructure for delivery, utility, and municipal vehicle operations. Amazon and UPS electrification commitments in Illinois and Ohio are forcing cable manufacturers to engineer 24/7 duty cycle products with predictive thermal monitoring.
- Public Charging Stations:Curbside, highway, and destination infrastructure serving transient users. NEVI-funded corridor projects across Montana and Wyoming are specifying armored cable jackets and retractor mechanisms to survive extreme temperature cycling and user abuse.
Fleet Charging leads on contract value; Public Charging Stations lead on federal funding access.
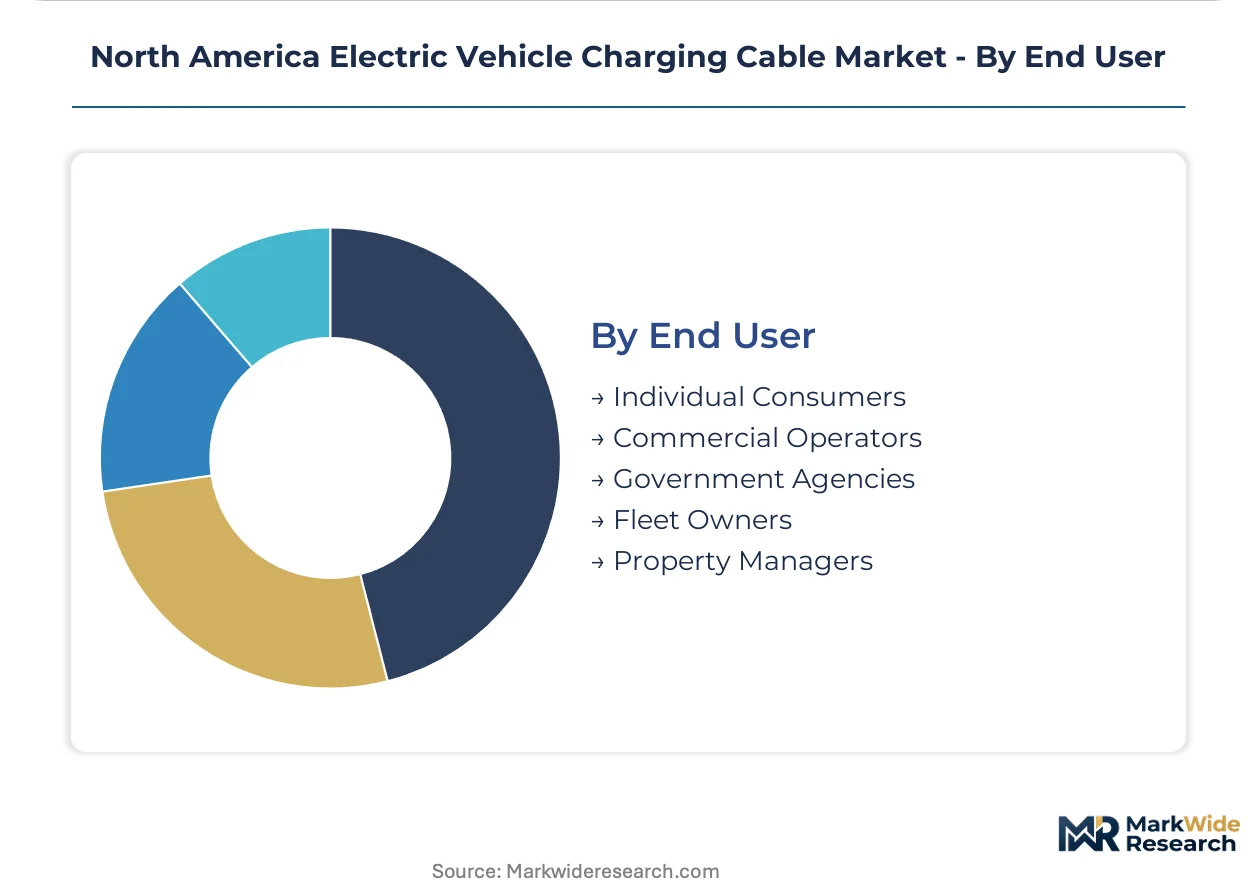
End User:
Procurement authority and volume scale diverge sharply across customer categories.
- Individual Consumers:Retail purchasers selecting replacement or upgrade cables through automotive dealerships and e-commerce channels. California ZEV mandate compliance programs subsidize Level 2 equipment purchases, inflating price sensitivity for unsubsidized accessories.
- Commercial Operators:Retail chains, employers, and real estate investment trusts installing customer-facing charging. Grocery and pharmacy chains across the US Southeast are consolidating procurement through national facility management contracts, squeezing independent cable suppliers.
- Government Agencies:Municipal, state, and federal entities deploying public infrastructure. NEVI formula funding requires Buy America-compliant cable assemblies, restricting supplier pools to domestic manufacturers with certified copper sourcing.
- Fleet Owners:Logistics, utility, and transit operators electrifying commercial vehicle pools. Waste management and postal service electrification timelines in New York and Quebec are compressing DC fast charging cable delivery schedules.
- Property Managers:Multi-unit dwelling operators retrofitting parking structures for tenant EV access. Condominium associations in Vancouver and Miami are navigating split-incentive problems between owners and renters, slowing Level 2 deployment decisions.
Fleet Owners lead on volume concentration; Government Agencies lead on compliance stringency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States dominates procurement volume for DC fast charging cable assemblies, while Canada accelerates cross-border standardization through Transport Canada-NHTSA harmonization efforts. Mexico's manufacturing corridor is emerging as a cable assembly sourcing node for North American charging infrastructure deployment.
United States
Fleet electrification mandates in California, New York, and Illinois are compressing delivery timelines for liquid-cooled cable systems rated above 350 amperes. NHTSA Federal Motor Vehicle Safety Standard No. 305 governs high-voltage isolation requirements, while IRA domestic content bonuses reshape supplier qualification criteria. The Texas Triangle corridor connecting Dallas, Houston, and San Antonio is attracting megawatt-capable cable prototypes for heavy-duty freight electrification.
Canada
Quebec's zero-emission vehicle standard and Ontario's EV manufacturing incentives are driving synchronized demand for CCS Combo 1 cable assemblies. Transport Canada's infrastructure investment program tightens durability specifications for public charging deployments. The Toronto-Waterloo corridor anchors insulated cable production, creating concentrated supply exposure to localized logistics disruptions.
Mexico
Nearshoring incentives under USMCA are positioning Baja California and Nuevo León as cable assembly export bases for US charging network operators. Mexican federal energy regulators are streamlining grid interconnection standards for cross-border corridor projects. The Tijuana-Mexicali manufacturing zone is scaling production of Level 2 residential cables for Southwest US markets.
North America Electric Vehicle Charging Cable Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated hardware-software vendors capturing direct procurement relationships from charging network operators. The vendor base organizes around three archetypes: sensor-integrated cable architects, liquid-cooled high-amperage specialists, and scale-driven residential cable producers. Consolidation pressures are intensifying as master service agreements concentrate purchasing power, while domestic content requirements under IRA tax credits force geographic repositioning of assembly operations.
Within the premium-tier vector, TE Connectivity Ltd. and HUBER+SUHNER AG exemplify divergent strategic positioning. TE Connectivity represents the sensor-integrated archetype, occupying a position where cable hardware links to recurring diagnostics revenue streams. HUBER+SUHNER AG anchors the liquid-cooled specialization segment, with Swiss-based engineering heritage visible in its corporate designation. Leoni AG sits within the scale-driven tier, its German AG structure signaling manufacturing volume orientation. These three entities collectively illustrate how connector architecture expertise, thermal management specialization, and production scale define competitive positioning boundaries.
| Leading Market Players |
|---|
| HUBER+SUHNER AG |
| TE Connectivity Ltd. |
| Leoni AG |
| Aptiv PLC |
| Nexans S.A. |
| Sumitomo Electric Industries, Ltd. |
| Sinbon Electronics Co., Ltd. |
| Coroplast Fritz Müller GmbH & Co. KG |
| Philatron Wire & Cable |
| Others |
Value Network & Pricing Analysis
Fleet procurement consolidation under NEVI funding requirements is forcing cable manufacturers to absorb copper commodity swings while qualifying domestic content for tax credit eligibility, compressing margin structures across Tier 1 and Tier 2 supplier tiers. This demand-side pressure cascades into supply chain reconfiguration as assemblers reshore production to capture IRA bonuses, fragmenting historical cost advantages from Asian manufacturing clusters.
Pricing Analysis
Capacity additions in Mexico and the US Southeast are reshaping price floors for Level 2 residential cables while liquid-cooled DC fast charging assemblies maintain premium positioning. Three-tier pricing structure across megawatt-capable, standard DC fast, and Level 2 residential levels reflects UL 2251 certification grade and copper gauge specifications. Cost compression in residential tiers is intensifying because of commodity-linked contract structures, with fleet operators showing least price sensitivity due to total-cost-of-ownership procurement frameworks.
Supply Chain Analysis
UL 2251 and CSA C22.2 No. 282 certification gating concentrates qualified supply among Ontario, Michigan, and Baja California assembly operations. Copper conductor and liquid cooling module sourcing draws from Chilean mining operations and German thermal management specialists respectively. Single-source vulnerability in high-amperage connector housings creates exposure to automotive Tier 1 allocation priority shifts. Distribution runs through charging system integrators holding master service agreements with Electrify America and EVgo network operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where NHTSA-Transport Canada harmonization on EV supply equipment standards is accelerating cable certification demand across cross-border corridor deployments.
For Market Incumbents: Deepen backward integration into North American copper refining to secure IRA domestic content qualification and defend margin position against Mexican nearshoring competitors. Accelerate sensor-integrated cable architectures to capture recurring diagnostics revenue streams as charging networks consolidate procurement through hardware-software bundles. For New Entrants and Emerging Players: Enter via Texas Triangle freight corridor deployments where megawatt-capable cable demand precedes established supplier lock-in. Target underpenetrated heavy-duty fleet charging specifications with NACS-compatible liquid-cooled assemblies as Ford and Rivian Supercharger integration timelines create specification windows. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale cable assemblers possessing UL 2251 pre-certification inventory and qualified Mexican production footprints. Long-term viability hinges on megawatt charging system standard adoption curves. The signal to watch is NEVI funding disbursement velocity through state transportation departments as inflection indicator for 2025-2030 deployment cadence.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Content Qualification | IRA tax credit compliance reshapes supplier geography toward Michigan and Ontario manufacturing clusters. |
| Liquid Cooling System Integration | Thermal management unification with silicon carbide controllers reduces dispenser footprint for urban retail installations. |
| NACS Connector Engineering | Proprietary Tesla architecture licensing creates specification divergence requiring dual production line investment. |
| Predictive Diagnostics Platform | Sensor-embedded cables transform hardware vendors into recurring-revenue service nodes for fleet operators. |
| NEVI Corridor Certification | Federal funding compliance accelerates UL 2251 testing queue positioning for highway infrastructure suppliers. |
Research Methodology
Bottom-up fleet operator procurement modeling reconciled against top-down charging network deployment tracking forms the analytical core of this study. Primary interviews with EV charging infrastructure procurement managers, cable manufacturing operations directors, NHTSA regulatory affairs specialists, and utility grid interconnection planners were validated against secondary sources including FERC interconnection filings, NEVI funding disbursement records, UL certification databases, and copper commodity exchange data.
Input-output matrices map connector architecture, charging level, and application segment demand against production capacity by qualified manufacturing geography across the projection horizon. CAGRs derive from deployment trajectory modeling weighted by state-level ZEV mandate stringency and fleet electrification commitment timelines. Forecast inputs incorporate silicon carbide adoption curves and megawatt charging system standard development progress.
Inputs from NHTSA rulemaking dockets and state transportation department NEVI plans were available through the study window; gaps in proprietary fleet operator procurement timelines introduce uncertainty bands around near-term volume assumptions. Forecasts reflect documented assumptions on copper price stabilization and certification queue clearance rates. A model refresh is warranted upon material change in IRA domestic content bonus credit interpretation or NACS standard adoption velocity among non-Tesla automakers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
APAC Electric Vehicle Charging Station Market
Electric Vehicle Charging
EV Charging Station Market
Electric Vehicle Charging
Sweden Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Global EV Charger Market
Electric Vehicle Charging
Copper in Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
DC Chargers Market
Electric Vehicle Charging
Electric Vehicle Supply Equipment (EVSE) Market
Electric Vehicle Charging
Europe Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
Electric Vehicle Coin Charging Station Market
Electric Vehicle Charging
Electric Bus Charging Infrastructure Market
Electric Vehicle Charging
North America Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Solar Charge Controller Market
Electric Vehicle Charging
South America Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Asia-Pacific Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
Electric Vehicle Charger Market
Electric Vehicle Charging
Electric Vehicle Charging System Market