
 Wood Pellet Market | 2026-2036
Wood Pellet Market Size, Share, and Industry Trends Forecast 2026-2036
Wood Pellet Market Intelligence
A long-standing balance between residential heating and industrial energy users is unwinding, with large-scale power generation buyers now commanding the market's direction. Drax Group dominates the European utility-scale segment through its large power station conversions in the UK. Enviva Partners leverages its extensive production and logistics network in the southeastern United States to supply this transatlantic trade.
Wood pellets are a biofuel made from compressed sawdust and related industrial wood waste. These pellets are standardized by density and low moisture content, typically below 10%, to ensure consistent combustion. Industrial pellets for power generation constitute the largest application segment, driven by policy-supported coal-to-biomass conversions. Within product types, premium pellets for residential heating command higher per-ton prices but represent a smaller volume compared to their industrial counterparts.
The EU's Renewable Energy Directive (RED) and national subsidy schemes in countries like the United Kingdom and Denmark create stable demand from utilities. In the United States, the EPA's New Source Performance Standards influence residential stove efficiency, while ISO 17225 provides a global benchmark for pellet classification. Producers must now navigate increasingly stringent sustainability and carbon accounting criteria to maintain market access and secure long-term offtake agreements.
Market Dynamics
The market's central dynamic is the policy-driven consolidation of demand within the utility-scale power generation sector. Government mandates for renewable energy in Europe are reorienting supply chains toward large, long-term contracts, eclipsing traditional residential heating markets.
Growth Catalysts
- Renewable Energy Mandates:The EU's Renewable Energy Directive (RED) creates durable demand for biomass in power generation, specifically for co-firing applications in converted coal plants.
- Standardization Frameworks:Global standards like ISO 17225 classify fuel by properties such as ash content, which facilitates reliable international trade.
- Coal Phase-Out Policies:National commitments in countries like the UK to exit coal power directly stimulate investment in biomass conversion projects, securing a key end-use.
Market Restraints
- Feedstock Cost Volatility:Producer margins are exposed to price fluctuations for raw materials like sawdust and forestry residues, which are also sought by panelboard manufacturers.
- Supply Chain Bottlenecks:Heavy reliance on production from the southeastern United States creates logistical vulnerabilities and potential price shocks from port congestion.
- Sustainability Verification Costs:Strict sustainability and carbon accounting criteria under EU rules impose significant compliance and auditing costs for market access.
Strategic Opportunities
- Asian Market Entry:Growing policy support for biomass co-firing in Japan and South Korea presents an opportunity for producers to diversify sales beyond European markets.
- Advanced Biofuel Feedstock:Torrefaction technology roasts biomass to create energy-dense "black pellets," offering a pathway to a higher-value, water-resistant fuel.
- Decentralized Energy Systems:Small-to-medium scale combined heat and power (CHP) systems for commercial buildings open a new demand segment.
Industry Challenges
- Logistical Capex Intensity:Establishing dedicated export terminals and specialized bulk carriers for industrial-scale trade requires substantial capital investment with extended payback periods.
- Navigating Certification Schemes:Producers face complexity in securing multiple sustainability certifications, each with unique chain-of-custody and greenhouse gas reporting rules.
- Public Scrutiny of Carbon Claims:The industry confronts debate on the carbon neutrality of forest biomass, creating reputational risk and potential policy shifts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood Pellet Market |
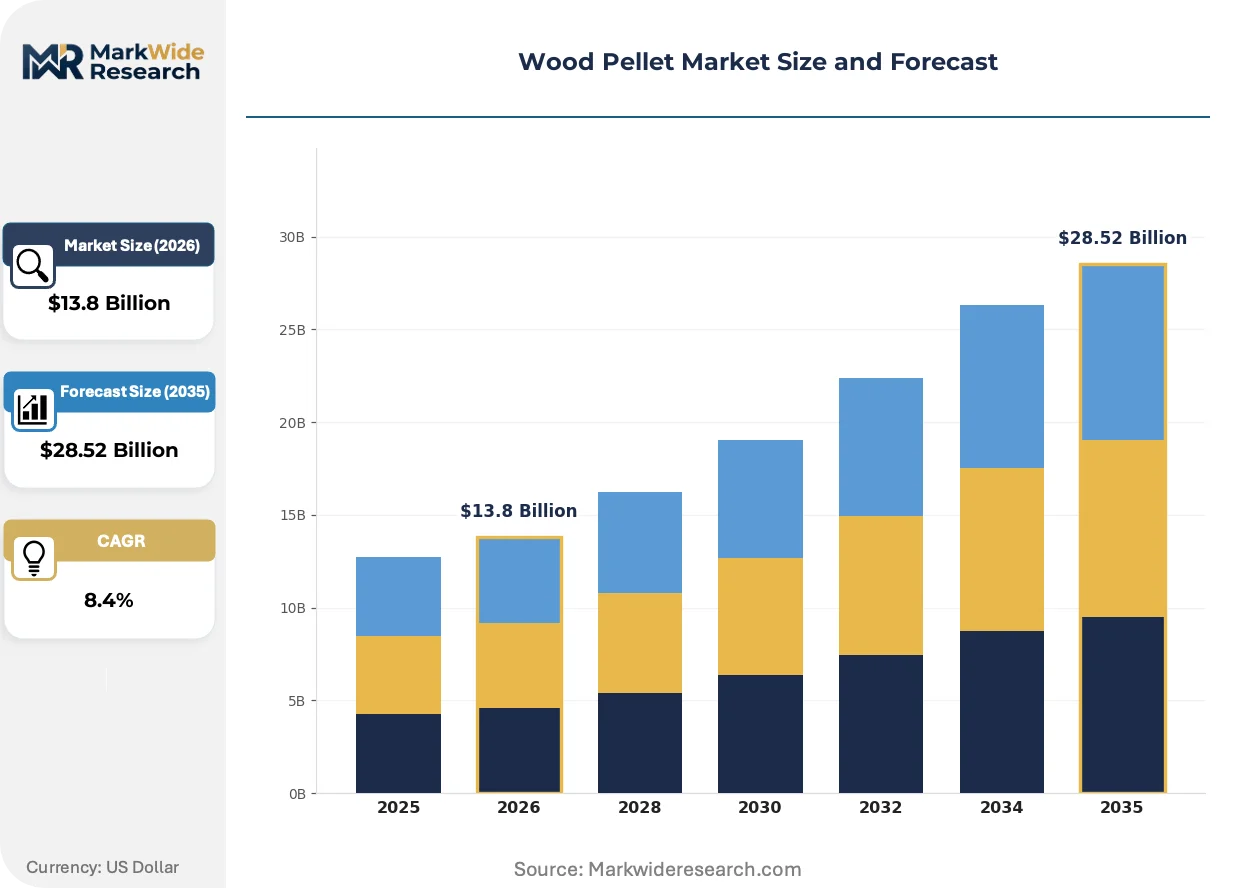
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Premium Pellets, Standard Pellets, Industrial Pellets, Stove Pellets Application: Residential Heating, Commercial Boilers, Power Generation, Agricultural Uses End User: Households, Manufacturing Plants, Energy Producers, Farming Operations Packaging Type: Bulk Bags, Paper Bags, Plastic Bags, Mini Sacks |
| Companies Covered | Enviva Partners, Drax Group, Pinnacle Renewable Energy Group, German Pellets GmbH, AS Graanul Invest, Lignetics, Segezha Group, The Westervelt Company, Fram Renewable Fuels, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood Pellet Market Strategic Shifts & Innovations
The market’s maturation is defined by a shift from a fragmented fuel source to a standardized industrial commodity. This transition drives innovations in process control, creates new regulatory pressures, and alters how supply contracts are structured.
Advanced sensor arrays and integrated process analytics provide real-time monitoring of production variables. Industrial-scale producers are adopting these systems to ensure compliance with buyer specifications and standards like ISO 17225. This technology is miniaturizing the acceptable tolerance for variations in moisture and density, yielding a more uniform fuel.
In the United States, the EPA’s New Source Performance Standards impose stricter emissions limits on residential biomass appliances. The regulation compels manufacturers to design more efficient pellet stoves that produce fewer particulates. This drives a preference for premium-grade pellets with low ash content in the North American residential market.
A shift away from spot-market transactions toward long-term, fixed-volume offtake agreements is occurring. This model favors large suppliers with dedicated logistics, marginalizing smaller producers who cannot meet multi-year volume guarantees. This purchasing behavior is most apparent in the transatlantic trade supplying European power stations.
Wood Pellet Market Segmentation
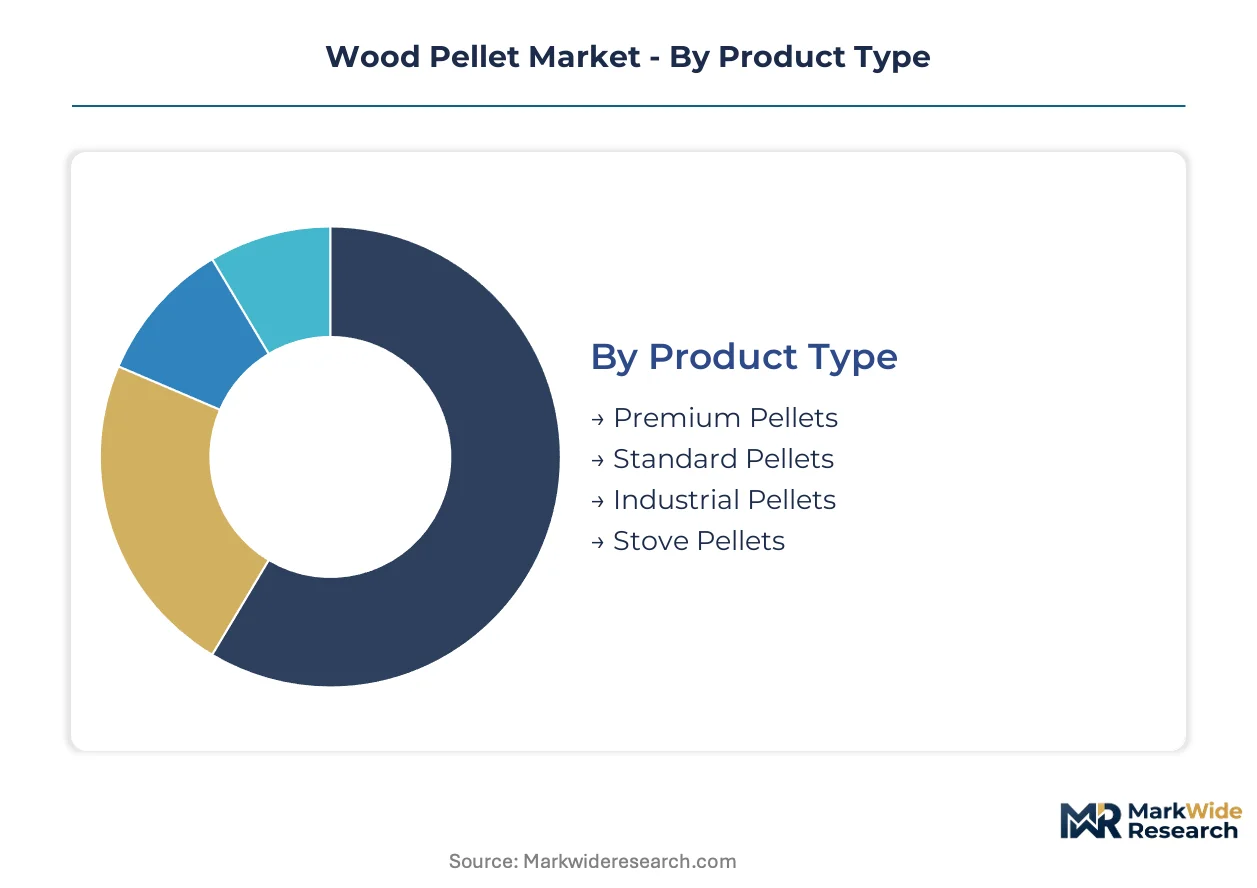
Understanding the distinct segments within the wood pellet market reveals how product specifications, end-use applications, and supply chain logistics converge. This granular analysis is essential for producers to align offerings with specific buyer requirements. Policy frameworks often target particular segments, further influencing market dynamics.
Product Type:
The distribution channels for wood pellets vary significantly based on their intended product type, influencing logistics and market access.
- Industrial Pellets:These high-volume pellets are typically produced to rigorous specifications for density and moisture, enabling efficient co-firing in large power plants. Demand concentrates heavily in European energy markets, driven by policy-supported coal-to-biomass conversions and long-term utility contracts.
- Premium Pellets:Designed for residential heating appliances, these pellets feature very low ash content and consistent dimensions for optimal combustion efficiency. North American residential markets exhibit strong demand, influenced by EPA's New Source Performance Standards for stove efficiency.
- Standard Pellets:These pellets meet general specifications for heating applications, offering a balance of quality and cost for various commercial and institutional users.
- Stove Pellets:Specifically sized for pellet stoves, these maintain consistent quality to prevent appliance damage and ensure reliable heat output for households.
By volume, Industrial Pellets lead the market. By growth pace, Premium Pellets are ahead.
Application:
Different end-user applications dictate specific pellet characteristics and procurement patterns across the wood pellet market.
- Power Generation:This segment utilizes large volumes of industrial-grade pellets for co-firing in converted coal power stations, demanding strict adherence to ISO 17225 standards. European utilities, notably in the United Kingdom and Denmark, drive this demand due to renewable energy mandates and coal phase-out policies.
- Residential Heating:Households use premium or stove pellets in dedicated appliances for space heating, prioritizing low ash content and consistent burn performance. Demand in the United States is shaped by EPA regulations on appliance efficiency and consumer preference for cleaner burning fuels.
- Commercial Boilers:Businesses and institutions use pellets in automated boiler systems for space heating and hot water, valuing consistent supply and competitive pricing.
- Agricultural Uses:Pellets serve as animal bedding, absorbents, or for heating agricultural facilities, requiring specific moisture and dust profiles.
Pricing differentiation between these application segments is pronounced, reflecting varied end-use requirements and scale of consumption.
End User:
Supply concentration patterns are significantly shaped by the scale and procurement sophistication of different end-user groups.
- Energy Producers:These large industrial entities, primarily power utilities, command substantial volumes through long-term offtake agreements, driving standardization and logistics infrastructure development. Drax Group in the UK exemplifies this segment, converting power stations to biomass and securing transatlantic supply.
- Households:Individual consumers purchase smaller volumes of packaged pellets for residential heating, emphasizing convenience, local availability, and ease of storage. Their purchasing decisions are often influenced by local retail networks and seasonal pricing fluctuations.
- Manufacturing Plants:Industrial facilities use pellets for process heat or combined heat and power systems, valuing consistent energy supply and sustainability credentials.
- Farming Operations:Agricultural businesses utilize pellets for heating barns or drying crops, focusing on cost-effectiveness and local sourcing to minimize transportation expenses.
Margin profiles vary substantially across end-user categories, influenced by volume commitments and sustainability compliance costs.
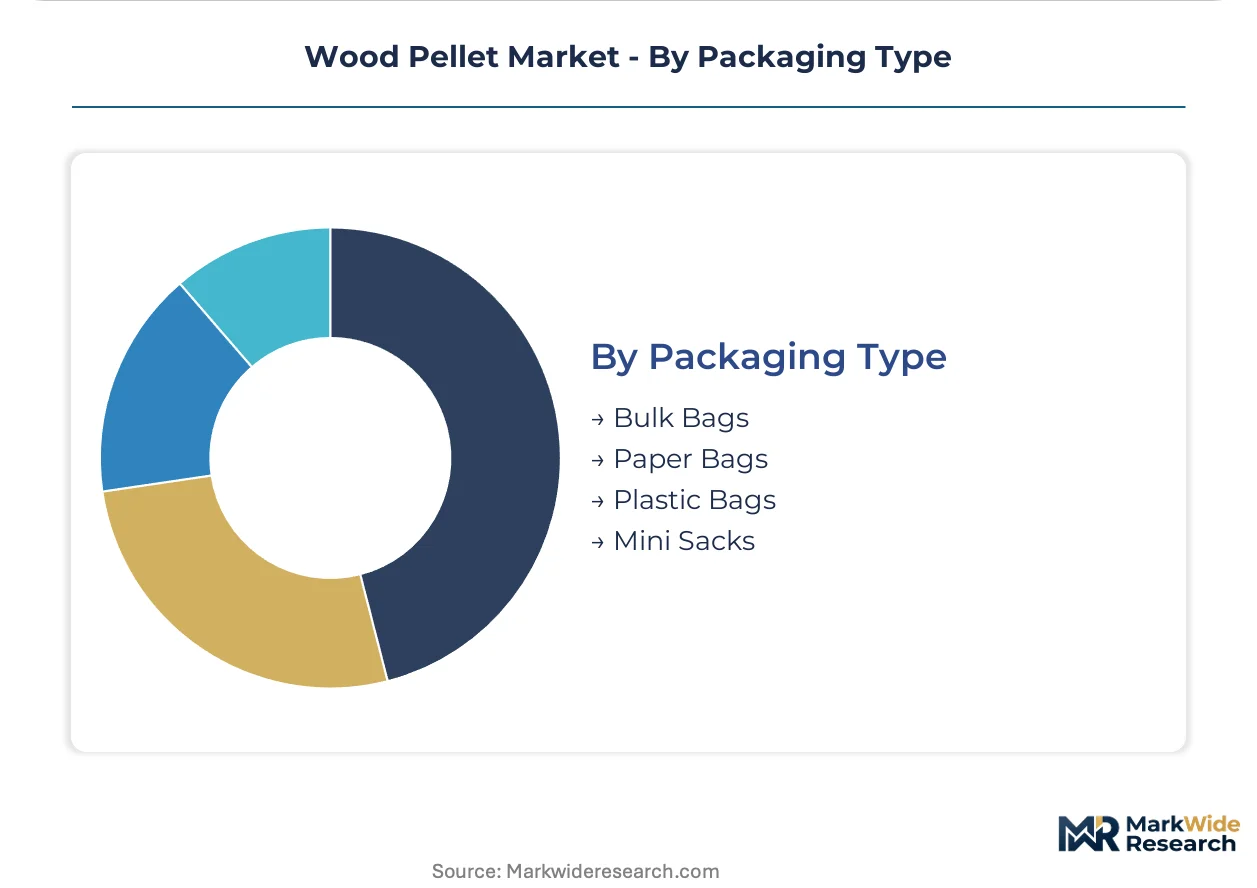
Packaging Type:
The cost tier of wood pellet delivery is heavily influenced by the chosen packaging type, impacting logistics and final consumer prices.
- Bulk Bags:These large industrial containers facilitate efficient transport and storage of high volumes of pellets, typically for utility-scale power generation or large commercial users. Their use minimizes handling costs and is critical for the transatlantic trade from the southeastern United States to Europe.
- Paper Bags:Commonly used for residential and smaller commercial markets, these packaging solutions offer convenience for transport and storage at the consumer level. Environmental considerations sometimes favor paper bags due to their recyclability and perceived sustainability.
- Plastic Bags:Offering moisture resistance and durability, plastic bags are prevalent in retail channels for residential heating pellets, protecting product integrity.
- Mini Sacks:Smaller, more manageable sacks cater to niche markets or consumers with limited storage space, often commanding a premium per unit weight.
The maturity of packaging solutions ranges from established industrial bulk handling to evolving retail-focused formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The wood pellet market's supply-side concentration heavily influences global distribution patterns. Production largely originates from the southeastern United States, driven by abundant forestry resources. This geographic focus creates a transatlantic trade route to European energy markets.
United Kingdom
Demand for wood pellets in the United Kingdom stems from its aggressive coal phase-out policies and renewable energy targets. The UK's Department for Energy Security and Net Zero (DESNZ) supports biomass conversions. Large-scale power stations, such as Drax in North Yorkshire, have converted units to co-firing biomass, securing substantial long-term supply agreements.
Denmark
Denmark's utility sector drives significant wood pellet consumption, aligned with its national renewable energy mandates. The Danish Energy Agency promotes biomass as a key component of its carbon reduction strategy. Power plants in cities like Copenhagen utilize industrial pellets for combined heat and power generation.
United States
The United States acts as a major production hub, particularly in its southeastern states, exporting industrial pellets to Europe. The Environmental Protection Agency (EPA) sets New Source Performance Standards influencing residential stove efficiency. Producers in states such as Georgia and Mississippi leverage extensive forestry resources for large-scale pellet manufacturing.
Japan
Japan is an emerging market for wood pellets, driven by policy support for biomass co-firing in its energy mix. The Ministry of Economy, Trade and Industry (METI) encourages renewable energy deployment to enhance energy security. Utilities in coastal regions are exploring biomass imports for power generation, diversifying their fuel sources.
South Korea
South Korea's energy transition policies are creating new demand for wood pellets, particularly for co-firing in existing power plants. The country's Renewable Portfolio Standard (RPS) incentivizes biomass use among energy producers. Port cities like Incheon are becoming key import hubs for industrial pellets to supply power generation facilities.
Wood Pellet Market Key Industry Players
Concentration sits with large-scale industrial producers and utility-backed suppliers in the wood pellet market. The market structure exhibits a tiered consolidation, with high-volume exporters dominating the transatlantic trade routes. Strategic archetypes include integrated producers managing vast forestry resources, specialized logistics providers ensuring efficient global transport, and regional residential suppliers focused on local distribution. Companies prioritize sustained capacity expansion and securing long-term offtake agreements to solidify their market share.
Within the utility-scale segment, Enviva Partners exemplifies a major producer with extensive logistics infrastructure, particularly in the United States, anchoring significant transatlantic supply. Drax Group, a UK-based energy producer, represents a substantial end-user, having converted large power stations to biomass and securing long-term supply. German Pellets GmbH, a German company, occupies a position among prominent European manufacturers, supplying both industrial and residential sectors across the continent. These entities underscore the market's reliance on large-scale production, efficient supply chains, and significant consumption from energy producers.
| Leading Market Players |
|---|
| Enviva Partners |
| Drax Group |
| Pinnacle Renewable Energy Group |
| German Pellets GmbH |
| AS Graanul Invest |
| Lignetics |
| Segezha Group |
| The Westervelt Company |
| Fram Renewable Fuels |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements lock in stable supply access for utilities and provide price visibility for large-scale wood pellet producers. This contract structure underpins the transatlantic trade routes, mitigating some inherent volatility.
Pricing Analysis
The EU's Renewable Energy Directive (RED) dictates the pricing tier structure for industrial wood pellets, supporting long-term, contract-based offtake models. Price differentiation stems from quality grade, with premium pellets commanding higher per-ton prices for residential use, and volume scale influencing industrial contracts. Pricing pressure stems from feedstock cost volatility, particularly for sawdust and forestry residues. Households purchasing smaller packaged volumes exhibit greater price sensitivity compared to energy producers with policy-mandated renewable targets.
Supply Chain Analysis
Extended lead times characterize the wood pellet supply chain, primarily due to transatlantic shipping from the southeastern United States to Europe. Geographic supply concentrates in the United States, which exports industrial pellets to European energy markets, notably the United Kingdom and Denmark. The market relies heavily on raw materials like sawdust and forestry residues. A structural risk involves logistics chokepoints, such as port congestion, which can disrupt supply flows. Distribution runs through bulk handling for industrial users and localized retail networks for residential consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
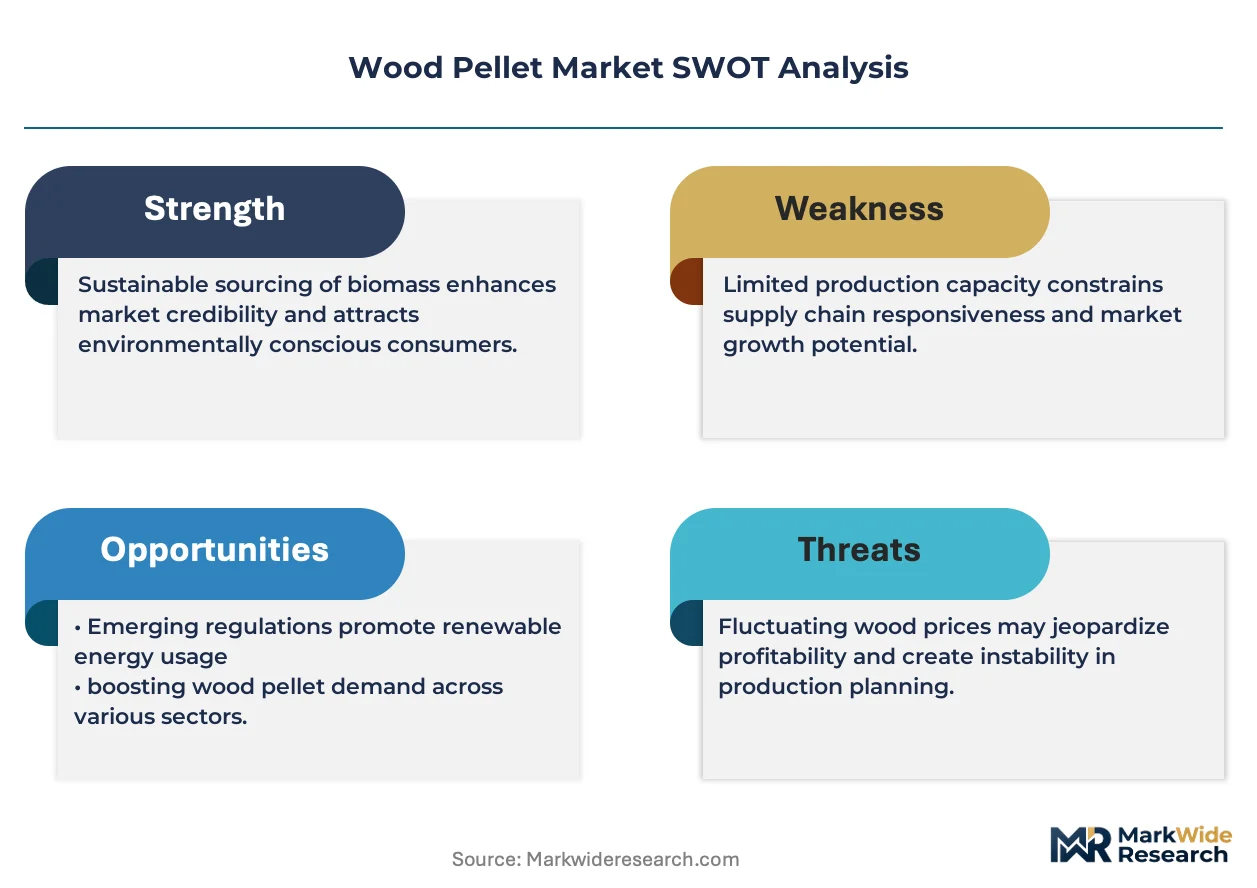
This market presents a defensive-moat story, primarily due to regulatory entrenchment from ambitious renewable energy mandates and high switching costs associated with power plant conversions.
For Market Incumbents: Shield market share by securing long-term offtake agreements with European utilities. Invest in robust sustainability certification and carbon accounting systems to navigate evolving EU regulations, countering public scrutiny of forest biomass claims. Expand vertical integration into forestry management to mitigate feedstock cost volatility and ensure consistent supply.
For New Entrants and Emerging Players: Anchor in niche segments or underserved geographies to build initial market traction. Japan and South Korea present white-space opportunities for biomass co-firing in power generation. Focus on advanced biofuel feedstock, such as torrefied pellets, to offer a higher-value, water-resistant product with superior energy density. Target decentralized energy systems for commercial buildings as a growth segment.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated producers with established production capacity and efficient logistics infrastructure, particularly those with a strong presence in the transatlantic trade. The long-term viability of the sector is supported by global decarbonization goals and stable policy frameworks. Watch for the expansion of renewable energy mandates in Asia as a key inflection indicator for new demand growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in US Southeast | Increases export volumes to meet growing European and Asian utility demand. |
| Long-term Offtake Agreements | Secures revenue streams and provides supply stability for power generators. |
| Green Certification Program Investment | Ensures market access in Europe and addresses sustainability concerns from regulators. |
| Torrefaction Technology Licensing | Develops higher-value black pellets for diverse applications and improved logistics. |
| Geographic Expansion into Asia | Diversifies sales channels and reduces reliance on the European energy market. |
Research Approach
Desk research of industry reports, government publications from the EU Green Deal and EPA, and company financial filings preceded structured interviews with utility procurement managers, pellet producers, logistics providers, and forestry experts. This approach combined primary insights with secondary validation, using both bottom-up and top-down triangulation to ensure data accuracy.
The analytical framework decomposed market variance across the analysis window, segmenting by product type (industrial, premium), application (power generation, residential heating), end user (energy producers, households), packaging type (bulk, bags), and regional regulatory frameworks. Compound annual growth rates were derived from historical data and projected market shifts. Key forecast inputs included renewable energy mandate targets and coal phase-out timelines.
Material uncertainties — geopolitical shifts, unforeseen technological breakthroughs, and changes in carbon accounting policies — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding policy stability and feedstock availability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Underground Coal Gasification Market
Fuels
Hydrogen Cylinder Market
Fuels
Global Charcoal Market
Fuels
LPG Tanker Market
Fuels
Middle East and Africa Compressed Natural Gas Dispenser Market
Fuels
No.2 Diesel Fuel Market
Fuels
Asia-Pacific Bunker Fuel Market
Fuels
LPG Vaporizer Market
Fuels
South America Defense Aircraft Aviation Fuel Market
Fuels
Anthracite Coal Mining Market
Fuels
Europe Firewood Market
Fuels
Global Fuel Ethanol Market
Fuels
Liquefied Helium Tanks Market
Fuels
Canada Coal Market
Fuels
Collapsible Fuel Tank Market
Fuels
India Liquified Petroleum Gas (LPG) Market