
 South America Commercial Aircraft Aviation Fuel Market | 2026-2036
South America Commercial Aircraft Aviation Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
South America Commercial Aircraft Aviation Fuel Market Analytics
Brazil's ANAC Resolution 934 is restructuring the cost-of-entry calculus for aviation fuel suppliers across the continent. Petroleo Brasileiro S.A. leverages its integrated refinery network to dominate domestic Jet A-1 distribution. Shell PLC anchors its position through dedicated fuel depot infrastructure at São Paulo Guarulhos. Repsol SA competes via specialized supply contracts with Latin American flag carriers.
Commercial aircraft aviation fuel encompasses refined petroleum products meeting strict thermal stability and freeze point specifications, primarily Jet A-1 with maximum freeze point of minus 47 degrees Celsius, formulated to power turbine engines under varying altitude and temperature conditions. Jet A-1 maintains structural leadership across South American commercial routes due to its universal engine compatibility and established infrastructure. Biofuel certification under ASTM D7566 represents the fastest-growing segment as carriers pursue ICAO Carbon Offsetting targets. Airlines constitute the dominant end-user channel, though cargo carriers exhibit accelerated uptake driven by e-commerce logistics expansion.
ANAC in Brazil, ENAP in Chile, and ICAO standards collectively govern fuel quality, storage safety, and emissions compliance across South American aviation corridors. These frameworks mandate sulfur content limits, hydration testing protocols, and traceability documentation that elevate operational costs while screening out informal suppliers. Stakeholders must monitor ICAO's evolving CORSIA eligibility criteria for sustainable aviation fuels to anticipate procurement shifts and infrastructure investment timing.
Market Dynamics
ANAC Resolution 934 is compressing supplier margins while accelerating infrastructure consolidation across Brazil's aviation fuel corridor. The regulation mandates sulfur content below 0.03 percent and traceability documentation that informal distributors cannot meet.
Growth Catalysts
- ICAO CORSIA eligibility expansion:Brazil's cargo carriers are retrofitting storage facilities to handle ASTM D7566-certified biofuel blends ahead of mandatory carbon offsetting phases.
- São Paulo-Guarulhos depot modernization:Dedicated Jet A-1 infrastructure investments are reducing turnaround times for narrow-body fleets serving the southeast aviation triangle.
- Andean corridor e-commerce logistics:Colombian and Peruvian cargo operators are expanding dedicated freighter routes, driving sustained uplift volume growth through Quito and Bogotá hubs.
Market Restraints
- Crude price volatility transmission:Jet fuel crack spreads swing with Brent benchmarks, compressing refinery margins and destabilizing long-term supply contracts for regional carriers.
- Refinery concentration risk:Petrobras controls over 80 percent of domestic Jet A-1 production capacity, creating single-source dependency for Brazilian airlines.
- Hydration testing protocol costs:ANAC-mandated Karl Fischer moisture analysis adds operational overhead that marginal suppliers cannot absorb, reducing market entry.
Strategic Opportunities
- Chilean ENAP biofuel blending mandate:Santiago's Arturo Merino Benítez International is positioning as a regional sustainable aviation fuel transhipment hub for Pacific routes.
- Direct airline-refinery offtake agreements:LATAM and Avianca are negotiating ten-year purchase commitments that bypass traditional distributor markups.
- Argentina's Vaca Muerta feedstock proximity:Neuquén basin condensate quality supports domestic Jet A-1 production, reducing import dependency for Buenos Aires Ezeiza operations.
Industry Challenges
- ASTM D7566 certification timeline compression:Biofuel pathway approvals require 18-24 month validation cycles that lag behind airline fleet renewal schedules.
- Legacy tank farm compatibility:Existing storage infrastructure across regional airports requires corrosion-resistant lining upgrades to handle fatty acid methyl ester blends.
- Specialized technician scarcity:Hydration testing and sustainable aviation fuel quality assurance protocols demand certified personnel that training programs have not yet scaled.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Commercial Aircraft Aviation Fuel Market |
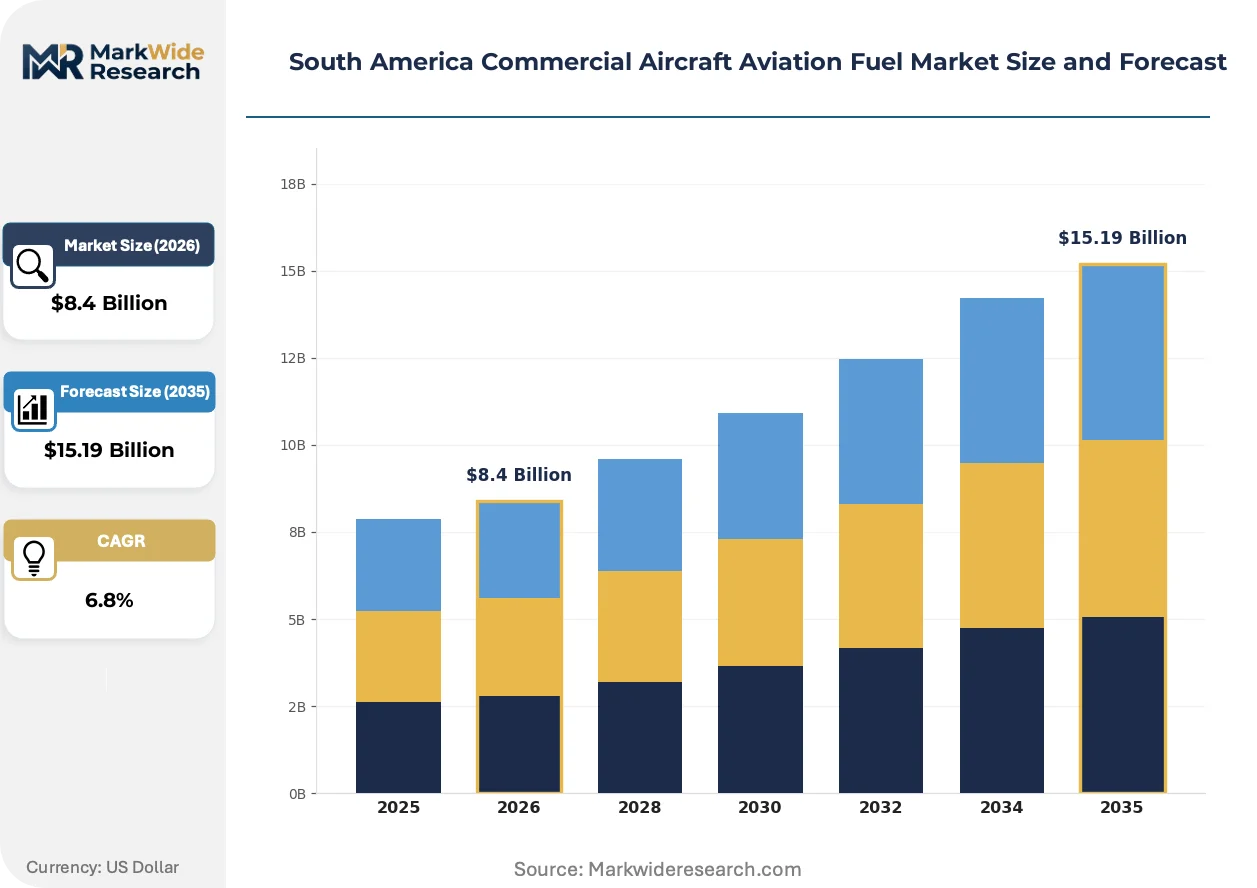
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Jet A, Jet A-1, Avgas, Biofuel End User: Airlines, Charter Services, Cargo Carriers, Government Aviation Distribution Channel: Direct Supply, Fuel Depots, Airports, Third-Party Vendors Certification: ASTM, ICAO, IATA, Others |
| Companies Covered | Petroleo Brasileiro S.A., Repsol SA, BP PLC, Shell PLC, TotalEnergies SE, ExxonMobil, ENAP, Air BP, Chevron, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Commercial Aircraft Aviation Fuel Market Evolving Landscape
Digital fuel management systems are displacing manual dipstick measurement across South American airport depots. These platforms integrate real-time density, temperature, and contamination monitoring with airline enterprise resource planning systems.
HEFA-SPK synthetic paraffinic kerosene is overtaking first-generation FAME blends in airline procurement specifications. Derived from waste oils and animal fats, HEFA-SPK offers superior thermal stability and freeze point performance. LATAM and Gol Linhas Aéreas have incorporated 50 percent blend ratios into their 2027 fleet transition plans, compressing demand for conventional Jet A-1 in São Paulo and Rio de Janeiro storage terminals.
ANAC Resolution 934's traceability documentation requirements are restructuring supplier qualification workflows. The regulation mandates blockchain-verified chain-of-custody records from refinery gate to wing tank. Brazilian domestic carriers are responding by consolidating approved vendor lists to five integrated suppliers capable of real-time compliance reporting, excluding smaller regional distributors from tender participation.
Cargo carrier procurement teams are unbundling fuel supply from ground handling contracts. Previously bundled service agreements masked true fuel costs; separated sourcing allows direct negotiation with Petrobras and international traders. This pattern is most visible among Colombian and Chilean integrators operating scheduled freighter networks, where fuel represents 35-40 percent of direct operating costs.
South America Commercial Aircraft Aviation Fuel Market Segmentation
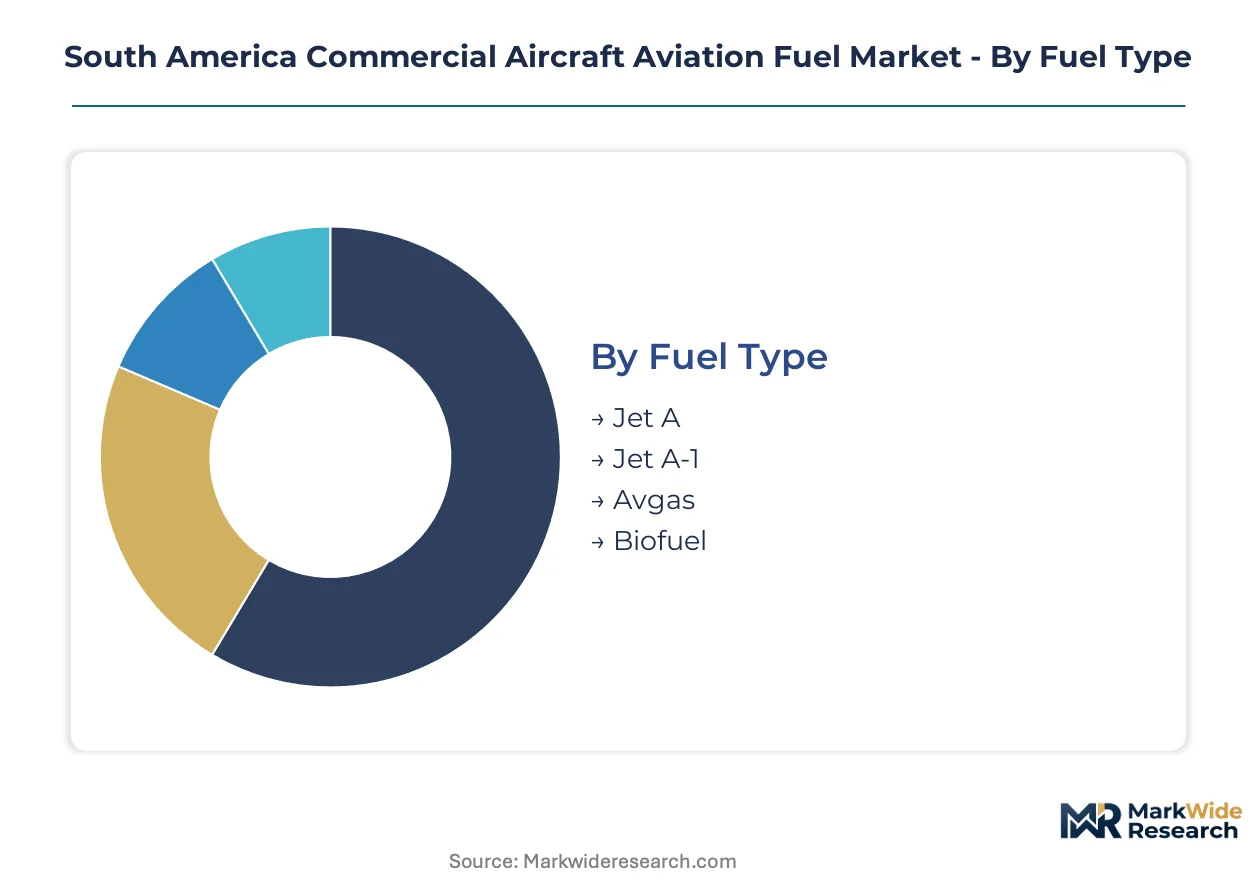
Aviation fuel segmentation in South America tracks specification hierarchies that determine engine compatibility and storage infrastructure requirements. Procurement teams structure supply contracts around fuel type and certification tier, with distribution channel selection directly impacting landed cost at remote Andean airfields.
Fuel Type:
Specification chemistry dictates storage protocols, thermal stability thresholds, and blending compatibility across South American refinery networks.
- Jet A-1:Refined kerosene with maximum minus 47 degrees Celsius freeze point, formulated for turbine engines operating at altitude. Brazilian carriers concentrate demand in São Paulo Guarulhos and Rio de Janeiro Galeão storage terminals, where ANAC Resolution 934 mandates sulfur content below 0.03 percent and full traceability documentation.
- Biofuel:ASTM D7566-certified synthetic paraffinic kerosene derived from HEFA-SPK pathways, offering superior thermal stability versus first-generation FAME blends. Chilean cargo operators at Santiago Arturo Merino Benítez are retrofitting tank farms to handle 50 percent blend ratios ahead of ICAO CORSIA mandatory phases.
- Jet A:Higher freeze point specification than Jet A-1, deployed primarily in domestic Brazilian routes where ambient temperatures rarely reach operational limits.
- Avgas:High-octane aviation gasoline for piston-engine aircraft, serving general aviation and training fleets across Argentina's interior provinces.
Jet A-1 leads on scale; biofuel leads on momentum.
End User:
Customer type determines volume commitment structures, with dedicated freighter operators now unbundling fuel from ground handling contracts.
- Cargo Carriers:Colombian and Peruvian integrators operating scheduled freighter networks through Quito and Bogotá hubs, where fuel represents 35-40 percent of direct operating costs. E-commerce logistics expansion is driving sustained uplift volume growth across the Andean corridor.
- Airlines:LATAM and Avianca negotiate ten-year direct offtake agreements with refineries, bypassing traditional distributor markups. Fleet renewal programs prioritize ASTM D7566-certified blends for carbon offsetting compliance.
- Charter Services:Point-to-point operators serving Brazil's southeast aviation triangle, dependent on fuel depot infrastructure at secondary airports.
- Government Aviation:Military and state aircraft procurement governed by ENAP and ANAC storage safety mandates, with specialized hydration testing protocols.
Cargo carriers lead on volume growth rate; airlines lead on contract sophistication.
Distribution Channel:
Channel selection determines compliance burden, with ANAC Resolution 934's blockchain-verified chain-of-custody requirements favoring integrated suppliers over fragmented networks.
- Fuel Depots:Dedicated Jet A-1 infrastructure at São Paulo Guarulhos reduces turnaround times for narrow-body fleets. Shell PLC anchors position through depot modernization investments serving the southeast aviation triangle.
- Direct Supply:LATAM and Gol Linhas Aéreas negotiate refinery gate agreements, consolidating approved vendor lists to five integrated suppliers capable of real-time compliance reporting.
- Airports:Legacy tank farms require corrosion-resistant lining upgrades to handle fatty acid methyl ester blends, with Karl Fischer moisture analysis adding operational overhead.
- Third-Party Vendors:Marginal distributors excluded from tender participation as Brazilian domestic carriers consolidate procurement around traceability-capable suppliers.
Fuel depots lead on throughput volume; direct supply leads on margin compression.
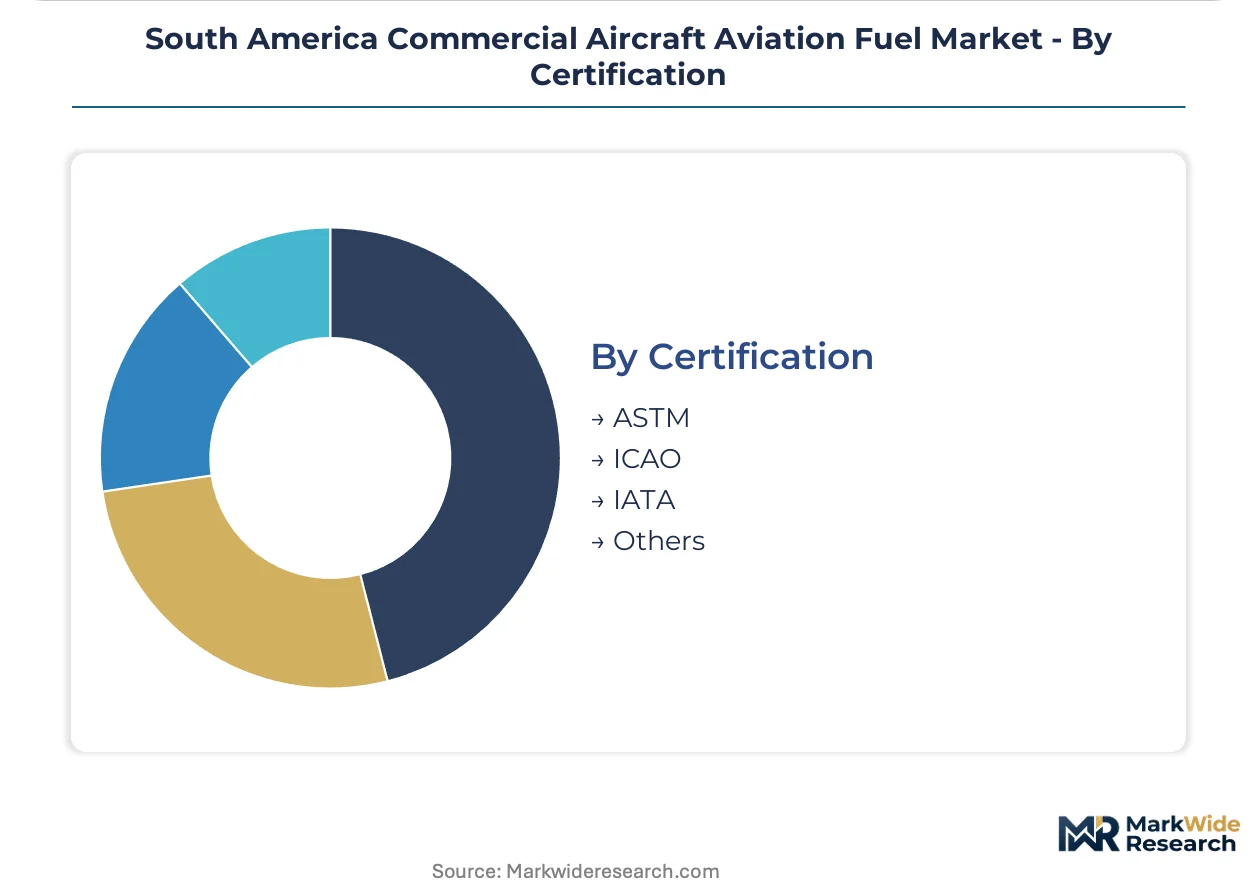
Certification:
Regulatory tier determines market access, with multi-standard alignment required for cross-border operations.
- ASTM:D7566 biofuel certification represents the segment expanding most quickly, with 18-24 month validation cycles governing pathway approvals.
- ICAO:CORSIA eligibility criteria for sustainable aviation fuels dictate procurement shifts and infrastructure investment timing across South American carriers.
- IATA:Operational safety and quality standards harmonizing ground handling protocols at major hub airports.
- Others:National standards including ANAC Resolution 934 and Chilean ENAP mandates governing sulfur content and traceability documentation.
ASTM leads on technology transition speed; ICAO leads on compliance obligation scope.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial aviation fuel distribution across South America traces its modern infrastructure to Brazil's state-led refinery buildout during the 1960s and 1970s, which established the continent's largest integrated Jet A-1 production network. This historical foundation continues to shape supply corridors today.
Brazil
Petrobras controls over 80 percent of domestic Jet A-1 production capacity, creating single-source dependency for carriers operating the southeast aviation triangle. ANAC Resolution 934 mandates sulfur content below 0.03 percent and blockchain-verified traceability documentation that informal distributors cannot meet. São Paulo Guarulhos anchors distribution with dedicated fuel depot infrastructure serving narrow-body fleet turnaround operations.
Chile
Santiago's Arturo Merino Benítez International is positioning as a regional sustainable aviation fuel transhipment hub for Pacific routes. ENAP governs storage safety mandates and biofuel blending specifications that exceed baseline ICAO requirements. Chilean cargo operators are retrofitting tank farms to handle 50 percent HEFA-SPK blend ratios ahead of mandatory carbon offsetting phases.
Colombia
Colombian integrators operating scheduled freighter networks through Bogotá hubs are unbundling fuel supply from ground handling contracts, where fuel represents 35-40 percent of direct operating costs. The national civil aviation authority enforces hydration testing protocols aligned with ASTM D7566 certification timelines. E-commerce logistics expansion is driving sustained uplift volume growth through El Dorado International.
Argentina
Neuquén basin condensate quality supports domestic Jet A-1 production, reducing import dependency for Buenos Aires Ezeiza operations. The national hydrocarbons regulator oversees fuel quality standards that harmonize with ICAO CORSIA eligibility criteria. Vaca Muerta feedstock proximity enables backward integration strategies for refinery operators serving Atlantic corridor routes.
Peru
Peruvian cargo carriers are expanding dedicated freighter routes through Lima Jorge Chávez International, connecting Andean mining corridors with Pacific export markets. The national transport and communications ministry enforces sulfur content limits that align with Chilean ENAP standards. Quarantine logistics and temperature-sensitive pharmaceutical exports are accelerating demand for certified cold-chain fuel handling protocols.
South America Commercial Aircraft Aviation Fuel Market Competitive Landscape
The competitive structure tilts toward integrated national oil companies with captive refinery assets. Petrobras dominates Brazilian domestic production through vertical control of upstream feedstock and downstream distribution. International majors anchor positions through dedicated depot infrastructure at hub airports. Three archetypes define the field: state-affiliated integrated producers, global trading houses with terminal assets, and specialized aviation fuel distributors. Consolidation pressures are accelerating as ANAC Resolution 934's compliance costs screen out marginal suppliers, while direct airline-refinery offtake agreements are compressing traditional distributor margins.
Within the state-affiliated tier, Petroleo Brasileiro S.A. exemplifies upstream-downstream integration that shapes pricing dynamics across the continent. Among European-based majors, Repsol SA and Shell PLC occupy positions defined by specialized supply contracts and dedicated infrastructure investments respectively. These three names anchor the competitive map without exhausting its complexity.
| Leading Market Players |
|---|
| Petroleo Brasileiro S.A. |
| Repsol SA |
| BP PLC |
| Shell PLC |
| TotalEnergies SE |
| ExxonMobil |
| ENAP |
| Air BP |
| Chevron |
| Others |
Value Network & Pricing Analysis
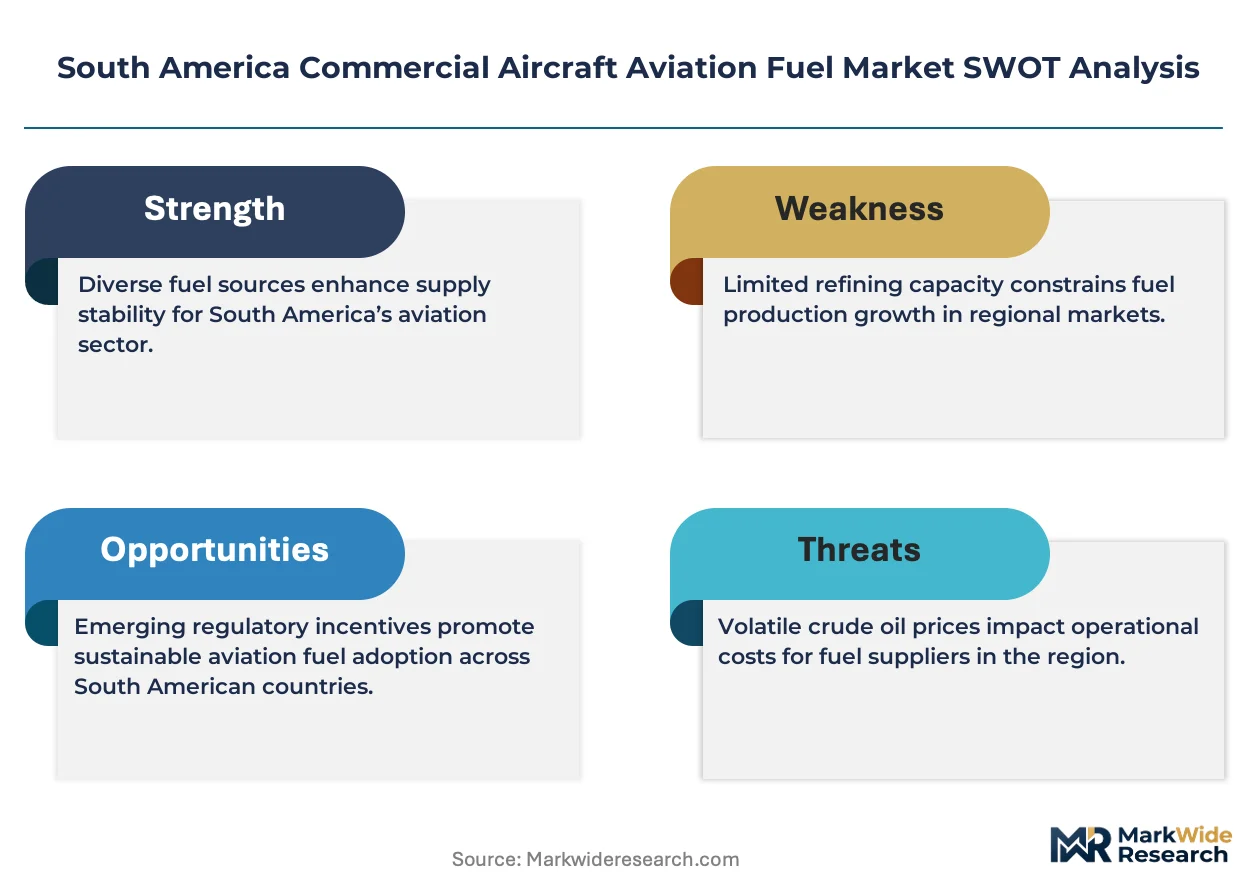
Jet fuel crack spreads transmit Brent crude volatility through to airline procurement budgets, compressing refinery margins and destabilizing long-term supply contracts across the southeast aviation triangle. ANAC-mandated sulfur content thresholds and traceability documentation add compliance premiums that informal distributors cannot absorb, stratifying the supplier base between integrated majors and excluded regional players.
Pricing Analysis
Long-term offtake agreements dominate procurement structures as LATAM and Avianca negotiate decade-spanning refinery gate contracts that bypass traditional distributor markups. Price differentiation centers on certification tier—ASTM D7566 biofuel blends command premiums over conventional Jet A-1—and volume scale, with cargo carriers leveraging 35-40 percent fuel-cost exposure to extract favorable terms. Pricing pressure intensifies as Petrobras production concentration limits competitive alternatives for Brazilian carriers. Cargo integrators exhibit highest price sensitivity due to thin operating margins, while flag carriers prioritize supply security over unit cost.
Supply Chain Analysis
Direct-to-airline channels handle hyperscale buyer demand as carriers consolidate approved vendor lists around five integrated suppliers capable of blockchain-verified chain-of-custody reporting. Geographic supply concentrates in Brazil, Chile, and Argentina, with Brazilian refinery output feeding the dominant southeast aviation corridor. Raw material dependencies center on Vaca Muerta condensate, imported Brent-linked crude, and HEFA-SPK feedstock from waste oil and animal fat pathways. Single-source vulnerability permeates the network—Petrobras controls over 80 percent of domestic Jet A-1 production capacity. Distribution runs through dedicated fuel depot infrastructure at São Paulo Guarulhos and Rio de Janeiro Galeão, with secondary airports reliant on third-party vendor networks facing exclusion under Resolution 934.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America commercial aircraft aviation fuel market represents a late-cycle quality story as ANAC Resolution 934 and ICAO CORSIA eligibility criteria force procurement teams toward premium-certified suppliers capable of real-time compliance documentation.
For Market Incumbents: Extend depot infrastructure modernization programs at São Paulo Guarulhos and Santiago Arturo Merino Benítez to capture biofuel blending volume ahead of mandatory carbon offsetting phases. Deepen backward integration into Vaca Muerta feedstock through dedicated condensate offtake agreements that secure cost-advantaged Jet A-1 production for Atlantic corridor routes. Direct airline-refinery contracting threatens traditional distributor margins; anchor position through ten-year supply commitments with LATAM and Gol Linhas Aéreas that bundle hydration testing and sustainable aviation fuel certification services. For New Entrants and Emerging Players: Colombian cargo integrators operating scheduled freighter networks through Bogotá and Quito represent the most penetrable buyer archetype, as these operators unbundle fuel from ground handling contracts and seek alternative suppliers to reduce 35-40 percent fuel-cost exposure. Target secondary airports in Brazil's interior states where ANAC Resolution 934 compliance requirements have excluded marginal distributors, creating supply gaps for certified regional operators. Enter through specialized biofuel logistics partnerships with HEFA-SPK pathway producers that lack dedicated South American terminal assets. For Investors and Strategic Acquirers: Consolidation pressure builds where ANAC-mandated Karl Fischer moisture analysis and blockchain traceability documentation screen out fragmented regional distributors incapable of real-time compliance reporting. Long-term viability favors integrated suppliers with captive refinery access and depot infrastructure at hub airports. Target acquisition archetype: mid-scale Brazilian distributors with established airline relationships but lacking capital for Resolution 934 compliance upgrades, where roll-up synergies with integrated majors capture stranded customer volumes. Watch ICAO CORSIA eligibility expansion timeline as inflection indicator—accelerated mandatory phases would compress demand for conventional Jet A-1 infrastructure and revalue biofuel-certified terminal assets.| Strategic Initiative | Industry Significance |
|---|---|
| HEFA-SPK Blending Infrastructure | Santiago Arturo Merino Benítez positions as Pacific route transhipment hub for sustainable aviation fuel. |
| Direct Airline-Refinery Offtake Agreements | Ten-year purchase commitments with LATAM and Avianca bypass traditional distributor markups entirely. |
| Blockchain Traceability System Deployment | ANAC Resolution 934 mandates verified chain-of-custody records from refinery gate to wing tank. |
| Vaca Muerta Feedstock Integration | Neuquén basin condensate quality reduces import dependency for Buenos Aires Ezeiza operations. |
| Legacy Tank Farm Corrosion-Resistant Upgrades | Existing storage infrastructure requires lining replacement to handle fatty acid methyl ester blends. |
Research Methodology
Bottom-up airline and cargo carrier demand modeling reconciled against top-down refinery output and depot throughput tracking forms the analytical core of this study. Primary interviews with aviation fuel procurement managers, ANAC compliance officers, refinery operations directors, and sustainable aviation fuel certification specialists were cross-validated against secondary sources including ANAC regulatory filings, ENAP storage safety mandates, ICAO CORSIA documentation, and Petrobras operational disclosures. Trade flow data from Brazilian customs authorities and Chilean hydrocarbon regulators anchored supply-side calibration.
Historical trendline analysis of Jet A-1 uplift volumes across São Paulo Guarulhos, Rio de Janeiro Galeão, and Santiago Arturo Merino Benítez established baseline growth trajectories. The forecast framework segments by fuel type, end-user category, distribution channel, and certification tier, with CAGRs derived from elasticity modeling against Brent crude price scenarios and fleet renewal schedules. Industry-specific inputs include HEFA-SPK pathway approval timelines, ANAC Resolution 934 implementation phases, and ICAO CORSIA mandatory carbon offsetting progression.
Underlying measurement precision varies by segment; biofuel certification and direct supply channel data carry tighter precision than fragmented third-party vendor estimates. Forecasts reflect assumptions regarding regulatory enforcement consistency, refinery capacity utilization, and sustainable aviation fuel feedstock availability. Periodic stress-testing of base assumptions is recommended, particularly around ICAO CORSIA timeline acceleration and Petrobras production allocation decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Gas Pooling Mechanism Market
Fuels
City Gas Distribution Market
Fuels
Global Charcoal Market
Fuels
Refuse Derived Fuel Market
Fuels
China LNG Bunkering Market
Fuels
Carbonizers Market
Fuels
Oil & Gas Lubricants Market
Fuels
Storage Tank Market
Fuels
Hydrogen Cylinder Market
Fuels
United Kingdom Chemical Logistics Market
Fuels
China Bunker Fuel Market
Fuels
Bituminous Coal Market
Fuels
Wood Charcoal Market
Fuels
Alcohol-To-Jet (ATJ) Fuel Market
Fuels
Germany Bunker Fuel Market
Fuels
Catalytic Hydrothermolysis Jet [CHJ] Fuel Market