
 Germany EV Charging Infrastructure Market | 2026-2036
Germany EV Charging Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Germany EV Charging Infrastructure Market Insights
Fleet procurement patterns across German logistics operators and municipal transport authorities is pivoting toward long-term charging service contracts rather than capital-heavy station ownership. Siemens leverages its industrial automation heritage to dominate manufacturing scale for DC fast-charging hardware across Central European production facilities. Ionity GmbH anchors its competitive position through exclusive highway corridor partnerships with German automotive OEMs, ensuring priority site access along Autobahn networks. ABB competes on technology leadership in high-power charging modules exceeding 350 kW output thresholds.
Germany EV charging infrastructure encompasses the physical and digital systems enabling electric vehicle energy replenishment, incorporating power conversion electronics, grid connection hardware, and communication protocols operating at outputs from 3.7 kW residential AC to 450 kW ultra-fast DC configurations. The primary commercial purpose centers on reducing vehicle downtime through scalable energy delivery while managing grid load profiles via smart load-balancing algorithms. Fast charging installations command premium positioning due to highway accessibility and fleet utilization rates, while smart charging technology represents the fastest-expanding segment as utilities mandate demand-response capabilities. Private station deployments retain mature growth profiles in suburban residential clusters where overnight AC charging satisfies daily commuting ranges.
Germany's Federal Network Agency (Bundesnetzagentur) enforces grid connection standards under the Energy Industry Act, while KBA type-approval requirements govern charging equipment safety certifications for public deployment. The EU Green Deal's transport decarbonization milestones, transposed through Germany's National Charging Infrastructure Masterplan, mandate minimum coverage densities that directly determine site licensing priority and public funding eligibility. Stakeholders must monitor emerging CSRD disclosure obligations affecting fleet operators' Scope 3 reporting requirements, as these sustainability audits will reshape procurement criteria for charging infrastructure providers serving commercial accounts.
Market Dynamics
Fleet operators across Germany's logistics corridors are abandoning capital-intensive station ownership for long-term charging service contracts, compressing equipment procurement cycles while expanding recurring revenue pools for infrastructure providers.
Growth Catalysts
- EU Green Deal transport decarbonization milestones:Binding coverage density mandates under Germany's National Charging Infrastructure Masterplan accelerate site licensing and unlock public funding streams for corridor deployments.
- Commercial fleet electrification:Logistics operators electrifying last-mile delivery networks generate sustained demand for highway-adjacent ultra-fast charging clusters serving intercity routes.
- F-Gas Regulation phase-down:Fluorinated gas restrictions on cooling systems for charging hardware force equipment upgrades, stimulating replacement demand across existing infrastructure bases.
Market Restraints
- Grid connection bottlenecks:Bundesnetzagentur approval timelines for high-capacity grid extensions delay commissioning of ultra-fast charging sites in metropolitan corridors.
- Power electronics supply concentration:Silicon carbide module fabrication concentrates among Asian semiconductor foundries, exposing hardware manufacturers to input volatility and extended lead times.
- Residential AC saturation:Suburban overnight charging penetration limits addressable market expansion for private station deployments in established commuter belts.
Strategic Opportunities
- CSRD disclosure obligations:Fleet operators' emerging Scope 3 reporting requirements reshape procurement criteria, creating premium positioning for charging providers with verified carbon accounting.
- Smart load-balancing algorithm integration:Utilities mandating demand-response capabilities open software revenue streams distinct from hardware sales.
- Rural corridor underpenetration:Eastern German highway segments between Berlin and Dresden show coverage gaps relative to western Autobahn networks.
Industry Challenges
- High-voltage certification timelines:KBA type-approval processes for 450 kW charging equipment extend product launch schedules and compress competitive windows.
- Interoperability protocol fragmentation:Competing communication standards between automotive OEMs and infrastructure operators complicate seamless roaming service delivery.
- Grid integration complexity:Bi-directional charging capabilities require distribution network upgrades that outpace utility capital allocation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany EV Charging Infrastructure Market |
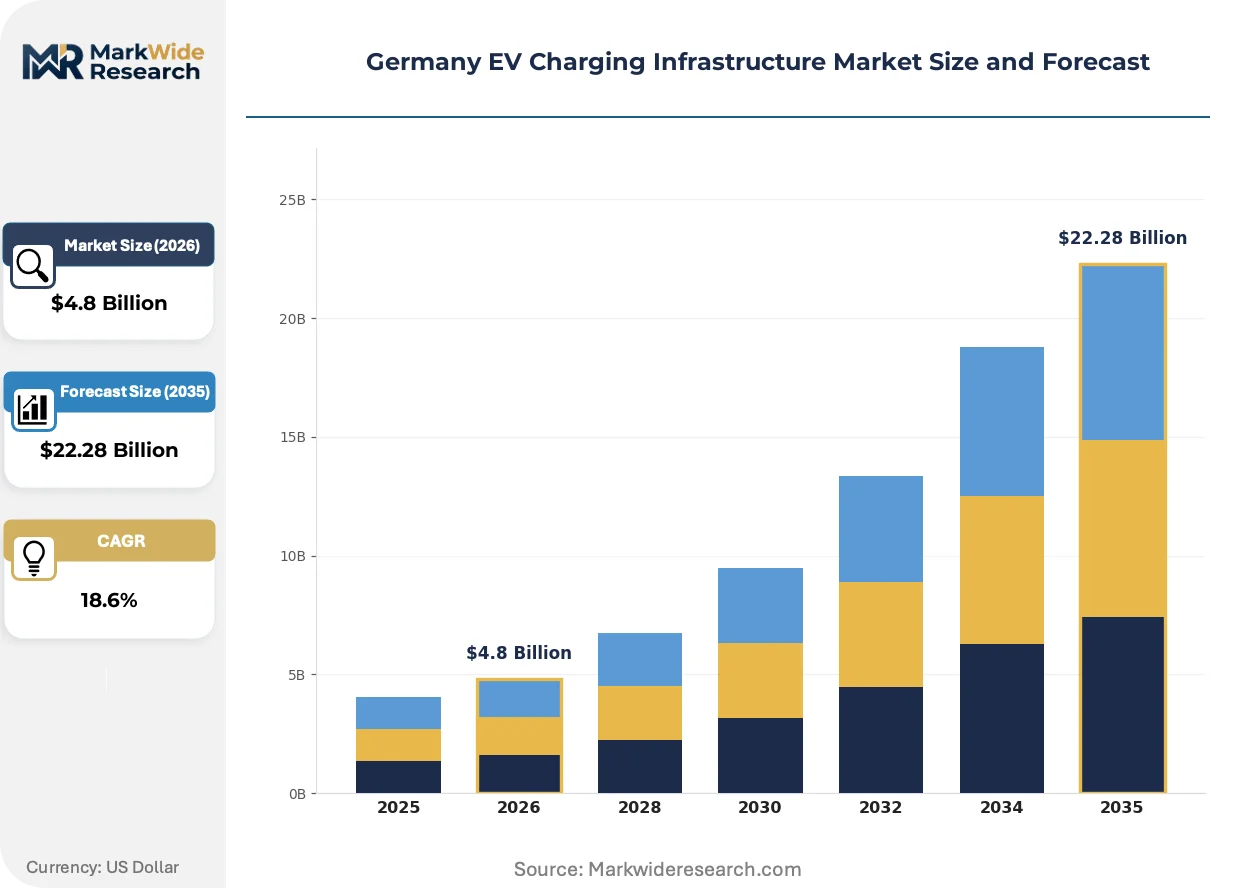
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fast Charging, Level 2 Charging, Wireless Charging, Ultra-Fast Charging Installation Type: Public Stations, Private Stations, Fleet Charging, Destination Charging Technology: DC Charging, AC Charging, Smart Charging, V2G Technology End User: Commercial Fleets, Residential Users, Retail Outlets, Public Transportation |
| Companies Covered | Siemens, EnBW Baden Württemberg AG, Ionity GmbH, Tesla, ABB, Enel X, ChargePoint, Shell, Schneider Electric, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany EV Charging Infrastructure Market Trends and Innovations
Hardware-software convergence is redefining competitive differentiation as charging infrastructure evolves from passive energy delivery to active grid management nodes.
Modular power conversion architectures are unifying AC and DC charging functions within single hardware platforms. Fleet operators deploying mixed vehicle pools favor these consolidated systems to reduce site footprint and maintenance overhead. The technology is unifying procurement specifications previously split between residential, commercial, and highway applications.
Bundesnetzagentur grid codes under the Energy Industry Act now mandate dynamic load management for public charging installations above 50 kW capacity. Equipment providers must embed real-time telemetry and remote curtailment capabilities to maintain connection permits. Fast charging corridor operators face the steepest compliance costs, passing these through to service contract pricing.
Long-term service agreements are displacing outright equipment purchases among municipal transport authorities. Berlin and Hamburg transit agencies now structure 10-year charging availability contracts with guaranteed uptime clauses. This model concentrates vendor selection on operational track records rather than upfront hardware specifications.
Germany EV Charging Infrastructure Market Segmentation
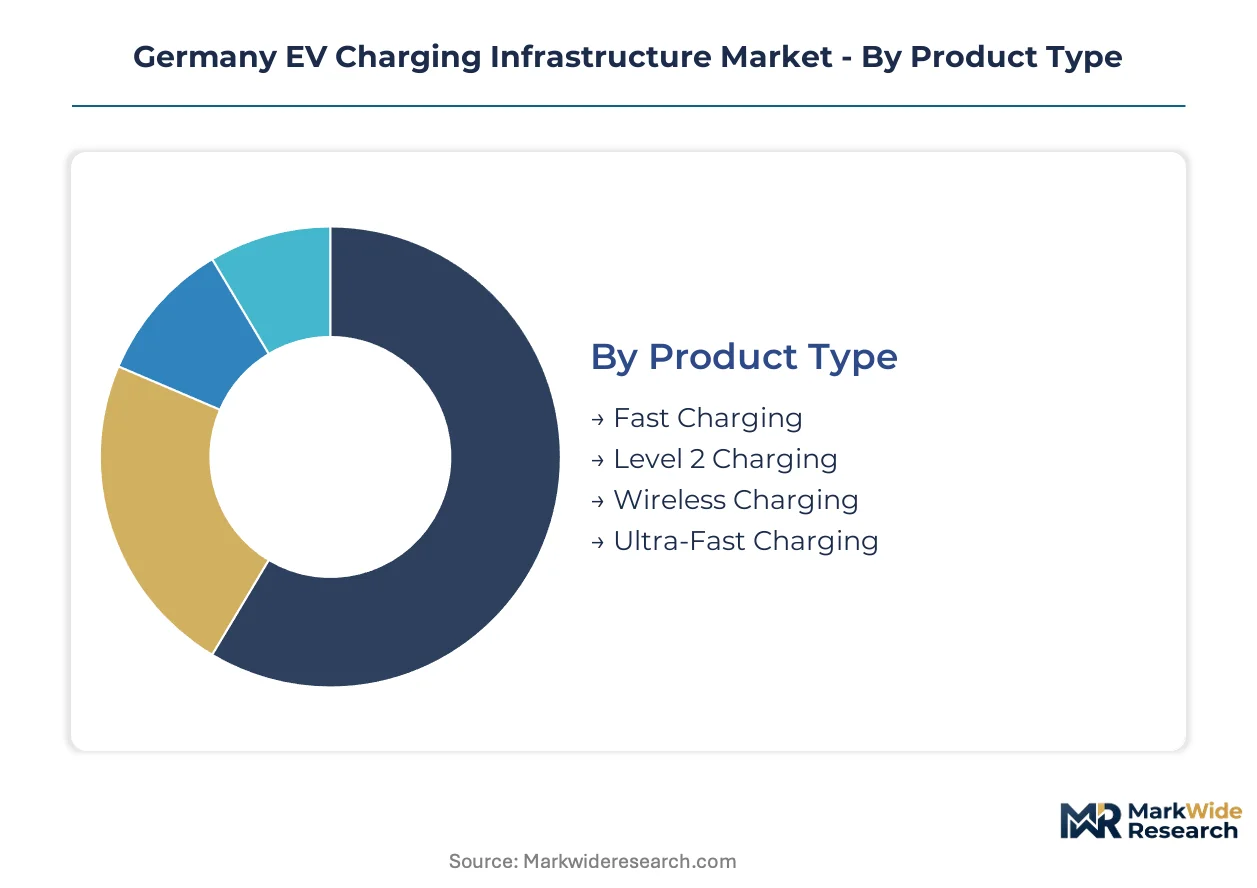
Segmentation reveals how charging infrastructure economics diverge across deployment contexts. Product specifications, installation ownership models, and end-user requirements create distinct competitive arenas with margin profiles that hardware providers must navigate strategically.
Product Type:
Fast charging commands premium positioning through highway corridor scarcity, while Level 2 AC hardware saturates residential markets with volume-driven economics.
- Fast Charging:DC power conversion at 50-150 kW outputs dominates Autobahn-adjacent locations. Demand concentrates with logistics operators requiring sub-30-minute replenishment for intercity freight routes.
- Ultra-Fast Charging:350-450 kW configurations utilizing liquid-cooled cable systems and silicon carbide power electronics. Deployment clusters along Berlin-Munich-Hamburg corridors where Bundesnetzagentur grid codes mandate dynamic load management above 50 kW capacity.
- Level 2 Charging:3.7-22 kW AC wallbox units serving overnight residential replenishment. Suburban commuter belts in North Rhine-Westphalia and Baden-Württemberg show mature penetration curves.
- Wireless Charging:Inductive pad systems operating at 11 kW with alignment tolerance protocols. Municipal bus depots in Hamburg and Stuttgart pilot automated opportunity charging for fixed-route electrification.
Today's leader: Fast Charging. Tomorrow's challenger: Ultra-Fast Charging.
Installation Type:
Ownership economics separate capital-heavy station deployment from service-contract models that transfer operational risk to infrastructure providers.
- Fleet Charging:Dedicated depot installations with 150-350 kW DC hubs serving centralized vehicle pools. Logistics operators in Ruhr industrial corridors favor 10-year availability contracts over asset ownership.
- Public Stations:Open-access highway and urban curbside infrastructure requiring KBA type-approval under Energy Industry Act grid codes. Ionity GmbH anchors corridor positioning through OEM-exclusive Autobahn partnerships.
- Private Stations:Residential and workplace installations with AC-dominant specifications. Single-family housing stock in Bavaria and Lower Saxony drives replacement cycles as early adopter units age.
- Destination Charging:Retail and hospitality-integrated AC units extending dwell-time revenue models. Shopping centers along A7 and A9 motorway junctions leverage charging as foot-traffic anchors.
Fleet Charging captures margin expansion through long-term service agreements. Public Stations face grid connection bottlenecks compressing deployment velocity.
Technology:
Power electronics architecture and software integration depth define competitive differentiation across hardware categories.
- DC Charging:Direct current conversion bypassing onboard vehicle inverters for maximum power delivery. Highway corridor operators specify modular architectures unifying 50-450 kW outputs within single platform footprints.
- Smart Charging:Real-time telemetry and demand-response algorithms mandated by Bundesnetzagentur for installations above 50 kW. This segment climbs fastest as utilities integrate charging loads into grid balancing markets.
- AC Charging:Alternating current delivery relying on vehicle-mounted rectification. Residential and workplace applications favor cost-minimized wallbox designs with basic connectivity.
- V2G Technology:Bidirectional power flow enabling vehicle battery discharge to grid or building loads. Distribution network upgrades in Berlin and Hamburg pilot zones lag hardware certification timelines.
Smart Charging leads software revenue attachment. V2G Technology awaits regulatory clarity on grid compensation frameworks.
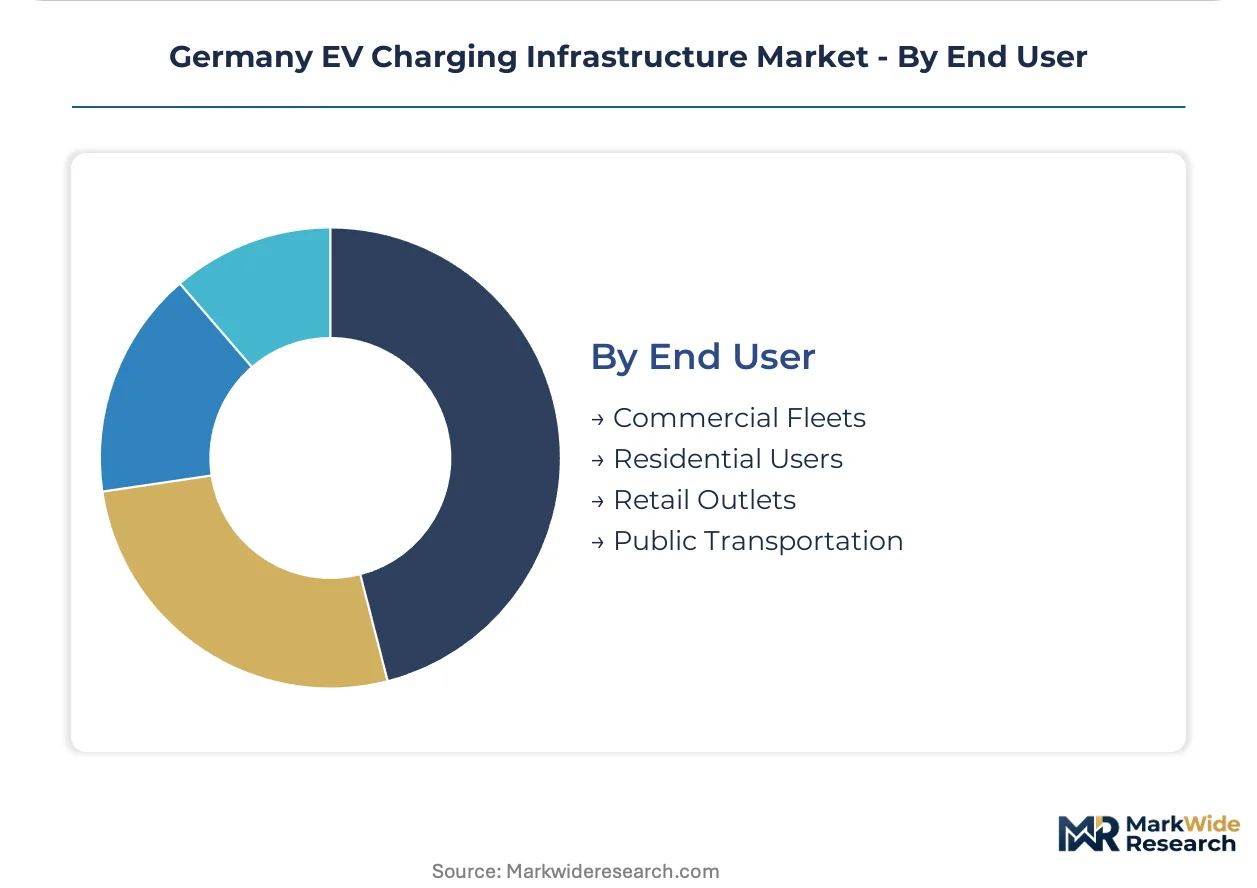
End User:
Procurement authority and utilization intensity create diverging requirements across customer segments.
- Commercial Fleets:Centralized procurement of high-availability charging services with guaranteed uptime clauses. Last-mile delivery electrification in Frankfurt and Cologne metropolitan areas drives corridor clustering.
- Public Transportation:Municipal authority contracts specifying 10-year operational availability. Berlin and Hamburg transit agencies structure vendor selection around track records rather than capital cost.
- Residential Users:Individual wallbox acquisition with overnight AC charging satisfying daily commuting ranges. Single-family suburban penetration limits addressable expansion in established commuter belts.
- Retail Outlets:Destination charging as customer acquisition infrastructure with AC-dominant specifications. Highway service stations integrate charging as amenity differentiation.
Commercial Fleets concentrate revenue concentration. Public Transportation offers contract duration stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's charging corridor density exceeds France's deployment velocity, yet both markets face similar grid connection bottlenecks under national energy codes. Metropolitan clusters across federal states concentrate demand while rural Autobahn segments lag coverage targets.
Bavaria
Munich anchors southern Germany's electrification momentum with dense fleet operator procurement for last-mile logistics. Bundesnetzagentur grid codes mandate dynamic load management for installations above 50 kW, accelerating hardware upgrade cycles. The Munich-Nuremberg corridor clusters ultra-fast charging hubs serving automotive OEM test fleets and commercial transport operators.
North Rhine-Westphalia
Ruhr industrial corridors generate concentrated demand from logistics operators abandoning asset ownership for service contracts. KBA type-approval requirements govern equipment safety certifications for public deployment across Cologne and Düsseldorf metropolitan zones. Dortmund and Essen depot installations favor 10-year availability contracts with guaranteed uptime clauses over capital purchases.
Baden-Württemberg
Stuttgart's automotive engineering heritage drives early adoption of high-power charging modules exceeding 350 kW outputs. The EU Green Deal's transport decarbonization milestones transposed through Germany's National Charging Infrastructure Masterplan determine site licensing priority. The Stuttgart-Mannheim corridor hosts pilot deployments of bi-directional charging capabilities requiring distribution network upgrades.
Lower Saxony
Wolfsburg's manufacturing concentration creates fleet electrification demand from corporate vehicle pools and supplier logistics networks. F-Gas Regulation phase-down restrictions on cooling systems for charging hardware stimulate replacement demand across existing infrastructure bases. Hanover's municipal transport authority structures vendor selection around operational track records rather than upfront capital cost.
Berlin-Brandenburg
The capital region concentrates public transportation electrification with 10-year operational availability contracts specifying guaranteed uptime. CSRD disclosure obligations reshape procurement criteria as fleet operators face emerging Scope 3 reporting requirements. Berlin's transit agencies and Brandenburg's regional bus operators prioritize charging providers with verified carbon accounting frameworks.
Germany EV Charging Infrastructure Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware manufacturing and charging network operation. Siemens leverages industrial automation heritage to dominate manufacturing scale for DC fast-charging hardware. The market structure consolidates around three strategic archetypes: integrated industrial conglomerates with captive energy divisions, pure-play charging network operators securing corridor exclusivity, and power electronics specialists competing on module output thresholds. Dominant competitive moves include strategic partnerships with automotive OEMs for highway site access and long-term service agreements displacing equipment ownership among fleet operators.
Within the integrated industrial tier, Siemens and ABB occupy positions exemplifying scale-driven manufacturing advantages for power conversion hardware. Ionity GmbH anchors the pure-play network operator archetype through corridor-focused deployment strategies. Among diversified energy conglomerates, EnBW Baden Württemberg AG represents the utility-backed charging service model combining generation assets with infrastructure deployment.
| Leading Market Players |
|---|
| Siemens |
| EnBW Baden Württemberg AG |
| Ionity GmbH |
| Tesla |
| ABB |
| Enel X |
| ChargePoint |
| Shell |
| Schneider Electric |
| Others |
Pricing and Supply Chain Analysis
Backward integration into silicon carbide power module production anchors both supply security and pricing power for German DC fast-charging hardware manufacturers facing Asian foundry concentration. This captive production strategy insulates equipment providers from input volatility while supporting premium positioning in highway corridor deployments.
Pricing Analysis
Capacity additions in Central European manufacturing zones are reshaping price floors for DC fast-charging hardware as domestic production scales compete with Asian imports. Three-tier pricing structure across premium liquid-cooled systems, standard air-cooled modules, and economy AC wallbox units reflects certification grade differentiation under KBA type-approval. Cost compression in standard-tier DC hardware intensifies because silicon carbide module supply bottlenecks ease with expanded foundry output. Municipal transport authorities show least price sensitivity due to 10-year availability contract structures, while residential users in saturated suburban belts drive volume pricing for AC units.
Supply Chain Analysis
Dual-sourcing requirements from Bundesnetzagentur grid code compliance mandate multi-supplier qualification for power electronics and cooling system components. Manufacturing concentration in China, South Korea, and Germany exposes hardware assemblers to single-source vulnerability in silicon carbide wafer fabrication. Critical inputs include copper busbars, liquid-cooled cable assemblies, and high-voltage contactors subject to commodity price volatility. Distribution runs through direct OEM partnerships for highway corridor deployments and electrical wholesale channels for residential AC installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's EV charging infrastructure functions as a regulatory compounder where EU Green Deal transport decarbonization milestones create sustained demand visibility through binding coverage density mandates. The National Charging Infrastructure Masterplan locks in deployment velocity regardless of near-term demand fluctuations.
For Market Incumbents: Deploy dynamic load-balancing software as a service layer to defend against pure-play software entrants capturing grid integration revenue. Siemens and ABB should deepen captive silicon carbide supply through foundry partnerships or in-house wafer production to offset Asian concentration risk. Long-term service contracts with fleet operators require operational track record investments that compress competitive windows for challengers.
For New Entrants and Emerging Players: CSRD disclosure obligations in Germany open a window for carbon-accounting-verified charging providers to capture premium positioning among fleet operators facing Scope 3 reporting requirements. Eastern German highway segments between Berlin and Dresden present the most penetrable geography with coverage gaps relative to western Autobahn networks. Smart charging algorithm development offers a software-first go-to-market angle distinct from capital-heavy hardware deployment.
For Investors and Strategic Acquirers: Consolidation pressure builds where operational track record scarcity meets municipal contract duration requirements favoring established vendors. Mid-cap hardware specialists with Bundesnetzagentur grid code certification and proven uptime metrics represent prime acquisition targets for energy conglomerates seeking charging service verticals. Watch bi-directional charging regulatory clarity on grid compensation frameworks as the inflection signal for V2G technology valuation repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Agreement | Secures power module inputs from Asian foundries for 350-450 kW hardware production. |
| Highway Corridor Exclusivity Partnership | Locks priority site access along Autobahn networks through OEM alliance structures. |
| Smart Charging Platform Launch | Embeds demand-response algorithms mandated by Bundesnetzagentur above 50 kW capacity. |
| 10-Year Service Contract Structure | Transports fleet operator procurement from capital purchase to recurring revenue models. |
| Bi-Directional Charging Certification | Positions for V2G revenue streams pending grid compensation framework finalization. |
Research Methodology
Direct dialogue with charging network operators, power electronics procurement leads at automotive OEMs, Bundesnetzagentur grid connection officers, and fleet logistics managers grounded qualitative insights in operational reality. Secondary validation drew from KBA type-approval filings, EU Green Deal transport decarbonization milestone documentation, F-Gas Regulation implementation guidance, and German customs data on charging hardware imports. Bottom-up installation forecasts triangulated against top-down EU coverage density mandates.
Market sizing outputs segment across product type, installation ownership model, power electronics architecture, and end-user procurement authority throughout the projection horizon. CAGRs derive from regression analysis of historical deployment velocity against regulatory milestone schedules, with specific weighting for grid connection approval timelines and fleet electrification commitment announcements.
Revisions become necessary when Bundesnetzagentur grid code amendments, silicon carbide supply disruptions, or automotive OEM platform electrification delays materialize outside modeled assumptions. Deviation in EU Green Deal transport decarbonization enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
China Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Portable Charging Units Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Infrastructure Market
Electric Vehicle Charging
Combined Charging System Market
Electric Vehicle Charging
Electric Vehicle AC Charging Pile Market
Electric Vehicle Charging
Electric Vehicle DC Fast Charging Station Market
Electric Vehicle Charging
Electric Vehicle Grid Integration Solutions Market
Electric Vehicle Charging
India Battery Swapping for Electric Two-Wheelers Market
Electric Vehicle Charging
Electric Vehicle Battery Charger Market
Electric Vehicle Charging
Home EV Chargers Market
Electric Vehicle Charging
Electric Vehicle Charger Operations and Maintenance Services Market
Electric Vehicle Charging
Spain Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
Asia-Pacific Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
Home Charging Piles Market
Electric Vehicle Charging
Engineered Polymers in Electric Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle Charger and Charging Station Market