
 Petroleum Fuel Dyes Sales Market | 2026-2036
Petroleum Fuel Dyes Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Petroleum Fuel Dyes Sales Market Insights
EPA fuel marking requirements under the Internal Revenue Code is expanding the compliance burden for dye suppliers entering the North American market. Innospec leverages its integrated additive-dye portfolio to capture refinery-direct contracts. BASF sustains European market presence through REACH-registered azo dye chemistries tailored to diesel and heating oil applications. John Hogg Technical Solutions specializes in custom color-matching systems for national tax authorities.
Petroleum fuel dyes are synthetic colorants, typically solvent-soluble azo or anthraquinone compounds, formulated to withstand hydrocarbon exposure and thermal degradation above 200°C while providing visible or spectroscopic traceability for tax differentiation and quality control. Solvent dyes dominate commercial volume due to their compatibility with gasoline, diesel, and kerosene matrices without phase separation. Oil refineries represent the most concentrated margin pool, as these buyers require bulk procurement with batch certification and technical support that locks in multi-year supply agreements. High-intensity formulations are gaining share in markets with automated optical detection systems for adulteration monitoring.
The EPA enforces fuel dye concentration thresholds through its fuels programs office, while ECHA administers REACH restrictions on aromatic amine content that constrain formulation options in Europe. India's BIS and CDSCO align with excise department rules requiring distinct color coding for subsidized versus market-priced kerosene and diesel. Stakeholders must monitor pending amendments to F-Gas Regulation analogs and national tax-marking budgets, as fiscal policy shifts directly alter dye procurement cycles without warning.
Market Dynamics
EPA fuel marking mandates under the Internal Revenue Code are compressing procurement cycles for dye suppliers, forcing reformulation investments and locking in multi-year refinery contracts before threshold enforcement dates.
Growth Catalysts
- EPA Traceability Mandates:The Internal Revenue Code's fuel dye concentration requirements are expanding addressable demand as distributors stockpile compliant formulations ahead of enforcement windows.
- India:BIS and excise department color-coding rules for subsidized kerosene and diesel are creating dedicated procurement streams for high-visibility solvent dyes.
- Solvent Dye Thermal Stability:Next-generation anthraquinone formulations withstand refinery temperatures above 200°C, opening high-margin bulk supply agreements with integrated oil companies.
Market Restraints
- Raw Material Volatility:Aromatic amine feedstock prices fluctuate with benzene derivative markets, squeezing margin predictability for azo dye manufacturers.
- REACH Registration Burden:ECHA's aromatic amine content restrictions constrain formulation flexibility in Europe, raising compliance costs for cross-border suppliers.
- Optical Detection Substitution:Spectroscopic fuel authentication systems in Germany and the Netherlands reduce reliance on visible dye intensity for tax enforcement.
Strategic Opportunities
- Automated Detection Convergence:Machine vision fuel monitoring systems in India and Brazil require dye formulations calibrated to specific spectral signatures, creating technical partnership openings.
- Biofuel Blending Mandates:Renewable diesel and SAF specifications in the US and Germany demand dyes compatible with oxygenated and paraffinic matrices.
- Direct Refinery Integration:Bypassing additive distributors to inject dyes at the blending terminal captures margin currently held by intermediaries.
Industry Challenges
- Batch Certification Complexity:Each refinery delivery requires spectroscopic verification against EPA or BIS reference standards, extending quality assurance timelines.
- Legacy Storage Infrastructure:Dye degradation in existing tank farms with temperature cycling forces inventory management upgrades at distributor terminals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Petroleum Fuel Dyes Sales Market |
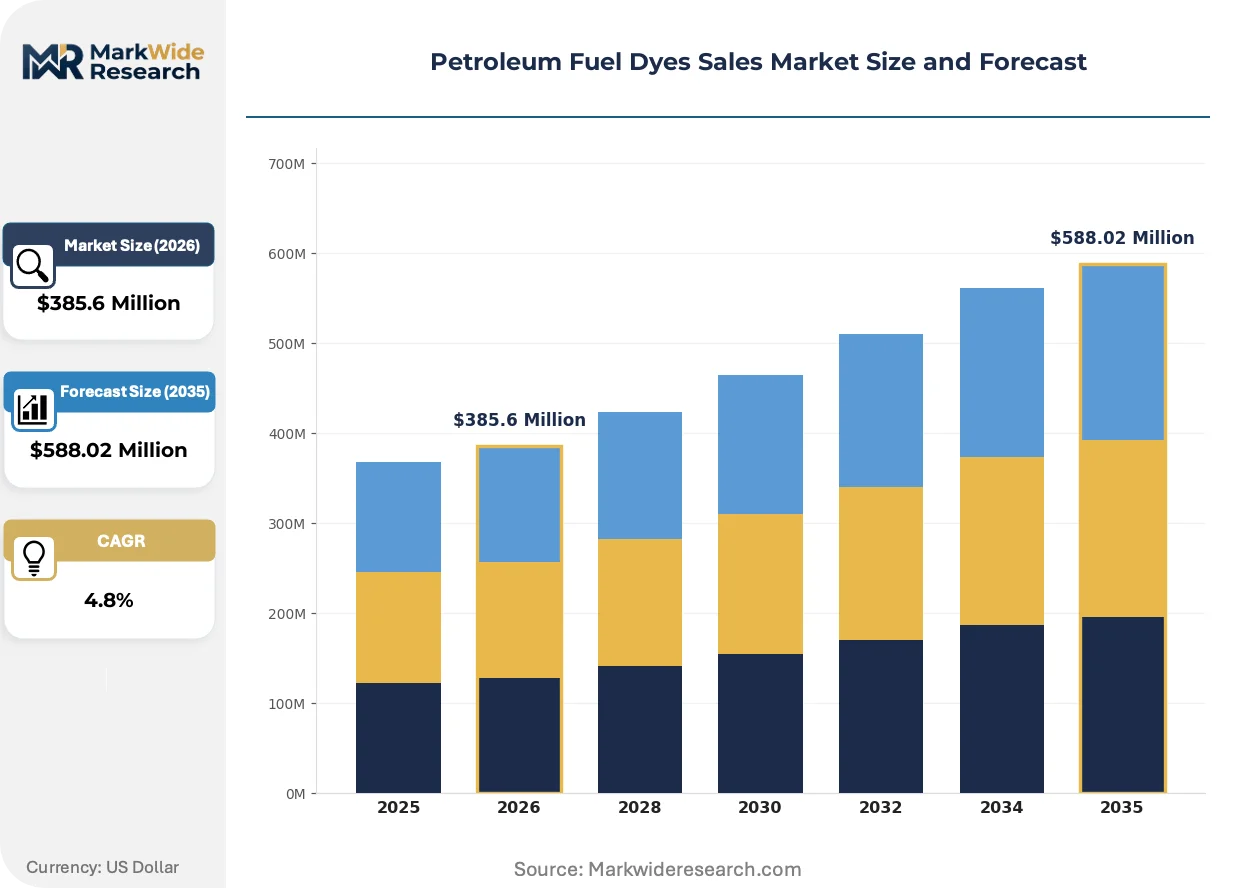
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $588.02 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent Dyes, Food Grade Dyes, Industrial Dyes, Reactive Dyes End User: Oil Refineries, Fuel Distributors, Chemical Manufacturers, Transportation Services Color Intensity: High Intensity, Medium Intensity, Low Intensity, Ultra High Intensity Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | United Color Manufacturing, Innospec, Dow, BASF, Sunbelt Corporation, John Hogg Technical Solutions, Authentix, SGS Société Générale de Surveillance, Johnson Matthey, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Petroleum Fuel Dyes Sales Market Trends and Innovations
Formulation science and detection technology are converging to redefine value capture in fuel marking, with thermal stability and spectral precision replacing commodity color intensity as the primary technical differentiator.
High-performance anthraquinone solvent dyes are absorbing market share from legacy azo formulations in high-temperature refinery applications. Integrated oil companies in the United States and Germany are specifying these chemistries for continuous process injection above 200°C. The shift is compressing margins for thermal-limited dye suppliers while rewarding integrated additive-dye portfolios with technical service capabilities.
REACH restrictions on aromatic amine content are narrowing the formulation toolkit available to European dye manufacturers. ECHA's evolving substance restrictions force reformulation investments that smaller suppliers cannot absorb, consolidating supply relationships around registrants with dedicated regulatory affairs functions. German heating oil and diesel marking applications face the tightest constraints, driving procurement toward pre-registered azo alternatives with documented safety profiles.
Refinery procurement departments are consolidating dye purchasing into multi-year framework agreements with technical support provisions. Direct supply relationships are displacing spot market transactions and additive distributor intermediation in the United States and India. This concentration is most visible among integrated oil companies with centralized blending operations, where batch certification and spectroscopic traceability documentation have become non-negotiable contract terms.
Petroleum Fuel Dyes Sales Market Segmentation
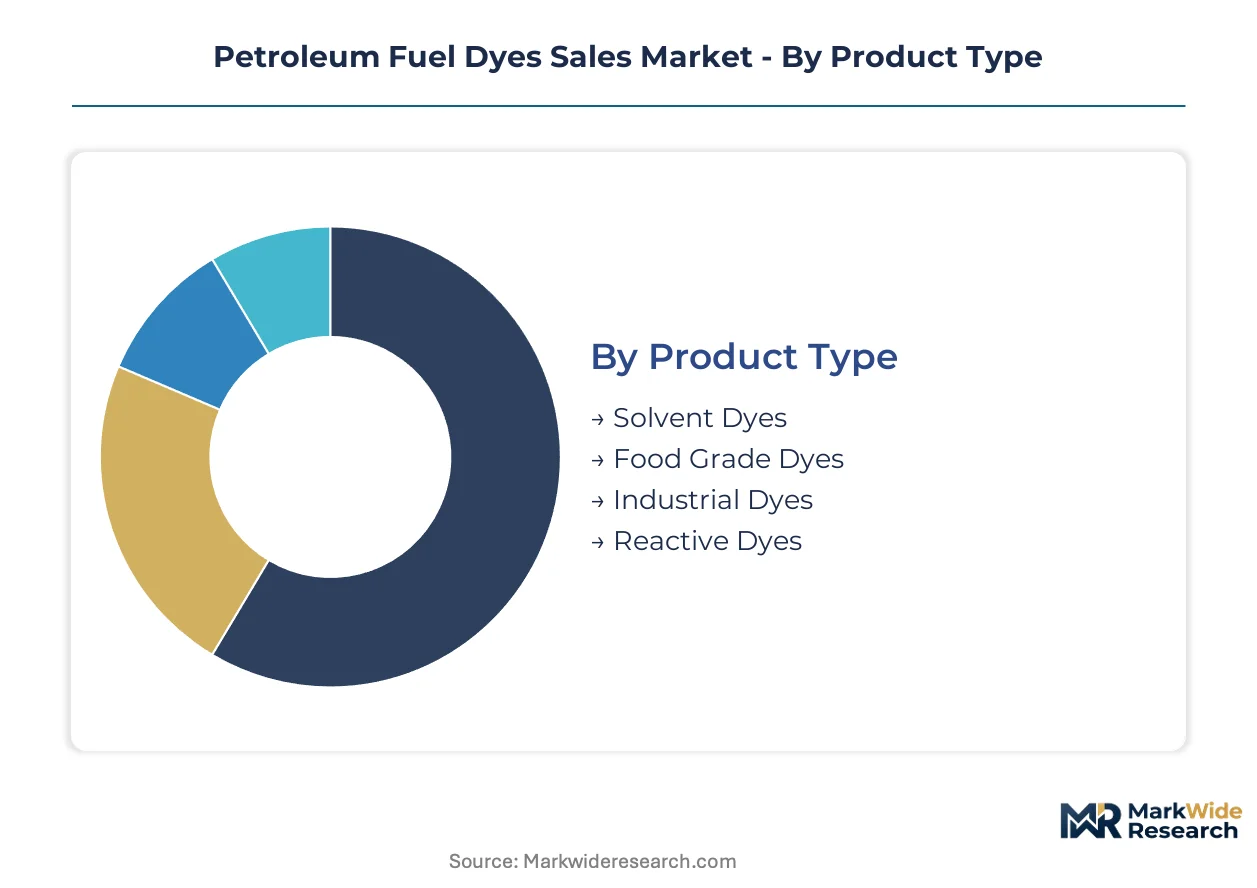
Segmentation in petroleum fuel dyes reveals how certification requirements, thermal specifications, and procurement channels fragment addressable value. Each dimension carries distinct regulatory burdens that determine supplier eligibility and contract structures across refinery and distributor tiers.
Product Type:
Solvent dyes carry EPA fuel marking certification under the Internal Revenue Code, while food grade and reactive alternatives face divergent approval pathways through FDA or industrial chemical registries.
- Solvent Dyes:Anthraquinone and azo-based formulations engineered for hydrocarbon solubility and thermal stability above 200°C. Oil refineries in the United States and Germany specify these chemistries for continuous process injection, with batch certification mandatory under EPA and REACH frameworks.
- Industrial Dyes:Non-certified colorants for lubricant and non-tax fuel applications where spectroscopic traceability is not required. Chemical manufacturers in India absorb volume here for process oil marking without excise compliance overhead.
- Food Grade Dyes:FDA-compliant colorants for incidental fuel contact scenarios in food transport vehicles.
- Reactive Dyes:Chemically unstable in hydrocarbon matrices; minimal penetration in petroleum applications.
Leading the category by volume: Solvent Dyes. Expanding most quickly: Industrial Dyes in non-regulated lubricant segments.
End User:
Procurement scale and technical support intensity separate end user tiers, with integrated oil companies demanding multi-year framework agreements and distributors operating on spot or quarterly contracts.
- Oil Refineries:Centralized blending terminals require bulk procurement with spectroscopic batch certification and on-site technical support. United States-based integrated operators lock in three-to-five year supply agreements, capturing margin through direct injection systems that bypass additive intermediaries.
- Fuel Distributors:Smaller volume procurement across fragmented terminal networks. Indian distributors face BIS color-coding mandates for subsidized kerosene, forcing inventory segmentation between tax-exempt and market-priced fuel streams.
- Chemical Manufacturers:Process oil and solvent marking without excise traceability requirements.
- Transportation Services:Fleet-level fuel marking for theft prevention and quality verification.
Dominant by contract value: Oil Refineries. Fastest procurement cycle compression: Fuel Distributors facing enforcement windows.
Color Intensity:
Detection methodology dictates intensity selection, with automated optical systems in Germany and the Netherlands reducing reliance on visible intensity while India and Brazil maintain human-visual enforcement standards.
- High Intensity:Formulations calibrated for machine vision detection systems and manual inspection alike. German heating oil marking combines high-intensity solvent dyes with spectroscopic authentication, requiring precise spectral signature alignment.
- Ultra High Intensity:Specialized concentrations for adulteration monitoring in high-volume diesel streams. Indian excise departments specify these for subsidized fuel differentiation where dilution detection is critical.
- Medium Intensity:Standard commercial heating oil applications with lower detection stringency.
- Low Intensity:Minimal penetration; largely displaced by regulatory threshold increases.
Highest specification complexity: Ultra High Intensity. Steepest demand trajectory: High Intensity aligning with automated detection rollout.
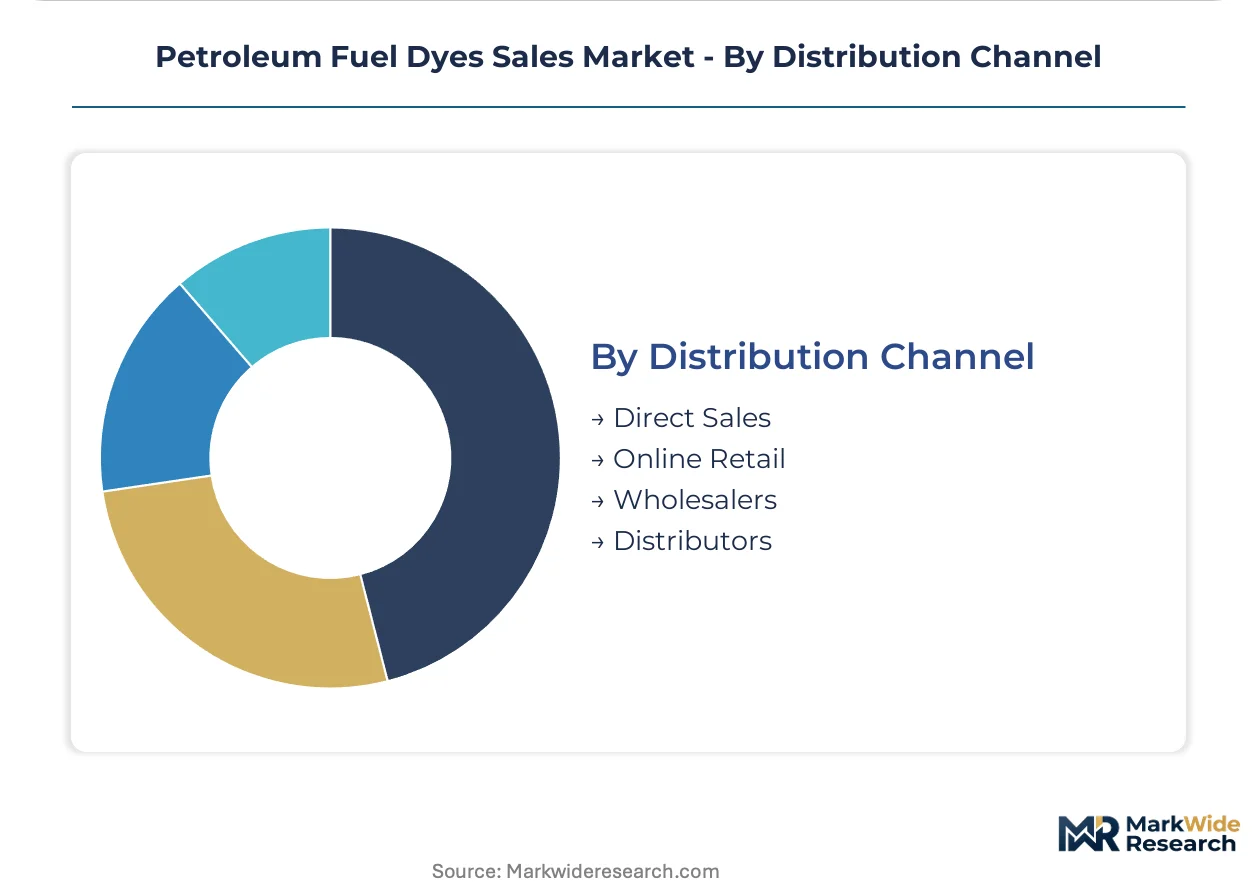
Distribution Channel:
Channel selection reflects buyer scale and technical service requirements, with direct relationships consolidating among refinery operators and intermediaries retaining fuel distributor access.
- Direct Sales:Technical service-intensive contracts with spectroscopic documentation and regulatory compliance support. United States refineries prefer this channel for EPA batch certification requirements, locking in supply security and margin capture.
- Distributors:Regional additive blenders serving fragmented fuel distributor networks. European REACH registration burdens concentrate this channel around established registrants with dedicated regulatory affairs functions.
- Wholesalers:Volume aggregation for smaller chemical manufacturers and transportation fleets.
- Online Retail:Minimal penetration; limited to non-certified industrial dye grades.
Channel concentration leader: Direct Sales. Fastest structural shift: Distributors consolidating around REACH-registered suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for petroleum fuel dyes concentrates in jurisdictions with strict excise enforcement and high refinery throughput. The United States, Germany, India, China, and Brazil collectively absorb the majority of solvent dye procurement for tax differentiation and quality control applications.
United States
Integrated oil companies along the Gulf Coast drive bulk procurement of anthraquinone-based solvent dyes for continuous refinery injection. EPA fuel marking mandates under the Internal Revenue Code compress procurement cycles ahead of enforcement windows. Houston-area blending terminals lock in multi-year framework agreements with direct technical support provisions.
Germany
Heating oil and diesel marking applications face the tightest REACH aromatic amine constraints in Europe. ECHA substance restrictions force procurement toward pre-registered azo alternatives with documented safety profiles. The Rhine-Ruhr industrial corridor concentrates demand among centralized blending operators requiring spectroscopic batch certification.
India
BIS color-coding rules for subsidized kerosene and diesel create dedicated procurement streams for high-visibility solvent dyes. Excise department mandates force distributors to segment inventory between tax-exempt and market-priced fuel streams. The Gujarat refinery cluster anchors volume demand for ultra-high-intensity formulations.
China
State-owned refineries in the Yangtze River Delta specify thermal-stable dye chemistries for high-temperature process injection. National fuel quality standards align with excise traceability requirements for differentiated tax treatment. The Shandong petrochemical corridor drives spot market volume for industrial dye applications.
Brazil
Federal fuel marking programs expand addressable demand as distributors stockpile compliant formulations. ANVISA-aligned quality protocols intersect with excise enforcement for biodiesel blending differentiation. The São Paulo industrial basin concentrates procurement among fuel distributors facing automated detection system rollouts.
Petroleum Fuel Dyes Sales Market Competitive Landscape
United States producers anchor one tier; European specialists hold formulation chemistry positions; Asian manufacturers capture volume in industrial dye segments. The vendor base organizes around three strategic archetypes: integrated additive-dye portfolios, regulatory-focused registrants with dedicated compliance functions, and regional distributors serving fragmented terminal networks. Competitive moves concentrate on direct refinery integration to bypass additive intermediaries and REACH registration investments to sustain European market access.
Among integrated additive specialists, Innospec and BASF exemplify portfolio breadth positions. Innospec occupies a space combining fuel additive and dye capabilities for refinery-direct contracting. BASF anchors the European registrant archetype with pre-registered azo chemistries. John Hogg Technical Solutions sits within the custom formulation tier, representing technical service-intensive positioning for national tax authority relationships.
| Leading Market Players |
|---|
| United Color Manufacturing |
| Innospec |
| Dow |
| BASF |
| Sunbelt Corporation |
| John Hogg Technical Solutions |
| Authentix |
| SGS Société Générale de Surveillance |
| Johnson Matthey |
| Others |
Pricing and Supply Chain Analysis
Anthraquinone solvent dye thermal stability above 200°C is compressing cost structures for high-temperature refinery injection while concentrating procurement power among integrated oil companies with direct terminal access. This chemistry transition simultaneously raises formulation R&D barriers and locks in multi-year supply agreements that displace spot-market intermediaries.
Pricing Analysis
Volume procurement by United States refineries commands contract-based long-term offtake structures with embedded technical service provisions, while Indian fuel distributors operate on quarterly spot arrangements with higher per-unit exposure. Price differentiation hinges on REACH registration status and batch certification depth, with German heating oil applications carrying premium compliance overhead. Cost compression in azo dye tiers is intensifying because aromatic amine feedstock volatility squeezes margin predictability. Fuel distributors facing BIS enforcement windows exhibit highest price sensitivity; integrated oil companies with captive blending terminals show least.
Supply Chain Analysis
Freight cost escalation for temperature-controlled aromatic amine feedstock transport from Germany and China is amplifying regional formulation advantages. Manufacturing concentration centers on Germany, India, and the United States for REACH-registered and EPA-certified production. Feedstock supply draws from benzene derivative markets, naphtha cracking outputs, and specialized anthraquinone intermediates. Single-source vulnerability persists for high-purity solvent dye precursors subject to ECHA substance restrictions. Distribution runs through direct refinery injection systems and regional additive blender networks serving fragmented terminal infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into aromatic amine feedstock supply and direct refinery terminal injection systems constitutes the dominant competitive race, as control over thermal-stable formulation inputs and bypassing distributor intermediaries captures margin pools.
For Market Incumbents: Hedge against optical detection substitution in Germany and the Netherlands by embedding spectroscopic calibration capabilities into dye portfolios. Secure REACH registration extensions for next-generation anthraquinone chemistries before ECHA aromatic amine restrictions tighten. Capacity addition in the Gujarat refinery cluster addresses India's ultra-high-intensity procurement surge. For New Entrants and Emerging Players: Launch via technical partnership models with automated fuel detection system vendors in Brazil and India, supplying dyes pre-calibrated to machine vision spectral signatures. The most penetrable white space sits in biofuel-compatible formulations for renewable diesel and SAF applications in Germany and the United States. Target chemical manufacturers in India's process oil segment where excise compliance overhead is absent. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated additive portfolios seeking dye capabilities for refinery-direct contracting. Long-term viability favors registrants with dedicated regulatory affairs functions spanning EPA and ECHA frameworks. Watch for national tax-marking budget amendments as fiscal policy inflection signals that alter procurement cycles without warning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aromatic Amine Supply | Captive feedstock sourcing from German and Chinese benzene derivative markets insulates margin from volatility. |
| REACH Registration Investment | Pre-registered azo chemistries sustain European market access as ECHA restrictions narrow formulation toolkits. |
| Direct Refinery Terminal Injection | Bypassing additive distributors captures margin currently held by intermediaries in United States Gulf Coast operations. |
| Spectroscopic Calibration Partnership | Machine vision system alignment in Brazil and India creates technical lock-in with automated detection rollouts. |
| Biofuel-Compatible Formulation Development | Oxygenated and paraffinic matrix compatibility addresses renewable diesel mandates in Germany and the United States. |
Research Methodology
Independent corroboration across refinery procurement directors, fuel additive technical managers, and regulatory affairs specialists at REACH registrants underwrites the qualitative findings. Secondary validation draws from EPA fuels program documentation, ECHA substance restriction updates, BIS certification registries, and customs trade data for aromatic amine feedstock flows. Bottom-up volume estimates from individual refinery procurement cycles triangulate against top-down market sizing from additive industry associations.
Comparable-period anchoring to historical enforcement windows and procurement cycle patterns shapes the projection methodology across the analysis window. Segmentation dimensions include dye chemistry family, thermal stability tier, color intensity specification, and distribution channel structure. CAGRs derive from elasticity modeling against excise policy enforcement schedules and refinery capacity expansion timelines. Forecast inputs incorporate BIS color-coding mandate implementation pacing and EPA threshold compliance deadlines.
Regulatory amendment timing, aromatic amine feedstock price shocks, and optical detection technology substitution are the dominant revision risks to modeled outcomes. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Canada Bunker Fuel Market
Fuels
No.2 Diesel Fuel Market
Fuels
Coal Gasification Market
Fuels
Global Chemical Logistics Market
Fuels
Compressed Natural Gas (CNG) Dispenser Market
Fuels
Fuel Oil Market
Fuels
LNG Fueling Station Market
Fuels
India Retail Fuel Market
Fuels
Germany Bunker Fuel Market
Fuels
Asia-Pacific Coal Market
Fuels
India Bunker Fuel Market
Fuels
Briquette Market
Fuels
Ethyl Tertiary Butyl Ether Market
Fuels
Anthracite Coal Mining Market
Fuels
Hydrogen Tube Trailer Market
Fuels
Solid Fuel Tablet Market