
 Japan Bunker Fuel Market | 2026-2036
Japan Bunker Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Bunker Fuel Market Insights
Marine fuel engineering talent scarcity is bifurcating the competitive landscape between integrated refiners and trading houses. ENEOS Corporation leverages its captive refining network across Kawasaki and Negishi to secure feedstock flexibility. Idemitsu Kosan anchors its position through specialized low-sulfur blending capabilities at Chiba. Mitsui & Co. competes by controlling terminal access at Osaka and Nagoya, extending logistics reach to smaller port calls.
Japan bunker fuel denotes residual and distillate marine fuels supplied to ocean-going and coastal vessels, with sulfur content specifications governed by ISO 8217 and the IMO 2020 global cap of 0.50% mass by mass. These fuels power main propulsion engines and auxiliary generators across the commercial fleet calling Japanese ports. LSFO and MGO segments command premium positioning as operators phase out HSFO in coastal routes and ferries serving the Seto Inland Sea. Deep sea applications at Yokohama and Kobe sustain volume leadership, while storage and distribution infrastructure investments concentrate along the Pacific seaboard where tanker traffic density peaks.
METI enforces fuel quality standards aligned with MARPOL Annex VI, while the Japan Coast Guard monitors sulfur compliance through port state control inspections at Tokyo Bay. PMDA and JIS standards indirectly shape marine lubricant and additive specifications that co-evolve with bunker formulations. Stakeholders must track METI's green fuel certification timeline and decide between retrofitting existing supply chains or building ammonia and methanol bunkering capabilities at designated Japanese ports.
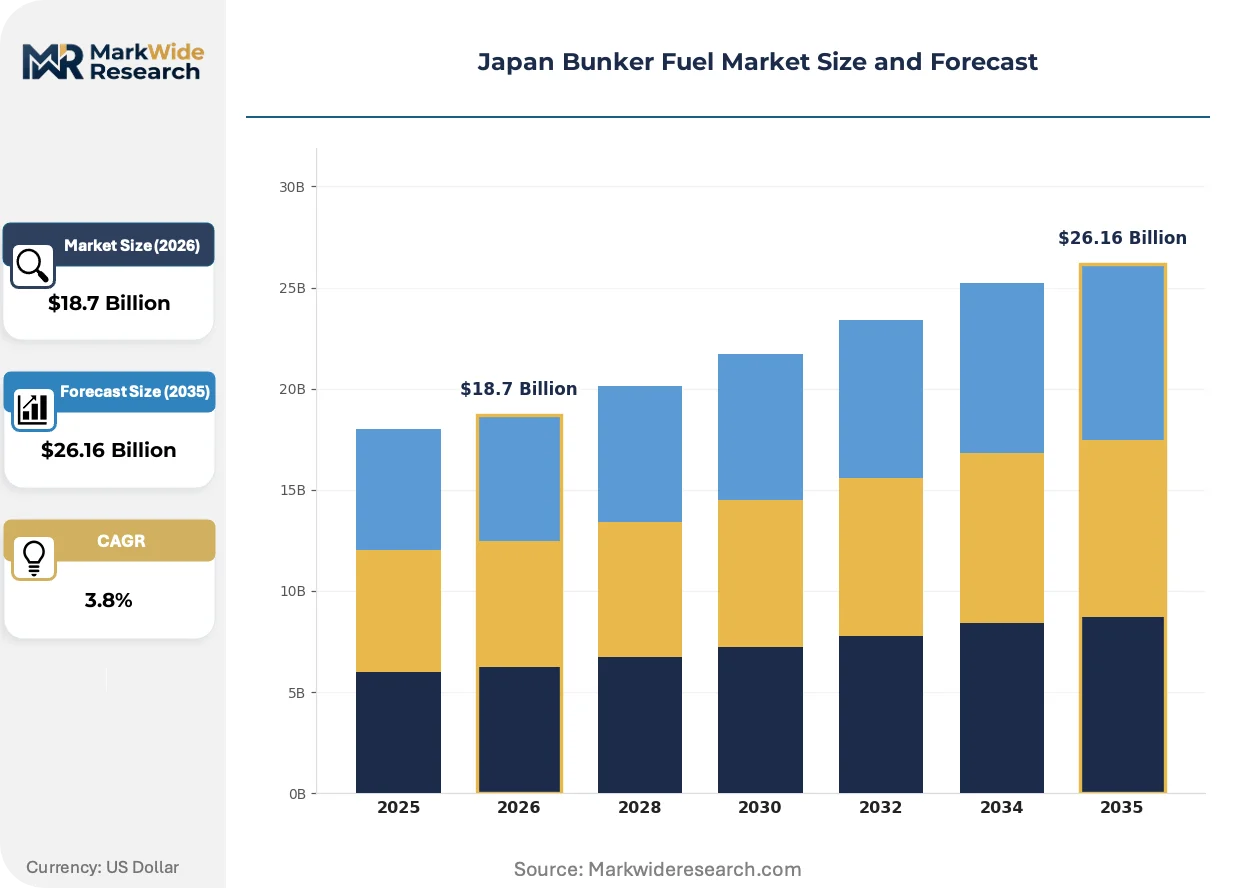
Market Dynamics
METI's carbon neutrality roadmap for maritime fuels is compressing investment timelines across Japan's refining complex. Suppliers must now choose between retrofitting existing infrastructure or building entirely new ammonia and methanol bunkering capabilities at designated ports.
Growth Catalysts
- Container shipping consolidation at Yokohama:Deep-sea liner operators are expanding terminal calls, concentrating bunker demand along Tokyo Bay. Volume density justifies dedicated storage investments.
- IMO 2020 compliance infrastructure:Japanese ports built certified low-sulfur fuel oil blending and testing capabilities ahead of the global sulfur cap. This early positioning now captures redirected regional traffic.
- Ferry electrification delays:Battery technology limitations for Seto Inland Sea routes extend residual fuel demand. Coastal operators continue ordering dual-fuel newbuilds rather than pure electric vessels.
Market Restraints
- Crude feedstock cost volatility:Refiners face margin compression when Middle Eastern crude benchmarks spike. ENEOS and Idemitsu Kosan lack price-pass-through power in contracted bunker supply agreements.
- Terminal access concentration:Osaka and Nagoya storage capacity sits under trading house control. Independent suppliers face capacity rationing during peak demand windows.
- Ammonia toxicity standards:PMDA marine safety protocols for toxic fuel handling remain incomplete. Early movers risk stranded asset exposure if certification timelines slip.
Strategic Opportunities
- Kyushu port underpenetration:Kitakyushu and Nagasaki call volumes lag Pacific corridor density. Greenfield methanol bunkering investments could capture rising Southeast Asia-Japan trade loops.
- Ship-to-ship transfer automation:Robotics-enabled offshore bunkering reduces port congestion charges. Technology convergence between autonomous vessels and fueling systems enables new service models.
- METI green fuel certification timeline:Early certification for synthetic marine fuels creates first-mover premium positioning. Suppliers aligning testing protocols with draft standards secure offtake priority.
Industry Challenges
- Marine fuel engineering talent scarcity:Specialized low-sulfur blending expertise concentrates at Chiba and Yokkaichi facilities. Competitors struggle to replicate Idemitsu Kosan's technical workforce depth.
- Dual-fuel engine certification complexity:ClassNK approval timelines for ammonia-compatible propulsion systems extend 18-24 months. Shipowners defer newbuild commitments pending operational certainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Bunker Fuel Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: HSFO, LSFO, MGO, ULSFO Vessel Type: Container Ships, Bulk Carriers, Tankers, Ferries Supply Chain Stage: Refining, Storage, Distribution, Delivery Application: Deep Sea, Coastal, Inland, Others |
| Companies Covered | ENEOS Corporation, Idemitsu Kosan Co., Ltd., Cosmo Energy Holdings Co., Ltd., Mitsui & Co., Ltd., Marubeni Corporation, Mitsubishi Corporation, Shell plc, PetroChina Company Limited, Bunker Holding, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Bunker Fuel Market Trends and Innovations
Maritime decarbonization mandates are forcing rapid fuel formulation evolution across Japanese supply chains. Refiners and trading houses are racing to certify next-generation marine fuels ahead of competitor ports.
Biofuel blending is displacing conventional marine gas oil in coastal ferry operations. Operators serving the Seto Inland Sea are trialing B30 and B50 formulations to meet voluntary carbon reduction targets. This displacement is compressing demand for straight-run distillates in short-sea segments where fuel switching costs remain manageable.
METI's draft ammonia bunkering safety guidelines are reshaping terminal investment priorities. The framework mandates dedicated handling infrastructure and crew certification protocols that exceed existing LNG bunkering requirements. Osaka and Kobe port authorities are accelerating berth modifications to maintain parity with Singapore and Rotterdam regulatory readiness.
Long-term contracting is replacing spot procurement among container lines calling Tokyo Bay. Major operators now seek 12-24 month supply agreements with fixed pricing bands and guaranteed sulfur compliance. This behavioral shift concentrates volume with integrated refiners possessing captive blending capacity, marginalizing trading houses dependent on third-party terminal access.
Japan Bunker Fuel Market Segmentation
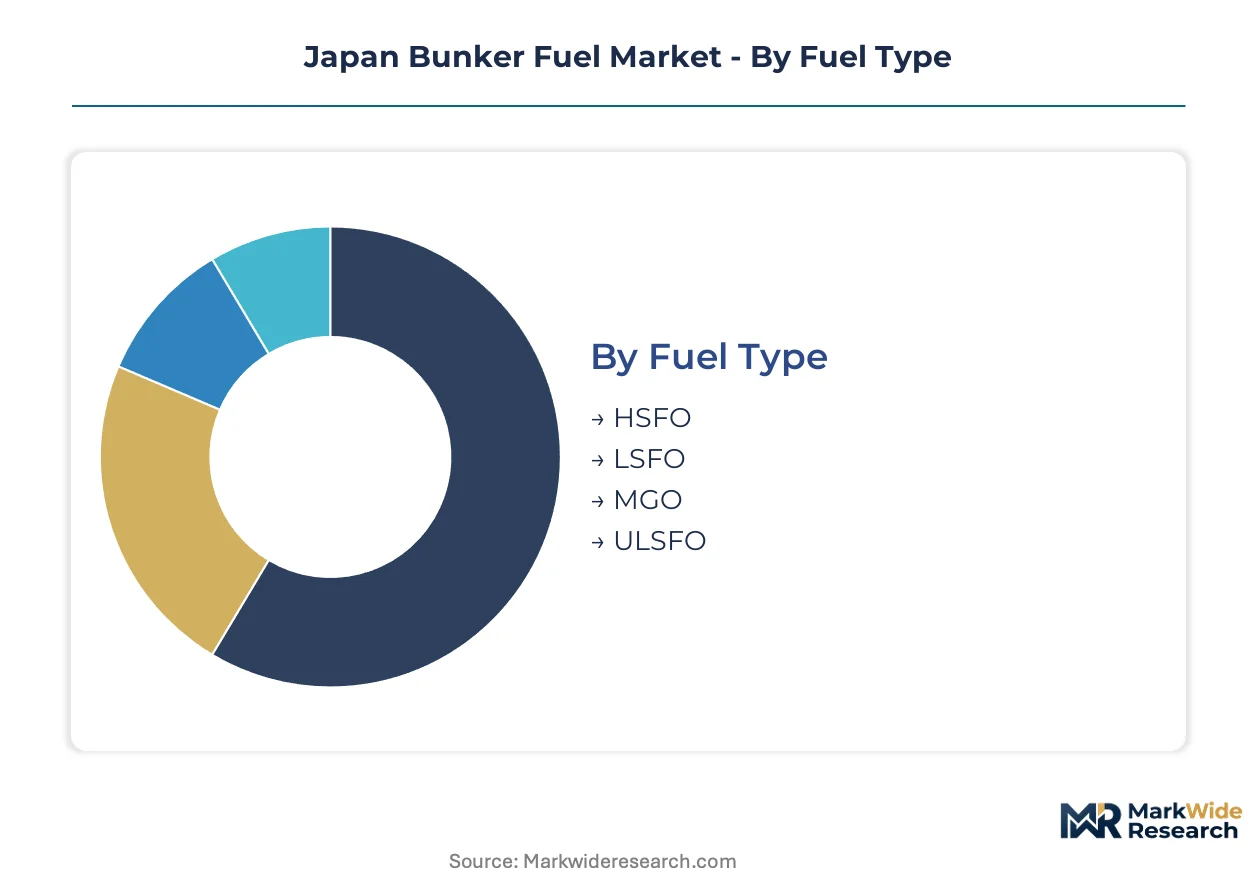
Japan's bunker fuel segmentation reflects the tension between legacy residual fuel demand and accelerating marine fuel transition. Fuel type and vessel categories determine infrastructure investment priorities across the Pacific coastal corridor.
Fuel Type:
Substitution pressure from ammonia and methanol bunkering programs threatens residual fuel segments most acutely, while distillate grades retain defensive positioning through dual-fuel engine compatibility requirements.
- HSFO:High-sulfur residual fuel oil exceeding 0.50% sulfur mass by mass, now restricted to vessels equipped with exhaust gas cleaning systems. Demand concentrates at Yokohama and Kobe for scrubber-fitted bulk carriers on long-haul routes, though METI's carbon neutrality timeline compresses the retrofit payback window.
- LSFO:Low-sulfur fuel oil blended to meet IMO 2020 specifications through vacuum gas oil and residual stream mixing. Blending capabilities at Chiba and Negishi refineries anchor supply security for container lines operating Tokyo Bay terminal rotations.
- MGO:Marine gas oil, a distillate fuel with sulfur content below 0.10% mass by mass, serving auxiliary engines and cold-weather operations. Ferries serving the Seto Inland Sea rely on MGO for operational flexibility where bunkering frequency constraints apply.
- ULSFO:Ultra-low-sulfur fuel oil with sulfur content capped at 0.10% mass by mass, positioned for emission control area compliance. Japanese ports developed certified ULSFO supply chains ahead of regional competitors, capturing redirected traffic from non-compliant Asian hubs.
LSFO retains volume leadership across Japanese ports; ULSFO holds the steepest expansion curve as emission control area boundaries extend.
Vessel Type:
Cost tier differentiation separates deep-sea operators with contracted supply agreements from coastal fleets dependent on spot market access.
- Container Ships:Liner operators with fixed schedules and high fuel consumption density command preferential terminal access at Yokohama and Osaka. These vessels drive long-term contracting behavior, concentrating volume with integrated refiners possessing captive blending capacity.
- Bulk Carriers:Dry cargo vessels with variable routing patterns and scrubber retrofit heterogeneity create demand fragmentation across HSFO and LSFO grades. Spot procurement dominance exposes operators to margin volatility when Middle Eastern crude benchmarks spike.
- Tankers:Liquid cargo vessels with specialized safety requirements and dedicated berth allocations at Chiba and Kawasaki. Product tankers on coastal routes sustain residual fuel demand where electrification timelines remain uncertain.
- Ferries:Passenger and vehicle carriers operating fixed coastal schedules, particularly across the Seto Inland Sea. Battery technology limitations for these routes extend distillate fuel demand as operators defer pure electric commitments.
Container ships anchor revenue concentration for integrated suppliers; ferries represent the most contested segment as biofuel blending trials accelerate.
Supply Chain Stage:
Geographic concentration of infrastructure assets along the Pacific seaboard determines competitive access and margin capture.
- Refining:Captive processing capacity at Kawasaki, Negishi, and Yokkaichi facilities secures feedstock flexibility for integrated refiners. ENEOS Corporation leverages this backward integration to manage crude cost volatility that compresses trading house margins.
- Storage:Terminal capacity concentration at Osaka and Nagoya under trading house control creates rationing risk during peak demand windows. Independent suppliers face capacity constraints when container line scheduling concentrates calls.
- Distribution:Barge and pipeline networks linking refining complexes to coastal bunkering points, with density peaking across Tokyo Bay. Logistics reach extensions to smaller port calls differentiate trading house service models.
- Delivery:Ship-to-ship transfer operations and quayside bunkering services, where automation investments in robotics-enabled offshore fueling reduce port congestion charges. Technology convergence between autonomous vessels and fueling systems enables new service tiering.
Refining commands the deepest margin capture; delivery infrastructure is climbing the fastest as METI's green fuel certification timeline accelerates berth modification investments.
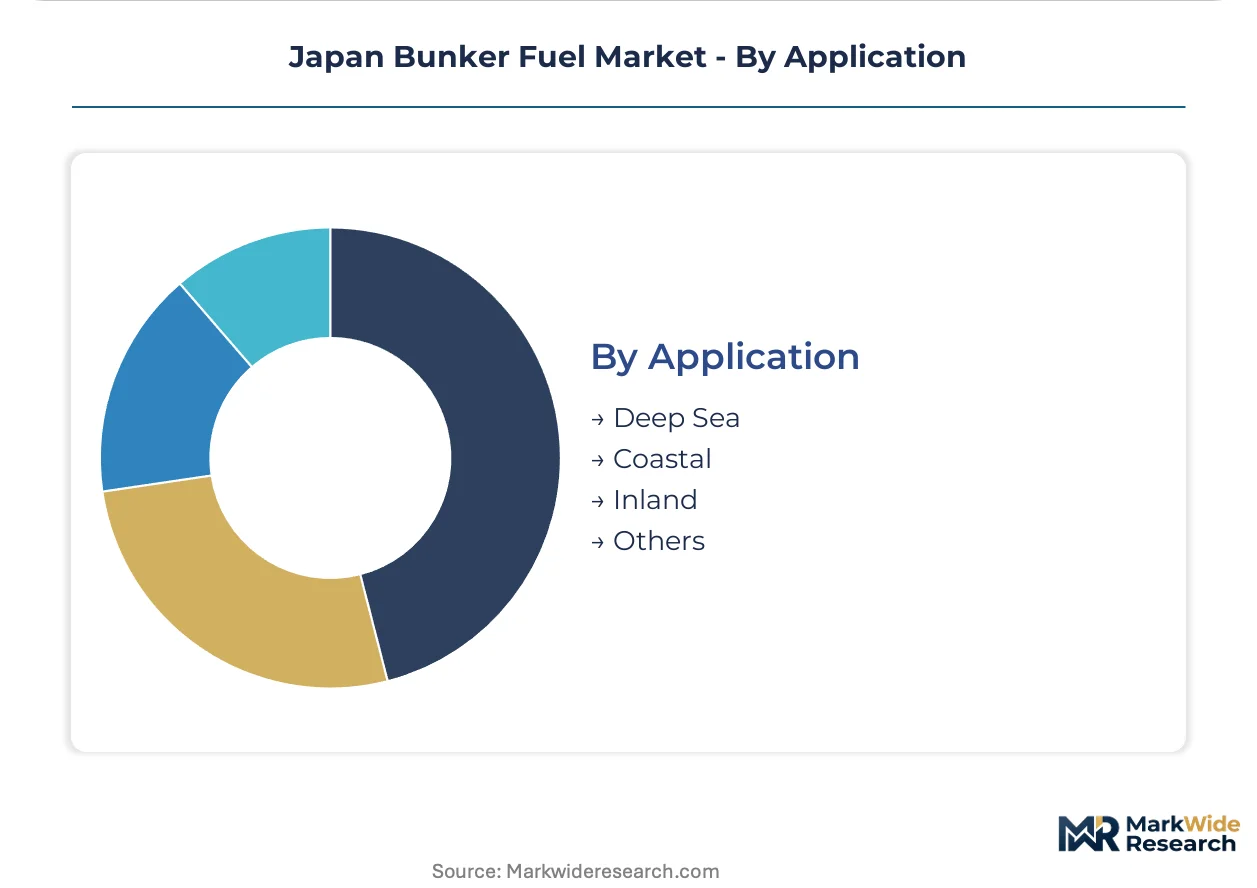
Application:
Operational intensity and regulatory exposure separate segments with transition clarity from those facing technological uncertainty.
- Deep Sea:Intercontinental voyages calling Yokohama and Kobe, where fuel switching costs and engine certification complexity delay ammonia adoption. ClassNK approval timelines for ammonia-compatible propulsion systems extend newbuild commitment deferrals.
- Coastal:Short-sea routes along the Pacific corridor and across the Seto Inland Sea, where biofuel blending trials are displacing straight-run distillates. B30 and B50 formulations serve voluntary carbon reduction targets with manageable switching costs.
- Inland:Waterway operations with limited penetration in Japan's geography, concentrated around Lake Biwa and certain river systems. Regulatory attention from METI remains minimal compared to maritime priorities.
- Others:Specialized applications including offshore support vessels and research fleet operations with customized fuel specifications. PMDA marine safety protocols for toxic fuel handling remain incomplete for these niche segments.
Deep sea applications retain volume leadership; coastal operations are gaining share fastest as ferry electrification delays extend residual fuel demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's carbon neutrality roadmap for maritime fuels anchors investment planning across Japan's Pacific coastal corridor. Refiners and trading houses concentrate infrastructure along Tokyo Bay and the Seto Inland Sea where vessel traffic density peaks.
Kanto/Tokyo
Container shipping consolidation at Yokohama and Chiba drives bunker fuel demand density. METI enforces fuel quality standards aligned with MARPOL Annex VI through port state control inspections. ENEOS Corporation leverages captive refining capacity at Kawasaki and Negishi to secure feedstock flexibility for contracted supply agreements.
Kansai/Osaka
Terminal access concentration at Osaka and Kobe creates rationing risk during peak demand windows. The Japan Coast Guard monitors sulfur compliance through dedicated inspection protocols. Trading houses anchor storage and distribution networks linking refining complexes to coastal bunkering points across Osaka Bay.
Chubu/Nagoya
Idemitsu Kosan anchors specialized low-sulfur blending capabilities at Yokkaichi facilities. PMDA marine safety protocols for toxic fuel handling shape investment timelines for ammonia bunkering readiness. The industrial cluster sustains residual fuel demand where electrification timelines for coastal routes remain uncertain.
Kyushu
Kitakyushu and Nagasaki call volumes lag Pacific corridor density, creating underpenetration for greenfield methanol bunkering investments. METI's draft ammonia bunkering safety guidelines mandate dedicated handling infrastructure exceeding existing LNG requirements. Port authorities accelerate berth modifications to capture rising Southeast Asia-Japan trade loops.
Seto Inland Sea
Ferry operators serving fixed coastal schedules sustain distillate fuel demand as battery technology limitations extend residual fuel reliance. Biofuel blending trials displace straight-run marine gas oil in short-sea segments. Dual-fuel newbuild commitments dominate procurement patterns pending ClassNK approval timelines for ammonia-compatible propulsion systems.
Japan Bunker Fuel Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Japan's bunker fuel supply structure. Captive refining capacity separates integrated refiners from trading houses dependent on third-party terminal access. Three archetypes dominate: backward-integrated refiners with blending capabilities, trading houses controlling logistics reach, and international majors leveraging global supply networks. Competitive moves concentrate on long-term contracting structures and berth modification investments for green fuel certification.
Among integrated refiners, ENEOS Corporation and Idemitsu Kosan Co., Ltd. exemplify the backward-integration archetype through captive processing networks. Mitsui & Co., Ltd. represents trading house positioning through terminal access concentration. These three entities anchor competitive dynamics as METI's certification timeline accelerates infrastructure differentiation between retrofit and greenfield investment pathways.
| Leading Market Players |
|---|
| ENEOS Corporation |
| Idemitsu Kosan Co., Ltd. |
| Cosmo Energy Holdings Co., Ltd. |
| Mitsui & Co., Ltd. |
| Marubeni Corporation |
| Mitsubishi Corporation |
| Shell plc |
| PetroChina Company Limited |
| Bunker Holding |
| Others |
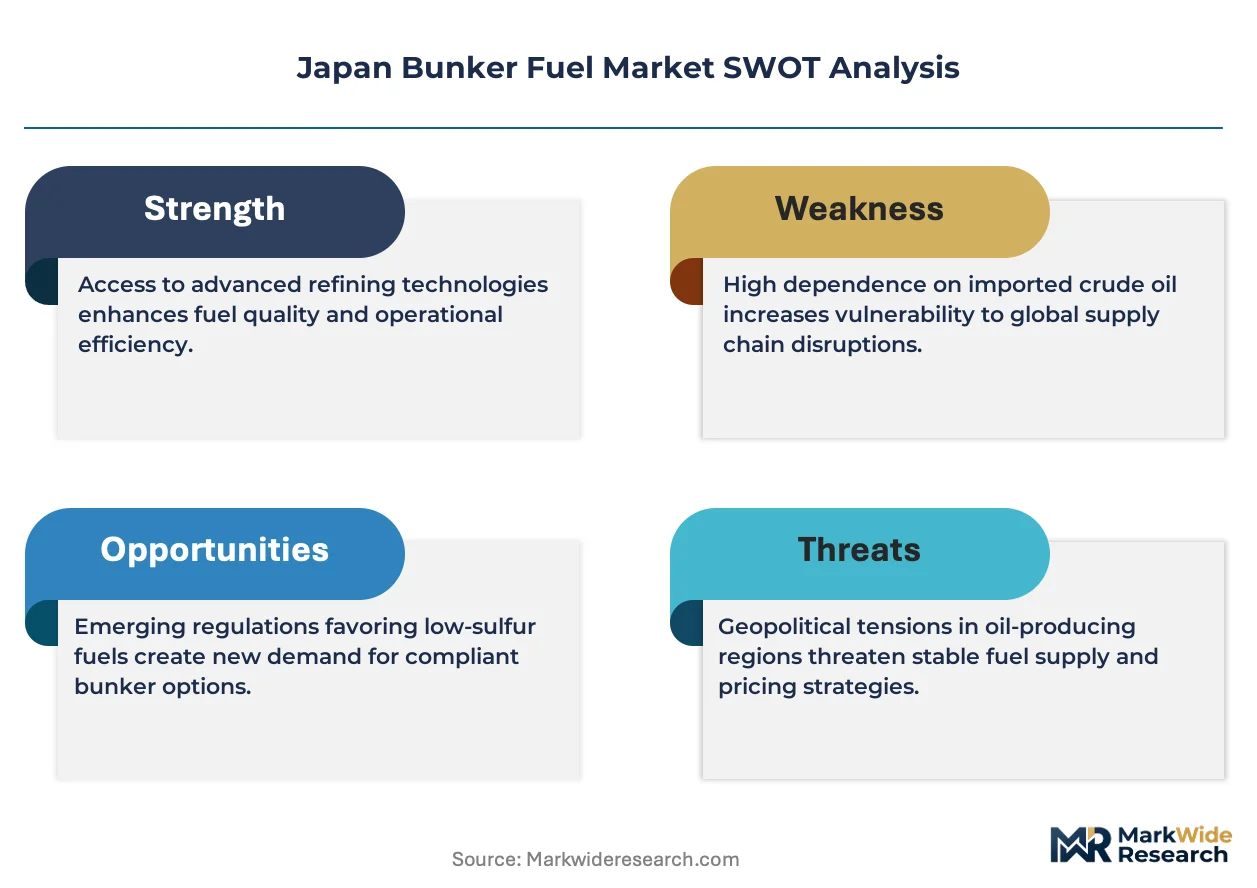
Pricing and Supply Chain Analysis
Tank farm utilization rates at Chiba and Yokkaichi refineries anchor price floors across the Pacific coastal corridor. Scale economies in low-sulfur blending concentrate margin capture with integrated suppliers, forcing trading houses to absorb logistics premiums when terminal access tightens.
Pricing Analysis
Price spreads between Tokyo Bay and Osaka Bay reflect terminal access concentration rather than crude cost differentials. Contract-based long-term offtake dominates container line procurement, with price differentiation driven by sulfur certification grade and volume scale commitments. Cost compression in spot-traded HSFO is intensifying because scrubber retrofit payback windows compress under METI's carbon neutrality timeline. Bulk carriers dependent on spot procurement exhibit highest price sensitivity; container lines with fixed schedules show lowest sensitivity due to operational inflexibility.
Supply Chain Analysis
Middle Eastern crude transit through the Strait of Hormuz underwrites feedstock security for Kawasaki and Negishi refining complexes. Geographic supply concentration centers on Japan, South Korea, and Singapore for certified low-sulfur blending components. Raw material dependencies include vacuum gas oil, residual fuel streams, and marine gas oil distillates. Single-source vulnerability concentrates in terminal access at Osaka and Nagoya under trading house control. Distribution runs through barge networks linking refining complexes to coastal bunkering points across Tokyo Bay.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as METI's green fuel certification timeline splinters demand between retrofit infrastructure and greenfield ammonia bunkering investments. Ferry electrification delays and dual-fuel engine certification complexity create service niches between legacy fuel supply and next-generation capabilities.
For Market Incumbents: Shield contracted volume positions by accelerating berth modification investments at Yokohama and Kobe ahead of competitor port readiness. Deepen backward integration into synthetic marine fuel testing protocols to capture METI certification priority. Terminal access rationing during peak demand windows represents the primary threat; captive refining capacity remains the critical defensive lever. For New Entrants and Emerging Players: Automated ship-to-ship transfer services at Kitakyushu and Nagasaki address incumbent under-service of smaller port calls. Target Kyushu greenfield methanol bunkering infrastructure where Pacific corridor density lags. Biofuel blending trials for Seto Inland Sea ferries offer the most penetrable entry segment; partner with coastal operators on B30 and B50 formulation certification. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated refiners with captive blending capacity and long-term container line contracts. Five-to-ten-year viability favors suppliers with dual-pathway flexibility across conventional low-sulfur fuels and ammonia bunkering readiness. Acquisition target archetype: regional trading houses with terminal access but lacking green fuel certification alignment. Watch METI's draft ammonia safety guideline finalization as the critical inflection signal for infrastructure investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Ammonia Bunkering Infrastructure Buildout | Osaka and Kobe port authorities accelerate berth modifications to match Singapore regulatory readiness. |
| Long-term Supply Agreement Restructuring | Container lines seek 12-24 month contracts with fixed pricing bands and guaranteed sulfur compliance. |
| Backward Integration into Synthetic Fuel Testing | Early certification alignment with METI draft standards secures offtake priority for integrated refiners. |
| Ship-to-Ship Transfer Automation Investment | Robotics-enabled offshore fueling reduces port congestion charges and enables new service tiering. |
| Biofuel Blending Certification Program | B30 and B50 formulations for Seto Inland Sea ferries capture voluntary carbon reduction targets. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with marine fuel procurement managers, refinery operations directors, and port authority planning officers; and secondary validation through METI policy documents, Japan Coast Guard inspection records, and ClassNK certification filings. Bottom-up volume modeling triangulated against top-down macroeconomic indicators across the Japanese maritime sector.
Across the analysis window, the forecast framework modeled fuel type substitution dynamics, vessel category demand intensity, and supply chain stage margin capture. CAGRs derived from segment-level volume trajectories weighted by price realization trends. Key inputs included crude benchmark volatility patterns, IMO regulatory compliance timelines, and METI green fuel certification progress.
Underlying assumptions cover continued IMO 2020 enforcement stringency and METI carbon neutrality commitment durability, with deviation risk concentrated in ammonia toxicity standard finalization delays and dual-fuel engine certification timeline extensions. Practitioners should keep alternative scenarios live as ClassNK approval protocols and PMDA marine safety guidelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
North America Commercial Aircraft Aviation Fuel Market
Fuels
Fuel Quality Testing Market
Fuels
Oil Dispenser Market
Fuels
Solid Fuel Tablet Market
Fuels
Global Gas Treatment Market
Fuels
Asia-Pacific Bunker Fuel Market
Fuels
Gas and Solid Fuels (Wood) Fireplaces Market
Fuels
LNG Filling Station Market
Fuels
Caribbean Islands Bunker Fuel Market
Fuels
Italy Chemical Logistics Market
Fuels
Europe Defense Aircraft Aviation Fuel Market
Fuels
LNG As a Fuel Market
Fuels
City Gas Distribution Market
Fuels
Europe Firewood Market
Fuels
Asia-Pacific Commercial Aircraft Aviation Fuel Market
Fuels
South America Bunker Fuel Market