
 Europe Firewood Market | 2026-2036
Europe Firewood Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Firewood Market Insights
Automated kiln-drying and moisture-control sensor integration is tilting firewood processing toward precision-manufactured fuel grades. B&P Brennholz & Pfahl leverages vertical integration across Baltic sourcing networks to secure consistent hardwood feedstock. ZOH Wood AB anchors its position through specialized seasoning infrastructure that commands premium pricing in Scandinavian retail channels. Holz & Feuer GmbH competes by controlling last-mile bulk delivery logistics across German-speaking markets.
Europe firewood comprises cut, split, and seasoned woody biomass—typically oak, beech, birch, or softwood species—dried to moisture content below 20 percent for efficient combustion in stoves, boilers, and fireplace inserts. The product serves residential heating, commercial hospitality, and small-scale industrial thermal applications where grid gas access remains limited or cost-prohibitive. Logs dominate value capture in Alpine and Eastern European markets where traditional stove penetration remains deepest, while pellets lead growth trajectories as automated boiler retrofits accelerate in France and Italy. Packaged retail formats sustain margin pools through certified sustainability labeling, though bulk delivery retains volume leadership in rural and agricultural end-use segments.
The EU Green Deal biomass sustainability criteria, the Ecodesign Directive's emission thresholds for solid fuel appliances, and national implementations of the Renewable Energy Directive shape product standards across member states. ECHA's REACH framework governs chemical treatment restrictions, while FSC and PEFC chain-of-custody certification increasingly gates market access in German and Austrian retail channels. Stakeholders must monitor evolving national calorific-value testing protocols and carbon-accounting methodologies that will determine which feedstock grades retain commercial viability under tightened greenhouse-gas balancing rules.
Market Dynamics
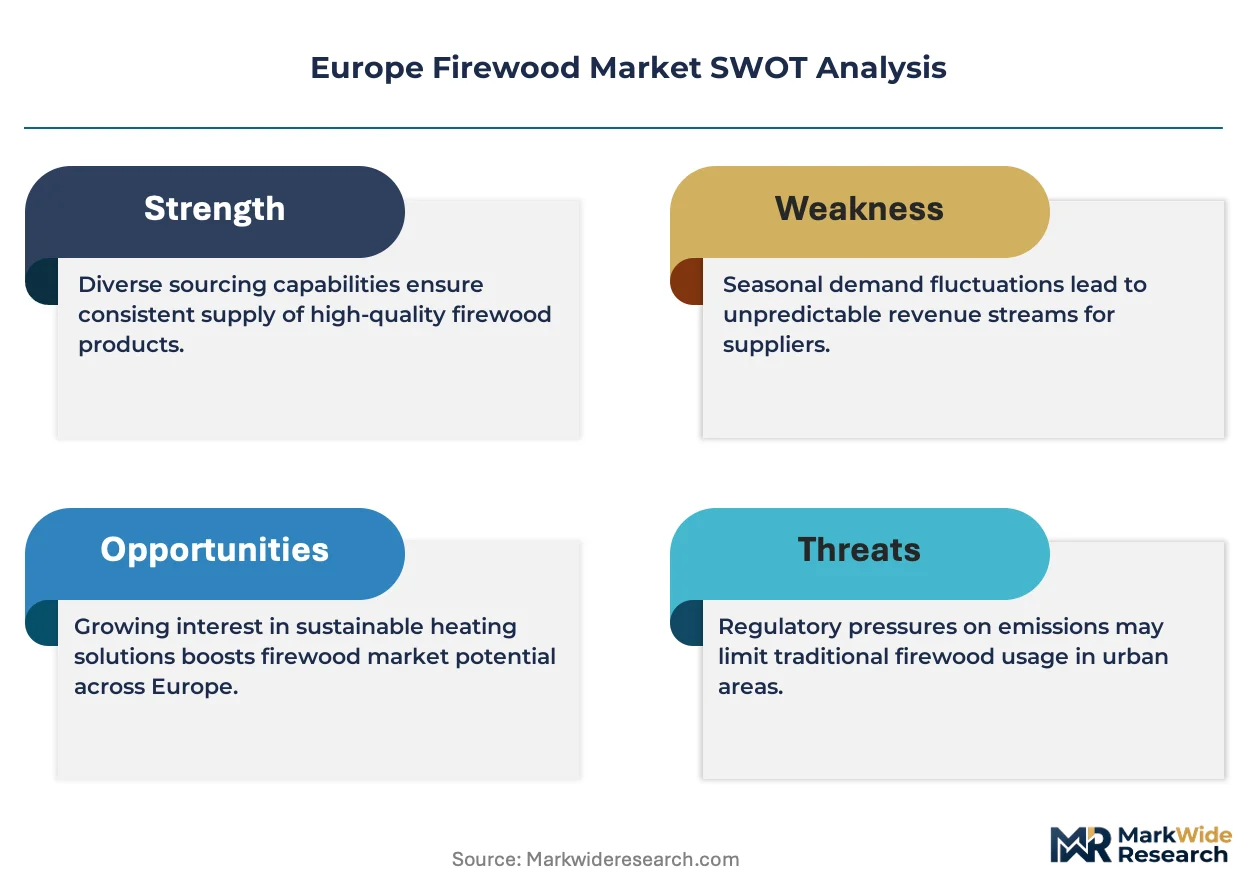
The EU Green Deal's tightening biomass sustainability criteria are restructuring firewood supply chains across member states, forcing processors to invest in certified kiln-drying infrastructure and chain-of-custody documentation systems that smaller regional suppliers cannot replicate.
Growth Catalysts
- Ecodesign Directive emission thresholds:Stove and boiler manufacturers in Germany and Austria now specify sub-20% moisture content firewood, creating certified-grade demand that commands pricing premiums in retail channels.
- Rural off-grid housing persistence:Alpine and Eastern European agricultural properties sustain bulk procurement volumes where grid gas extension remains economically unviable for utilities.
- FSC and PEFC certification penetration:Austrian and German retail channels increasingly gate market access through chain-of-custody requirements that favor established processors with documentation systems.
Market Restraints
- Hardwood feedstock concentration:Baltic sourcing networks control premium oak and beech supply, exposing mid-market processors to volume allocation risk during peak heating seasons.
- Seasoning infrastructure capex intensity:Automated moisture-control sensor integration and covered drying yards require capital deployment that fragments competitive tiers between integrated and merchant suppliers.
- Pellet substitution in automated systems:French and Italian boiler retrofits favor pellet formats for automated feed mechanisms, compressing log-format growth in district heating applications.
Strategic Opportunities
- Polish district heating retrofits:Municipal systems transitioning from coal present bulk procurement contracts for certified biomass suppliers with established logistics networks.
- Packaged retail format expansion:Sustainability-labeled convenience formats in Scandinavian urban markets capture margin pools through premium positioning in hardware and garden center channels.
- Carbon-accounting methodology alignment:Early adoption of greenhouse-gas balancing protocols positions suppliers for preferential treatment under evolving national renewable heat incentive schemes.
Industry Challenges
- Moisture-content testing protocol fragmentation:Divergent national calorific-value standards across Germany, France, and Poland complicate cross-border product certification and batch documentation.
- Last-mile logistics reconfiguration:Bulk delivery fleet optimization for rural agricultural end-users requires route density that conflicts with seasonal demand concentration in heating months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Firewood Market |
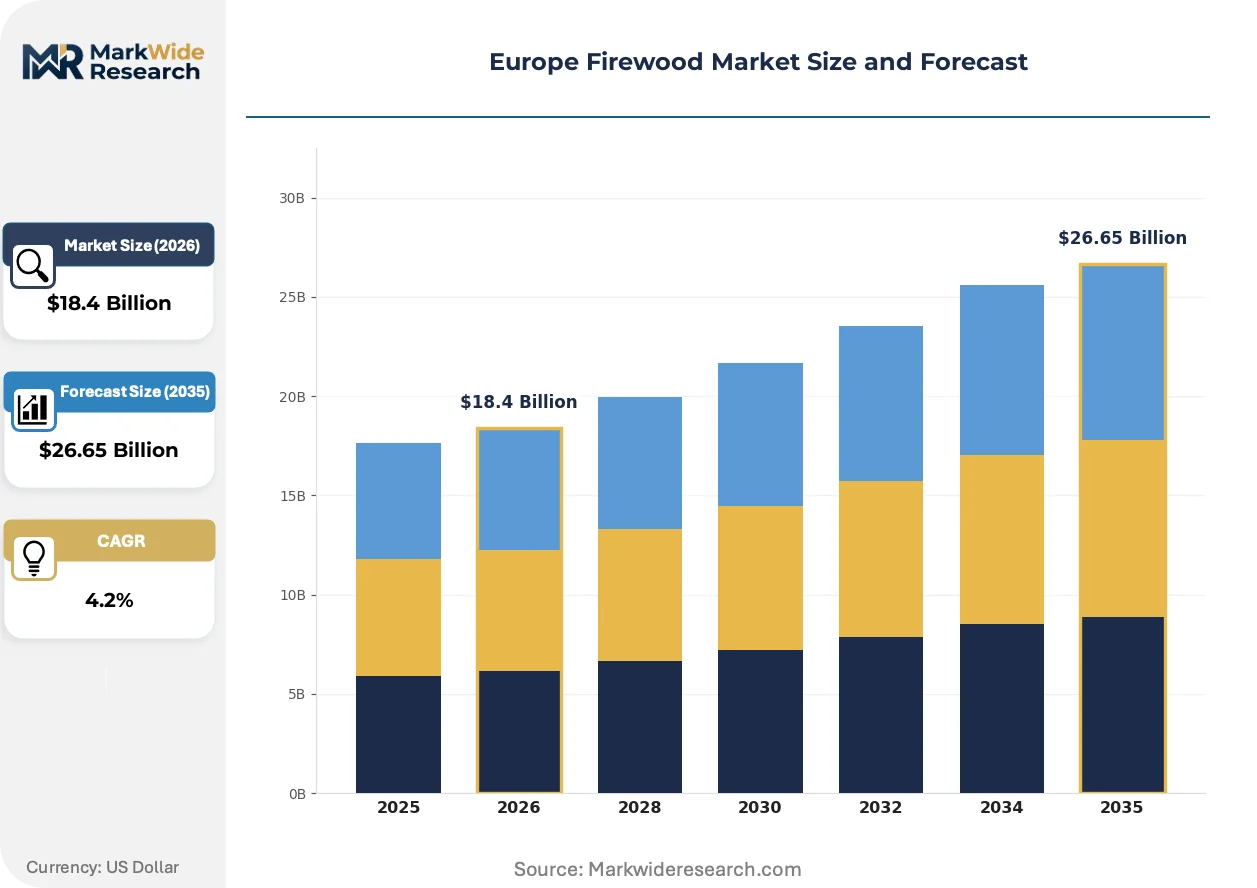
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $26.65 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Logs, Pellets, Chips, Bricks Delivery Method: Bulk, Packaged, Retail, Online End User: Residential, Commercial, Industrial, Agriculture Firewood Grade: Seasoned, Green, Hardwood, Softwood |
| Companies Covered | B&P Brennholz & Pfahl, Holz & Feuer GmbH, ZOH Wood AB, ROSTES WOOD, Holzhof Stormarn GmbH, ABB Holz GmbH, Drusedau SP. Z O.O, Surefire Wood, ALBAN technische Anlagen GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Firewood Market Trends and Innovations
Firewood processing is migrating from artisanal seasoning yards toward precision-manufactured fuel grades with integrated quality verification, reshaping competitive differentiation around documented combustion performance rather than origin reputation alone.
Automated kiln-drying with real-time moisture telemetry is migrating from industrial pellet producers to mid-scale log processors serving residential heating markets. German and Austrian stove manufacturers now specify certified fuel grades in warranty documentation, accelerating retailer demand for documented sub-20% moisture content. This specification migration from recommendation to contractual requirement is compressing informal supplier participation in premium retail channels.
The EU Green Deal biomass sustainability criteria are tightening chain-of-custody documentation requirements across member states. Processors must now verify feedstock origin and drying energy sources to retain commercial viability under greenhouse-gas balancing rules. Nordic and Alpine retail channels are responding fastest, with Swedish and Austrian distributors requiring PEFC or FSC certification for shelf placement.
Buyer preference is consolidating around certified sustainability labeling that documents carbon intensity and forest management practices. Traditional origin-based purchasing in rural agricultural segments is yielding to specification-driven procurement in district heating and commercial hospitality applications. This behavioral shift is most visible in German-speaking markets, where hardware retailers now merchandise firewood by certified grade rather than species origin alone.
Europe Firewood Market Segmentation
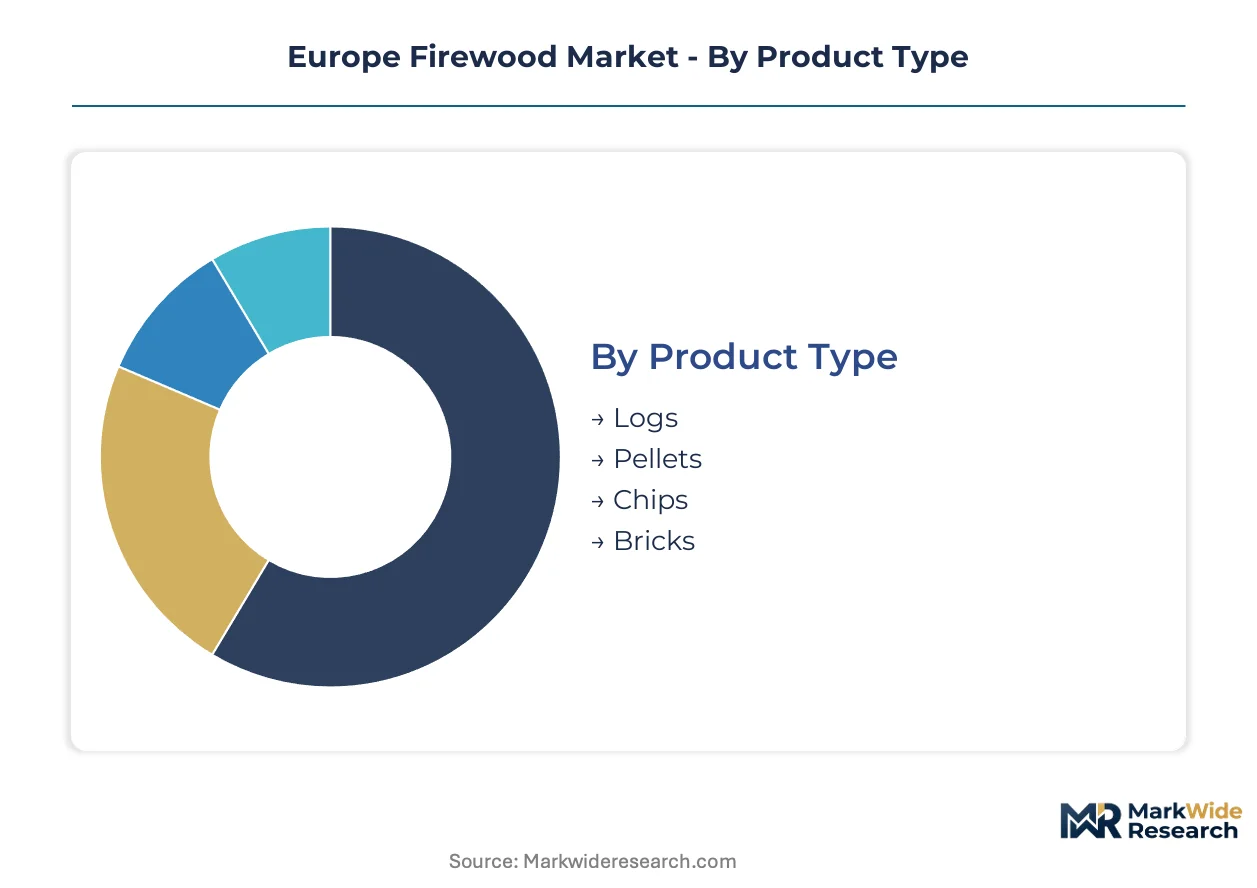
Firewood procurement patterns diverge sharply across Europe based on heating infrastructure, logistics access, and regulatory compliance requirements. Each segmentation dimension reveals distinct margin structures and competitive dynamics that suppliers must navigate to capture value.
Product Type:
Inventory velocity varies dramatically across formats, with pellets turning fastest due to automated consumption systems while logs retain the longest seasonal holding periods.
- Logs:Cut and split hardwood or softwood pieces, typically 25-50cm in length, dried to sub-20% moisture content for stove and fireplace combustion. Demand concentrates in Alpine regions and Eastern European rural zones where traditional masonry stoves dominate residential heating; bulk procurement sustains volume leadership despite slower turnover.
- Pellets:Compressed sawdust cylinders manufactured to ENplus A1 or A2 standards for automated boiler feed systems. French and Italian district heating retrofits drive the steepest demand expansion as utilities phase out coal-fired infrastructure.
- Chips:Irregular wood fragments from forest residue or sawmill byproducts, primarily serving small-scale industrial thermal applications and agricultural drying operations in Poland and Romania.
- Bricks:Densely compressed sawdust blocks offering standardized combustion characteristics for urban retail channels in Germany and Austria where storage space constraints favor stackable formats.
Logs anchor the volume base while pellets gain share at the steepest rate.
Delivery Method:
Logistics cost structures stratify sharply between high-touch bulk operations and automated retail fulfillment networks.
- Bulk:Loose firewood delivered by tipping truck or container to agricultural properties and rural heating installations. Polish and Romanian farmsteads sustain this channel through seasonal procurement concentrated in autumn months.
- Packaged:Net-wrapped or crated volumes, typically 1-2 cubic meters, positioned at hardware retailers and garden centers across German-speaking markets. FSC and PEFC certification requirements increasingly gate shelf placement.
- Retail:Small-format bags and boxes merchandised through convenience channels, commanding premium pricing per energy unit in Scandinavian urban markets where apartment dwellers lack storage capacity.
- Online:Direct-to-consumer platforms coordinating third-party logistics for home delivery, expanding fastest in UK and Netherlands markets where digital procurement habits penetrate heating fuel categories.
Bulk delivery retains volume leadership while online channels expand most quickly.
End User:
Procurement sophistication escalates from price-sensitive agricultural buyers to specification-driven commercial operators.
- Residential:Individual households purchasing for primary or supplemental heating, spanning Alpine chalet owners to Eastern European pensioners reliant on wood-fired stoves. Ecodesign Directive compliance pressures reshape fuel quality expectations.
- Commercial:Hospitality operators, campgrounds, and restaurant chains requiring consistent burn characteristics and documented sustainability credentials. Austrian and German hoteliers increasingly mandate PEFC-certified supply.
- Industrial:Small-scale thermal process users including bakeries, kilns, and craft breweries where biomass substitutes for natural gas in off-grid locations.
- Agriculture:Farmsteads with captive woodland or purchasing power for district heating cooperatives, sustaining seasonal demand spikes tied to crop drying and livestock housing.
Residential users anchor demand volume while commercial buyers drive certification premiums.
Firewood Grade:
Moisture content and species hardness determine combustion efficiency, storage requirements, and pricing tier placement.
- Seasoned:Air-dried or kiln-dried material below 20% moisture content, now specified in German and Austrian stove warranties. Automated moisture-control infrastructure separates integrated suppliers from merchant competitors.
- Green:Fresh-cut wood requiring 12-24 months storage before combustion, appealing to price-sensitive buyers with available drying space in rural Poland and Romania.
- Hardwood:Oak, beech, and birch species delivering extended burn duration and higher calorific value per volume, commanding Baltic sourcing premiums.
- Softwood:Pine and spruce varieties igniting rapidly for kindling and mixed-fuel applications, sourced from Nordic and Alpine forest operations.
Seasoned hardwood anchors premium positioning while kiln-dried softwood climbs fastest in automated boiler segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baltic suppliers route premium hardwood feedstock through German and Austrian distribution hubs, while Nordic producers direct kiln-dried softwood toward Scandinavian retail channels. This trade-flow architecture concentrates value capture in processing centers with certification infrastructure.
Germany
District heating cooperatives in Bavaria and Baden-Württemberg sustain bulk procurement volumes for certified firewood grades. The Ecodesign Directive's emission thresholds now mandate sub-20% moisture content in stove warranty documentation, compressing informal supplier participation. The Black Forest region anchors precision-manufactured fuel processing with integrated moisture-control infrastructure.
France
Municipal coal-to-biomass retrofits in Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur drive pellet-format demand for automated boiler systems. The EU Green Deal's biomass sustainability criteria require chain-of-custody verification for public procurement contracts. The Alps corridor concentrates log-format demand among chalet owners with traditional masonry heating infrastructure.
Poland
Rural agricultural properties in Masovia and Lesser Poland sustain seasonal bulk procurement for farmstead heating and crop-drying operations. National implementations of the Renewable Energy Directive shape calorific-value testing protocols for cross-border shipments. The Baltic port cluster facilitates hardwood import processing for redistribution to German-speaking markets.
Sweden
Urban apartment dwellers in Stockholm and Gothenburg generate packaged retail demand where storage constraints favor small-format convenience purchasing. PEFC certification requirements now gate shelf placement in hardware retail channels under tightened greenhouse-gas balancing rules. The Västra Götaland region hosts specialized seasoning infrastructure commanding premium positioning.
Austria
Alpine hospitality operators in Tyrol and Salzburg mandate documented sustainability credentials for commercial heating contracts. REACH framework compliance governs chemical treatment restrictions in processed fuel grades. The Upper Austria industrial cluster integrates automated kiln-drying with real-time moisture telemetry for specification-driven procurement channels.
Europe Firewood Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. The vendor base stratifies between integrated processors with captive feedstock networks and merchant suppliers dependent on spot-market hardwood allocation. Three archetypes dominate: Baltic-sourced vertical integrators, Nordic seasoning specialists, and German-speaking logistics controllers. Competitive moves concentrate on certification infrastructure deployment and last-mile delivery fleet optimization.
Among Baltic-sourced integrators, B&P Brennholz & Pfahl occupies a position exemplifying upstream feedstock control. ZOH Wood AB represents the Nordic specialist archetype with dedicated seasoning infrastructure. Holz & Feuer GmbH anchors the logistics-controller tier through German-speaking market presence. These three company structures illustrate how geographic origin and organizational suffix signal strategic positioning across certification-driven procurement channels.
| Leading Market Players |
|---|
| B&P Brennholz & Pfahl |
| Holz & Feuer GmbH |
| ZOH Wood AB |
| ROSTES WOOD |
| Holzhof Stormarn GmbH |
| ABB Holz GmbH |
| Drusedau SP. Z O.O |
| Surefire Wood |
| ALBAN technische Anlagen GmbH |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Polish seasoning yards is compressing spot-market hardwood premiums while simultaneously accelerating processor migration toward certified kiln-dried grades. Baltic feedstock controllers exploit this utilization asymmetry to enforce volume allocation discipline across German and Austrian procurement channels.
Pricing Analysis
Kiln-dried certified grades command substantial premiums over air-dried and green material as Ecodesign Directive warranty specifications harden. Pricing stratifies across premium certified hardwood, standard kiln-dried softwood, and economy green material tiers. Cost compression in the green-wood segment is intensifying because agricultural buyers with captive drying space bypass formal supply chains. District heating cooperatives exhibit lowest price sensitivity while Eastern European farmsteads anchor the economy tier.
Supply Chain Analysis
EU Green Deal biomass sustainability criteria function as de facto export controls limiting uncertified feedstock flows across member state borders. Geographic supply concentrates in Baltic states, Poland, and Nordic forest operations. Processing draws from hardwood sawmill byproducts, softwood thinnings, and forest residue streams. Single-source vulnerability runs through Baltic oak and beech allocation networks controlled by integrated processors. Distribution runs through German-speaking retail hubs and Polish bulk delivery cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent firewood processors face a substitution defense against pellet-format automated heating systems that capture district heating retrofit contracts. Pellet infrastructure investments by French and Italian utilities threaten log-format volume in commercial thermal applications.
For Market Incumbents: Insulate core positioning by accelerating PEFC and FSC certification infrastructure deployment before 2025 EU Green Deal enforcement deadlines. Secure backward integration into Baltic hardwood sourcing networks to eliminate peak-season allocation risk from merchant suppliers. Channel control through last-mile bulk delivery fleet density in Alpine agricultural zones remains defensible against pellet substitution in rural segments.
For New Entrants and Emerging Players: Polish district heating cooperatives transitioning from coal represent the most penetrable entry point for certified biomass suppliers with logistics capabilities. Scandinavian urban packaged retail channels offer white-space expansion for sustainability-labeled convenience formats targeting apartment dwellers. A go-to-market angle anchored on carbon-accounting methodology alignment positions new entrants for preferential renewable heat incentive treatment.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated kiln-drying infrastructure as moisture-control sensor integration becomes mandatory for retail channel access. Long-term viability favors processors with integrated feedstock networks and certification documentation systems rather than merchant suppliers exposed to spot-market volatility. Acquisition target archetypes include Baltic-sourced vertical integrators and Nordic seasoning specialists with established PEFC positioning. The signal to watch is national calorific-value testing protocol harmonization that would eliminate cross-border compliance friction for scaled operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Infrastructure Deployment | PEFC and FSC chain-of-custody systems gate German and Austrian retail shelf placement under EU Green Deal criteria. |
| Backward Integration into Feedstock | Baltic hardwood sourcing networks eliminate peak-season volume allocation risk for integrated processors. |
| Automated Kiln-Drying Capacity Addition | Real-time moisture telemetry enables sub-20% specification compliance for Ecodesign Directive warranty documentation. |
| Last-Mile Delivery Fleet Optimization | Route density in Alpine agricultural zones sustains bulk procurement relationships against pellet substitution. |
| Carbon-Accounting Methodology Alignment | Early greenhouse-gas balancing protocol adoption secures preferential positioning under evolving national renewable heat incentives. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, EU regulatory filings, and forest industry association reports. Interviews with kiln-drying equipment manufacturers, Baltic feedstock procurement managers, German hardware retail category buyers, and Austrian district heating cooperative directors informed demand-side validation. Secondary sources included FSC and PEFC certification databases, ECHA REACH documentation, and national renewable energy agency statistics. Bottom-up volume modeling triangulated against top-down macroeconomic drivers across the analysis window.
Forecast inputs incorporate product type segmentation across logs, pellets, chips, and bricks alongside delivery method dynamics spanning bulk, packaged, retail, and online channels. End-user segmentation modeled residential, commercial, industrial, and agricultural procurement patterns. Grade-tier differentiation between seasoned hardwood, kiln-dried softwood, and green material shaped price elasticity assumptions. CAGRs were derived from regression analysis against heating degree-day correlations and regulatory compliance timeline acceleration.
Practitioners should monitor EU Green Deal biomass sustainability criteria enforcement timing and national calorific-value testing protocol harmonization progress for early signals. Forecasts reflect assumptions regarding pellet substitution rates in automated boiler retrofits and certification penetration trajectories in German-speaking retail channels. Material shifts in hardwood feedstock availability from Baltic sourcing networks or accelerated pellet infrastructure deployment in district heating applications would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Aerospace Aviation Fuels Market
Fuels
Saudi Arabia Automotive Fuels Market
Fuels
LPG Vaporizer Market
Fuels
Tire Derived Fuel Market
Fuels
Synthetic Natural Gas (SNG) Market
Fuels
City Gas Distribution Market
Fuels
Global Industrial Burner Market
Fuels
Europe Compressed Natural Gas Dispenser Market
Fuels
Fuel Conditioning System Market
Fuels
Canada Bunker Fuel Market
Fuels
Electric Fuel Heater Market
Fuels
LPG Gas Cylinder Market
Fuels
CNG Dispenser Market
Fuels
Caribbean Islands Bunker Fuel Market
Fuels
Oil Dispenser Market
Fuels
Europe Coal Market