
 Commercial Aircraft Aviation Fuel Market | 2026-2036
Commercial Aircraft Aviation Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Aviation Fuel Market Outlook
Jet fuel supply contracts between refiners and airport fuel farms is reconfiguring as airlines seek longer-term offtake security. ExxonMobil Corporation leverages its integrated refining and midstream footprint to lock in pipeline-to-wing delivery economics. Shell PLC competes through dedicated aviation terminals at Rotterdam, Singapore, and Houston that sustain throughput for international carriers.
Commercial aircraft aviation fuel denotes refined kerosene meeting ASTM D1655 or DEF STAN 91-091 specifications, with flash points above 38 degrees Celsius and freeze points below minus 40 degrees Celsius, formulated to deliver specific energy of 43 megajoules per kilogram for turbine propulsion. Jet A-1 dominates transoceanic routes where cold-flow properties prevent waxing at cruise altitudes, while biofuel blends represent the fastest-growing fuel type as ReFuelEU Aviation and California LCFS create enforceable offtake obligations. Long-haul flights anchor absolute volume demand, though cargo transport yields firmer margins per gallon due to less price-sensitive contract structures and overnight departure scheduling.
FAA certification requirements under 14 CFR Part 21 and EPA Tier 3 sulfur standards constrain product formulation and refinery configuration choices for US suppliers. The EU ETS and ICAO CORSIA framework impose emissions-accounting costs that reshape procurement priorities toward lower-carbon intensity certificates. Stakeholders must monitor SAF offtake guarantee enforcement, refinery co-processing capacity announcements, and jet fuel margin compression at complex versus simple refineries.
Market Dynamics
ReFuelEU Aviation mandates are forcing refiners and airlines into binding sustainable aviation fuel procurement contracts, restructuring long-term supply relationships around certified carbon intensity thresholds rather than spot price arbitrage.
Growth Catalysts
- Fleet Modernization:Airlines retiring older wide-bodies for fuel-efficient twin-engine aircraft expand aggregate seat-mile capacity per gallon consumed, tightening jet fuel demand elasticity to passenger volume recovery.
- ReFuelEU Aviation:The European Union's escalating blend mandate creates enforceable offtake floors that guarantee SAF volume absorption regardless of crude price volatility, de-risking refinery co-processing investments.
- Hub-and-Spoke Network Density:United States domestic carriers concentrate flight operations at major connecting airports, sustaining pipeline-fed fuel farm throughput that justifies dedicated storage and hydrant system capital deployment.
Market Restraints
- Crude Feedstock Volatility:Jet fuel crack spreads compress unpredictably when complex refineries prioritize gasoline or diesel yields, squeezing standalone aviation kerosene production economics at simple refineries.
- SAF Feedstock Competition:Limited supplies of waste oils, agricultural residues, and synthetic alcohols face rival demand from road transport biodiesel and marine fuel blending, constraining aviation-specific allocation.
- Pipeline Infrastructure Rigidity:Colonial Pipeline and comparable systems route product to predetermined terminals, limiting flexibility to redirect jet fuel volumes toward emerging demand centers without batch sequencing penalties.
Strategic Opportunities
- India Domestic Aviation Expansion:IndiGo and Air India fleet growth plans target secondary city connectivity, creating greenfield fuel farm and into-plane service requirements at airports lacking existing jet fuel infrastructure.
- Power-to-Liquid Synthesis:Electrofuel production combining green hydrogen with captured carbon dioxide offers pathway to 100% synthetic drop-in jet fuel qualifying for zero-carbon intensity certificates under ICAO CORSIA.
- Airport Hydrant System Modernization:Aging underground fueling networks at London Heathrow and Frankfurt Main present upgrade contracts for integrated service providers capable of delivering continuous flow during construction phases.
Industry Challenges
- SAF Certification Bottlenecks:ASTM D7566 annex approvals for novel conversion pathways require multi-year testing protocols, delaying commercial deployment of alcohol-to-jet and gasification technologies already proven at pilot scale.
- Jet Fuel Storage Contamination Control:Microbial growth in long-dormant airport tanks during pandemic demand collapse degraded fuel quality, forcing costly filtration system overhauls and extended supply chain testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Aviation Fuel Market |
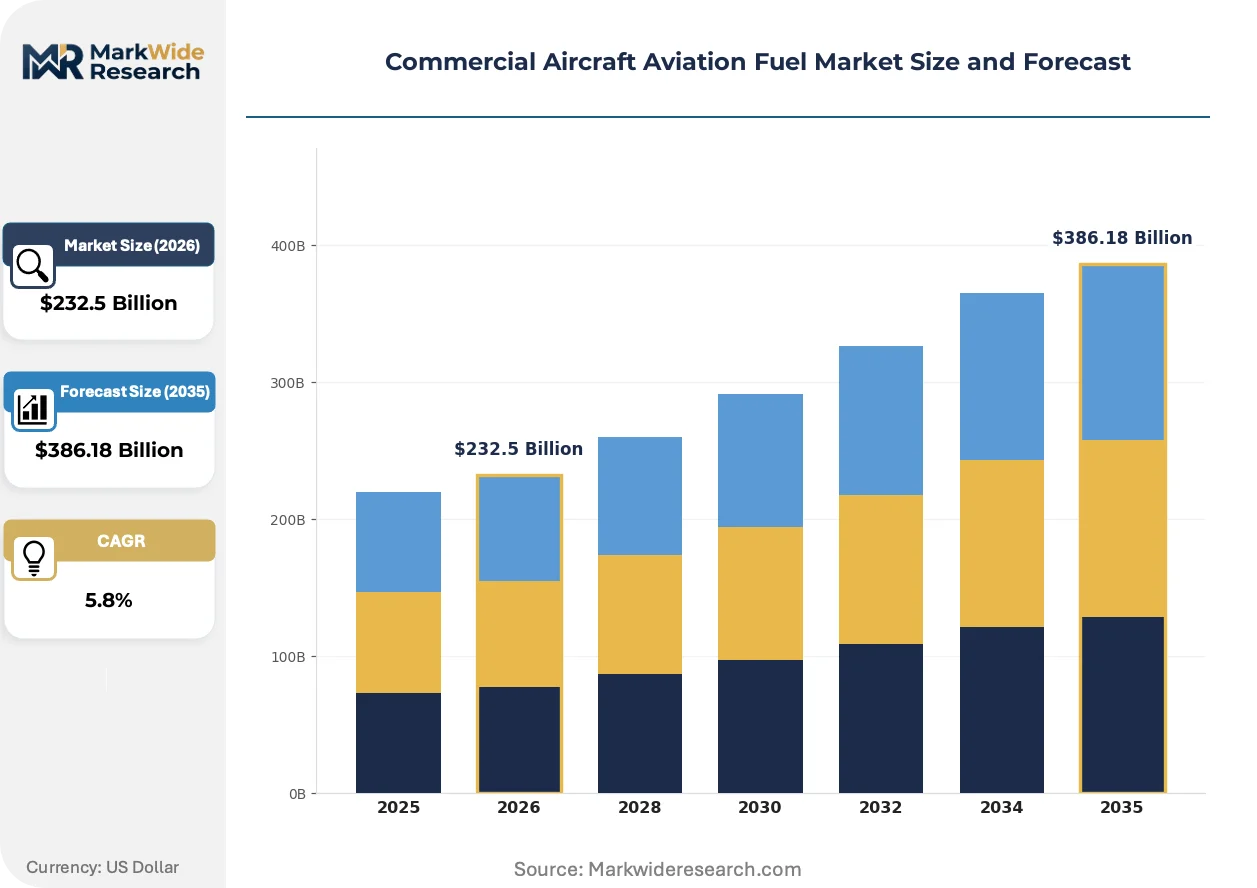
| Market Size in 2026 | $232.5 Billion |
| Market Size in 2035 | $386.18 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Jet A, Jet A-1, Avgas, Biofuel Application: Short-Haul Flights, Long-Haul Flights, Cargo Transport, Military Operations Distribution Channel: Direct Sales, Retail, Online, Resellers End User: Commercial Airlines, Cargo Operators, Government Agencies, Private Aviation |
| Companies Covered | ExxonMobil Corporation, Chevron Corporation, Shell PLC, TotalEnergies SE, BP PLC, Phillips 66, World Fuel Services Corp, Vitol Holding BV, Valero Energy Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Aviation Fuel Market Strategic Shifts
Aviation fuel markets are restructuring around carbon accounting infrastructure that traces molecules from refinery gate to aircraft wing, embedding emissions data into procurement contracts and hedging instruments.
Co-processing technology is migrating from standalone hydrotreatment units toward integrated refinery configurations that upgrade renewable feedstocks alongside conventional crude streams. European refiners at Rotterdam and Antwerp deploy this approach to maintain jet fuel output while satisfying ReFuelEU blending floors. The technology is migrating from pilot demonstrations to commercial-scale operations, compressing capital requirements for SAF production relative to greenfield biorefinery construction.
California LCFS credit markets now influence aviation fuel procurement far beyond state borders, as carriers operating Los Angeles and San Francisco routes monetize carbon intensity differentials through book-and-claim certificate trading. The regulation rewards feedstock pathways with lower lifecycle emissions, redirecting refinery investment toward waste-based and synthetic options. International carriers without California exposure increasingly demand equivalent certification structures from fuel suppliers to satisfy internal net-zero commitments.
Long-term offtake contracting is displacing spot market purchasing among network carriers seeking supply security for projected fleet growth. Airlines negotiate five-to-ten-year purchase agreements directly with refiners or integrated oil companies, locking in volume commitments that underpin infrastructure financing. This pattern concentrates most visibly at Singapore Changi and Amsterdam Schiphol, where hub carriers pre-commit to terminal throughput guarantees.
Commercial Aircraft Aviation Fuel Market Segmentation
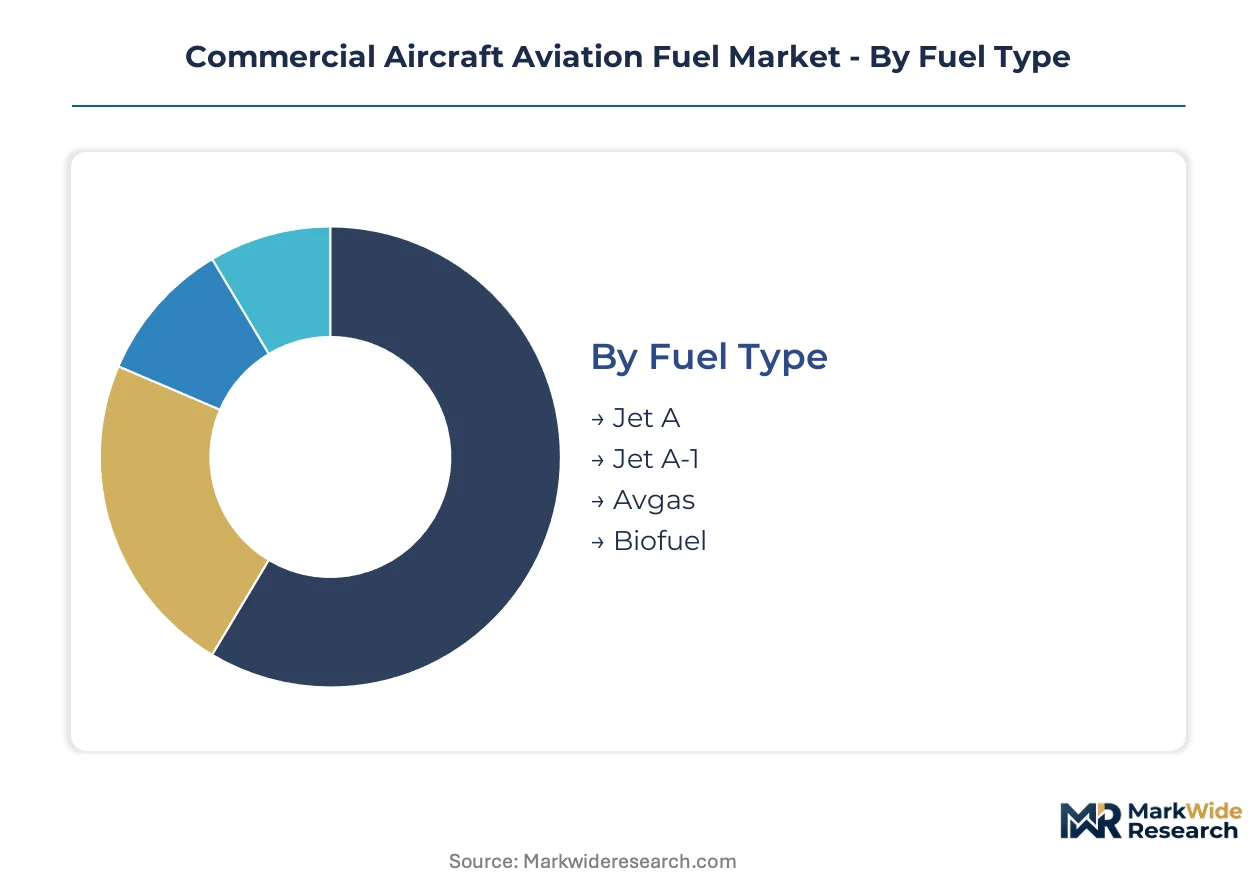
Commercial aircraft aviation fuel segmentation reveals how product specifications, flight profiles, and procurement channels create distinct margin structures. Refiners and distributors configure operations around these boundaries to optimize throughput and carbon intensity compliance.
Fuel Type:
Refined kerosene grades serve distinct operational envelopes across temperature ranges, altitude performance, and regulatory compliance thresholds.
- Jet A:Refined kerosene with freeze point of minus 40 degrees Celsius and flash point minimum 38 degrees Celsius, formulated for turbine engines operating in temperate climates. United States domestic carriers at Atlanta Hartsfield-Jackson and Dallas-Fort Worth rely on pipeline-fed Jet A for hub-and-spoke network density, though cold-flow limitations restrict winter operations at Minneapolis-St. Paul and Denver.
- Jet A-1:Lower freeze point specification at minus 47 degrees Celsius enables transoceanic and polar route operations without waxing risk at cruise altitudes. European Union carriers at London Heathrow and Amsterdam Schiphol mandate Jet A-1 for North Atlantic crossings, with ReFuelEU Aviation blend requirements now embedding into Jet A-1 procurement contracts as co-processed SAF volumes rise.
- Avgas:Aviation gasoline for piston-engine aircraft with 100 octane rating and leaded formulation meeting ASTM D910, serving general aviation and flight training markets.
- Biofuel:Hydrotreated renewable jet meeting ASTM D7566 Annex A1-A7 specifications, derived from waste oils, agricultural residues, or synthetic alcohols.
The dominant share belongs to Jet A-1, while biofuel is closing the gap fastest.
Application:
Flight distance and payload characteristics determine fuel burn rates, tankering economics, and contract pricing structures across operational categories.
- Short-Haul Flights:Regional routes under 1,500 nautical miles with frequent climb-descent cycles that elevate fuel consumption per seat-mile relative to cruise-efficient long-haul operations. European low-cost carriers at Barcelona El Prat and Milan Malpensa optimize turnarounds around single-aisle aircraft tankering limits, with ReFuelEU mandates accelerating SAF blend requirements for intra-European segments.
- Long-Haul Flights:Intercontinental services consuming 35,000 to 45,000 gallons per wide-body departure, anchoring absolute jet fuel volume demand through hub airports. Singapore Changi and Dubai International sustain dedicated aviation fuel terminals to service twin-aisle fleet rotations, with into-plane operators managing 45-minute refueling windows during layovers.
- Cargo Transport:Dedicated freighter operations and belly-hold freight with less price-sensitive contract structures tied to overnight departure scheduling.
- Military Operations:Defense procurement through national stockpiles and NATO pipeline systems with JP-8 and F-34 specifications.
Long-haul flights command the largest volume share, though cargo transport is expanding most quickly on e-commerce logistics growth.
Distribution Channel:
Supply chain configuration determines working capital intensity, price transparency, and carbon accounting traceability from refinery gate to aircraft wing.
- Direct Sales:Refiner-to-airline contracts locking in five-to-ten-year offtake volumes with terminal throughput guarantees. ExxonMobil leverages integrated pipeline networks to deliver direct sales at Houston Bush Intercontinental, while Shell PLC structures direct agreements at Rotterdam and Singapore Changi that bypass intermediary markups.
- Retail:Spot market purchases through fuel farm operators and into-plane service providers at airports lacking dedicated refinery relationships. General aviation terminals at Phoenix Deer Valley and Van Nuys depend on retail channels with higher per-gallon premiums reflecting fragmented demand aggregation.
- Online:Digital procurement platforms emerging for carbon credit verification and SAF certificate trading.
- Resellers:Independent distributors aggregating volumes across multiple refiners for smaller carriers and charter operators.
Direct sales dominate network carrier procurement, while online channels are gaining share fastest on carbon accounting automation.
End User:
Customer scale and regulatory exposure create tiered pricing structures and contract duration preferences across aviation fuel buyers.
- Commercial Airlines:Scheduled passenger carriers negotiating long-term supply agreements with refinery co-processing commitments for SAF volumes. United Airlines and Delta Air Lines structure direct contracts with renewable fuel producers to secure California LCFS credit eligibility, embedding carbon intensity thresholds into procurement specifications.
- Cargo Operators:Dedicated freighter airlines and integrated logistics providers with 24-hour operational schedules and centralized fuel farm relationships. FedEx Express and UPS Airlines concentrate volume at Memphis and Louisville hubs, leveraging overnight departure density to negotiate firm-margin contracts with less spot market exposure.
- Government Agencies:Military and state aviation departments procuring through defense fuel supply centers with strategic reserve requirements.
- Private Aviation:Corporate flight departments and charter operators with fragmented demand patterns and higher per-gallon service premiums.
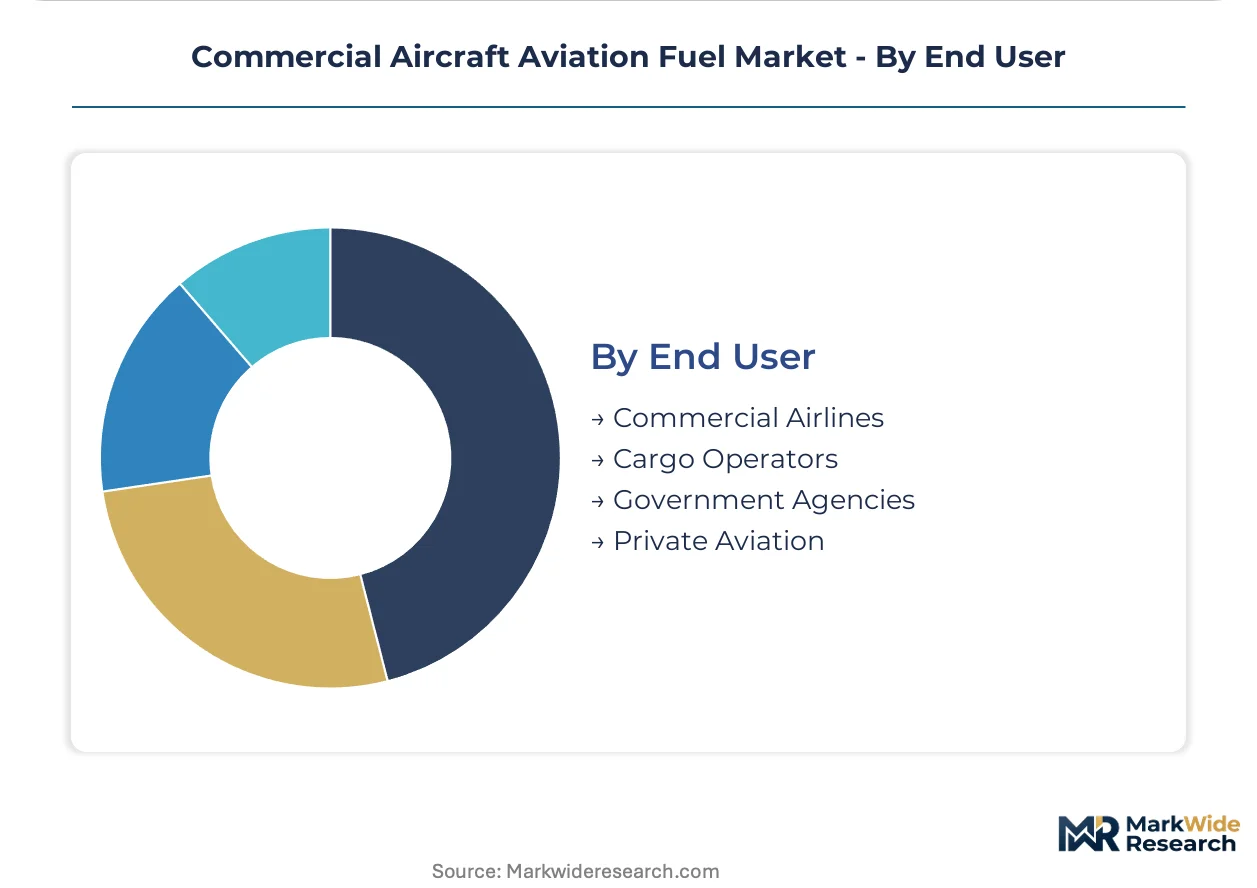
Commercial airlines hold the dominant share, while cargo operators are climbing the fastest on dedicated freighter fleet expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Colonial Pipeline anchors North American jet fuel distribution, feeding storage terminals from Houston to New York Harbor with batch-scheduled kerosene volumes.
United States
Hub-and-spoke networks at Atlanta Hartsfield-Jackson and Dallas-Fort Worth sustain pipeline-fed fuel farm throughput. FAA certification under 14 CFR Part 21 constrains refinery formulation choices. Gulf Coast complex refineries at Houston and Port Arthur dominate production, with dedicated aviation terminals serving Delta and United long-haul fleets.
Germany
Frankfurt Main and Munich anchor Central European jet fuel demand for Lufthansa's intercontinental network. ReFuelEU Aviation mandates force binding SAF procurement contracts with certified carbon intensity thresholds. The Leuna refinery corridor supplies kerosene through the Central Europe Pipeline System to Rhine-Main airports.
Singapore
Changi Airport's dedicated aviation fuel terminal services twin-aisle rotations for Singapore Airlines and transit carriers. The Maritime and Port Authority coordinates bunker fuel blending rules that intersect with aviation kerosene storage logistics. Jurong Island refineries maintain jet fuel export capacity for Asia-Pacific hub airports.
Netherlands
Rotterdam's port complex hosts Shell's dedicated aviation terminal with direct pipeline links to Schiphol Airport. The EU Green Deal accelerates co-processing investments at Antwerp refineries to meet ReFuelEU blend floors. The Amsterdam-Rotterdam-Antwerp cluster processes North Sea crude and renewable feedstocks for European carrier supply.
India
IndiGo and Air India fleet expansion targets secondary city connectivity from Delhi and Mumbai. The Petroleum and Natural Gas Regulatory Board oversees fuel farm licensing at greenfield airports. Reliance Industries' Jamnagar refinery supplies kerosene to emerging aviation hubs lacking existing jet fuel infrastructure.
Commercial Aircraft Aviation Fuel Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream. The market consolidates around integrated oil companies with refining, pipeline, and terminal assets. Three archetypes dominate: refinery-integrated majors with captive pipeline networks, independent fuel farm operators with into-plane service contracts, and renewable fuel specialists with ASTM D7566 certification pathways. Competitive moves center on long-term offtake contracting and co-processing capacity expansion.
Among integrated majors, ExxonMobil Corporation, Shell PLC, and BP PLC exemplify the refinery-to-wing archetype. ExxonMobil leverages Gulf Coast pipeline networks for direct sales at Houston Bush Intercontinental. Shell occupies a position at Rotterdam and Singapore Changi with dedicated aviation terminals bypassing intermediary markups. BP sits within the European supply matrix with terminal throughput guarantees tied to ReFuelEU compliance structures.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Chevron Corporation |
| Shell PLC |
| TotalEnergies SE |
| BP PLC |
| Phillips 66 |
| World Fuel Services Corp |
| Vitol Holding BV |
| Valero Energy Corporation |
| Others |
Value Chain & Pricing Dynamics
Crude feedstock volatility at complex Gulf Coast refineries determines both the spread between contract and spot pricing tiers and the geographic shape of aviation fuel supply networks. When crack spreads compress unpredictably, simple refineries exit standalone kerosene production while integrated majors consolidate pipeline-fed terminal access.
Pricing Analysis
Volume-discount tiering structures separate network carriers with five-to-ten-year offtake guarantees from spot-market purchasers at fragmented airports. Price differentiation rests on certification grade—ASTM D1655 versus DEF STAN 91-091 specifications—and volume scale with hub-and-spoke density. Cost compression in the retail tier is intensifying because cargo operators negotiate firmer margins through overnight scheduling concentration. General aviation terminals exhibit highest price sensitivity; long-haul network carriers with direct refinery relationships show least.
Supply Chain Analysis
Integrated majors ExxonMobil, Shell, and BP hold concentrated refining and terminal capacity across the United States, Netherlands, and Singapore. Raw material dependencies include North Sea crude, Middle Eastern sour grades, and renewable feedstocks for co-processed SAF. Single-source vulnerability runs through the Colonial Pipeline batch sequencing system. Distribution feeds from refinery gate through dedicated aviation terminals to airport hydrant systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASTM D7566 certification pathways for novel conversion technologies represent the binding constraint—refiners with approved annexes command scarcity rents while airlines face procurement gaps.
For Market Incumbents: Entrench terminal throughput guarantees at Rotterdam, Singapore, and Houston by locking network carriers into decade-long contracts with SAF co-processing commitments. Expand hydrotreatment capacity to process waste oil and synthetic alcohol feedstocks before regulatory deadlines tighten blend floors.
For New Entrants and Emerging Players: Pursue power-to-liquid synthesis partnerships with green hydrogen producers to capture zero-carbon intensity certificates under ICAO CORSIA. India's secondary city aviation infrastructure presents the most penetrable white space as IndiGo and Air India fleet expansion outruns existing fuel farm capacity.
For Investors and Strategic Acquirers: ReFuelEU Aviation enforcement reshapes the acquisition landscape toward refiners with operational co-processing units and certified carbon accounting infrastructure. Long-term viability centers on feedstock security for synthetic and waste-based pathways. Monitor SAF offtake guarantee enforcement as the signal for margin inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| SAF Co-Processing Capacity Expansion | Antwerp and Rotterdam refineries secure ReFuelEU compliance without greenfield construction costs. |
| Long-Term Offtake Contracting | Singapore Changi hub carriers pre-commit volumes that underpin dedicated terminal financing. |
| Power-to-Liquid Partnership | Electrofuel synthesis qualifies for California LCFS credits and CORSIA zero-carbon certificates. |
| Airport Hydrant Modernization | London Heathrow upgrades create service contracts with continuous-flow construction capabilities. |
| India Greenfield Fuel Farm Development | Reliance Industries leverages Jamnagar refinery proximity to emerging secondary city airports. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EIA petroleum data, IEA aviation energy reports, SEC 10-K refinery disclosures, and EU ETS transaction records. Interviews with refinery operations directors, airline fuel procurement managers, airport into-plane service heads, and renewable fuel certification specialists informed supply chain dynamics. Bottom-up terminal throughput estimates triangulated against top-down jet fuel demand projections from fleet utilization databases.
Forecast inputs span fuel type segmentation by Jet A, Jet A-1, and biofuel blend ratios; application categories across short-haul, long-haul, and cargo transport; and distribution channel configuration from direct sales through retail and emerging digital procurement. CAGRs derived from regression against passenger revenue kilometer recovery curves and SAF mandate enforcement schedules. Carbon intensity accounting infrastructure and co-processing technology migration curves entered as scenario variables.
Macroeconomic conditions sit as an overlay; deviation in crude price volatility, jet fuel crack spreads, or renewable feedstock competition from road transport biodiesel would shift the trajectory. Forecasts reflect assumptions on ReFuelEU blend floor implementation and ICAO CORSIA phase-in adherence. Quarterly review of SAF certification annex approvals, refinery co-processing announcements, and airline fleet delivery schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
South America Aviation Fuel Market
Fuels
Bituminous Coal Market
Fuels
United States Coal Market
Fuels
Solid Fuel Tablet Market
Fuels
Gasoline Octane Improvers Market
Fuels
South America Defense Aircraft Aviation Fuel Market
Fuels
Global Industrial Burner Market
Fuels
North America Commercial Aircraft Aviation Fuel Market
Fuels
Coal Intelligent Dry Separators Market
Fuels
Japan Bunker Fuel Market
Fuels
Oil & Gas Lubricants Market
Fuels
Smart Gas Solutions Market
Fuels
UAE Chemical Logistics Market
Fuels
High-Temperature Industrial Burner Market
Fuels
LNG Fueling Station Market
Fuels
Chafing Fuel Market