
 Gasoline Market | 2026-2036
Gasoline Market Size, Share, and Industry Trends Forecast 2026-2036
Gasoline Market Intelligence
The octane-based distinction between premium and regular unleaded gasoline is hardening, creating separate value chains for each grade. This shift influences refinery investment and retail strategy. ExxonMobil leverages its integrated model to optimize production across different fuel grades and chemical feedstocks. Shell, in contrast, differentiates through its branded retail network and premium fuel additives.
Gasoline is a volatile, flammable liquid fuel derived from crude oil through fractional distillation and refining. It consists of a mixture of hydrocarbons, with its performance primarily defined by its octane rating, which measures resistance to engine knocking. Its principal application is as a fuel for internal combustion engines in vehicles and equipment. The regular unleaded fuel type constitutes the largest volume segment, serving the mass market for light-duty vehicles.
Fuel quality standards, such as those mandated by the US EPA and China's GB standards, dictate permissible levels of sulfur and other components. Concurrently, regulations like the EU's REACH framework govern the chemical additives used in formulations, impacting market access and production costs. Refiners must now balance investments in traditional gasoline production with strategic preparations for a future influenced by alternative fuels and electrification.
Market Dynamics
The gasoline market's central dynamic is the tension between legacy vehicle parc demand and the capital-intensive refinery upgrades required by tightening fuel quality regulations. This forces a strategic bifurcation between producing mass-market regular unleaded and higher-margin premium grades.
Growth Catalysts
- Advanced Engine Technologies:The proliferation of gasoline direct injection (GDI) and turbocharged engines in new light-duty vehicles necessitates higher-octane gasoline to achieve designed efficiency and prevent engine knocking, pulling demand for premium fuels.
- Mobility Expansion in India:Sustained economic growth and urbanization in India are expanding the vehicle parc, particularly in the two-wheeler and passenger car segments, creating a foundational source of volume demand for gasoline.
- Stringent Emissions Standards:Regulations like the US EPA's Tier 3 program and China's GB standards mandate significant reductions in sulfur content, compelling refiners to produce cleaner gasoline formulations and invest in desulfurization capacity.
Market Restraints
- BEV Substitution:The accelerating market penetration of battery electric vehicles (BEVs) presents a direct and permanent substitution threat, eroding long-term gasoline demand in the core light-duty vehicle segment, especially in developed economies.
- Crude Oil Price Volatility:As the primary feedstock, the price volatility of crude oil creates significant margin pressure for refiners and price uncertainty for consumers, complicating investment decisions and demand forecasting.
- Regulatory Compliance Costs:Frameworks such as the EU's REACH regulation impose complex and costly requirements for the testing and registration of chemical additives used in gasoline, acting as a barrier to market entry and innovation.
Strategic Opportunities
- Specialty Fuel Formulations:Developing and marketing specialized, high-performance gasoline blends for niche applications like motorsports, classic cars, and non-road power equipment offers a high-margin opportunity less vulnerable to electrification.
- Biofuel Integration Mandates:Government policies mandating biofuel blending, such as the promotion of E10 and E15 fuels, create opportunities for refiners to diversify feedstocks and capture value from integrated ethanol supply chains.
- Small-Engine Market Growth:Expanding demand for gasoline-powered small engines in applications like generators, pumps, and landscaping equipment in Southeast Asia provides a resilient, volume-based market segment.
Industry Challenges
- Refinery Capital Investment:Upgrading existing refinery units, such as isomerization and alkylation plants, to meet higher-octane and lower-sulfur specifications requires substantial capital expenditure with long payback periods and uncertain future utilization.
- Logistical Complexity of Blending:The logistics of blending ethanol and other additives to create finished gasoline that meets varying regional and seasonal specifications adds significant complexity and cost to the downstream supply chain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gasoline Market |
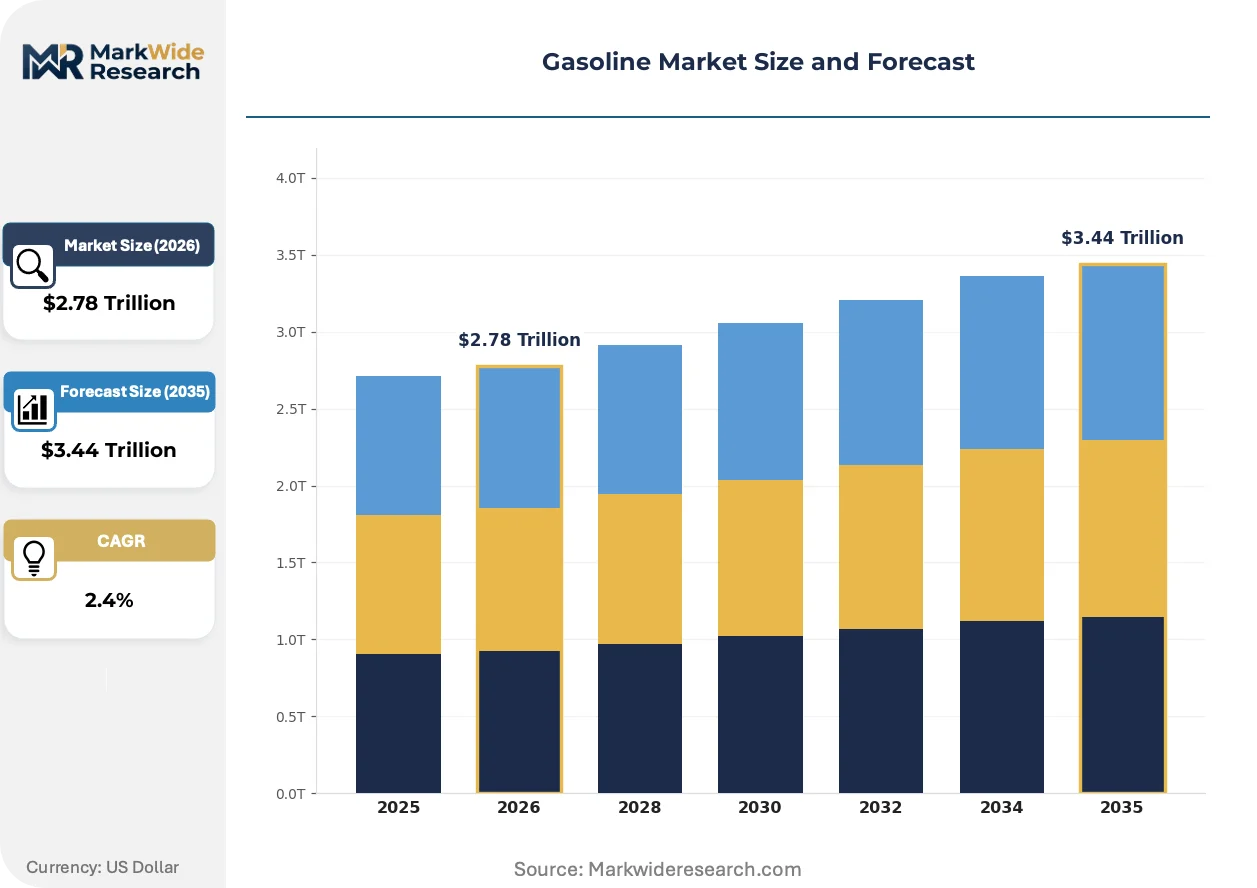
| Market Size in 2026 | $2.78 Trillion |
| Market Size in 2035 | $3.44 Trillion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Regular Unleaded, Premium Unleaded, Mid-Grade, Reformulated Gasoline, Oxygenated Gasoline Application: Light-Duty Vehicles, Two-Wheelers, Recreational Vehicles, Marine Engines, Power Generators Distribution Channel: Retail Gas Stations, Direct Sales to Fleet Operators, Convenience Stores, Bulk Supply, Online Ordering Platforms End User: Personal Vehicle Owners, Commercial Fleet Managers, Agricultural Operators, Construction Companies, Event Organizers |
| Companies Covered | Saudi Aramco, ExxonMobil, Chevron, PetroChina, Shell, TotalEnergies, BP, Valero Energy, Phillips 66, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gasoline Market Strategic Shifts & Innovations
The gasoline market is being redefined by a dual focus on optimizing the performance of the traditional fuel itself while simultaneously managing its role in a multi-energy future. This involves innovations in production, compliance with evolving standards, and adapting to new consumer behaviors at the retail level.
Digital twin technology is a key innovation for process optimization. These virtual replicas of physical refinery assets use real-time data to simulate operational scenarios, predict equipment failure, and identify efficiency improvements. Major refiners are deploying this to maximize yields of high-value products from various crude oil inputs. This technology is integrating complex process variables and market data, enabling a more agile and profitable refinery operation.
Regulatory mandates for renewable fuel content are altering the chemical composition of gasoline. The US Environmental Protection Agency's Renewable Fuel Standard (RFS) requires specific volumes of biofuels to be blended into the national fuel supply. This forces obligated parties to either physically blend ethanol or purchase compliance credits, directly impacting the economics of gasoline production. The program most heavily affects US refiners, who must manage the financial risks associated with volatile credit prices.
Consumer behavior at the retail point of sale is shifting from price-centric fuel purchasing to a demand for integrated convenience. This trend is challenging the viability of fuel-only service stations, favoring larger sites that combine fueling with robust convenience stores, quick-service restaurants, and other amenities like EV charging. This shift is most pronounced in North American and European markets, where retail brand and customer experience are becoming critical differentiators.
Gasoline Market Segmentation
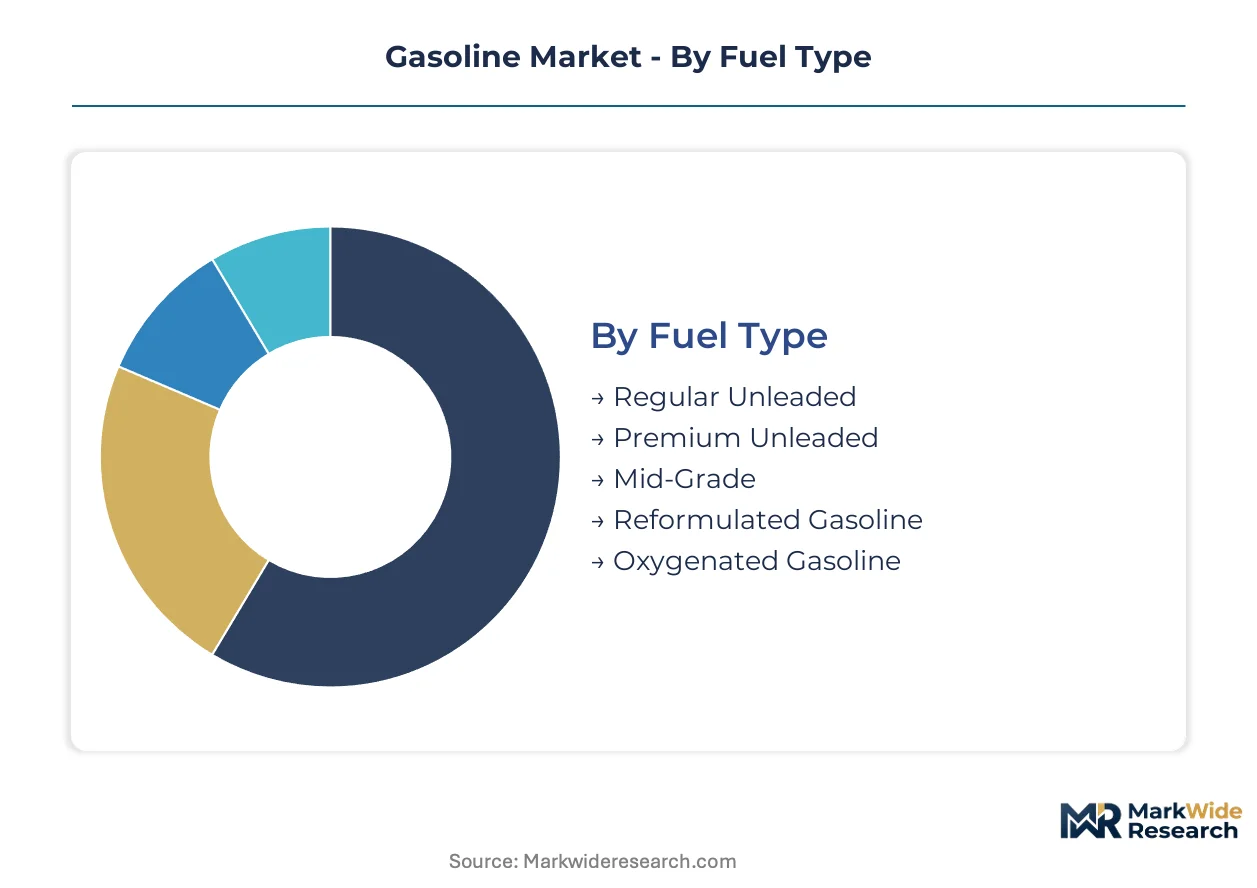
Understanding the gasoline market's segmentation is critical for refiners, distributors, and retailers to align production, logistics, and marketing strategies effectively. This granular view reveals where demand is concentrated, how different fuel types are consumed, and the varied requirements of end-users across diverse applications. Strategic investment decisions hinge on accurately assessing the value and growth potential within each segment.
Fuel Type:
Buyers in the gasoline market often differentiate their needs based on engine specifications and performance requirements, driving distinct demand for various fuel formulations.
- Regular Unleaded:This fuel type typically has an octane rating of 87 and forms the largest volume segment, serving the mass market for standard internal combustion engines. Its widespread availability and lower cost make it the default choice for the majority of light-duty vehicles across North America and Europe.
- Premium Unleaded:Characterized by higher octane ratings, typically 91 or 93, this gasoline is formulated for high-compression or turbocharged engines to prevent knocking and maximize efficiency. Demand for premium fuels is increasing in developed economies as advanced engine technologies become more prevalent in new passenger cars.
- Mid-Grade:Positioned between regular and premium, mid-grade gasoline usually carries an 89 octane rating, catering to vehicles that recommend but do not strictly require premium fuel.
- Reformulated Gasoline:This specialized blend contains lower levels of volatile organic compounds and toxic air pollutants, mandated by environmental regulations in specific urban areas, particularly in the US.
- Oxygenated Gasoline:Containing oxygenates like ethanol, this fuel type is used in areas with carbon monoxide air pollution problems, promoting more complete combustion.
Volume sits with Regular Unleaded; growth tilts toward Premium Unleaded.
Application:
The diverse range of internal combustion engines across various sectors dictates gasoline consumption patterns.
- Light-Duty Vehicles:This segment includes passenger cars, SUVs, and light trucks, representing the primary application for gasoline globally due to the vast existing vehicle parc. Demand in this segment is anchored by personal mobility needs in countries like India and China, despite electrification trends in Western markets.
- Two-Wheelers:Motorcycles, scooters, and mopeds constitute a significant application, particularly in emerging economies across Asia, where they serve as a foundational mode of personal transportation. Rapid urbanization and economic expansion in Southeast Asia are driving sustained volume demand in this category.
- Recreational Vehicles:This category encompasses ATVs, snowmobiles, and personal watercraft, requiring gasoline for leisure and outdoor activities.
- Marine Engines:Gasoline powers a wide array of boats, from small fishing vessels to recreational yachts, with specific fuel requirements often tied to engine performance and environmental standards.
- Power Generators:Small-scale gasoline generators provide backup power for residential, commercial, and industrial use, especially in regions with unreliable electricity grids.
Light-Duty Vehicles continue to command the largest share, while the Two-Wheelers segment is expanding most quickly.
Distribution Channel:
Supply chain efficiency and customer accessibility are paramount considerations for gasoline distribution.
- Retail Gas Stations:These are the most common points of sale, offering gasoline directly to individual consumers through a network of branded and independent stations. The integration of convenience stores and other amenities at these locations is reshaping consumer purchasing behavior.
- Direct Sales to Fleet Operators:This channel involves bulk delivery of gasoline directly to commercial enterprises managing fleets of vehicles, such as logistics companies, taxi services, and government agencies. These sales often involve negotiated contracts and specialized fueling infrastructure.
- Convenience Stores:Many retail gasoline stations are co-located with convenience stores, leveraging cross-selling opportunities and offering a broader customer experience.
- Bulk Supply:Large-volume purchasers, including industrial users, agricultural operations, and remote construction sites, receive gasoline via tankers or rail cars for on-site storage.
- Online Ordering Platforms:Emerging services allow consumers or businesses to order gasoline for delivery to their location, offering increased convenience in select urban markets.
Retail Gas Stations remain the primary point of sale, with Direct Sales to Fleet Operators gaining share due to bulk procurement efficiencies.
End User:
Distinct operational requirements and purchasing behaviors characterize different end-user groups in the gasoline market.
- Personal Vehicle Owners:This segment comprises individual consumers who purchase gasoline for their private cars, motorcycles, and light trucks, primarily driven by daily commuting and personal travel needs. Convenience and price are significant factors influencing their purchasing decisions at the pump.
- Commercial Fleet Managers:Responsible for fueling company vehicles, these managers prioritize fuel efficiency, bulk purchasing discounts, and reliable supply to minimize operational costs. Their decisions often involve long-term contracts and specialized fuel card programs.
- Agricultural Operators:Farmers and agricultural businesses use gasoline for tractors, harvesters, and other farm machinery, particularly in smaller equipment and auxiliary power units.
- Construction Companies:Gasoline fuels various heavy equipment, portable generators, and light-duty vehicles used on construction sites, requiring consistent supply for project timelines.
- Event Organizers:This group utilizes gasoline for temporary power generation, specialized vehicles, and equipment at concerts, festivals, and other large-scale public gatherings.
Personal Vehicle Owners constitute the largest user base, and Commercial Fleet Managers are increasingly seeking integrated fuel solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai's expanding personal mobility needs drive significant gasoline consumption. The city's growing vehicle parc, particularly two-wheelers, presents a foundational demand source. This fuels investments in retail infrastructure across the Indian subcontinent.
India
Expanding personal mobility and a rising vehicle parc in India are foundational demand drivers. India's PLI scheme for automotive manufacturing supports domestic vehicle production, indirectly boosting fuel demand. The Delhi-NCR region, with its dense population, experiences high gasoline consumption and infrastructure development.
United States
Advanced engine technologies and a large existing light-duty vehicle fleet sustain gasoline demand in the United States. The US EPA's Tier 3 program mandates lower sulfur content, requiring refiners to invest in cleaner formulations. Houston, Texas, a major refining hub, focuses on producing compliant gasoline grades for national distribution.
China
Urbanization and economic growth in China generate substantial gasoline demand, particularly for passenger cars. China's GB standards for fuel quality enforce strict emissions and efficiency requirements on gasoline formulations. The Yangtze River Delta region, a key economic zone, exhibits high fuel consumption due to its industrial and transport activities.
Germany
The premium vehicle segment and a robust automotive industry support demand for higher-octane gasoline in Germany. EU's REACH framework influences the chemical additives used in German gasoline production, impacting formulation costs. The Rhine-Ruhr area, a major industrial heartland, requires diverse fuel types for its extensive logistics networks.
Saudi Arabia
Domestic transportation needs and a growing population drive gasoline consumption in Saudi Arabia. The Kingdom's national energy policies prioritize stable fuel supply for its citizens and industries. Jubail Industrial City, with its large refining complexes, is a critical production center for various petroleum products, including gasoline.
Gasoline Market Key Industry Players
Premium-margin players sit above commodity-margin players across product differentiation, primarily driven by octane ratings and fuel additives. The market structure exhibits a tiered consolidation, with large integrated oil companies dominating primary production. Strategic archetypes include integrated majors, specialized refiners focusing on high-octane blends, and retail network operators emphasizing customer experience. Companies pursue capacity expansion in desulfurization units and portfolio diversification into alternative fuels to maintain competitive positioning.
At the scale-driven end, Saudi Aramco, a state-owned enterprise, anchors significant crude oil production and refining capacity. ExxonMobil, a US-based integrated energy company, exemplifies the global major archetype, leveraging its extensive upstream and downstream assets. Shell, a Netherlands-based multinational, represents a retail-focused player, emphasizing its branded network and premium fuel offerings. These entities collectively shape the global gasoline supply chain, influencing production volumes and distribution strategies.
| Leading Market Players |
|---|
| Saudi Aramco |
| ExxonMobil |
| Chevron |
| PetroChina |
| Shell |
| TotalEnergies |
| BP |
| Valero Energy |
| Phillips 66 |
| Others |
Cost & Logistics Intelligence
The EU's REACH framework, governing chemical additives, gates both qualified supply and premium-tier pricing access for gasoline formulations. This regulation necessitates significant investment in compliant product development and testing.
Pricing Analysis
Engine performance optimization serves as the primary value-based pricing anchor in the gasoline market. Price differentiation stems from octane ratings and specialized fuel additives that enhance engine efficiency or reduce emissions. Pricing pressure stems from crude oil price volatility, which directly impacts refining margins for all grades. Personal vehicle owners remain highly price-sensitive for regular unleaded, while commercial fleet managers prioritize consistent supply and bulk discounts.
Supply Chain Analysis
Workforce availability in major refining hubs, including Houston, Jubail Industrial City, and the Yangtze River Delta, underpins the gasoline supply chain. Raw material dependencies center on crude oil and various chemical additives like ethanol and desulfurization agents. Commodity price volatility for crude oil presents a significant structural risk across the entire supply chain. Distribution runs primarily through a vast network of retail gas stations and direct sales to fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gasoline market is witnessing a vertical-integration race, with players pursuing advanced refining capabilities and downstream retail network control.
For Market Incumbents:Anchor existing market share by investing in advanced desulfurization and isomerization units to meet evolving fuel quality standards. Diversify product portfolios by expanding into biofuel blending and specialty fuel formulations for niche applications. Mitigate the BEV substitution threat through strategic retail site redevelopment, integrating EV charging infrastructure and enhanced convenience offerings. Control key refining assets to maintain production flexibility across fuel grades.
For New Entrants and Emerging Players:Enter via specialized fuel formulations targeting high-margin segments like motorsports or classic cars, which are less vulnerable to electrification trends. Target underpenetrated small-engine markets in Southeast Asia, leveraging existing distribution channels for generators and landscaping equipment. A go-to-market angle could involve partnering with local distributors to offer tailored fuel solutions for specific regional needs. Focus on niche applications where performance and reliability command a premium.
For Investors and Strategic Acquirers:Accelerated BEV adoption is the leading indicator that long-term gasoline demand will gradually erode, particularly in developed economies. Acquisition targets should include specialized refiners with proprietary high-octane or low-sulfur production technologies, or companies with strong retail networks capable of multi-energy transition. A sustained decline in light-duty vehicle parc growth in key regions warrants ongoing watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Desulfurization | Increases compliance with stringent emissions standards, ensuring market access for refiners. |
| Investment in Premium Fuel Additives | Enhances fuel performance and efficiency, supporting higher-margin product differentiation for brands. |
| Retail Network Modernization | Transforms traditional gas stations into multi-energy hubs, adapting to changing consumer behaviors. |
| Biofuel Blending Infrastructure | Enables compliance with renewable fuel mandates, diversifying feedstock options for producers. |
| Digital Twin Technology Adoption | Optimizes refinery operations and yield management, improving profitability from complex crude inputs. |
Research Approach
Government energy reports, industry association publications, and company financial filings formed the secondary backbone, complemented by primary interviews. This included conversations with refinery process engineers, retail network managers, fuel additive manufacturers, and commercial fleet operators. The analysis triangulated insights from these diverse sources with a bottom-up and top-down approach.
The analytical lens applied a bottom-up assessment of vehicle parc growth and fuel consumption patterns, cross-referenced with top-down macroeconomic indicators. Segmentation dimensions modeled included fuel type, application, distribution channel, and end-user, alongside regional regulatory frameworks. Compound annual growth rates were derived from historical data extrapolation and forward-looking projections of technological and regulatory shifts. Crude oil price forecasts and regional vehicle sales projections served as key industry-specific inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant geopolitical disruptions or accelerated electrification rates. The analysis reflects assumptions regarding global economic stability and the pace of regulatory enforcement. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Biobutanol Market
Fuels
Methane Market
Fuels
Electric Fuel Heater Market
Fuels
North America LNG Bunkering Market
Fuels
Coal Briquette Box Market
Fuels
South Africa Bunker Fuel Market
Fuels
Bunker Fuel Market
Fuels
China LNG Bunkering Market
Fuels
Asia-Pacific Commercial Aircraft Aviation Fuel Market
Fuels
Europe Coal Market
Fuels
North America Wood Pellet Market
Fuels
Gas and Solid Fuels (Wood) Fireplaces Market
Fuels
Mobile Fuel Delivery Market
Fuels
Bituminous Coal Market
Fuels
Renewable Fuel Quality and Regulatory Compliance Test Instruments Market
Fuels
LPG Tanker Market