
 Global Powertrain Market | 2026-2036
Global Powertrain Market Size, Share, and Industry Trends Forecast 2026-2036
Global Powertrain Market Foresight
Software-defined powertrain calibration sold as subscription-based performance upgrades is repositioning how OEMs monetize drivetrain assets. Robert Bosch GmbH leverages its embedded software stack to control module-level powertrain intelligence across European and Asian platforms. Continental AG anchors its competitive stance through in-house production of powertrain electronics and sensor fusion hardware. ZF Friedrichshafen AG specializes in integrated electric axle systems that consolidate motor, inverter, and transmission into single assemblies.
A powertrain comprises the integrated assembly of engine, transmission, driveshaft, differential, and axle components that generate mechanical propulsion for wheeled, tracked, or marine vehicles, with modern architectures specifying torque outputs from 150 Nm in compact passenger electric motors to exceeding 3,000 Nm in heavy-duty commercial hybrid systems. Electric Motor and Hybrid Drive segments are capturing expanding margin pools as OEMs redesign platforms around modular e-axle architectures, while Internal Combustion Engine configurations retain volume dominance in emerging-market commercial vehicle applications where refueling infrastructure remains sparse. Transmission Systems face structural pressure from multispeed e-axle integration, yet retain relevance in off-road and marine segments demanding precise torque modulation.
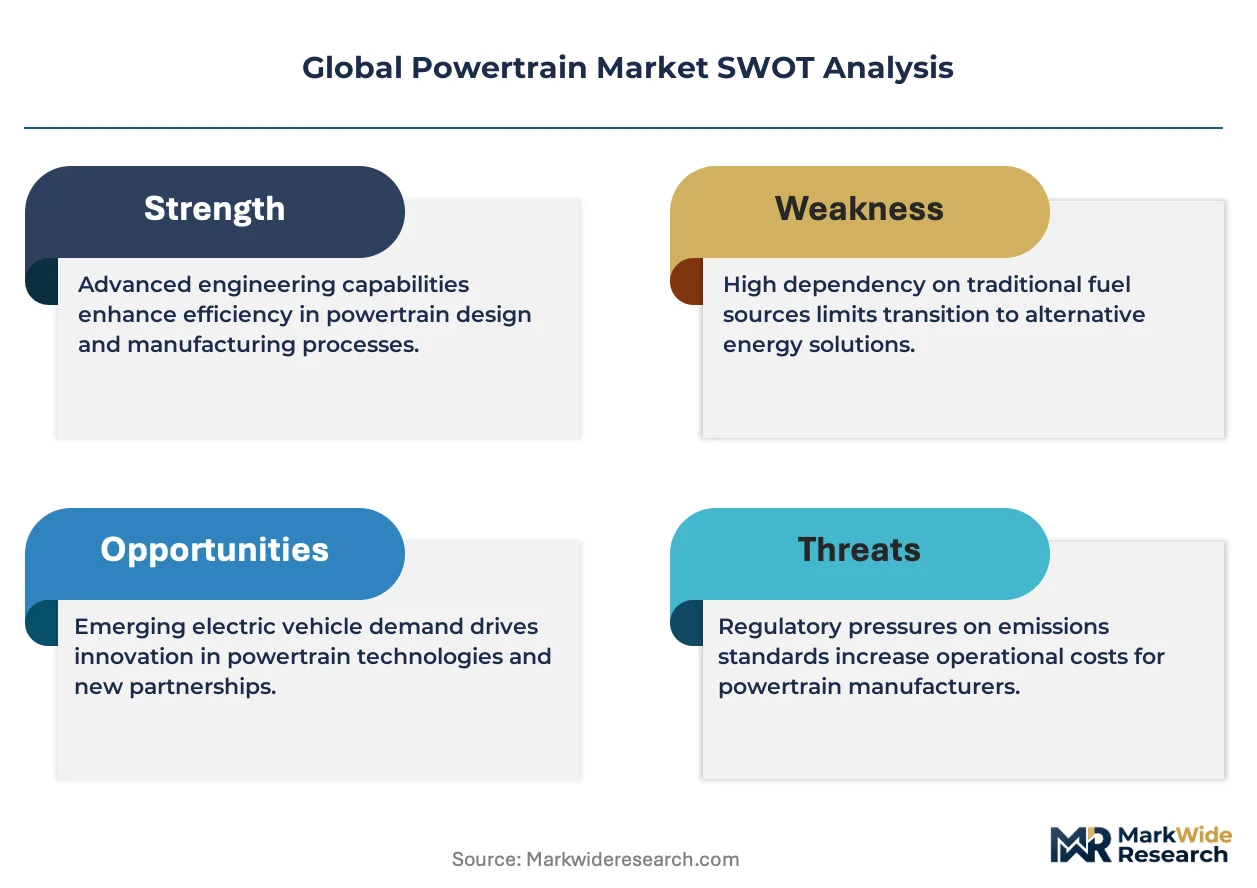
EPA tailpipe standards, the EU Green Deal's CO2 fleet mandates, and China's MIIT new energy vehicle credit system are forcing powertrain suppliers to maintain parallel certification tracks for combustion, hybrid, and fully electric architectures. NHTSA safety protocols for battery propulsion systems add compliance layers that favor Tier-1 suppliers with established validation laboratories. Stakeholders must monitor regulatory divergence between California's Advanced Clean Trucks rule and federal baseline standards to avoid stranded platform investments.
Market Dynamics
Modular e-axle architectures are compressing traditional component hierarchies as OEMs redesign platforms around integrated motor-inverter-transmission assemblies, forcing suppliers to abandon standalone transmission and engine module strategies.
Growth Catalysts
- EPA tailpipe standards:US commercial fleet operators are accelerating hybrid procurement to meet tightening Phase 3 greenhouse gas rules for medium and heavy-duty vehicles.
- China MIIT credit system:New energy vehicle quotas mandate minimum production ratios that push domestic automakers toward dedicated hybrid and fully electric platforms.
- EU Green Deal CO2 fleet mandates:European passenger car manufacturers face binding 2035 phase-out deadlines that compress powertrain electrification timelines.
Market Restraints
- Rare earth supply concentration:Permanent magnet motor production depends on Chinese-processed neodymium and dysprosium, creating geopolitical input risk.
- Legacy asset stranding:Internal combustion engine manufacturing facilities face accelerated depreciation as platform volumes shift toward electrification.
- Refueling infrastructure gaps:Sparse hydrogen and high-power charging networks in Brazil, India, and Southeast Asia limit fuel cell and battery electric commercial vehicle deployment.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for advanced chemistry cell manufacturing and electric vehicle assembly attract powertrain component localization.
- Marine electrification:Harbor craft and short-sea shipping segments in Norway and Denmark adopt hybrid-electric propulsion under port authority emission controls.
- Software-defined calibration:Over-the-air performance upgrades enable recurring revenue streams from existing hardware installations.
Industry Challenges
- Embedded systems talent scarcity:Powertrain control software development requires automotive-grade functional safety expertise that outpaces graduate pipeline output.
- Parallel certification complexity:Suppliers must maintain simultaneous homologation tracks for combustion, hybrid, and battery electric architectures under divergent NHTSA, KBA, and MIIT protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Powertrain Market |
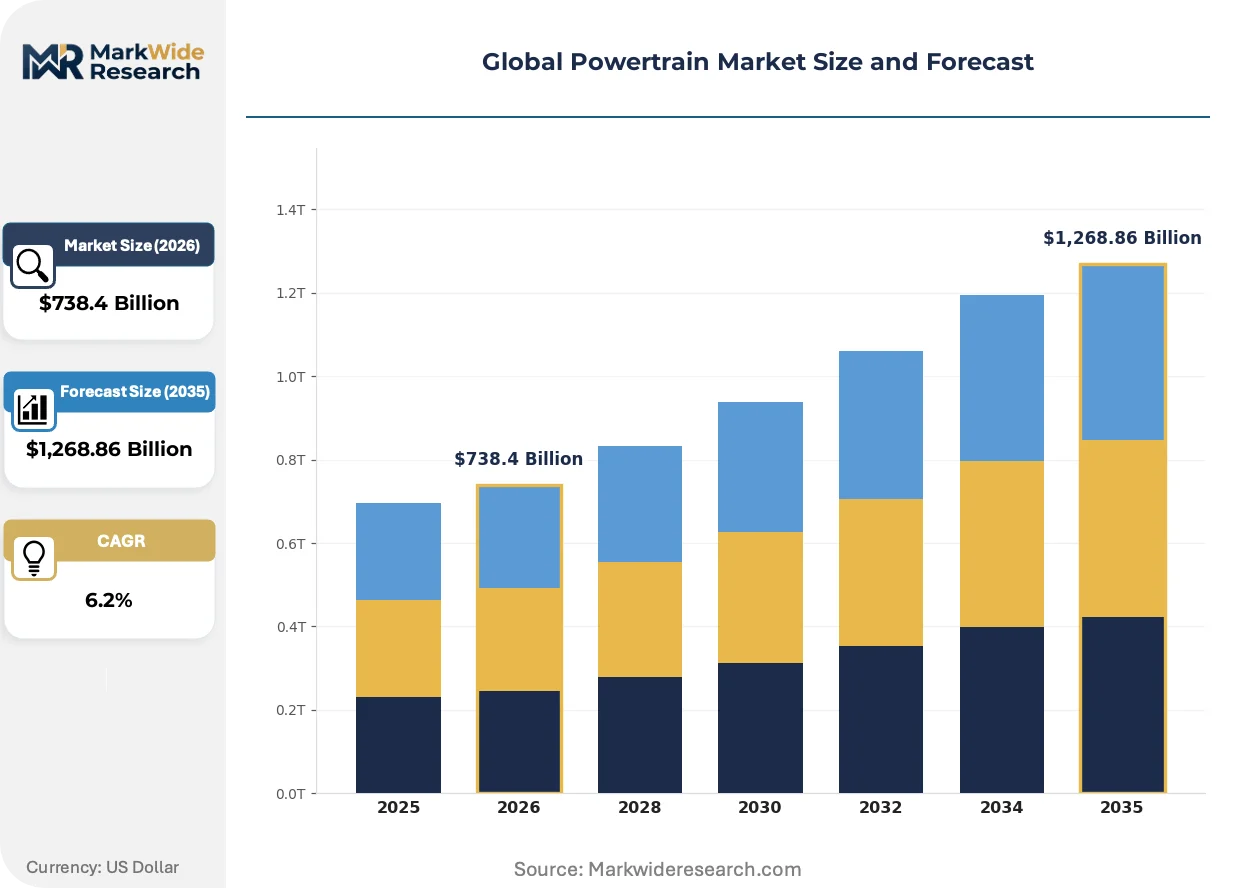
| Market Size in 2026 | $738.4 Billion |
| Market Size in 2035 | $1,268.86 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Internal Combustion Engine, Electric Motor, Hybrid Drive, Transmission Systems, Fuel Cells Technology: Turbocharging, Direct Injection, Variable Valve Timing, Solid State Battery, Regenerative Braking Application: Passenger Vehicles, Commercial Vehicles, Off-Road Vehicles, Motorcycles, Marine Vessels End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers, Specialty Vehicle Manufacturers |
| Companies Covered | Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, Denso Corporation, Magna International Inc., Aisin Seiki, BorgWarner Inc., General Motors Company, Hyundai Motor Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Powertrain Market Shifts & Advancements
Powertrain engineering is pivoting from mechanical optimization to electromechanical integration, with software control layers determining performance differentiation more than hardware specifications.
Silicon carbide power electronics is consolidating inverter efficiency gains into compact form factors that enable higher motor speeds and reduced thermal management mass. Commercial vehicle manufacturers in Germany and Japan are adopting 800-volt architectures for long-haul electric trucks. This voltage transition is consolidating supplier tiers as inverter and motor engineering teams merge under single component ownership.
The EU Green Deal's CO2 fleet mandates impose binding manufacturer-specific targets that escalate through 2030 and culminate in a 2035 new combustion vehicle prohibition. European suppliers have reallocated R&D budgets toward integrated e-axle development and away from transmission refinement. Passenger car platforms launching from 2026 face the strictest compliance windows, compressing validation cycles for hybrid system integration.
Fleet procurement is fragmenting across ownership models as logistics operators pilot battery-as-a-service and powertrain-subscription arrangements that unbundle capital expenditure from utilization risk. Third-party fleet managers in the Netherlands and California are negotiating guaranteed residual value clauses that shift technology obsolescence risk back to OEM captive finance arms. This financial restructuring is most visible in heavy-duty segments where asset lifecycles exceed seven years and secondary market liquidity remains uncertain.
Global Powertrain Market Segmentation
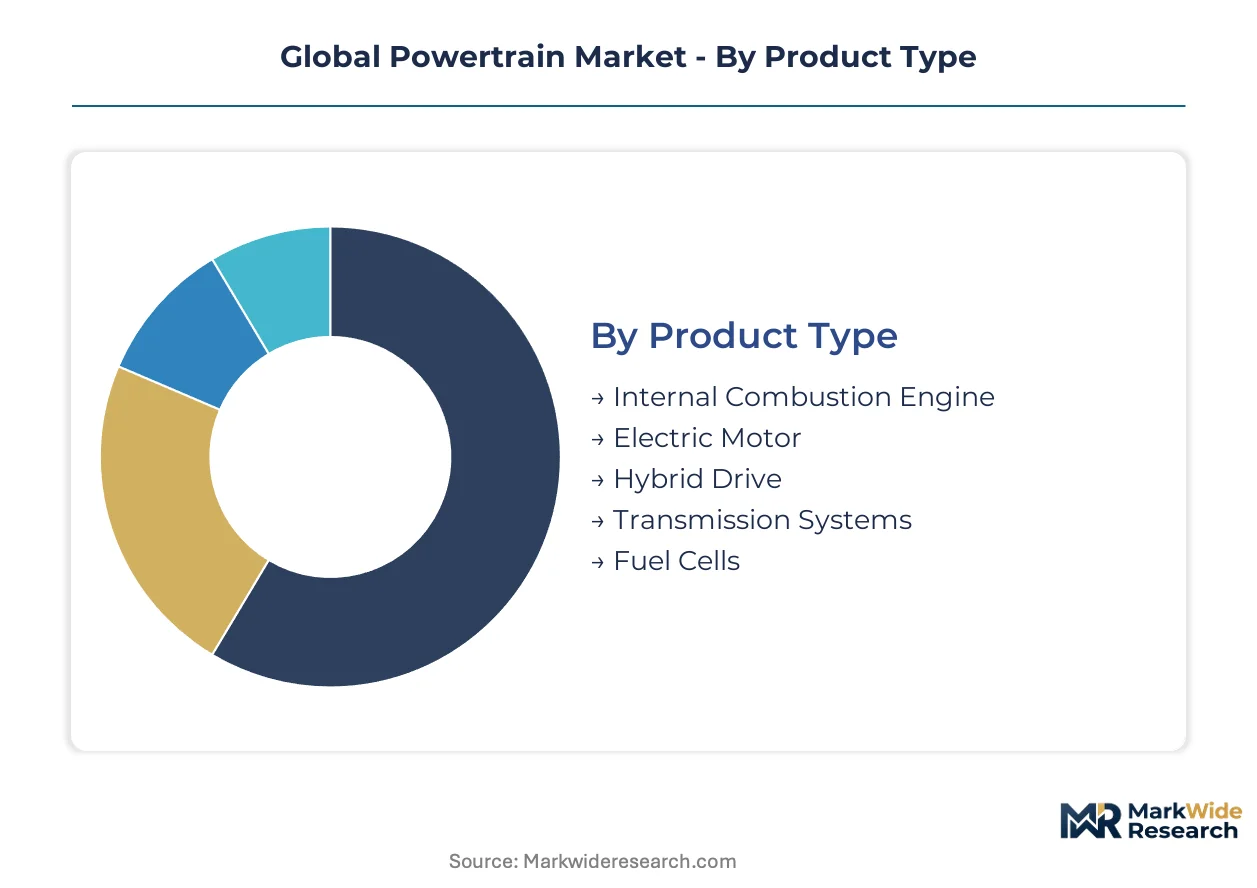
Powertrain segmentation reveals divergent certification burdens across electrification pathways, with hybrid architectures demanding parallel homologation tracks that strain supplier validation capacity. Technology choices determine margin structure and regulatory exposure more than end-use application in the current compliance environment.
Product Type:
Certification complexity varies sharply across propulsion architectures, with EPA Phase 3, EU Green Deal CO2 mandates, and China MIIT credit rules imposing distinct testing protocols on each segment.
- Internal Combustion Engine:Compression-ignition and spark-ignition architectures retain dominance in heavy-duty commercial fleets where refueling infrastructure constrains electrification. Demand concentrates in Brazil and India where biodiesel blending mandates and sparse charging networks preserve diesel platform viability. Tier-1 suppliers face stranded asset risk as OEMs freeze new combustion R&D spending.
- Electric Motor:Permanent magnet synchronous and induction motor designs specify torque densities exceeding 15 kW/kg for passenger car integration. Procurement concentrates around Stuttgart and Shanghai manufacturing corridors where magnet supply chains and winding automation clusters co-locate. Rare earth processing concentration in China creates input vulnerability for European and Japanese motor programs.
- Hybrid Drive:Parallel and series-parallel architectures combine thermal and electric torque paths through planetary gear sets or clutch-coupled motor-generator units. EPA tailpipe rules and EU fleet mandates accelerate medium-duty fleet procurement.
- Transmission Systems:Multispeed automated manual and dual-clutch units face displacement by integrated e-axle gear reduction stages. Off-road and marine segments retain demand for precise torque modulation.
- Fuel Cells:Proton exchange membrane stacks paired with hydrogen storage systems target long-haul trucking where battery weight penalties limit payload capacity. Deployment concentrates in California, Germany, and South Korea where hydrogen corridor funding exists.
Internal Combustion Engine sits at the top of the volume ranking, with Electric Motor climbing the fastest.
Technology:
Technology selection determines cost tier positioning, with premium architectures commanding 40-60% price premiums over baseline configurations.
- Turbocharging:Variable geometry and twin-scroll turbochargers force-feed combustion chambers to extract power density from downsized engine displacements. Demand persists in European performance passenger segments and Chinese domestic brand SUVs where fuel economy regulations meet consumer power expectations.
- Direct Injection:High-pressure gasoline and diesel common-rail systems optimize combustion phasing for particulate and NOx compliance. Euro 6e and EPA Tier 3 particulate number limits drive hardware upgrades.
- Variable Valve Timing:Cam-phasing and lift-modulation mechanisms reduce pumping losses across engine load ranges. Mature technology with margin compression.
- Solid State Battery:Lithium-metal anode and ceramic electrolyte architectures promise energy densities exceeding 400 Wh/kg with reduced thermal runaway risk. Toyota and QuantumScape pilot lines target automotive qualification.
- Regenerative Braking:Blended brake systems recover kinetic energy through motor-generator torque reversal, feeding high-voltage battery packs. Integration complexity with foundation brake systems creates Tier-1 consolidation pressure.
Turbocharging retains the largest installed base, though Solid State Battery gains share fastest among emerging technologies.
Application:
Application segmentation tracks customer type divergence between fleet procurement and retail consumer purchase patterns.
- Passenger Vehicles:Battery electric and plug-in hybrid platforms dominate OEM electrification roadmaps, with 800-volt architectures reducing charge duration. European and Chinese manufacturers lead platform launches.
- Commercial Vehicles:Medium and heavy-duty fleets face binding EPA Phase 3 and EU CO2 standards that compress powertrain replacement cycles. Hybrid procurement accelerates in US regional haul and last-mile delivery segments.
- Off-Road Vehicles:Agricultural tractors and construction equipment demand high-torque, low-speed operation that challenges electric motor thermal management. Diesel-electric hybrid architectures bridge compliance gaps.
- Motorcycles:Two-wheeler electrification concentrates in India and Southeast Asia where government subsidies and urban air quality mandates reshape urban mobility. Swappable battery business models reduce upfront cost barriers.
- Marine Vessels:Harbor craft and short-sea shipping in Norway, Denmark, and California adopt hybrid-electric propulsion under port authority emission controls. Battery energy density constraints limit deep-sea applications.
Passenger Vehicles command the greatest absolute volume, while Marine Vessels expands most quickly from a small base.
End User:
End user structure reflects supply chain position and captive versus merchant market exposure.
- OEMs:Volkswagen, Toyota, and BYD internalize powertrain design and assembly for platform control, though module sourcing remains partially external. Vertical integration intensity varies by electrification strategy.
- Tier-1 Suppliers:Bosch, Continental, and ZF manufacture complete powertrain modules for multiple OEM platforms, bearing homologation and warranty liability. Software-defined calibration creates recurring revenue opportunities.
- Vehicle Assemblers:Contract manufacturers and emerging EV brands procure complete powertrain systems rather than developing in-house capability. Margin pressure concentrates at this tier.
- Aftermarket Providers:Remanufactured transmissions and engine rebuild services serve aging fleet populations in markets with extended vehicle lifecycles. Electrification threatens long-term addressable market.
- Specialty Vehicle Manufacturers:Military, mining, and emergency vehicle builders specify ruggedized powertrain configurations with extended service intervals and field repairability. Low volume, high customization requirements.
Tier-1 Suppliers capture the highest revenue concentration, with Specialty Vehicle Manufacturers showing the steepest expansion trajectory in defense and resource extraction segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing powertrain manufacturing investment toward jurisdictions offering lower cost-of-compliance for parallel certification tracks. Suppliers are relocating validation capacity to exploit gaps between EPA Phase 3 stringency and emerging-market enforcement timelines.
United States
Commercial fleet operators in California and the Midwest are accelerating hybrid procurement ahead of EPA Phase 3 greenhouse gas rules for medium and heavy-duty vehicles. The NHTSA safety protocols for battery propulsion systems add compliance layers that favor established Tier-1 suppliers with captive validation laboratories. Detroit and the Southeast manufacturing corridor concentrate e-axle assembly investments from domestic and transplant OEMs.
Germany
Passenger car manufacturers face binding EU Green Deal CO2 fleet mandates that culminate in a 2035 combustion vehicle prohibition. The KBA homologation authority maintains Europe's most stringent type-approval protocols for hybrid system integration. Stuttgart and Friedrichshafen anchor supplier R&D clusters where Bosch, Continental, and ZF co-locate powertrain electronics development with OEM platform engineering teams.
China
Domestic automakers are redirecting platform development toward dedicated hybrid and fully electric architectures under MIIT new energy vehicle credit system quotas. The dual carbon goals accelerate decommissioning of combustion-focused production lines in coastal provinces. Shanghai and the Yangtze River Delta manufacturing belt concentrate permanent magnet motor winding automation and rare earth processing integration.
Japan
Keiretsu-affiliated suppliers maintain parallel development tracks for solid-state battery qualification and hybrid transmission refinement under METI technology roadmaps. Domestic OEMs internalize powertrain design for platform control while sourcing power electronics from captive supplier networks. Nagoya and the Kansai industrial region concentrate silicon carbide inverter engineering and thermal management system prototyping.
India
Two-wheeler electrification concentrates in Maharashtra and Tamil Nadu where state-level subsidies and urban air quality mandates reshape urban mobility procurement. The PLI scheme for advanced chemistry cell manufacturing attracts powertrain component localization from Korean and Japanese battery suppliers. Chennai and Pune host emerging e-axle assembly joint ventures serving domestic OEMs and export markets.
Global Powertrain Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with Tier-1 module suppliers capturing concentrated revenue pools in electrified architectures while vehicle assemblers face margin compression. The supplier base organizes around three archetypes: integrated system architects controlling motor-inverter-transmission assemblies, component specialists defending positions in thermal and friction management, and software-defined calibration providers monetizing recurring revenue from installed hardware. Consolidation pressure favors backward integration into power electronics and forward partnerships with fleet finance arms to guarantee residual values.
Within the integrated system architect tier, Robert Bosch GmbH and Continental AG exemplify European-based suppliers that have reallocated R&D toward e-axle development and embedded software stacks. ZF Friedrichshafen AG occupies a position specializing in consolidated electric axle assemblies that merge multiple propulsion functions under single component ownership. These three German entities anchor the premium-tier competitive vector where homologation liability and warranty coverage create barriers to merchant market entry.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| ZF Friedrichshafen AG |
| Denso Corporation |
| Magna International Inc. |
| Aisin Seiki |
| BorgWarner Inc. |
| General Motors Company |
| Hyundai Motor Company |
| Others |
Supply & Pricing Matrix
Rare earth magnet feedstock flows from Chinese processing facilities through winding automation clusters in Shanghai and Stuttgart before reaching three-tier pricing structure across premium, standard, and economy levels at OEM assembly lines. Neodymium price volatility propagates downstream through motor-inverter-transmission assemblies, compressing margins for Tier-1 suppliers lacking captive magnet supply while rewarding integrated e-axle architects with backward integration into power electronics.
Pricing Analysis
Distributor margins on powertrain modules compress as OEMs consolidate procurement under single-source e-axle contracts. Three-tier pricing structure across premium, standard, and economy levels separates silicon carbide inverter configurations from silicon-based alternatives, with EPA Phase 3 certification grade commanding additional engineering surcharges. Cost compression in standard-tier hybrid systems is intensifying because Chinese domestic brands are scaling parallel production lines. Fleet operators demonstrate highest price sensitivity through battery-as-a-service arrangements that unbundle capital expenditure.
Supply Chain Analysis
Permanent magnet supply rests on Chinese-processed neodymium and dysprosium, with Japanese and Korean motor programs drawing from concentrated rare earth refining capacity in Inner Mongolia and Jiangxi province. Winding copper, silicon carbide substrates, and thermal interface materials constitute secondary input dependencies. Single-source vulnerability in magnet processing creates geopolitical exposure for European e-axle programs. Distribution runs through captive OEM supply chains in Germany and China, with merchant market penetration limited by homologation liability barriers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Powertrain procurement is shifting toward premium integrated architectures as fleet operators prioritize guaranteed residual values over lowest unit cost. This quality migration favors suppliers with captive software calibration stacks and validation laboratory networks.
For Market Incumbents: Acquire silicon carbide inverter engineering teams to consolidate motor-inverter-transmission ownership under single component architecture. Secure winding automation capacity in the Yangtze River Delta to offset rare earth processing concentration. Defend against emerging Chinese e-axle exporters by embedding functional safety certification deeper into control software layers. For New Entrants and Emerging Players: EPA Phase 3 in the United States opens a window for medium-duty hybrid system specialists to capture fleet procurement cycles ahead of Tier-1 incumbent reallocation. Target last-mile delivery operators in California and the Midwest with modular retrofit kits compatible with existing chassis platforms. Lead with subscription-based calibration revenue models that shift buyer preference toward software-upgradeable hardware. For Investors and Strategic Acquirers: Consolidation pressure builds where Tier-2 component specialists lack capital to fund parallel certification tracks for combustion, hybrid, and battery electric architectures. Long-term viability favors integrated system architects with established KBA and MIIT validation relationships over standalone transmission or thermal component vendors. Watch EPA enforcement variance between California's Advanced Clean Trucks rule and federal baseline standards as inflection signal for stranded platform risk.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces validation burden across EPA, KBA, and MIIT certification tracks for multi-region OEM programs. |
| Battery Supply Agreement | Secures advanced chemistry cell allocation under India's PLI scheme for localized e-axle assembly. |
| Software-Defined Vehicle Investment | Enables recurring revenue from over-the-air powertrain calibration upgrades on installed hardware bases. |
| Geographic Manufacturing Footprint | Positions e-axle assembly near Stuttgart and Shanghai corridors to co-locate with magnet supply chains. |
| Charging Infrastructure Partnership | De-risks commercial fleet procurement by guaranteeing high-power charging access for 800-volt architectures. |
Research Methodology
Multiple input streams — OEM platform engineering disclosures, Tier-1 supplier procurement patterns, and regulatory filing databases — were reconciled through structured interviews with powertrain control software architects, homologation validation leads, fleet procurement officers, and aftermarket distribution managers. Secondary validation drew from EPA certification records, EU type-approval documentation, MIIT new energy vehicle credit filings, and vehicle production registration databases. Bottom-up segment sizing and top-down macroeconomic anchoring were cross-checked for consistency across the analysis window.
Data-stream reconciliation produced volume and value estimates segmented by propulsion architecture, vehicle class, content per vehicle, OEM tier positioning, and regional production cluster. CAGRs were derived from installed base turnover modeling and replacement cycle compression under tightening tailpipe standards. Forecast inputs incorporated silicon carbide adoption curves, rare earth price trajectories, and fleet ownership model fragmentation.
Revisions become necessary when regulatory enforcement timelines diverge between California and federal baselines, when rare earth export restrictions materialize, or when solid-state battery qualification accelerates platform redesign cycles. A small set of named triggers — EPA Phase 3 stringency variance, MIIT credit system adjustments, and EU Green Deal implementation pacing — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Intermediate Shaft Market
Powertrain
Gear Oil Market
Powertrain
Automotive Conversion Kit Market
Powertrain
Powertrain Domain Control Unit Platforms Market
Powertrain
High Speed Engine Market
Powertrain
Automotive Slipper Clutch Market
Powertrain
Electric Powertrain Systems Market
Powertrain
Mechanical Reciprocating Engine Market
Powertrain
Automotive Engine Air Filter Market
Powertrain
Diesel Particulate Filter (DPF) Market
Powertrain
Car Oil Filter Market
Powertrain
Transmission Oil Pumps Market
Powertrain
Automotive Oil Sump Market
Powertrain
Fuel Cell Powertrain Market
Powertrain
Automotive Water Pump Market
Powertrain
Automotive Fluid Reservoir Market