
 Gasoline Direct Injection Market | 2026-2036
Gasoline Direct Injection Market Size, Share, and Industry Trends Forecast 2026-2036
Gasoline Direct Injection Market Analysis
Euro 7 emission standards is restructuring the cost-of-entry calculus for gasoline direct injection suppliers, forcing investments in particulate filter integration and higher injection pressures. Robert Bosch GmbH leverages its vertical integration across fuel injectors and control electronics to sustain engineering margins. Denso Corporation anchors its position through manufacturing scale in Asian automotive clusters. Continental AG competes on sensor fusion capabilities that differentiate its pump-control unit architectures.
Gasoline direct injection is a fuel delivery architecture that pressurizes gasoline to 200-350 bar before atomizing it directly into the combustion chamber, enabling precise charge stratification and lean-burn operation for thermal efficiency gains above port-injection systems. Fuel injectors and high-pressure pumps command the dominant margin pools within the component segment due to precision machining requirements and materials substitution toward piezoelectric actuators. Turbocharged dual-injection configurations represent the fastest-growing technology segment as OEMs combine port and direct injection to mitigate particulate emissions while preserving power density.
EPA tailpipe standards in the United States, Euro 7 in Europe, and China's Stage 6b emissions rules administered by MEE collectively mandate lower particulate number limits that expand addressable demand for gasoline particulate filters and recalibrated injection strategies. NHTSA fuel economy requirements in the United States reinforce this trajectory by penalizing fleet-average consumption shortfalls. Stakeholders must monitor regulatory divergence between particulate-count methodologies and CO2 credit trading mechanisms when allocating R&D across regional product variants.
Market Dynamics
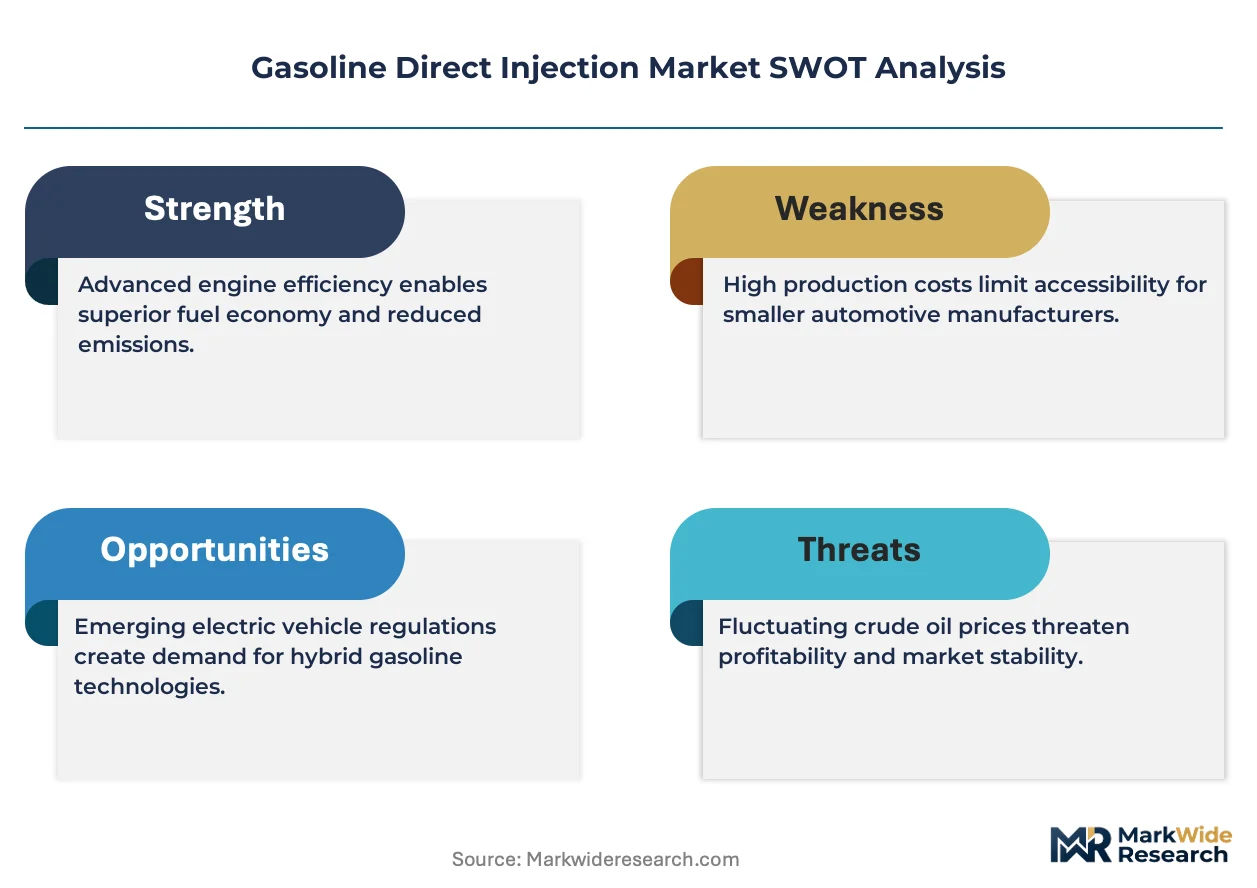
The gasoline direct injection market is being restructured by Euro 7 particulate number limits, which mandate sub-10 nm filtration thresholds that force simultaneous hardware redesign across fuel injectors, pumps, and exhaust aftertreatment architectures.
Growth Catalysts
- Euro 7 emission limits:The European Union's particulate matter thresholds compel OEMs to adopt high-pressure injection systems with integrated gasoline particulate filters, expanding component demand across powertrain portfolios.
- Turbocharged dual-injection architectures:The convergence of port and direct injection enables lean-burn operation while mitigating soot formation, attracting engineering investment from passenger vehicle manufacturers in China and Japan.
- Stage 6b rules:China's MEE-administered standards impose equivalent particulate constraints, accelerating localized production of electronic control units and high-pressure pumps in automotive clusters near Shanghai and Guangzhou.
Market Restraints
- Piezoelectric actuator cost volatility:Precision-machined ceramic components and rare-earth dependencies concentrate input cost risk with specialized suppliers in Germany and Japan.
- High-pressure pump supply concentration:Precision forging and surface treatment capabilities cluster with tier-one automotive suppliers in Bavaria and Aichi Prefecture, creating single-source vulnerabilities.
- Technical limitation of injector nozzle durability:Cavitation erosion at 350 bar operating pressures constrains service intervals and warranty exposure for direct injection systems.
Strategic Opportunities
- India's BS-VI Phase II transition:The country's tightening particulate standards create white space for localized fuel system manufacturing as Maruti Suzuki and Tata Motors expand direct injection penetration in compact segments.
- Electrification-convergence hybrid powertrains:Integration of direct injection with 48V mild-hybrid architectures enables cylinder deactivation strategies that preserve thermal efficiency during electric-only operation.
- Aftermarket calibration services:Independent service channels in the United States are developing flash-programming capabilities for injection timing optimization as EPA enforcement of tampering restrictions intensifies.
Industry Challenges
- Precision machining skill scarcity:Micro-drilling of injector nozzles to 100-micron tolerances requires specialized metrology and process engineering expertise concentrated with aging workforces in Stuttgart and Nagoya.
- Certification timeline compression:Euro 7's 2025 implementation deadline forces parallel validation of hardware and software across multiple engine families, straining dynamometer and emissions testing capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gasoline Direct Injection Market |
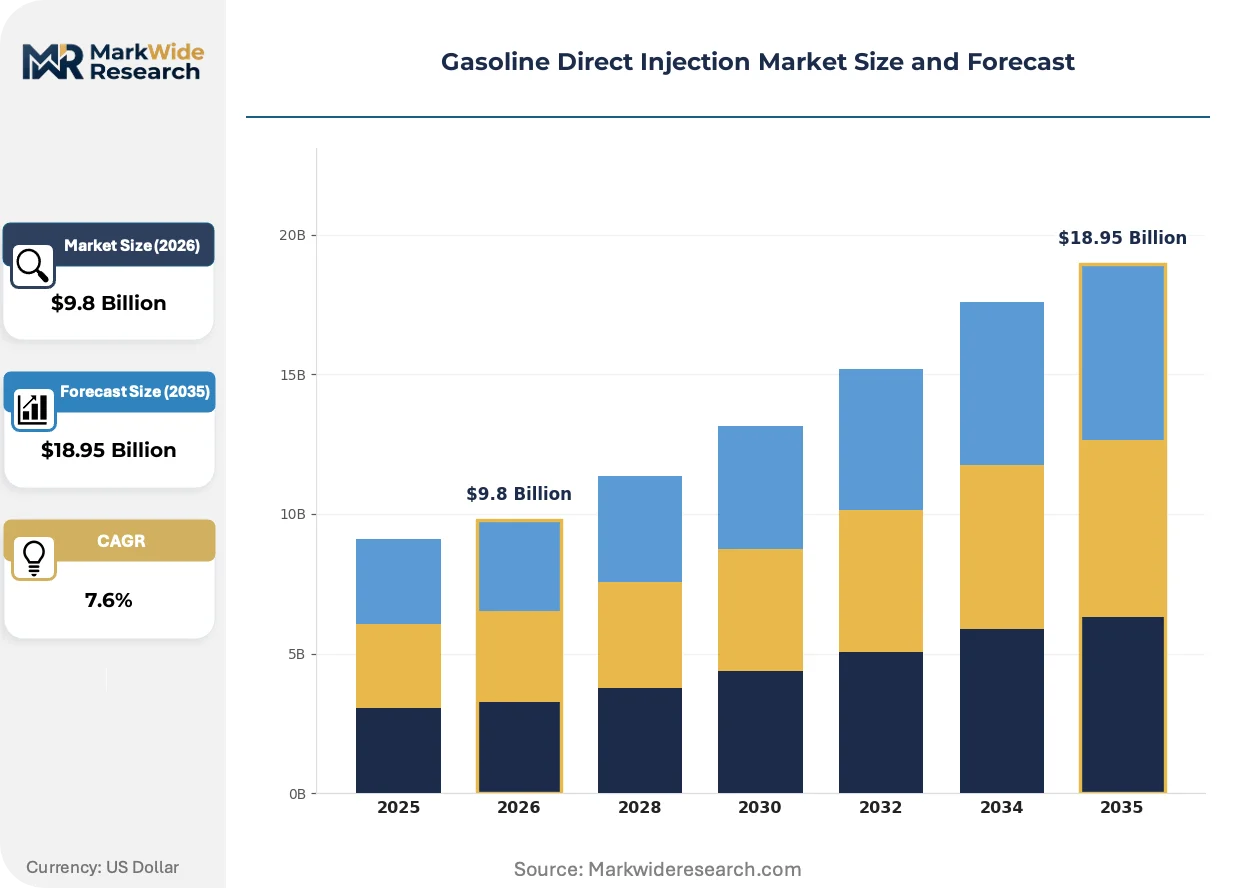
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $18.95 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Fuel Injectors, Pumps, Control Units, Sensors Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Small Engines Technology: Single Injection, Multi-Point Injection, Dual Injection, Turbocharged End User: OEMs, Aftermarket Providers, Dealerships, Repair Shops |
| Companies Covered | Robert Bosch GmbH, Denso Corporation, Continental AG, Marelli Holdings Co., Ltd., BorgWarner Inc., Magneti Marelli S.p.A., Hitachi Astemo, Ltd., Infineon Technologies AG, Stanadyne Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gasoline Direct Injection Market Emerging Trajectories
Technology trajectories in gasoline direct injection are converging on higher-pressure operation, sensor fusion, and modular architectures that reduce variant complexity while satisfying divergent regional emission protocols.
Piezoelectric direct-acting fuel injectors are consolidating competitive positioning in premium powertrain segments. These actuators enable multiple injection events per combustion cycle with sub-millisecond response times. German and Japanese OEMs are embedding this hardware across four-cylinder turbocharged engines to achieve stratified charge operation without sacrificing durability. The technology is consolidating supplier margins toward precision ceramic manufacturing and away from legacy solenoid architectures.
REACH compliance deadlines for per- and polyfluoroalkyl substances are forcing reformulation of fuel system seals and coatings. The European Chemicals Agency's restriction proposals target fluoropolymer materials common in high-pressure o-rings and piston coatings. Component suppliers are accelerating validation of hydrogenated nitrile rubber and advanced thermoplastic elastomers. The seal and gasket segment is absorbing disproportionate R&D allocation as substitution timelines compress.
Fleet procurement of injection systems is fragmenting toward engine-family-specific contracts rather than platform-wide supply agreements. OEM powertrain divisions are unbundling hardware from calibration intellectual property, treating injection strategies as licensable assets distinct from physical components. This pattern is most visible in the United States, where EPA certification binds specific calibrations to engine families, creating incentive for modular software architectures that span supplier boundaries.
Gasoline Direct Injection Market Segmentation
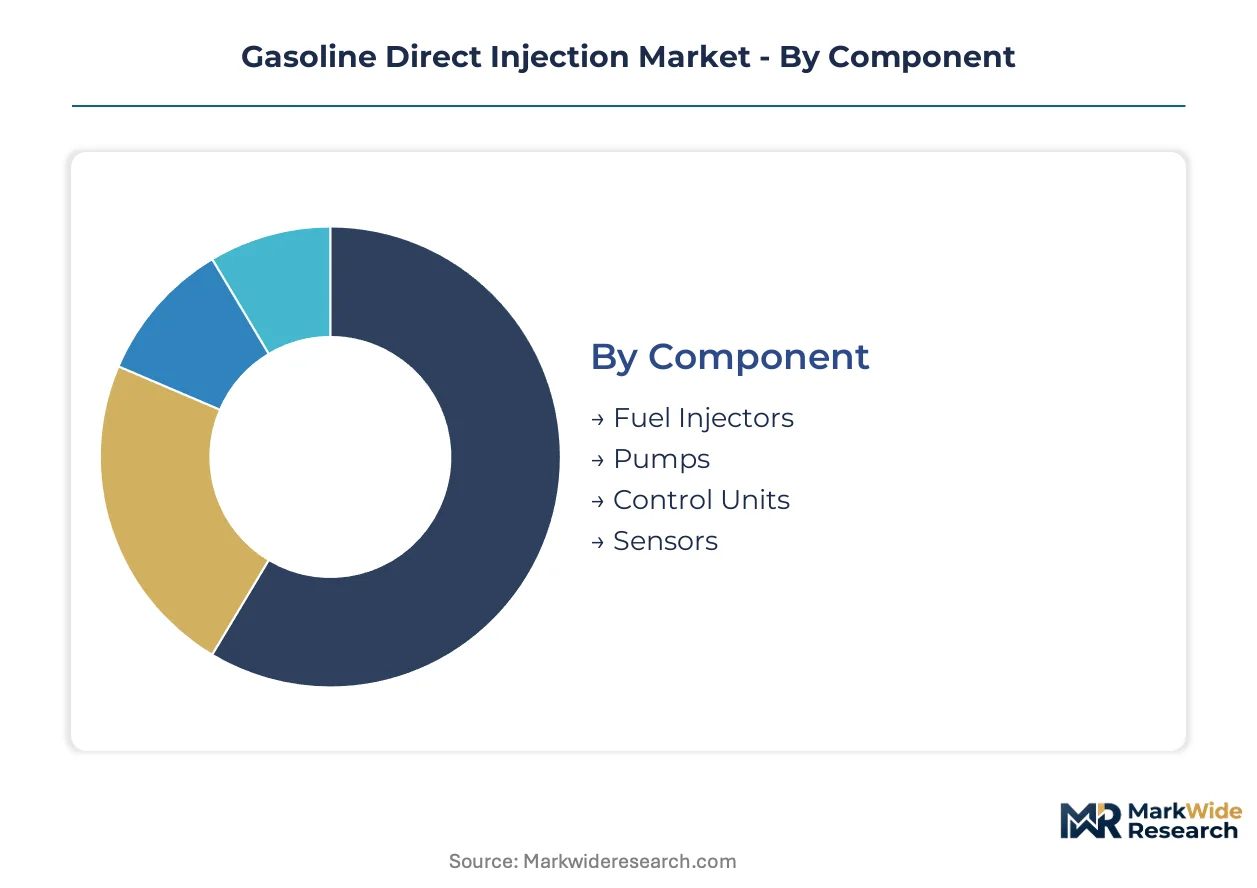
Component selection in gasoline direct injection hinges on pressure ratings and emission compliance trajectories. Application segmentation tracks divergent durability requirements across vehicle classes. Technology and end-user splits reveal where hardware margins concentrate versus where software and calibration value accumulates.
Component:
Procurement decisions prioritize pressure tolerance, precision machining heritage, and integration complexity with engine control architectures.
- Fuel Injectors:Piezoelectric and solenoid actuators atomize gasoline at 200-350 bar through micro-machined nozzles with 100-micron tolerances. Demand clusters with German and Japanese passenger vehicle OEMs pursuing Euro 7 stratified charge operation.
- Pumps:High-pressure fuel pumps utilize precision-forged cam lobes and diamond-like carbon coatings to sustain 15,000 rpm operation. Bavarian and Aichi Prefecture suppliers dominate forging and surface treatment capacity for turbocharged engine platforms.
- Control Units:Electronic control modules integrate injection timing algorithms with lambda sensor feedback.
- Sensors:Rail pressure and temperature transducers enable closed-loop injection control.
Volume sits with fuel injectors; growth tilts toward control units as OEMs unbundle hardware from calibration intellectual property.
Application:
Duty cycles and emission exposure hours determine injection system specification and warranty exposure.
- Passenger Vehicles:Turbocharged downsized engines in compact and mid-size segments drive dual-injection adoption for particulate mitigation. Chinese and Indian OEMs accelerate localization of fuel system manufacturing for Stage 6b and BS-VI Phase II compliance.
- Commercial Vehicles:Light commercial vans and small trucks require extended service intervals under high-load operation.
- Motorcycles:Single-cylinder and parallel-twin engines adopt simplified direct injection for fuel economy gains in Southeast Asian commuter markets.
- Small Engines:Lawn equipment and marine outboards face emerging particulate standards in California and the European Union.
Passenger vehicles absorb the dominant hardware volume; motorcycles represent the steepest expansion trajectory as two-wheeler emission rules tighten across Asia.
Technology:
Injection event sequencing and pressure modulation capabilities separate premium powertrain architectures from cost-optimized systems.
- Dual Injection:Combined port and direct injection enables lean-burn stratified operation while reducing particulate formation through fuel wall-wetting control. Japanese and German OEMs deploy this architecture across four-cylinder turbocharged engines to satisfy Euro 7 particulate number limits without gasoline particulate filters.
- Turbocharged:Forced induction raises cylinder pressures and thermal loads, demanding 350-bar injection systems with enhanced nozzle durability.
- Multi-Point Injection:Sequential port injection persists in cost-sensitive segments and as a dual-injection companion.
- Single Injection:Baseline direct injection architectures serve emerging market price points with simplified control strategies.
Dual injection commands the premium tier; turbocharged configurations scale fastest as downsizing penetrates mid-market segments.
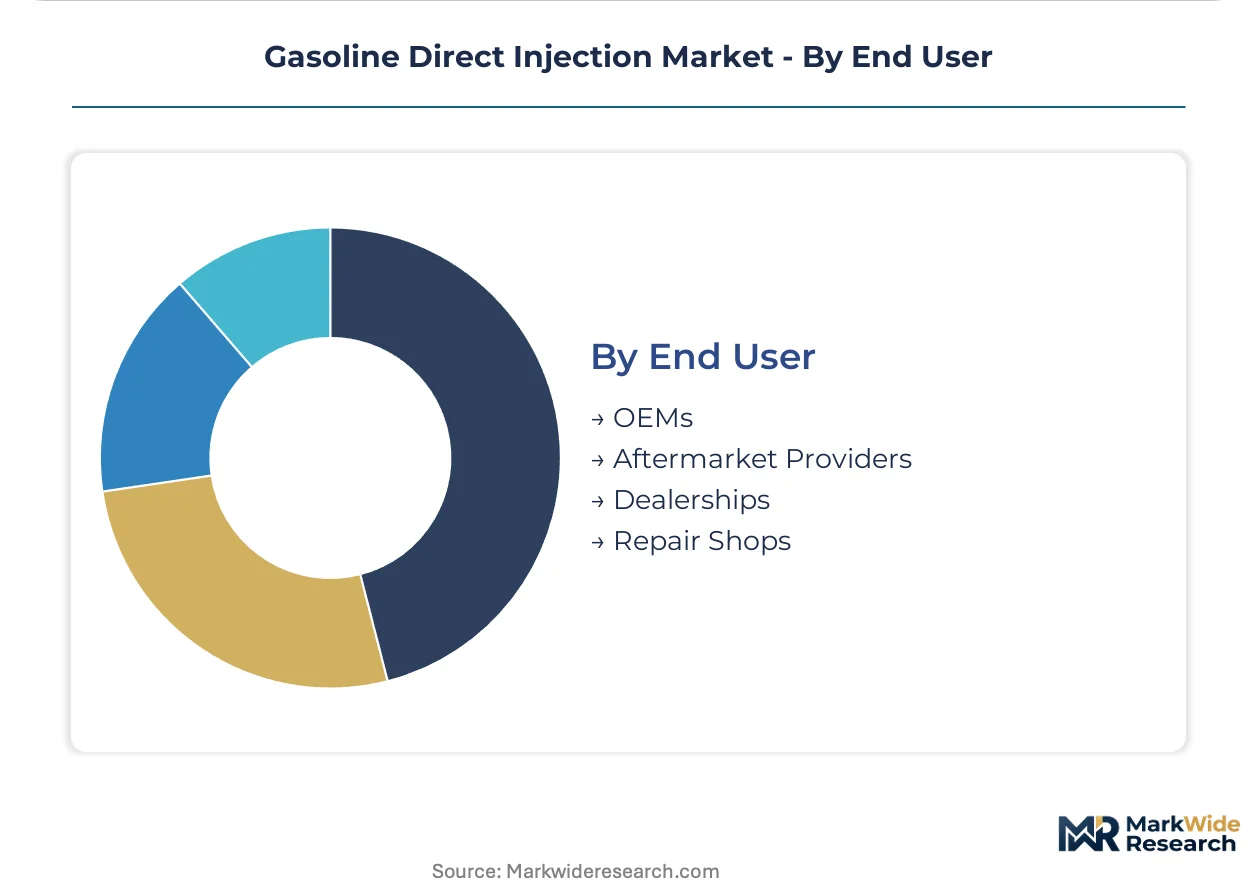
End User:
Channel structure determines who captures calibration value and aftermarket service revenue.
- OEMs:Original equipment manufacturers specify injection systems at the engine family level, treating injection strategies as licensable assets distinct from physical components. EPA and Euro 7 certification binds specific calibrations to engine families, reinforcing modular software architectures.
- Aftermarket Providers:Independent channels develop flash-programming capabilities for injection timing optimization as EPA enforcement of tampering restrictions intensifies.
- Dealerships:Authorized service networks handle warranty repairs and software updates under manufacturer control.
- Repair Shops:General maintenance facilities replace failed injectors and pumps with remanufactured or pattern parts.
OEMs retain the value concentration; aftermarket providers gain share fastest as vehicle parc ages and independent calibration tools proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive special economic zones in Stuttgart, Shanghai, and Nagoya concentrate direct injection manufacturing capacity. These clusters attract tier-one suppliers through tax incentives and proximity to OEM engineering centers. The resulting geographic pattern splits production between European precision-machining heritage and Asian high-volume assembly.
Germany
Bavarian automotive clusters supply high-pressure pumps and piezoelectric injectors to Mercedes-Benz and BMW powertrain divisions. KBA enforces Euro 7 certification timelines that compress hardware validation cycles. Stuttgart-based engineering centers coordinate with Aachen research institutes on 350-bar injection system development.
China
Shanghai and Guangzhou automotive corridors localize electronic control unit production for Stage 6b compliance. MEE-administered particulate number limits drive dual-injection adoption across Geely and BYD engine families. Yangtze River Delta suppliers expand forging capacity for turbocharged four-cylinder platforms.
Japan
Toyota and Honda source precision-machined components through Nagoya-centered supplier networks. METI coordinates cross-industry consortia on lean-burn stratified charge research. Aichi Prefecture machine shops specialize in diamond-like carbon coating for cam lobe durability at 15,000 rpm.
United States
Detroit-area powertrain engineering centers specify injection systems for EPA-certified engine families. NHTSA fuel economy penalties reinforce demand for downsized turbocharged architectures. Michigan-based dynamometer facilities strain under parallel Euro 7 and EPA validation workloads.
India
Maruti Suzuki and Tata Motors expand direct injection penetration in compact segments ahead of BS-VI Phase II deadlines. BIS particulate standards create white space for localized fuel system manufacturing. Chennai and Pune automotive clusters attract pump forging investments from Japanese and German tier-one suppliers.
Gasoline Direct Injection Market Vendor Landscape
German producers anchor one tier; Japanese specialists hold manufacturing scale advantages in Asian automotive corridors. The vendor base concentrates around precision-machining heritage and electronics integration capabilities. Three archetypes dominate: vertically integrated system integrators, component specialists with forging expertise, and semiconductor suppliers embedding control algorithms. Competitive moves center on capacity expansion in Chinese automotive clusters and strategic partnerships for 48V mild-hybrid calibration intellectual property.
Within the integrated-system tier, Robert Bosch GmbH and Denso Corporation occupy positions that span fuel injectors through electronic control modules. Continental AG exemplifies the sensor-fusion archetype, anchoring competitive positioning on pump-control unit architectures. These three entities represent distinct geographic and capability concentrations—German precision engineering, Japanese high-volume manufacturing, and cross-border electronics integration.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Denso Corporation |
| Continental AG |
| Marelli Holdings Co., Ltd. |
| BorgWarner Inc. |
| Magneti Marelli S.p.A. |
| Hitachi Astemo, Ltd. |
| Infineon Technologies AG |
| Stanadyne Holdings |
| Others |
Supply Flow & Price Mechanics
Micro-drilling specialists in Stuttgart and Nagoya command wage premiums that compress margin spreads between economy-grade solenoid injectors and premium piezoelectric architectures. Labor-cost differentials between Bavarian precision-machining centers and Yangtze River Delta assembly corridors stratify pricing tiers across the component portfolio.
Pricing Analysis
Short-lead-time premiums for 350-bar fuel injectors run 15-25% above contract-schedule pricing as Euro 7 validation bottlenecks stretch delivery windows. Contract-based long-term offtake agreements dominate procurement between OEM powertrain divisions and tier-one suppliers, with price differentiation anchored in certification grade and volume scale. Cost compression in economy solenoid tiers is intensifying because Chinese domestic suppliers are expanding forging capacity for high-pressure pumps. Fleet procurement managers at volume passenger vehicle OEMs exhibit highest price sensitivity, while premium German and Japanese manufacturers prioritize injection precision over unit cost.
Supply Chain Analysis
China's Stage 6b domestic-content mandates are reshaping sourcing patterns for electronic control units, compelling foreign tier-one suppliers to localize software calibration centers in Shanghai and Guangzhou. Precision forging capacity for cam lobes and diamond-like carbon coating services concentrates in Germany, Japan, and China. The supply chain draws from rare-earth ceramic feedstocks for piezoelectric actuators and specialized steel alloys for pump housings. Single-source vulnerability clusters with Bavarian and Aichi Prefecture suppliers holding exclusive surface-treatment IP for 15,000-rpm pump operation. Distribution runs through engine-family-specific contracts rather than platform-wide supply agreements, with OEM powertrain divisions unbundling hardware from calibration intellectual property.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gasoline direct injection market is becoming a vertical-integration race as suppliers pursue captive control over piezoelectric ceramic manufacturing to defend margin pools against input cost volatility.
For Market Incumbents: Extend forging capacity in Yangtze River Delta automotive corridors to capture Stage 6b localization incentives while deepening backward integration into rare-earth ceramic supply for piezoelectric actuators. Pressure from Chinese domestic suppliers on pump pricing makes captive sourcing of precision-machined components essential for margin defense. For New Entrants and Emerging Players: Sensor fusion algorithms for pump-control unit integration offer a technology-first wedge into mid-tier OEM procurement portfolios where Continental AG and Robert Bosch GmbH hold entrenched positions. India's BS-VI Phase II transition presents the most penetrable geography, with Maruti Suzuki and Tata Motors expanding direct injection penetration in compact segments lacking established supplier relationships. A calibration-services-first go-to-market angle bypasses capital-intensive hardware manufacturing barriers. For Investors and Strategic Acquirers: Re-rating potential sits with precision-machining specialists possessing diamond-like carbon coating IP given Euro 7's 350-bar pressure requirements and durability constraints. Long-term viability over a five-to-ten-year horizon hinges on electrification-convergence positioning for 48V mild-hybrid architectures. The signal to watch is OEM unbundling velocity—how rapidly powertrain divisions separate hardware procurement from software licensing—as this determines whether component suppliers or calibration IP holders capture expanding value pools.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces variant complexity across Euro 7, Stage 6b, and BS-VI Phase II calibration requirements. |
| Battery Supply Agreement | Secures lithium-ion cell allocation for 48V mild-hybrid powertrain integration with direct injection systems. |
| Software-Defined Vehicle Investment | Enables over-the-air injection timing updates as EPA enforcement of tampering restrictions intensifies. |
| Geographic Manufacturing Footprint | Localizes pump forging and ECU production in Chennai and Pune for India's tightening particulate standards. |
| Charging Infrastructure Partnership | Positions gasoline direct injection as bridge technology during extended hybrid-powertrain transition periods. |
Methodological Framework
SEC filings, automotive production databases, and IHS Markit vehicle registration data formed the secondary backbone of this analysis. Primary interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and dealership operations heads combined with secondary validation through bottom-up and top-down triangulation. The stakeholder span covered fuel system manufacturing, powertrain engineering, and emissions compliance functions across German, Chinese, Japanese, and Indian automotive clusters.
Historical trendline analysis of fuel injector shipments, pump production volumes, and ECU installation rates established baseline growth patterns across the projection horizon. Segmentation modeling incorporated component type, vehicle application, injection technology architecture, and end-user channel structure alongside regional regulatory cluster alignment. CAGRs were derived from regression analysis against emission standard implementation timelines and OEM powertrain electrification roadmaps, with specific weighting for turbocharged dual-injection penetration rates and particulate filter adoption curves.
Several conditions sit outside the modeled scope, including potential regulatory delays to Euro 7 enforcement, breakthroughs in solid-state battery commercialization that accelerate full-electric displacement, and trade policy disruptions affecting rare-earth ceramic supply chains. Forecasts reflect documented assumptions regarding OEM platform lifecycles and supplier contract renewal patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Asia-Pacific Passenger Vehicles Lubricants Market
Automotive Parts
India Automotive Lubricants Market
Automotive Parts
Windshield Washer Fluid Market
Automotive Parts
Europe Automotive Engine Oils Market
Automotive Parts
Automotive Disc Brake Market
Automotive Parts
Iran Automotive Engine Oils Market
Automotive Parts
Argentina Passenger Vehicles Lubricants Market
Automotive Parts
Air Filter Cartridges Market
Automotive Parts
Automotive Bearing Seals Market
Automotive Parts
Accelerator Pedal Module Market
Automotive Parts
Global EV Speed Reducer Market
Automotive Parts
Traffic Control Products Market
Automotive Parts
US Automotive Parts Magnesium Die Casting Market
Automotive Parts
Italy Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Common Rail System Market
Automotive Parts
EV Reduction Gears Market