
 Automotive Crankshaft Market | 2026-2036
Automotive Crankshaft Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Crankshaft Market Analysis
The EU Green Deal's binding CO2 fleet emission targets is broadening the addressable market for lightweight hollow crankshafts across European passenger car platforms. ThyssenKrupp AG leverages its integrated steel-to-forging operations to supply OEM crankshaft programs with captive metallurgical control. Bharat Forge Limited anchors high-volume forged crankshaft exports to commercial vehicle assemblers in Asia-Pacific and Latin America. Maschinenfabrik Alfing Kessler GmbH specializes in precision-machined crankshaft assemblies for premium engine architectures.
An automotive crankshaft is a mechanical component that converts reciprocating piston motion into rotational torque, typically forged from microalloyed steel or nodular cast iron with journal surface hardness exceeding 55 HRC and fillet rolling fatigue resistance above 800 MPa. Solid crankshafts dominate mass-market internal combustion engines where unit cost sensitivity overrides weight reduction priorities, while hollow crankshafts command expanding share in high-performance and hybrid applications seeking rotating mass reduction. The material dimension stratifies around steel forgings for heavy-duty commercial engines, cast iron for economy passenger car displacement classes, and emerging aluminum-composite hybrids for range-extended electric architectures.
EPA emission certification requirements and NHTSA corporate average fuel economy standards in the United States enforce crankshaft durability validation cycles that extend product development timelines and elevate testing infrastructure investment. EMA and REACH compliance in Europe restrict certain alloying element formulations and mandate material traceability through tiered supply chains. China's GB standards and MIIT fuel consumption regulations impose parallel technical barriers for crankshaft suppliers accessing domestic vehicle assembly contracts. Stakeholders must monitor how multi-jurisdiction emission convergence affects forging capacity allocation and alloy specification harmonization across regional production networks.
Market Dynamics
The EU Green Deal's binding CO2 fleet targets are forcing crankshaft suppliers to reengineer rotating mass specifications, compressing development cycles and redistributing forging capacity toward hollow steel architectures.
Growth Catalysts
- Commercial vehicle durability mandates:Brazil and India are scaling orders for forged steel crankshafts as diesel engine load requirements intensify in heavy-duty trucking applications.
- Lightweighting regulatory pressure:The EU Green Deal's fleet emission targets are broadening demand for hollow crankshaft designs across European passenger car platforms.
- Engineering corridor concentration:Demand is clustering in Germany's automotive manufacturing belt around Stuttgart and Munich, anchoring precision machining capacity.
Market Restraints
- Microalloyed steel input volatility:Forging-grade steel pricing fluctuations compress margin buffers for high-volume crankshaft producers dependent on continuous mill supply.
- EMA and REACH compliance friction:European chemical restrictions on alloying element formulations force material reformulation and extend qualification timelines.
- Electric powertrain substitution:Battery-electric architectures eliminate crankshaft demand entirely, threatening long-term volume in passenger car displacement classes below 2.0 liters.
Strategic Opportunities
- Range-extended electric architectures:Aluminum-composite hybrid crankshafts are opening specification windows for compact generator applications in plug-in hybrid platforms.
- MIIT fuel consumption regulations:China's domestic vehicle assembly contracts are creating parallel technical barriers that favor suppliers with dual-certification capability.
- Aftermarket remanufacturing channels:Commercial vehicle fleet operators are adopting reconditioned crankshaft programs to manage total cost of ownership in long-haul operations.
Industry Challenges
- Fillet rolling fatigue expertise scarcity:Precision surface treatment technicians capable of achieving 800+ MPa fatigue resistance are concentrated among German and Japanese forging specialists.
- Multi-jurisdiction certification complexity:EPA, NHTSA, EMA, and GB standard harmonization demands redundant testing infrastructure investment across regional production networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Crankshaft Market |
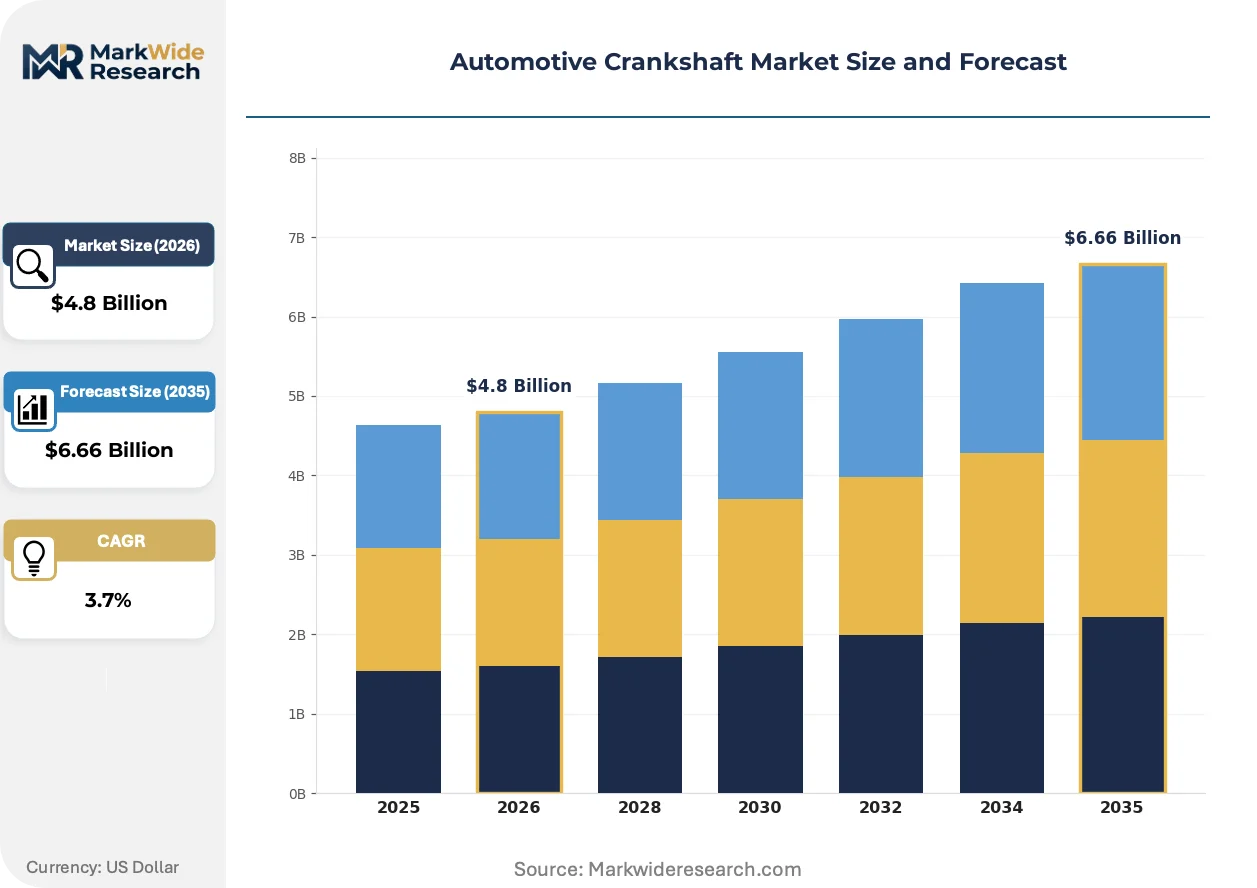
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Crankshaft, Hollow Crankshaft, Counterweighted Crankshaft, Performance Crankshaft Material: Steel, Aluminum, Cast Iron, Composite Manufacturing Process: Forging, Casting, Machining, Heat Treatment End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | MAHLE GmbH, Sandvik AB, ThyssenKrupp AG, Linamar Corporation, NSI Crankshaft Company, Bharat Forge Limited, Maschinenfabrik Alfing Kessler GmbH, Tupy S.A., Rheinmetall AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Crankshaft Market Emerging Trajectories
Crankshaft manufacturing is pivoting toward material-process integration, with hollow forging techniques and surface treatment automation redrawing competitive boundaries between steel and cast iron supply bases.
Hollow steel crankshaft technology is consolidating its position in high-performance and hybrid powertrain applications. Premium European OEMs are adopting these designs for rotating mass reduction in downsized turbocharged engines. The shift is compressing demand for traditional solid forged architectures in displacement segments above 1.5 liters.
REACH chemical restrictions and the EU Green Deal's material traceability mandates are forcing alloy specification transparency through tiered supply chains. European crankshaft suppliers must document alloying element sourcing from steel mill to finished component. This regulatory layering most affects microalloyed steel formulations containing restricted additives, pushing reformulation toward boron-manganese alternatives.
Commercial vehicle procurement is consolidating around durability-validated forging partnerships rather than transactional component sourcing. Fleet operators in Brazil and India are locking in multi-year supply agreements with forged steel specialists capable of extended warranty coverage. This behavioral shift is most visible in heavy-duty diesel engine programs where total cost of ownership calculations override unit price sensitivity.
Automotive Crankshaft Market Segmentation
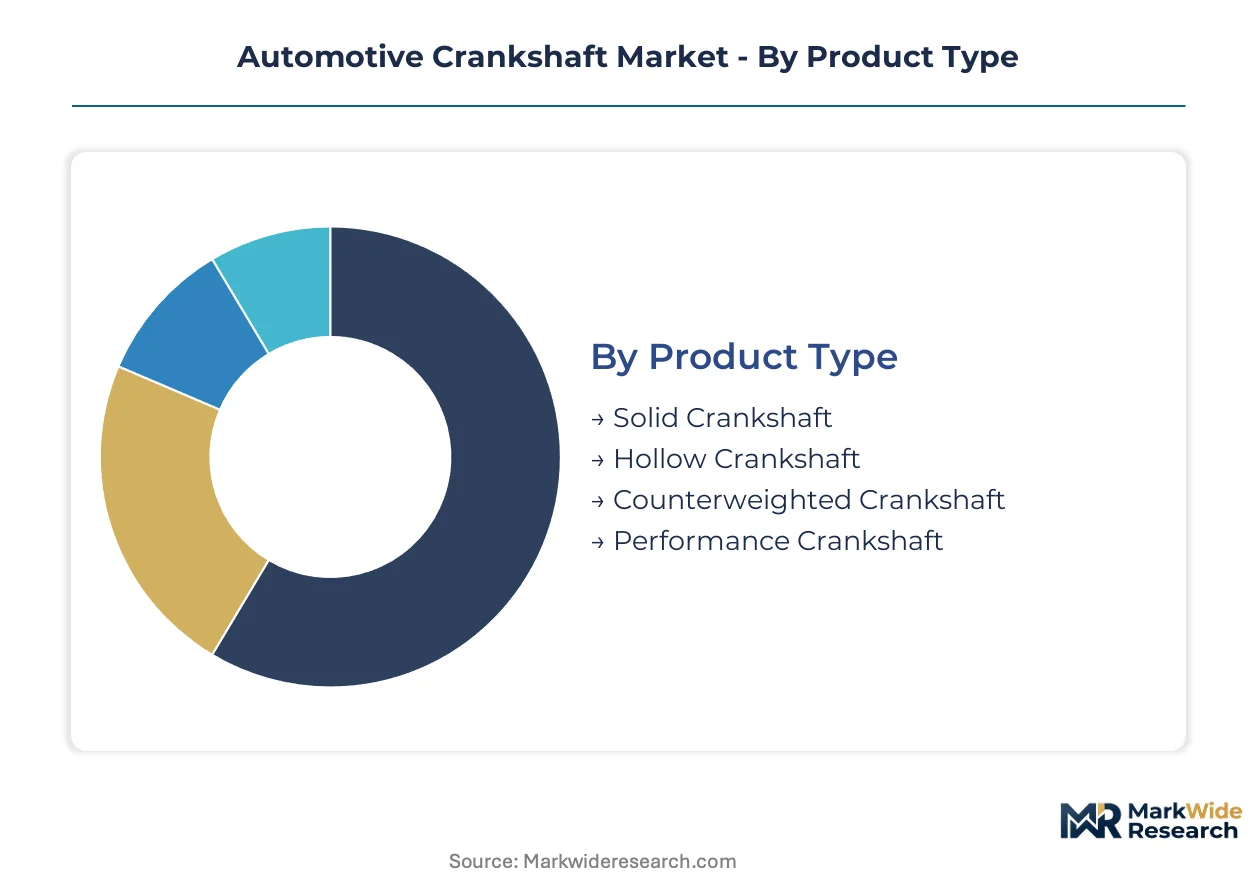
Crankshaft segmentation reflects divergent technical requirements across durability, weight, and cost axes. Material and process choices determine which suppliers capture volume in commercial versus passenger vehicle programs.
Product Type:
Rotating mass specifications differentiate powertrain architectures across displacement classes and duty cycles.
- Solid Crankshaft:Monolithic construction from microalloyed steel or nodular cast iron dominates mass-market internal combustion engines. Demand concentrates in economy passenger car platforms across Brazil and India where unit cost sensitivity overrides weight reduction priorities.
- Hollow Crankshaft:Gun-drilled or mandrel-forged architectures reduce rotating inertia by 15-25 percent versus solid designs. European OEMs in Stuttgart and Munich are adopting these specifications for downsized turbocharged engines under EU Green Deal fleet emission mandates.
- Counterweighted Crankshaft:Integral balance masses reduce harmonic vibration in inline-four and V6 configurations. Found extensively in light commercial vehicle applications.
- Performance Crankshaft:Cross-drilled oil galleries and nitrided bearing surfaces withstand sustained high-RPM operation. Commands premium positioning in motorsport and supercar engine programs.
Mature deployment sits with Solid Crankshaft. Newer deployment is concentrated in Hollow Crankshaft.
Material:
Alloy selection tracks load intensity, thermal exposure, and manufacturing process compatibility across engine architectures.
- Steel:Microalloyed forging grades deliver 800+ MPa fatigue resistance through fillet rolling. Demand clusters in heavy-duty diesel engines for Brazilian and Indian commercial fleets where durability warranties extend beyond 500,000 kilometers.
- Cast Iron:Nodular grades with ferritic-pearlitic matrices offer cost-efficient vibration damping. Dominates displacement classes below 1.6 liters in economy passenger vehicles.
- Aluminum:Hypereutectic alloys with ceramic reinforcement enable 40-50 percent mass reduction. Emerging specification for range-extended electric generator applications.
- Composite:Carbon fiber reinforced polymer hybrids with metallic bearing journals represent experimental architectures for ultra-lightweight powertrains.
Steel commands the steepest expansion trajectory in commercial vehicle procurement. Cast Iron retains volume leadership in entry-level passenger segments.
Manufacturing Process:
Process technology determines surface integrity, dimensional precision, and production economics at scale.
- Forging:Closed-die hammer or press forming aligns grain flow along stress trajectories. ThyssenKrupp AG and Bharat Forge Limited anchor capacity in Germany and India respectively.
- Casting:Green sand or investment casting enables complex counterweight geometries at lower capital intensity. Preferred for cast iron architectures in high-volume passenger car programs.
- Machining:CNC crankshaft grinding and polishing achieve journal roundness tolerances below 2 microns. Maschinenfabrik Alfing Kessler GmbH specializes in precision-machined assemblies.
- Heat Treatment:Induction hardening and nitriding operations establish 55+ HRC surface hardness for bearing journal durability.
Forging retains margin leadership in heavy-duty applications. Machining-intensive finishing is climbing the fastest in premium engine architectures.
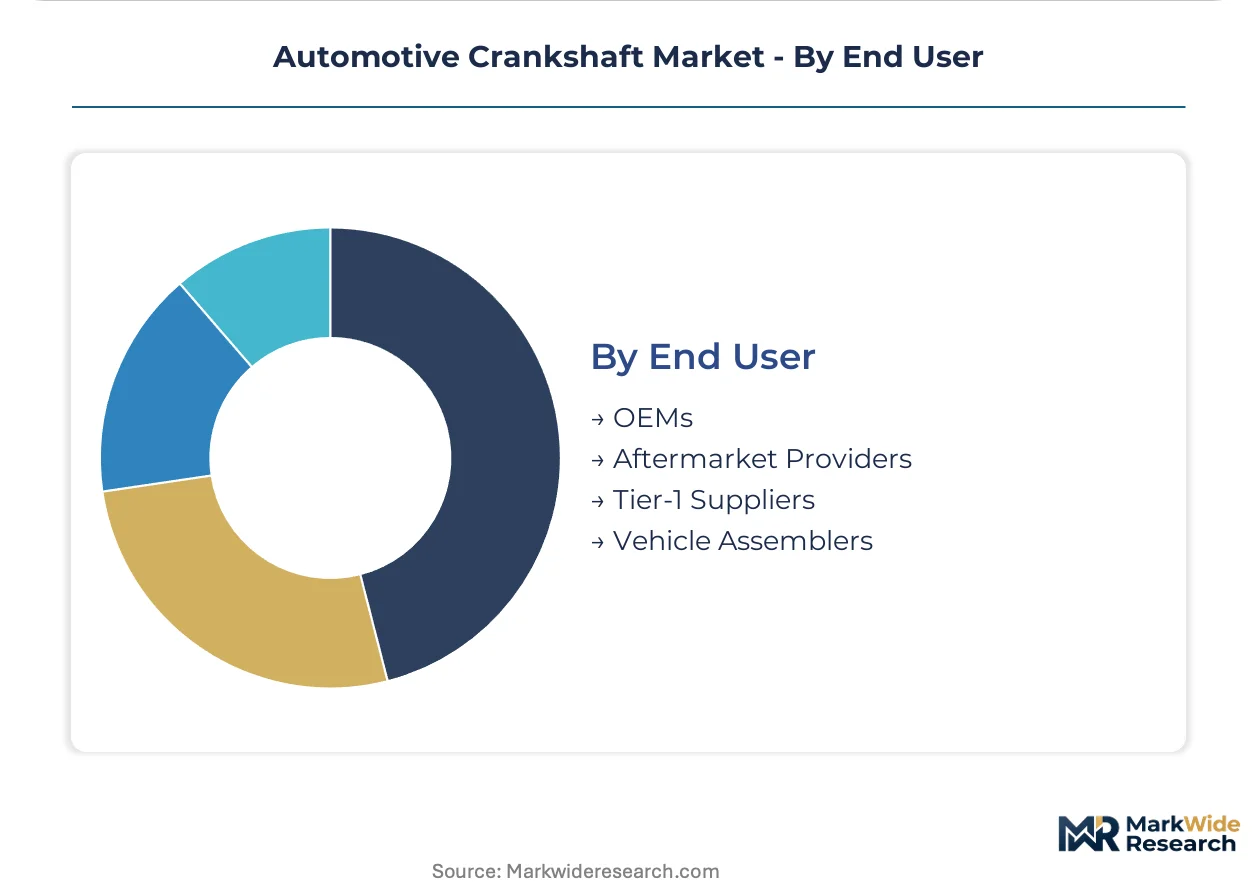
End User:
Procurement behavior diverges between long-term program partnerships and transactional component sourcing.
- OEMs:Volkswagen AG, BMW AG, and Tata Motors Limited specify crankshaft architectures during powertrain development. Multi-year supply agreements lock in forging capacity and metallurgical validation cycles.
- Aftermarket Providers:Independent remanufacturers recondition worn crankshafts through journal welding and regrinding. Fleet operators in long-haul trucking adopt these programs to manage total cost of ownership.
- Tier-1 Suppliers:Continental AG and BorgWarner Inc. integrate crankshaft modules with engine block assemblies for just-in-sequence delivery.
- Vehicle Assemblers:Contract manufacturers without captive forging capacity rely on qualified supplier bases for crankshaft sourcing.
OEMs anchor specification control. Aftermarket Providers are gaining share fastest as commercial fleet age profiles extend.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Crankshaft production concentrates in forging corridors with captive steel supply, while consumption splits between European lightweighting mandates and emerging market commercial vehicle procurement. The geographic divide separates precision-machining hubs from high-volume assembly locations.
Germany
Stuttgart and Munich anchor hollow crankshaft development for downsized turbocharged engines. EU Green Deal fleet emission targets mandate rotating mass reduction across BMW AG and Volkswagen AG powertrain programs. Baden-Württemberg's automotive engineering corridor hosts specialized fillet rolling capacity for 800+ MPa fatigue resistance specifications.
China
Domestic vehicle assembly contracts drive demand for dual-certified forging capacity serving export and local markets. MIIT fuel consumption regulations impose technical barriers that favor suppliers with integrated steel-to-component traceability. Yangtze River Delta clusters concentrate machining-intensive finishing operations for premium engine architectures.
India
Commercial vehicle OEMs in Pune and Chennai scale forged steel orders as diesel engine durability requirements intensify for heavy-duty trucking. Bharat Forge Limited anchors high-volume export capacity to Latin American fleet operators. Tamil Nadu's automotive belt concentrates forging partnerships validated beyond 500,000-kilometer warranty coverage.
Brazil
Long-haul fleet operators lock in multi-year supply agreements with forged steel specialists capable of extended durability validation. ANVISA compliance frameworks run parallel to OEM technical specifications for commercial vehicle crankshaft sourcing. São Paulo state's manufacturing triangle concentrates procurement decisions for Mercosur heavy-duty engine programs.
United States
EPA emission certification and NHTSA corporate average fuel economy standards enforce durability validation cycles that extend product development timelines. Detroit's powertrain engineering corridor concentrates specification control for North American OEM programs. Michigan and Ohio host redundant testing infrastructure serving multi-jurisdiction certification requirements.
Automotive Crankshaft Market Vendor Landscape
The competitive structure tilts toward integrated steel-to-forging operators with captive metallurgical control. Consolidation around durability-validated supply partnerships has compressed transactional component sourcing in commercial vehicle segments. Three archetypes dominate: integrated steel-forging conglomerates with upstream raw material control, high-volume forging specialists serving emerging market commercial fleets, and precision-machining houses targeting premium engine architectures. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers reposition for hollow crankshaft qualification windows.
Among integrated steel-forging conglomerates, ThyssenKrupp AG exemplifies captive metallurgical control from mill to finished component. Bharat Forge Limited occupies a position as a high-volume forging specialist with export orientation toward commercial vehicle assemblers. Maschinenfabrik Alfing Kessler GmbH represents the precision-machining archetype focused on premium engine program specifications.
| Leading Market Players |
|---|
| MAHLE GmbH |
| Sandvik AB |
| ThyssenKrupp AG |
| Linamar Corporation |
| NSI Crankshaft Company |
| Bharat Forge Limited |
| Maschinenfabrik Alfing Kessler GmbH |
| Tupy S.A. |
| Rheinmetall AG |
| Others |
Supply Flow & Price Mechanics
Fillet rolling technicians concentrated in Baden-Württemberg and Nagoya anchor labor-cost differentials that widen pricing spreads between premium fatigue-rated crankshafts and standard-grade commercial vehicle components. This workforce scarcity compresses margins at the precision-forging tier while economy cast iron producers in India and Brazil absorb input volatility through volume scale.
Pricing Analysis
Margin tightening in hollow steel architectures reflects EU Green Deal compliance costs and microalloyed steel input volatility. Contract-based long-term offtake dominates OEM procurement, with price differentiation tracking certification grade and volume scale. Cost-down pressure on solid forged designs accelerates because Brazilian and Indian fleet operators prioritize unit economics over rotating mass reduction. Commercial vehicle assemblers exhibit highest price sensitivity; premium European OEMs demonstrate lowest.
Supply Chain Analysis
Dual-sourcing mandates from Volkswagen AG and BMW AG force qualified supplier rosters spanning Germany, India, and China. Raw material flows draw from forging-grade steel mills, nodular cast iron foundries, and emerging aluminum-ceramic composite feedstock. Single-source vulnerability concentrates in specialized fillet rolling capacity. Distribution runs through Tier 1 engine module integrators for just-in-sequence delivery to assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive crankshaft market occupies a technology-transition phase where hollow steel architectures displace solid forged designs under regulatory pressure for rotating mass reduction.
For Market Incumbents: To counter electric powertrain substitution below 2.0-liter displacement classes, ThyssenKrupp AG and Bharat Forge Limited should deepen backward integration into microalloyed steel supply and expand hollow forging capacity in Germany's engineering corridor. Certification investment for dual GB and EPA compliance creates defensive moats against emerging market entrants. For New Entrants and Emerging Players: Enter via aluminum-composite hybrid crankshafts for range-extended electric generator applications, the most penetrable white-space segment. China's MIIT fuel consumption regulations favor suppliers with integrated traceability systems. A go-to-market angle through aftermarket remanufacturing channels for commercial vehicle fleets bypasses entrenched OEM supply agreements. For Investors and Strategic Acquirers: Re-rating potential sits with precision-machining specialists given hollow crankshaft qualification windows and fillet rolling expertise scarcity. Long-term viability in this market hinges on positioning for hybrid powertrain architectures rather than pure ICE volume exposure. The signal to watch is OEM platform engineering shifts toward 48V mild-hybrid integration rates.| Strategic Initiative | Industry Significance |
|---|---|
| Hollow Forging Capacity Expansion | Captures EU Green Deal-driven demand from Stuttgart and Munich engineering clusters. |
| Backward Integration into Steel Supply | ThyssenKrupp AG's captive metallurgical control insulates against forging-grade input volatility. |
| Dual-Certification Investment | GB and EPA compliance unlocks Chinese domestic contracts and North American OEM programs. |
| Aftermarket Remanufacturing Partnership | Brazilian fleet operators adopt reconditioned crankshafts to manage total cost of ownership. |
| Aluminum-Composite R&D Program | Range-extended electric architectures open specification windows for mass-reduced generator applications. |
Methodological Framework
Independent corroboration across OEM platform engineers, Tier 1 supplier procurement leads, commercial vehicle fleet operators, and aftermarket remanufacturers underwrites the qualitative findings. Primary fieldwork combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC filings of listed forging groups, and customs trade records established demand trajectories. Bottom-up segment sizing and top-down macroeconomic triangulation reconciled volume estimates across the analysis window.
Rate-of-change decomposition across material type, manufacturing process, end-user procurement behavior, and regional regulatory cluster shaped the analytical framework. CAGRs derived from segment-level volume trajectories and value-per-unit assumptions across solid, hollow, and emerging aluminum-composite architectures. Forecast inputs incorporated EPA emission certification timelines, EU Green Deal fleet target phase-ins, and MIIT fuel consumption regulation enforcement patterns without year-specific anchoring.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated battery-electric adoption in passenger car segments below 2.0 liters. Deviation in commercial vehicle diesel engine durability mandates or REACH chemical restriction scope expansions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Power Distribution Block Market
Powertrain
Timing Belt Market
Powertrain
Global Automotive Engine and Engine Mounts Market
Powertrain
Automotive PTC Heaters Market
Powertrain
Continuously Variable Transmission (CVT) Market
Powertrain
Automatic Transmission Solenoid Pack Market
Powertrain
Global Automotive Dyno Market
Powertrain
Global Hydrogen Combustion Engine Market
Powertrain
United Kingdom Automotive Engine Oils Market
Powertrain
North America Electro Hydraulic Power Steering Market
Powertrain
Positive Crankcase Ventilation Valve Market
Powertrain
Automotive Cylinder Block Market
Powertrain
Fuel Pumps Market
Powertrain
Brazil Automotive Market
Powertrain
Transmission Mounting Brackets Market
Powertrain
Asia-Pacific Automotive Engine Oils Market