
 Automatic Transmission Solenoid Pack Market | 2026-2036
Automatic Transmission Solenoid Pack Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Transmission Solenoid Pack Market Insights
Mexico is rewriting assembly capacity patterns across North American transmission supply chains. BorgWarner leverages its valve body integration expertise to anchor regional sourcing for Detroit-based OEM programs. Denso sustains manufacturing scale advantages through dedicated electromechanical solenoid lines in Guanajuato. Continental competes on electrohydraulic module precision for premium passenger vehicle platforms.
An automatic transmission solenoid pack comprises multiple electromagnetic actuators mounted within or adjacent to the valve body, typically operating at 12V with response times under 15 milliseconds to direct hydraulic fluid flow for gear engagement. These packs govern shift quality, torque converter lockup timing, and line pressure modulation in step-ratio and dual-clutch automatic transmissions. Valve body solenoids occupy the mature volume core where margin pools have compressed amid standardized specifications. Digital control architectures represent the fastest-expanding technology segment as OEMs pursue software-defined shift calibration over hardware-intensive hydraulic circuits. Electrohydraulic systems still dominate commercial vehicle applications where duty cycles demand proven durability.
The US EPA and NHTSA coordinate Corporate Average Fuel Economy standards that directly tighten permissible shift efficiency losses, compelling OEMs to specify higher-precision solenoid packs. China's MIIT enforces dual carbon goals that accelerate electrified transmission adoption, reshaping solenoid demand toward hybrid-optimized proportional control designs. ISO 26262 functional safety requirements now penetrate transmission control module procurement, raising qualification barriers for solenoid pack suppliers. Stakeholders must decide whether to absorb escalating validation costs or cede share to vertically integrated transmission builders.
Market Dynamics
Electronic shift control architectures are compressing hardware margins while elevating software-defined calibration as the primary value layer in transmission control systems. This structural pivot rewards suppliers with embedded control expertise and penalizes pure-play hydraulic component manufacturers.
Growth Catalysts
- Corporate Average Fuel Economy standards:The US EPA and NHTSA mandate tighter shift efficiency tolerances. OEMs specify higher-precision solenoid packs to minimize hydraulic losses during gear changes.
- Hybrid-optimized proportional control:China's MIIT dual carbon goals accelerate electrified transmission adoption. Proportional solenoid designs enable seamless engine-motor torque blending in PHEV architectures.
- Localized assembly expansion:Mexico's concentrated auto manufacturing growth creates anchor demand for regional solenoid supply. Guanajuato and Aguascalientes clusters pull dedicated production lines from multinational suppliers.
Market Restraints
- Copper and rare-earth magnet volatility:Solenoid coil winding costs fluctuate with commodity markets. Smaller manufacturers lack hedging capacity to absorb input price swings.
- ISO 26262 functional safety barriers:ASIL-D qualification requirements for transmission control modules extend validation timelines. Tier-2 suppliers face capital barriers to independent certification.
- Electromechanical actuator substitution:Dual-clutch transmission builders integrate motor-driven shift forks. Hydraulic solenoid packs face displacement in performance-oriented passenger segments.
Strategic Opportunities
- India's PLI scheme for automotive components:Domestic value-add mandates create openings for solenoid pack localization. Tamil Nadu and Gujarat assembly corridors offer scale anchoring for new entrants.
- Software-defined shift calibration:Over-the-air update capability enables recurring revenue from shift map optimization. Cloud-connected solenoid diagnostics transform hardware into service platforms.
- Commercial vehicle electrohydraulic durability:Heavy-duty duty cycles resist full electrification. Proven solenoid designs command premium positioning in truck and bus applications.
Industry Challenges
- Embedded software talent scarcity:Shift control algorithm development requires mechatronics expertise spanning hydraulics and real-time computing. Suppliers compete with automotive OEMs for limited firmware engineering pools.
- Legacy transmission integration complexity:Retrofitting digital solenoid packs into existing valve body architectures demands custom adapter engineering. Aftermarket channels struggle with fitment standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Transmission Solenoid Pack Market |
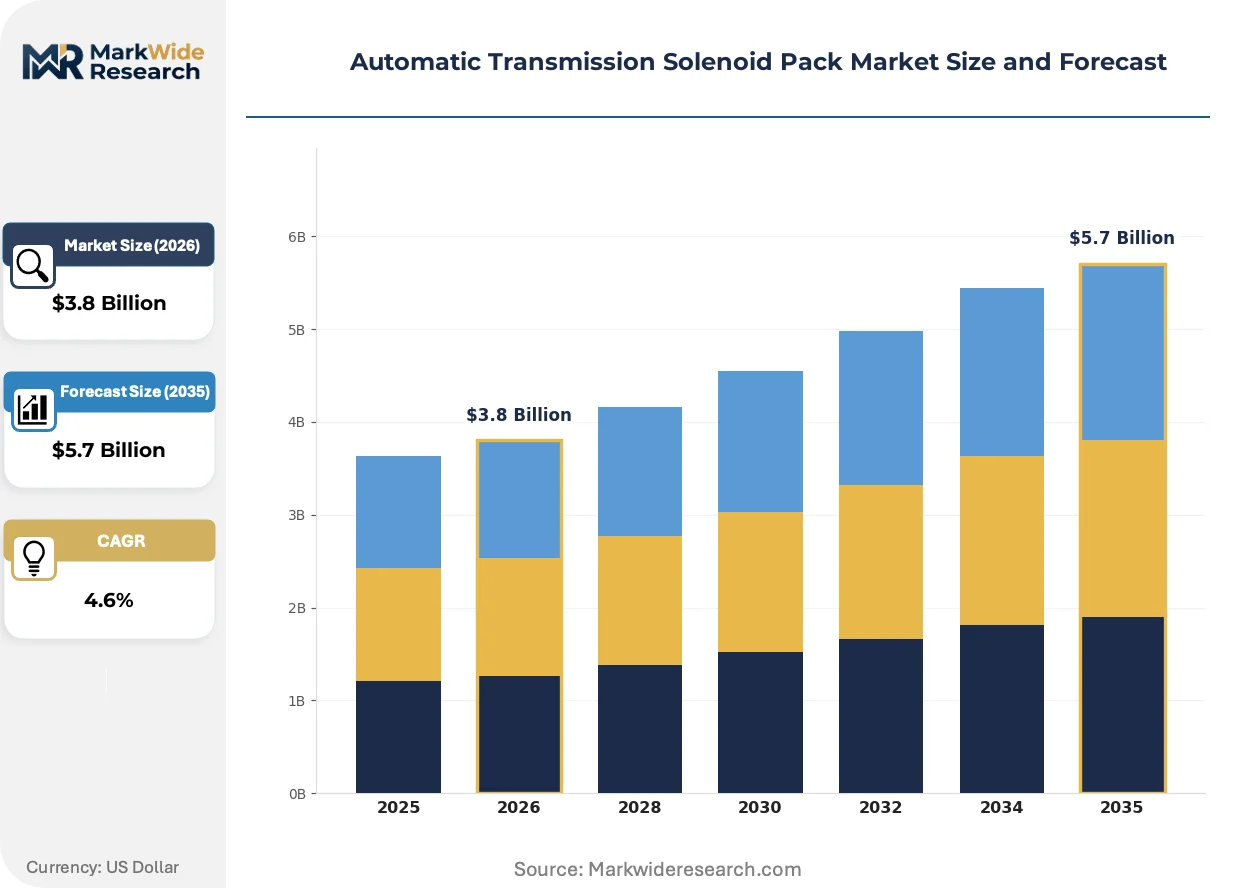
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Valve Body Solenoid, Pressure Control Solenoid, Shift Solenoid, Torque Converter Clutch Solenoid, Others Technology: Electromechanical, Electrohydraulic, Piezoelectric, Proportional Control, Digital Control Application: Passenger Vehicles, Commercial Vehicles, Heavy Duty Machinery, Off-Highway Equipment, Construction Equipment End User Industry: OEMs, Aftermarket Suppliers, Fleet Operators, Vehicle Refurbishment Shops, Repair Services |
| Companies Covered | BorgWarner, Robert Bosch, Continental, Denso, Hitachi Astemo, Aisin, Schaeffler, Magna International, Nidec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Transmission Solenoid Pack Market Trends and Innovations
Digital control architectures are displacing hardware-intensive hydraulic circuits as the primary mechanism for transmission precision. This shift elevates software competence above manufacturing scale in supplier selection criteria.
Proportional solenoid technology with pulse-width modulated current control is digitizing shift quality management. Passenger vehicle OEMs in Germany and Japan adopt these designs for seamless torque transfer. The technology is digitizing calibration workflows, compressing development cycles from months to weeks through virtual valve body simulation.
The EU F-Gas Regulation and REACH substance restrictions are tightening permissible hydraulic fluid formulations. Biodegradable transmission oils with modified viscosity profiles demand solenoid material compatibility updates. European premium passenger platforms face the steepest reformulation timelines, accelerating supplier R&D coordination with fluid compounders.
Direct OEM procurement of solenoid packs is consolidating tier-1 valve body integration roles. Tier-2 electromechanical specialists now contract directly with transmission builders for module subassemblies. This pattern concentrates most visibly in China's Yangtze River Delta, where SAIC and Geely transmission affiliates source solenoid packs independently from legacy system suppliers.
Automatic Transmission Solenoid Pack Market Segmentation
Segmentation in the automatic transmission solenoid pack market reveals distinct performance requirements across hydraulic control architectures. Product type and technology choices determine precision specifications, while application scope dictates durability standards and procurement volumes.
Product Type:
Each solenoid variant addresses specific hydraulic circuit functions within transmission valve bodies, from line pressure modulation to torque transfer timing.
- Valve Body Solenoid:These electromagnetic actuators direct clutch pack engagement through precise hydraulic routing. Passenger vehicle OEMs in Germany and Japan specify sub-15 millisecond response times for seamless shift quality. Established volume favors this segment; emerging adoption favors torque converter clutch solenoids in hybrid powertrains.
- Pressure Control Solenoid:Proportional designs modulate line pressure continuously rather than binary on-off operation. China's MIIT fuel efficiency mandates accelerate demand for pressure modulation precision in dual-clutch transmissions. Commercial vehicle builders specify hardened variants for 500,000+ kilometer duty cycles.
- Shift Solenoid:Binary actuators govern gear selection sequencing in conventional step-ratio automatics.
- Torque Converter Clutch Solenoid:Lockup timing control reduces parasitic losses during highway cruise conditions.
- Others:Auxiliary solenoids manage transmission fluid cooling circuits and auxiliary pump engagement.
Cost tier stratification separates commodity valve body solenoids from precision pressure control variants.
Technology:
Actuation mechanisms span mature electromechanical designs through emerging digital architectures with embedded control intelligence.
- Electromechanical:Conventional 12V electromagnetic coils with spring-return plungers dominate aftermarket replacement volumes. India's PLI scheme for automotive components attracts electromechanical production to Tamil Nadu assembly corridors. Mature margin compression characterizes this technology tier.
- Electrohydraulic:Integrated valve-solenoid modules combine hydraulic amplification with electronic control for commercial vehicle durability requirements. Heavy-duty truck OEMs specify electrohydraulic packs for 1.2 million kilometer service intervals. European REACH substance restrictions drive fluid compatibility updates in this segment.
- Piezoelectric:Ultra-fast response actuators enable sub-5 millisecond shift events in performance dual-clutch applications.
- Proportional Control:Pulse-width modulated current enables infinite valve positioning between fully open and closed states.
- Digital Control:Embedded microcontrollers enable software-defined calibration with over-the-air update capability.
Application maturity favors electrohydraulic durability; technology transition favors digital control architectures.
Application:
Duty cycle severity and shift frequency requirements create divergent specification thresholds across vehicle categories.
- Passenger Vehicles:Light-duty shift schedules prioritize NVH refinement and fuel efficiency over absolute durability. Japanese OEMs specify multi-solenoid packs with integrated temperature compensation for CVT and multi-speed automatic applications. ISO 26262 ASIL-D requirements penetrate premium platform procurement.
- Commercial Vehicles:Severe-duty cycles with frequent grade shifts demand hardened coil insulation and corrosion-resistant plunger materials. US EPA and NHTSA coordinated standards tighten shift efficiency tolerances for Class 8 truck powertrains. Fleet operators specify predictive maintenance integration through solenoid current signature monitoring.
- Heavy Duty Machinery:Mining and agricultural equipment subjects solenoids to contamination and temperature extremes.
- Off-Highway Equipment:Construction and forestry machinery requires sealed environmental protection ratings.
- Construction Equipment:Articulated haulers and wheel loaders specify high-flow solenoid capacities for powershift transmissions.
Volume concentration favors passenger vehicle platforms; specification intensity favors commercial vehicle applications.
End User Industry:
Procurement patterns diverge between integrated transmission builders and distributed aftermarket channels.
- OEMs:Direct solenoid pack procurement from tier-2 electromechanical specialists bypasses traditional valve body integrators. China's Yangtze River Delta transmission affiliates source solenoid packs independently for hybrid-optimized proportional control designs. Long-term supply agreements coordinate R&D roadmaps with fluid compounders.
- Aftermarket Suppliers:Replacement volume concentrates on electromechanical valve body and shift solenoids with standardized pin configurations. Mexico's Guanajuato cluster anchors regional distribution for North American service channels. Cross-reference proliferation challenges fitment standardization across transmission generations.
- Fleet Operators:Large-scale procurement with predictive maintenance integration and total cost of ownership modeling.
- Vehicle Refurbishment Shops:Remanufacturing demand for legacy transmission platforms with obsolete solenoid specifications.
- Repair Services:Diagnostic-driven component replacement with real-time inventory sourcing through distributor networks.
Supply chain proximity favors OEM direct procurement; margin retention favors aftermarket channel consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Valve body integrators cluster around Detroit, Stuttgart, and Nagoya to anchor OEM transmission programs. Tier-2 electromechanical specialists concentrate in Guanajuato and the Yangtze River Delta to capture localized assembly demand.
United States
Detroit-based OEM programs drive specification intensity for sub-15 millisecond response solenoids. The EPA and NHTSA coordinate Corporate Average Fuel Economy standards that tighten shift efficiency tolerances for passenger and commercial vehicle powertrains. Michigan and Ohio transmission corridors anchor BorgWarner valve body integration capacity.
China
SAIC and Geely transmission affiliates source solenoid packs independently for hybrid-optimized proportional control designs. MIIT enforces dual carbon goals that accelerate electrified transmission adoption. The Yangtze River Delta manufacturing belt concentrates demand through Shanghai and Hangzhou assembly clusters.
Germany
Premium passenger vehicle OEMs specify multi-solenoid packs with integrated temperature compensation for CVT applications. The EU F-Gas Regulation and REACH substance restrictions tighten permissible hydraulic fluid formulations. Stuttgart and Munich anchor Continental electrohydraulic module precision for luxury platforms.
Mexico
Guanajuato and Aguascalientes clusters pull dedicated production lines from multinational suppliers to serve North American OEM programs. Localized auto assembly expansion concentrates regional solenoid demand. Denso sustains manufacturing scale advantages through dedicated electromechanical lines in Guanajuato.
Japan
Japanese OEMs specify multi-solenoid packs with integrated temperature compensation for CVT and multi-speed automatic applications. METI industrial policy supports precision component manufacturing for export-oriented transmission programs. Aichi Prefecture around Nagoya anchors Aisin and Denso production corridors.
Automatic Transmission Solenoid Pack Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream as tier-2 electromechanical suppliers. The market exhibits tiered concentration with valve body integrators consolidating around Detroit, Stuttgart, and Nagoya while tier-2 specialists fragment across regional manufacturing clusters. Two strategic archetypes dominate: vertically integrated transmission builders with captive solenoid supply, and independent electromechanical specialists competing on qualification speed. M&A activity targets embedded software competence; capacity expansion concentrates in Guanajuato and the Yangtze River Delta.
Within the tier-2 specialist tier, BorgWarner and Denso occupy positions as scale anchors for regional OEM programs, while Continental exemplifies precision-focused positioning for premium passenger platforms. These three represent divergent geographic anchoring strategies—BorgWarner around Detroit-based programs, Denso through Guanajuato manufacturing scale, and Continental via Stuttgart-centered electrohydraulic module supply. Their collective presence illustrates how qualification barriers and embedded software requirements stratify competitive position.
| Leading Market Players |
|---|
| BorgWarner |
| Robert Bosch |
| Continental |
| Denso |
| Hitachi Astemo |
| Aisin |
| Schaeffler |
| Magna International |
| Nidec |
| Others |
Pricing and Supply Chain Analysis
Guanajuato's electromechanical production corridors anchor North American solenoid supply capacity, concentrating manufacturing scale among three multinational suppliers and compressing margin pools for tier-2 specialists lacking equivalent localization. This geographic clustering amplifies pricing power for integrated valve body providers while forcing independent component vendors toward certification-heavy differentiation strategies.
Pricing Analysis
EPA and NHTSA coordinated Corporate Average Fuel Economy standards dictate the pricing tier structure across the automatic transmission solenoid pack market, separating ASIL-D qualified precision designs from commodity electromechanical replacements. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 26262 certification grade and response time specifications. Cost compression in the standard tier is intensifying because passenger vehicle OEMs consolidate direct procurement with embedded software capability. Aftermarket distributors exhibit highest price sensitivity; premium OEM platforms demonstrate lowest sensitivity due to shift quality warranty exposure.
Supply Chain Analysis
Copper winding feedstock and rare-earth magnet materials draw from Chilean mining operations, Chinese rare-earth processing facilities, and Indonesian nickel supply chains before reaching coil manufacturing stages. Finished solenoid pack assembly concentrates in Mexico, China, and Japan, with valve body integration clustering in Germany and the United States. Single-source vulnerability around neodymium magnet supply creates structural exposure for proportional control solenoid producers. Distribution runs through tier-1 transmission system integrators and direct OEM procurement channels, with aftermarket service parts flowing through regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across hybrid-optimized proportional control designs and software-defined calibration architectures creates specialist opportunities outside consolidated valve body integration. Electrified transmission adoption splits demand between legacy hydraulic precision and embedded control intelligence, opening niches for qualified entrants.
For Market Incumbents: Pre-empt displacement from motor-driven shift fork substitution by deepening backward integration into rare-earth magnet supply and accelerating ASIL-D certification coverage for digital control architectures. Denso's Guanajuato scale model offers a template for regional capacity anchoring that locks in Detroit-based OEM programs. Electromechanical actuator substitution in dual-clutch segments demands defensive software competence acquisition.
For New Entrants and Emerging Players: Establish a beachhead in India's Tamil Nadu assembly corridor under PLI scheme domestic value-add mandates, where localized solenoid pack production faces limited incumbent saturation. Commercial vehicle electrohydraulic durability specifications offer the most penetrable segment given heavy-duty duty cycle resistance to full electrification. Cloud-connected diagnostic platforms provide a service-based go-to-market angle that transforms hardware margins into recurring revenue.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because tier-2 electromechanical specialists face capital barriers to independent ISO 26262 certification while OEM direct procurement patterns bypass traditional valve body integrators. Acquisition targets with embedded microcontroller competence and over-the-air calibration capability command strategic premium. Watch for inflection in China's MIIT enforcement intensity around dual carbon goals, which accelerates hybrid-optimized proportional control demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Software Talent Acquisition | Mechatronics expertise spanning hydraulics and real-time computing commands supplier selection priority from Detroit-based OEMs. |
| Regional Manufacturing Footprint Expansion | Guanajuato and Yangtze River Delta localization captures anchor demand from concentrated auto assembly clusters. |
| ASIL-D Certification Investment | Functional safety qualification penetrates transmission control module procurement, raising barriers for unqualified competitors. |
| Over-the-Air Calibration Platform | Software-defined shift maps enable recurring revenue from cloud-connected solenoid diagnostics and optimization services. |
| Rare-Earth Magnet Supply Agreement | Long-term offtake contracts with Chinese and Australian processors hedge commodity volatility for proportional solenoid production. |
Research Methodology
A spread of perspectives from OEM platform engineers, tier-1 valve body procurement managers, aftermarket distributor operations heads, and electromechanical component R&D directors converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against EPA regulatory filings, NHTSA CAFE standard documentation, MIIT policy circulars, vehicle production databases, and SEC supplier disclosures. Bottom-up segment sizing triangulated against top-down OEM transmission program volumes.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling solenoid pack demand by propulsion architecture, vehicle class, content per transmission, and regional production cluster. CAGRs derived from segment-level growth trajectory synthesis, with hybrid adoption curves and software-defined vehicle penetration serving as primary automotive-specific forecast inputs.
Sensitivities concentrate around MIIT enforcement intensity, rare-earth magnet supply disruptions, and dual-clutch transmission builder integration decisions. Forecasts reflect documented assumptions regarding electrified transmission adoption pace and ISO 26262 qualification timeline compression. Cross-checking against IHS Markit powertrain production forecasts and supplier order book disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Powertrain Market
Powertrain
Automotive Paddle Shifter Market
Powertrain
Truck Auxiliary Power Units Market
Powertrain
Automotive Fuel Pressure Regulator Market
Powertrain
Electric Two-Wheeler Powertrain and Range Validation Test Systems Market
Powertrain
Automotive Oil Sump Market
Powertrain
EV Powertrain Market
Powertrain
Automotive Variable Discharge Oil Pump Market
Powertrain
Timing Belt Kits Market
Powertrain
Automotive Fuel Injector Market
Powertrain
Natural Gas Engines Market
Powertrain
Automotive Balance Shaft Market
Powertrain
Automotive Engine Degreasers Market
Powertrain
Steering Damper Market
Powertrain
Internal Combustion Engine Market
Powertrain
Global Automotive Damper Pulley Market