
 South America Internal Combustion Engines Market | 2026-2036
South America Internal Combustion Engines Market Size, Share, and Industry Trends Forecast 2026-2036
South America Internal Combustion Engines Market Insights
The South America internal combustion engines market is rebalancing between premium turbocharged direct-injection systems and commodity naturally aspirated gasoline units as fleet operators and OEMs split procurement strategies. Toyota Motor Corporation leverages its hybrid engine portfolio to anchor position in Brazilian passenger vehicle assembly. Volkswagen Group competes through localized diesel production serving Argentina's commercial vehicle sector. Stellantis dominates the aftermarket channel with powertrain remanufacturing operations across Mercosur manufacturing zones.
An internal combustion engine converts chemical energy from fuel combustion into mechanical work through reciprocating piston motion within cylinders, typically operating at compression ratios between 9:1 for gasoline and 16:1 for diesel variants, with power outputs spanning from sub-50 kW motorcycle units to 500+ kW heavy-duty truck engines. Diesel engines lead in commercial vehicle and generator applications across the Andean region due to torque density and fuel availability, while hybrid engines represent the fastest-growing product category as Brazilian OEMs integrate mild-hybrid architectures to meet PROCONVE emission thresholds. Turbocharged technology commands the strongest margin pool in the technology dimension, though naturally aspirated systems retain volume dominance in entry-level passenger vehicles and small motorcycles.
Brazil's PROCONVE standards, administered by the country's national environmental regulator, mandate escalating nitrogen oxide and particulate matter reductions that force engine recalibration and after-treatment investments. Argentina's IRAM certification framework and Chile's Ministry of Transport emission protocols create a fragmented compliance landscape where multi-country suppliers must maintain parallel homologation processes. Stakeholders must monitor the divergence between Brazilian biofuel blending mandates and Argentine natural gas engine incentives when allocating R&D resources across Mercosur production networks.
Market Dynamics
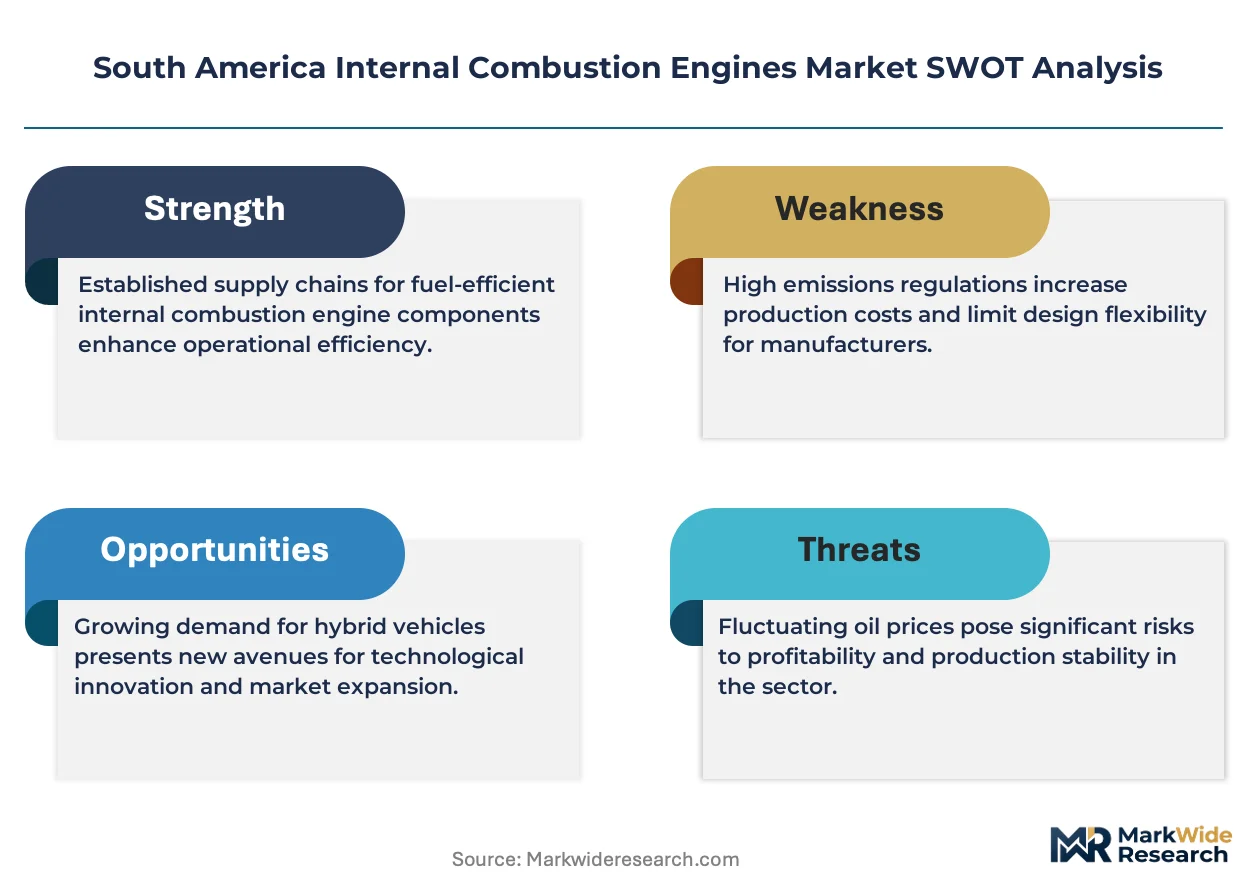
Brazil's PROCONVE emission tier progression and Argentina's IRAM particulate standards are forcing simultaneous engine recalibration and after-treatment investments across Mercosur manufacturing corridors, compressing supplier margins while accelerating turbocharger adoption.
Growth Catalysts
- PROCONVE L7/L8 tiers:Brazil's national environmental regulator mandates nitrogen oxide reductions that require common-rail fuel injection upgrades across commercial vehicle fleets.
- Biofuel blending infrastructure:Sugarcane ethanol distribution networks in São Paulo state sustain flex-fuel engine demand for passenger vehicle OEMs.
- Andean mining expansion:Chilean and Peruvian copper extraction operations drive generator-set diesel engine procurement for remote power applications.
Market Restraints
- Common-rail component concentration:Precision fuel injection hardware supply concentrates among German and Japanese tier-one suppliers, exposing assemblers to currency volatility.
- Natural gas substitution:Argentine government incentives for compressed natural gas vehicle conversions divert fleet investment from diesel powertrains in Córdoba and Buenos Aires provinces.
- Homologation fragmentation:Parallel IRAM, PROCONVE, and Chilean Ministry of Transport certification processes multiply compliance costs for multi-country suppliers.
Strategic Opportunities
- Paraguay and Uruguay fleet renewal:Underpenetrated commercial vehicle markets in Asunción and Montevideo corridors offer first-mover positioning for Euro V-compliant engine platforms.
- Mild-hybrid architecture convergence:Integration of 48V belt-integrated starter-generators with downsized gasoline engines addresses PROCONVE urban emission testing cycles.
- Remanufacturing channel development:Mercosur trade bloc rules of origin create favorable conditions for powertrain rebuild operations serving Brazilian aftermarket demand.
Industry Challenges
- After-treatment calibration expertise:Selective catalytic reduction and diesel particulate filter tuning require scarce combustion engineering talent concentrated in São Paulo and Córdoba industrial zones.
- Legacy fleet interoperability:New emission-compliant engines must interface with existing vehicle electronic architectures without full platform redesign, constraining thermal management optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Internal Combustion Engines Market |
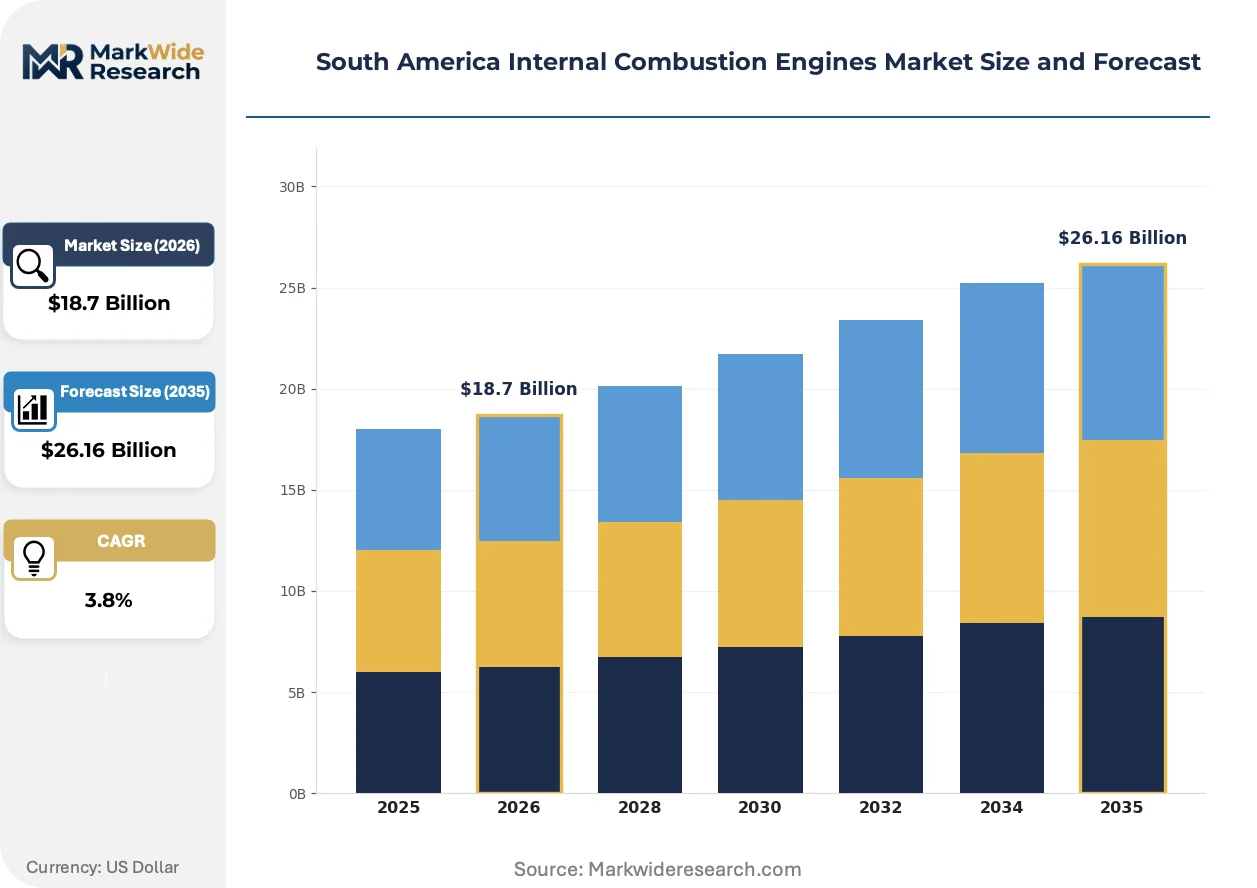
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline Engines, Diesel Engines, Hybrid Engines, Alternative Fuel Engines End User: Automotive OEMs, Aftermarket Providers, Industrial Applications, Marine Applications Technology: Turbocharged, Naturally Aspirated, Direct Injection, Variable Valve Timing Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Generators |
| Companies Covered | Toyota Motor Corporation, Volkswagen Group, Renault Group, General Motors, Ford Motor Company, MAN SE, Stellantis, Volvo AB, Cummins, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Internal Combustion Engines Market Trends and Innovations
Turbocharger technology is penetrating segments previously dominated by naturally aspirated architectures, while regulatory testing protocols and procurement patterns undergo parallel transformation across the continent's automotive corridors.
Variable geometry turbochargers are integrating with exhaust gas recirculation loops to meet PROCONVE transient emission test requirements. Brazilian commercial vehicle assemblers in São Paulo state deploy these systems across medium-duty truck platforms. The technology is integrating previously separate engine and after-treatment control domains into unified thermal management strategies.
Argentina's IRAM certification framework now mandates onboard diagnostic verification for particulate matter accumulation, extending beyond Brazilian PROCONVE scope. Engine suppliers must maintain dual calibration databases for cross-border vehicle registrations. The regulation most affects generator-set manufacturers serving Patagonian remote installations where service intervals stretch warranty compliance.
Fleet operators in Brazil's agricultural belt now unbundle engine procurement from complete vehicle purchases, sourcing powertrains directly for self-propelled harvester retrofits. This channel disintermediation compresses traditional OEM distribution margins. The pattern is most visible in Mato Grosso soybean operations where equipment utilization rates justify independent engine sourcing.
South America Internal Combustion Engines Market Segmentation
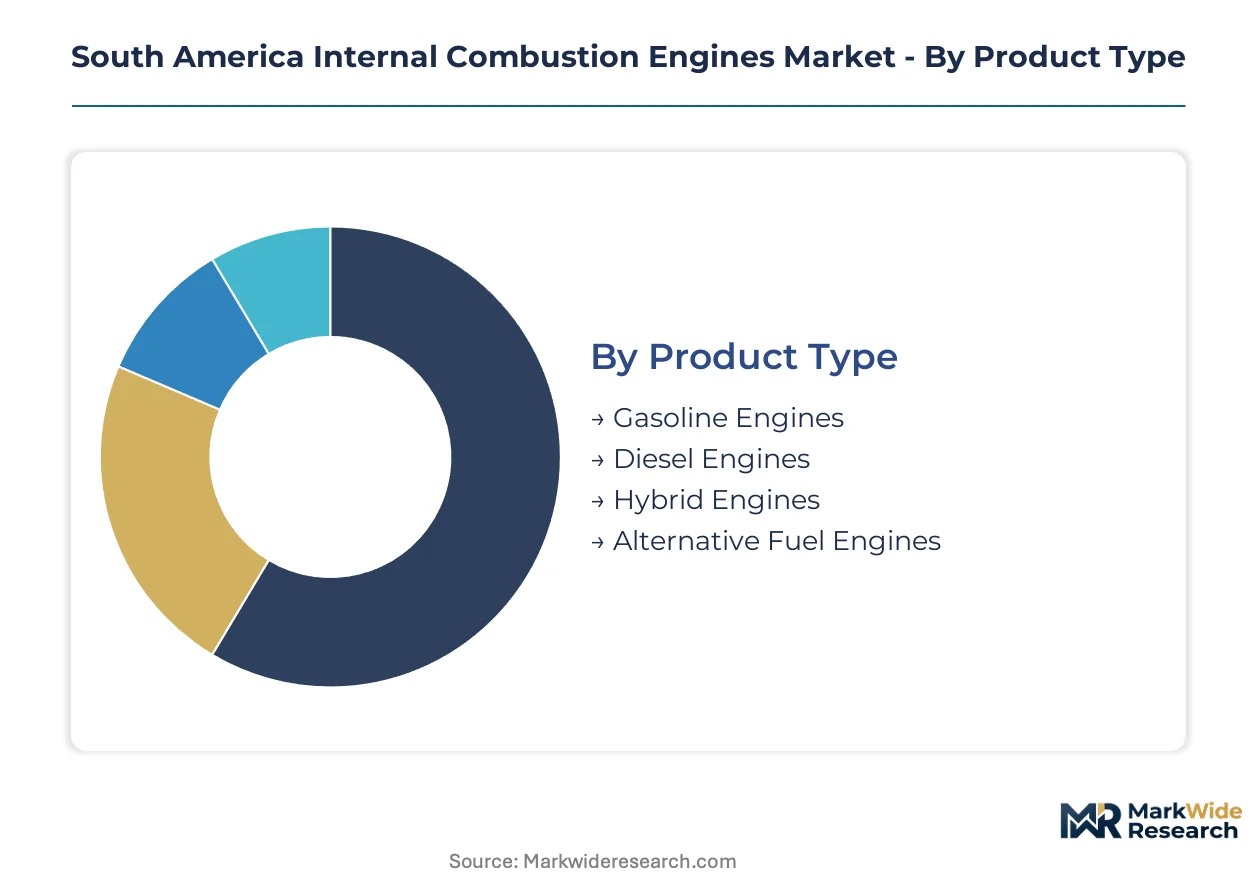
Engine procurement patterns across South America diverge sharply between premium turbocharged architectures for commercial fleets and cost-optimized naturally aspirated units for entry-level passenger vehicles. Understanding these segment boundaries reveals where supplier margins concentrate versus where volume flows.
Product Type:
Supply concentration for high-pressure fuel systems and after-treatment hardware tilts competitive advantage toward segments requiring precision engineering over commodity manufacturing.
- Gasoline Engines:Flex-fuel configurations dominate Brazilian passenger vehicle assembly, with ethanol-compatible cylinder heads and hardened valve seats engineered for São Paulo state's sugarcane ethanol distribution infrastructure. São Paulo industrial corridor OEMs source these powertrains for compact car platforms where PROCONVE emission tiers drive multi-fuel calibration complexity.
- Diesel Engines:Common-rail direct injection architectures with variable geometry turbochargers serve Argentina's Córdoba commercial vehicle cluster and Andean mining generator applications. Torque density requirements for copper extraction operations in Chilean and Peruvian high-altitude sites sustain demand for 500+ kW heavy-duty variants despite Argentine natural gas conversion incentives diverting some fleet investment.
- Hybrid Engines:Mild-hybrid 48V belt-integrated starter-generator systems address PROCONVE urban emission testing cycles.
- Alternative Fuel Engines:Compressed natural gas and ethanol-dedicated configurations respond to Argentine government fleet conversion programs.
Diesel engines absorb the bulk of installed capacity across commercial and industrial applications; hybrid engines are expanding most quickly as Brazilian OEMs integrate electrified architectures to meet tightening emission thresholds.
End User:
Customer procurement sophistication varies from multinational OEMs with integrated powertrain engineering teams to fragmented aftermarket operators sourcing remanufactured units.
- Automotive OEMs:Integrated vehicle assemblers in São Paulo and Córdoba corridors specify engines with unified thermal management strategies spanning combustion and after-treatment domains.
- Aftermarket Providers:Powertrain remanufacturing operations leverage Mercosur trade bloc rules of origin to serve Brazilian fleet renewal demand.
- Industrial Applications:Generator-set procurement for Patagonian remote installations and Mato Grosso agricultural operations requires extended service interval engineering.
- Marine Applications:Coastal fishing fleet operators in southern Brazil specify marinized diesel architectures with corrosion-resistant cooling systems.
Automotive OEMs command the largest share of new-engine procurement volume; aftermarket providers are climbing the fastest as fleet operators extend asset life cycles amid emission compliance cost pressures.
Technology:
Margin capture concentrates where calibration expertise and precision hardware supply create defendable supplier positions.
- Turbocharged:Variable geometry systems integrate with exhaust gas recirculation loops to meet PROCONVE transient emission test requirements. Brazilian medium-duty truck assemblers deploy these across São Paulo state platforms where thermal management optimization unifies previously separate engine and after-treatment control domains.
- Naturally Aspirated:Port-fuel-injected architectures retain cost advantage in entry-level passenger vehicles and small motorcycles where PROCONVE compliance remains achievable without forced induction complexity.
- Direct Injection:Gasoline direct injection with stratified charge capability addresses specific urban emission testing protocols.
- Variable Valve Timing:Cam-phasing systems optimize pumping losses across Brazilian flex-fuel operating ranges.
Turbocharged technology commands the strongest margin pool; direct injection is gaining share fastest as gasoline engine architectures adopt pressure-charged combustion chambers.
Application:
End-use thermal and duty-cycle requirements dictate fuel system specification and after-treatment packaging constraints.
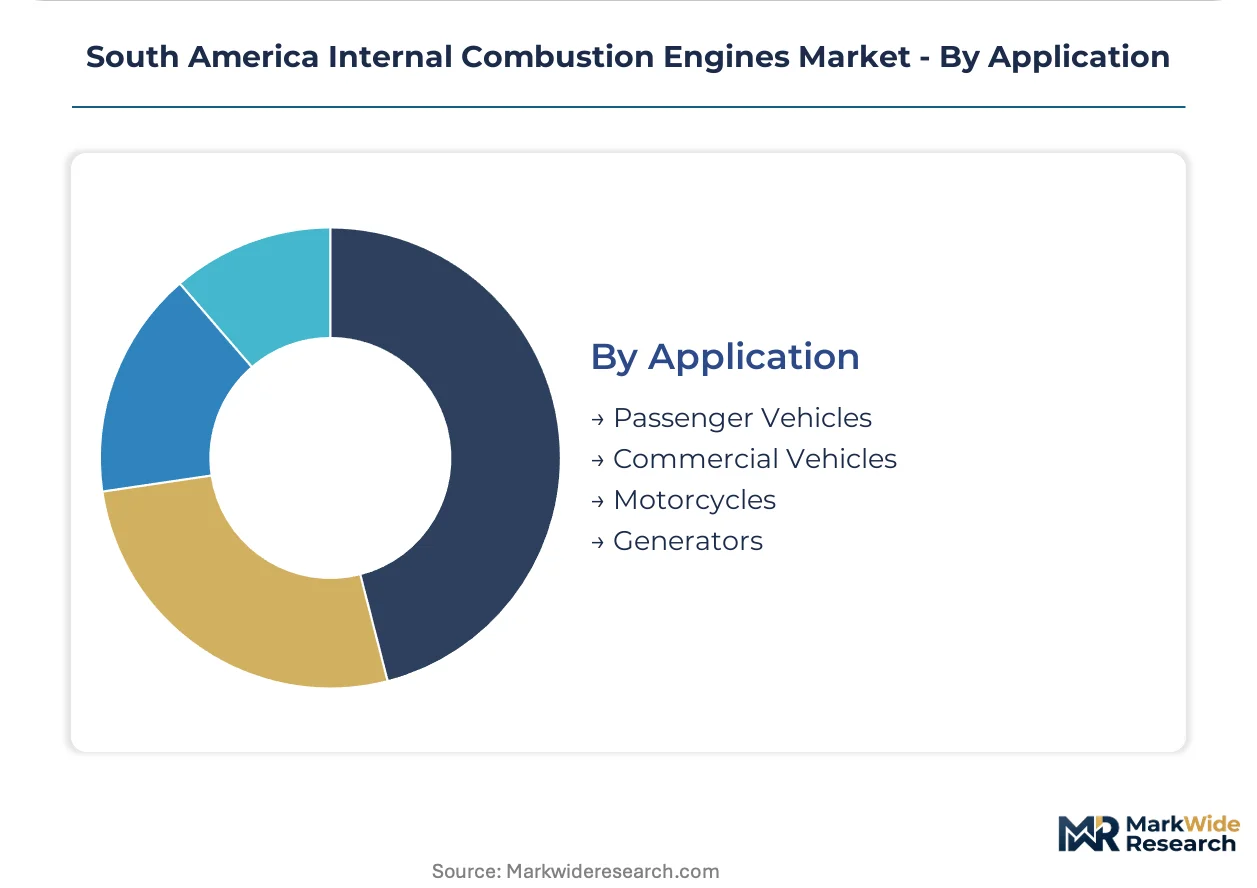
- Passenger Vehicles:Compact and mid-size platforms in Brazilian assembly plants integrate downsized turbocharged gasoline engines with 48V mild-hybrid systems to navigate PROCONVE urban test cycles.
- Commercial Vehicles:Medium and heavy-duty truck fleets across Mercosur corridors specify common-rail diesel with selective catalytic reduction and diesel particulate filter after-treatment.
- Motorcycles:Single-cylinder naturally aspirated engines dominate commuter segments in urban Brazilian and Colombian markets.
- Generators:Stationary and mobile power units for Andean mining and Patagonian remote installations require altitude-compensated fuel injection calibration.
Commercial vehicles anchor the largest installed base; passenger vehicles are expanding most quickly as Brazilian OEMs refresh compact car platforms with emission-compliant powertrains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's industrial corridor anchors engine assembly and after-treatment component manufacturing across the southern cone. Brazilian PROCONVE emission tiers and Argentine IRAM standards reshape procurement patterns from the Atlantic coast to the Andean highlands.
Brazil
Sugarcane ethanol distribution networks sustain flex-fuel engine demand for passenger vehicle OEMs. ANVISA and the national environmental regulator administer PROCONVE L7/L8 tiers mandating nitrogen oxide reductions. São Paulo state assemblers deploy common-rail fuel injection upgrades across medium-duty truck platforms.
Argentina
Compressed natural gas conversion incentives divert fleet investment from diesel powertrains in Buenos Aires and Córdoba provinces. IRAM certification frameworks mandate onboard diagnostic verification beyond Brazilian scope. Córdoba's automotive cluster hosts localized diesel production serving commercial vehicle sectors.
Chile
Copper extraction operations in high-altitude mining districts drive generator-set diesel engine procurement. The Ministry of Transport emission protocols create parallel homologation requirements for cross-border suppliers. Patagonian remote installations require extended service interval engineering for warranty compliance.
Peru
Andean mining expansion sustains demand for 500+ kW heavy-duty diesel variants despite fuel logistics challenges. The national mining regulator enforces equipment emission standards at extraction sites. Lima-based distributors coordinate altitude-compensated fuel injection calibration for mountain operations.
Paraguay and Uruguay
Underpenetrated commercial vehicle markets in Asunción and Montevideo corridors offer positioning for Euro V-compliant engine platforms. Mercosur trade bloc rules of origin create favorable conditions for powertrain rebuild operations. Fleet renewal programs in both capitals attract remanufacturing channel development.
South America Internal Combustion Engines Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology and after-treatment integration dimensions. The supplier base concentrates around three tiers: integrated vehicle assemblers with captive powertrain engineering, independent engine specialists serving commercial and industrial applications, and aftermarket remanufacturing operators leveraging regional trade preferences. Strategic moves center on turbocharger technology licensing and selective vertical integration into high-pressure fuel system production.
Within the integrated assembler tier, Toyota Motor Corporation and Volkswagen Group occupy positions spanning passenger and commercial vehicle segments. Stellantis anchors the aftermarket channel through powertrain remanufacturing operations. MAN SE and Cummins exemplify the independent engine specialist archetype serving heavy-duty applications.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Volkswagen Group |
| Renault Group |
| General Motors |
| Ford Motor Company |
| MAN SE |
| Stellantis |
| Volvo AB |
| Cummins |
| Others |
Pricing and Supply Chain Analysis
Variable geometry turbocharger adoption across Brazilian medium-duty truck platforms simultaneously escalates precision component costs and concentrates procurement leverage among German and Japanese tier-one suppliers. This technology transition tightens margin pools for assemblers while amplifying pricing power for fuel system specialists serving PROCONVE-compliant fleets.
Pricing Analysis
Uptime guarantees for mining generator-sets in Chilean and Peruvian high-altitude operations anchor value-based pricing for heavy-duty diesel architectures. Three-tier pricing structure across premium turbocharged, standard common-rail, and economy naturally aspirated levels reflects certification grade and after-treatment complexity. Cost compression in entry-level passenger vehicle powertrains is intensifying because flex-fuel calibration investments multiply engineering overhead. Fleet operators in Argentina's Córdoba corridor exhibit highest price sensitivity, while Andean mining procurement teams prioritize reliability over unit cost.
Supply Chain Analysis
Mercosur trade bloc rules of origin reshape sourcing patterns by mandating regional content thresholds for powertrain assemblies. Precision fuel injection hardware draws from Germany, Japan, and domestic Brazilian machining operations. Common-rail component dependencies, selective catalytic reduction substrates, and turbocharger compressor wheels create single-source vulnerability for emission-compliant architectures. Distribution runs through São Paulo state logistics hubs serving aftermarket remanufacturing channels across the southern cone.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over high-pressure fuel system production separates margin leaders from commodity assemblers. Players are pursuing backward integration into precision component machining to defend pricing power.
For Market Incumbents: Deepen captive production of common-rail injectors and turbocharger assemblies to offset tier-one supplier concentration. Expand remanufacturing capacity in São Paulo state to capture aftermarket volume as PROCONVE compliance extends fleet lifecycles. Battery-electric commercial vehicle entrants threaten diesel engine demand in urban delivery segments. For New Entrants and Emerging Players: Aftermarket distributors in Paraguay and Uruguay represent the most penetrable channel partner type for Euro V-compliant engine platforms. Target generator-set procurement for Patagonian remote installations where extended service intervals justify premium positioning. Partner with Mato Grosso agricultural equipment dealers to bypass OEM distribution for harvester retrofit powertrains. For Investors and Strategic Acquirers: Re-rating potential sits with independent engine specialists possessing selective catalytic reduction calibration expertise given PROCONVE L8 tier acceleration. Long-term viability hinges on hybrid architecture integration capability across the projection horizon. Acquisition targets should demonstrate in-house exhaust after-treatment development. Watch Argentine natural gas conversion subsidy renewal as demand inflection signal for diesel-dependent segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fuel Injection Hardware | Captive common-rail production insulates Brazilian assemblers from yen-euro currency volatility. |
| Remanufacturing Channel Expansion | Mercosur rules of origin enable Stellantis to rebuild powertrains for Brazilian fleet renewal demand. |
| Mild-Hybrid Architecture Licensing | 48V belt-integrated starter-generator partnerships help Toyota meet PROCONVE urban emission cycles. |
| Andean Mining Generator-Set Partnership | Long-term service contracts with Chilean copper extractors secure altitude-compensated calibration revenue. |
| Natural Gas Engine Platform Development | Compressed natural gas configurations capture Argentine government fleet conversion incentives in Córdoba. |
Research Methodology
ANVISA regulatory filings, PROCONVE certification databases, and Mercosur trade statistics formed the secondary backbone for market sizing. Primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket service heads, and agricultural fleet maintenance directors validated demand assumptions. Bottom-up production volume estimates triangulated against top-down fuel consumption data across the analysis window.
Historical trendline analysis of engine displacement trends and emission tier adoption rates informed projection modeling. Segmentation dimensions span product type, end user archetype, technology tier, and application duty cycle. CAGRs derive from regression-weighted scenario outputs incorporating biofuel blending mandate trajectories and mining capital expenditure patterns.
Caveats apply where Argentine natural gas subsidy revisions or Brazilian PROCONVE tier acceleration could materially shift the outlook. Forecasts embed assumptions around currency stability and common-rail component supply continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive TCU Market
Powertrain
Automotive Engine Cylinder Block Market
Powertrain
Transmission Fluids Market
Powertrain
Car Drive System Market
Powertrain
Torque Limiter Market
Powertrain
Electric Powertrain Systems Market
Powertrain
Automotive Transmission Fluid Market
Powertrain
Automotive Transmission System Market
Powertrain
Global Automotive Fuel Delivery and Injection Systems Market
Powertrain
Automotive Thrust Washer Market
Powertrain
Car Active Purge Pump Market
Powertrain
Automotive Chain Tensioners Market
Powertrain
Automotive Active Purge Pump Market
Powertrain
Timing Belt Market
Powertrain
Brazil Automotive Engine Oils Market
Powertrain
Global Automotive Exhaust Gas Turbochargers Market